
 AI in Project Management Market | 2026-2036
AI in Project Management Market Size, Share, and Industry Trends Forecast 2026-2036
AI in Project Management Market Analytics
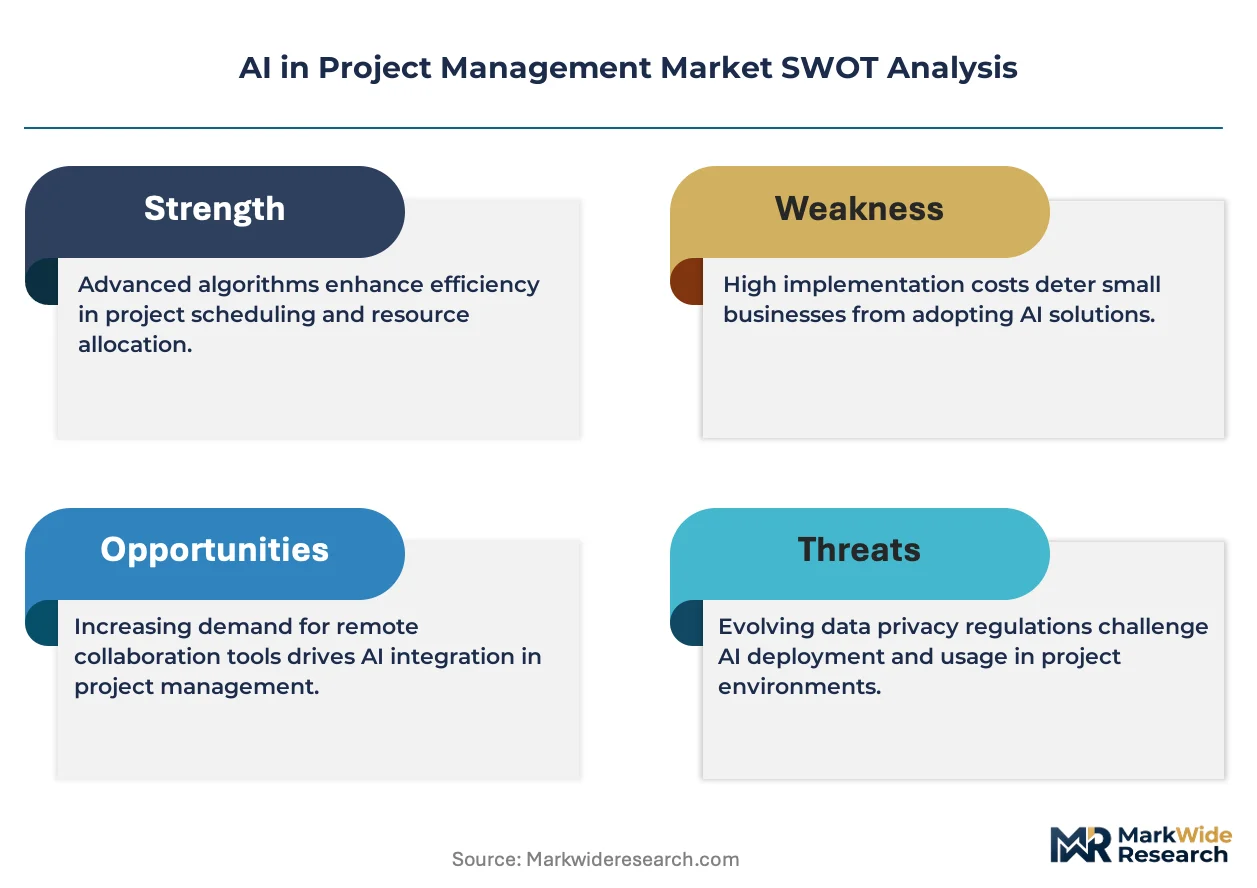
Subscription-based SaaS financing is reshaping competitive entry in AI project management, lowering capital barriers for mid-tier vendors while pressuring perpetual-license incumbents. Microsoft Corporation leverages its Azure cloud infrastructure to bundle AI planning tools with enterprise productivity suites. IBM Corporation anchors its position through Watson-powered risk analytics integrated with legacy project portfolios. Oracle Corporation competes by extending database-centric resource allocation into predictive scheduling modules.
AI in project management denotes software systems that apply machine learning algorithms, natural language processing, and predictive analytics to automate task sequencing, resource leveling, and risk detection across complex workstreams; these systems typically process structured project data alongside unstructured communications to generate real-time schedule adjustments and bottleneck forecasts. Cloud-based deployment leads volume adoption as enterprises prioritize elastic scaling and reduced IT overhead, while hybrid architectures capture organizations with segmented data sovereignty requirements. Task management software represents the most mature product category with established vendor saturation, whereas risk management solutions command premium pricing due to specialized actuarial model integration and higher implementation complexity.
The EU AI Act classifies automated project decision systems by risk tier, directly affecting how vendors architect transparency and human-override features for European deployments. In the United States, NIST AI Risk Management Framework shapes procurement standards for federal contractors selecting predictive scheduling platforms. Stakeholders must monitor evolving algorithmic accountability requirements across jurisdictions to determine compliance investment sequencing and market prioritization.
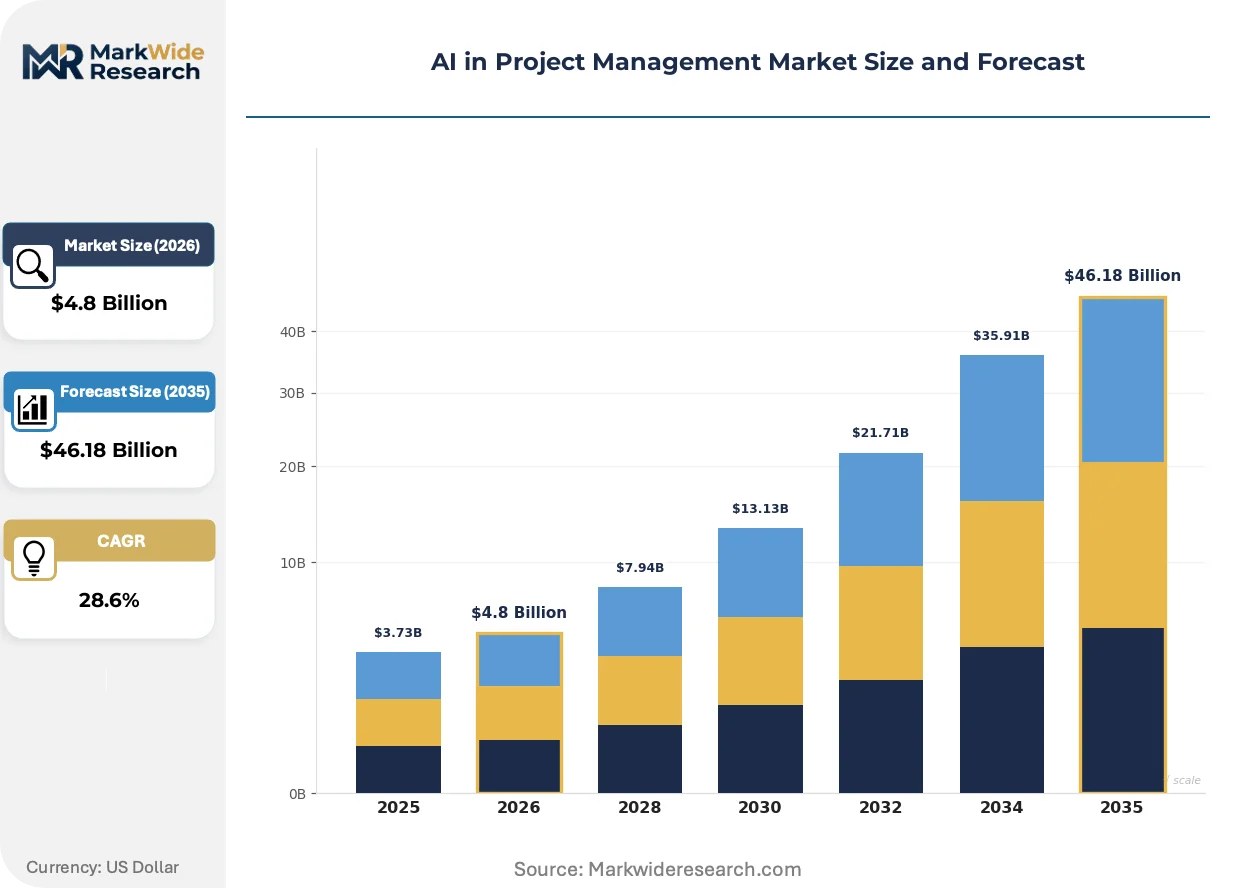
Market Dynamics
Cloud-native architectures are collapsing the traditional on-premises deployment model as construction firms and federal contractors prioritize elastic scaling over capital-intensive infrastructure ownership.
Growth Catalysts
- Federal Infrastructure Spending:United States procurement of predictive scheduling platforms accelerates under bipartisan infrastructure legislation, with agencies mandating AI-enabled risk analytics for projects exceeding defined capital thresholds.
- EU AI Act Risk Classification:Automated project decision systems face tiered compliance requirements that create procurement specifications favoring vendors with pre-built transparency modules and human-override architectures.
- Natural Language Processing:Unstructured communications parsing—emails, meeting transcripts, change orders—now feeds real-time schedule adjustments, compressing manual status-update cycles from days to minutes.
Market Restraints
- Data Sovereignty Segmentation:Hybrid deployment architectures proliferate as German automotive manufacturers and French defense contractors resist full cloud migration due to project data residency mandates.
- Actuarial Model Scarcity:Risk management solutions command premium pricing because specialized quantitative talent for construction-specific loss prediction concentrates in London and Zurich insurance hubs.
- Legacy System Entrenchment:Oracle database-centric resource allocation tools retain sticky enterprise accounts through decades of embedded workflow dependencies that resist API-based displacement.
Strategic Opportunities
- India PLI Scheme Alignment:Domestic software vendors qualify for production-linked incentives when AI project management modules integrate with government infrastructure tracking portals.
- Digital Twin Convergence:Building information modeling platforms merge with predictive scheduling engines, enabling real-time 4D simulation that compresses pre-construction planning cycles.
- Subscription Financing Expansion:Mid-tier SaaS vendors penetrate construction sub-contractor segments previously locked out by perpetual-license capital requirements.
Industry Challenges
- Prompt Engineering Talent Gap:Construction technology departments lack personnel capable of tuning large language models for domain-specific terminology in change-order classification.
- NIST Framework Implementation:Federal contractors face extended procurement timelines as AI Risk Management Framework documentation requirements add validation layers to vendor selection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI in Project Management Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $46.18 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Project Planning Tools, Resource Allocation, Task Management Software, Risk Management Solutions Deployment: On-Premises, Cloud-Based, Hybrid, Mobile Platforms End User: IT Companies, Construction Firms, Consulting Agencies, Educational Institutions Application: Agile Management, Budget Tracking, Schedule Optimization, Performance Monitoring |
| Companies Covered | Microsoft Corporation, IBM Corporation, Oracle Corporation, Atlassian Corporation, Amazon Web Services, Google LLC, ServiceNow, Adobe Inc., ALICE Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI in Project Management Market Evolving Landscape
Generative interfaces are restructuring how project stakeholders interact with scheduling systems, replacing dashboard-centric workflows with conversational command structures that compress training requirements.
Reinforcement learning from human feedback is collapsing the accuracy gap between automated resource leveling and veteran project manager intuition. Tier-one engineering firms in Texas and California deploy these systems for capital projects exceeding five-year durations, compressing buffer allocation debates from weeks to automated recommendations with auditable confidence intervals.
The EU AI Act's high-risk system designation forces vendors to retrofit algorithmic explainability modules for European deployments. Construction software providers now embed counterfactual reasoning displays that show why schedule adjustments were proposed, with French and German regulators requiring this transparency for public infrastructure tenders above specified thresholds.
Consumption-based licensing is displacing seat-count models as primary revenue architecture. EPC contractors in the United Arab Emirates and Saudi Arabia prefer per-project pricing that aligns vendor compensation with milestone achievement rather than user enrollment, compressing sales cycles and shifting implementation risk to technology providers.
AI in Project Management Market Segmentation
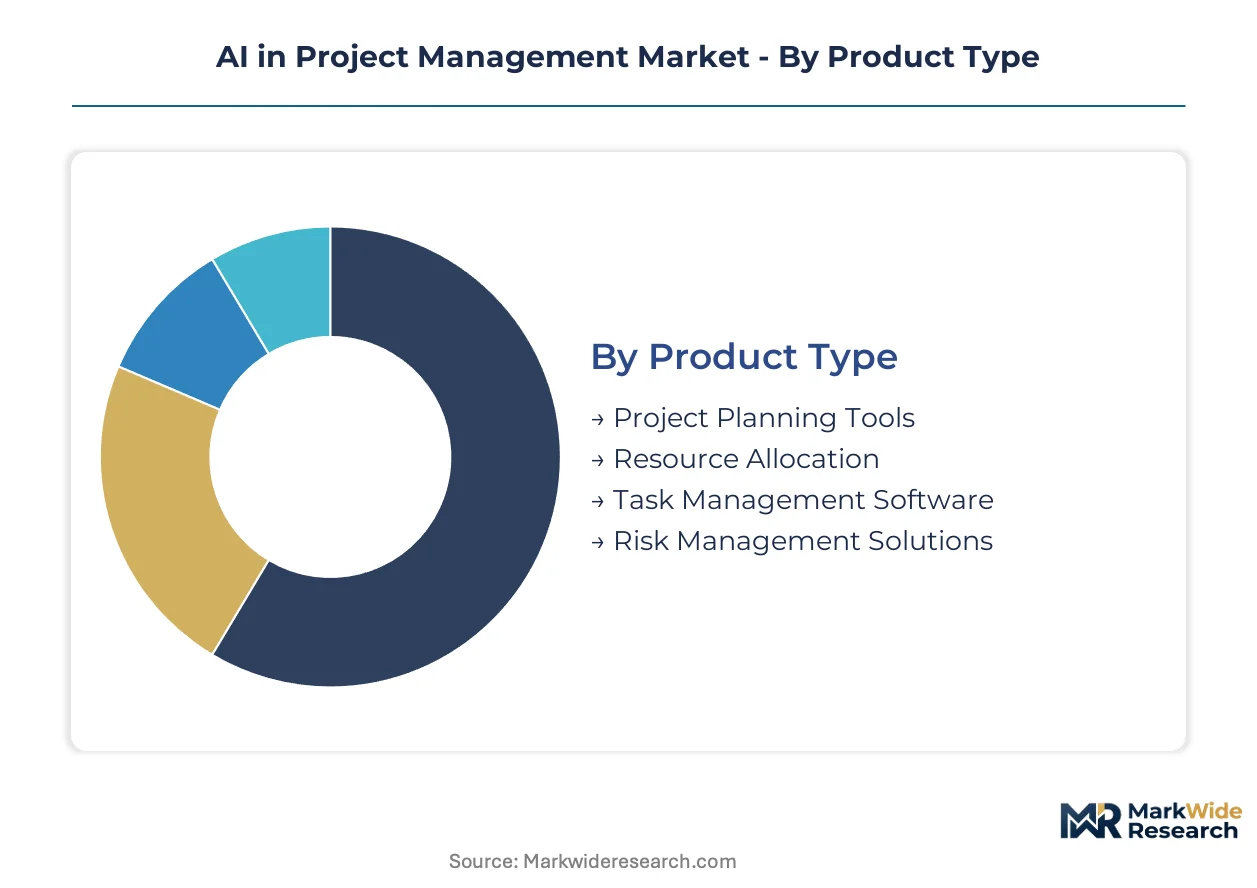
Segmentation in AI project management reveals how vendor specialization aligns with buyer procurement patterns. Each dimension—product architecture, delivery model, user profile, and use case—carries distinct margin structures and implementation complexity that shape competitive positioning.
Product Type:
After-sales service intensity varies dramatically across product categories, with risk management solutions demanding continuous actuarial model tuning while task management software operates on lighter support footprints.
- Task Management Software:Established category with mature API ecosystems and standardized workflow templates. Demand concentrates among consulting agencies in the United States seeking rapid team coordination without heavy configuration overhead.
- Risk Management Solutions:Specialized systems integrating predictive loss models with project portfolio data. Construction firms in Texas and California deploy these for capital projects exceeding five-year durations, compressing buffer allocation debates through automated recommendations with auditable confidence intervals.
- Project Planning Tools:Core scheduling engines with Gantt visualization and critical path analysis.
- Resource Allocation:Workforce optimization modules balancing skill matrices against timeline constraints.
Task management software holds the largest share; momentum sits with risk management solutions.
Deployment:
Cost tier stratification separates enterprise buyers willing to absorb infrastructure ownership from mid-market adopters prioritizing operational expenditure models.
- Cloud-Based:Elastic scaling architectures with subscription pricing and reduced IT overhead. Federal contractors in the United States accelerate procurement under NIST AI Risk Management Framework documentation requirements.
- Hybrid:Segmented architectures preserving sensitive data on-premises while leveraging cloud analytics. German automotive manufacturers and French defense contractors favor this model due to project data residency mandates under EU AI Act specifications.
- On-Premises:Legacy installations with perpetual licensing and dedicated hardware requirements.
- Mobile Platforms:Field-optimized interfaces for real-time status updates and photograph-based progress reporting.
Cloud-based deployment commands the dominant position; hybrid architectures are climbing the fastest as sovereignty requirements harden.
End User:
Application complexity diverges sharply between technology-driven adopters and asset-heavy industries with legacy workflow dependencies.
- Construction Firms:Project-centric buyers integrating AI scheduling with building information modeling platforms. United States infrastructure spending drives implementation velocity for predictive analytics on federally funded projects.
- IT Companies:Early adopters with mature DevOps cultures and API-first integration requirements. These buyers in California and Washington state compress deployment cycles through existing cloud-native toolchains.
- Consulting Agencies:Professional services firms reselling configured platforms to client portfolios.
- Educational Institutions:Research-driven adopters piloting AI project coordination for grant-funded collaboration networks.
Construction firms represent the largest addressable base; IT companies are gaining share fastest through agile methodology alignment.
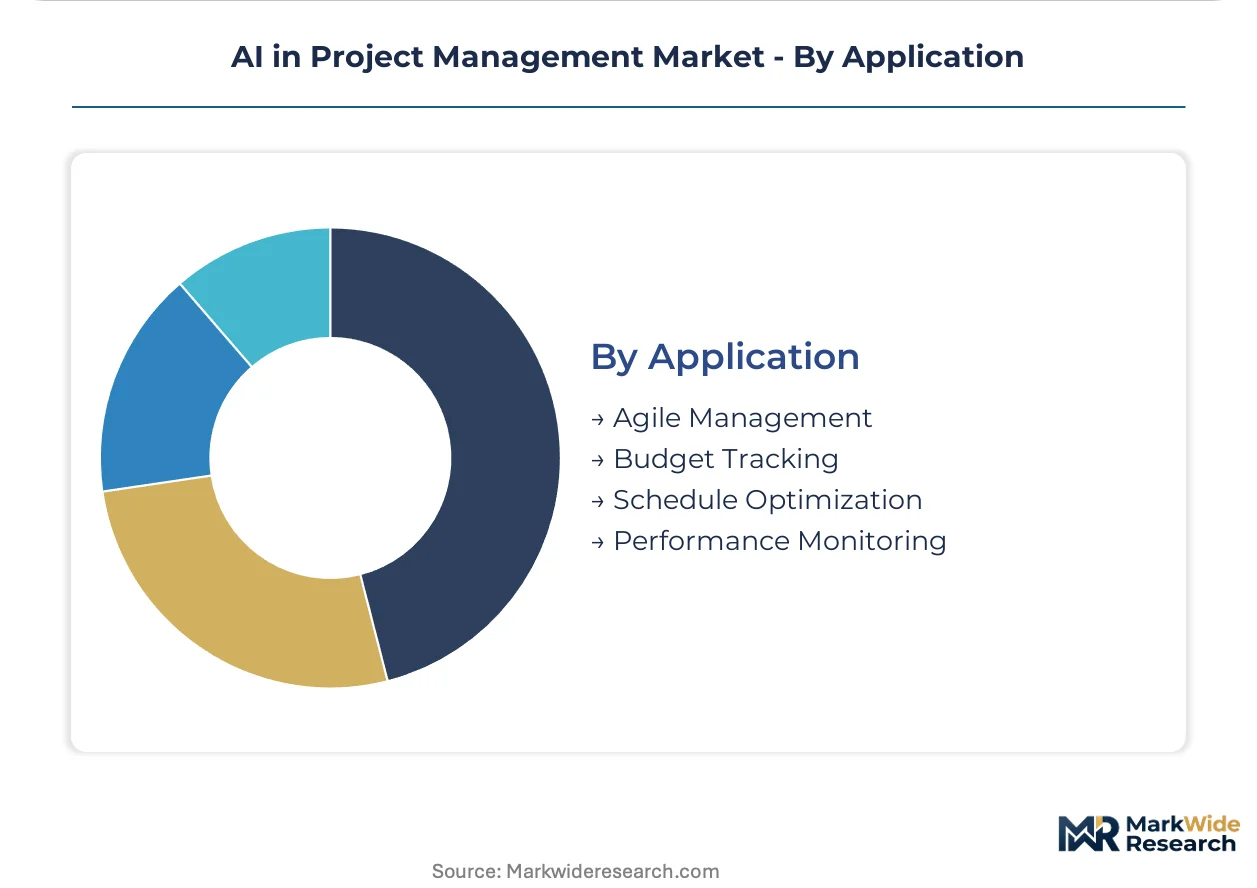
Application:
Maturity gradients separate established methodologies from emerging performance disciplines requiring specialized sensor integration.
- Schedule Optimization:Critical path automation with resource leveling and float analysis. United States federal agencies mandate AI-enabled risk analytics for projects above defined capital thresholds under bipartisan infrastructure legislation.
- Agile Management:Sprint planning and velocity tracking adapted for software development workflows. Indian software vendors qualify for production-linked incentives when modules integrate with government infrastructure tracking portals.
- Budget Tracking:Earned value management with predictive cost-to-complete forecasting.
- Performance Monitoring:Real-time KPI dashboards with anomaly detection for milestone deviation.
Schedule optimization retains the largest installed base; agile management shows the steepest expansion trajectory among digital-native adopters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial trade surplus in AI project management software exports, while Germany and China remain net importers of specialized risk analytics platforms. Import dependency concentrates in construction-specific actuarial modules where London and Zurich insurance hubs retain proprietary model ownership.
United States
Federal infrastructure spending and technology sector procurement accelerate predictive scheduling adoption. NIST AI Risk Management Framework documentation requirements shape vendor selection for contractors above defined capital thresholds. Texas and California engineering firms deploy reinforcement learning systems for multi-year capital projects.
Germany
Automotive manufacturers and defense contractors drive hybrid deployment architectures due to data residency mandates. EU AI Act risk classification forces algorithmic explainability retrofits for public infrastructure tenders. Bavarian industrial clusters favor segmented models preserving sensitive project data on-premises.
China
State-backed infrastructure investment and smart city initiatives expand domestic vendor opportunity. National data localization requirements favor indigenous cloud platforms over foreign SaaS providers. Yangtze River Delta construction technology clusters integrate AI scheduling with building information modeling platforms.
India
Domestic software vendors leverage PLI scheme incentives when modules integrate with government infrastructure tracking portals. Agile methodology alignment accelerates adoption among Bangalore and Hyderabad IT services exporters. Production-linked incentives reshape competitive entry for mid-tier SaaS providers.
United Arab Emirates
EPC contractors prefer consumption-based licensing that aligns vendor compensation with milestone achievement. Saudi Arabia and UAE mega-project pipelines drive demand for real-time 4D simulation capabilities. Dubai-based construction consortia pilot digital twin convergence with predictive scheduling engines.
AI in Project Management Market Competitive Landscape
On the supply side, the industry is consolidating around cloud-native platforms with established enterprise distribution channels. Incumbent productivity suite vendors leverage installed base advantages while specialized construction technology firms carve risk analytics niches. Strategic archetypes include hyperscale platform bundlers, database-centric resource optimizers, and actuarial model specialists. Dominant competitive moves encompass API ecosystem expansion and consumption-based pricing model migration.
Within the hyperscale platform tier, Microsoft Corporation exemplifies cloud infrastructure leverage through Azure-anchored productivity bundling. IBM Corporation occupies a position in risk analytics integration through Watson-powered portfolio tools. Oracle Corporation represents database-centric resource allocation extension into predictive modules. These three anchors illustrate how legacy enterprise software vendors defend position through workflow embedding and infrastructure control.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| Oracle Corporation |
| Atlassian Corporation |
| Amazon Web Services |
| Google LLC |
| ServiceNow |
| Adobe Inc. |
| ALICE Technologies |
| Others |
Value Network & Pricing Analysis
Single-source dependency on London and Zurich actuarial model providers compresses pricing spreads between risk management tiers and task management tiers while forcing hybrid deployment architectures across European and Middle Eastern supply chains. NIST AI Risk Management Framework documentation requirements for United States federal contractors further stratify vendor pricing power based on compliance investment depth.
Pricing Analysis
Industrial OEM buyers anchor consumption-based licensing as the dominant pricing structure, with EPC contractors in Saudi Arabia and the United Arab Emirates preferring per-project pricing that aligns vendor compensation with milestone achievement. Price differentiation rests on actuarial model sophistication and EU AI Act transparency module certification, with risk management solutions commanding substantial premiums over task management software. Pricing pressure stems from subscription financing expansion among mid-tier SaaS vendors penetrating construction sub-contractor segments. Federal contractors demonstrate lowest price sensitivity due to mandated compliance requirements, while educational institutions and consulting agencies exhibit highest sensitivity to per-seat cost escalations.
Supply Chain Analysis
Cloud infrastructure concentration among hyperscale providers in the United States, Ireland, and Singapore shapes global delivery capacity for AI project management platforms. Raw material dependencies center on GPU compute clusters, proprietary NLP training datasets, and construction-specific loss prediction models sourced from London and Zurich insurance hubs. Supply chain risk manifests as regulatory chokepoint exposure where EU AI Act algorithmic explainability requirements delay European deployments. Distribution runs through direct enterprise sales teams for tier-one engineering firms and channel partnerships for mid-market construction sub-contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's high-risk system designation creates a structural inflection that separates compliant vendors from retrofitting laggards across European public infrastructure tenders. Natural language processing advancement compresses implementation timelines from months to weeks for adopters with mature cloud-native toolchains.
For Market Incumbents: Insulate embedded workflow advantages by deepening API ecosystem expansion around legacy Oracle database installations and Microsoft Azure productivity suites. Prioritize pre-built transparency modules and human-override architectures to preempt EU AI Act compliance disruption. Counter emerging SaaS entrants through consumption-based pricing migration that shifts implementation risk toward vendor balance sheets. For New Entrants and Emerging Players: Pursue white-space penetration in Indian infrastructure tracking portal integration under PLI scheme qualification criteria. Target construction sub-contractor segments previously locked out by perpetual-license capital requirements through subscription financing models. Establish go-to-market positioning around agile methodology alignment for Bangalore and Hyderabad IT services exporters. For Investors and Strategic Acquirers: EU AI Act enforcement milestones reshape the acquisition landscape toward vendors with pre-certified algorithmic explainability modules and established European regulatory affairs capabilities. Long-term viability favors specialized risk analytics firms with proprietary construction actuarial models over generalized task management platforms facing saturation. Monitor NIST AI Risk Management Framework procurement documentation requirements as the signal indicating federal contractor vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft Azure bundling with enterprise productivity suites captures federal contractor procurement under NIST requirements. |
| Acquisition of Specialist Firm | Actuarial model specialists in London and Zurich insurance hubs command scarcity premiums in risk analytics consolidation. |
| Product Launch | Generative interfaces replacing dashboard-centric workflows compress training requirements for construction technology departments. |
| Strategic Partnership | Building information modeling platform convergence enables real-time 4D simulation for Dubai-based construction consortia. |
| Geographic Expansion | India PLI scheme alignment opens government infrastructure tracking portal integration for domestic software vendors. |
Research Methodology
Operator-level perspectives from project management office directors, construction technology VPs, federal procurement officers, and cloud infrastructure architects anchored the qualitative base. Primary interview findings triangulated against secondary sources including SEC 10-K filings from hyperscale platform vendors, EU AI Act regulatory documentation, NIST AI Risk Management Framework publications, and building information modeling platform technical specifications. Bottom-up segment sizing across deployment models and end-user verticals converged with top-down market boundary validation.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation modeling spanning product architecture, delivery model, organization size, and regional adoption pattern. CAGRs derived from elasticity-adjusted technology diffusion curves incorporating federal infrastructure spending trajectories and EU regulatory compliance timelines. Reinforcement learning deployment rates among Texas and California engineering firms provided industry-specific forecast calibration inputs.
Macroeconomic conditions sit as an overlay; deviation in federal infrastructure appropriations cycles or EU AI Act enforcement stringency would shift the trajectory. Forecasts reflect documented assumptions regarding cloud migration velocity and actuarial model talent availability. Quarterly review of NIST procurement documentation requirements and EU public infrastructure tender specifications is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Synthetic Data Generation Market
Artificial Intelligence (AI)
Emotion Detection and Recognition (EDR) Market
Artificial Intelligence (AI)
Cloud Computing Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
Generative AI Market
Artificial Intelligence (AI)
Robotic Vision Market
Artificial Intelligence (AI)
Multimodal AI Market
Artificial Intelligence (AI)
Artificial Intelligence-Based Security Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Food and Beverages Market
Artificial Intelligence (AI)
AI in Robotics Market
Artificial Intelligence (AI)
AI Development Service Market
Artificial Intelligence (AI)
Global Cloud Telecommunication AI Market
Artificial Intelligence (AI)
Deep Learning Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) Accelerator Market
Artificial Intelligence (AI)
CLV and Churn Prediction AI Market
Artificial Intelligence (AI)
Global Conversational Computing Platform Market
Artificial Intelligence (AI)
Federated Learning Market