
 Smart Home Digital Assistant [Voice] Market | 2026-2036
Smart Home Digital Assistant [Voice] Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Home Digital Assistant [Voice] Market Outlook
Residential energy management is decoupling from traditional utility interfaces as voice-controlled climate and lighting systems penetrate climate-conscious households. Amazon.com, Inc. leverages its Alexa ecosystem to anchor smart home commerce and device interoperability across North American installations. Google LLC competes through AI integration that sustains search-to-action continuity within voice-activated routines. Apple Inc. differentiates via privacy-centric architecture that controls on-device speech processing for security-sensitive users.
A smart home digital assistant [voice] is an embedded or standalone computing system that processes natural language commands through far-field microphone arrays, cloud-based natural language processing engines, and speaker-dependent voice recognition algorithms to execute domestic tasks. Its primary commercial purpose is to reduce friction in human-device interaction across lighting, climate, entertainment, and security subsystems. Smart Speaker product types dominate current volume shipments, while AI Integration technology captures expanding margin pools as on-device inference displaces cloud-only architectures. Natural Language Processing segments mature around multilingual intent parsing, whereas Cloud-Based deployments face structural pressure from hybrid edge-cloud models.
The FCC governs radio frequency emissions from voice-activated hardware in the United States, while the EU AI Act imposes risk-classification obligations on biometric inference systems deployed in European households. GDPR data minimization principles restrict cross-border voice recording retention, forcing architecture redesigns for cloud-dependent assistants. Stakeholders must monitor evolving interoperability mandates from the European Telecommunications Standards Institute and the U.S. National Institute of Standards and Technology as these frameworks determine which ecosystem participants retain platform control versus becoming voice-skill subordinate.
Market Dynamics
Hybrid edge-cloud architectures are forcing a fundamental restructuring of voice assistant supply chains as on-device inference capabilities reduce dependency on centralized cloud infrastructure. This shift compresses latency benchmarks while fragmenting hardware-software integration strategies across ecosystem participants.
Growth Catalysts
- EU AI Act biometric risk classification:The regulation mandates transparency obligations for emotion recognition systems, creating compliance-driven demand for auditable voice processing architectures in European installations.
- Residential energy management decoupling:Climate-conscious households are bypassing traditional utility interfaces through voice-controlled HVAC and lighting integration, pulling demand for interoperable climate subsystems.
- Suburban single-family penetration:United States households with dedicated smart home infrastructure are expanding voice assistant deployment density beyond living-room speakers into kitchens, bedrooms, and outdoor spaces.
Market Restraints
- GDPR data minimization friction:Cross-border voice recording retention restrictions force cloud-dependent assistants to redesign storage architectures, increasing operational complexity for multi-jurisdiction deployments.
- Far-field microphone array cost concentration:Specialized MEMS microphone supply concentrates among East Asian component fabricators, exposing hardware manufacturers to input cost volatility and single-source risk.
- Natural language processing talent scarcity:Multilingual intent parsing expertise concentrates within a narrow pool of computational linguists, constraining rapid feature localization for emerging language markets.
Strategic Opportunities
- On-device speech processing convergence:Neural processing unit integration with local large language models is modularizing privacy-sensitive deployments for security-conscious enterprise and healthcare verticals.
- ETSI interoperability mandates:European standardization requirements for cross-platform voice skill compatibility are creating openings for middleware providers to capture value between locked ecosystems.
- India smart city integration:Voice-controlled municipal service interfaces in urban infrastructure projects represent an underpenetrated channel beyond residential consumer markets.
Industry Challenges
- ISO/IEC 27001 certification timelines:Information security management system audits for voice data handlers extend deployment schedules by 8-14 months in regulated European and North American enterprise segments.
- Legacy home automation protocol integration:Z-Wave and Zigbee interoperability with IP-based voice assistants requires complex gateway middleware, increasing installation failure rates and support costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Home Digital Assistant [Voice] Market |
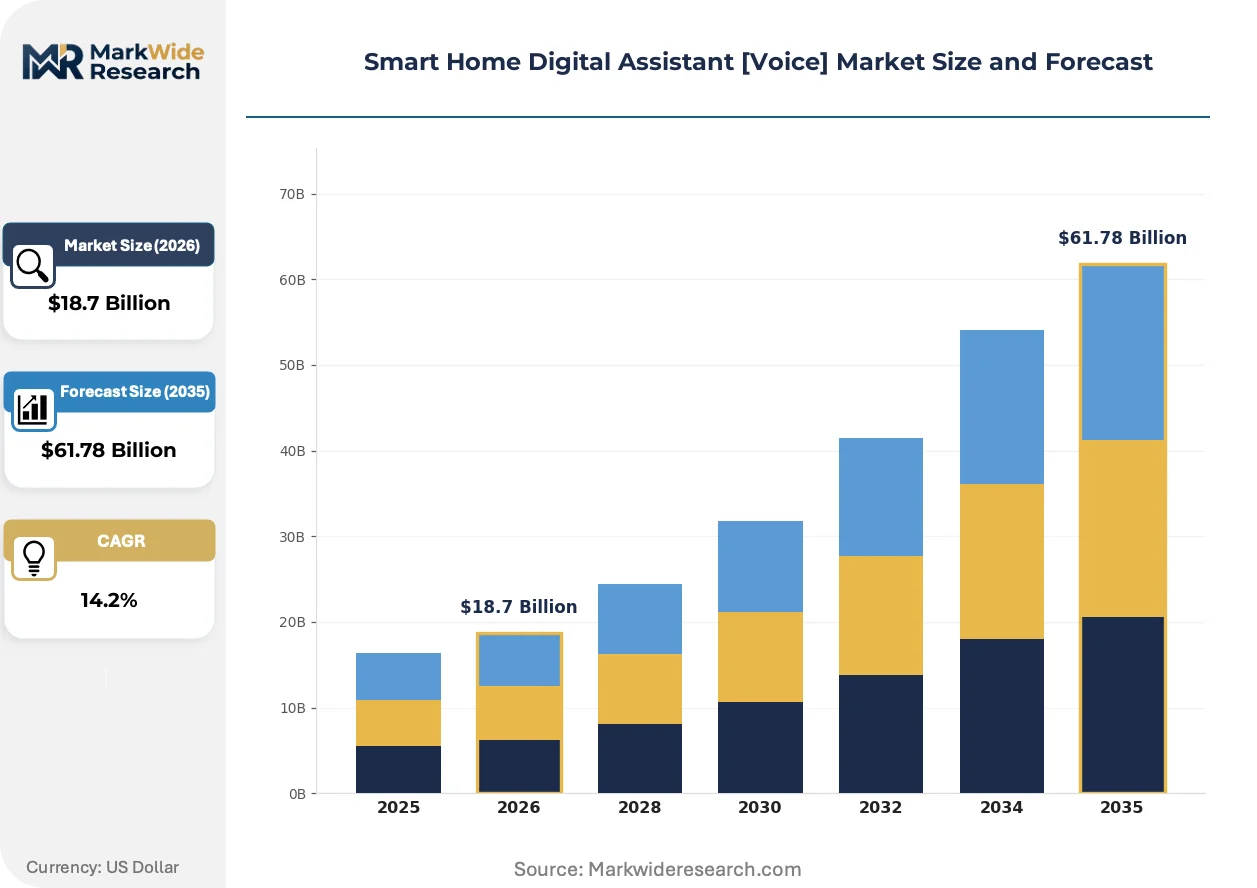
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone, Integrated, Portable, Smart Speaker Technology: Natural Language Processing, AI Integration, Cloud-Based, Voice Recognition End User: Homeowners, Renters, Families, Tech Enthusiasts Installation Type: DIY, Professional, Smart Hub Integration, Standalone Setup |
| Companies Covered | Amazon.com, Inc., Google LLC, Apple Inc., Samsung Electronics Co., Ltd., Microsoft Corporation, Alibaba Group Holding Limited, Xiaomi Corporation, Baidu, Inc., Yandex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Home Digital Assistant [Voice] Market Strategic Shifts
Voice assistant architectures are fragmenting along privacy-performance axes as regulatory pressure and consumer preference divergence create distinct technical trajectories. Three developments are reshaping competitive positioning.
On-device large language model inference is modularizing voice processing workflows by distributing computation between edge neural engines and selective cloud fallback. Security-sensitive users in financial services and healthcare verticals are adopting these hybrid architectures fastest. The technology is compressing cloud infrastructure margins while elevating semiconductor content value in speaker hardware.
The EU AI Act's risk-tier classification system is imposing documentation and human-oversight obligations on biometric inference systems deployed in European households. Industrial consequence includes mandatory conformity assessments for emotion detection and speaker identification features. Smart speaker manufacturers serving Germany and France are stripping advanced biometric capabilities to avoid high-risk system classification.
Subscription-based skill monetization is displacing one-time app purchases as the dominant voice commerce revenue model. Developer economics are shifting toward recurring revenue streams, with kitchen and wellness applications leading adoption. This pattern is most visible in United States suburban markets where smart home device density supports multi-service household spending.
Smart Home Digital Assistant [Voice] Market Segmentation
Voice assistant market segmentation reveals divergent capital requirements across hardware form factors and processing architectures. Product type and technology choices determine whether vendors absorb semiconductor inventory risk or capture recurring service margins.
Product Type:
Capital intensity varies sharply across form factors, with integrated systems demanding the heaviest upfront manufacturing investment while portable devices minimize fixed asset exposure.
- Smart Speaker:Far-field microphone arrays and dedicated amplifier circuits dominate bill-of-materials costs. Demand concentrates in United States suburban single-family installations where device density now extends beyond living rooms into kitchens and bedrooms.
- Integrated:Embedded modules within thermostats, lighting controls, and security panels require custom industrial design and extended certification cycles. European OEMs favor this segment to satisfy GDPR data minimization through on-device processing architectures.
- Standalone:Purpose-built voice hubs with display screens command premium positioning.
- Portable:Battery-powered units with Bluetooth and Wi-Fi connectivity target mobility-oriented users.
Smart Speaker absorbs the bulk of installed capacity; Integrated is expanding most quickly.
Technology:
Margin profiles diverge between cloud-dependent architectures with recurring infrastructure costs and edge-native systems with higher silicon content but lower ongoing service overhead.
- AI Integration:Neural processing unit deployment enables on-device large language model inference. Security-sensitive healthcare and financial services verticals in Germany and France are adopting hybrid edge-cloud architectures fastest to satisfy EU AI Act biometric risk classification requirements.
- Cloud-Based:Centralized natural language processing engines scale across language models but face structural pressure from data residency mandates. GDPR cross-border voice recording retention restrictions force architecture redesigns for multi-jurisdiction deployments.
- Natural Language Processing:Multilingual intent parsing expertise concentrates among computational linguists in the United States and United Kingdom.
- Voice Recognition:Speaker-dependent algorithms require enrollment workflows and biometric storage protocols.
Cloud-Based retains the largest installed base; AI Integration is gaining share fastest.
End User:
Customer lifetime value spreads widest between tech enthusiasts with multi-device ecosystem loyalty and renters with single-unit purchase patterns and elevated churn risk.
- Homeowners:Permanent residents with dedicated smart home infrastructure demonstrate highest device-per-household ratios. United States suburban markets show particular concentration where HVAC and lighting integration drives voice-controlled climate subsystem demand.
- Families:Multi-user households with children generate complex voice profile management requirements and parental control feature demand.
- Tech Enthusiasts:Early adopters with cross-platform experimentation behavior.
- Renters:Transient users with installation restrictions and lower ecosystem lock-in.
Homeowners generate the majority of recurring service revenue; Families show the steepest expansion trajectory.
Installation Type:
Channel economics separate high-touch professional deployment with extended margin capture from self-service models with compressed upfront revenue but lower customer acquisition costs.
- Smart Hub Integration:Voice assistant modules bundled with centralized home automation controllers require Z-Wave and Zigbee gateway middleware. Installation failure rates run elevated where legacy protocol interoperability demands complex configuration.
- Professional:Certified installer networks in the United States and United Kingdom handle enterprise healthcare deployments and high-end residential projects with ISO/IEC 27001 information security management system requirements.
- DIY:Consumer self-installation through retail and direct channels.
- Standalone Setup:Single-device configuration without ecosystem dependencies.
Smart Hub Integration commands the highest service attach rates; Professional installation is climbing the fastest in regulated enterprise segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hardware fabrication concentrates in East Asian semiconductor clusters, while voice data processing infrastructure and end-user demand distribute across North American and European metropolitan markets. This geographic split shapes regulatory compliance architectures and supply chain risk profiles for ecosystem participants.
United States
Suburban single-family homes drive device-per-household expansion beyond living-room speakers into kitchens, bedrooms, and outdoor spaces. FCC radio frequency emission standards govern far-field microphone array hardware certification. Seattle and San Francisco Bay Area clusters anchor cloud infrastructure deployment for voice processing backends serving North American latency benchmarks.
Germany
Industrial OEMs integrate voice modules into building automation systems for commercial and residential climate control. EU AI Act biometric risk classification mandates documentation and human oversight for emotion recognition features. Munich and Stuttgart engineering centers specialize in on-device speech processing architectures that satisfy GDPR data minimization principles.
China
Domestic smart speaker manufacturing scales through Shenzhen and Dongguan electronics corridors serving both local consumption and export assembly. MIIT radio equipment type approval and GB standards regulate wireless transmission parameters. Shanghai and Beijing house natural language processing R&D operations targeting Mandarin intent parsing and dialect localization.
United Kingdom
Professional installer networks handle enterprise healthcare deployments with ISO/IEC 27001 information security management system requirements. GDPR cross-border voice recording retention restrictions force architecture redesigns for cloud-dependent assistants. London fintech and Cambridge technology clusters adopt hybrid edge-cloud voice systems for security-sensitive financial services verticals.
India
Smart city infrastructure projects incorporate voice-controlled municipal service interfaces in urban development schemes. TRAI data localization guidelines shape voice recording storage architecture decisions for foreign platform operators. Bangalore and Hyderabad technology corridors concentrate multilingual NLP engineering talent for Indic language voice assistant localization.
Smart Home Digital Assistant [Voice] Market Competitive Environment
Top-tier vendors anchor platform ecosystems, while mid-tier hardware fabricators compete on component cost and regional distribution reach. The vendor base stratifies across three tiers: cloud-native platform operators with recurring service revenue, consumer electronics conglomerates with captive device channels, and specialized semiconductor suppliers with neural processing unit IP. Strategic moves center on M&A for NLP talent acquisition and backward integration into MEMS microphone component supply.
Within the cloud-native platform tier, Amazon.com, Inc. and Google LLC occupy positions defined by search-to-action continuity and smart home commerce anchoring. Apple Inc. represents the privacy-centric architecture archetype with on-device processing differentiation. These three entities exemplify the strategic divergence between cloud-dependent and edge-native technical trajectories reshaping competitive dynamics.
| Leading Market Players |
|---|
| Amazon.com, Inc. |
| Google LLC |
| Apple Inc. |
| Samsung Electronics Co., Ltd. |
| Microsoft Corporation |
| Alibaba Group Holding Limited |
| Xiaomi Corporation |
| Baidu, Inc. |
| Yandex |
| Others |
Value Chain & Pricing Dynamics
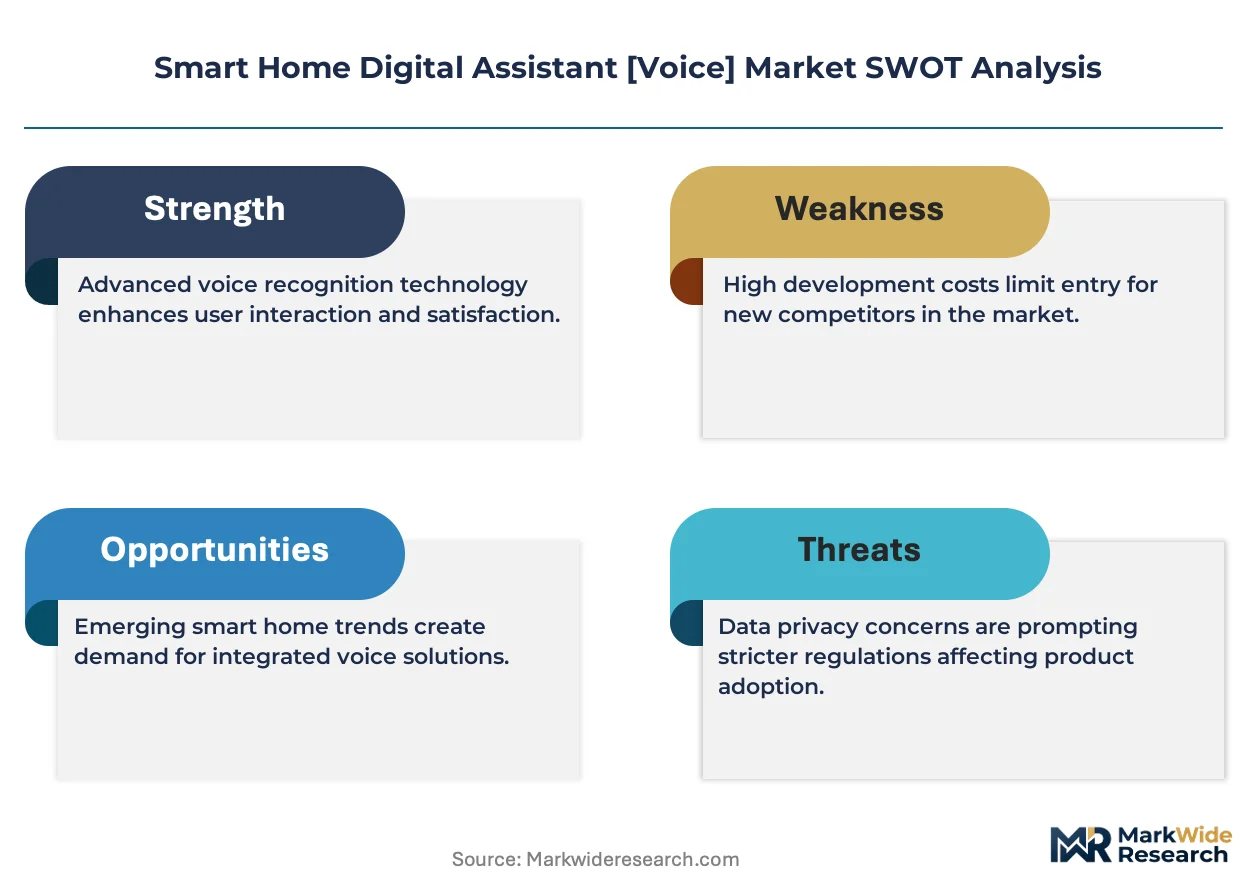
EU AI Act biometric risk classification mandates are forcing European OEMs to absorb premium costs for auditable on-device processing architectures, compelling hardware suppliers to reconfigure component sourcing around neural processing unit integration and compressing margins on cloud-dependent smart speaker tiers.
Pricing Analysis
Short lead-time premiums for MEMS microphone arrays and neural processing units command 15-25 percent markups over standard procurement cycles as East Asian foundry capacity tightens. Three-tier pricing structure across premium on-device inference, standard hybrid edge-cloud, and economy cloud-only tiers separates security-sensitive enterprise buyers from mass-market consumers. Pricing pressure stems from GDPR data minimization compliance costs that force architecture redesigns for multi-jurisdiction deployments. Renters and transient users exhibit highest price sensitivity, while homeowners with dedicated smart home infrastructure accept premium positioning for integrated climate and security subsystem compatibility.
Supply Chain Analysis
Regional distribution centers in Shenzhen, Dongguan, and Shanghai anchor hub-and-spoke patterns for smart speaker hardware assembly serving North American and European end markets. Taiwan, South Korea, and China concentrate MEMS microphone fabrication and neural processing unit design, creating single-source vulnerability for far-field array components. Raw material dependencies include rare earth elements for magnet assemblies, silicon wafers for semiconductor foundry feedstock, and lithium-ion cells for portable device power management. Distribution runs through certified installer networks in the United States and United Kingdom for enterprise healthcare deployments, while direct-to-consumer retail channels dominate suburban single-family residential volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid edge-cloud architectures are displacing cloud-only voice processing as the dominant technical trajectory, with on-device large language model inference replacing legacy centralized natural language processing engines across security-sensitive verticals.
For Market Incumbents: To counter margin compression from neural processing unit cost inflation, Amazon and Google must deepen backward integration into MEMS microphone component supply and accelerate ISO/IEC 27001 certification for enterprise healthcare segments. Defensive capacity expansion in Taiwan and South Korea semiconductor clusters secures foundry allocation priority. Channel control through certified installer network exclusivity preserves service attach rates in regulated North American and European markets. For New Entrants and Emerging Players: Municipal procurement officers in Indian smart city infrastructure projects represent an underserved buyer archetype with limited incumbent penetration and simplified technical requirements compared to residential ecosystem complexity. White-space targets include voice-controlled public service kiosks and urban climate monitoring interfaces. Go-to-market execution through systems integrators with existing municipal relationships bypasses direct consumer brand building costs. For Investors and Strategic Acquirers: The window for entry favors computational linguistics talent pools and neural processing unit IP holders before incumbent platform operators complete acquisition cycles. Long-term viability hinges on hybrid architecture deployment share across healthcare and financial services verticals with strict data residency requirements. Watch ETSI interoperability mandate implementation timelines as inflection indicators for middleware provider valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| On-Device LLM Integration | Neural processing unit deployment satisfies EU AI Act biometric risk classification for German and French healthcare verticals. |
| MEMS Microphone Backward Integration | Captive supply of far-field array components insulates against East Asian foundry capacity constraints and tariff exposure. |
| ETSI Interoperability Certification | Cross-platform voice skill compatibility opens middleware revenue streams between locked Amazon, Google, and Apple ecosystems. |
| ISO/IEC 27001 Compliance Investment | Information security management system certification enables 8-14 month faster deployment in regulated United States enterprise segments. |
| Indian Smart City Partnership | TRAI data localization guidelines favor local voice processing infrastructure in Bangalore and Hyderabad technology corridors. |
Study Parameters
SEC filings from Amazon, Google, Apple, and Samsung, ETSI technical standards documentation, and FCC equipment authorization databases formed the secondary backbone, supplemented by customs records tracking MEMS microphone and neural processing unit trade flows. Primary interviews with smart home platform engineering directors, enterprise healthcare IT procurement officers, certified installer network managers, and computational linguistics R&D leads validated hardware bill-of-materials cost structures and deployment timeline assumptions. Bottom-up device shipment modeling and top-down service revenue aggregation were triangulated against cloud infrastructure capex disclosures.
Historical trendline analysis of smart speaker installed base expansion and voice skill transaction velocity informed projection framework construction across the analysis window. Segmentation dimensions modeled include product type, processing architecture, end-user category, and installation channel, with particular attention to hybrid edge-cloud versus cloud-only technology trajectories. CAGRs were derived from S-curve adoption pattern fitting for suburban single-family penetration rates and multilingual NLP capability rollout schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act enforcement severity, GDPR cross-border data ruling interpretations, and East Asian semiconductor supply disruption scenarios. Outputs reflect documented assumptions around voice assistant ecosystem lock-in persistence and professional installation channel growth. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Digital Intelligence Technology Market
Artificial Intelligence (AI)
Context Aware Computing Market
Artificial Intelligence (AI)
Artificial Intelligence for IT Operations (Aiops) Market
Artificial Intelligence (AI)
Cloud Computing Artificial Intelligence (AI) Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) in Food and Beverages Market
Artificial Intelligence (AI)
Adaptive AI Market
Artificial Intelligence (AI)
AI Industrial Defect Detection Market
Artificial Intelligence (AI)
Affective Computing Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Oil and Gas Market
Artificial Intelligence (AI)
Asia-Pacific Generative AI Market
Artificial Intelligence (AI)
Automated Data Annotation Tool Market
Artificial Intelligence (AI)
Natural Language Processing in BFSI Market
Artificial Intelligence (AI)
Artificial Intelligence in Transportation Market
Artificial Intelligence (AI)
Global Cognitive Operations Market
Artificial Intelligence (AI)
Edge AI Market
Artificial Intelligence (AI)
Artificial Intelligence in Telecommunication Market