
 Robotic Paint Booth Market | 2026-2036
Robotic Paint Booth Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic Paint Booth Market Intelligence
Buyer concentration among automotive OEMs is shifting as tier-one suppliers and specialty coating shops fragment procurement across smaller batch operations. Dürr Group leverages its captive engineering network to dominate turnkey booth installations for European automakers. FANUC Corporation anchors high-volume robot arm supply through deep partnerships with Japanese paint system integrators. KUKA Aktiengesellschaft competes on modular configurations that let mid-size manufacturers scale cell capacity without greenfield construction.
A robotic paint booth is an enclosed environment integrating multi-axis robotic arms, atomizers, and ventilation systems to apply liquid or powder coatings with programmed precision across complex geometries. These systems maintain controlled temperature, humidity, and airflow to ensure film uniformity while capturing overspray through filtration or water-wash separation. Electrostatic spray technology leads installed base volume due to its transfer efficiency and material savings on metal substrates. AI-Powered Systems represent the fastest-expanding technology segment as machine learning optimizes path planning and reduces rework rates in real time. Fixed systems still occupy the majority of revenue pools, though modular configurations are capturing margin from manufacturers seeking reconfigurable floor space.
EPA emission standards and OSHA permissible exposure limits for hexavalent chromium and isocyanates are forcing booth upgrades with advanced filtration and sealed robot enclosures. REACH compliance in Europe adds material traceability requirements that favor suppliers with integrated coating chemistry and equipment portfolios. Stakeholders must monitor how collaborative robotics certifications evolve to determine whether human-robot co-presence in paint cells becomes economically viable for low-volume custom finishing.
Market Dynamics
Automotive OEMs are fragmenting procurement across tier-one suppliers and specialty coating shops, compressing order sizes while demanding modular booth configurations that adapt to volatile production schedules without greenfield construction.
Growth Catalysts
- EPA Emission Standards:Tightening VOC limits in the United States force booth upgrades with advanced filtration and sealed robot enclosures, creating replacement demand across existing installed base.
- Electrostatic Spray Technology:Transfer efficiency advantages on metal substrates drive retrofit cycles in automotive stamping and appliance manufacturing operations.
- German Supply Clusters:Concentrated engineering capabilities around Stuttgart and Cologne anchor turnkey installation capacity for European vehicle manufacturers expanding automated finishing lines.
Market Restraints
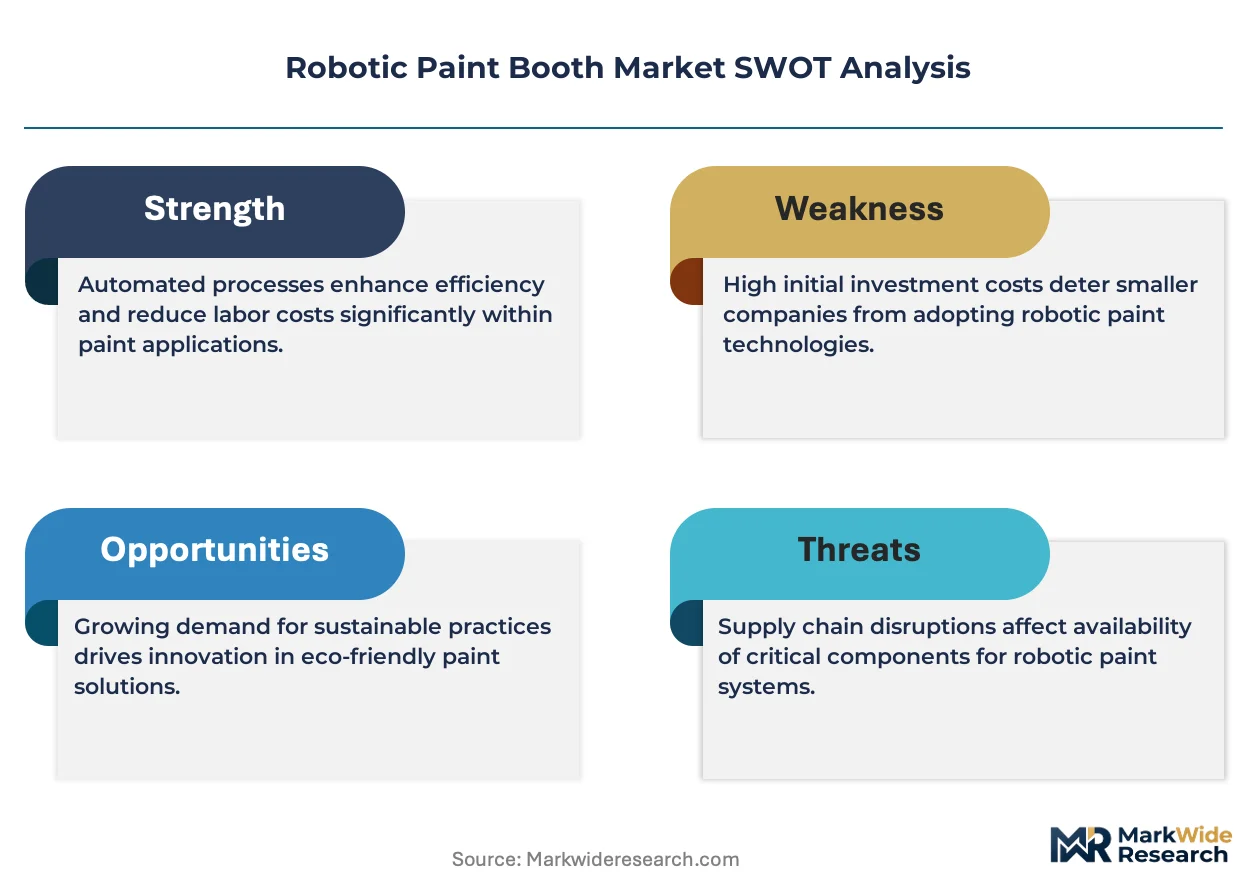
- Capital Equipment Intensity:Full booth installations require substantial upfront outlay for ventilation, filtration, and robotic integration, stretching payback periods for mid-size manufacturers.
- Specialized Integration Talent:Scarcity of engineers capable of programming multi-axis path planning for complex geometries limits deployment velocity outside established automotive hubs.
- REACH Material Traceability:European coating chemistry documentation requirements favor integrated suppliers, squeezing standalone booth vendors without captive chemistry portfolios.
Strategic Opportunities
- AI-Powered Path Planning:Machine learning integration with existing robot arms enables real-time rework reduction, opening retrofit revenue from installed base customers.
- Collaborative Robotics Certification:Pending OSHA and ISO safety standard evolution for human-robot co-presence could unlock low-volume custom finishing cells currently uneconomical to automate.
- Modular Floor Space Reconfiguration:Mid-size manufacturers in Japan seek cell capacity scaling without facility expansion, favoring vendors with standardized sub-assembly designs.
Industry Challenges
- Hexavalent Chromium Compliance:OSHA permissible exposure limits for isocyanates and heavy metals demand sealed enclosure redesigns, extending engineering validation timelines.
- Legacy System Integration:Brownfield automotive plants require booth retrofits compatible with existing conveyor and SCADA architectures, complicating vendor qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotic Paint Booth Market |
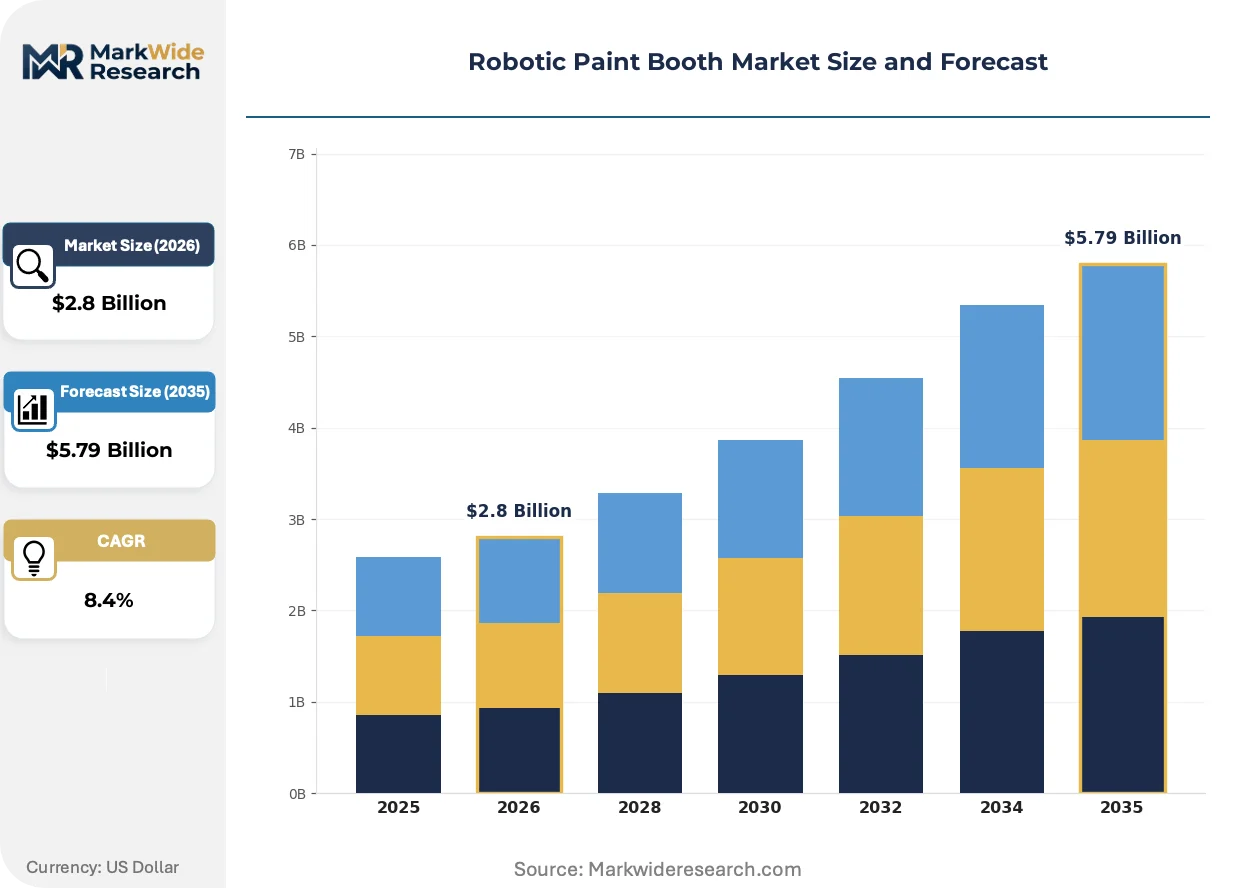
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrostatic Spray, Automated Roller, Automated Dip, Powder Coating Technology: Industrial Robotics, Collaborative Robotics, Machine Vision, AI-Powered Systems End User: Automotive Manufacturers, Aerospace Producers, Consumer Goods, Electronics Assemblers Installation: On-Premises, Mobile Units, Fixed Systems, Modular Configurations |
| Companies Covered | ABB Ltd, FANUC Corporation, KUKA Aktiengesellschaft, Yaskawa Electric Corporation, Dürr Group, Kawasaki Heavy Industries, Eisenmann GmbH, Stäubli International AG, CMA Robotics Spa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic Paint Booth Market Strategic Shifts & Innovations
Machine learning is compressing the gap between simulation and production reality, while regulatory pressure on worker safety and emissions accelerates hardware refresh cycles beyond traditional depreciation schedules.
Electrostatic spray technology is consolidating its position as the dominant coating method for metal substrates in high-volume automotive and appliance manufacturing. Tier-one suppliers are adopting integrated atomizer-robot packages to reduce material waste and film thickness variation. The technology is consolidating vendor margins around transfer efficiency guarantees rather than equipment hardware alone.
REACH compliance in Europe adds material traceability requirements that favor suppliers with integrated coating chemistry and equipment portfolios. Booth vendors without captive chemistry capabilities face procurement friction as automotive OEMs consolidate supplier audits. German and French automakers are responding by qualifying fewer turnkey providers with full-stack documentation capabilities.
Buyer concentration patterns are fragmenting as tier-one suppliers and specialty coating shops displace direct OEM procurement for smaller batch operations. Distributors serving custom finishing and aerospace MRO channels are capturing margin previously held by direct manufacturer sales forces. This pattern is most visible in Germany and Japan where mid-size job shops cluster around automotive and precision manufacturing supply chains.
Robotic Paint Booth Market Segmentation
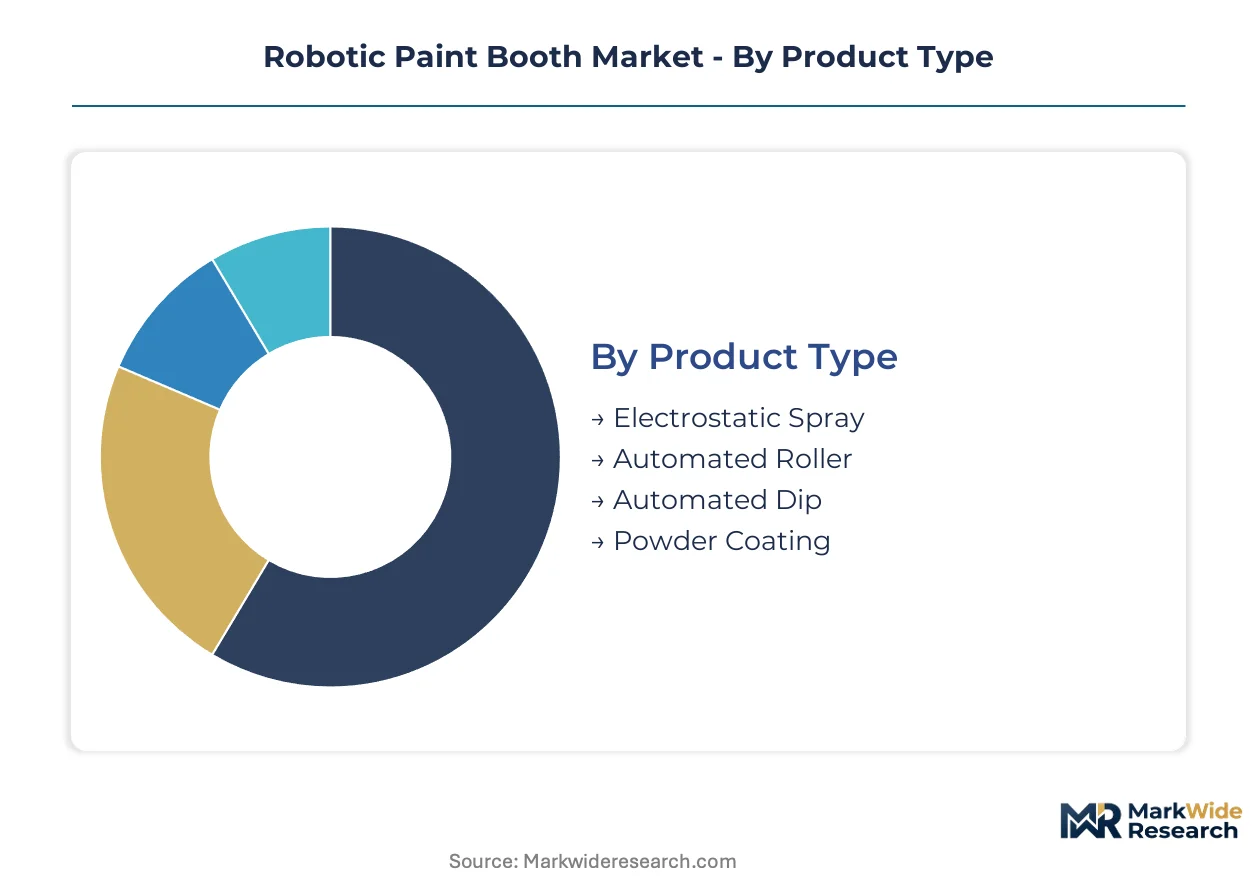
Segmentation in robotic paint booth systems reflects how coating specifications, production scale, and facility constraints fragment procurement decisions across automotive, aerospace, and precision manufacturing verticals. Understanding these axes reveals where equipment suppliers concentrate R&D investment and which configurations command premium pricing.
Product Type:
Coating method selection hinges on substrate material, transfer efficiency requirements, and overspray recovery economics.
- Electrostatic Spray:Charged atomizers deposit liquid coatings onto grounded metal substrates with transfer efficiency exceeding conventional air spray. Automotive stamping operations in Germany and Japan favor this method for material savings on high-volume body-in-white lines. EPA VOC limits accelerate retrofit demand from legacy air-atomized installations.
- Powder Coating:Thermoset or thermoplastic powders fuse to metal surfaces through electrostatic attraction and oven curing, eliminating solvent emissions entirely. Appliance manufacturers in the United States specify powder systems to meet California Air Resources Board standards without carbon-bed filtration.
- Automated Roller:Precision roller applicators deposit uniform liquid films onto flat or gently curved panels. Metal furniture and shelving producers deploy roller booths for consistent mil thickness on repetitive geometries.
- Automated Dip:Submersion systems coat complex hollow sections and internal cavities inaccessible to spray nozzles. Agricultural equipment manufacturers specify dip configurations for chassis components requiring complete edge coverage.
Electrostatic spray leads on scale; AI-powered path planning is accelerating momentum across all product categories.
Technology:
Automation architecture determines programming complexity, cycle time flexibility, and integration with existing manufacturing execution systems.
- Industrial Robotics:Six-axis articulated arms with 20-50 kg payload capacity execute high-speed spray trajectories across automotive body shells. FANUC and KUKA installations dominate European and Japanese OEM lines where throughput exceeds 60 jobs per hour.
- AI-Powered Systems:Machine learning algorithms optimize spray paths in real time based on 3D vision feedback, reducing rework rates and material overconsumption. Tier-one suppliers in Germany pilot these systems for mixed-model production where part geometries vary shift-to-shift.
- Collaborative Robotics:Force-limited arms with simplified programming interfaces enable human-robot co-presence in low-volume finishing cells. OSHA and ISO safety standard evolution will determine adoption viability for custom aerospace MRO applications.
- Machine Vision:3D scanning and defect detection systems guide robot positioning and quality verification. Electronics assemblers integrate vision modules for micron-level coating uniformity on circuit board enclosures.
Industrial robotics commands installed base volume; AI-powered systems are expanding most quickly as retrofit upgrades.
End User:
Buyer technical sophistication and batch size requirements fragment procurement across direct OEM and tiered supplier channels.
- Automotive Manufacturers:OEMs specify turnkey booth installations with integrated conveyor, filtration, and SCADA architectures. German and Japanese automakers consolidate supplier audits around vendors with captive chemistry documentation capabilities.
- Aerospace Producers:Low-volume, high-mix operations demand modular configurations adaptable to airframe sections ranging from control surfaces to full fuselage barrels. Specialty coating shops serving Boeing and Airbus supply chains capture margin previously held by direct manufacturer sales forces.
- Consumer Goods:Appliance and furniture manufacturers prioritize transfer efficiency and film thickness consistency over cycle time optimization. Powder coating penetration is highest in this segment due to durability requirements and regulatory pressure on solvent emissions.
- Electronics Assemblers:Precision coating of enclosures and heat sinks requires controlled humidity environments and electrostatic discharge protection. Cleanroom-compatible booth designs command premium pricing in this segment.
Automotive manufacturers anchor procurement volume; aerospace producers are driving modular configuration innovation.
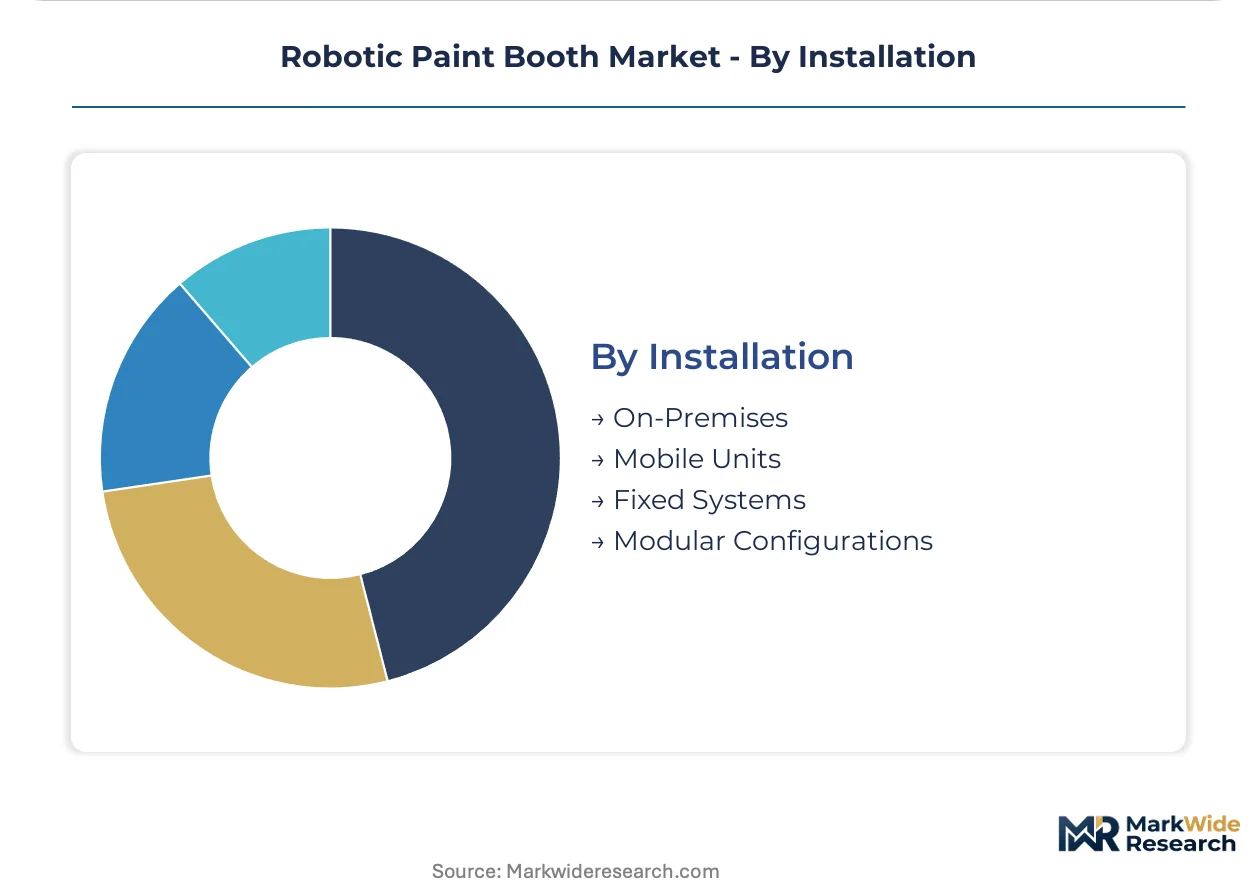
Installation:
Facility constraints and production volatility determine whether manufacturers favor permanent infrastructure or reconfigurable assets.
- Fixed Systems:Permanent installations with dedicated ventilation and conveyor integration serve high-volume, stable product mixes. These configurations occupy the majority of revenue pools in established automotive stamping plants.
- Modular Configurations:Standardized sub-assemblies enable capacity scaling without greenfield construction or facility expansion. Mid-size manufacturers in Japan and Germany favor modular designs for volatile production schedules.
- On-Premises:Customer-site installation with full utility integration and regulatory compliance validation. Brownfield automotive plants require retrofits compatible with existing building footprints and emissions permits.
- Mobile Units:Containerized or trailer-mounted booths deploy to MRO facilities, construction sites, or temporary production surges. Wind turbine blade manufacturers utilize mobile powder coating for field repair operations.
Fixed systems dominate current revenue; modular configurations are gaining share fastest among mid-size manufacturers seeking floor space flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Stuttgart, Nagoya, and Detroit anchor automated finishing line development for automotive OEMs. These concentrations supply specialized integrators capable of programming multi-axis path planning for complex vehicle geometries. Regional procurement patterns fragment further as tier-one suppliers displace direct OEM orders.
Germany
Automotive OEMs in Baden-Württemberg and North Rhine-Westphalia expand automated stamping lines to manage volatile production schedules. REACH compliance mandates material traceability documentation that favors turnkey providers with captive chemistry portfolios. The Stuttgart engineering corridor concentrates Dürr Group and Eisenmann GmbH installations serving BMW, Mercedes-Benz, and Volkswagen supply chains.
United States
EPA VOC emission limits force booth upgrades with advanced filtration and sealed robot enclosures across legacy automotive plants. OSHA permissible exposure limits for hexavalent chromium demand enclosure redesigns extending engineering validation timelines. The Detroit-Windsor corridor anchors brownfield retrofit demand as Ford, General Motors, and Stellantis reconfigure existing conveyor architectures.
Japan
METI industrial automation incentives support mid-size manufacturers scaling cell capacity without greenfield construction. FANUC Corporation leverages deep partnerships with domestic paint system integrators to supply high-volume robot arm installations. The Nagoya-Toyota City corridor concentrates electrostatic spray retrofits for mixed-model production lines.
China
MIIT smart manufacturing directives accelerate AI-powered path planning pilots for real-time rework reduction. Dual carbon goals pressure domestic automakers toward powder coating systems eliminating solvent emissions entirely. The Yangtze River Delta clustering around Shanghai supplies modular booth configurations for electric vehicle startups scaling without facility expansion.
South Korea
MFDS workplace chemical exposure standards tighten compliance requirements for isocyanate-handling booth designs. Hyundai and Kia supply chains drive demand for integrated atomizer-robot packages reducing film thickness variation. The Ulsan-Busan industrial corridor anchors high-throughput installations exceeding sixty jobs per hour on dedicated SUV and EV platforms.
Robotic Paint Booth Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across fragmented procurement channels. Tier-one suppliers and specialty coating shops displace direct OEM relationships, compressing order sizes while demanding modular configurations. Three archetypes dominate: integrated turnkey providers with captive chemistry documentation, robot arm manufacturers partnering through system integrators, and modular sub-assembly specialists enabling floor-space reconfiguration. Competitive moves concentrate on strategic partnerships for AI-powered path planning integration and geographic expansion through distributor networks serving custom finishing channels.
Within the integrated turnkey tier, Dürr Group and Eisenmann GmbH exemplify providers anchoring European automotive supply chains with full-stack documentation capabilities. FANUC Corporation occupies a position among robot arm manufacturers leveraging deep partnerships with Japanese paint system integrators for high-volume installations. KUKA Aktiengesellschaft represents the modular configuration archetype, enabling mid-size manufacturers to scale cell capacity without greenfield construction.
| Leading Market Players |
|---|
| ABB Ltd |
| FANUC Corporation |
| KUKA Aktiengesellschaft |
| Yaskawa Electric Corporation |
| Dürr Group |
| Kawasaki Heavy Industries |
| Eisenmann GmbH |
| Stäubli International AG |
| CMA Robotics Spa |
| Others |
Cost & Logistics Intelligence
Steel and filtration media costs cascade through turnkey booth pricing tiers, with German and Japanese engineering premiums separating high-integration providers from modular sub-assembly vendors serving mid-size manufacturers.
Pricing Analysis
Bundled turnkey installations command premiums over unbundled robot-arm-and-ventilation packages. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Cost compression in economy tiers is intensifying because mid-size manufacturers in Japan and Germany seek reconfigurable floor space without captive chemistry portfolios. Tier-one suppliers show least price sensitivity due to consolidated supplier audits; specialty coating shops drive hardest bargain for modular configurations.
Supply Chain Analysis
Domestic-content mandates in China and South Korea are reshaping sourcing for AI-powered path planning modules and electrostatic atomizer components. Engineering talent clusters draw from Germany, Japan, and the United States for multi-axis integration expertise. Raw material dependencies rest on specialty steel for enclosures, high-efficiency filtration media, and precision servo motors. Single-source vulnerability concentrates around FANUC and KUKA robot arm supply for high-throughput automotive lines. Distribution runs through certified system integrators anchoring regional installation capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as automotive OEMs consolidate supplier audits around vendors with full-stack REACH documentation and captive chemistry capabilities.
For Market Incumbents: Extend engineering validation capabilities to compress lead times for sealed enclosure redesigns demanded by OSHA hexavalent chromium limits. Backward integration into filtration media production defends margin position against commodity volatility. Dürr Group and Eisenmann GmbH anchor this consolidation logic through Stuttgart engineering corridors. For New Entrants and Emerging Players: Launch via distributor networks serving aerospace MRO and custom finishing channels where direct OEM relationships fragment. White-space concentrates in mobile powder coating units for wind turbine blade field repairs and collaborative robotics pilots pending ISO safety certification. Japan and Germany offer most penetrable modular configuration demand from mid-size job shops. For Investors and Strategic Acquirers: Roll-up economics work for regional system integrators because tier-one supplier procurement fragmentation creates acquisition targets with captive customer relationships. Five-to-ten year viability hinges on AI-powered retrofit revenue from installed base customers. Signal to monitor: OSHA collaborative robotics standard finalization unlocking low-volume custom finishing automation economics.| Strategic Initiative | Industry Significance |
|---|---|
| AI Path Planning Integration | Machine learning retrofits reduce rework rates for German automotive stamping operations. |
| Modular Configuration Scale-Up | Standardized sub-assemblies capture Japanese mid-size manufacturer floor space flexibility demand. |
| Captive Chemistry Documentation | REACH compliance capabilities consolidate European OEM supplier audits around turnkey providers. |
| Collaborative Robotics Certification | Pending OSHA standards unlock aerospace MRO human-robot co-presence economics. |
| Mobile Unit Deployment | Containerized booths serve wind turbine field repair operations without fixed infrastructure. |
Research Approach
Coverage spans Germany, Japan, the United States, China, and South Korea, with primary inputs from each market combining interviews with paint system integrators, automotive OEM procurement teams, aftermarket service heads, and plant engineers with secondary validation against EPA emission filings, MIIT smart manufacturing directives, METI industrial automation disclosures, and customs trade data. Bottom-up equipment shipment analysis triangulates against top-down automotive production capacity modeling.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions include coating method, automation architecture, end-user vertical, and installation configuration. CAGRs derive from installed base replacement cycles, regulatory-driven upgrade mandates, and greenfield capacity additions. Industry-specific inputs incorporate REACH material traceability timelines and OSHA permissible exposure limit enforcement patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under collaborative robotics standard delays or acute specialty steel supply disruptions. Forecasts reflect documented assumptions about regulatory enforcement intensity and automotive production volatility. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Warehouse Automation Solutions Market
Industrial Automation
Sortation Systems Market
Industrial Automation
Intelligent Conveyor System Market
Industrial Automation
Industry 4.0 Market
Industrial Automation
Industrial Robotic Motors Market
Industrial Automation
Europe ICS Market
Industrial Automation
Global Industrial Automation and Control Systems Market
Industrial Automation
Intralogistics Market
Industrial Automation
Industrial Internet Connectivity Tracker Market
Industrial Automation
North America Industrial Automation Market
Industrial Automation
Asia Pacific Manufacturing Execution Systems (MES) Market
Industrial Automation
Conveyor-Free Sortation Modules Market
Industrial Automation
Distribution Feeder Automation Market
Industrial Automation
Safety Programmable Controller Market
Industrial Automation
Global Distribution Feeder Automation System Market
Industrial Automation
Latin America Process Automation Market