
 AI Document Generator Market | 2026-2036
AI Document Generator Market Size, Share, and Industry Trends Forecast 2026-2036
AI Document Generator Market Insights
EU AI Act transparency requirements is realigning vendor investment toward explainable output pipelines and audit-ready generation logs. Microsoft leverages its Azure cloud infrastructure to anchor enterprise deployments with embedded compliance tooling. Google differentiates through native multimodal capabilities that extend document synthesis into visual and tabular formats. IBM specializes in regulated industries where Watsonx governance modules sustain procurement confidence among risk-averse buyers.
An AI document generator is a software system that employs large language models, retrieval-augmented generation architectures, and structured template engines to autonomously produce formatted text documents from natural language prompts or structured data inputs, operating at throughput rates measured in thousands of pages per hour for enterprise workloads. Cloud-based deployment leads solution delivery due to elastic scaling demands during quarterly reporting cycles, though hybrid configurations capture margin pools from defense and healthcare buyers with data residency constraints. Natural language generation dominates solution offerings for high-volume contract and report production, while data extraction capabilities represent the fastest-expanding segment as enterprises seek to repurpose legacy document repositories into structured knowledge bases.
FDA guidance on machine learning-based software as a medical device shapes clinical trial documentation standards, while SEC disclosure rules pressure financial reporting automation vendors to embed provenance tracking. EMA parallel requirements for pharmacovigilance report consistency create dual-jurisdiction compliance burdens for multinational pharmaceutical adopters. Stakeholders must evaluate whether their current vendor's regulatory roadmap covers emerging algorithmic accountability frameworks before committing to long-term enterprise licensing structures.
Market Dynamics
EU AI Act documentation mandates are compressing vendor roadmaps toward audit-ready generation pipelines, forcing platform providers to embed provenance tracking and explainability layers as core architecture rather than aftermarket modules.
Growth Catalysts
- EU AI Act compliance deadlines:Financial services legal departments in Frankfurt, Paris, and Amsterdam are procuring contract automation platforms with embedded decision logs to satisfy algorithmic accountability requirements.
- Retrieval-augmented generation architectures:Enterprise IT teams are replacing static template engines with RAG pipelines that ground outputs in verified document corpora, reducing hallucination risk for regulated communications.
- Quarterly reporting cycle compression:Public company finance functions in the United States are scaling cloud-based deployment to handle 10x document volume spikes during earnings periods without permanent infrastructure expansion.
Market Restraints
- GPU cluster cost volatility:Training and inference workloads for billion-parameter models face input cost swings tied to NVIDIA H100 supply allocation and cloud provider spot pricing mechanics.
- Data residency enforcement:Defense and healthcare buyers in Germany, France, and Italy are mandating hybrid configurations that fragment vendor economies of scale and extend implementation timelines.
- Substitution by human legal review:High-stakes M&A documentation in London and New York continues to require partner-level sign-off, capping automation penetration at junior associate workflows.
Strategic Opportunities
- Pharmacovigilance automation in Basel and Boston:EMA and FDA parallel requirements for adverse event report consistency create dual-jurisdiction demand for standardized generation templates.
- Multimodal synthesis convergence:Native integration of visual, tabular, and textual generation is opening clinical trial documentation and regulatory submission workflows previously served by separate tools.
- India's BIS standardization push:The Bureau of Indian Standards is developing AI documentation guidelines that will mandate structured output formats for government procurement, creating first-mover advantage for compliant vendors.
Industry Challenges
- Prompt engineering talent scarcity:Enterprise implementation teams lack specialists capable of designing retrieval contexts that maintain factual consistency across thousand-page document sets.
- Legacy ECM integration friction:Documentum and SharePoint repositories in established enterprises require custom connector development that extends deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Document Generator Market |
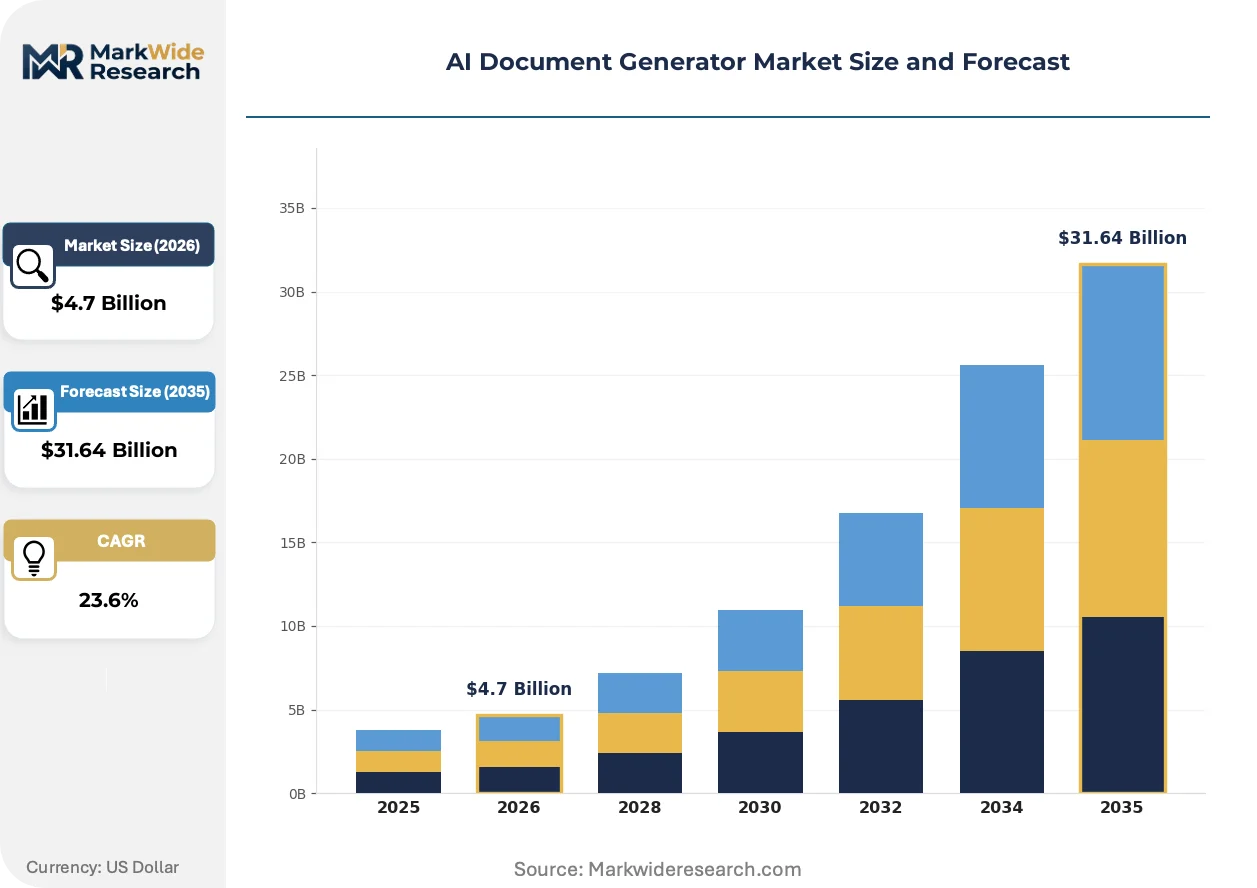
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $31.64 Billion |
| CAGR (2026 – 2036) | 23.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge Solution Offering: Template Automation, Natural Language Generation, Text Summarization, Data Extraction, Report Generation Use Case: Contract Creation, Financial Reporting, Legal Document Drafting, Marketing Content, Technical Manuals Customer Type: Enterprises, Small and Medium Businesses, Educational Institutions, Government Agencies |
| Companies Covered | Microsoft, Google, IBM, Adobe, Salesforce, DocuSign, UiPath, Templafy, Jotform, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Document Generator Market Trends and Innovations
Foundation model capabilities are expanding from text synthesis into structured data interpretation, compressing the traditional boundary between document generation and business intelligence tooling.
Multimodal large language models are expanding into visual and tabular document formats, enabling automated generation of FDA-compliant clinical study reports that integrate statistical graphics with narrative sections. Pharmaceutical regulatory affairs teams in Research Triangle Park and Basel are piloting these pipelines for IND submissions. The technology is expanding into workflows previously requiring separate biostatistics and medical writing functions.
SEC disclosure rules on machine learning transparency are mandating provenance tracking for algorithmically generated financial statements, forcing vendors to embed immutable audit logs. The regulation compresses vendor differentiation toward compliance infrastructure rather than raw generation quality. Financial reporting automation platforms serving Fortune 500 filers are responding by partnering with blockchain-based attestation services.
Enterprise buying committees are unbundling document generation from adjacent workflow automation, contracting directly with specialized LLM providers rather than monolithic enterprise suites. This pattern displaces traditional software reseller margins and concentrates procurement authority within central IT architecture teams. The shift is most visible in United States healthcare systems renegotiating EHR-embedded documentation tools.
AI Document Generator Market Segmentation
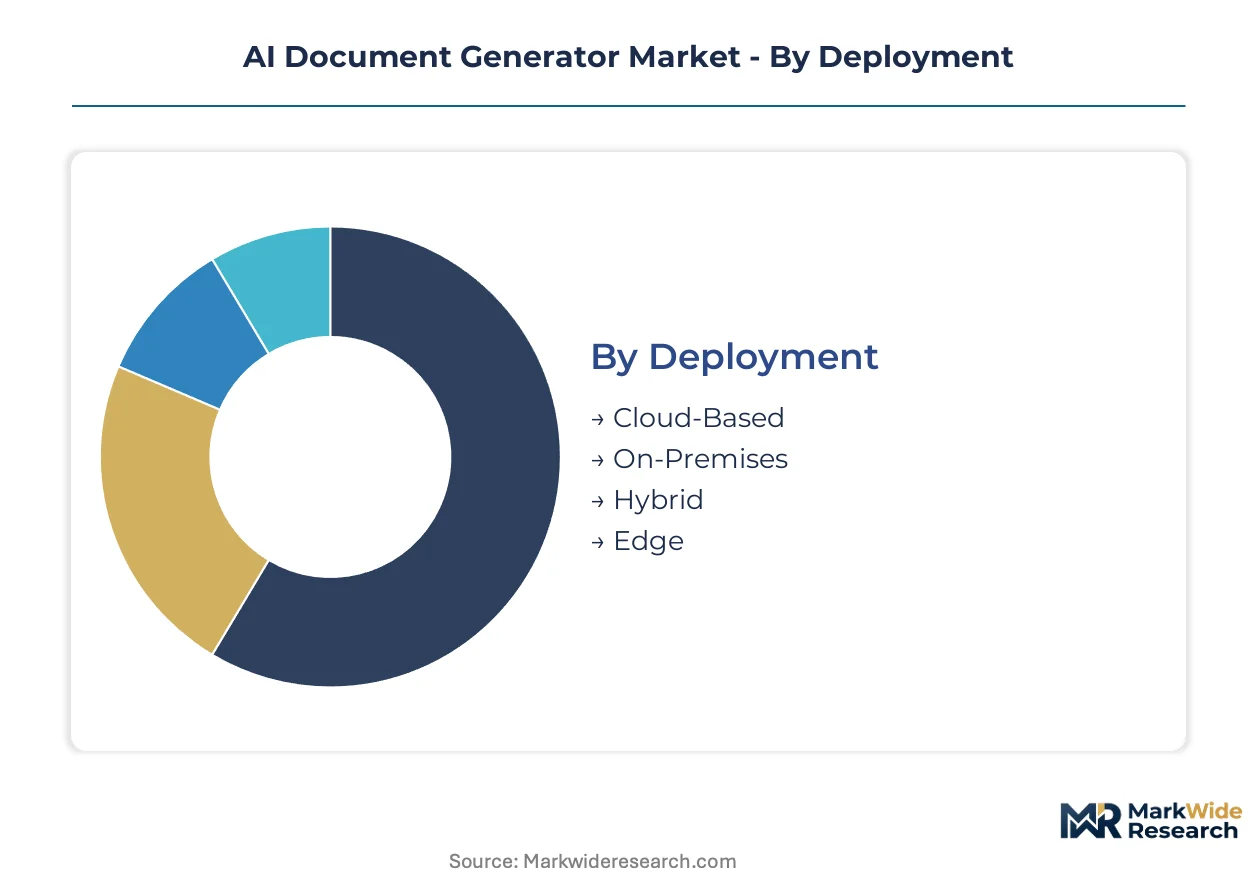
Segmentation in the AI document generator market reveals distinct integration patterns across deployment architectures and solution layers. Buyers choose between standalone platforms and embedded modules based on data sensitivity, workflow complexity, and compliance jurisdiction.
Deployment:
Integration depth varies sharply—cloud deployments operate as fully external services while edge configurations embed directly into endpoint devices.
- Cloud-Based:Elastic compute pools handle quarterly reporting spikes for US public companies without permanent infrastructure. Financial services procurement in New York and Chicago prioritizes this model for contract automation at scale.
- Hybrid:Split architectures keep sensitive data on-premises while routing generation workloads to cloud inference clusters. German defense contractors and Italian healthcare networks mandate this configuration for data residency compliance.
- On-Premises:Air-gapped installations serve classified environments and critical infrastructure operators with zero external data transmission.
- Edge:Embedded models run on local hardware for field documentation in remote energy extraction sites and maritime operations with intermittent connectivity.
Volume placements concentrate in Cloud-Based configurations; the faster expansion belongs to Hybrid as residency requirements proliferate.
Solution Offering:
Cost tiering separates commodity template tools from premium generative systems with retrieval-augmented grounding.
- Natural Language Generation:Large language models synthesize narrative prose from structured inputs at throughput rates exceeding thousands of pages hourly. Legal departments in Frankfurt and Paris deploy these systems for EU AI Act-compliant contract drafting with embedded decision logs.
- Data Extraction:Computer vision and NLP pipelines parse legacy document repositories into structured knowledge bases. Pharmaceutical regulatory affairs teams in Basel and Research Triangle Park lead adoption for pharmacovigilance report standardization.
- Template Automation:Rule-based engines populate predefined document structures with database fields for high-volume transactional paperwork.
- Text Summarization:Abstractive and extractive models compress lengthy regulatory filings and research literature into executive briefings.
- Report Generation:Integrated pipelines combine narrative synthesis with tabular and visual elements for clinical study and financial disclosure documents.
Revenue concentration sits with Natural Language Generation; Data Extraction is climbing the fastest as enterprises digitize legacy archives.
Use Case:
Application maturity spans from routine administrative tasks to high-stakes regulated communications with partner-level review requirements.
- Contract Creation:Automated clause assembly and risk-flagging accelerates procurement and employment documentation. EU financial services legal teams in Amsterdam and Frankfurt drive procurement with algorithmic accountability mandates.
- Financial Reporting:SEC disclosure rules pressure vendors to embed provenance tracking for machine-generated statements. Fortune 500 filers in the United States scale cloud deployments for earnings cycle compression.
- Legal Document Drafting:M&A and litigation support tools remain capped at junior associate workflows due to partner sign-off requirements in London and New York.
- Marketing Content:Brand-compliant copy generation scales digital asset production for e-commerce and media publishers.
- Technical Manuals:Structured documentation pipelines serve aerospace and industrial equipment manufacturers with version-controlled output.
Procurement volume favors Contract Creation; Financial Reporting shows the steepest expansion trajectory as regulatory transparency mandates tighten.
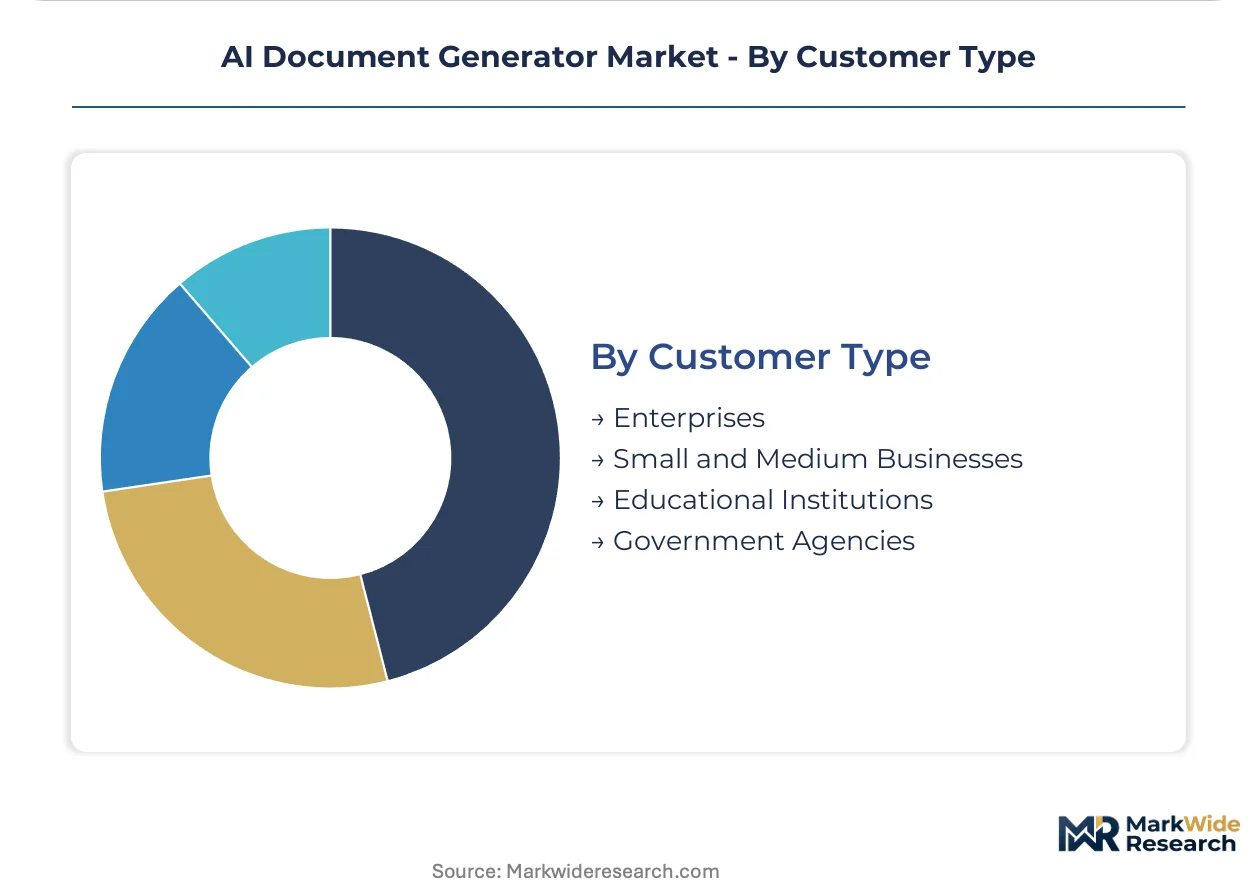
Customer Type:
Organizational scale determines solution complexity—enterprise buyers demand audit trails and governance modules while smaller adopters prioritize speed-to-deployment.
- Enterprises:Central IT architecture teams contract directly with specialized LLM providers, displacing traditional software reseller margins. Healthcare systems in the United States unbundle documentation tools from EHR suites.
- Government Agencies:India's BIS standardization push will mandate structured output formats for public procurement, creating compliant vendor preference. Defense and civilian agencies impose data residency and security clearance requirements.
- Small and Medium Businesses:SaaS subscriptions with per-seat pricing lower barriers for professional services and regional law practices.
- Educational Institutions:Research universities pilot multimodal synthesis for grant proposal and administrative document production.
Revenue concentration rests with Enterprises; Government Agencies are gaining share fastest as algorithmic accountability frameworks expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement concentrates in the United States, where Fortune 500 finance functions scale cloud deployments for earnings cycle compression. Frankfurt, Paris, and Amsterdam legal departments drive European adoption through EU AI Act compliance mandates. Basel and Research Triangle Park pharmaceutical clusters anchor specialized demand for regulatory documentation.
United States
SEC disclosure rules on machine learning transparency pressure vendors to embed provenance tracking for algorithmically generated financial statements. Fortune 500 filers scale cloud-based deployments to handle tenfold document volume spikes during quarterly reporting without permanent infrastructure expansion. Healthcare systems in Boston and the Research Triangle unbundle documentation tools from EHR suites, contracting directly with specialized LLM providers.
Germany
Defense contractors and automotive manufacturers mandate hybrid deployment configurations to satisfy data residency requirements under national security frameworks. The country's federal data protection authority enforces strict algorithmic accountability standards for automated decision documentation. Frankfurt's financial services legal departments procure contract automation platforms with embedded decision logs to satisfy EU AI Act mandates.
India
The Bureau of Indian Standards is developing AI documentation guidelines that will mandate structured output formats for government procurement, creating first-mover advantage for compliant vendors. Hyderabad and Bangalore IT services clusters pilot multimodal synthesis for administrative document production and grant proposal automation. Small and medium professional services firms adopt SaaS subscriptions with per-seat pricing to lower barriers for regional law practices.
Switzerland
Pharmaceutical regulatory affairs teams in Basel pilot multimodal large language models for FDA-compliant clinical study reports integrating statistical graphics with narrative sections. Swissmedic maintains parallel requirements with EMA for pharmacovigilance report consistency, creating dual-jurisdiction compliance burdens. The country's precision manufacturing sector drives demand for technical manual automation with version-controlled output pipelines.
United Kingdom
High-stakes M&A documentation in London continues to require partner-level sign-off, capping automation penetration at junior associate workflows. The Financial Conduct Authority consults on algorithmic transparency rules that would extend provenance tracking requirements to machine-generated regulatory filings. Edinburgh and Manchester legal services clusters adopt template automation for high-volume transactional paperwork.
AI Document Generator Market Competitive Landscape
United States technology conglomerates anchor one tier of the market; European and Asian specialists hold differentiated positions in regulated industry verticals. The vendor structure concentrates around cloud infrastructure providers with embedded compliance tooling, pure-play document automation platforms, and enterprise software suites unbundling documentation modules. Three archetypes dominate: hyperscale cloud platforms, vertical-specific governance specialists, and workflow-integrated productivity suites. Competitive moves center on strategic partnerships with blockchain attestation services and geographic expansion through compliance-first localization.
Among hyperscale cloud providers, Microsoft and Google exemplify the infrastructure-anchored archetype, while IBM occupies a position within the regulated industry specialist tier. These three companies represent divergent strategic postures: Azure-embedded compliance tooling, native multimodal synthesis capabilities, and Watsonx governance modules for risk-averse procurement committees. Each anchors a distinct competitive vector without overlapping positioning.
| Leading Market Players |
|---|
| Microsoft |
| IBM |
| Adobe |
| Salesforce |
| DocuSign |
| UiPath |
| Templafy |
| Jotform |
| Others |
Pricing and Supply Chain Analysis
EU AI Act compliance mandates for automated decision documentation are forcing enterprise buyers toward audit-ready generation platforms with embedded governance modules, compelling vendors to absorb certification costs that stratify pricing tiers and compress margins for non-compliant suppliers.
Pricing Analysis
Volume placements concentrate in cloud-based SaaS tiers while margin capture sits with hybrid deployments carrying data residency premiums. Three-tier pricing structure across enterprise, professional, and developer levels separates audit-trail-enabled platforms from basic template automation. Pricing pressure stems from GPU cluster cost volatility tied to NVIDIA H100 supply allocation. Small and medium businesses exhibit highest price sensitivity; Fortune 500 legal departments demonstrate lowest sensitivity due to compliance-driven procurement mandates.
Supply Chain Analysis
India's Bureau of Indian Standards developing AI documentation guidelines is reshaping vendor localization strategies for government procurement eligibility. Inference hardware concentrates in Taiwan, South Korea, and the United States. Foundation model training draws from specialized GPU clusters, proprietary training datasets, and cloud compute credits. Single-source vulnerability runs through NVIDIA's datacenter chip allocation. Distribution runs through direct enterprise sales with embedded professional services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AI document generator market functions as a cost-of-compliance arena where EU AI Act algorithmic accountability requirements erect barrier-to-entry moats favoring vendors with pre-built audit infrastructure.
For Market Incumbents: Acquire specialized compliance engineering teams to fortify provenance tracking capabilities against emerging governance-first entrants. Defensive consolidation should prioritize RAG architecture specialists in Basel and Research Triangle Park pharmaceutical clusters. Channel control through direct LLM provider contracts displaces traditional software reseller margins. For New Entrants and Emerging Players: Capture India's government procurement segment ahead of BIS standardization enforcement by building structured output format compliance. White-space targets include pharmacovigilance automation for EMA-FDA dual jurisdiction and edge deployment for maritime energy operations. Go-to-market angle: per-seat SaaS pricing for regional European law practices. For Investors and Strategic Acquirers: The window for entry favors vertical-specific governance specialists over horizontal platform plays. Long-term viability hinges on regulatory roadmap alignment across FDA, EMA, and emerging algorithmic accountability frameworks. Acquisition target archetype: compliance-embedded document automation serving Fortune 500 filers. Signal to watch: SEC disclosure rule expansion to machine-generated regulatory filings.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance-First Platform Integration | Embedding EU AI Act audit trails satisfies Frankfurt and Amsterdam legal department procurement mandates. |
| Multimodal Synthesis Development | Native visual-tabular-textual generation opens FDA clinical trial documentation previously requiring separate tools. |
| Hybrid Deployment Architecture | Split on-premise-cloud configurations capture German defense and Italian healthcare data residency requirements. |
| Specialist Firm Acquisition | Absorbing RAG pipeline engineers addresses prompt engineering talent scarcity in thousand-page document workflows. |
| Geographic Expansion via Localization | India BIS guideline compliance creates first-mover advantage for government procurement eligibility. |
Research Methodology
Document review covered SEC disclosure filings, EMA pharmacovigilance guidance, EU AI Act regulatory texts, and hyperscaler infrastructure capex reports, complemented by interviews with legal department procurement officers, enterprise IT architects, pharmaceutical regulatory affairs leads, and cloud platform integration specialists. Secondary validation drew from FDA software-as-medical-device guidance, BIS standardization drafts, and clinical trial documentation databases. Bottom-up deployment volume estimates triangulated against top-down enterprise software spending patterns.
Cross-referencing historical adoption curves against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, solution offering tier, use case complexity, and customer organizational scale. CAGRs were derived from elasticity-adjusted enterprise procurement trajectories. Industry-specific forecast inputs incorporated quarterly reporting cycle compression patterns and pharmacovigilance report standardization timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to GPU supply allocation shocks and algorithmic accountability framework expansion beyond current EU and US jurisdictions. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and enterprise unbundling of documentation tools from monolithic suites. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
AI Content Creation Tool Market
Artificial Intelligence (AI)
Automated Data Annotation Tool Market
Artificial Intelligence (AI)
Machine Learning As a Service (Mlaas) Market
Artificial Intelligence (AI)
Artificial Intelligence in Transportation Market
Artificial Intelligence (AI)
Global Artificial Intelligence (AI) Hardware Market
Artificial Intelligence (AI)
Legal AI Market
Artificial Intelligence (AI)
Federated Learning Market
Artificial Intelligence (AI)
Artificial Intelligence (AI) in Retail Market
Artificial Intelligence (AI)
AI Data Labeling Market
Artificial Intelligence (AI)
Content Automation AI Tools Market
Artificial Intelligence (AI)
Global AI Governance Market
Artificial Intelligence (AI)
Underwater Autonomous Data Processor Market
Artificial Intelligence (AI)
Artificial Intelligence for IT Operations (Aiops) Market
Artificial Intelligence (AI)
Europe Generative AI Market
Artificial Intelligence (AI)
North America Conversational AI Market
Artificial Intelligence (AI)
Far-Field Speech and Voice Recognition Market