
 Global Business Intelligence and Analytics Market | 2026-2036
Global Business Intelligence and Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Business Intelligence and Analytics Market Analysis
Enterprise-grade analytics certification is bifurcating the competitive landscape into premium compliance-ready platforms and standard utility offerings. Microsoft Corporation leverages its Azure cloud fabric to anchor large-scale deployments across regulated industries. Oracle Corporation sustains dominance in database-integrated analytics through backward integration into its proprietary data infrastructure. SAP SE differentiates via embedded analytics within its ERP ecosystem, competing directly against standalone visualization vendors.
Business intelligence and analytics encompasses software systems that ingest structured and unstructured data, apply statistical models and machine learning algorithms, and render actionable insights through dashboards, reports, and predictive forecasts. These systems operate on data latency thresholds ranging from real-time streaming to batch-processed warehouses, serving commercial purposes spanning operational optimization, risk quantification, and strategic planning. Cloud-based deployment leads absolute revenue contribution as enterprises migrate from capital-intensive on-premises installations to elastic consumption models. Predictive analytics represents the fastest-expanding solution segment, with margin pools concentrating in vertically specialized customer analytics applications for retail chains and healthcare providers.
The EU AI Act imposes conformity requirements on high-risk automated decision systems, compelling analytics vendors to implement explainability protocols and human oversight mechanisms. The US FDA issues guidance on AI-enabled clinical decision support, shaping product standards for healthcare analytics deployments. China's SAMR enforces algorithmic recommendation regulations that affect customer analytics functionality. Stakeholders must monitor divergence between regional compliance frameworks when architecting multi-tenant platform roadmaps.
Market Dynamics
Cloud migration compresses deployment timelines from quarters to weeks while the EU AI Act forces explainability retrofits onto legacy algorithmic systems. This dual pressure rewards vendors with pre-built compliance architectures and punishes point-solution specialists.
Growth Catalysts
- EU AI Act compliance mandates:High-risk automated decision systems require human oversight protocols. Healthcare analytics vendors retrofit explainability modules to maintain European market access.
- Healthcare predictive analytics:Providers deploy machine learning platforms for readmission risk stratification and resource allocation. FDA guidance on clinical decision support accelerates procurement cycles.
- Real-time streaming infrastructure:Apache Kafka and cloud-native event processing displace batch warehouses in fraud detection and supply chain monitoring.
Market Restraints
- Data residency requirements:China's SAMR algorithmic recommendation rules and GDPR localization clauses fragment cloud architectures. Multi-tenant platforms absorb 15-25% cost premiums for regional instance duplication.
- Specialized talent scarcity:MLOps engineers and explainability researchers command compensation premiums exceeding general software development by 40-60%.
- Legacy ERP lock-in:SAP and Oracle database-integrated analytics create switching costs that extend replacement cycles beyond typical depreciation schedules.
Strategic Opportunities
- India's digital health stack:The country's ABHA identifier system and PLI scheme for electronics manufacturing create localized deployment opportunities for clinical analytics vendors.
- Edge analytics convergence:5G network slicing and containerized inference engines enable sub-10 millisecond latency for manufacturing quality control.
- CSRD sustainability reporting:The EU Corporate Sustainability Reporting Directive mandates granular emissions tracking. Carbon accounting analytics modules attach to existing BI deployments.
Industry Challenges
- Explainability engineering:Black-box neural networks in credit scoring and hiring tools require SHAP or LIME implementation. Data science teams lack standardized tooling for regulatory documentation.
- Cross-border data governance:Divergent adequacy decisions between the EU, UK, and Singapore complicate multi-region platform architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Business Intelligence and Analytics Market |
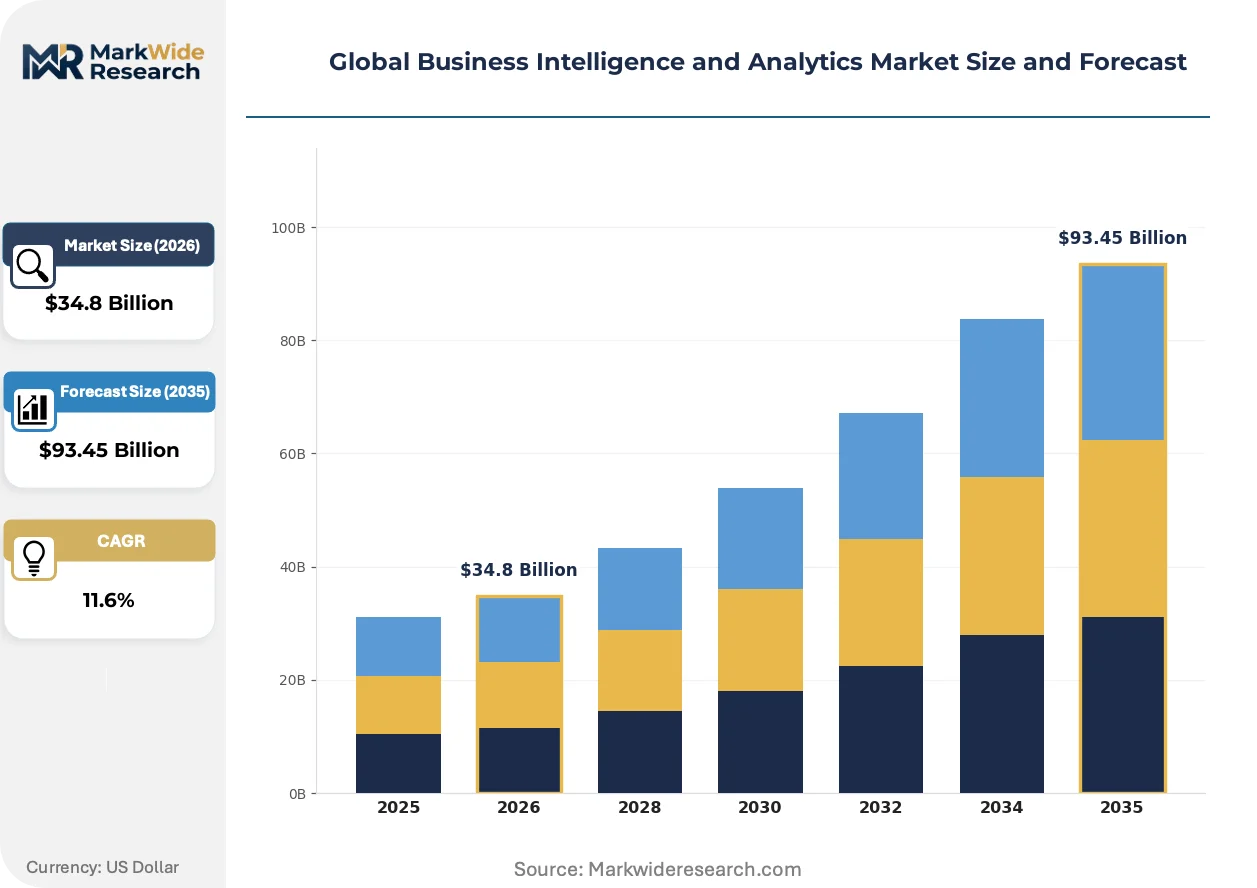
| Market Size in 2026 | $34.8 Billion |
| Market Size in 2035 | $93.45 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Financial Analysis, Supply Chain Management, Customer Analytics, Reporting Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Healthcare Providers, Retail Chains, Manufacturing Firms, Government Agencies Solution: Data Visualization, Predictive Analytics, Reporting Tools, Data Mining |
| Companies Covered | Microsoft Corporation, Oracle Corporation, SAP SE, IBM Corporation, SAS Institute Inc., Tableau Software, LLC, QlikTech International AB, Google LLC, Informatica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Business Intelligence and Analytics Market Emerging Trajectories
Generative AI is compressing the analytics value chain by automating insight narration and dashboard configuration. Vendors race to embed large language models without triggering the EU AI Act's high-risk system classification.
Natural language query interfaces are displacing traditional drag-and-drop visualization builders. Business users at retail chains and logistics operators adopt conversational analytics for ad-hoc exploration. This interface shift compresses time-to-insight from hours to minutes while reducing dependency on dedicated BI developer headcount.
The EU AI Act's conformity assessment requirements reshape product roadmaps for algorithmic decision systems. Vendors must implement technical documentation, human oversight mechanisms, and post-market monitoring. Healthcare analytics deployments face the steepest compliance burden given clinical decision support's high-risk classification.
Subscription-based consumption models displace perpetual license arrangements across mid-market enterprises. Finance and operations teams prefer operational expenditure alignment with usage volatility. This preference shift concentrates revenue predictability with cloud-native vendors while pressuring on-premises incumbents to accelerate SaaS transitions.
Global Business Intelligence and Analytics Market Segmentation
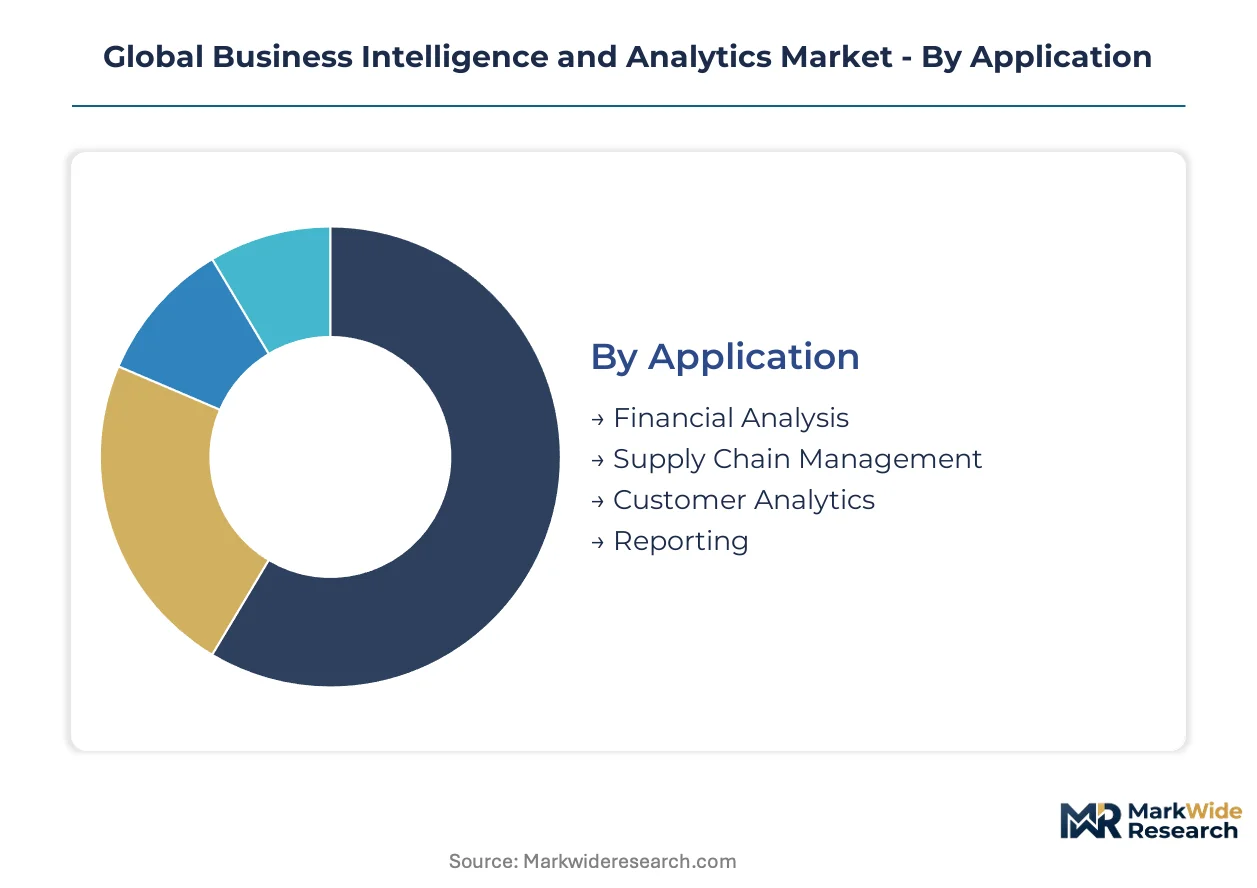
Segmentation reveals how deployment preferences and regulatory exposure fragment vendor strategies across the business intelligence landscape. Application-specific requirements and end-user compliance burdens create divergent margin profiles that reshape competitive positioning.
Application:
Financial analysis applications concentrate procurement in domestic banking hubs, while supply chain and customer analytics segments serve export-oriented manufacturing clusters across multiple continents.
- Financial Analysis:Risk quantification engines process real-time trading feeds and regulatory capital calculations. Demand clusters in New York, London, and Singapore financial districts as Basel III liquidity reporting deadlines compress implementation windows.
- Supply Chain Management:Inventory optimization and demand forecasting modules integrate with ERP systems. German automotive suppliers and South Korean electronics manufacturers drive procurement for multi-tier supplier visibility.
- Customer Analytics:Segmentation and lifetime value scoring tools embed in retail loyalty platforms.
- Reporting:Standardized dashboard and compliance documentation systems serve regulated industries.
Financial analysis commands the established base. The steepest expansion runs through customer analytics.
Deployment:
Cost tier stratification separates capital-intensive perpetual licenses from elastic consumption models, with hybrid architectures absorbing compliance-driven data residency premiums.
- Cloud-Based:Elastic compute and storage resources scale with query volume and user concurrency. United States enterprises lead migration from owned data centers, while EU AI Act explainability requirements force architectural retrofits for algorithmic workloads.
- SaaS:Multi-tenant platforms deliver pre-configured analytics modules through subscription contracts. Mid-market finance teams in Australia and Canada prefer operational expenditure alignment over capital deployment cycles.
- On-Premises:Dedicated hardware installations serve classified government workloads and proprietary trading infrastructure.
- Hybrid:Split architectures retain sensitive data on-premises while bursting compute to cloud regions.
On-premises deployments retain the legacy installed base. Cloud-based solutions are climbing the fastest.
End User:
Customer type maturity varies sharply, with healthcare and government segments imposing documentation burdens that extend sales cycles while manufacturing procurement emphasizes throughput metrics.
- Healthcare Providers:Clinical decision support and operational analytics platforms integrate with electronic health records. FDA guidance on AI-enabled diagnostics shapes procurement standards for United States hospital systems, while India's ABHA identifier creates localized deployment opportunities.
- Retail Chains:Demand forecasting and personalization engines process point-of-sale and loyalty program data. Brazilian and Mexican supermarket operators adopt cloud-native customer analytics to compete with multinational entrants.
- Manufacturing Firms:Quality control and predictive maintenance applications deploy at production lines.
- Government Agencies:Fraud detection and citizen service analytics operate under strict procurement regulations.
Retail chains command the established base. Healthcare providers are gaining share fastest.
Solution:
Technology readiness separates visualization tools with immediate user adoption from predictive platforms requiring specialized implementation services and change management.
- Predictive Analytics:Machine learning models forecast demand, attrition, and equipment failure from historical patterns. Healthcare readmission risk stratification and Japanese automotive quality prediction drive vertical specialization.
- Data Visualization:Interactive dashboards and self-service exploration tools democratize access to warehouse data. Natural language query interfaces from United States and Israeli vendors displace traditional drag-and-drop builders in logistics and retail operations.
- Reporting Tools:Scheduled distribution of standardized metrics serves regulatory and executive audiences.
- Data Mining:Pattern discovery algorithms extract segments and anomalies from unstructured sources.
Reporting tools command the established base. Predictive analytics shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net services exports from the United States and Ireland tilt the trade balance toward surplus for cloud-based analytics platforms. Import dependence concentrates in specialized hardware components and on-premises legacy systems from German and Japanese suppliers.
United States
Hospital systems in Massachusetts and California deploy predictive analytics for clinical decision support under FDA guidance. The SEC mandates XBRL structured data reporting for public issuers, driving demand for compliance-integrated BI platforms. New York financial services firms consume real-time risk quantification engines processing trading feeds.
Germany
Automotive suppliers in Baden-Württemberg adopt supply chain visibility tools for multi-tier supplier monitoring. The EU AI Act forces explainability retrofits onto algorithmic quality control systems deployed at production lines. Munich and Stuttgart host concentrated procurement clusters for ERP-embedded analytics.
China
Retail chains in Shanghai and Shenzhen implement customer analytics for loyalty program optimization. SAMR enforces algorithmic recommendation regulations affecting personalization engine architectures. The MIIT promotes domestic cloud infrastructure alternatives for data residency compliance.
India
Healthcare providers in Karnataka and Maharashtra integrate clinical analytics with the ABHA identifier system. The PLI scheme for electronics manufacturing creates localized deployment opportunities for edge analytics vendors. Telangana's Hyderabad hosts emerging SaaS analytics development clusters.
United Kingdom
London financial institutions process regulatory capital calculations through cloud-native risk engines. The FCA's operational resilience requirements shape procurement standards for real-time monitoring systems. Edinburgh and Manchester develop specialized fintech analytics service capabilities.
Global Business Intelligence and Analytics Market Vendor Landscape
Listed leaders compete with private specialists across deployment architecture preferences, creating a tiered competitive structure. Cloud-native platforms challenge database-integrated incumbents through elastic consumption models. Three archetypes dominate: hyperscale cloud providers with compliance-ready platforms, ERP-embedded analytics specialists, and standalone visualization vendors. Strategic moves concentrate on SaaS transition acceleration and vertical specialization through healthcare and retail modules.
Within the database-integrated tier, Oracle Corporation and SAP SE exemplify backward integration strategies, anchoring analytics capabilities within proprietary data infrastructure. Microsoft Corporation occupies a position bridging cloud fabric and productivity software ecosystems. These three represent contrasting approaches to enterprise lock-in versus platform openness.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Oracle Corporation |
| SAP SE |
| IBM Corporation |
| SAS Institute Inc. |
| Tableau Software, LLC |
| QlikTech International AB |
| Google LLC |
| Informatica |
| Others |
Supply Flow & Price Mechanics
Ninety-day implementation cycles for cloud-native analytics platforms compress procurement timelines while concentrating pricing power with vendors holding pre-built EU AI Act compliance architectures. This lead-time compression rewards hyperscale providers and punishes point-solution specialists lacking modular explainability components.
Pricing Analysis
Industrial OEM buyers anchor subscription-based SaaS pricing across mid-market manufacturing deployments. Pricing stratifies across premium compliance-ready tiers, standard utility modules, and economy self-service tiers, with differentiation driven by certification grade and vertical specialization depth. Cost compression in standard tiers intensifies because hyperscale cloud providers bundle analytics into broader infrastructure contracts. Healthcare providers exhibit lowest price sensitivity due to FDA-mandated procurement standards, while retail chains demonstrate highest sensitivity to per-user licensing costs.
Supply Chain Analysis
Thirty-day provisioning windows for cloud compute instances mask underlying concentration in United States, Ireland, and Singapore hyperscale regions. The supply chain draws from specialized GPU hardware, proprietary database engines, and open-source machine learning frameworks. Single-source vulnerability concentrates in NVIDIA accelerator supply for training workloads. Distribution runs through direct enterprise sales teams and hyperscaler marketplaces, with systems integrators capturing implementation services revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Business Intelligence and Analytics Market sits in early-cycle recovery as cloud migration capex resumes following post-pandemic optimization. Enterprise procurement committees reactivate deferred analytics modernization budgets.
For Market Incumbents: Consolidate compliance engineering capabilities to defend against cloud-native entrants exploiting EU AI Act retrofit burdens. Oracle Corporation and SAP SE should deepen backward integration into explainability tooling rather than licensing third-party SHAP implementations. Incumbents must absorb 15-25% cost premiums for regional instance duplication demanded by China's SAMR algorithmic regulations.
For New Entrants and Emerging Players: Mid-market healthcare providers in India present the most penetrable white-space target, given ABHA identifier integration requirements and limited SAP-Oracle footprint. New entrants should pursue vertical specialization through clinical decision support modules rather than horizontal visualization platforms. A channel partnership strategy with regional systems integrators accelerates hospital procurement committee access.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because divergence between EU AI Act, FDA guidance, and SAMR rules creates persistent demand for multi-tenant compliance architectures. Acquisition targets should display pre-built explainability protocols and human oversight mechanisms. The signal to watch is FDA issuance of final rulemaking on AI-enabled clinical decision support, which would trigger hospital system procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Pre-built explainability modules secure European market access for healthcare analytics vendors. |
| Vertical Healthcare Specialization | Readmission risk stratification tools integrate with Epic and Cerner electronic health record systems. |
| Edge Analytics Containerization | Sub-10 millisecond inference engines deploy on 5G network slices for manufacturing quality control. |
| Sustainability Reporting Module Launch | Carbon accounting analytics attach to existing BI deployments under EU CSRD mandates. |
| Natural Language Interface Integration | Conversational query tools displace drag-and-drop builders in retail logistics operations. |
Methodological Framework
The analysis maps predictive analytics, data visualization, reporting tools, and data mining segments, each validated through CTOs, IT procurement officers, platform engineers, and channel partners. Primary interviews with hospital system biomedical engineers and retail chain operations directors combined with secondary validation against SEC filings, hyperscaler capex disclosures, and FDA guidance documents. Bottom-up deployment volume estimates triangulated against top-down cloud infrastructure spend analysis.
Consistency checks validated model outputs against external benchmarks across deployment model, organization size, vertical industry, and regional adoption pattern segmentation. CAGRs derived from elasticity-adjusted growth curves incorporating EU AI Act implementation timelines and FDA regulatory pathway acceleration. Forecast inputs included healthcare provider EHR modernization cycles and manufacturing firm ERP replacement schedules.
Forecasts assume regulatory continuity in EU AI Act, FDA, and SAMR enforcement regimes; material policy shifts would require re-modeling. Revision becomes warranted when cloud migration cost arbitrage crosses enterprise depreciation cycle thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
Global in-Store Analytics Market
Analytics
IT Operation Analytics (ITOA) Market
Analytics
Europe Supply Chain Analytics Market
Analytics
Sales Intelligence Market
Analytics
TV Analytics Solutions Market
Analytics
Research and Development (Randd) Analytics Market
Analytics
Mobile Apps and Web Analytics Market
Analytics
Europe HR Analytics Market
Analytics
Asia-Pacific Contact Center Analytics Market
Analytics
Global in-Memory Analytics Market
Analytics
UK Video Analytics Market
Analytics
Middle East and Africa Location Analytics Market
Analytics
Europe Network and Location Analytics Market
Analytics
Location Analytics Adoption Spending Market
Analytics
Application Metrics and Monitoring Tools Market
Analytics
Multichannel Analytics Market