
 Retail Robotics Market | 2026-2036
Retail Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Retail Robotics Market Analysis
The EU Green Deal is restructuring procurement criteria for retail automation across European supermarkets and distribution centers. Zebra Technologies leverages its dominance in enterprise asset intelligence to anchor automated tracking systems in major grocery chains. Symbotic competes through deep specialization in AI-powered warehouse orchestration platforms for big-box retailers.
Retail robotics encompasses autonomous systems engineered for material handling, shelf monitoring, and customer interaction within commercial retail environments, typically operating with payload capacities from 50 to 1,500 kilograms and navigation precision within centimeter-scale tolerances. Autonomous Mobile Robots occupy the largest installed base due to their flexibility across warehouse aisles and store floors, while Robotic Arms capture concentrated margin pools in micro-fulfillment centers where pick-and-place speed determines throughput economics. Drones remain nascent in last-meter inventory applications but show structural promise for high-bay warehouse scanning where vertical reach exceeds conventional robot limits.
The EU Machinery Directive and CE marking requirements shape product design standards for collaborative robots deployed in European retail settings, while OSHA guidelines in the United States govern worker-safety protocols around autonomous systems in warehouse and store environments. Stakeholders must monitor divergence between regional certification frameworks as robotics vendors pursue multi-continent deployment strategies without redundant engineering cycles.
Market Dynamics
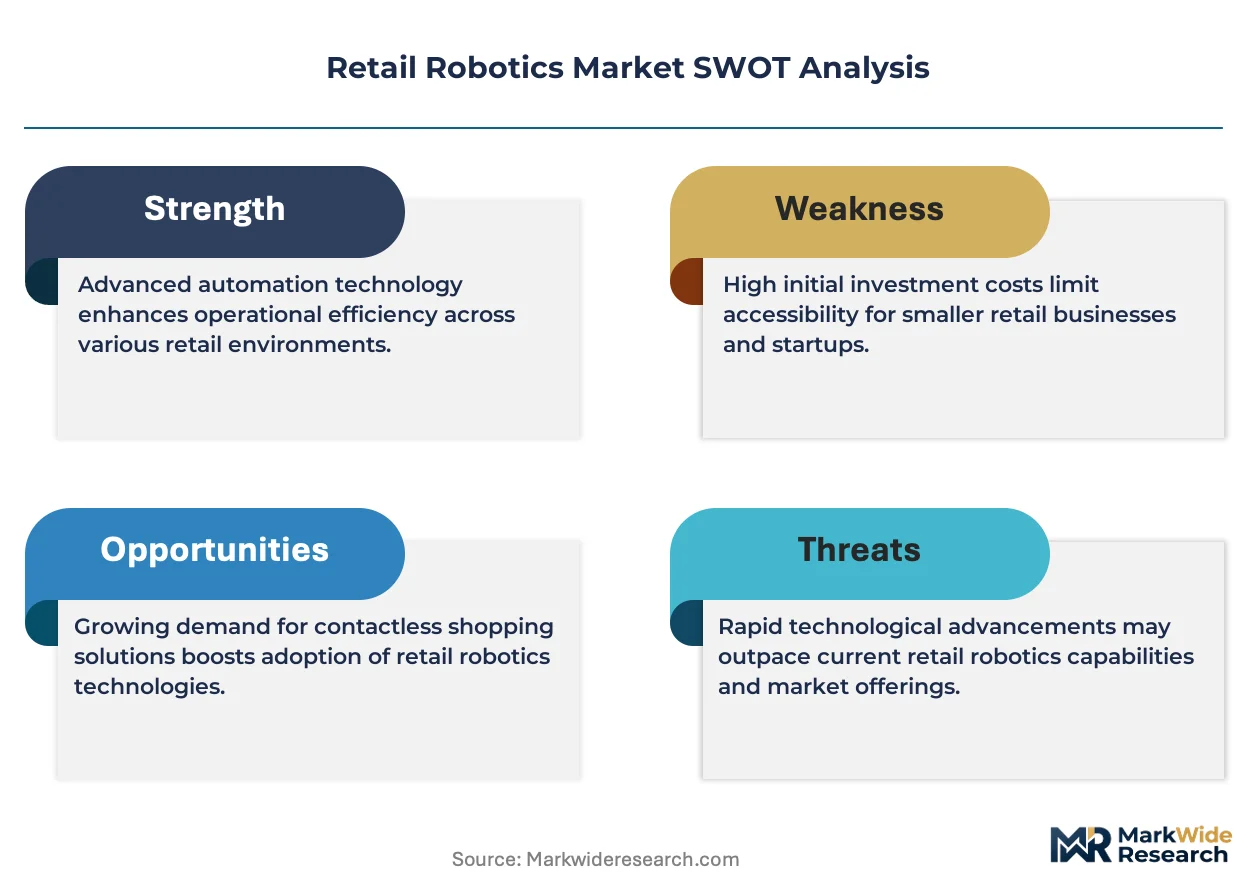
Labor scarcity across warehouse operations is compressing payback-period thresholds for autonomous mobile robot deployments, forcing capital allocation decisions toward systems with sub-18-month ROI verification.
Growth Catalysts
- OSHA workplace safety mandates:Stricter enforcement of ergonomic standards in US distribution centers accelerates substitution of manual material handling with collaborative robotic systems.
- Micro-fulfillment center proliferation:Urban grocery networks deploy compact automated storage and retrieval systems to enable sub-hour delivery promises in dense metropolitan zones.
- LiDAR sensor cost curves:Component price declines below critical thresholds unlock autonomous navigation deployments in mid-tier retail operations previously priced out of automation.
Market Restraints
- Steel and rare-earth magnet volatility:Robot actuator manufacturing faces input cost instability from concentrated Chinese processing capacity for neodymium and dysprosium.
- CE marking timeline friction:EU Machinery Directive conformity assessment cycles extend 8-14 months, delaying product launches in European grocery and apparel chains.
- Fixed automation legacy:Existing conveyor and shuttle systems in established distribution centers create sunk-cost barriers against mobile robot retrofits.
Strategic Opportunities
- India organized retail expansion:Reliance Retail and DMart infrastructure buildouts create first-mover advantages for vendors establishing local service networks.
- EU AI Act compliance services:Risk classification requirements for autonomous decision-making systems generate recurring revenue streams for certification and audit providers.
- Computer vision and edge computing convergence:On-device shelf-scanning analytics reduce cloud dependency and latency for real-time inventory accuracy in hypermarket environments.
Industry Challenges
- Mechatronics talent scarcity:Shortages of robotics integration engineers delay deployment timelines and inflate implementation costs for mid-market retailers.
- Warehouse management system interoperability:Proprietary APIs from legacy software vendors fragment data flows between autonomous mobile robots and enterprise resource planning platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail Robotics Market |
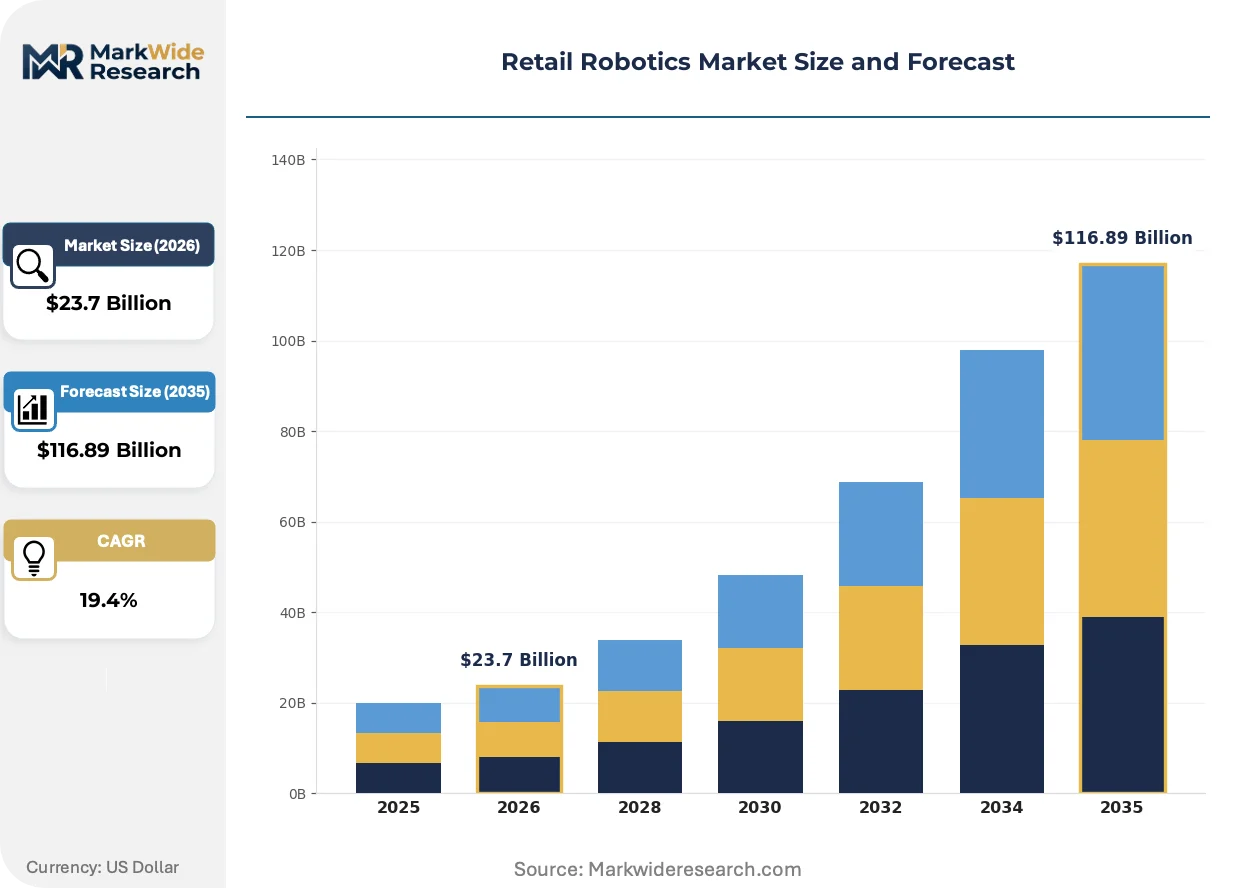
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $116.89 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autonomous Mobile Robots, Robotic Arms, Automated Guided Vehicles, Drones Application: Inventory Management, Customer Assistance, Shelf Scanning, Delivery End User: Supermarkets, E-commerce, Warehouses, Department Stores Technology: Computer Vision, Machine Learning, Navigation Systems, Artificial Intelligence |
| Companies Covered | Agility Robotics, Zebra Technologies, SoftBank Robotics, Miso Robotics, Bear Robotics, Simbe Robotics, Badger Technologies, Symbotic, UBTECH Robotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail Robotics Market Emerging Trajectories
Convergence of edge AI and low-cost sensing hardware is democratizing autonomous navigation, compressing the addressable market from enterprise-only deployments toward regional retail chains and independent logistics operators.
Vision-based simultaneous localization and mapping is overtaking magnetic tape and QR-code guidance in warehouse aisle navigation. Grocery fulfillment centers in Germany and the Netherlands adopt camera-only systems at replacement rates exceeding 40% annually for greenfield installations. This shift eliminates infrastructure retrofit costs while enabling dynamic route optimization that tape-based systems cannot support.
The EU AI Act's risk-based classification framework imposes documentation and human-oversight requirements on autonomous inventory robots making real-time stocking decisions. Retailers operating cross-border European networks must maintain conformity assessments across multiple notified bodies. French and Italian supermarket cooperatives are consolidating vendor selection around suppliers with pre-certified high-risk system credentials to accelerate deployment timelines.
Subscription-based robot-as-a-service contracts are displacing capital purchase models among mid-tier apparel and home goods retailers. Third-party logistics providers in the United States now bundle autonomous mobile robot fleets with labor management software, transferring obsolescence risk from end-users to equipment financiers. This financing innovation expands addressable demand among retailers with sub-$50 million annual technology budgets.
Retail Robotics Market Segmentation
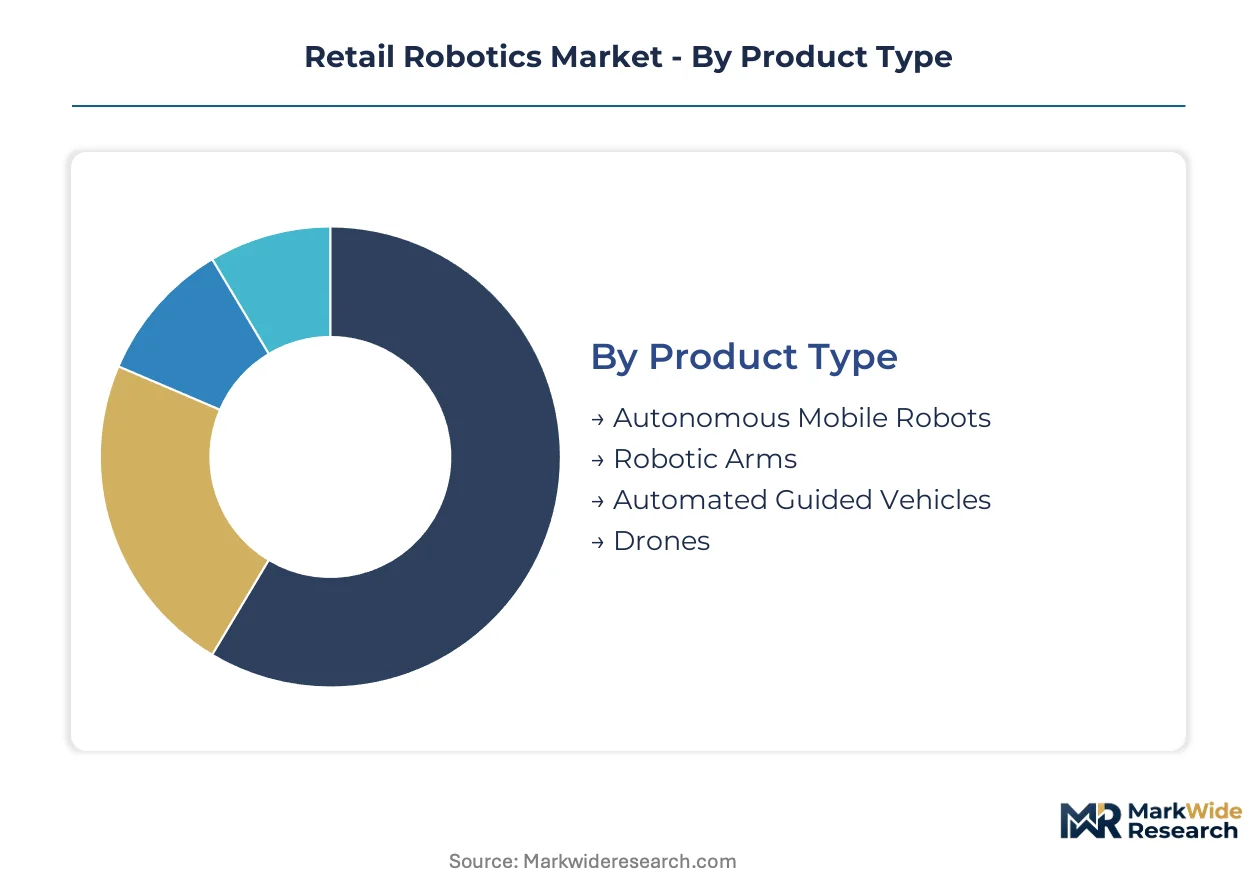
Retail robotics buyers face divergent technical requirements across fulfillment density, customer proximity, and payload precision. Segmentation reveals how capital allocation splits between warehouse-scale automation and front-of-store service applications.
Product Type:
Payload capacity and navigation flexibility separate procurement decisions between high-volume distribution centers and constrained retail floors.
- Autonomous Mobile Robots:These wheeled platforms carry 50-1,500 kilograms through dynamic warehouse aisles using LiDAR and camera fusion. Grocery chains in the United States deploy them for case picking where labor turnover exceeds 100% annually. Their centimeter-scale positioning enables slotting density improvements in e-commerce fulfillment centers.
- Robotic Arms:Articulated manipulators perform pick-and-place operations in micro-fulfillment centers with cycle times under five seconds per item. German supermarket cooperatives install them in urban dark stores where vertical space constraints demand compact footprints. Gripping technology limits remain the binding constraint for fresh produce handling.
- Automated Guided Vehicles:Magnetic tape or QR-guided transporters move palletized loads along fixed routes in established distribution centers. Legacy installations in French hypermarket supply chains favor their predictability over autonomous alternatives.
- Drones:Aerial systems scan high-bay warehouse racks beyond conventional robot reach. Dutch logistics operators pilot them for cycle counting in facilities exceeding 15 meters clear height.
Autonomous Mobile Robots lead volumes today; Robotic Arms are gaining share fastest in urban grocery networks.
Application:
Operational pain points determine whether buyers prioritize labor substitution, accuracy improvement, or customer experience enhancement.
- Inventory Management:Real-time stock tracking systems integrate with warehouse management software to eliminate manual cycle counting. Warehouse operators in the Netherlands achieve 99.9% location accuracy using RFID-tagged bins and autonomous mobile robot fleets.
- Shelf Scanning:Vision-equipped robots traverse store aisles detecting out-of-stock items and price label errors. United States grocery chains deploy them overnight to avoid customer interference.
- Customer Assistance:Interactive robots guide shoppers to product locations and answer inventory queries. Department stores in Japan test them for multilingual support in tourist-heavy districts.
- Delivery:Last-meter autonomous vehicles transport online orders from micro-fulfillment centers to customer vehicles. Pilot programs in California focus on curbside handoff precision.
Inventory Management leads volumes today; Shelf Scanning is expanding most quickly as camera costs decline.
End User:
Capital intensity and order profile heterogeneity shape technology selection across retail formats.
- Warehouses:Large-scale distribution centers process mixed-SKU pallets for multi-store replenishment. OSHA ergonomic mandates accelerate collaborative robot adoption for repetitive material handling tasks.
- E-commerce:Pure-play fulfillment centers demand single-piece picking at throughput rates exceeding 400 units per hour per station. Machine learning optimizes batch consolidation across variable order profiles.
- Supermarkets:Hybrid retail environments combine customer-facing operations with backroom fulfillment. CE marking requirements under the EU Machinery Directive extend deployment timelines for European grocery cooperatives.
- Department Stores:Apparel and home goods retailers prioritize customer engagement over operational speed. Vision systems must distinguish between visually similar SKUs with size and color variants.
Warehouses lead volumes today; E-commerce is climbing the fastest as delivery speed promises tighten.
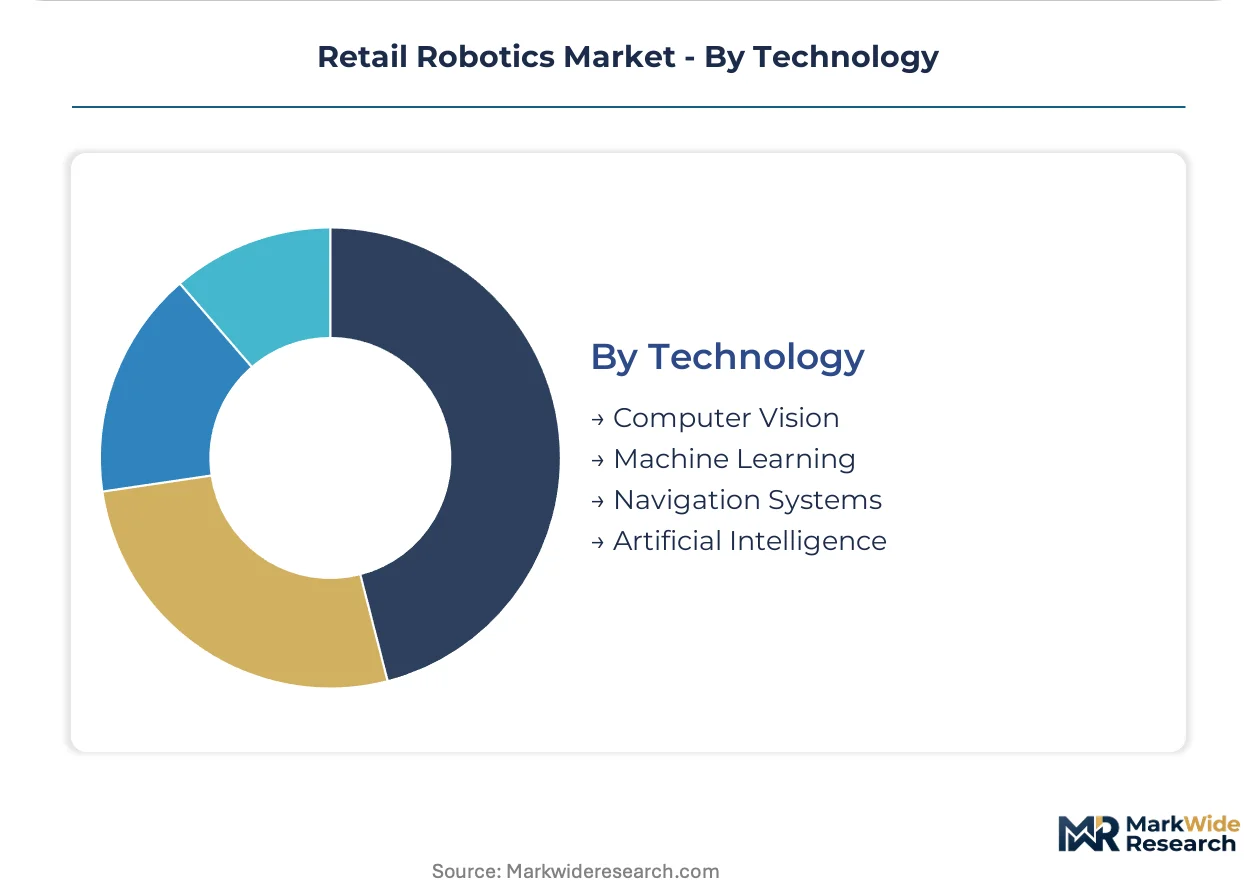
Technology:
Software maturity and hardware cost curves determine which capabilities reach mid-market price points first.
- Computer Vision:Camera-based perception enables object recognition, barcode scanning, and navigation without infrastructure modifications. Edge processing reduces cloud latency for real-time shelf analysis.
- Machine Learning:Predictive models optimize robot routing and demand forecasting based on historical throughput patterns. Training data scarcity for novel SKU categories constrains accuracy in fashion retail.
- Navigation Systems:SLAM algorithms build facility maps dynamically without pre-installed beacons or tape. German engineering standards influence safety certification requirements for autonomous path planning.
- Artificial Intelligence:High-risk classification under the EU AI Act imposes documentation and human oversight requirements for autonomous stocking decisions. Retailers operating cross-border European networks must maintain conformity assessments across multiple notified bodies.
Navigation Systems lead volumes today; Computer Vision is gaining share fastest as camera-only deployments displace tape-guided alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Retail robotics first achieved commercial scale in Japan during the 1980s, with automated guided vehicles deployed in Toyota's manufacturing supply chain before migrating to distribution applications. The industry's geographic footprint now spans three distinct regulatory and demand environments.
United States
OSHA workplace safety mandates and chronic warehouse labor turnover above 100% annually drive AMR procurement by Kroger, Walmart, and Amazon fulfillment networks. The Department of Labor's ergonomic enforcement in distribution centers accelerates collaborative robot substitution for manual palletizing. Greater Chicago and the Inland Empire host the densest concentrations of pilot deployments for shelf-scanning systems in 24-hour grocery operations.
Germany
Engineering standards from the KBA and EU Machinery Directive CE marking requirements extend product certification cycles to 8-14 months for collaborative robots. The country's supermarket cooperatives prioritize pre-certified vendors to compress deployment timelines. The Rhine-Ruhr corridor anchors Europe's largest concentration of micro-fulfillment center automation for urban grocery delivery networks.
China
Domestic robot actuator manufacturing faces input cost pressure from concentrated rare-earth processing capacity for neodymium magnets under MIIT industrial policy guidance. SAMR standards for service robot safety are converging with ISO benchmarks. The Yangtze River Delta manufacturing cluster around Shanghai supplies 60% of Asia-Pacific AMR navigation hardware components.
Netherlands
Dutch logistics operators pilot drone-based cycle counting in high-bay warehouses exceeding 15 meters clear height, enabled by permissive FAA-equivalent airspace regulations for indoor unmanned systems. Rotterdam's port-centric distribution network tests last-meter autonomous delivery vehicles for curbside handoff precision. The country's warehouse operators achieve 99.9% inventory location accuracy using RFID-tagged bin systems integrated with robot fleets.
India
Reliance Retail and DMart infrastructure buildouts create first-mover opportunities for vendors establishing local service networks. BIS certification requirements for industrial automation equipment remain less stringent than CE or OSHA equivalents, compressing market entry timelines. The Delhi-Mumbai Industrial Corridor hosts emerging fulfillment center clusters where labor cost arbitrage still favors semi-automated solutions over full AMR deployment.
Retail Robotics Market Vendor Landscape
Premium-margin players sit above commodity-margin players across software orchestration capabilities and sensor fusion sophistication. The vendor base organizes into three tiers: enterprise-scale warehouse automation specialists, front-of-store service robot developers, and component suppliers for navigation and gripping subsystems. Consolidation pressure intensifies as capital allocation favors vendors with sub-18-month ROI verification and pre-certified regulatory credentials across multiple jurisdictions. Dominant competitive moves include strategic partnerships between robot OEMs and warehouse management software vendors, plus geographic expansion through local service network establishment.
Within the enterprise warehouse automation tier, Symbotic and Zebra Technologies exemplify divergent strategic positioning—Symbotic representing deep vertical integration into AI-powered orchestration platforms, Zebra anchoring automated tracking systems through enterprise asset intelligence dominance. Among customer-facing service robot developers, Miso Robotics and Bear Robotics occupy positions in food service and hospitality-adjacent retail applications respectively. Agility Robotics sits within the humanoid manipulation specialist category, targeting logistics use cases requiring bipedal mobility in unconstrained environments.
| Leading Market Players |
|---|
| Agility Robotics |
| Zebra Technologies |
| SoftBank Robotics |
| Miso Robotics |
| Bear Robotics |
| Simbe Robotics |
| Badger Technologies |
| Symbotic |
| UBTECH Robotics |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up warehouse automation specialists have consolidated component sourcing networks across North America and Europe, tightening pricing discipline through captive service agreements and volume-scale procurement leverage. Their ownership structure rewards predictable recurring revenue over project-based margins, reshaping how robot OEMs negotiate actuator and sensor contracts.
Pricing Analysis
Subscription-based robot-as-a-service contracts dominate mid-tier retail procurement, displacing capital purchase models through bundled fleet management and software licensing. Price differentiation rests on CE marking tier and after-sales service bundling, with pre-certified European vendors commanding premiums over uncertified competitors. Cost compression in standard-tier AMR deployments is intensifying because LiDAR component prices have fallen below critical adoption thresholds. Regional grocery chains exhibit highest price sensitivity, while e-commerce fulfillment operators prioritize throughput guarantees over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare-earth processing capacity for neodymium and dysprosium magnets anchoring robot actuator manufacturing. Component sourcing draws from China, South Korea, and Germany for navigation hardware, precision motors, and industrial controllers respectively. Tariff exposure on steel and magnet alloys creates margin volatility for vendors without backward integration into magnet supply. Distribution runs through third-party logistics providers bundling AMR fleets with labor management software, transferring obsolescence risk to equipment financiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in retail robotics hinges on software attach rates rising as hardware commoditizes, with edge AI and computer vision modules capturing premium pricing against bare-metal robot sales.
For Market Incumbents: Extend certification coverage across multiple jurisdictions to compress deployment timelines for European grocery cooperatives facing EU Machinery Directive friction. Anchor automated tracking systems through enterprise asset intelligence dominance while defending against AI-powered orchestration platforms through deeper warehouse management system integration partnerships. For New Entrants and Emerging Players: Direct-to-channel software marketplaces offer low-friction entry points for computer vision and edge analytics modules targeting regional retail chains priced out of full-stack automation. India's organized retail expansion presents the most penetrable geography, with Reliance Retail and DMart infrastructure buildouts creating first-mover advantages for vendors establishing local service networks ahead of full AMR deployment. For Investors and Strategic Acquirers: Valuations sit cheapest among component suppliers for navigation and gripping subsystems lacking downstream software differentiation. Long-term viability favors vendors with pre-certified high-risk system credentials under the EU AI Act, with the signal to watch being consolidation pressure as capital allocation favors sub-18-month ROI verification.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Orchestration Platform Integration | Symbotic's warehouse automation stack demonstrates how vertical software control captures margin from hardware commoditization. |
| CE Marking Pre-Certification Investment | French and Italian supermarket cooperatives consolidate vendor selection around suppliers with accelerated European deployment timelines. |
| Local Service Network Establishment | India's BIS certification requirements compress market entry timelines for vendors targeting Reliance Retail infrastructure buildouts. |
| Computer Vision Edge Computing Convergence | On-device shelf-scanning analytics reduce cloud dependency for real-time inventory accuracy in hypermarket environments. |
| Robot-as-a-Service Financing Innovation | Third-party logistics providers bundle AMR fleets with labor software, expanding addressable demand among sub-$50 million technology budgets. |
Methodological Framework
Bottom-up warehouse operator modeling reconciled against top-down navigation hardware supply tracking forms the analytical core of this study. Primary interviews with warehouse automation directors, robotics integration engineers, grocery chain procurement leads, and third-party logistics operators were validated against secondary sources including OSHA enforcement records, EU Machinery Directive conformity databases, and customs data on robot actuator imports. Trade association filings from material handling equipment federations and hyperscaler fulfillment center capex disclosures provided cross-reference points for deployment velocity estimates.
Historical trendline analysis of AMR installed base growth and robotic arm cycle-time improvements informed the projection framework across the analysis window. Segmentation modeling captured product type, application, end user, and technology dimensions, with additional granularity on certification tier and financing structure. CAGRs were derived from penetration rate assumptions tied to labor cost arbitrage thresholds and LiDAR sensor cost curves, with sensitivity testing around EU AI Act compliance timelines and rare-earth magnet price volatility.
The model assumes a particular technology adoption path; alternative pathways for vision-based SLAM navigation displacing magnetic tape guidance would alter the outlook. Forecasts reflect assumptions about OSHA ergonomic enforcement intensity and European supermarket cooperative consolidation patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Solar Panel Cleaning Robot Market
Robotics and Automation
Healthcare Assistive Robot Market
Robotics and Automation
Spain Cloud Robotics Market
Robotics and Automation
Global Robot Kitchen Market
Robotics and Automation
Construction Robotics Market
Robotics and Automation
Hotel Robot Market
Robotics and Automation
Autonomous Polishing Machine Market
Robotics and Automation
Underwater Rescue Robot Market
Robotics and Automation
Case and Box Handling Robots Market
Robotics and Automation
Europe Warehouse Robotics Market
Robotics and Automation
Piece Picking Robots Market
Robotics and Automation
Singapore Cloud Robotics Market
Robotics and Automation
Long-Range Drone Package Delivery Market
Robotics and Automation
Consumer Robotics Market
Robotics and Automation
Restaurant Delivery Robot Market
Robotics and Automation
Smart Remote Control Market