
 AI Watermarking Market | 2026-2036
AI Watermarking Market Size, Share, and Industry Trends Forecast 2026-2036
AI Watermarking Market Insights
Entertainment studios is broadening its share of AI watermarking procurement as synthetic media production scales across streaming, gaming, and advertising workflows. Google leverages its cloud infrastructure to embed watermarking APIs across generative AI services, sustaining developer ecosystem lock-in. Digimarc anchors its position through deep integration with packaging and print-to-digital authentication, while Verimatrix specializes in broadcast-grade forensic tracking for premium video distribution.
AI watermarking denotes the imperceptible embedding of identifying signals into digital content—typically via frequency-domain modifications or latent-space perturbations—enabling provenance verification and tamper detection after distribution. The technique serves industrial purposes ranging from copyright enforcement to disinformation containment, with detection thresholds commonly tuned below human perceptibility limits. Deep Learning and Computer Vision segments lead current deployment, as convolutional and transformer architectures enable robust embedding against compression and cropping attacks; Cloud-based Platforms capture expanding margin pools by reducing deployment friction for mid-market content owners. Software Solutions dominates product-type revenue, though Hybrid Systems are gaining traction among government agencies requiring air-gapped verification.
The EU AI Act and GDPR impose transparency and audit-trail obligations on generative AI deployers, directly expanding addressable demand for embedded provenance systems. The US NIST AI Risk Management Framework and emerging FCC guidance on synthetic media in political broadcasting further shape product specifications and procurement criteria. Stakeholders must monitor whether watermarking interoperability standards consolidate under ISO or remain fragmented across national regulatory silos.
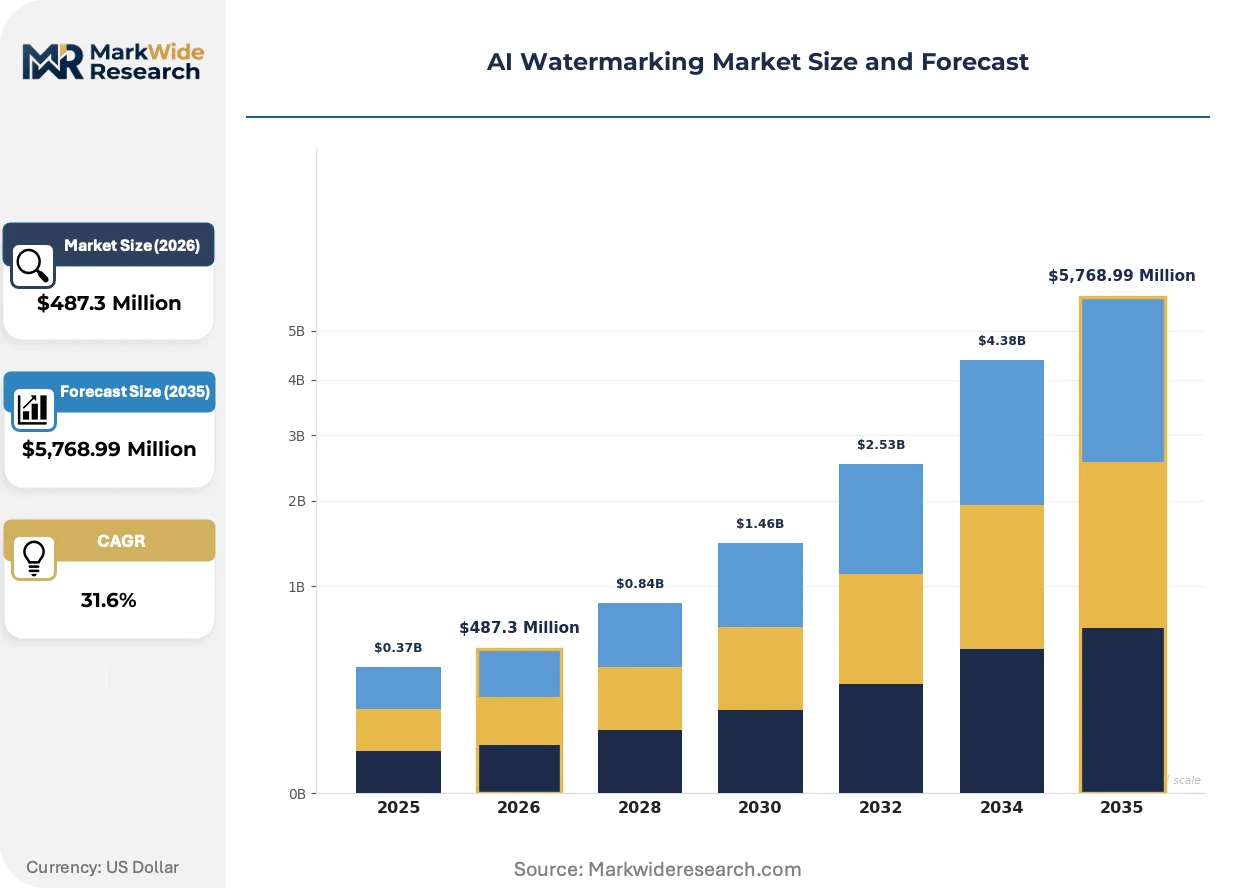
Market Dynamics
Forensic-grade watermarking procurement is accelerating as synthetic media volume overwhelms manual provenance verification, forcing platforms to embed authentication at the generation layer rather than post-production.
Growth Catalysts
- EU AI Act transparency mandates:Deployers of generative AI systems must label synthetic content, creating binding demand for embedded watermarking infrastructure across European content platforms.
- Deepfake proliferation in political broadcasting:Election integrity concerns are driving FCC-adjacent guidance on synthetic media disclosure, expanding procurement from news organizations and campaign infrastructure providers.
- Convolutional neural network architectures:Frequency-domain embedding techniques now withstand compression and cropping attacks at scale, enabling watermarking deployment across streaming video pipelines.
Market Restraints
- GPU compute cost volatility:Latent-space perturbation methods require substantial inference overhead, tying watermarking economics to NVIDIA supply allocation and cloud compute pricing cycles.
- Adversarial attack sophistication:Gradient-based watermark removal techniques developed by academic researchers threaten detection reliability, forcing continuous algorithmic refresh cycles.
- Fragmented national standards:Divergent authentication requirements between the EU AI Act, US state-level deepfake legislation, and China's synthetic content rules complicate cross-border platform deployment.
Strategic Opportunities
- India's creator economy expansion:YouTube and Instagram content volumes in Mumbai and Bangalore clusters exceed current watermarking penetration, creating whitespace for localized API-first vendors.
- Healthcare imaging provenance:FDA 21 CFR Part 11 compliance requirements for AI-generated diagnostic imagery are extending watermarking demand into radiology PACS integration.
- Blockchain-anchored verification:Immutable ledger integration with forensic watermarking is unifying tamper detection with distributed trust architectures for high-value asset classes.
Industry Challenges
- Cross-functional talent scarcity:Teams must combine signal processing expertise with adversarial machine learning knowledge, a combination concentrated in academic labs rather than commercial labor pools.
- Legacy broadcast infrastructure integration:SDI-based production workflows in established studios resist IP-native watermarking insertion without substantial gateway hardware replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI Watermarking Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $5,768.99 Million |
| CAGR (2026 – 2036) | 31.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Deep Learning, Machine Learning, Neural Networks, Natural Language Processing, Computer Vision Application: Digital Media Protection, Intellectual Property Rights, Content Authentication, Digital Forensics, Broadcast Monitoring Product Type: Software Solutions, Hardware Solutions, Hybrid Systems, Cloud-based Platforms, On-premise Software End User: Entertainment Studios, Publishing Houses, Government Agencies, Advertising Agencies, Educational Institutions |
| Companies Covered | Google, Digimarc, Clarifai, Verimatrix, IMATAG, ZOO Digital Group, Vobile Group, MarkAny, Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI Watermarking Market Trends and Innovations
Watermarking technology is migrating from post-hoc forensic analysis to generative model-native embedding, compressing the verification chain and embedding provenance at the moment of synthetic content creation.
Diffusion-model-native watermarking is unifying content generation with imperceptible signal embedding, eliminating separate pipeline stages. Hollywood studios and advertising agencies are adopting these integrated architectures for campaign asset production. This convergence is compressing vendor stacks and marginalizing standalone watermarking tools that operate downstream of generation.
The EU AI Act's Article 50 transparency obligations are mandating technical documentation for synthetic content systems, compelling deployers to implement embedded provenance by default. Industrial consequence includes procurement specification shifts toward ISO/IEC 27001-aligned watermarking vendors. Premium video distribution platforms in Germany and France are responding with accelerated forensic system upgrades ahead of enforcement timelines.
Content authentication purchasing is consolidating under chief information security officers rather than creative operations heads, reflecting risk management reframing. Enterprise buyers now evaluate watermarking through zero-trust architecture compatibility rather than creative workflow fit. This shift is most visible in United States financial services and defense contractor content pipelines, where supply chain security audits now include synthetic media provenance verification.
AI Watermarking Market Segmentation
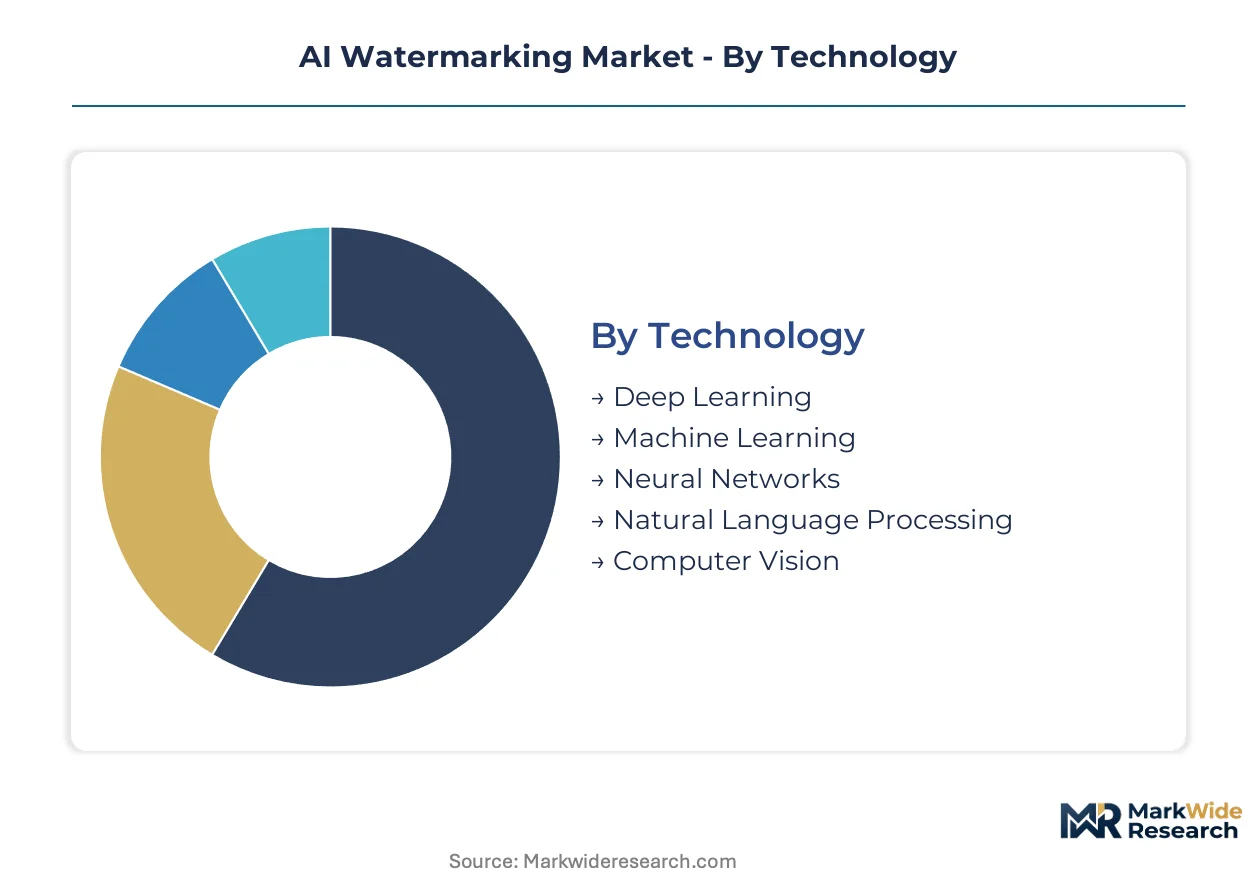
AI watermarking architectures diverge sharply across deployment contexts, from real-time broadcast pipelines requiring hardware-native embedding to cloud-native API services serving mid-market content creators. Technology choices cascade through product configuration, end-user procurement criteria, and regulatory compliance posture.
Technology:
Standardization dominates convolutional and transformer architectures, while latent-space perturbation methods remain bespoke to generative model providers.
- Deep Learning:Convolutional neural networks embed watermarks via frequency-domain modifications that withstand compression and cropping attacks. Hollywood studios deploy these architectures across streaming video pipelines to satisfy EU AI Act transparency mandates.
- Computer Vision:Transformer-based architectures enable robust embedding in synthetic imagery from diffusion models. Demand concentrates in United States advertising technology stacks where campaign asset provenance verification is becoming standard.
- Machine Learning:Statistical embedding methods persist in legacy broadcast infrastructure where computational constraints limit neural deployment.
- Neural Networks:Recurrent architectures serve sequential content authentication in podcast and audiobook distribution workflows.
- Natural Language Processing:Token-level watermarking for large language model outputs addresses text-based disinformation containment requirements.
Leading the category by volume: Deep Learning. Expanding most quickly: Computer Vision.
Application:
Cost tier stratification separates forensic-grade authentication systems from automated content labeling tools.
- Content Authentication:Real-time provenance verification systems embed cryptographic signatures at generation layer. Germany and France premium video platforms are upgrading forensic capabilities ahead of EU AI Act enforcement timelines.
- Digital Media Protection:Automated copyright enforcement pipelines integrate with content delivery networks to trace unauthorized redistribution. United States cloud providers bundle these capabilities into generative AI service APIs.
- Intellectual Property Rights:Registry-linked watermarking supports litigation-ready documentation for creative asset disputes.
- Digital Forensics:Law enforcement agencies deploy tamper-detection systems for synthetic media evidence verification.
- Broadcast Monitoring:Real-time signal analysis tracks premium content distribution across satellite and terrestrial networks.
Dominating procurement spend: Content Authentication. Steepest expansion trajectory: Digital Media Protection.
Product Type:
Deployment friction varies across margin structures, with cloud platforms capturing recurring revenue while hybrid systems command premium pricing for air-gapped environments.
- Cloud-based Platforms:API-first architectures reduce integration overhead for mid-market content owners. Google and Amazon Web Services embed watermarking into generative AI inference pipelines, sustaining developer ecosystem lock-in.
- Hybrid Systems:Air-gapped verification hardware serves government agencies and defense contractors with zero-trust architecture requirements. United States financial services procurement now includes synthetic media provenance in supply chain security audits.
- Software Solutions:Standalone applications persist in post-production workflows at smaller creative studios.
- On-premise Software:Enterprise licensing models dominate legacy broadcasters with established data center infrastructure.
- Hardware Solutions:FPGA-based embedding appliances address SDI-native production environments resisting IP conversion.
Capturing widest deployment: Cloud-based Platforms. Growing fastest: Hybrid Systems.
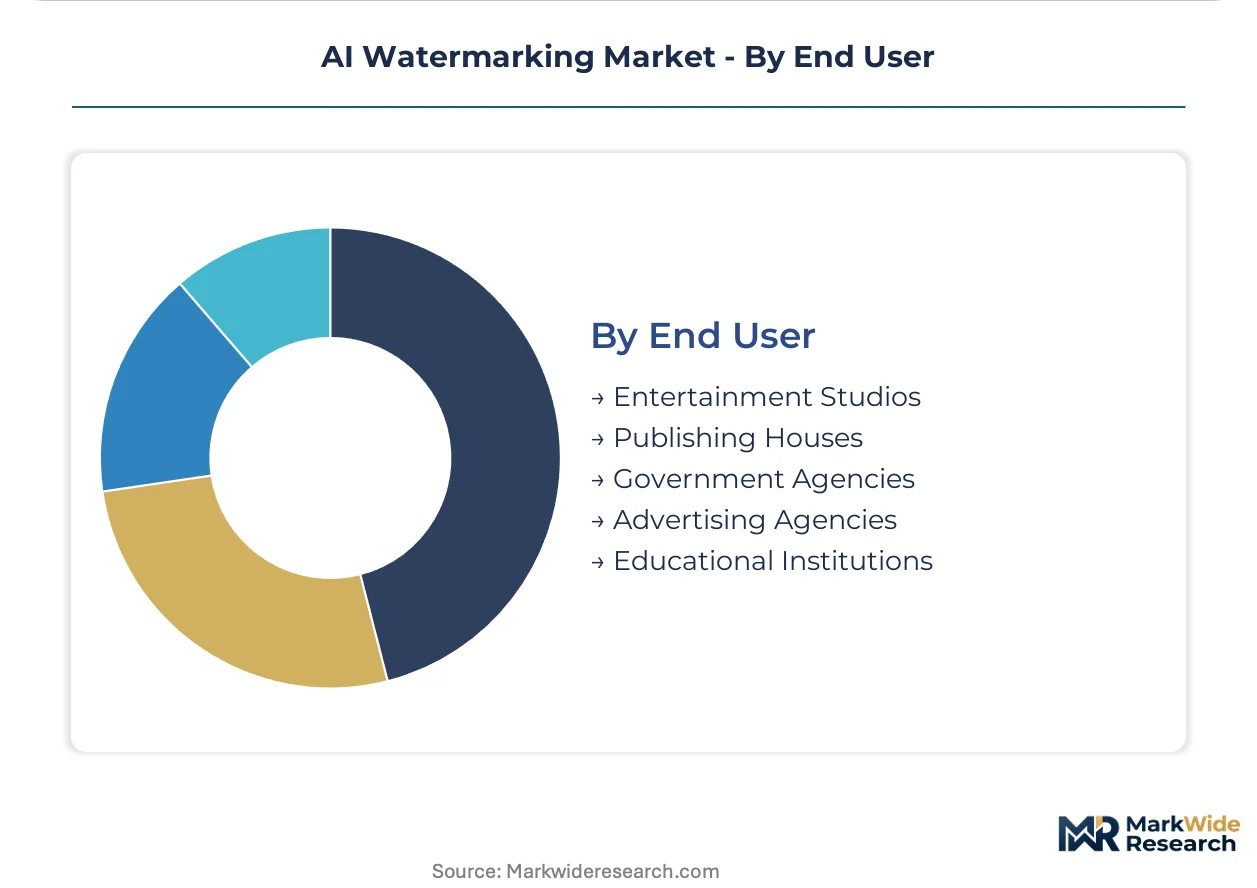
End User:
Customer type determines procurement authority, with risk management functions displacing creative operations in enterprise purchasing decisions.
- Entertainment Studios:Synthetic media production at scale across streaming, gaming, and advertising workflows drives platform integration requirements. Major Hollywood studios now mandate watermarking at asset generation rather than post-production.
- Government Agencies:National security and election integrity applications demand tamper-proof provenance systems. FCC-adjacent guidance on synthetic media in political broadcasting is expanding procurement from campaign infrastructure providers.
- Advertising Agencies:Campaign asset authentication protects brand reputation against deepfake manipulation.
- Publishing Houses:Text and image provenance verification addresses academic integrity and newsroom disinformation concerns.
- Educational Institutions:Student assessment authentication and research data integrity drive institutional adoption.
Commanding largest procurement volume: Entertainment Studios. Gaining share fastest: Government Agencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Hyderabad, Shenzhen, and Dubai Internet City concentrate AI watermarking R&D through tax holidays and subsidized cloud infrastructure. These zones attract generative AI labs and forensic technology vendors seeking reduced operational costs.
United States
Hollywood studios and cloud hyperscalers drive procurement volume across streaming and advertising workflows. FCC guidance on synthetic media disclosure in political broadcasting compels campaign infrastructure upgrades. Los Angeles production clusters now mandate watermarking at asset generation rather than post-production.
Germany
Premium video distribution platforms accelerate forensic system upgrades ahead of EU AI Act enforcement timelines. The country's national media regulator enforces transparency labeling requirements for synthetic content. Berlin-Brandenburg media tech clusters host watermarking API development for European broadcast compliance.
China
Domestic generative AI platforms embed watermarking to satisfy synthetic content regulations from the national cyberspace administration. MIIT standards mandate provenance verification for algorithm-recommended content. Shenzhen special economic zone hosts diffusion-model-native watermarking R&D for export-oriented advertising technology.
India
YouTube and Instagram content volumes in Mumbai and Bangalore exceed current watermarking penetration, creating whitespace for localized vendors. The country's central bank guidelines on AI-generated financial communications drive enterprise procurement. Hyderabad's HITEC City clusters attract API-first watermarking startups serving creator economy platforms.
United Arab Emirates
Dubai Internet City free zone offers zero-tax infrastructure for forensic technology vendors targeting Middle East broadcast markets. The country's media regulatory authority requires synthetic content disclosure for newsroom AI applications. Abu Dhabi sovereign wealth vehicles invest in blockchain-anchored verification systems for high-value asset authentication.
AI Watermarking Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with cloud-native platforms capturing recurring revenue while hardware-anchored vendors serve air-gapped government deployments. The vendor base clusters around three strategic archetypes: hyperscaler-integrated API providers, broadcast-grade forensic specialists, and hybrid-system integrators for defense contractors. Dominant competitive moves include strategic partnerships with generative AI model providers and geographic expansion through localized compliance certification.
Within the hyperscaler-integrated tier, Google and Microsoft exemplify cloud infrastructure lock-in through embedded watermarking APIs across generative AI inference pipelines. Digimarc occupies a position among packaging-authentication specialists extending into synthetic media provenance. Verimatrix represents broadcast-grade forensic tracking vendors serving premium video distribution with tamper-detection hardware.
| Leading Market Players |
|---|
| Digimarc |
| Clarifai |
| Verimatrix |
| IMATAG |
| ZOO Digital Group |
| Vobile Group |
| MarkAny |
| Microsoft |
| Others |
Pricing and Supply Chain Analysis
Signal processing and adversarial machine learning expertise concentrated in United States academic labs and Bangalore R&D clusters drives labor-cost differentials that separate premium forensic-grade watermarking tiers from economy API offerings. GPU compute allocation volatility from NVIDIA supply constraints feeds directly into pricing spreads across cloud-native and on-premise deployment modes.
Pricing Analysis
Short lead times for EU AI Act compliance-ready systems command substantial premiums over spot inventory of legacy broadcast watermarking hardware. Three-tier pricing structure across premium forensic-grade, standard cloud-API, and economy self-serve tiers separates government agencies from mid-market content creators and individual developers. Price differentiation hinges on ISO/IEC 27001 certification status and inference throughput guarantees. Cost compression in the standard tier is intensifying because hyperscalers bundle watermarking into generative AI inference pipelines at marginal cost. Individual developers and small creative studios exhibit highest price sensitivity; defense contractors and national security agencies demonstrate lowest.
Supply Chain Analysis
Returns and refurbishment flows for FPGA-based embedding appliances create secondary hardware channels serving legacy SDI broadcast infrastructure in established studios. Manufacturing concentrates in Taiwan for high-performance inference accelerators, Germany for precision broadcast hardware, and China for cost-optimized edge deployment devices. The supply chain draws from NVIDIA GPU silicon, Xilinx/AMD FPGA components, and specialized signal processing ASICs. Single-source vulnerability around NVIDIA H100 and Blackwell allocation creates procurement risk for latent-space perturbation watermarking vendors. Distribution runs through hyperscaler marketplaces, systems integrators serving government verticals, and direct OEM relationships with Hollywood studios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The AI watermarking market is becoming a vertical-integration race as hyperscalers embed provenance verification directly into generative model inference layers, compressing standalone vendor margins and forcing specialists to control upstream model partnerships or downstream forensic detection networks.
For Market Incumbents: Anchor market position through exclusive integration partnerships with leading diffusion model providers, locking out competing watermarking APIs from generation-native embedding. Pursue backward integration into adversarial robustness research by acquiring university spinouts with gradient-based attack expertise. The threat of hyperscaler bundling demands defensive certification investments in Common Criteria and FedRAMP to maintain government procurement eligibility. For New Entrants and Emerging Players: Mid-tier advertising technology platforms in India and Southeast Asia represent an underserved buyer archetype with provenance verification requirements but limited hyperscaler dependency. API-first deployment targeting Mumbai and Bangalore creator economy clusters bypasses entrenched broadcast-grade vendor relationships. White-space exists in healthcare imaging PACS integration where FDA 21 CFR Part 11 compliance creates procurement urgency without established vendor lock-in. For Investors and Strategic Acquirers: The window for entry favors forensic detection network operators with established tamper-response infrastructure over pure-play embedding technology vendors. Long-term viability rests on controlling the verification layer where zero-trust architecture mandates are concentrating enterprise spend. Acquisition targets should demonstrate adversarial robustness testing capabilities and government security clearance pathways. Monitor EU AI Act enforcement timelines and FCC synthetic media guidance implementation as inflection indicators for enterprise procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Diffusion-Model-Native Embedding Partnership | Google and Microsoft leverage inference pipeline control to marginalize downstream watermarking vendors. |
| Forensic Detection Network Expansion | Verimatrix extends tamper-response infrastructure across European premium video distribution platforms. |
| Government Security Certification Investment | Digimarc pursues FedRAMP and Common Criteria to access United States defense contractor procurement pipelines. |
| Healthcare PACS Integration Development | Specialist vendors target FDA-compliant radiology workflow embedding ahead of diagnostic AI deployment. |
| Adversarial Robustness Research Acquisition | Incumbents acquire university labs with gradient-based attack expertise to refresh algorithmic defenses. |
Research Methodology
Independent corroboration across primary interviews with platform engineering leads at cloud hyperscalers, forensic technology procurement officers at Hollywood studios, and regulatory compliance directors at European broadcasters underwrites the qualitative findings. Secondary validation draws from SEC filings of publicly traded watermarking vendors, EU AI Act implementation guidance documents, FCC dockets on synthetic media disclosure, and hyperscaler generative AI service documentation. Bottom-up demand modeling triangulates against top-down market sizing from technology spend allocations across identified end-user segments.
Rate-of-change decomposition separates volume expansion in synthetic media generation from value migration toward forensic-grade verification systems across the projection horizon. The analytical framework models technology adoption by deployment architecture, end-user risk tolerance tier, and regional regulatory enforcement pattern. CAGRs derive from segment-level demand curves weighted by procurement authority shifts from creative operations to chief information security officers. Industry-specific inputs include generative AI inference volume trajectories and EU AI Act compliance deadline proximity effects.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to adversarial attack breakthroughs and watermarking interoperability standard consolidation. Forecasts reflect assumptions regarding regulatory enforcement rigor and hyperscaler bundling strategies. Practitioners should monitor academic publications on gradient-based watermark removal and ISO/IEC standardization committee progress for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Artificial Intelligence and Machine Learning Market
Artificial Intelligence (AI)
Agentic AI Market
Artificial Intelligence (AI)
Cloud Artificial Intelligence Market
Artificial Intelligence (AI)
Asia-Pacific Natural Language Processing in BFSI Market
Artificial Intelligence (AI)
Content Automation AI Tools Market
Artificial Intelligence (AI)
Autonomic Platform Market
Artificial Intelligence (AI)
Global AI Training Dataset Market
Artificial Intelligence (AI)
Artificial Intelligence As a Service Market
Artificial Intelligence (AI)
GCC Artificial Intelligence Market
Artificial Intelligence (AI)
Enterprise AI Governance and Compliance Market
Artificial Intelligence (AI)
Mlops Market
Artificial Intelligence (AI)
Generative AI Market
Artificial Intelligence (AI)
Home AI Oven Market
Artificial Intelligence (AI)
Aiops Market
Artificial Intelligence (AI)
Generative AI in Healthcare Market
Artificial Intelligence (AI)
Embedded Intelligence Market