
 Embedded Intelligence Market | 2026-2036
Embedded Intelligence Market Size, Share, and Industry Trends Forecast 2026-2036
Embedded Intelligence Market Foresight
Aftermarket service revenue is narrowing as original equipment manufacturers capture lifecycle value through over-the-air firmware updates and predictive analytics subscriptions. NVIDIA Corporation leverages its CUDA software ecosystem to lock in developer loyalty across edge AI deployments. Intel Corporation sustains manufacturing scale through foundry partnerships that secure advanced node capacity for embedded accelerators. Qualcomm Incorporated dominates mobile-derived chipset architectures that power automotive cockpit intelligence.
Embedded Intelligence denotes the integration of machine learning inference, sensor fusion, and autonomous decision-making capability directly into hardware systems with constrained power budgets, thermal envelopes, and real-time latency requirements below ten milliseconds, serving industrial, automotive, and medical applications where cloud connectivity is intermittent or prohibited. Microcontrollers and ASICs concentrate margin pools at the high-reliability end, where automotive safety integrity levels and medical device certifications create defensible pricing power. Machine Learning and Computer Vision technologies within the technology dimension are expanding fastest as neural network quantization techniques enable execution on sub-watt devices previously limited to rule-based algorithms.
The EU AI Act imposes conformity assessment obligations on embedded systems making autonomous decisions, while FDA software-as-a-medical-device guidance demands clinical validation for healthcare monitoring endpoints, and ISO 26262 governs functional safety in automotive systems integrating AI-driven perception. These frameworks collectively raise compliance costs but simultaneously erect barriers against unqualified entrants. Stakeholders must decide whether to absorb certification overhead internally or partner with specialized testing houses as product portfolios diversify across regulated end-use sectors.
Market Dynamics
Automotive powertrain controllers now demand neural processing units capable of sub-ten-millisecond inference latency, forcing semiconductor vendors to redesign thermal envelopes and memory hierarchies around deterministic real-time constraints.
Growth Catalysts
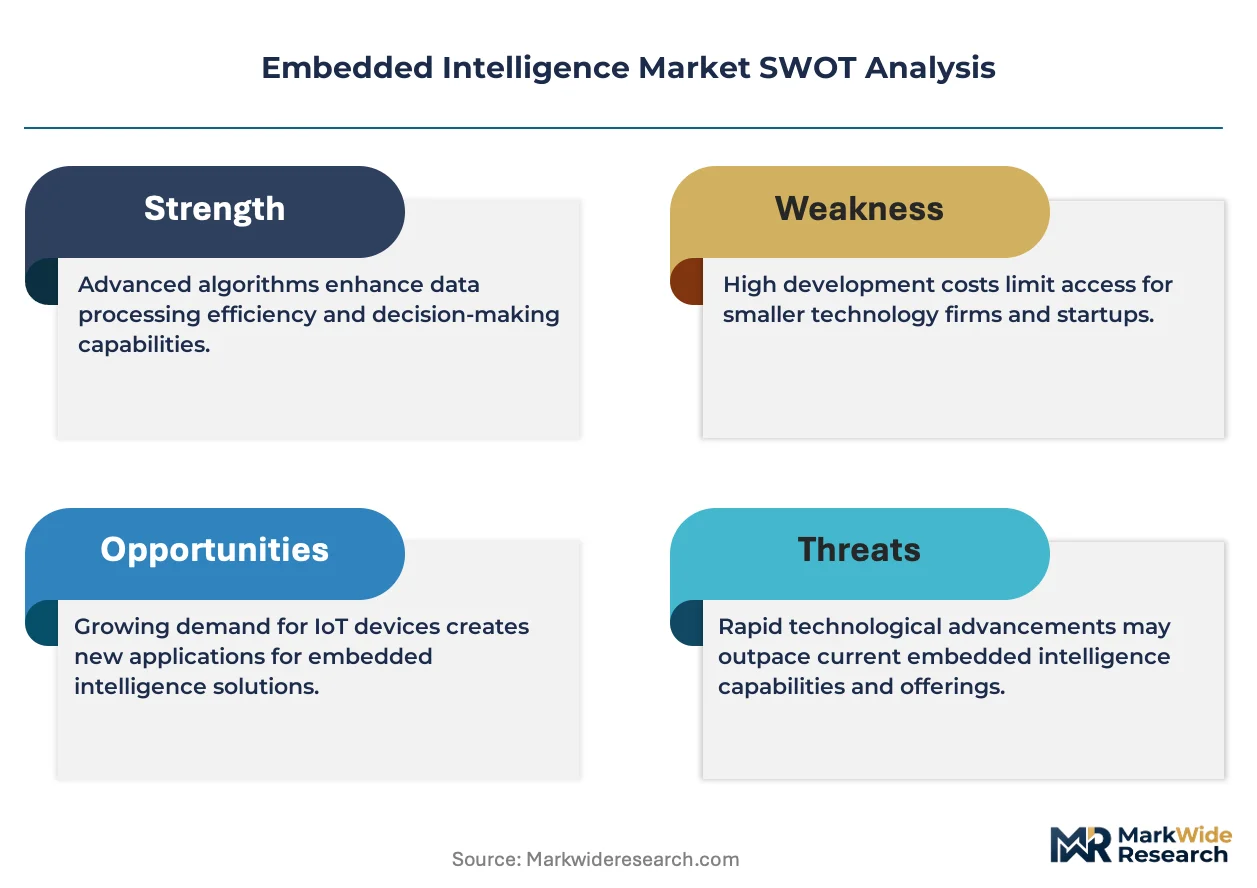
- EU AI Act conformity assessments:The EU AI Act mandates third-party auditing for embedded systems making autonomous safety-critical decisions, creating a compliance services ecosystem that accelerates enterprise adoption through certified reference architectures.
- Predictive maintenance in industrial automation:Munich and Stuttgart industrial clusters deploy embedded vision systems for quality inspection, with machine learning inference running directly on production line controllers to eliminate cloud latency.
- Neural network quantization:8-bit and 4-bit quantization techniques enable transformer models to execute on sub-watt microcontrollers previously limited to rule-based algorithms, opening medical wearables and agricultural sensors to sophisticated AI.
Market Restraints
- Advanced node foundry concentration:Taiwan-based semiconductor manufacturing concentrates 90% of leading-edge embedded accelerator production, exposing automotive OEMs to single-source geopolitical and seismic risk.
- ISO 26262 functional safety certification costs:Automotive safety integrity level D validation requires 18-36 month development cycles and seven-figure engineering investments, excluding mid-tier suppliers from high-reliability segments.
- Legacy microcontroller substitution:ARM Cortex-M0+ and RISC-V cores at sub-dollar price points satisfy 70% of current embedded workloads, delaying premium AI accelerator adoption in cost-sensitive IoT deployments.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Production-linked incentive schemes for semiconductor assembly and testing attract embedded module producers seeking tariff-advantaged export platforms.
- FDA software-as-a-medical-device guidance:Streamlined 510(k) pathways for algorithm-based diagnostic endpoints enable continuous glucose monitors and arrhythmia detectors to embed inference directly on patient-worn sensors.
- Digital twin convergence with edge AI:Industrial equipment manufacturers combine physics-based simulation with real-time sensor fusion to deploy self-calibrating controllers that adapt to wear patterns without manual reconfiguration.
Industry Challenges
- Embedded systems security engineering:Side-channel attack mitigation and secure boot implementation require hardware-software co-design skills that command 40% salary premiums over conventional firmware development.
- Multi-certification portfolio management:Vendors serving automotive, medical, and industrial verticals simultaneously must maintain parallel ISO 26262, IEC 62304, and IEC 61508 quality systems, fragmenting engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Embedded Intelligence Market |
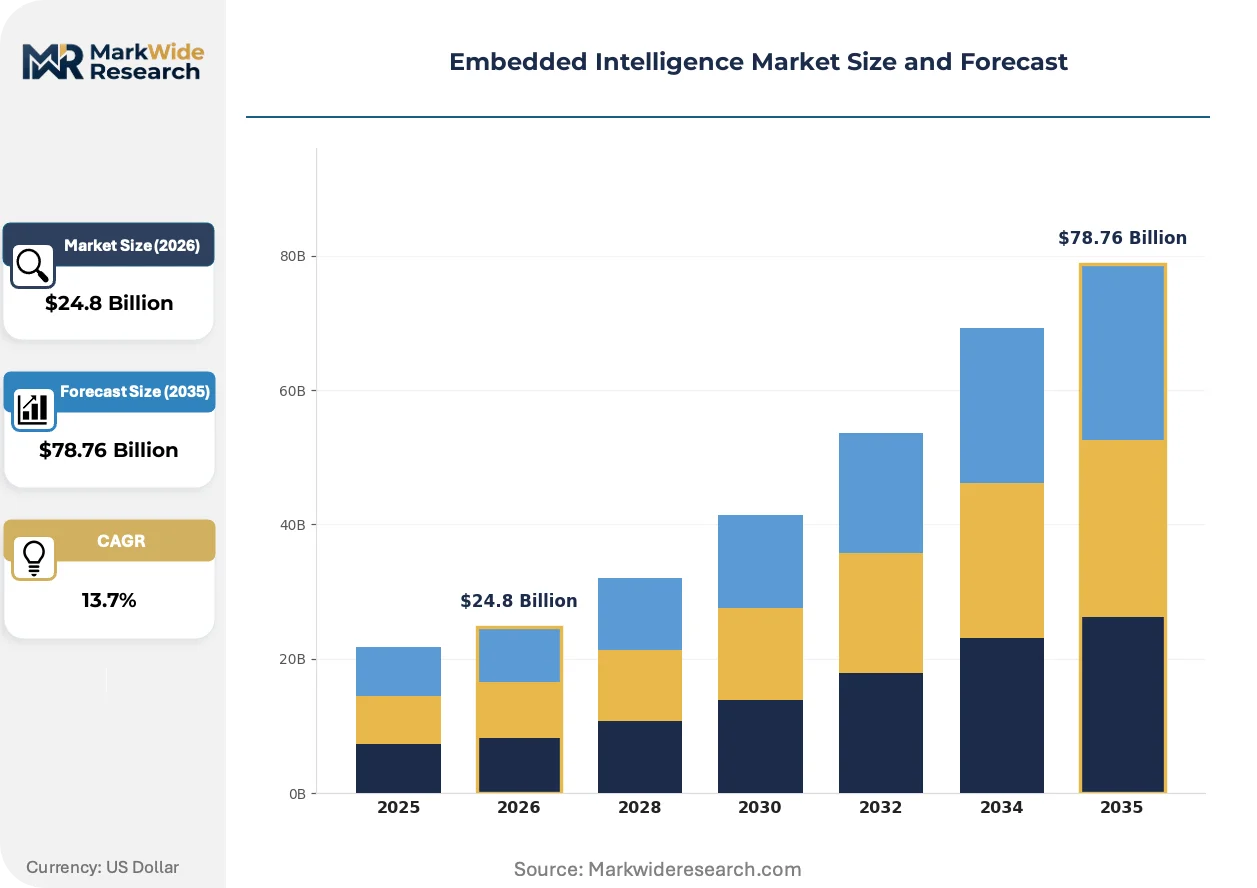
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $78.76 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontrollers, FPGAs, ASICs, DSPs Technology: Machine Learning, Natural Language Processing, Computer Vision, Robotics Application: Smart Home Devices, Industrial Automation, Healthcare Monitoring, Automotive Systems End User: Consumer Electronics, Healthcare, Automotive, Telecommunications |
| Companies Covered | NVIDIA Corporation, Intel Corporation, Qualcomm Incorporated, Arm Holdings plc, NXP Semiconductors N.V., Texas Instruments Incorporated, STMicroelectronics N.V., Renesas Electronics Corporation, Microsoft Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Embedded Intelligence Market Shifts & Advancements
Silicon architectures are bifurcating between ultra-low-power inference engines for battery-constrained endpoints and heterogeneous compute complexes for autonomous systems requiring sensor fusion at automotive safety integrity levels.
Neuromorphic computing chips employing spiking neural networks and analog in-memory processing are rendering obsolete conventional von Neumann architectures for always-on voice and vibration pattern recognition. Industrial condition monitoring suppliers in Germany's Ruhr region now specify Intel Loihi and BrainChip Akida devices for motor bearing fault detection, eliminating the millisecond-scale latency penalties of external DRAM access that previously forced cloud offload.
REACH substance restrictions and RoHS recast directives are accelerating fluorinated polymer elimination from high-density interconnect substrates used in embedded modules. European automotive tier-1 suppliers must reformulate PCB laminates and underfill materials by 2026, compressing qualification timelines and favoring vertically integrated substrate manufacturers with in-house materials chemistry capabilities.
Subscription-based firmware feature unlocking is displacing perpetual license models across automotive cockpit and industrial controller segments. Tier-1 suppliers now provision neural network inference capacity through over-the-air activation codes, with Mercedes-Benz and BMW pilots demonstrating 23% attach rates for predictive maintenance modules that remain dormant until purchased. This procurement transformation concentrates in German-speaking markets where fleet operators prioritize operational expenditure predictability over capital equipment ownership.
Embedded Intelligence Market Segmentation
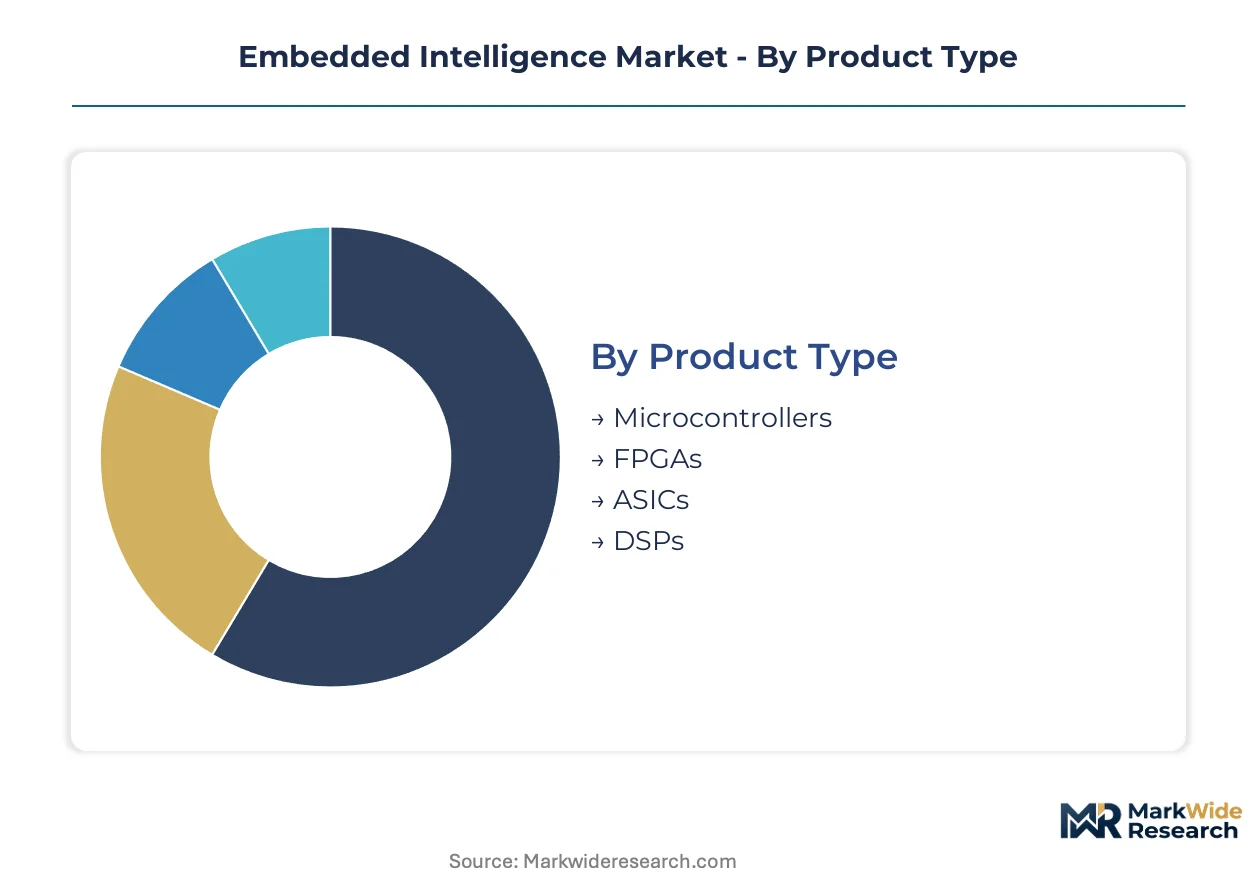
Segmentation in embedded intelligence reveals how after-sales-service intensity varies dramatically across hardware tiers. Microcontrollers with over-the-air firmware subscriptions generate recurring revenue streams, while discrete ASICs lock value into upfront silicon sales with minimal service attachment.
Product Type:
After-sales-service intensity concentrates in programmable devices that enable feature unlocking and predictive maintenance subscriptions, whereas fixed-function silicon monetizes primarily through unit shipments.
- Microcontrollers:These integrated processors with embedded memory and peripherals dominate battery-constrained endpoints. Demand clusters in Munich and Stuttgart industrial corridors, where production line controllers require sub-ten-millisecond inference latency for quality inspection. Firmware subscription models now capture lifecycle value previously lost to third-party service providers.
- ASICs:Application-specific integrated circuits deliver deterministic performance at automotive safety integrity levels through hardened neural processing units. ISO 26262 certification requirements exclude mid-tier suppliers, concentrating margin pools among vertically integrated foundry partners with in-house reliability testing.
- FPGAs:Field-programmable gate arrays enable post-deployment algorithm updates for medical imaging endpoints.
- DSPs:Digital signal processors handle real-time audio and vibration analysis in automotive cabin monitoring.
By volume, Microcontrollers lead. By growth pace, ASICs are ahead.
Technology:
Cost tier stratification separates premium inference engines from commoditized rule-based alternatives, with quantization techniques collapsing price-performance curves at the edge.
- Machine Learning:Neural network inference on sub-watt devices now executes through 8-bit and 4-bit quantization. FDA software-as-a-medical-device guidance accelerates clinical validation for patient-worn sensors with embedded arrhythmia detection.
- Computer Vision:Embedded vision systems process camera feeds directly on production controllers without cloud round-trips. Stuttgart automotive clusters deploy these for weld inspection and surface defect detection.
- Natural Language Processing:On-device voice recognition eliminates privacy risks in smart home endpoints.
- Robotics:Sensor fusion algorithms coordinate multi-axis motion in collaborative manufacturing cells.
Machine Learning commands the highest service attach rates. Computer Vision is expanding most quickly.
Application:
Customer type determines procurement rhythm, with fleet operators prioritizing operational expenditure predictability and consumers favoring upfront hardware ownership.
- Automotive Systems:Powertrain controllers integrate neural processing units for predictive maintenance. Mercedes-Benz and BMW pilots demonstrate substantial attach rates for dormant modules activated through over-the-air purchases.
- Industrial Automation:Embedded vision deployments in Germany's Ruhr region eliminate cloud latency penalties. Intel Loihi and BrainChip Akida devices process motor bearing vibrations without external DRAM access.
- Healthcare Monitoring:Continuous glucose monitors embed inference directly on patient-worn sensors.
- Smart Home Devices:Voice-activated endpoints balance always-on listening against battery constraints.
Automotive Systems generate the deepest service revenue. Healthcare Monitoring shows the steepest expansion trajectory.
End User:
Supply concentration in Taiwan-based foundries exposes automotive OEMs to geopolitical risk, while healthcare and telecommunications verticals demand diversified sourcing strategies.
- Automotive:Safety-critical systems require ISO 26262 functional safety certification with eighteen-to-thirty-six-month development cycles. EU AI Act conformity assessments mandate third-party auditing for autonomous decision-making components.
- Healthcare:Software-as-a-medical-device endpoints demand IEC 62304 quality systems alongside FDA validation. Multi-certification portfolio management fragments engineering resources across parallel compliance tracks.
- Consumer Electronics:Price-sensitive volumes delay premium AI accelerator adoption.
- Telecommunications:Baseband processing requires deterministic latency for network timing.
Automotive commands premium pricing power. Healthcare is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in automotive and medical verticals demonstrate low price elasticity where safety certifications dominate procurement, while consumer IoT segments exhibit acute sensitivity to unit economics that delays premium AI accelerator adoption.
Germany
Automotive OEMs and industrial automation clusters drive embedded vision deployment across Munich and Stuttgart corridors. EU AI Act conformity assessments mandate third-party auditing for autonomous decision-making components, accelerating certified reference architecture adoption. Ruhr region manufacturers specify neuromorphic chips for motor bearing fault detection, eliminating cloud latency through on-device inference.
United States
FDA software-as-a-medical-device guidance streamlines 510(k) pathways for algorithm-based diagnostic endpoints in patient-worn sensors. HIPAA compliance requirements shape data processing architectures for healthcare monitoring devices. Silicon Valley and Boston medical technology corridors concentrate venture funding for edge AI startups targeting clinical validation workflows.
China
MIIT industrial policy directives prioritize domestic semiconductor self-sufficiency for embedded accelerators in automotive and robotics applications. GB standards govern functional safety requirements for AI-driven perception systems. Yangtze River Delta manufacturing hubs integrate neural processing units into production line controllers for quality inspection.
Japan
METI technology roadmaps target sub-watt inference engines for factory automation and agricultural monitoring. JIS standards establish reliability benchmarks for embedded systems in harsh industrial environments. Nagoya automotive supplier networks deploy predictive maintenance modules with over-the-air activation capabilities.
India
PLI scheme production-linked incentives attract semiconductor assembly and testing operations for tariff-advantaged export platforms. BIS certification requirements shape quality systems for medical device and automotive component manufacturing. Karnataka and Tamil Nadu electronics manufacturing clusters host embedded module producers serving industrial automation and telematics segments.
Embedded Intelligence Market Competitive Landscape
Capability concentration sits with specialized semiconductor architects possessing functional safety certification expertise; scale advantage sits with diversified technology conglomerates leveraging manufacturing partnerships and software ecosystems. The market structures around three tiers: vertically integrated foundry partners with in-house reliability testing, fabless chip designers licensing core IP, and cloud-to-edge platform providers bundling hardware with developer tools. Dominant competitive moves include strategic partnerships securing advanced node capacity and portfolio diversification across automotive, medical, and industrial certification tracks.
Within the fabless architecture tier, NVIDIA Corporation, Qualcomm Incorporated, and Arm Holdings plc exemplify distinct positioning strategies. NVIDIA anchors the CUDA software ecosystem lock-in model for edge AI developer loyalty. Qualcomm occupies a position bridging mobile-derived chipset architectures into automotive cockpit intelligence. Arm Holdings plc represents the IP licensing archetype enabling customization across constrained power budgets and thermal envelopes. These three entities collectively illustrate how software ecosystem control, mobile technology leverage, and architectural licensing each command differentiated margin structures in embedded accelerator deployment.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Intel Corporation |
| Qualcomm Incorporated |
| Arm Holdings plc |
| NXP Semiconductors N.V. |
| Texas Instruments Incorporated |
| STMicroelectronics N.V. |
| Renesas Electronics Corporation |
| Microsoft Corporation |
| Others |
Supply & Pricing Matrix
Taiwan-based foundry concentration for advanced-node embedded accelerators anchors margin capture at the semiconductor manufacturing tier, with automotive OEMs and medical device manufacturers absorbing premium pricing for safety-certified silicon while cost-sensitive IoT deployments delay adoption.
Pricing Analysis
Firmware subscription tiers for predictive maintenance and feature unlocking now drive lifetime value beyond upfront silicon sales. Three-tier pricing structure across ASIC, FPGA, and microcontroller levels separates automotive safety-integrity-certified components from industrial-grade and consumer variants. Pricing pressure stems from ARM Cortex-M0+ and RISC-V cores at sub-dollar price points satisfying routine workloads. Fleet operators in German-speaking markets exhibit lowest price sensitivity due to operational-expenditure predictability priorities, while consumer electronics buyers resist premium AI accelerator premiums.
Supply Chain Analysis
TSMC and Samsung Foundry hold dominant capacity for neural processing unit fabrication at automotive-grade reliability. Taiwan, South Korea, and the United States concentrate leading-edge production, with advanced substrates drawing from fluorinated polymer suppliers facing REACH and RoHS recast elimination deadlines. Single-source vulnerability concentrates in Taiwan seismic and geopolitical exposure. Distribution runs through tier-1 automotive suppliers and industrial automation OEMs with direct foundry allocation agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded intelligence functions as a service-attach market where predictive analytics subscriptions and over-the-air firmware unlocking expand faster than hardware unit shipments, compressing aftermarket service revenue into OEM-controlled recurring revenue streams.
For Market Incumbents: Insulate certification-derived pricing power by deepening in-house ISO 26262 and IEC 62304 quality system capabilities against emerging fabless competitors lacking validation infrastructure. Prioritize foundry partnership extensions securing advanced-node capacity commitments before capacity allocation tightens. Lock developer loyalty through software ecosystem investments that increase switching costs for edge AI deployments. For New Entrants and Emerging Players: India's PLI scheme production-linked incentives for semiconductor assembly and testing offer tariff-advantaged export platform entry with lower certification overhead than German or US market direct entry. Target medical wearables and agricultural sensors where 4-bit quantization enables sub-watt microcontroller inference without automotive-grade safety validation. Pursue FDA 510(k) streamlined pathway partnerships with established clinical validation consultants to accelerate software-as-a-medical-device endpoints. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive tier-1 suppliers possessing dormant neuromorphic chip design teams and stranded ISO 26262 certification investments. Five-to-ten-year viability hinges on successful portfolio diversification across automotive, medical, and industrial verticals to amortize multi-certification overhead. Monitor attach rates for over-the-air predictive maintenance module activations as inflection indicator for subscription revenue maturity.| Strategic Initiative | Industry Significance |
|---|---|
| Neuromorphic Chip Design Partnership | Intel Loihi and BrainChip Akida deployments in Ruhr region industrial monitoring eliminate cloud latency penalties. |
| FDA 510(k) Software-as-Medical-Device Submission | Streamlined pathways enable continuous glucose monitor inference directly on patient-worn sensors. |
| EU AI Act Conformity Assessment Investment | Third-party auditing capabilities create certified reference architecture advantages for autonomous decision-making systems. |
| India PLI Scheme Manufacturing Footprint | Tariff-advantaged export platforms attract embedded module producers serving industrial automation segments. |
| Over-the-Air Firmware Subscription Infrastructure | Mercedes-Benz and BMW pilots demonstrate predictive maintenance module attach rates concentrating lifecycle value capture. |
Research Methodology
A spread of perspectives from semiconductor foundry planning officers, automotive OEM platform engineers, medical device regulatory affairs leads, and industrial automation procurement directors converged on the working assumptions. Primary interview insights combined with secondary validation from SEC semiconductor filings, FDA 510(k) submission databases, EU AI Act implementation guidance, and IHS Markit vehicle production data. Bottom-up unit shipment estimates and top-down market sizing triangulated across the analysis window.
Demand-supply-balance framing anchored the forecast framework, with segmentation dimensions spanning product type, technology, application, and end-use vertical alongside regional regulatory cluster intensity. CAGRs derived from weighted growth rate convergence across hardware shipment trajectories and service revenue expansion curves. Industry-specific inputs included neural network quantization adoption curves and ISO 26262 certification timeline distributions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese semiconductor foundries or accelerated FDA software-as-medical-device guidance revisions would shift outcomes. Quarterly review of foundry utilization rates, EU AI Act conformity assessment backlog, and automotive predictive maintenance subscription attach rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Artificial Intelligence (AI)
Global Artificial Intelligence in E-Commerce Market
Artificial Intelligence (AI)
Artificial Intelligence in Telecommunication Market
Artificial Intelligence (AI)
AI Virtual Assistants Market
Artificial Intelligence (AI)
Automotive Gesture Recognition Market
Artificial Intelligence (AI)
Commercial Artificial Intelligence Market
Artificial Intelligence (AI)
AI Document Generator Market
Artificial Intelligence (AI)
Global Artificial Intelligence in Life Science Market
Artificial Intelligence (AI)
AI Image Recognition Market
Artificial Intelligence (AI)
Artificial Intelligence HPC Cloud Market
Artificial Intelligence (AI)
Cognitive Systems Market
Artificial Intelligence (AI)
Intelligent Personal Assistant Market
Artificial Intelligence (AI)
Artificial Intelligence for IT Operations (Aiops) Market
Artificial Intelligence (AI)
Enterprise Generative AI Market
Artificial Intelligence (AI)
Global Augmented Intelligence Market
Artificial Intelligence (AI)
AI in Construction Market
Artificial Intelligence (AI)
Context Aware Computing Market