
 Global Medical Drones Market | 2026-2036
Global Medical Drones Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Drones Market Foresight
Emergency medical response networks are rotating toward autonomous drone fleets as first-mile logistics partners. Zipline Inc. dominates Africa's medical drone corridors with fixed-wing platforms that sustain beyond-visual-line-of-sight operations across Rwanda and Ghana. Wingcopter leverages tilt-rotor engineering to anchor European last-mile vaccine distribution, while Matternet specializes in urban hospital-to-laboratory networks that control Swiss and US metropolitan airspace.
Medical drones are unmanned aerial vehicles engineered for temperature-controlled payload transport, typically featuring insulated compartments, GPS-guided navigation, and real-time telemetry for biological sample integrity. Their primary commercial purpose is to bypass ground infrastructure limitations for time-critical healthcare logistics. Fixed-wing drones lead inter-facility routes over rural terrain where range and speed outweigh vertical landing needs, while rotary-wing systems capture urban emergency response where precision hover capability determines landing site access. Hybrid platforms represent the fastest-growing architecture as operators seek to consolidate runway-independent deployment with extended endurance.
The FAA's Part 135 unmanned aircraft certification and the EU's U-space regulatory framework shape operator market access by mandating detect-and-avoid systems and command-link redundancy. EASA's specific category operational authorizations further segment European deployment by risk class, directing investment toward certified platforms. Stakeholders must monitor evolving beyond-visual-line-of-sight rulemaking across civil aviation authorities, as regulatory convergence or divergence will determine which hardware architectures achieve cross-border economies of scale.
Market Dynamics
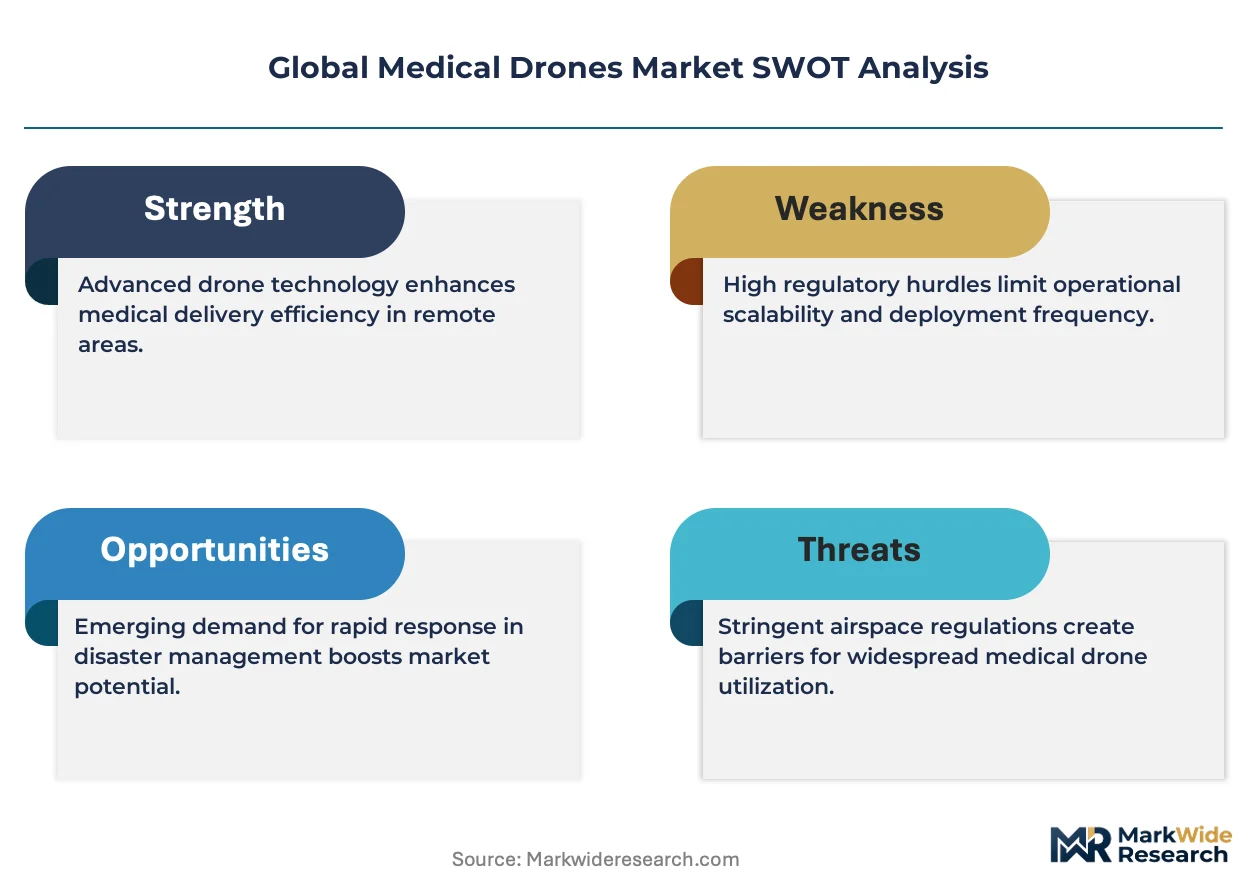
Beyond-visual-line-of-sight certification pathways are compressing operator qualification timelines while fragmenting competitive positioning between fixed-wing incumbents and hybrid-platform challengers. Regulatory convergence across civil aviation authorities determines which hardware architectures achieve cross-border economies of scale.
Growth Catalysts
- FAA Part 135 unmanned aircraft certification:The FAA's air carrier pathway accelerates commercial operator qualification timelines for autonomous medical logistics networks.
- Rwanda and Ghana national drone corridors:These anchored distribution infrastructures demonstrate scalable rural healthcare delivery models that neighboring countries are replicating.
- Hybrid tilt-rotor engineering:Consolidated runway-independent deployment with extended endurance addresses both urban precision landing and inter-facility range requirements.
Market Restraints
- Lithium-ion battery supply concentration:Cell production gravity in East Asia creates input cost volatility and geopolitical exposure for drone manufacturers.
- Command-link redundancy mandates:EASA's specific category operational authorizations impose technical certification costs that favor scaled operators over regional entrants.
- Ground infrastructure substitution:Cold-chain road networks and motorcycle courier systems retain cost advantages for non-urgent pharmaceutical distribution.
Strategic Opportunities
- Indian pharmaceutical cold-chain:Underpenetrated last-mile vaccine distribution to rural health sub-centers lacks temperature-controlled aerial logistics coverage.
- EU U-space regulatory framework:Mandated detect-and-avoid systems create certified-platform preference tailwinds for compliant hardware vendors.
- AI-powered predictive dispatch:Convergence of machine learning algorithms with real-time epidemiological surveillance enables pre-positioned medical supply staging.
Industry Challenges
- Aviation-grade software certification:DO-178C compliance timelines for autonomous navigation systems extend product development cycles.
- Legacy hospital inventory integration:ERP system interoperability with drone fleet management platforms requires custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Drones Market |
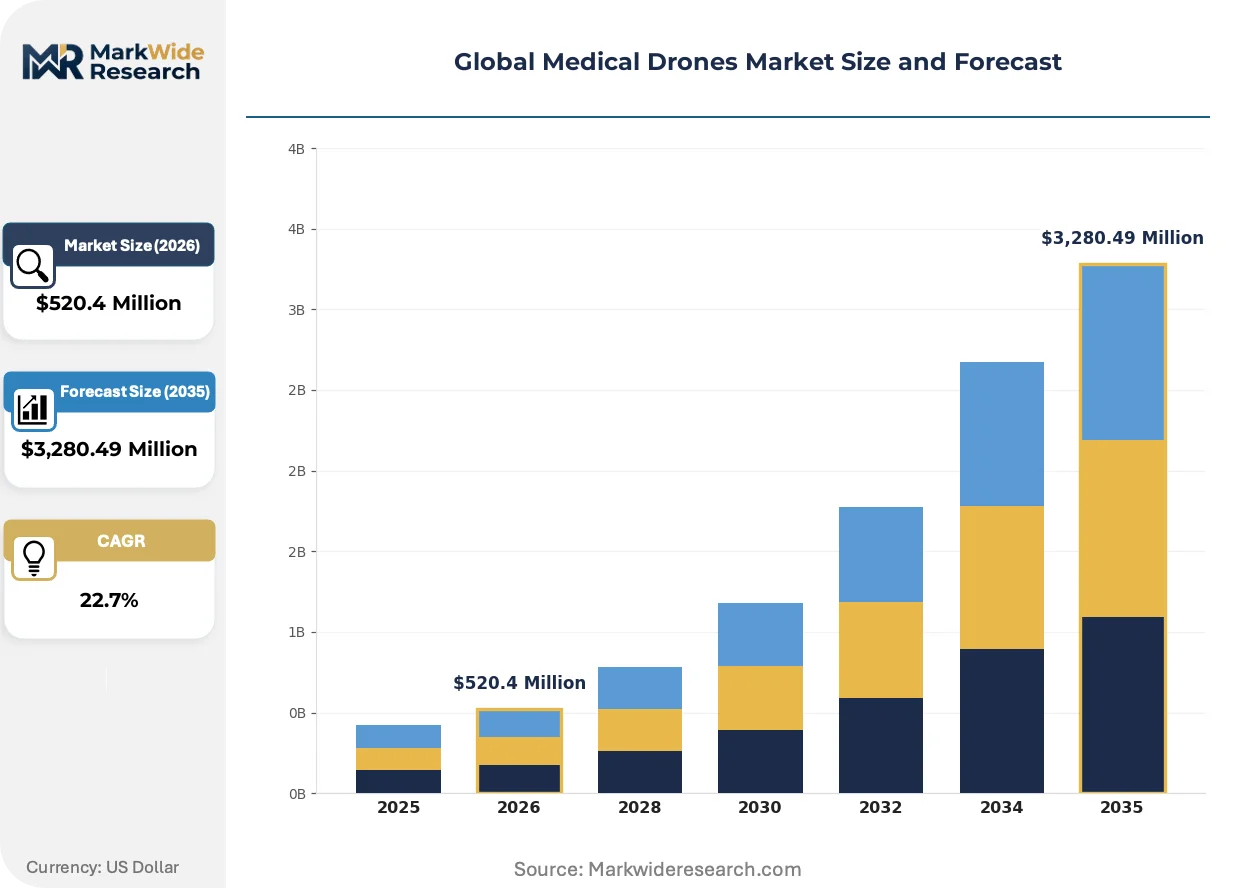
| Market Size in 2026 | $520.4 Million |
| Market Size in 2035 | $3,280.49 Million |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
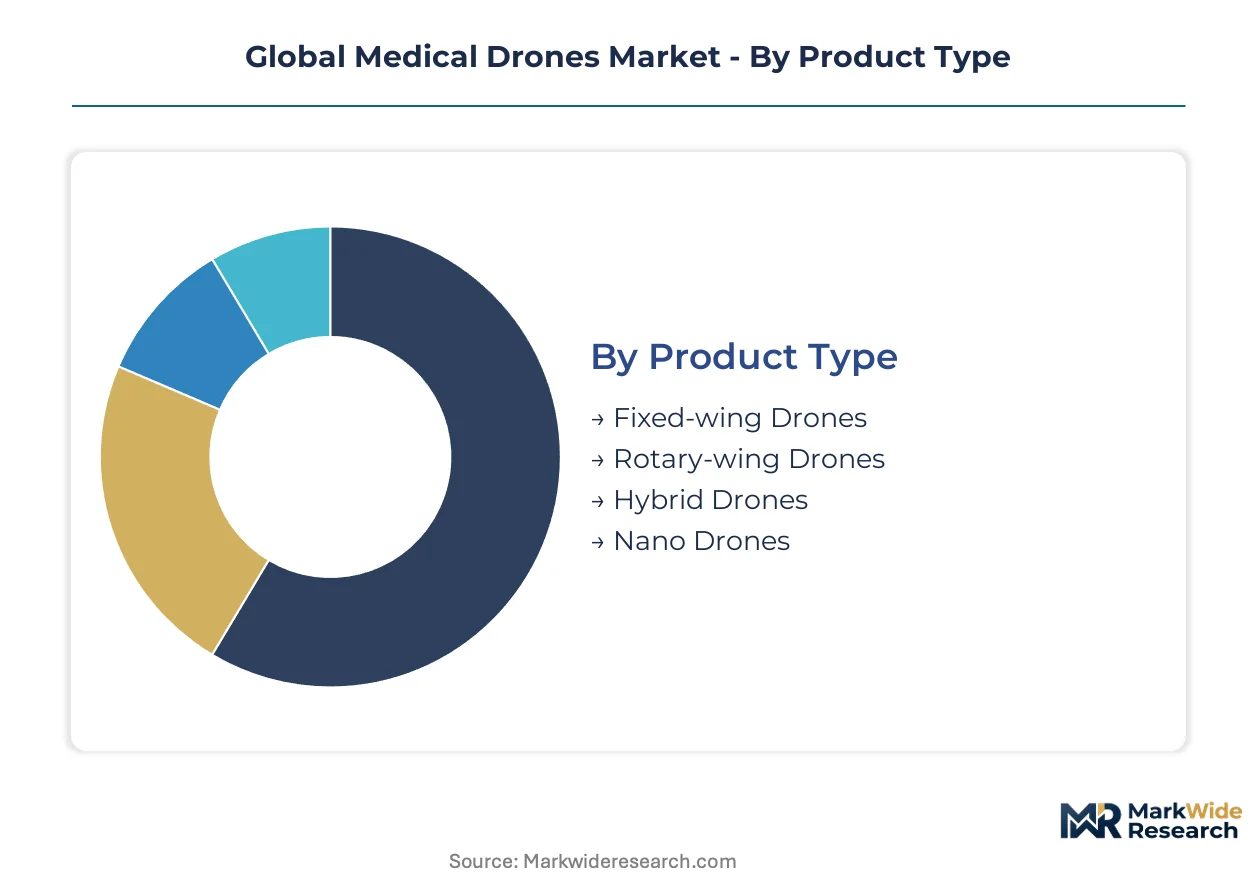
| Segmentation | Product Type: Fixed-wing Drones, Rotary-wing Drones, Hybrid Drones, Nano Drones Application: Blood Sample Transport, Vaccine Delivery, Emergency Medical Response, Medical Supply Distribution End User: Hospitals, Ambulance Services, Diagnostic Centers, Research Institutes Deployment: On-demand Delivery, Scheduled Delivery, Remote Area Supply, Urban Area Support |
| Companies Covered | Zipline Inc., Wingcopter, Matternet, Swoop Aero Pty Ltd, Volansi, Inc., EHang Holdings Limited, Draganfly Inc., Avy, Vayu Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Drones Market Shifts & Advancements
Autonomous navigation architectures are fragmenting competitive positioning between specialized hardware vendors and vertically integrated health system operators. Three convergent developments reshape how aerial medical logistics networks deploy and scale.
Hybrid propulsion systems is fragmenting platform specialization across the market. These architectures combine multi-rotor vertical takeoff capability with fixed-wing cruise efficiency. European vaccine distributors and African emergency response networks are adopting tilt-rotor designs at accelerating pace. The technology is fragmenting procurement patterns as buyers abandon single-purpose fleet strategies.
EASA's U-space regulatory framework mandates detect-and-avoid capabilities and command-link redundancy for beyond-visual-line-of-sight operations. This industrial consequence elevates certified-platform barriers to entry while compressing timelines for compliant operators. Swiss and German metropolitan hospital-to-laboratory networks are responding by consolidating procurement around pre-certified hardware architectures.
Hospital procurement departments are unbundling emergency response logistics from traditional ground-courier contracts. This behavior change disrupts established pharmaceutical distribution channels as health systems establish direct relationships with aerial logistics operators. The shift is most visible in Swiss cantonal hospital networks and Ghana's regional health directorates.
Global Medical Drones Market Segmentation
Medical drone procurement patterns diverge sharply across operational contexts, with regulatory certification requirements and payload specifications driving hardware selection. Understanding these segment boundaries clarifies where capital deployment concentrates and which technology architectures capture margin.
Product Type:
EASA's specific category operational authorizations and FAA Part 135 certification pathways create divergent compliance burdens across airframe architectures, directing procurement toward pre-certified platforms.
- Fixed-wing Drones:Long-endurance airframes with extended range capability dominate inter-facility routes across Rwanda's national drone corridor and Ghana's distribution networks. These systems sacrifice vertical landing for fuel efficiency, making them dependent on prepared airstrips or catapult launchers in rural terrain where ground infrastructure remains sparse.
- Rotary-wing Drones:Multi-rotor platforms enable precision hover capability for hospital rooftop landings and confined urban environments. Swiss metropolitan hospital-to-laboratory networks and US emergency response operators favor these systems where landing site flexibility outweighs range limitations, though battery endurance constrains operational radius to sub-50 kilometer missions.
- Hybrid Drones:Tilt-rotor configurations consolidate vertical takeoff with fixed-wing cruise efficiency, attracting European vaccine distributors seeking runway-independent deployment without sacrificing payload-range performance.
- Nano Drones:Sub-2kg platforms target laboratory sample transport within hospital campuses and controlled indoor environments where regulatory thresholds for unmanned aircraft certification do not apply.
Fixed-wing systems handle the majority of throughput across established African corridors; hybrid platforms are gaining share fastest as operators consolidate fleet architectures.
Application:
Payload temperature requirements and time-criticality determine route economics, with cold-chain biological materials commanding premium pricing over ambient medical supplies.
- Blood Sample Transport:Diagnostic networks require continuous temperature logging and shock-resistant containment for hematological integrity. Ghana's regional health directorates and Swiss cantonal hospital systems have established dedicated aerial corridors for stat laboratory access, compressing turnaround times from hours to minutes for time-sensitive coagulation panels.
- Vaccine Delivery:Ultra-cold-chain requirements for mRNA formulations drive insulated payload compartment specifications and real-time telemetry integration. Wingcopter's tilt-rotor deployments across European last-mile distribution networks demonstrate scalable models for temperature excursion elimination in rural immunization campaigns.
- Emergency Medical Response:Defibrillator and antivenom deployment to inaccessible trauma scenes prioritizes speed over payload mass, favoring rotary-wing systems with sub-10-minute response windows.
- Medical Supply Distribution:Ambient pharmaceuticals and consumables represent volume opportunities where cost parity with ground couriers determines adoption timing.
Blood sample transport commands the highest per-kilometer revenue; vaccine delivery is expanding most quickly as national immunization programs integrate aerial logistics.
End User:
Procurement authority and fleet integration complexity segment the customer base, with centralized health systems achieving faster deployment timelines than fragmented provider networks.
- Hospitals:Cantonal hospital networks in Switzerland and regional health directorates in Ghana direct capital budgets toward dedicated aerial logistics infrastructure, establishing direct operator relationships that bypass traditional pharmaceutical distributors.
- Ambulance Services:Emergency medical systems evaluate drone deployment as force multipliers for wilderness rescue and mass-casualty incidents where ground access is compromised.
- Diagnostic Centers:Independent laboratory chains seek hub-and-spoke sample consolidation to centralized testing facilities, creating demand for scheduled inter-facility routes.
- Research Institutes:Clinical trial logistics and biological specimen export compliance drive specialized payload certification requirements for temperature-sensitive investigational materials.
Hospital networks dominate current procurement volume; diagnostic center partnerships are climbing the fastest as laboratory consolidation accelerates.
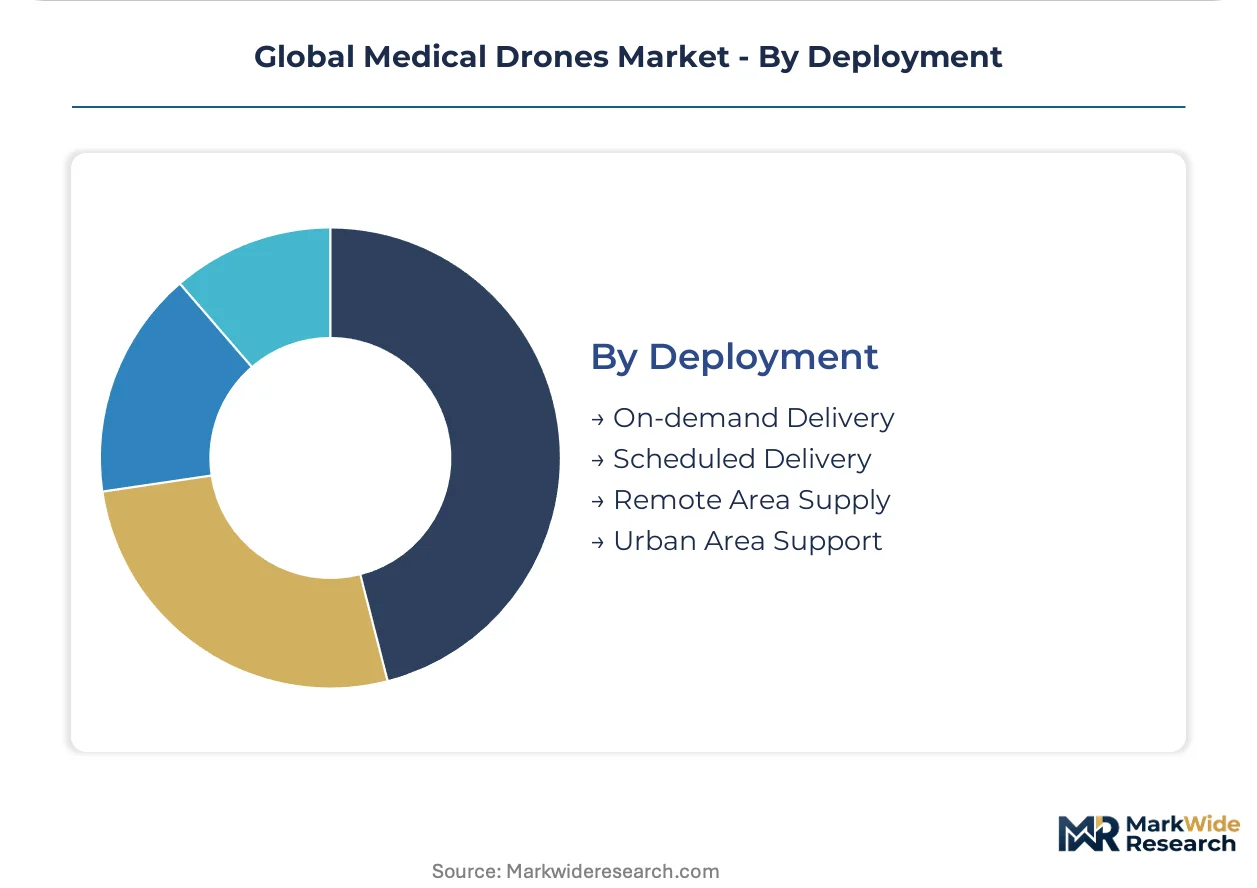
Deployment:
Route predictability and demand forecasting sophistication determine operational model selection, with scheduled networks achieving unit economics that on-demand services cannot match.
- On-demand Delivery:Emergency response networks require predictive dispatch algorithms and pre-positioned supply staging to compress response windows below critical clinical thresholds.
- Scheduled Delivery:Recurring inter-facility routes between regional hospitals and reference laboratories enable payload consolidation and return-leg utilization that improves asset turns.
- Remote Area Supply:Rwanda's national drone corridor demonstrates how government-anchored distribution infrastructure creates predictable demand baselines for operator investment.
- Urban Area Support:Dense metropolitan airspace requires detect-and-avoid system integration and U-space regulatory compliance that elevates platform certification costs.
Scheduled delivery captures the majority of flight hours; remote area supply is the fastest mover on share as national drone corridor programs proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rwanda exports operational blueprints to Ghana and Malawi, establishing a knowledge corridor that anchors sub-Saharan drone logistics deployment. European operators import certification protocols from Swiss and German regulators, while Asian pharmaceutical distributors source hybrid-platform engineering from European and American manufacturers.
United States
Emergency response networks in North Carolina and California deploy defibrillator-carrying rotary-wing systems for cardiac arrest intervention. FAA Part 135 unmanned aircraft certification compresses operator qualification timelines, enabling Beyond Visual Line of Sight commercial routes. The Research Triangle Park cluster in North Carolina anchors hospital-to-laboratory sample transport networks that integrate with major academic medical centers.
Germany
Island communities in the North Sea and rural Bavarian health districts drive demand for vaccine delivery infrastructure that bypasses winter road closures. EASA's U-space regulatory framework mandates detect-and-avoid systems and command-link redundancy for autonomous operations. The Munich-Stuttgart corridor hosts tilt-rotor engineering development centers that supply European pharmaceutical distributors with certified hybrid platforms.
Switzerland
Cantonal hospital networks in Zurich, Geneva, and Basel pioneered urban hospital-to-laboratory aerial corridors for stat diagnostic sample transport. Swissmedic's operational authorizations for specific-risk unmanned aircraft categories elevate certified-platform barriers to entry. The Lake Geneva region concentrates drone fleet management software development that integrates with hospital ERP systems.
India
Rural health sub-centers in Telangana and Karnataka lack temperature-controlled last-mile vaccine distribution coverage, creating underpenetrated demand for cold-chain aerial logistics. The Directorate General of Civil Aviation's conditional exemptions for experimental drone operations enable pilot programs for medical supply delivery. The Hyderabad-Bengaluru corridor anchors pharmaceutical manufacturing clusters that require outbound specimen transport for contract research organizations.
Australia
Remote indigenous communities in Queensland and the Northern Territory face medical supply access challenges that ground infrastructure cannot address cost-effectively. The Civil Aviation Safety Authority's remotely piloted aircraft systems regulations enable Beyond Visual Line of Sight operations for emergency medical response. The Brisbane-Southeast Queensland cluster hosts operators deploying fixed-wing platforms for inter-facility routes across vast rural catchment areas.
Global Medical Drones Market Competitive Landscape
Player mix skews toward vertically integrated health system operators and specialized hardware vendors with certified-platform portfolios. Market structure concentrates procurement authority around national health ministries and cantonal hospital networks that establish direct operator relationships. Two strategic archetypes dominate: African corridor specialists with Beyond Visual Line of Sight operational scale, and European certification-focused engineering houses with U-space compliance. Competitive moves center on fleet architecture consolidation and regulatory pre-certification investments that compress deployment timelines.
Within the African corridor specialist tier, Zipline Inc. and Swoop Aero Pty Ltd represent operational-scale archetypes that anchor national drone distribution infrastructure. Among European engineering-focused vendors, Wingcopter occupies a position exemplifying tilt-rotor hybrid development for vaccine distribution networks. Matternet sits within the urban hospital-to-laboratory specialization, reflecting metropolitan airspace integration requirements. These three companies illustrate how geographic deployment focus and regulatory certification strategy determine competitive positioning.
| Leading Market Players |
|---|
| Zipline Inc. |
| Wingcopter |
| Matternet |
| Swoop Aero Pty Ltd |
| Volansi, Inc. |
| EHang Holdings Limited |
| Draganfly Inc. |
| Avy |
| Vayu Inc. |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation agreements between African national health ministries and certified drone operators lock in both fleet access and per-flight pricing visibility across Rwanda's drone corridor and Ghana's regional distribution networks. These contractual structures insulate public procurement from lithium-ion cell volatility while constraining operator margin flexibility.
Pricing Analysis
Fixed-wing platform pricing gaps separate current-gen hybrid tilt-rotor systems from prior-gen pure multi-rotor designs and developmental autonomous swarming architectures. Three-tier pricing structure across premium certified, standard compliant, and economy experimental tiers tracks EASA specific-category authorization levels and FAA Part 135 certification status. Cost compression in economy-tier hardware is intensifying because Chinese component suppliers are flooding export markets with uncertified airframes. Hospital procurement committees exhibit highest price sensitivity, while emergency response agencies prioritize response-time guarantees over unit economics.
Supply Chain Analysis
Port congestion along the Shanghai-Rotterdam trade lane elevates inbound logistics costs for European drone manufacturers sourcing composite airframe materials and avionics subassemblies. Cell production concentrates in China, South Korea, and Japan, creating battery pack dependencies that tether fleet operators to East Asian supply schedules. Single-source vulnerability in aviation-grade GPS module sourcing poses structural risk as semiconductor foundry capacity prioritizes automotive and consumer electronics. Distribution runs through national health ministry tender processes in sub-Saharan Africa and cantonal hospital consortiums in Switzerland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Beyond-visual-line-of-sight regulatory convergence represents a technological inflection that compresses deployment timelines and consolidates procurement around pre-certified hardware platforms.
For Market Incumbents: Compound fleet utilization rates through backward integration into battery cell refurbishment facilities in Rwanda and Ghana, countering lithium supply concentration. Deepen vertical control over ground station maintenance networks to lock out regional challengers lacking EASA command-link redundancy certification. For New Entrants and Emerging Players: FAA Part 135 certification fast-tracks enable market entry through white-space targeting of Indian rural health sub-centers lacking temperature-controlled aerial logistics. Penetrate diagnostic laboratory hub-and-spoke networks in Telangana and Karnataka via scheduled sample consolidation contracts rather than emergency response competition. For Investors and Strategic Acquirers: African corridor specialists with established government relationships and BVLOS operational scale represent the acquisition target archetype with strongest defensible positioning. Watch for EASA-U.S. regulatory reciprocity agreements as the inflection signal that would unlock cross-border platform certification economies and trigger consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Certification Investment | EASA specific-category authorization compresses deployment timelines for compliant hardware vendors. |
| Hybrid Platform Fleet Consolidation | Tilt-rotor engineering addresses both urban precision landing and inter-facility range requirements. |
| National Drone Corridor Partnership | Government-anchored distribution infrastructure creates predictable demand baselines for operator investment. |
| AI-Powered Predictive Dispatch Development | Machine learning convergence with epidemiological surveillance enables pre-positioned medical supply staging. |
| Hospital ERP System Integration | Custom middleware development bridges legacy inventory systems with drone fleet management platforms. |
Research Methodology
Cross-validation between regulatory filing analysis and operator deployment data anchors the qualitative findings in this study. Primary interviews with fleet operations directors, civil aviation authority certification leads, hospital procurement managers, and biomedical logistics coordinators combined with secondary validation against FAA Part 135 dockets, EASA operational authorization registers, and national health ministry tender records. Bottom-up route density modeling and top-down pharmaceutical cold-chain spend analysis complete the triangulation.
Sensitivity analysis across platform architecture adoption curves, battery cost decline trajectories, and regulatory timeline scenarios shapes the analytical framework over the projection horizon. Segmentation dimensions include airframe type, payload temperature requirement, deployment model, end-user procurement authority, and regional regulatory cluster. CAGRs derive from fleet deployment run rates and per-kilometer pricing convergence with ground courier alternatives, incorporating hospital network consolidation pace and diagnostic laboratory centralization trends as industry-specific inputs.
Decision-makers should treat outputs as directional under base assumptions of continued FAA-EASA regulatory convergence and stable lithium supply; material deviation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Bionic Implant Market
Medical Devices
Metered Dose Squeeze Dispenser Market
Medical Devices
Peri-Implantitis Market
Medical Devices
Global Automated Suturing Devices Market
Medical Devices
Knee Braces Market
Medical Devices
Cardiac Rhythm Management (CRM) Devices Batteries Market
Medical Devices
Electrophysiology Ablation Market
Medical Devices
Light Therapy Market
Medical Devices
Military Wearable Medical Device Market
Medical Devices
Airway Clearance Devices System Market
Medical Devices
Sensor Based Smart Catheters Market
Medical Devices
Spain Aesthetic Devices Market
Medical Devices
Inhaled Corticosteroid Device Market
Medical Devices
Global Interventional Neurology Devices Market
Medical Devices
Global Urethral Dilator Market
Medical Devices
Ligament Stabilizers Market