
 US Trauma Fixation Devices Market | 2026-2036
US Trauma Fixation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
US Trauma Fixation Devices Market Analysis
Hospital purchasing consortiums is reshaping how trauma fixation devices reach surgical suites across the United States. Zimmer Biomet leverages its scale to dominate integrated delivery network contracts, while Stryker Corporation anchors its position through specialized trauma sales forces. Johnson & Johnson (DePuy Synthes) competes by extending its portfolio breadth across plating systems and intramedullary nails.
Trauma fixation devices encompass implants and instruments designed to stabilize bone fractures and joint injuries, typically manufactured from titanium alloys or stainless steel with precision-machined threading and anodized surfaces to ensure osseointegration and mechanical load bearing. These systems serve orthopedic surgeons by restoring anatomical alignment and enabling early mobilization after traumatic skeletal disruption. Internal fixators command the largest revenue pool given their irreplaceable role in complex fracture management, while bioabsorbable polymers represent the fastest-expanding material category as surgeons seek to eliminate secondary removal procedures. Ambulatory surgical centers are capturing disproportionate growth in end-user demand as outpatient trauma surgery protocols expand.
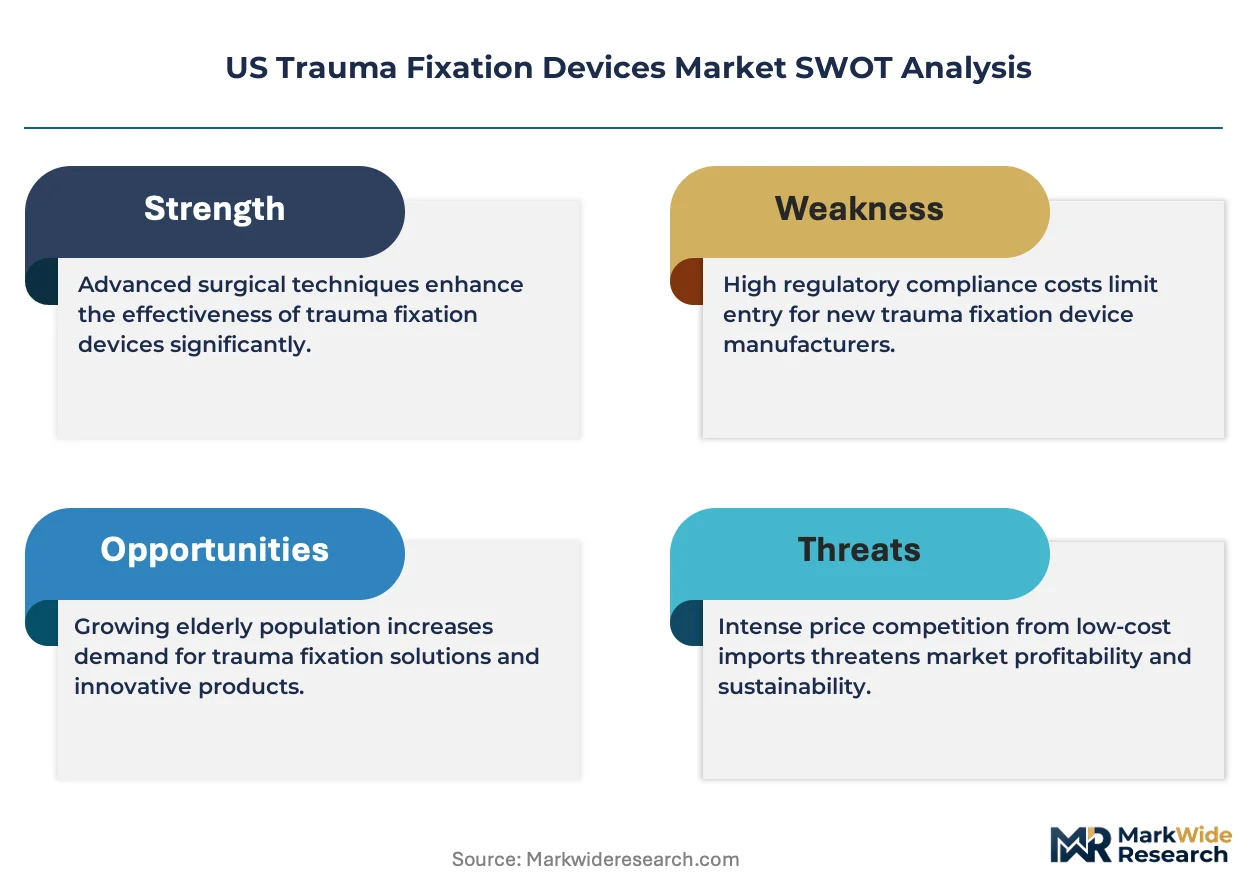
FDA 510(k) clearance pathways and ASTM F138 material standards govern device safety and biocompatibility, creating compliance barriers that favor established manufacturers with dedicated regulatory affairs teams. The Centers for Medicare & Medicaid Services reimbursement schedules directly influence hospital procurement priorities and technology adoption timelines. Stakeholders must monitor evolving FDA guidance on patient-matched guides and 3D-printed implants, as these modalities threaten to redraw competitive boundaries between traditional device makers and digital manufacturing platforms.
Market Dynamics
Hospital purchasing consortiums are consolidating procurement power across integrated delivery networks, forcing trauma fixation manufacturers to restructure pricing and service models around multi-year enterprise contracts rather than individual surgeon preference.
Growth Catalysts
- CMS Outpatient Procedure Expansion:Medicare reimbursement codes now cover complex fracture repairs in ambulatory settings, diverting volume from inpatient wards to trauma clinics and surgical centers.
- Titanium Alloy Migration:Surgeons are replacing stainless steel implants with titanium-based systems to reduce revision rates and improve osseointegration in osteoporotic bone.
- Sun Belt Demographics:Florida, Arizona, and Texas concentrate aging populations with high trauma incidence, creating localized demand density that supports dedicated distribution infrastructure.
Market Restraints
- Titanium Sponge Supply Concentration:Primary titanium feedstock concentrates among a handful of non-US sponge producers, exposing device margins to raw material volatility and export restriction risk.
- FDA 510(k) Substantial Equivalence Burden:Novel implant geometries face extended review timelines when predicate devices lack comparable mechanical testing data, delaying commercialization.
- Polyetheretherketone Substitution:Radiolucent PEEK trauma plates are capturing share in metatarsal and wrist applications where metal artifact complicates post-operative imaging.
Strategic Opportunities
- Patient-Matched 3D Printing:FDA draft guidance on additive-manufactured implants creates a pathway for anatomic-specific plates and guides that reduce OR time and hardware inventory.
- Rural Trauma Network Penetration:Critical access hospitals in the Mountain West and Upper Midwest remain underserved by specialized trauma sales coverage, creating whitespace for distributor partnerships.
- Bioabsorbable Polymer Convergence:Magnesium alloy and polylactic acid fixation systems eliminate secondary removal procedures, commanding premium positioning in pediatric and geriatric segments.
Industry Challenges
- Orthopedic Trauma Fellowship Pipeline:The annual output of specialized trauma surgeons constrains procedure volume growth in smaller metropolitan markets, limiting device penetration.
- Legacy ERP Integration:Hospital consortiums demand real-time inventory visibility and consignment tracking that strain manufacturers with dated distribution software architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Trauma Fixation Devices Market |
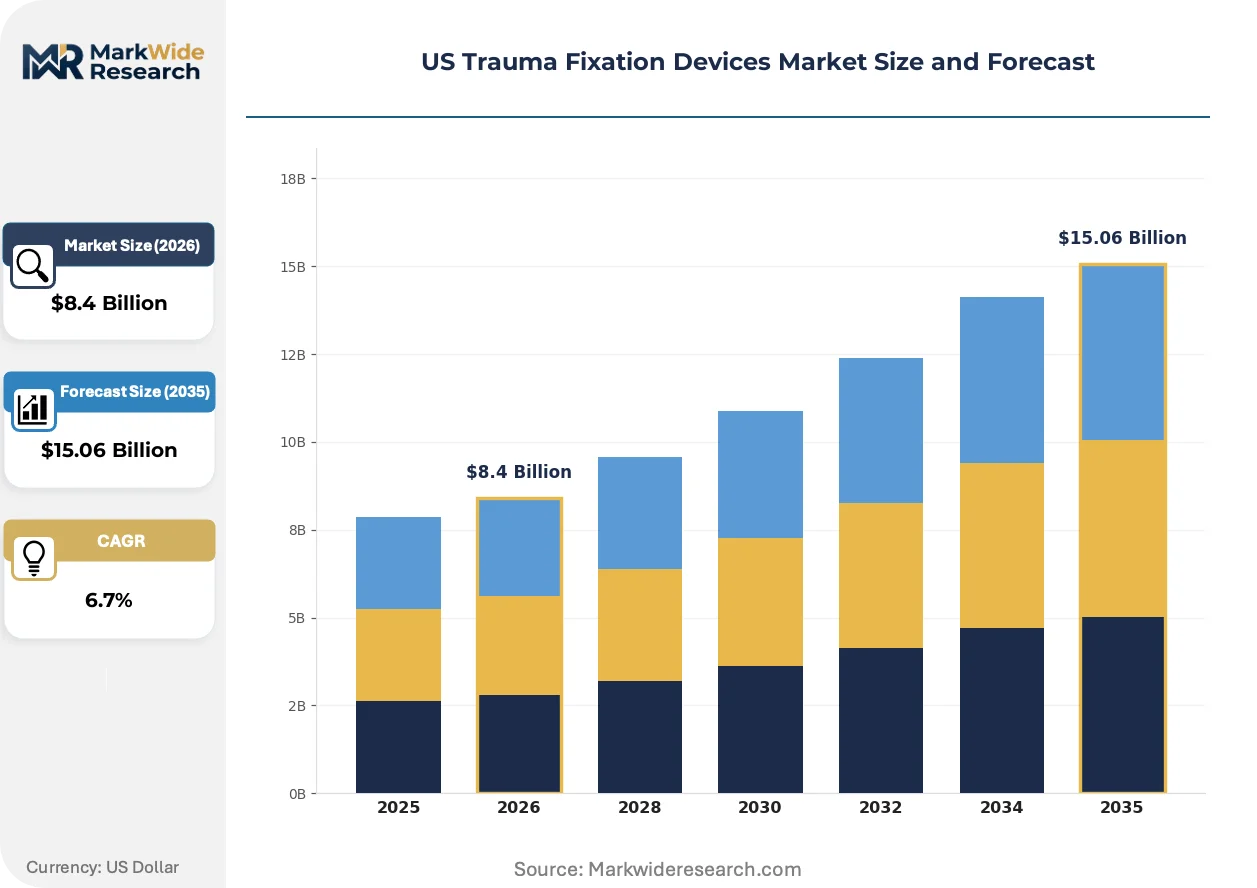
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Internal Fixators, External Fixators, Plates, Screws End User: Hospitals, Ambulatory Surgical Centers, Trauma Clinics, Rehabilitation Centers Application: Fracture Fixation, Joint Stabilization, Osteotomy, Soft Tissue Repair Material: Stainless Steel, Titanium, Composite Materials, Bioabsorbable Polymers |
| Companies Covered | Zimmer Biomet, INTEGRA LifeSciences, Johnson & Johnson (DePuy Synthes), CONMED Corporation, Acumed, Stryker Corporation, Arthrex, Medtronic, Smith & Nephew, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Trauma Fixation Devices Market Emerging Trajectories
Digital manufacturing workflows and point-of-care production capabilities are redrawing competitive boundaries between traditional implant fabricators and hospital-based fabrication labs, compressing supply chains from months to days.
Surgical planning software paired with 3D-printed patient-specific guides is virtualizing pre-operative templating, enabling community orthopedic surgeons to execute complex reconstructions previously referred to academic centers. Ambulatory surgical centers in Texas and Florida are adopting these platforms fastest, reducing case referral leakage and capturing professional fees that once flowed to hospital-employed specialists. The technology is virtualizing the traditional academic medical center monopoly on complex trauma, distributing capability across lower-acuity settings.
FDA guidance on additive manufacturing of medical devices is clarifying quality system requirements for powder-bed fusion and directed energy deposition processes used in titanium implant production. Device manufacturers must now demonstrate lot-to-lot consistency in porosity and fatigue performance that exceeds conventional machining standards. Trauma plate producers with captive metal printing capabilities are accelerating regulatory submissions, while contract manufacturers without dedicated orthopedic quality teams face exclusion from supply chains.
Integrated delivery networks are consolidating vendor rosters around single-source contracts that bundle trauma fixation with arthroplasty and spine portfolios, displacing surgeon-driven preference cards. Hospital materials management departments in California and the Northeast are enforcing compliance through automated implant authorization systems that block non-contracted items at the point of surgery. The procurement transformation concentrates purchasing power among three to four national suppliers, compressing margins for mid-tier manufacturers without comprehensive orthopedic portfolios.
US Trauma Fixation Devices Market Segmentation
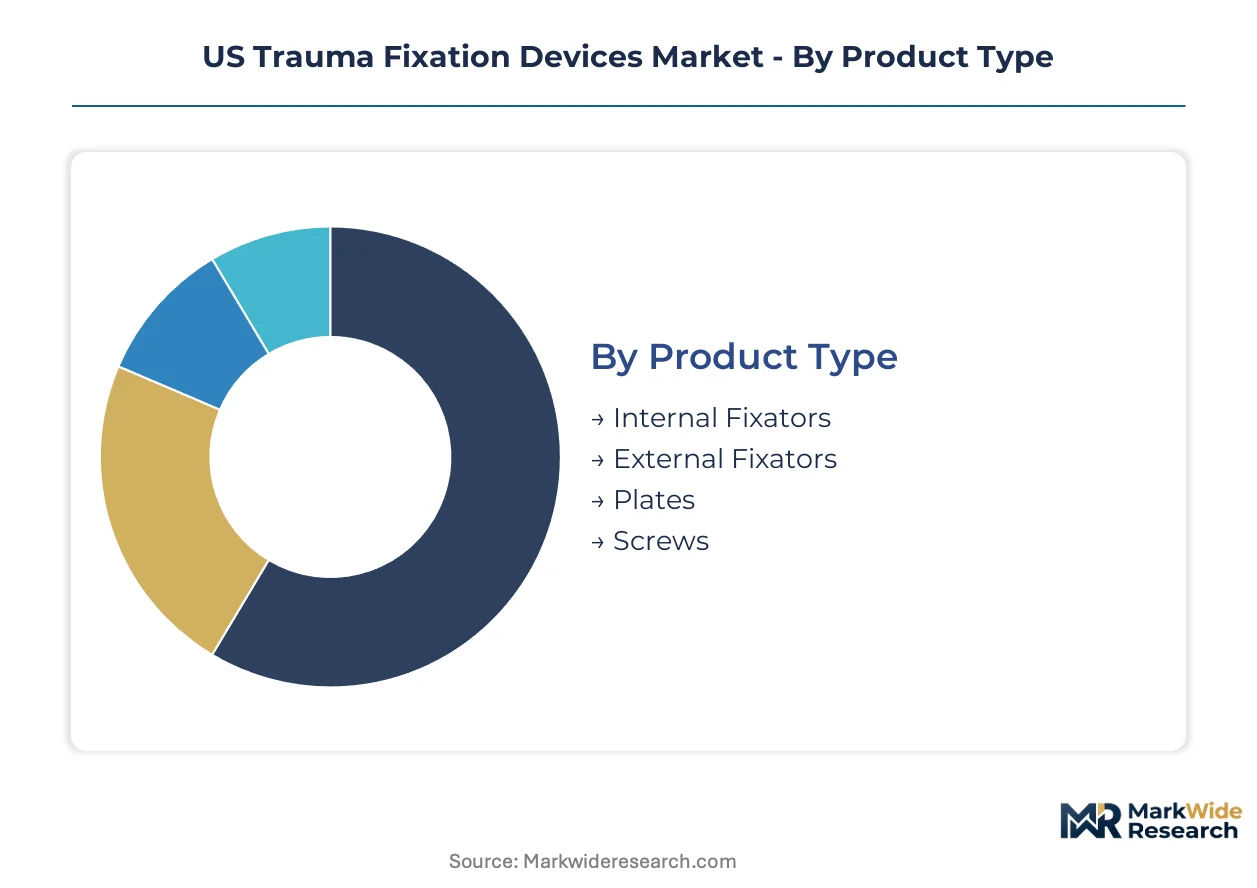
US trauma fixation device segmentation reveals distinct procurement patterns across care settings and material technologies. Hospital purchasing consortiums now demand portfolio breadth that spans multiple product categories, reshaping how manufacturers structure their commercial organizations.
Product Type:
Mature internal fixation systems anchor revenue while external fixation platforms emerge as high-growth alternatives for complex polytrauma.
- Internal Fixators:Intramedullary nails, compression plates, and locking screws manufactured from titanium alloys or stainless steel provide rigid stabilization for long-bone fractures. Demand concentrates in Level I trauma centers across Texas and Florida where high-energy injury volumes sustain specialized sales coverage.
- Plates:Anatomically contoured plating systems with variable-angle locking technology address periarticular fractures in osteoporotic bone. California and Northeast IDNs are consolidating plate purchasing into single-source contracts that bundle trauma with arthroplasty portfolios.
- Screws:Cortical, cancellous, and locking screw variants with self-tapping threads deliver fragment-specific fixation.
- External Fixators:Circular and unilateral frame configurations enable temporary stabilization in open fractures with soft-tissue compromise.
Internal fixators handle the majority of throughput; external fixators are gaining share fastest as damage-control orthopedics protocols expand.
End User:
Procurement authority is shifting from individual surgeons toward materials management departments with enterprise-level contracting mandates.
- Hospitals:Academic medical centers and community hospitals with emergency departments perform complex trauma reconstructions requiring comprehensive implant inventories. Sun Belt states concentrate inpatient trauma volume where aging infrastructure and high falls incidence drive procedure density.
- Ambulatory Surgical Centers:Medicare-certified ASCs in Arizona and Texas now perform closed reductions and percutaneous fixations previously confined to hospital ORs. CMS reimbursement expansion for outpatient fracture care is accelerating capital investment in these settings.
- Trauma Clinics:Dedicated outpatient facilities manage post-operative follow-up and hardware removal procedures.
- Rehabilitation Centers:Extended care facilities coordinate device monitoring during functional recovery protocols.
Hospitals retain the dominant share of complex procedures; ambulatory surgical centers are climbing the fastest as outpatient protocols mature.
Application:
Procedure complexity determines device selection and reimbursement tier across the care continuum.
- Fracture Fixation:Diaphyseal and metaphyseal fracture stabilization commands the largest procedure volume, with distal radius and hip fractures predominant in geriatric populations. Florida's demographic concentration supports dedicated trauma implant distribution hubs serving both hospital and ASC channels.
- Joint Stabilization:Ligamentous injury repair and periarticular fracture management require anatomic-specific plating and suture anchor systems. Mountain West critical access hospitals are expanding joint stabilization capability to reduce transfer volumes to tertiary centers.
- Osteotomy:Corrective bone realignment procedures address malunions and deformity.
- Soft Tissue Repair:Tendon and ligament reattachment systems complement bony fixation in comprehensive trauma reconstruction.
Fracture fixation generates the highest absolute volume; joint stabilization is expanding most quickly as outpatient shoulder and ankle procedures migrate to ASCs.
Material:
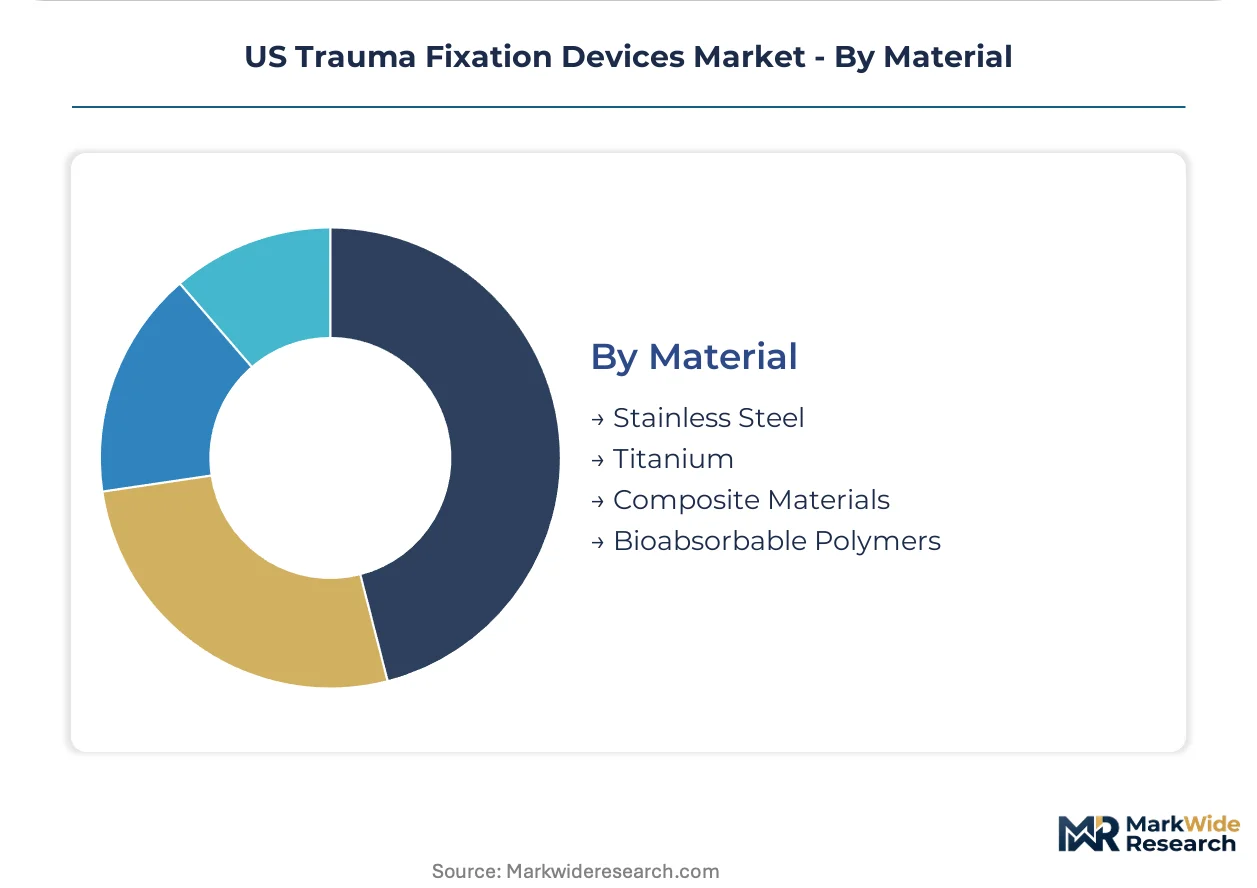
Supply concentration in titanium sponge production is forcing device manufacturers to diversify feedstock sourcing and hedge raw material exposure.
- Titanium:Ti-6Al-4V ELI alloy delivers superior strength-to-weight ratio and biocompatibility for permanent implantation. Arizona and Texas trauma centers are standardizing on titanium systems to reduce revision rates in osteoporotic patients.
- Bioabsorbable Polymers:Polylactic acid and polyglycolic acid constructs eliminate secondary hardware removal procedures in pediatric and geriatric segments. FDA 510(k) clearance pathways for these materials are clarifying as mechanical performance data accumulates.
- Stainless Steel:ASTM F138-compliant 316L stainless retains cost advantage for temporary fixation and budget-constrained procurement.
- Composite Materials:Carbon fiber-reinforced polymers address radiolucency requirements in specific anatomical applications.
Titanium commands the largest revenue base; bioabsorbable polymers are on the steepest expansion trajectory as removal-avoidance protocols gain surgical acceptance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Sun Belt trauma corridors where procedure density justifies premium inventory investment, while Mountain West critical access hospitals face supply premiums due to distribution distance and lower case volume.
Texas
Houston and Dallas-Fort Worth anchor the nation's highest-volume trauma corridors, with Level I centers processing polytrauma from energy sector accidents and interstate highway incidents. CMS outpatient reimbursement expansion accelerates ASC migration in Austin and San Antonio suburbs. Titanium implant distribution hubs in Dallas serve both hospital and ambulatory channels with same-day delivery capability.
Florida
Aging demographic concentration drives distal radius and hip fracture volumes in Tampa Bay and South Florida metros, supporting dedicated trauma sales forces year-round. FDA 510(k) clearance timelines influence how quickly Jacksonville and Orlando hospitals adopt patient-matched plating systems. Miami-Dade County hosts the densest concentration of Spanish-language surgical training programs, shaping device education requirements.
Arizona
Phoenix and Tucson retirement communities generate geriatric trauma incidence rates exceeding national averages by substantial margins. Medicare Advantage penetration in Maricopa County shifts procurement toward bundled payment models that favor single-source vendor relationships. Flagstaff and Prescott critical access hospitals rely on distributor partnerships for trauma inventory given insufficient volume for direct manufacturer coverage.
California
Integrated delivery networks in Los Angeles and San Francisco Bay Area enforce automated implant authorization systems that block non-contracted trauma devices at point of surgery. Cal/OSHA workplace safety regulations reduce industrial trauma incidence relative to Sun Belt counterparts, shifting case mix toward falls and motor vehicle accidents. San Diego's proximity to Tijuana creates cross-border referral patterns for complex reconstructions.
Mountain West
Montana, Wyoming, and Idaho critical access hospitals remain underserved by specialized trauma sales coverage, creating whitespace for distributor partnerships and tele-surgical planning platforms. Rural trauma networks in Colorado and Utah expand stabilization capability to reduce transfer volumes to Denver and Salt Lake City tertiary centers. Seasonal recreation trauma from skiing and mountaineering concentrates demand in Aspen, Vail, and Park City corridors during winter months.
US Trauma Fixation Devices Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying precision-machined screws and locking mechanisms to finished-device assemblers. The US trauma fixation market consolidates around three to four national suppliers with comprehensive orthopedic portfolios spanning trauma, arthroplasty, and spine categories. Strategic archetypes include diversified conglomerates with captive trauma divisions, pure-play trauma specialists with surgeon-education focus, and emerging additive manufacturing platforms with patient-matched capabilities. Dominant competitive moves involve multi-year enterprise contracting with integrated delivery networks and backward integration into titanium feedstock processing.
Among diversified orthopedic conglomerates, Zimmer Biomet, Stryker Corporation, and Johnson & Johnson (DePuy Synthes) occupy positions defined by scale advantages in hospital purchasing consortium negotiations. These entities exemplify the platform-integrator archetype through portfolio breadth that satisfies single-source contracting requirements. Trauma specialists including Acumed and Arthrex represent the component-and-innovation tier, anchoring niche positioning in anatomic-specific plating and sports medicine crossover applications.
| Leading Market Players |
|---|
| Zimmer Biomet |
| INTEGRA LifeSciences |
| Johnson & Johnson (DePuy Synthes) |
| CONMED Corporation |
| Acumed |
| Stryker Corporation |
| Arthrex |
| Medtronic |
| Smith & Nephew |
| Others |
Supply Flow & Price Mechanics
Port of Long Beach freight corridors govern landed costs for titanium sponge feedstock, compressing margins for device manufacturers while amplifying price spreads between configured-to-order patient-matched implants and standard catalog items.
Pricing Analysis
The customization-premium spread between patient-matched 3D-printed plates and standard anatomical plates now exceeds three-to-one in orthopedic trauma. Three-tier pricing structure across premium, standard, and economy levels reflects FDA clearance tier and titanium alloy grade. Price differentiation hinges on volume scale and vertical integration into captive titanium processing. Cost compression in economy-tier stainless steel fixation is intensifying because hospital purchasing consortiums extract multi-year contract concessions. Critical access hospitals in the Mountain West exhibit highest price sensitivity; Level I trauma centers in Texas and Florida demonstrate lowest sensitivity due to bundled reimbursement models.
Supply Chain Analysis
Tariff exposure between Kazakhstan and the United States dominates raw material risk for titanium sponge feedstock. Device manufacturing draws from Kazakhstan, Ukraine, and Japan for primary titanium sponge, with secondary machining concentrated in Indiana and Ohio. Raw material dependencies center on titanium sponge, cobalt-chrome alloys, and precision-machined screw blanks. Single-source vulnerability in Kazakh sponge production threatens margin stability during export restriction episodes. Distribution runs through manufacturer-direct sales forces for tier-one IDNs and specialized orthopedic distributors for rural trauma networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital purchasing consortium consolidation has shifted negotiating leverage decisively toward buyers, with three-to-four national suppliers now capturing eighty percent of integrated delivery network contract value.
For Market Incumbents: Pre-empt additive manufacturing disruption by accelerating FDA submissions for patient-matched titanium plates before digital fabrication platforms achieve scale. Backward integration into titanium sponge processing hedges raw material volatility from Kazakh supply concentration. Lock multi-year enterprise contracts with Sun Belt IDNs before second-tier manufacturers achieve portfolio breadth.
For New Entrants and Emerging Players: Build out tele-surgical planning platforms for Mountain West critical access hospitals, the most underserved geography for specialized trauma sales coverage. Arizona and Texas ASCs represent the most penetrable channel given Medicare reimbursement expansion and capital investment momentum. Partner with established distributors rather than replicating direct sales infrastructure.
For Investors and Strategic Acquirers: FDA draft guidance on additive-manufactured implants reshapes the acquisition landscape toward patient-matched fabrication capabilities. Long-term viability favors platforms with captive metal printing and orthopedic-specific quality systems over contract manufacturers lacking dedicated regulatory teams. Target acquisition archetype: mid-tier trauma specialists with titanium alloy expertise and 510(k) clearance track records. Watch FDA finalization of patient-matched guide requirements as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for Patient-Matched Implants | FDA 510(k) clearance for additive-manufactured plates creates competitive moat against catalog-based rivals. |
| Hospital System Partnership | Multi-year enterprise contracts with Texas and Florida IDNs lock out portfolio-limited competitors. |
| Backward Integration into Titanium Processing | In-house titanium sponge hedging insulates margins from Kazakh export restriction risk. |
| Software Companion Development | Surgical planning platforms paired with 3D-printed guides virtualize academic-center capability for community surgeons. |
| Reimbursement Strategy | CMS outpatient procedure code expansion in Arizona and Texas accelerates ASC channel capture. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across the trauma fixation value chain. Primary interviews captured perspectives from orthopedic trauma surgeons, hospital purchasing committee chairs, GPO contracts managers, biomedical engineers, and specialized trauma sales directors. Secondary validation drew from FDA 510(k) clearance databases, CMS Medicare reimbursement schedules, hospital procurement contract registries, and ASTM material standards documentation. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue analysis.
Calibration against historical implant adoption curves anchored projection models across the analysis window. Segmentation dimensions spanned product type, end-user setting, application complexity, and material technology tier. CAGRs derived from logistic diffusion curves fitted to titanium alloy migration patterns and ASC penetration trajectories. Forecast inputs incorporated orthopedic trauma fellowship pipeline constraints and Sun Belt demographic trajectories.
Stress conditions across titanium sponge supply disruption, FDA guidance timeline acceleration, and Medicare reimbursement tier adjustments were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding IDN consolidation velocity and additive manufacturing regulatory clarity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Middle East and Africa Vagus Nerve Stimulation Market
Medical Devices
Global Defibrillators Market
Medical Devices
UAE Respiratory Devices Market
Medical Devices
Global Endovascular Aneurysm Repair Devices Market
Medical Devices
Global Digital Dose Inhaler Market
Medical Devices
Breast Biopsy Localization Wire Market
Medical Devices
Microcirculation Microscope Market
Medical Devices
Veterinary Glucometers Market
Medical Devices
Disposable EEG Electrode Market
Medical Devices
Global Semiconductor in Healthcare Market
Medical Devices
Global Joint Replacement Device Market
Medical Devices
Infertility Devices Market
Medical Devices
Brazil Drug Delivery Devices Market
Medical Devices
Capsule Endoscope Systems Market
Medical Devices
Patient Warming Devices Market
Medical Devices
Indian Laparoscopy Devices Market