
 Italy Minimally Invasive Surgery Devices Market | 2026-2036
Italy Minimally Invasive Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Minimally Invasive Surgery Devices Market Foresight
Modular platform configurations—where visualization systems, energy devices, and robotic arms bundle into interoperable suites—is realigning hospital procurement strategies across Italy. Karl Storz GmbH leverages its endoscope manufacturing depth to anchor premium laparoscopic segments. Johnson & Johnson Services, Inc. competes through broad instrument portfolios that span open and minimally invasive workflows. Medtronic Plc differentiates via surgical robotics integration with its existing energy and stapling platforms.
Italy Minimally Invasive Surgery Devices comprise precision-engineered instruments, endoscopes, robotic platforms, and imaging systems designed for procedures through small incisions, typically requiring trocar diameters between five and twelve millimeters and high-definition or three-dimensional visualization for operative accuracy. Laparoscopic instruments and endoscopic devices constitute the mature volume base, while surgical robotics captures the fastest expansion trajectory as Italian hospitals seek to offset specialist shortages through automated precision. Advanced energy devices within the technology dimension command disproportionate margin pools due to disposable blade and generator attachment economics.
Italy's Ministry of Health reimbursement classifications and CE marking requirements under the EU Medical Device Regulation shape product registration timelines and pricing negotiations for manufacturers seeking national formulary inclusion. The Italian Medicines Agency (AIFA) coordinates with regional health authorities to evaluate cost-effectiveness of robotic-assisted procedures, creating uneven adoption across Italy's decentralized healthcare system. Stakeholders must monitor how Lombardy and Veneto regional tenders consolidate purchasing power while tracking AIFA's evolving digital surgery reimbursement framework.
Market Dynamics
Modular surgical platform architectures are compressing procurement cycles across Italian hospital networks as administrators demand interoperable visualization, energy, and robotic systems from single-vendor relationships. This integration imperative favors manufacturers with full-stack capabilities while marginalizing point-solution specialists in regional tender processes.
Growth Catalysts
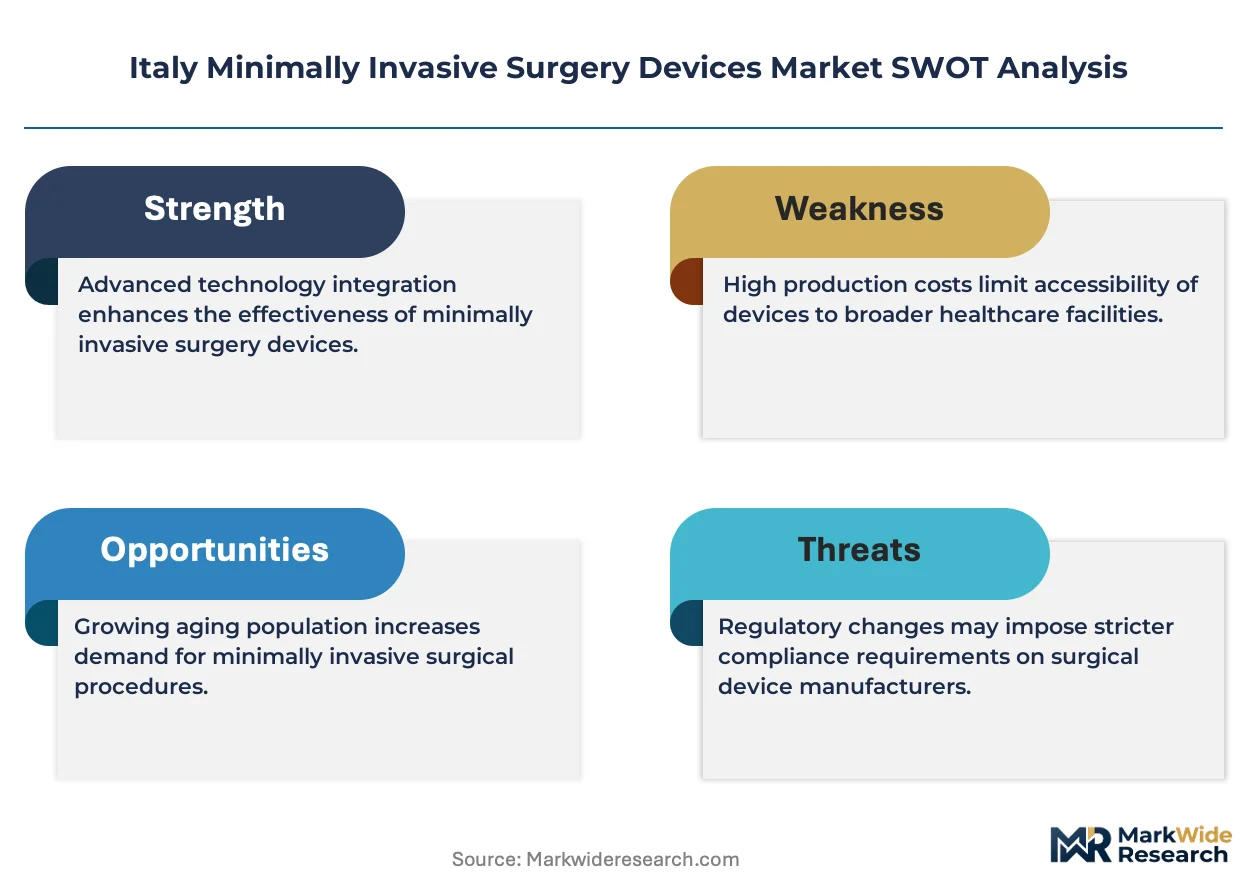
- EU MDR harmonization:Streamlined CE marking pathways under the Medical Device Regulation are accelerating product registrations for advanced laparoscopic instruments, reducing time-to-market for manufacturers targeting Italian formulary inclusion.
- Robotic-assisted reimbursement:Italy's Ministry of Health DRG tariff adjustments for da Vinci and comparable systems are incentivizing public hospitals in Lombardy and Emilia-Romagna to expand specialist training programs.
- Tertiary center concentration:Milan's Policlinico and Humanitas networks generate procedure volumes that justify capital-intensive robotic suite investments, creating reference-site effects for regional adoption.
Market Restraints
- Disposable instrument economics:Per-procedure costs for robotic stapler cartridges and energy device tips strain operating budgets at medium-sized provincial hospitals with limited case volumes.
- Specialist supply bottlenecks:Italy's medical residency training capacity for minimally invasive surgery trails installed robotic platform growth, creating utilization gaps in Calabria and Sicily.
- AIFA evaluation timelines:Cost-effectiveness assessments for novel surgical technologies extend 18-24 months, delaying regional reimbursement parity and freezing procurement decisions.
Strategic Opportunities
- Veneto and Tuscany regional tenders:Consolidated purchasing frameworks in these regions present entry points for second-tier manufacturers seeking to challenge incumbent platform vendors through leasing-based acquisition models.
- Day-surgery center expansion:Italy's 2023-2025 PNRR hospital infrastructure investments prioritize ambulatory surgical facilities requiring compact, multi-specialty laparoscopic towers.
- Fluorescence-guided surgery convergence:Integration of near-infrared imaging with standard laparoscopic stacks enables real-time perfusion assessment, commanding premium positioning in oncology resections.
Industry Challenges
- Biomedical engineering technician scarcity:Robotic platform maintenance requires specialized training that outpaces Italian technical institute output, extending equipment downtime at peripheral facilities.
- Legacy stack integration complexity:Hospitals with 2015-2018 vintage visualization systems face costly bridge hardware requirements to adopt next-generation 4K/3D camera heads without full suite replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Minimally Invasive Surgery Devices Market |
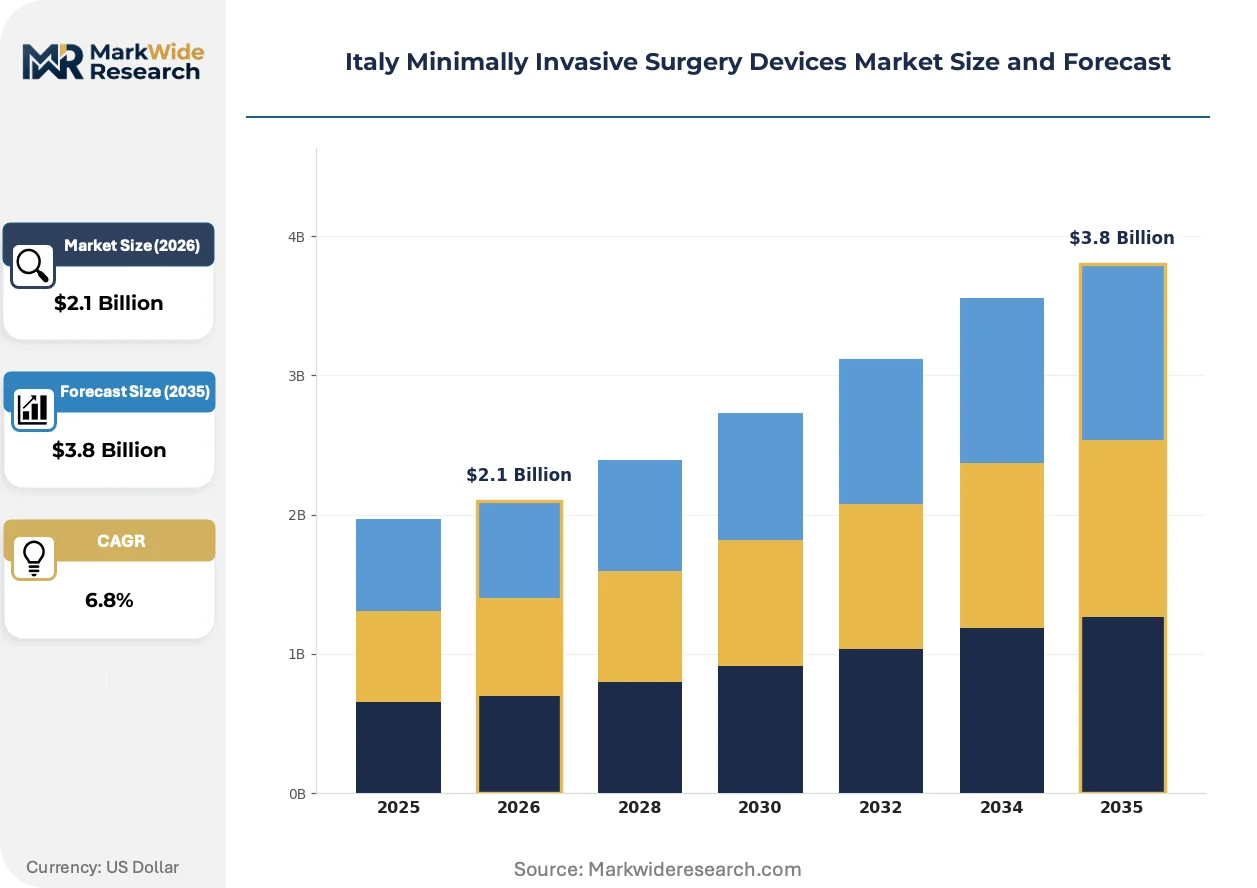
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Laparoscopic Instruments, Endoscopic Devices, Surgical Robotics, Visualization Systems Application: General Surgery, Gynecological Surgery, Urological Procedures, Cardiothoracic Surgery End User: Hospitals, Ambulatory Surgical Centers, Clinics, Specialty Surgical Centers Technology: Robotic-Assisted Surgery, Digital Imaging, Advanced Energy Devices, Single-Port Surgery |
| Companies Covered | Karl Storz GmbH, Johnson & Johnson Services, Inc., Medtronic Plc, Drägerwerk AG & Co KGaA, Siemens Healthineers AG, Olympus Corporation, Terumo Corporation, LED SpA, GE Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Minimally Invasive Surgery Devices Market Shifts & Advancements
Digital surgery ecosystems are redefining competitive advantage in Italy as hardware vendors bundle proprietary analytics platforms with instrument sales. This software-hardware coupling creates switching costs that protect installed bases while generating recurring revenue streams.
Single-port laparoscopic platforms are expanding into Italian gynecology and urology departments as manufacturers refine articulating instruments for constrained access procedures. Academic medical centers in Bologna and Padua are piloting these systems for complex hysterectomies and prostatectomies, compressing the learning curve that previously limited adoption to niche applications.
Italy's AIFA cost-effectiveness framework is tightening evidentiary requirements for robotic-assisted procedure reimbursement, forcing manufacturers to submit real-world outcome data from Italian cohorts rather than extrapolating from US or German studies. This regulatory localization extends registration timelines but creates competitive moats for vendors with established Italian clinical partnerships.
Regional health authority consolidation is concentrating purchasing power in Lombardy, Veneto, and Emilia-Romagna, displacing hospital-level procurement autonomy with centralized tender specifications that favor full-service platform contracts over best-of-breed instrument sourcing. Medium-sized device manufacturers are responding with specialized clinical application bundles targeting specific procedure types rather than competing for comprehensive system awards.
Italy Minimally Invasive Surgery Devices Market Segmentation
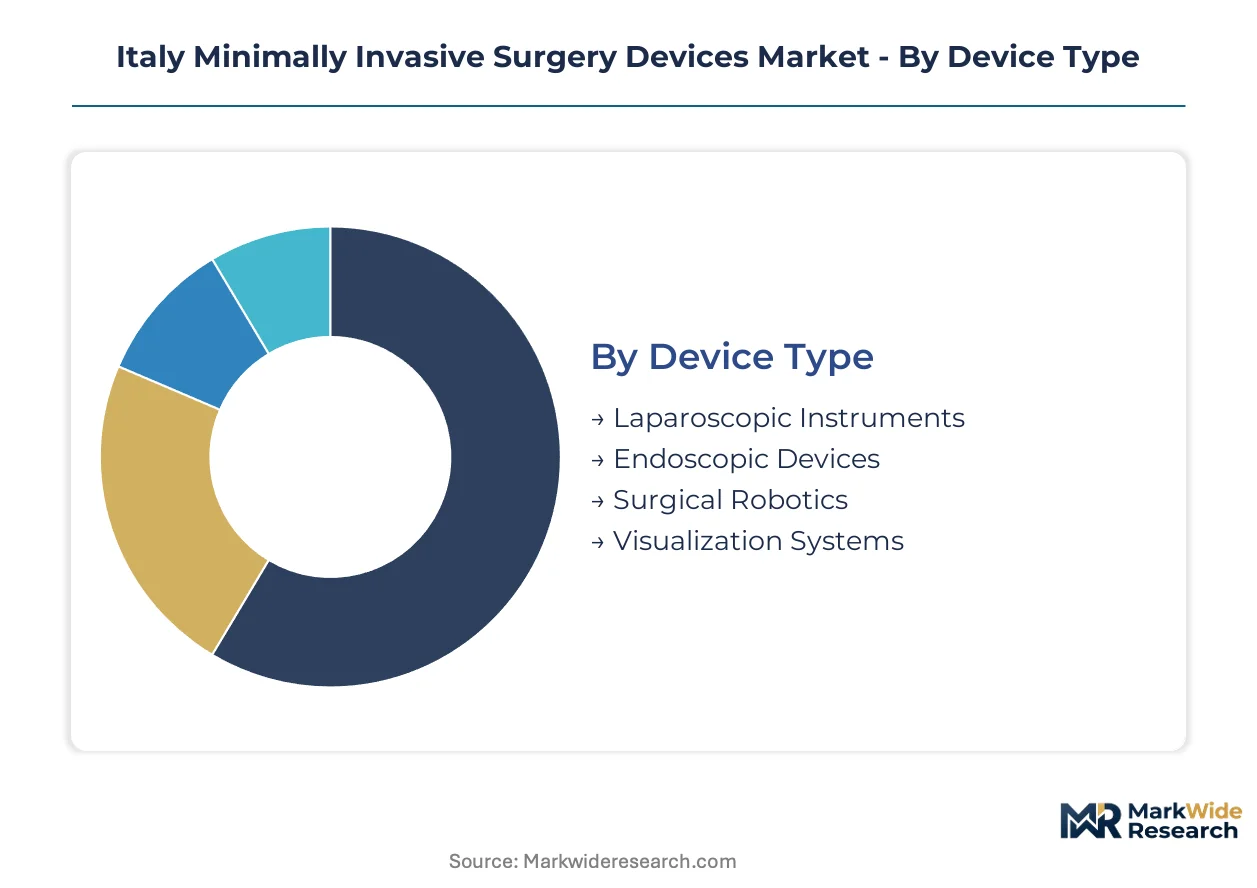
Device categorization in Italy's minimally invasive surgery market reveals stark divergence between mature laparoscopic volumes and capital-intensive robotic platforms. Procurement patterns vary dramatically across application settings, with tertiary centers driving premium technology uptake while provincial facilities prioritize cost-efficient instrument bundles.
Device Type:
Standalone laparoscopic instruments function independently in most Italian operating theaters, whereas surgical robotics demand full-stack integration with visualization and energy systems.
- Laparoscopic Instruments:Precision-engineered graspers, dissectors, and clip appliers manufactured from surgical-grade stainless steel with insulated shafts for electrosurgical compatibility. Demand concentrates at Policlinico di Milano and Humanitas Research Hospital, where high-volume general surgery departments prioritize instrument durability and standardization across procedure types.
- Surgical Robotics:Multi-arm platforms integrating 3D visualization, wristed instrumentation, and tremor filtration for enhanced operative precision. Lombardy's regional tender frameworks are accelerating placement in academic medical centers, though disposable instrument economics constrain adoption at medium-sized provincial hospitals.
- Endoscopic Devices:Flexible and rigid scopes with high-definition optics for diagnostic and interventional procedures across gastrointestinal and respiratory applications.
- Visualization Systems:4K and 3D camera heads, light sources, and monitor stacks enabling operative accuracy through enhanced depth perception and tissue differentiation.
Volume placements concentrate in Laparoscopic Instruments; the faster expansion belongs to Surgical Robotics.
Application:
Procedure complexity and reimbursement intensity determine technology selection across surgical disciplines, with high-acuity specialties commanding premium platform investments.
- General Surgery:Cholecystectomy, hernia repair, and colorectal resections constitute the procedural backbone for minimally invasive adoption in Italy. Veneto regional health authorities are consolidating procurement for laparoscopic towers to standardize equipment across provincial hospital networks.
- Urological Procedures:Robot-assisted prostatectomy and partial nephrectomy leverage wristed instrumentation for deep pelvic dissection. Milan's Istituto Nazionale dei Tumori anchors national training capacity, creating reference-site effects for robotic platform diffusion.
- Gynecological Surgery:Hysterectomy and myomectomy applications are gaining traction with single-port platform refinements reducing abdominal wall trauma.
- Cardiothoracic Surgery:Minimally invasive valve repair and lung resection procedures require specialized instrumentation and perfusion support systems.
General Surgery generates the highest absolute procedure counts; Urological Procedures command the steepest technology premium per case.
End User:
Capital availability and case volume thresholds create sharp segmentation between integrated hospital networks and standalone surgical facilities.
- Hospitals:Public and private acute-care institutions with 24-hour surgical services and intensive care backup. Lombardy and Emilia-Romagna regional tenders are consolidating purchasing power across hospital networks, displacing facility-level procurement autonomy.
- Ambulatory Surgical Centers:Day-surgery facilities prioritized under Italy's PNRR hospital infrastructure investments. Tuscany's regional health authority is piloting compact multi-specialty laparoscopic towers for these settings.
- Clinics:Smaller diagnostic and minor-procedure facilities with limited surgical capabilities.
- Specialty Surgical Centers:Focused facilities for ophthalmology, orthopedics, or cosmetic procedures requiring specialized minimally invasive equipment.
Hospitals retain dominant capital expenditure share; Ambulatory Surgical Centers are expanding most quickly under ambulatory-care policy directives.
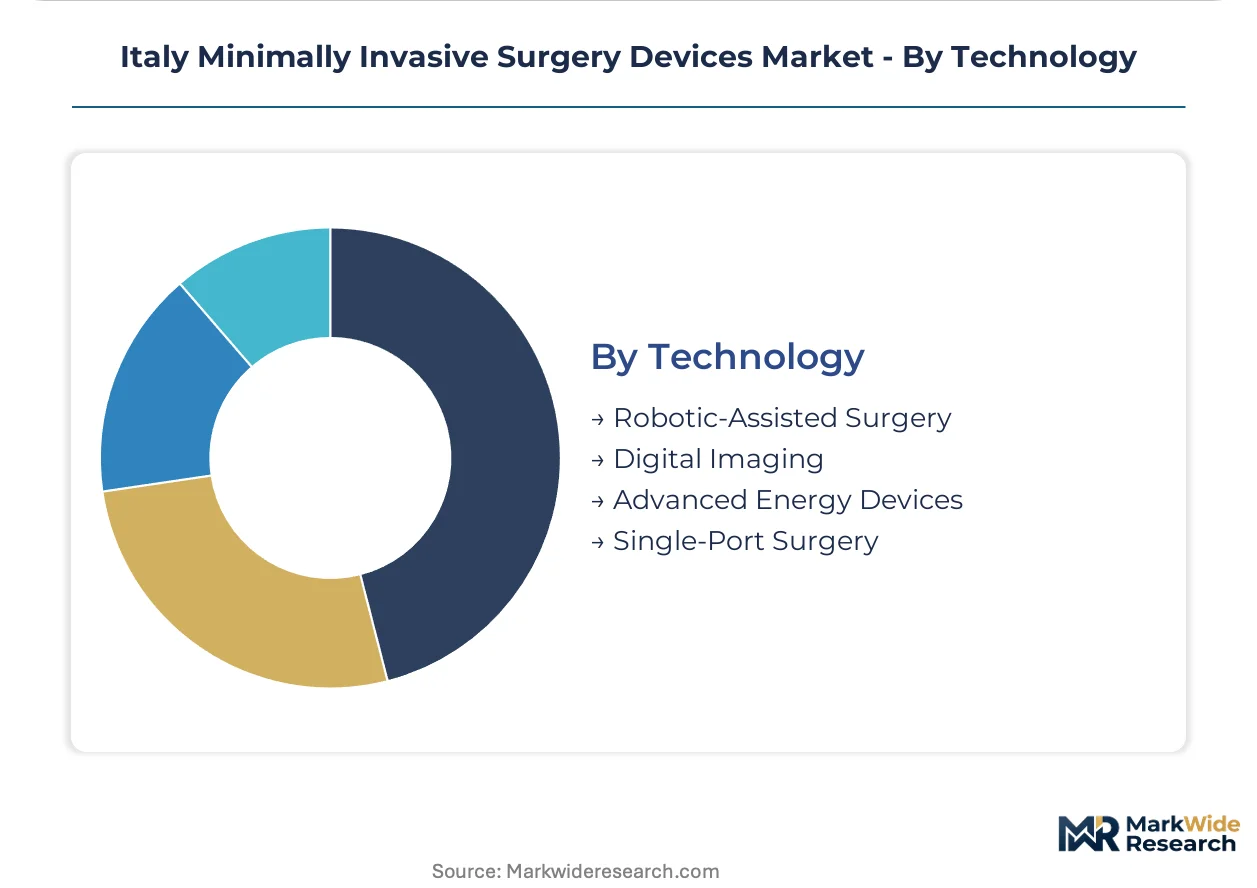
Technology:
Technology layering determines competitive differentiation, with digital and robotic capabilities commanding premium positioning over foundational energy and access platforms.
- Robotic-Assisted Surgery:Automated platforms with surgeon-controlled arms and haptic feedback systems. AIFA cost-effectiveness assessments are tightening evidentiary requirements, forcing manufacturers to submit Italian real-world outcome data rather than extrapolating from foreign studies.
- Advanced Energy Devices:Ultrasonic and bipolar systems for vessel sealing and tissue dissection with minimal thermal spread. Disposable blade and generator attachment economics generate recurring revenue streams that protect installed bases.
- Digital Imaging:4K resolution, 3D depth perception, and fluorescence-guided near-infrared capabilities for real-time perfusion assessment.
- Single-Port Surgery:Constrained-access platforms with articulating instruments reducing incision count for cosmetic and pain-recovery benefits.
Advanced Energy Devices anchor current margin pools; Digital Imaging capabilities are gaining share fastest through fluorescence-guided surgery convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's minimally invasive surgery device market consumes precision-engineered imports while domestic production concentrates in Lombardy's medical technology corridor. Regional health authorities drive procurement centralization that favors established platform vendors.
Lombardy
Milan's Policlinico and Humanitas networks generate the highest procedure volumes nationally, justifying capital-intensive robotic suite investments. The region's health authority (ATS) coordinates centralized tenders that bundle visualization, energy, and robotic systems into single-vendor contracts. Bergamo and Brescia hospital clusters are expanding laparoscopic training capacity to offset specialist shortages.
Veneto
Padua's academic medical center pilots single-port platforms for complex gynecological procedures, creating reference-site effects for regional adoption. The regional health authority (ULSS) is consolidating procurement for multi-specialty laparoscopic towers across provincial hospital networks. Verona and Vicenza surgical centers are prioritizing compact equipment configurations for day-surgery expansion under PNRR infrastructure investments.
Emilia-Romagna
Bologna's Istituto Ortopedico Rizzoli and university hospital anchor orthopedic and general surgery robotics programs. The regional health authority (AUSL) is standardizing energy device specifications across public hospital networks to reduce per-procedure costs. Modena and Parma facilities are expanding ambulatory surgical capacity with interoperable instrument platforms.
Piedmont
Turin's Molinette Hospital and university medical center drive demand for advanced imaging integration in oncologic resections. The regional health authority (ASL) evaluates cost-effectiveness of fluorescence-guided surgery technologies for colorectal applications. Novara and Alessandria hospitals face procurement constraints from limited case volumes relative to robotic platform economics.
Tuscany
Florence's Careggi University Hospital anchors central Italian training capacity for minimally invasive cardiothoracic procedures. The regional health authority (Azienda USL Toscana) pilots compact laparoscopic towers for day-surgery center expansion. Pisa and Siena facilities are consolidating instrument standardization to streamline maintenance and technician training requirements.
Italy Minimally Invasive Surgery Devices Market Competitive Landscape
The competitive structure tilts toward integrated platform vendors with full-stack visualization, energy, and robotic capabilities. Regional tender consolidation across Lombardy and Veneto favors manufacturers offering interoperable suite configurations over point-solution specialists. Three archetypes dominate: German precision endoscope manufacturers, diversified US conglomerates with broad surgical portfolios, and specialized robotics integrators. M&A activity targets digital surgery analytics capabilities, while strategic partnerships lock in exclusive supply relationships with major hospital networks.
Among Germany-based manufacturers, Karl Storz GmbH exemplifies the precision endoscope archetype with manufacturing depth anchoring premium laparoscopic segments. Johnson & Johnson Services, Inc. and Medtronic Plc represent diversified US conglomerates competing through instrument portfolio breadth and robotics-energy platform integration respectively. These three occupy positions that align with regional tender specifications favoring comprehensive system contracts over specialized component sourcing.
| Leading Market Players |
|---|
| Karl Storz GmbH |
| Johnson & Johnson Services, Inc. |
| Medtronic Plc |
| Drägerwerk AG & Co KGaA |
| Siemens Healthineers AG |
| Olympus Corporation |
| Terumo Corporation |
| LED SpA |
| GE Healthcare |
| Others |
Supply & Pricing Matrix
CE-MDR certification tiering bifurcates Italy's minimally invasive surgery device market into premium validated platforms and economy instrument bundles, with this divergence manifesting in both hospital procurement budgets and manufacturer distribution footprints. Lombardy's consolidated regional tenders favor full-suite vendors with Class III device registrations, while provincial facilities in Calabria and Sicily source unbundled laparoscopic instruments through fragmented distributor networks.
Pricing Analysis
Margin tightening in robotic-assisted platforms reflects AIFA's extended cost-effectiveness evaluation timelines and disposable cartridge economics that strain medium-hospital operating budgets. Three-tier pricing structure across premium, standard, and economy levels tracks CE-MDR certification grade and after-sales service bundling, with Lombardy academic centers least price-sensitive and Sicilian provincial hospitals most constrained. Cost-down pressure on laparoscopic instrument bundles accelerates because Veneto and Tuscany regional tenders consolidate purchasing power across multi-facility networks.
Supply Chain Analysis
Regional distribution centers in Milan and Bologna anchor hub-and-spoke patterns that feed Lombardy and Emilia-Romagna hospital networks with 48-hour instrument replenishment cycles. Manufacturing concentration rests on Germany for precision endoscopes, the United States for robotic platforms, and Switzerland for advanced energy generators. Supply chain risk centers on single-source vulnerability for 4K camera sensor modules sourced from South Korean fabs. Distribution runs through authorized dealer networks with exclusive territorial rights rather than direct manufacturer-to-hospital contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's minimally invasive surgery device sector sits in a platform-transition phase, with robotic-assisted systems displacing conventional laparoscopic stacks in high-volume tertiary centers while day-surgery facilities demand compact multi-specialty towers.
For Market Incumbents: Anchor platform loyalty through proprietary energy device attachment economics that lock hospitals into recurring cartridge purchases. Defend against second-tier manufacturers by securing exclusive supply relationships with Lombardy and Veneto regional health authorities through leasing-based acquisition models. Deepen backward integration into fluorescence-guided imaging modules to capture premium positioning in oncology resections. For New Entrants and Emerging Players: Enter via specialized clinical application bundles targeting single-port gynecology platforms rather than competing for comprehensive robotic system awards. Calabria and Sicily present the most penetrable geographies given specialist shortages and limited incumbent field service presence. A go-to-market angle through biomedical engineering technician training partnerships addresses maintenance capability gaps at peripheral facilities. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified US conglomerates seeking Italian clinical partnership networks for AIFA real-world outcome data generation. Long-term viability favors manufacturers with established CE-MDR technical documentation and Lombardy reference-site relationships over pure-technology plays. Watch for AIFA digital surgery reimbursement framework finalization as the inflection signal for robotic platform utilization rates.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR technical documentation accelerates Italian formulary inclusion for advanced laparoscopic instruments. |
| Hospital System Partnership | Exclusive supply contracts with Policlinico di Milano create reference-site effects for regional adoption. |
| Software Companion Development | Proprietary analytics platforms bundled with hardware generate recurring revenue and switching costs. |
| Reimbursement Strategy | AIFA cost-effectiveness submissions using Italian cohort data secure DRG tariff parity for robotic procedures. |
| Backward Integration | In-house production of 4K camera heads reduces bridge hardware requirements for legacy stack upgrades. |
Research Methodology
Document review covered EU MDR guidance documents, AIFA reimbursement circulars, and Lombardy regional tender specifications, complemented by interviews with hospital purchasing committee directors, biomedical engineering technicians, GPO contracts managers, and minimally invasive surgery specialists. Secondary validation drew from hospital procurement databases, CE marking registries, and PNRR infrastructure investment disclosures. Bottom-up procedure volume estimates triangulated against top-down device shipment data.
Cross-referencing historical installation trends with specialist panel input anchored the analytical framework across the analysis window. Segmentation dimensions modeled include device type, application specialty, end-user facility tier, and technology layer. CAGRs derived from logistic diffusion curves for robotic platform penetration and linear extrapolation for mature laparoscopic instrument replacement cycles. Forecast inputs incorporated AIFA evaluation timeline probabilities and regional health authority consolidation trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under AIFA reimbursement rejection scenarios or EU MDR notified body capacity constraints. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ultrasound Transducers Market
Medical Devices
Infusion Management Market
Medical Devices
Wireless Portable Medical Devices Market
Medical Devices
Breast Biopsy Marker Market
Medical Devices
Double-Lumen Biliary Catheters Market
Medical Devices
Europe Biopsy Devices Market
Medical Devices
Global Joint Pain Injections Market
Medical Devices
Transcatheter Aortic Valve Implantation (TAVI) Market
Medical Devices
Japan Contraceptive Devices Market
Medical Devices
Americas Wearable Medical Device Market
Medical Devices
Global Medical Implants Market
Medical Devices
Liver-On-Chip Market
Medical Devices
Veterinary Stereotactic Radiosurgery System Market
Medical Devices
Life Science and Chemical Instruments Market
Medical Devices
Myopia Management Lenses Market
Medical Devices
Global Electrophysiology Devices Market