
 Application Virtualization Market | 2026-2036
Application Virtualization Market Size, Share, and Industry Trends Forecast 2026-2036
Application Virtualization Market Intelligence
Subscription-based consumption and managed service financing is tilting competitive dynamics toward vendors with recurring revenue infrastructure. Microsoft Corporation leverages its Azure-hosted desktop virtualization stack to anchor enterprise accounts. VMware, Inc. sustains technology leadership in server virtualization through deep hypervisor integration. Citrix Systems, Inc. specializes in remote access protocols that dominate healthcare and government deployments.
Application virtualization decouples software execution from local hardware by streaming or hosting application logic on centralized servers, using container-based isolation or hypervisor-mediated sessions to deliver pixel streams or API calls to endpoint devices. Its primary commercial purpose is to reduce client-side maintenance, enforce uniform security policies, and extend legacy software lifecycles across heterogeneous devices. Cloud deployment is capturing the fastest expansion as enterprises abandon capital-intensive on-premises data centers. Containerization is emerging as the margin-rich segment because it enables microservices density and DevOps velocity that monolithic virtualization cannot match. Desktop virtualization retains the largest installed base but faces substitution pressure from browser-based alternatives.
FDA 21 CFR Part 11 and HIPAA shape healthcare adoption by mandating audit trails and access controls that application virtualization platforms must embed. The EPA and NIST frameworks influence federal procurement specifications, filtering vendor eligibility for government contracts. Stakeholders must monitor how zero-trust architecture mandates from CISA reshape authentication requirements across remote access modes.
Market Dynamics
Containerization standards from the Cloud Native Computing Foundation are compressing deployment cycles and forcing vendors to rebuild isolation architectures around Kubernetes-native orchestration rather than legacy hypervisor mediation.
Growth Catalysts
- Federal cloud-first mandates:United States government procurement rules now prioritize cloud-hosted application delivery, accelerating refresh cycles across hospital systems and insurance providers.
- HIPAA audit trail requirements:Healthcare enterprises must embed access controls and session logging that application virtualization platforms natively provide.
- Microservices density:Container-based isolation enables DevOps velocity that monolithic virtualization cannot match, pulling enterprise workloads toward modernized stacks.
Market Restraints
- Hypervisor licensing costs:Per-socket pricing models from dominant server virtualization vendors inflate total cost of ownership for multi-tenant deployments.
- GPU allocation bottlenecks:Graphics-intensive workloads face technical limitations in session-based virtualization, constraining design and engineering use cases.
- FDA 21 CFR Part 11 validation timelines:Pharmaceutical manufacturers face extended compliance documentation requirements that delay production rollouts.
Strategic Opportunities
- Browser-based application streaming:WebAssembly and progressive web applications are converging with virtualization protocols to eliminate client-side agents entirely.
- Zero-trust architecture mandates:CISA directives across federal agencies create procurement tailwinds for vendors embedding continuous authentication into remote access layers.
- India's digital health mission:National telemedicine infrastructure investments open deployment opportunities for centralized application hosting in distributed clinical networks.
Industry Challenges
- Kubernetes certification scarcity:Container orchestration expertise gaps constrain enterprise migration timelines and inflate implementation partner costs.
- Legacy client-server integration:Mainframe-dependent financial services workflows require complex middleware bridges that fragment user experience consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Application Virtualization Market |
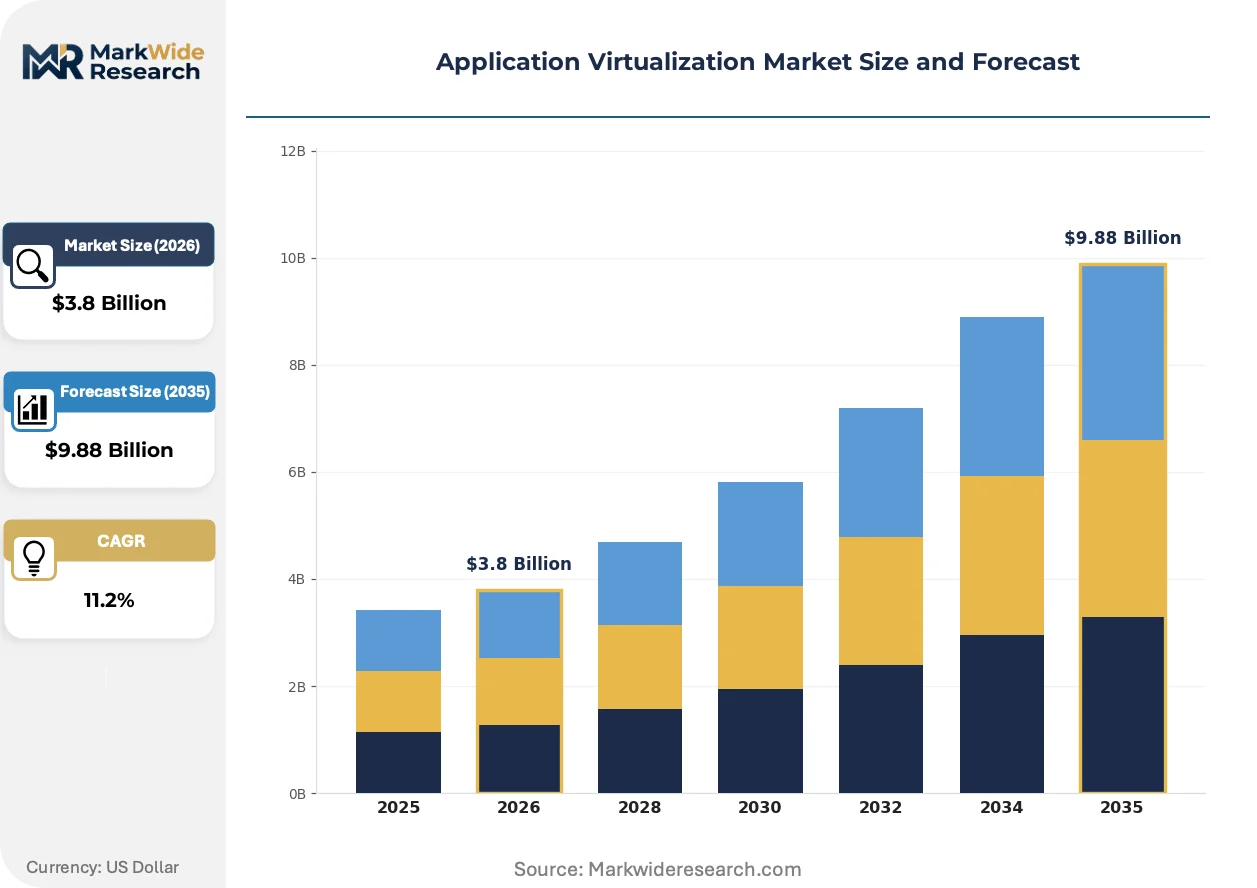
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud, Hybrid, Hosted, Edge Solution Type: Desktop Virtualization, Server Virtualization, Streaming, Application Isolation, Containerization End User Industry: Banking, Telecommunications, Manufacturing, Education, Government Access Mode: Remote Access, Local Access, Mobile Access, Web Access, Virtual Desktop Infrastructure |
| Companies Covered | Oracle Corporation, Amazon.com, Inc., VMware, Inc., Docker, Inc., Nutanix, Inc., Citrix Systems, Inc., Broadcom Inc., Red Hat, Microsoft Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Application Virtualization Market Strategic Shifts & Innovations
Remote application delivery is fragmenting into specialized execution models as browser-based streaming, container-native isolation, and GPU-accelerated virtualization each capture distinct workload categories.
WebAssembly runtime environments are digitizing how compute-intensive applications reach endpoint devices without local installation. Engineering software vendors now compile CAD and simulation tools to WASM modules that execute in sandboxed browser contexts. This architecture is digitizing the traditional desktop virtualization value proposition by eliminating agent management overhead while preserving graphics performance through GPU compute shaders.
EU AI Act risk classification frameworks are reshaping procurement specifications for virtualization platforms hosting machine learning inference workloads. High-risk AI system deployments must demonstrate auditability and human oversight mechanisms that session recording and access logging satisfy. Medical device manufacturers in Germany and France are prioritizing vendors with pre-validated compliance documentation to accelerate CE marking timelines.
Consumption-based licensing is compressing enterprise commitment cycles as finance teams demand usage-aligned spending rather than perpetual seat purchases. Healthcare systems in the United States are unbundling managed service contracts to separate infrastructure costs from application delivery fees. This pattern is most visible among mid-market hospital networks negotiating three-year agreements with annual true-up provisions tied to clinician headcount fluctuations.
Application Virtualization Market Segmentation
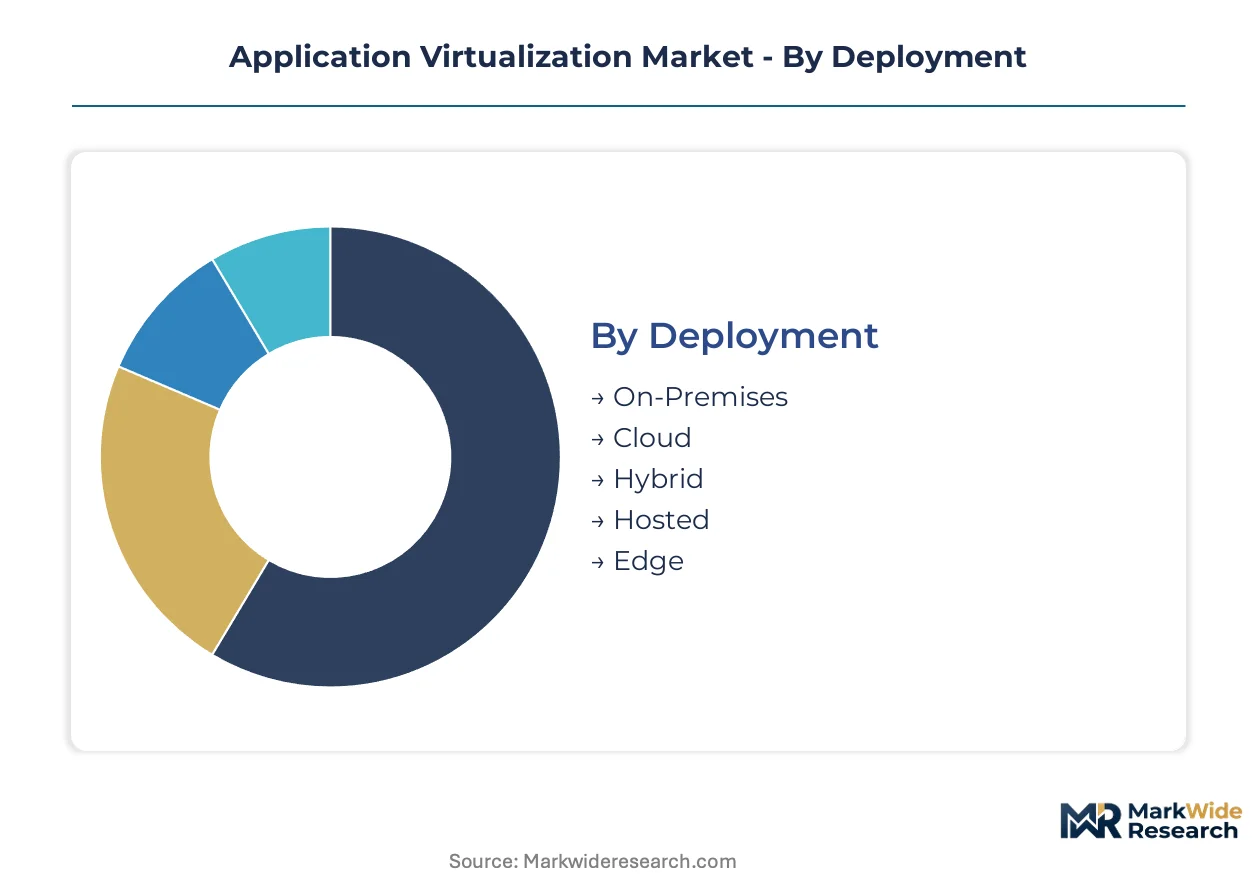
Application virtualization vendors engineer distinct pricing and support architectures around deployment topology, solution complexity, and access modality. Segmentation clarity enables procurement teams to align subscription tiers with actual consumption patterns rather than over-provisioning capacity.
Deployment:
Post-deployment service intensity varies dramatically by infrastructure location, with cloud-hosted instances demanding continuous optimization support while on-premises installations require periodic hardware refresh orchestration.
- On-Premises:Organizations retain full stack control within owned data centers. Financial services firms in Frankfurt and Singapore maintain these configurations to satisfy data sovereignty requirements imposed by national banking regulators.
- Cloud:Third-party infrastructure eliminates capital expenditure and shifts operational burden to vendors. Healthcare systems across the United States are migrating clinical applications here to satisfy HIPAA audit trail mandates without building internal security operations centers.
- Hybrid:Workloads split between owned facilities and public cloud based on sensitivity classification. Manufacturing enterprises use this architecture to keep intellectual property on-site while bursting engineering simulations to scalable cloud compute.
- Hosted:Managed service providers operate dedicated single-tenant environments. Mid-market insurance carriers prefer this model to access enterprise-grade infrastructure without internal platform expertise.
- Edge:Containerized application nodes deploy at network periphery to minimize latency. Telecommunications providers install these at cellular base stations to support low-latency industrial IoT control systems.
By volume, Cloud leads. By growth pace, Edge is ahead.
Solution Type:
Margin profiles diverge sharply across solution architectures, with containerization commanding premium pricing due to scarce Kubernetes expertise while desktop virtualization competes on seat-based economies of scale.
- Desktop Virtualization:Centralized Windows or Linux desktop sessions stream to thin clients or BYOD endpoints. Hospital systems in the United States deploy this to standardize clinical workstation configurations across thousands of distributed care sites.
- Server Virtualization:Hypervisor-mediated workload isolation maximizes hardware utilization in data centers. This segment retains the largest installed base but faces margin compression from container-native alternatives.
- Streaming:Application logic executes remotely while only display pixels transmit to endpoints. Design firms in Japan leverage this to deliver graphics-intensive CAD tools to remote contractors without local GPU investment.
- Application Isolation:Sandbox environments separate untrusted code from host operating systems. Government agencies specify this for contractor access to sensitive networks under zero-trust architecture mandates.
- Containerization:OS-level virtualization enables microservices density and DevOps velocity that monolithic architectures cannot match. This segment claims the steepest expansion trajectory as enterprises modernize legacy application portfolios.
By revenue concentration, Server Virtualization dominates. By margin expansion, Containerization is pulling ahead.
End User Industry:
Procurement sophistication varies by vertical, with banking and government demanding extensive compliance documentation while education prioritizes cost minimization over feature depth.
- Banking:Trading floors and retail branches require sub-millisecond application response with comprehensive session recording. Institutions in Switzerland and Singapore lead adoption of GPU-accelerated virtualization for quantitative analytics.
- Telecommunications:Network operations centers and customer service hubs need elastic capacity to handle demand spikes. Carriers in India deploy centralized application hosting to support national digital inclusion initiatives.
- Manufacturing:Shop floor systems and engineering workstations demand reliable access to legacy ERP modules. German automotive suppliers use application streaming to extend obsolete client-server software lifecycles.
- Education:Computer labs and remote learning platforms prioritize low per-seat cost over advanced features. K-12 districts in Texas and California negotiate volume agreements based on semester-by-semester enrollment fluctuations.
- Government:Classified and unclassified networks require distinct isolation architectures. Federal agencies in the United States specify FedRAMP-authorized platforms under cloud-first procurement directives.
By contract value, Banking leads. By deployment velocity, Telecommunications is expanding most quickly.
Access Mode:
Authentication complexity scales with access modality, with mobile and web channels demanding continuous identity verification while traditional VDI maintains session-based trust models.
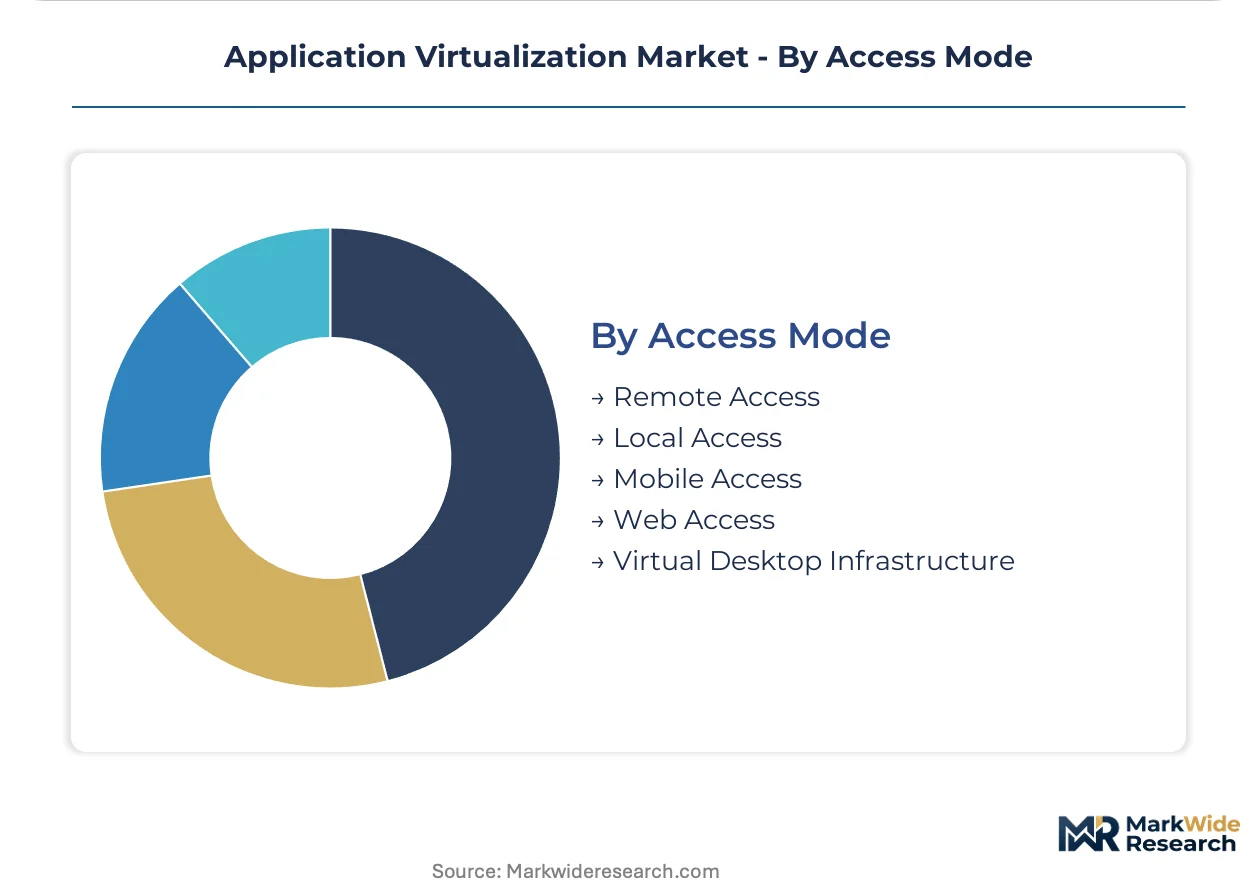
- Remote Access:VPN-independent application delivery to off-network endpoints. Pharmaceutical sales forces use this to access CRM systems from physician office waiting rooms without corporate device management.
- Local Access:Virtualized applications execute on cached local resources with periodic synchronization. This mode persists in bandwidth-constrained environments like offshore oil platforms.
- Mobile Access:Touch-optimized interfaces adapt full desktop applications to smartphone and tablet form factors. Field service technicians in Australia rely on this for real-time inventory lookup during customer visits.
- Web Access:Browser-native execution eliminates client installation entirely. WebAssembly runtimes now enable compute-intensive engineering tools to run in sandboxed browser contexts without local agents.
- Virtual Desktop Infrastructure:Complete desktop environments hosted centrally and delivered as a service. This architecture dominates healthcare deployments where clinicians roam between workstations and require persistent personalized configurations.
By installed base, Virtual Desktop Infrastructure leads. By feature innovation velocity, Web Access is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a substantial trade surplus in application virtualization services, exporting cloud-hosted platforms to European healthcare systems while importing specialized container orchestration tools from Germany and container-native security modules from Israel.
United States
Federal cloud-first procurement mandates and HIPAA compliance requirements drive hospital system refresh cycles. CISA zero-trust architecture directives reshape authentication specifications across remote access deployments. The Dallas-Fort Worth metroplex hosts concentrated managed service operations serving mid-market insurance carriers.
Germany
Automotive engineering workflows demand GPU-accelerated virtualization for CAD and simulation tools. The EU AI Act risk classification frameworks reshape procurement specifications for platforms hosting machine learning inference. Stuttgart and Munich anchor industrial software vendor clusters extending legacy ERP lifecycles through application streaming.
India
National telemedicine infrastructure investments under the digital health mission accelerate centralized application hosting adoption. TRAI connectivity regulations support distributed clinical network deployments. Bengaluru and Hyderabad concentrate DevOps talent pools enabling container-native migration programs for financial services firms.
United Kingdom
Financial services trading floors require sub-millisecond application response with comprehensive session recording. GDPR and FCA operational resilience mandates enforce audit trail capabilities. The City of London and Canary Wharf cluster quantitative analytics operations leveraging GPU-accelerated virtualization.
Japan
Manufacturing enterprises use application streaming to extend obsolete client-server software supporting shop floor systems. METI digital transformation incentives subsidize legacy modernization programs. The Nagoya industrial corridor concentrates automotive supplier networks deploying centralized application delivery to distributed engineering sites.
Application Virtualization Market Key Industry Players
On the supply side, the industry is consolidating around three strategic tiers: hyperscale cloud platforms, enterprise virtualization incumbents, and container-native specialists. Dominant archetypes include infrastructure-anchored ecosystems, protocol-specialized access vendors, and Kubernetes-native orchestration providers. Competitive dynamics center on strategic partnerships embedding virtualization layers into broader cloud contracts and portfolio diversification into adjacent security and identity services.
Within the hyperscale tier, Microsoft Corporation and Amazon.com, Inc. represent infrastructure-anchored ecosystem plays, leveraging cloud hosting dominance to bundle application delivery capabilities. VMware, Inc. and Citrix Systems, Inc. occupy positions as enterprise virtualization incumbents with deep protocol and hypervisor integration heritage. Docker, Inc. and Nutanix, Inc. exemplify the container-native specialist archetype, targeting DevOps velocity requirements that monolithic architectures cannot satisfy.
| Leading Market Players |
|---|
| Oracle Corporation |
| Amazon.com, Inc. |
| VMware, Inc. |
| Docker, Inc. |
| Nutanix, Inc. |
| Citrix Systems, Inc. |
| Broadcom Inc. |
| Red Hat |
| Microsoft Corporation |
| Others |
Cost & Logistics Intelligence
Overcapacity in cloud infrastructure regions is compressing vendor margins and forcing hyperscale providers to bundle application virtualization services at discounted rates within broader enterprise contracts. This utilization imbalance simultaneously pressures independent software vendors to absorb integration costs while creating procurement leverage for healthcare systems negotiating multi-year managed service agreements.
Pricing Analysis
Industrial OEM buyers anchor subscription-based pricing structures that stratify across consumption tiers tied to clinician headcount or compute volume. Price differentiation rests on FedRAMP authorization status and HIPAA audit trail depth, with certified platforms commanding premiums over uncertified alternatives. Cost compression in mid-market segments is intensifying because container-native specialists are undercutting legacy hypervisor vendors on per-seat economics. Hospital networks exhibit highest price sensitivity due to constrained capital budgets, while federal agencies accept premium pricing for pre-validated compliance documentation.
Supply Chain Analysis
Upstream feedstock for virtualization platforms draws from semiconductor fabrication concentrated in Taiwan, South Korea, and the United States, with GPU accelerators particularly tethered to NVIDIA supply allocations. Kubernetes distribution dependencies and hypervisor kernel modules constitute critical software inputs alongside bare-metal server hardware. Single-source vulnerability in GPU allocation constrains graphics-intensive workload delivery. Distribution runs through hyperscale cloud marketplaces, direct enterprise sales forces, and specialized healthcare IT channel partners serving hospital procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of certified Kubernetes engineers and validated container security architects is constraining enterprise migration timelines and inflating implementation partner rates. This capability gap creates asymmetric opportunities across vendor tiers.
For Market Incumbents: Entrench hypervisor integration advantages by deepening certification investments in FDA 21 CFR Part 11 validation documentation to accelerate pharmaceutical procurement cycles. Expand channel control through exclusive managed service partnerships with mid-market hospital networks facing internal platform expertise shortages. Counter container-native substitution threats by embedding zero-trust authentication layers that satisfy CISA federal mandates. For New Entrants and Emerging Players: Establish a beachhead in India's national telemedicine infrastructure deployments where centralized application hosting demand is outpacing domestic vendor capacity. Target German automotive engineering workflows requiring GPU-accelerated CAD virtualization as the most penetrable segment among industrial OEMs. Pursue a go-to-market angle bundling WebAssembly runtime environments with browser-native streaming to eliminate client-side agent management entirely. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across container-native orchestration segments as open-source tooling commoditizes core platform functions. Long-term viability favors vendors with recurring revenue infrastructure and compliance certification moats rather than pure technology plays. Acquisition targets should demonstrate pre-validated HIPAA or FedRAMP documentation and established clinician user bases. Watch hyperscaler bundling discounts as the inflection signal indicating independent pricing power erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Kubernetes-Native Platform Migration | Cloud Native Computing Foundation standards are compressing deployment cycles for healthcare DevOps teams. |
| FedRAMP Authorization Investment | Federal cloud-first mandates from CISA filter vendor eligibility for hospital system contracts. |
| Zero-Trust Architecture Integration | Continuous authentication layers satisfy procurement specifications across United States government agencies. |
| GPU-Accelerated Virtualization Partnership | German automotive suppliers leverage NVIDIA allocation for CAD simulation workload delivery. |
| WebAssembly Runtime Development | Browser-native execution eliminates agent management overhead for engineering software vendors. |
Research Approach
Cross-validation between primary interviews with healthcare CIOs, DevOps platform engineers, hospital procurement managers, and federal IT security officers anchors the qualitative findings. Secondary validation draws from SEC 10-K filings of hyperscale cloud providers, Cloud Native Computing Foundation technical specifications, HIPAA audit documentation databases, and federal procurement records. Bottom-up and top-down triangulation reconciles vendor-reported subscription metrics with enterprise IT spending surveys.
Calibration against historical adoption curves in comparable infrastructure software categories informs the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment topology, solution architecture complexity, end-user industry vertical, and regional regulatory cluster. CAGRs were derived through logistic diffusion curve fitting adjusted for compliance mandate acceleration. Kubernetes certification penetration rates and federal cloud migration timelines constitute industry-specific forecast inputs.
Stress conditions across GPU supply allocation volatility, container orchestration talent scarcity, and zero-trust mandate implementation pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about HIPAA audit trail enforcement continuity and hyperscaler pricing discipline. Cross-checking against external benchmarks from healthcare IT spending consortiums is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Gamification Software Market
Software & Services
Global Food Traceability Software Market
Software & Services
Banking Team Collaboration Software Market
Software & Services
Instant Messaging Software Market
Software & Services
Global Managed File Transfer Software Market
Software & Services
3D Animation Software Market
Software & Services
Global Budgeting Software Market
Software & Services
Global ITSM Software Market
Software & Services
Global Automotive Software Market
Software & Services
Staffing Agency Software Market
Software & Services
Telecom IT Services Market
Software & Services
Global Data Mining Software Market
Software & Services
Sales Intelligence Software Market
Software & Services
Driver Updater Software Market
Software & Services
Medical E-Commerce Software Market
Software & Services
Global Call Center Software Market