
 Global Budgeting Software Market | 2026-2036
Global Budgeting Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Budgeting Software Market Foresight
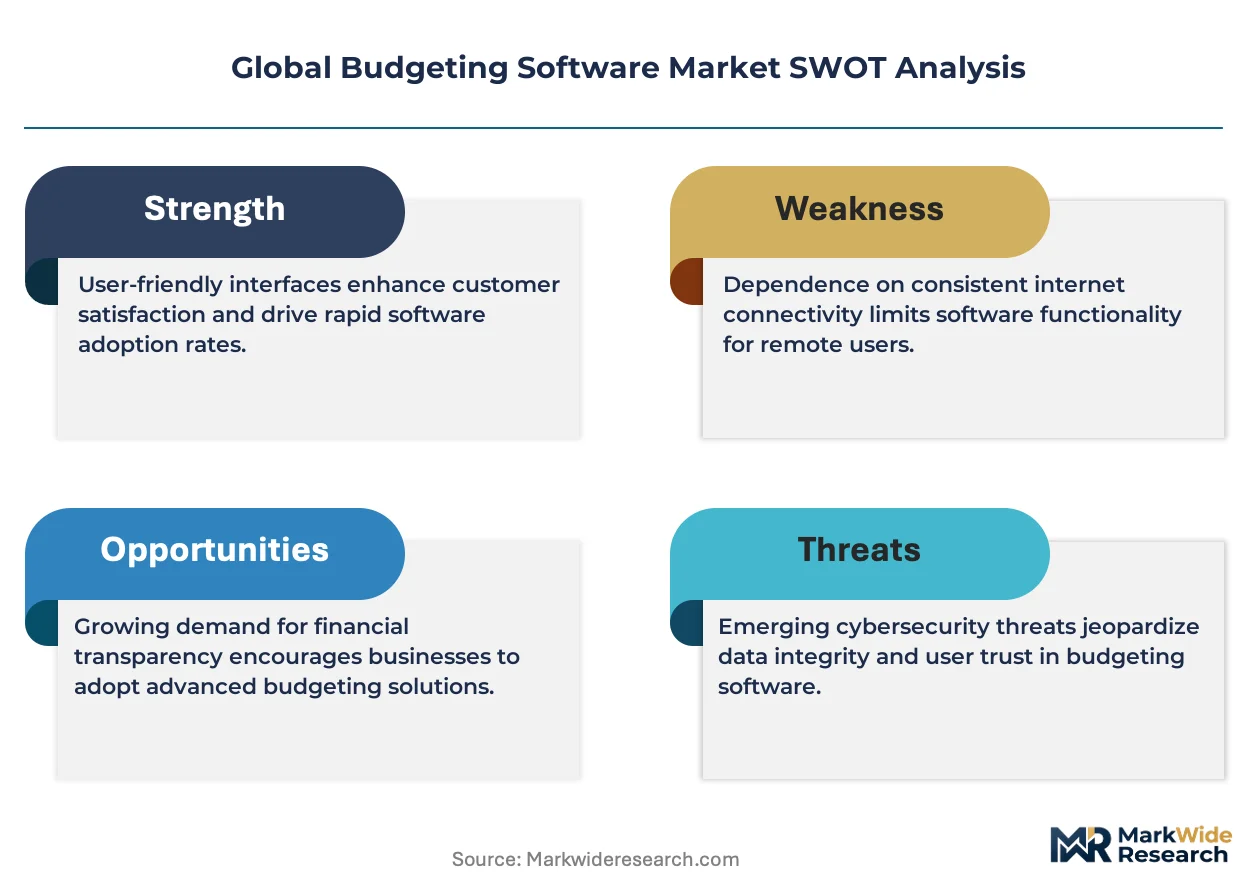
The capital-intensity divergence between legacy ERP incumbents and cloud-native specialists is bifurcating competitive dynamics in budgeting software. Oracle leverages its database-to-application stack to sustain bundled pricing power across large enterprises. Anaplan specializes in connected planning architectures that differentiate its offering for complex scenario modeling.
Budgeting software comprises applications that automate financial planning, forecasting, and resource allocation through algorithmic scenario engines, multi-dimensional data cubes, and real-time ERP integration protocols. Cloud-based deployment leads solution type adoption as finance teams prioritize remote accessibility and automatic version control over capital-intensive on-premises infrastructure. Expense management modules capture expanding margin pools as organizations seek granular spend visibility, while scenario analysis capabilities attract fastest-growing demand from risk-conscious treasury functions.
FCC guidelines on data locality, GDPR cross-border transfer rules, and ISO 27001 certification requirements collectively shape vendor qualification criteria and procurement timelines. India's RBI mandates on financial data localization and Germany's BSI IT-Grundschutz standards further constrain architecture choices for multinational deployments. Stakeholders must evaluate whether a vendor's compliance footprint matches their operational geography before committing to multi-year implementations.
Market Dynamics
The migration from on-premises ERP to cloud-native planning platforms is compressing vendor switching costs and redistributing bargaining power toward finance teams that demand granular API access and real-time scenario modeling.
Growth Catalysts
- GDPR cross-border transfer frameworks:European data-sovereignty mandates accelerate procurement of EU-hosted cloud instances, shortening sales cycles for compliant vendors.
- Mid-market finance automation:Companies with 500-5,000 employees replace spreadsheet-based planning with algorithmic forecasting engines to reduce quarterly close times.
- Real-time ERP integration protocols:Native connectors to SAP S/4HANA and Oracle Fusion eliminate manual data reconciliation, driving replacement demand among treasury functions.
Market Restraints
- Implementation cost concentration:Multi-year deployments require sustained professional services expenditure that mid-market buyers struggle to capitalize.
- Cloud infrastructure supplier concentration:Dependence on AWS, Azure, and GCP for hosting creates single-point-of-failure risk for vendor uptime commitments.
- Legacy data architecture drag:Decades of on-premises financial data stored in proprietary formats resist clean extraction and migration.
Strategic Opportunities
- India's RBI data localization mandates:Domestic hosting requirements create protected market space for vendors establishing Mumbai and Bangalore data centers.
- AI-augmented scenario modeling:Machine learning convergence with multi-dimensional data cubes enables probabilistic forecasting beyond deterministic spreadsheet logic.
- Embedded finance partnerships:Banking-as-a-Service distribution channels expose budgeting tools to SMBs through neobank interfaces.
Industry Challenges
- Actuarial-to-technical talent gap:Vendors struggle to hire professionals who bridge financial planning expertise with cloud architecture implementation.
- ISO 27001 certification timelines:Six-to-twelve month audit cycles delay market entry for new entrants targeting enterprise procurement panels.
- Legacy system integration complexity:Custom COBOL and mainframe connectors consume disproportionate engineering resources relative to cloud-native development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Budgeting Software Market |
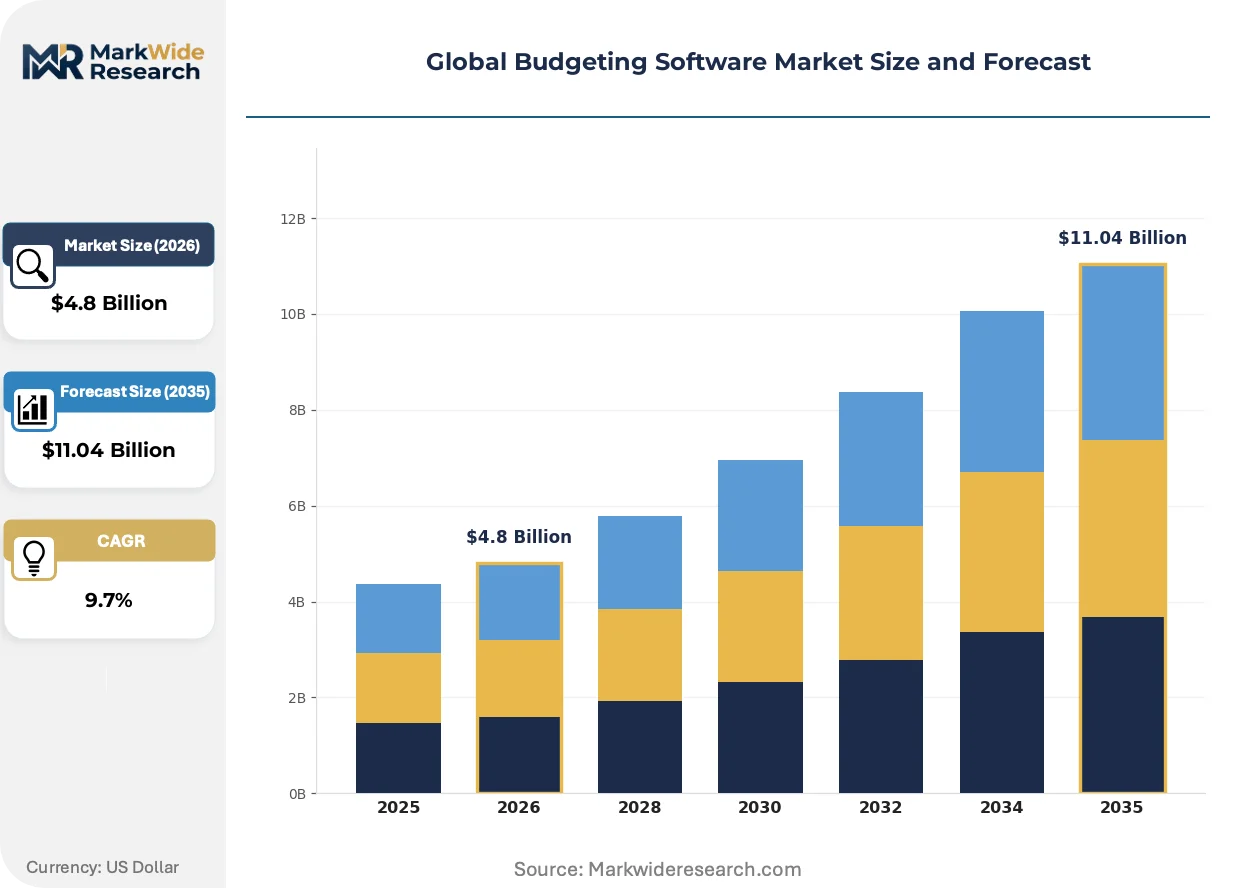
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
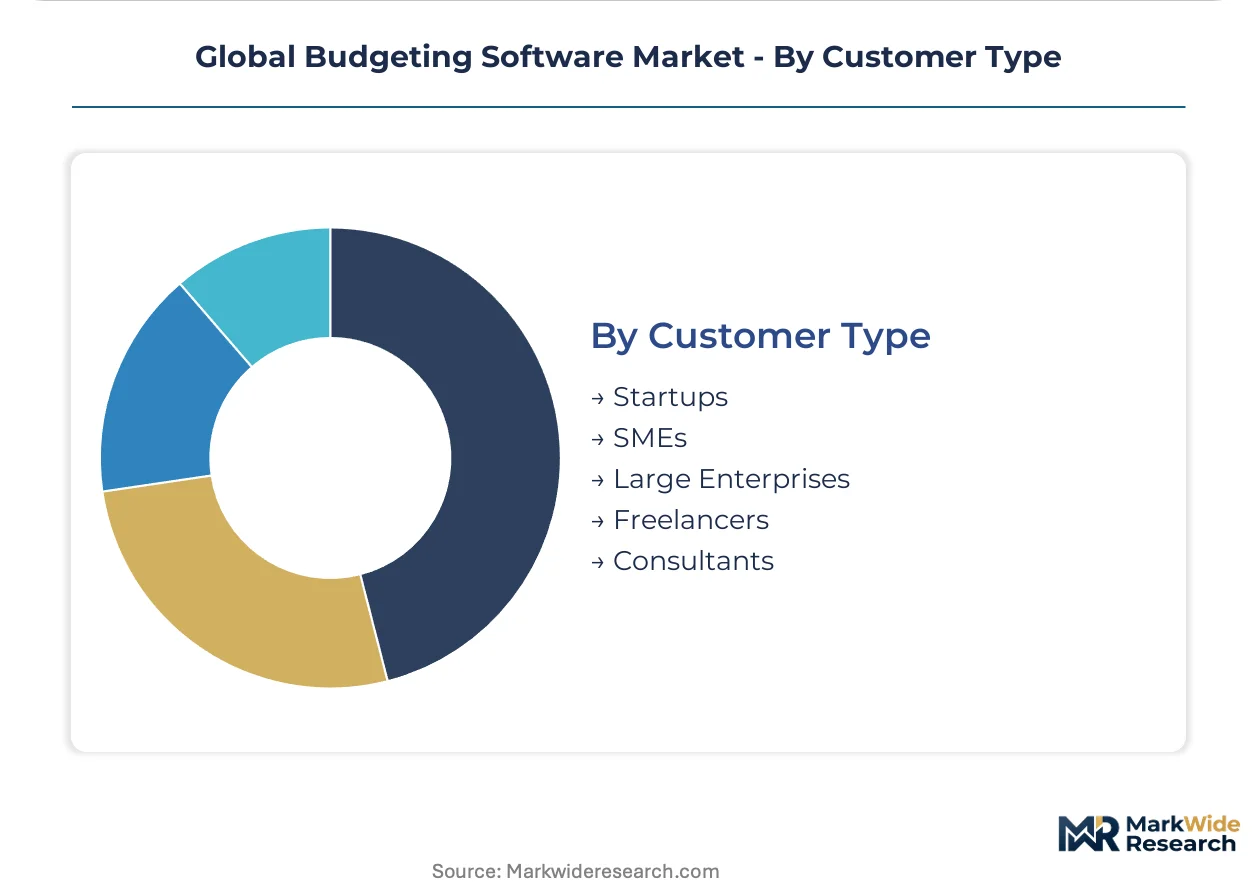
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Hosted Solution Type: Financial Planning, Expense Management, Cash Flow Forecasting, Scenario Analysis, Cost Allocation Application: Corporate Finance, Nonprofit Organizations, Educational Institutions, Government Agencies, Small Businesses Customer Type: Startups, SMEs, Large Enterprises, Freelancers, Consultants |
| Companies Covered | Oracle, SAP SE, Workday Inc., NetSuite Inc., Anaplan Inc., Deltek Inc., Planful Inc., Sage Intacct Inc., Prophix Software Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Budgeting Software Market Shifts & Advancements
Artificial intelligence is embedding predictive capabilities directly into financial planning workflows, compressing the gap between data ingestion and decision-ready insight while forcing incumbent vendors to rearchitect around API-first delivery models.
Multi-dimensional data cube technology is fragmenting the traditional monolithic ERP planning module into composable microservices. Finance teams at mid-market enterprises adopt these components to customize forecasting workflows without full platform replacement. The decomposition is fragmenting vendor lock-in and enabling best-of-breed procurement strategies that were previously uneconomical.
CSRD sustainability reporting mandates in the European Union require granular carbon and social metric tracking alongside financial forecasts. Corporate planning teams must reconfigure data models to capture non-financial KPIs with audit-grade traceability. German automotive and industrial conglomerates lead compliance investment, pressuring vendors to embed ESG data pipelines natively.
Subscription pricing for planning software is displacing perpetual license models across buyer segments. CFOs at SaaS and technology companies favor operational expenditure treatment for software costs, aligning vendor revenue recognition with customer cash flow preferences. This shift concentrates most visibly in the United States, where venture-backed growth companies prioritize balance sheet flexibility.
Global Budgeting Software Market Segmentation
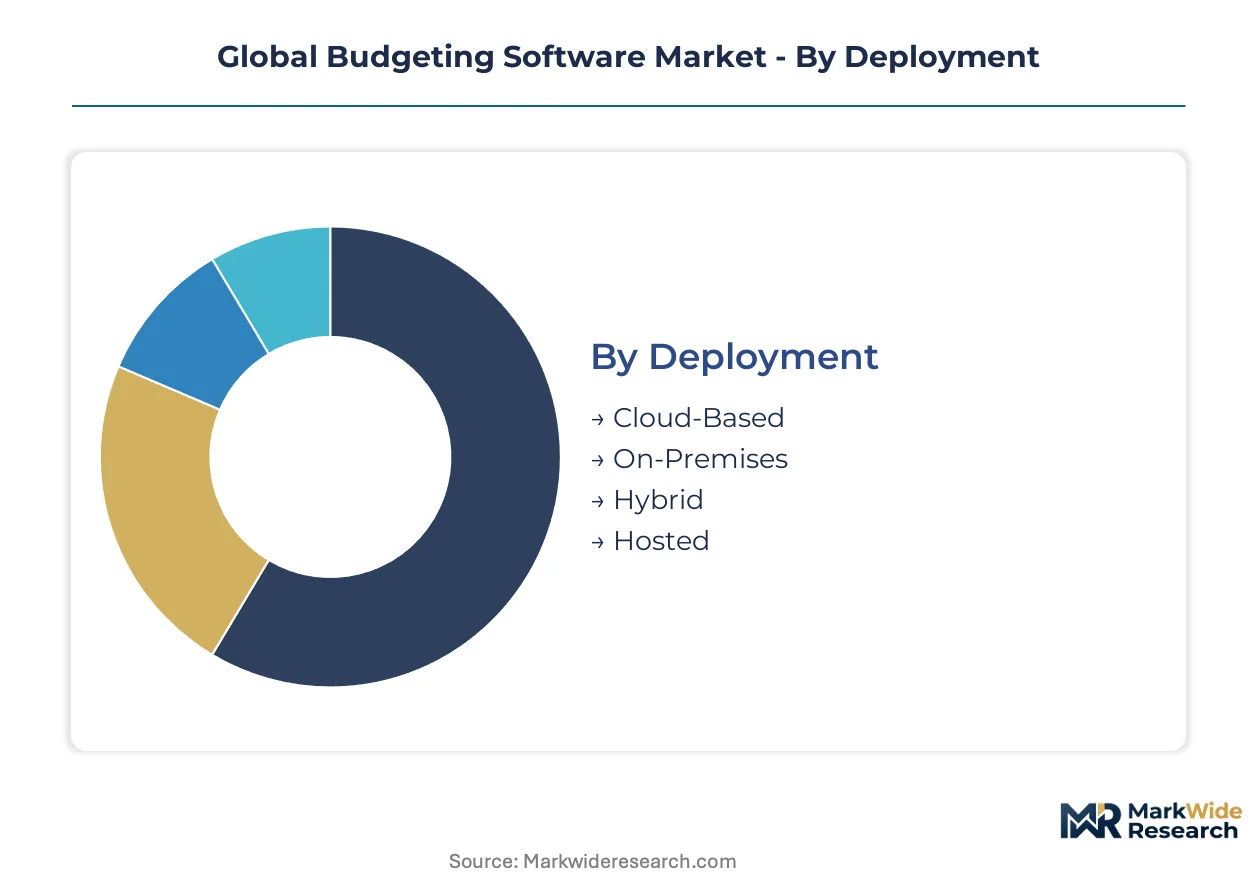
Budgeting software segmentation reveals how deployment architecture, solution specialization, and customer scale determine procurement channel preferences and vendor competitive positioning. Understanding these divides clarifies where cloud-native specialists capture share versus where legacy incumbents defend installed base.
Deployment:
Channel mix bifurcates sharply between self-service SaaS marketplaces and consultant-led enterprise implementations, with deployment mode dictating sales cycle length and professional services attachment rates.
- Cloud-Based:Browser-accessible multi-tenant architectures with automatic version updates and API-first integration protocols. Demand concentrates among mid-market finance teams in Germany replacing spreadsheet workflows under BSI IT-Grundschutz compliance pressure.
- On-Premises:Licensed software deployed within customer-controlled data centers requiring dedicated infrastructure teams. Large enterprises in India with RBI-mandated data localization requirements sustain this segment despite higher total cost of ownership.
- Hybrid:Split architectures keeping sensitive financial data on-premises while extending planning workflows to cloud analytics layers. Organizations with mixed compliance jurisdictions favor this approach.
- Hosted:Single-tenant cloud instances managed by vendors or third-party operators offering dedicated infrastructure without customer-side maintenance burden.
On-Premises dominates installed base. Cloud-Based is where expansion concentrates.
Solution Type:
Margin pools shift toward modules that compress decision latency, with scenario analysis commanding premium pricing against commoditized expense tracking.
- Financial Planning:Core budgeting engines automating variance analysis, rolling forecasts, and capital allocation workflows. Corporate finance departments in the United States drive replacement demand as they migrate from legacy ERP planning modules.
- Expense Management:Granular spend visibility tools capturing real-time transaction data through corporate card integrations and receipt capture. Treasury functions seeking procurement control sustain fastest adoption velocity.
- Cash Flow Forecasting:Liquidity prediction models integrating accounts payable, receivable, and external market indicators.
- Scenario Analysis:Multi-dimensional data cube architectures enabling probabilistic modeling of strategic alternatives under uncertainty.
- Cost Allocation:Activity-based costing engines distributing overhead to products, services, and business units with audit-grade traceability.
Financial Planning commands the largest revenue pool. Scenario Analysis is climbing the fastest.
Application:
Vertical specialization requirements fragment vendor addressable market, with compliance-heavy sectors demanding customized data models and audit trails.
- Corporate Finance:Public and private company FP&A teams managing investor reporting, board presentations, and SEC or equivalent regulatory filings. German automotive conglomerates lead investment under CSRD sustainability reporting mandates.
- Nonprofit Organizations:Fund accounting and grant compliance modules tracking restricted versus unrestricted net assets. Donor transparency requirements in the United States accelerate cloud migration.
- Educational Institutions:Multi-fund budgeting across tuition, research grants, and endowment distributions.
- Government Agencies:Appropriation-based planning with encumbrance accounting and public audit trail requirements.
- Small Businesses:Simplified cash-based forecasting without complex allocation or consolidation needs.
Corporate Finance generates the highest average contract value. Nonprofit Organizations represent the steepest expansion trajectory.
Customer Type:
Organizational maturity and capital access determine willingness to absorb implementation complexity versus preference for out-of-box functionality.
- Startups:Venture-backed companies prioritizing operational expenditure treatment and rapid deployment without IT infrastructure investment. SaaS companies in the United States favor subscription pricing for balance sheet flexibility.
- SMEs:Mid-market enterprises with 500-5,000 employees replacing spreadsheet-based planning with algorithmic forecasting to reduce quarterly close times. India hosts dense concentrations of this segment.
- Large Enterprises:Complex multi-entity organizations requiring consolidation across currencies, accounting standards, and regulatory jurisdictions.
- Freelancers:Individual practitioners needing basic income projection and tax estimation tools.
- Consultants:Advisory firms delivering planning services to clients requiring portable, client-segregated data environments.
Large Enterprises anchor vendor revenue. SMEs are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where SaaS buyers absorb premium subscription tiers, while procurement cycles in India compress vendor margins through aggressive localization mandates and domestic hosting requirements.
United States
Venture-backed technology companies and SaaS operators drive replacement demand as CFOs prioritize operational expenditure treatment for software costs. SEC disclosure requirements and SOX compliance frameworks elevate audit-grade traceability to a procurement prerequisite. San Francisco Bay Area and New York Metro clusters host the densest concentrations of buyers migrating from legacy ERP planning modules.
Germany
Automotive and industrial conglomerates under CSRD sustainability reporting mandates reconfigure data models to capture non-financial KPIs alongside financial forecasts. BSI IT-Grundschutz standards and GDPR cross-border transfer rules constrain architecture choices for multinational deployments. Bavaria's manufacturing corridor and Baden-Württemberg's automotive belt lead compliance investment in ESG-integrated planning platforms.
India
Mid-market enterprises with 500-5,000 employees represent the fastest-expanding buyer segment as they replace spreadsheet-based planning with algorithmic forecasting engines. RBI mandates on financial data localization create protected market space for vendors establishing Mumbai and Bangalore data centers. Karnataka's technology corridor and Maharashtra's financial services cluster sustain dense implementation partner networks.
United Kingdom
Corporate finance teams in London's financial district drive demand for real-time ERP integration protocols and multi-entity consolidation capabilities. FCA regulatory reporting requirements and post-Brexit data sovereignty considerations shape vendor qualification criteria. The Southeast England corridor concentrates procurement activity among asset management and insurance operators.
Japan
Large enterprises with complex multi-entity organizations require consolidation across currencies and accounting standards. METI digital transformation incentives accelerate cloud migration timelines for traditional manufacturing conglomerates. Tokyo-Osaka industrial corridor hosts the primary concentration of buyers evaluating hybrid deployment architectures.
Global Budgeting Software Market Competitive Landscape
Concentration sits with legacy ERP incumbents that leverage database-to-application stack integration to sustain bundled pricing power across large enterprises. Cloud-native specialists fragment the mid-market through API-first delivery models and composable microservices. Three archetypes dominate: full-stack platform vendors, connected planning specialists, and vertical-focused module providers. Competitive moves center on M&A to fill capability gaps and strategic partnerships with cloud infrastructure suppliers.
Within the full-stack platform tier, Oracle and SAP SE exemplify incumbents defending installed base through deep ERP integration, while Anaplan Inc. occupies a specialist position in connected planning architectures for complex scenario modeling. Workday Inc. and NetSuite Inc. represent cloud-native challengers that have captured share among buyers prioritizing remote accessibility and automatic version control over capital-intensive infrastructure.
| Leading Market Players |
|---|
| Oracle |
| SAP SE |
| Workday Inc. |
| NetSuite Inc. |
| Anaplan Inc. |
| Deltek Inc. |
| Planful Inc. |
| Sage Intacct Inc. |
| Prophix Software Inc. |
| Others |
Supply & Pricing Matrix
Multi-tenant cloud infrastructure amortization across AWS, Azure, and GCP data centers compresses marginal delivery costs for SaaS vendors while establishing price floors that on-premises competitors cannot match without equivalent scale. This concentration of hosting capacity in hyperscaler networks simultaneously anchors subscription pricing tiers and constrains vendor margin flexibility as procurement teams benchmark against standardized cloud unit economics.
Pricing Analysis
The customization-premium spread separates standard SaaS tiers from configured-to-order enterprise implementations, with the latter commanding three-to-five multiple pricing through dedicated implementation teams and bespoke integration protocols. Subscription pricing dominates as CFOs at venture-backed technology companies favor operational expenditure treatment for balance sheet flexibility. Price differentiation hinges on integration complexity and compliance certification tier, with ISO 27001 and SOC 2 Type II attestation unlocking premium positioning. Pricing pressure stems from mid-market procurement panels standardizing around out-of-box functionality, while large enterprises with dedicated IT infrastructure teams exhibit lowest price sensitivity due to bundled ERP replacement budgets.
Supply Chain Analysis
Inventory and lead-time compression in cloud-native delivery models eliminates traditional software manufacturing cycles, reducing vendor working capital requirements to near-zero through automated provisioning pipelines. Supply concentration rests on hyperscaler infrastructure in the United States, Ireland, and Singapore, with compute and storage resources drawing from Intel, AMD, and ARM semiconductor architectures. Raw material dependencies center on data center construction materials, submarine cable capacity, and specialized encryption hardware. Single-source vulnerability concentrates in AWS regional availability zones, where outages cascade across dependent vendor uptime commitments. Distribution runs through direct sales organizations for enterprise accounts and self-service marketplaces for mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Budgeting software demand is recovering from cyclical enterprise IT investment pauses as CFOs resume deferred cloud migration projects and compliance-driven replacement cycles accelerate procurement timelines.
For Market Incumbents: Secure API-first architecture investments to defend against composable microservice challengers fragmenting the planning module market. Deepen vertical integration into database-to-application stacks to sustain bundled pricing power against cloud-native specialists. Prioritize ISO 27001 certification maintenance as procurement panels harden security requirements. Channel control through implementation partner networks remains critical for large enterprise retention. For New Entrants and Emerging Players: Lead with AI-augmented scenario modeling capabilities to differentiate against deterministic spreadsheet logic entrenched in mid-market finance teams. Target India's domestic hosting requirements under RBI mandates as the most penetrable geography, where localized data centers create protected market space. Pursue embedded finance partnerships with neobank distribution channels to reach SMB segments without direct sales infrastructure investment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native specialists with API-first delivery models and composable microservice architectures, signaling superior long-term cash flow quality. Acquisition targets should emphasize vendors with established EU-hosted instances and CSRD-compliant ESG data pipelines. Watch for inflection in mid-market procurement velocity as spreadsheet-to-automation replacement cycles accelerate.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native SAP S/4HANA and Oracle Fusion connectors eliminate manual reconciliation for treasury functions. |
| Strategic Partnership | Banking-as-a-Service distribution exposes budgeting tools to SMBs through neobank interfaces. |
| Acquisition of Specialist Firm | Scenario analysis module providers fill capability gaps in deterministic legacy ERP planning stacks. |
| Geographic Expansion | Mumbai and Bangalore data centers satisfy RBI localization mandates for financial data hosting. |
| Product Launch | CSRD-native ESG data pipelines capture sustainability reporting investment from German automotive conglomerates. |
Research Methodology
A spread of perspectives from CFOs at mid-market enterprises, IT procurement officers, cloud platform engineers, and implementation consultants converged on the working assumptions driving segmentation and growth estimates. Primary interviews with finance transformation leads and treasury system administrators were validated against secondary sources including SEC filings, hyperscaler capex disclosures, and EU regulatory guidance documents on CSRD and GDPR compliance timelines. Bottom-up deployment counts and top-down SaaS spend estimates were triangulated to anchor market sizing.
Segmentation dimensions modeled include deployment architecture, solution type specialization, customer scale tier, and regional regulatory cluster across the analysis window. CAGRs were derived from fitted adoption curves weighted by compliance mandate effective dates and ERP replacement cycle timing. Forecast inputs incorporated cloud infrastructure pricing trajectories, professional services cost inflation, and mid-market finance automation penetration rates.
Underlying assumptions cover sustained cloud migration preference and stable hyperscaler pricing, with deviation risk concentrated in extended enterprise procurement freezes or accelerated on-premises data localization mandates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Archiving Software Market
Software & Services
Global Saas Backup Software Market
Software & Services
Indonesia Big Data Analytics Software Market
Software & Services
Open Stack Service Market
Software & Services
Bridge Analysis Software Market
Software & Services
Mind Mapping Software Market
Software & Services
Global Handyman Software Market
Software & Services
Global Roofing Software Market
Software & Services
Retail Space Planning Software Market
Software & Services
Global Mobile Application Testing Solution Market
Software & Services
Global Catalog Management Systems Market
Software & Services
Tech Support Services Market
Software & Services
Supplier Quality Management Applications Market
Software & Services
Content Services Platforms Market
Software & Services
HSM-As-A-Service Market
Software & Services
GCC Human Capital Management Software Market