
 Telecom IT Services Market | 2026-2036
Telecom IT Services Market Size, Share, and Industry Trends Forecast 2026-2036
Telecom IT Services Market Intelligence
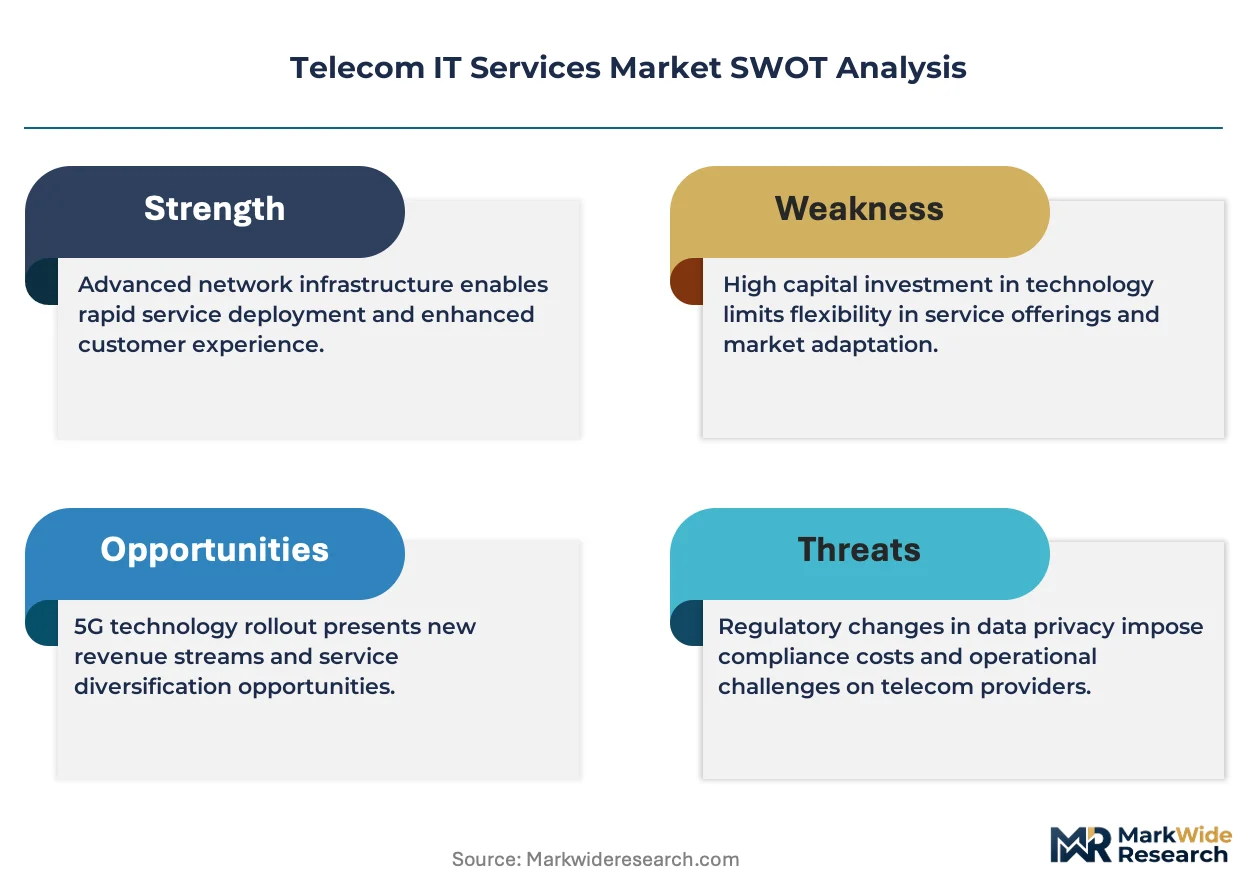
Enterprise cloud migration is pivoting telecom IT spending away from legacy on-premise infrastructure. Cisco dominates enterprise routing and security layers for service providers. Ericsson anchors 5G core modernization programs across European operators. Huawei competes aggressively on price-performance in emerging market deployments despite trade restrictions.
Telecom IT Services encompass the design, deployment, and management of software systems that enable telecommunications networks to process voice, data, and video traffic with sub-millisecond latency requirements and carrier-grade reliability standards. These services ensure operational continuity for networks handling millions of concurrent subscriber sessions. Cloud Services within the Service Type dimension captures the fastest-expanding margin pool as operators shift from owned data centers to distributed edge architectures. Network Optimization under Application Area leads in contract value due to 5G densification requirements, while Customer Experience Management remains mature with slower growth but stable recurring revenue.
FCC net neutrality rulings and EU GDPR frameworks shape how telecom IT vendors architect subscriber data platforms and cross-border traffic management systems. India's TRAI mandates on quality of service drive investment in real-time network analytics. Stakeholders must weigh sovereign data requirements against cloud economics when selecting deployment architectures for next-generation core networks.
Market Dynamics
Managed services contracts are compressing capital intensity for mobile network operators while 5G standalone rollouts force vendor consolidation under divergent regulatory frameworks.
Growth Catalysts
- EU GDPR frameworks:Mandates on subscriber data localization drive investment in sovereign cloud architectures for telecom core networks.
- Network densification:5G mid-band deployment requirements in urban India accelerate demand for real-time radio optimization platforms.
- Edge computing:Distributed processing architectures reduce backhaul costs for latency-sensitive video traffic in Japanese industrial zones.
Market Restraints
- Semiconductor supply concentration:Advanced node chip fabrication bottlenecks in Taiwan constrain baseband processor availability for European equipment vendors.
- FCC equipment authorization delays:Extended certification timelines for software-defined radios slow vendor product launches in the US market.
- Open RAN interoperability gaps:Fragmented interface specifications between disaggregated hardware layers inflate integration costs for tier-two operators.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for telecom equipment manufacturing attract IT service providers to establish captive development centers in Gujarat and Tamil Nadu.
- AI-driven network automation:Convergence of machine learning inference engines with streaming telemetry creates new service revenue pools for predictive maintenance contracts.
- Private 5G deployments:Industrial campuses in Germany's Ruhr region seek turnkey IT integration services for standalone campus networks.
Industry Challenges
- Cloud-native skill scarcity:Container orchestration and microservices architecture expertise remains concentrated among a limited pool of engineers in Bangalore and Stockholm.
- Legacy billing integration:Proprietary mediation systems from the 3G era resist API-based modernization, forcing expensive middleware layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telecom IT Services Market |
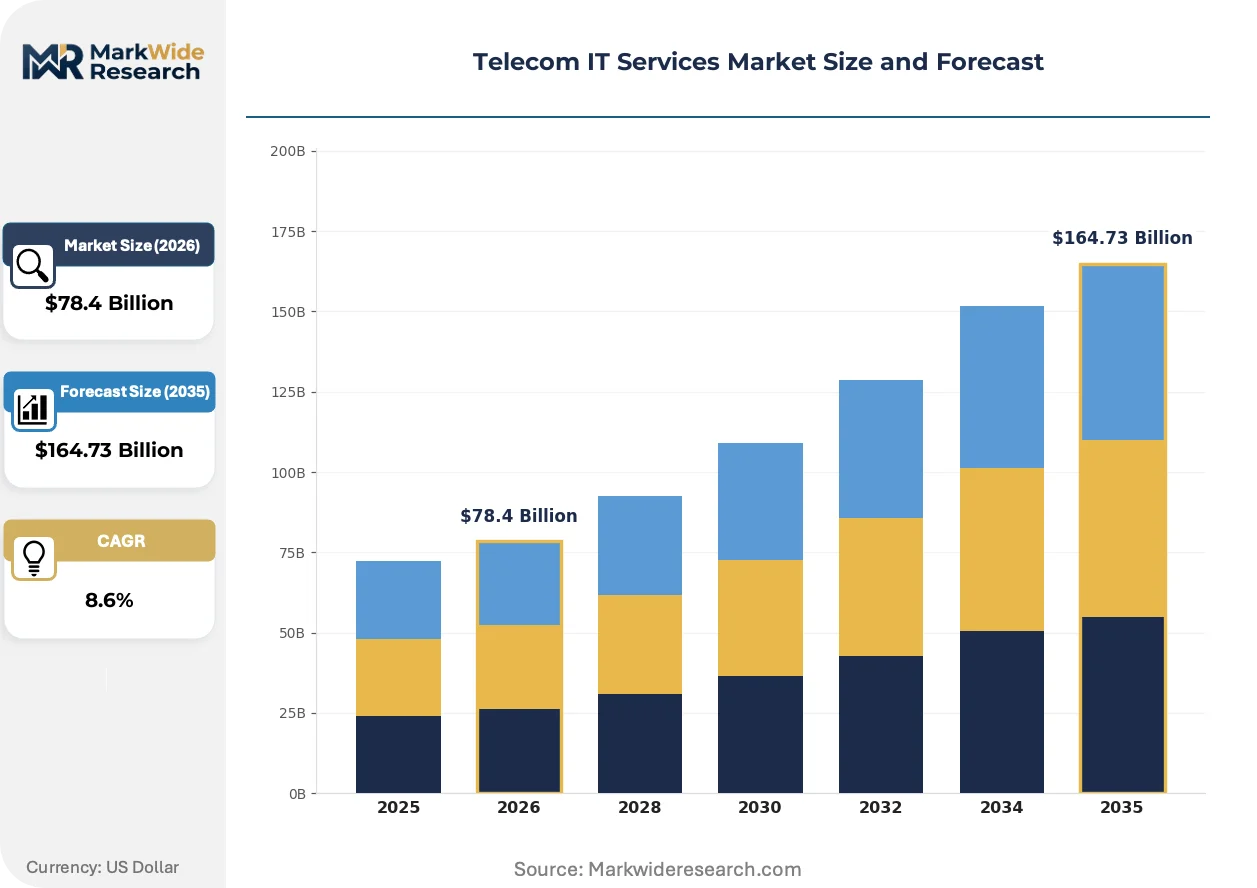
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $164.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Network Management, IT Consulting, System Integration, Application Management, Cloud Services, Data Analytics Deployment Model: On-Premise, Cloud-Based, Hybrid Cloud, Managed Services End User Industry: Telecommunication Operators, Internet Service Providers, Technology Vendors, Content Providers, Government Agencies Application Area: Customer Experience Management, Network Optimization, Revenue Assurance, Fraud Management, IT Infrastructure, Security Management |
| Companies Covered | Huawei, Cisco, Accenture, Capgemini, NTT Data, IBM, Nokia, Infosys, Ericsson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telecom IT Services Market Strategic Shifts & Innovations
Telecom IT architecture is pivoting from centralized data centers toward distributed edge fabrics that co-locate compute with radio access infrastructure.
Containerized network functions are rewriting how operators deploy core services. Mobile operators in South Korea and Finland are migrating subscriber management to Kubernetes-orchestrated workloads. This shift is compressing hardware vendor lock-in and accelerating multi-vendor procurement cycles.
India's TRAI quality-of-service mandates now require granular latency reporting at the district level. Operators must deploy continuous probe-based measurement systems rather than periodic drive tests. Tier-one carriers are responding by embedding analytics engines directly into transport layer equipment.
Enterprise buyers are unbundling managed services from infrastructure procurement. German automotive manufacturers now contract network operations separately from radio equipment purchases, creating openings for specialized IT service vendors. This pattern is most pronounced in Bavaria's industrial corridor where factory automation demands carrier-grade reliability without vendor-tied support contracts.
Telecom IT Services Market Segmentation
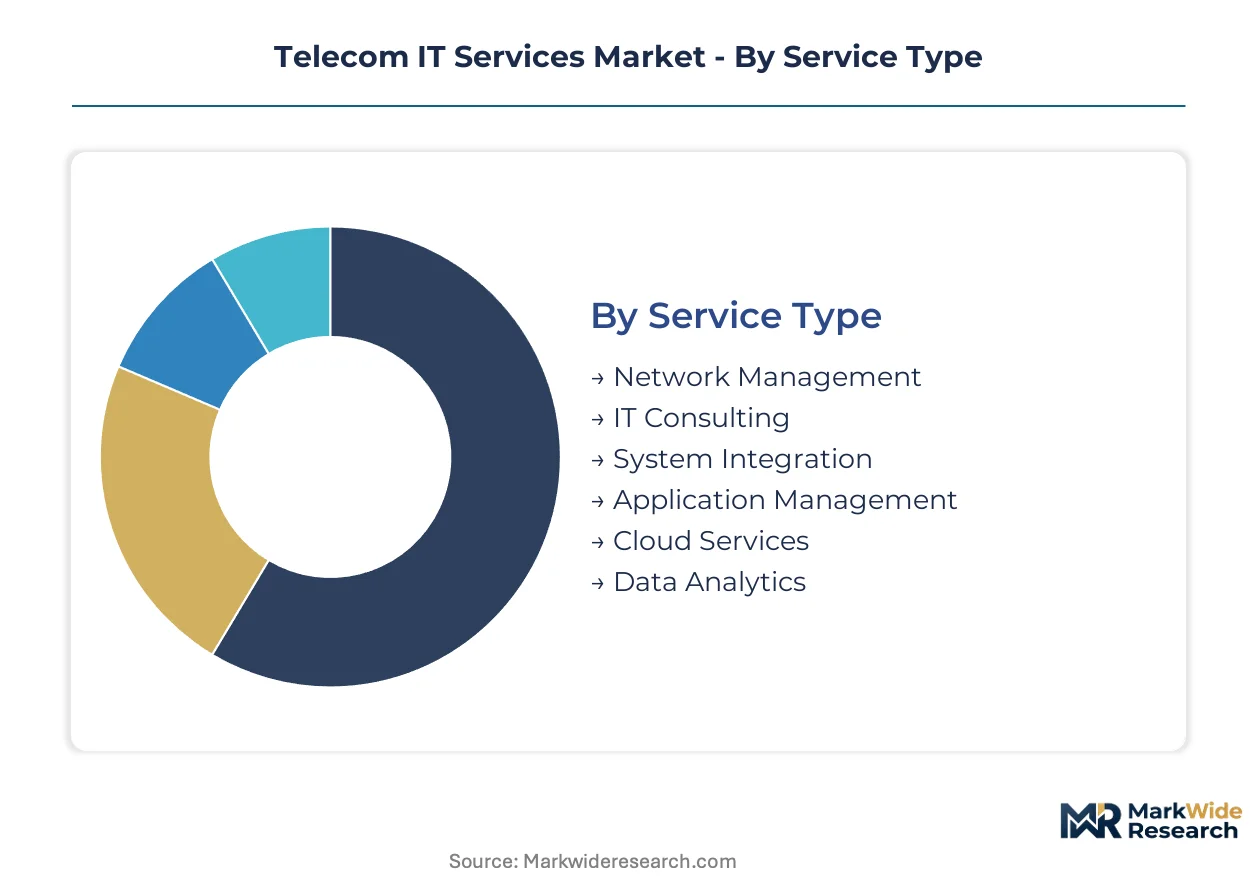
Telecom IT Services Market segmentation reveals distinct procurement patterns across service layers, deployment architectures, and operational applications. Operators prioritize segments that reduce capital intensity while meeting carrier-grade reliability standards for 5G core modernization.
Service Type:
Technical sophistication and margin structure vary sharply across service layers, with cloud-native offerings commanding premium pricing against legacy managed services.
- Cloud Services:Distributed edge architectures co-locate compute with radio access infrastructure, reducing backhaul costs for latency-sensitive traffic. Indian operators Jio and Airtel are driving large-scale migrations from owned data centers to sovereign cloud frameworks under TRAI mandates.
- Network Management:Real-time orchestration platforms process streaming telemetry from millions of subscriber sessions with sub-millisecond response requirements. European operators under EU GDPR frameworks invest heavily in subscriber data localization within sovereign network cores.
- IT Consulting:Strategic advisory for 5G standalone migration and vendor consolidation programs.
- System Integration:Middleware deployment bridging proprietary 3G-era billing systems with API-native cloud platforms.
- Application Management:Lifecycle support for containerized network functions on Kubernetes-orchestrated workloads.
- Data Analytics:Predictive maintenance engines and real-time network optimization algorithms.
Mature deployment sits with Network Management. Newer deployment is concentrated in Cloud Services.
Deployment Model:
Cost tier alignment determines procurement patterns, with hybrid architectures capturing mid-market operators balancing legacy debt against cloud economics.
- Managed Services:Outsourced network operations compress capital intensity for mobile operators while transferring operational risk to specialized vendors. German automotive manufacturers in Bavaria's industrial corridor now contract network operations separately from infrastructure procurement.
- Hybrid Cloud:Workload portability between on-premise cores and distributed edge nodes addresses data sovereignty requirements without sacrificing elasticity. South Korean and Finnish operators lead migration of subscriber management to Kubernetes-orchestrated hybrid environments.
- On-Premise:Dedicated infrastructure for classified government communications and ultra-low-latency industrial control systems.
- Cloud-Based:Fully outsourced SaaS models for customer experience management and non-critical business applications.
Volume concentration favors Managed Services. Margin expansion is steepest in Hybrid Cloud.
End User Industry:
Application context shapes specification requirements, with telecommunications operators demanding carrier-grade reliability unavailable to enterprise IT buyers.
- Telecommunication Operators:Mobile network operators and fixed-line incumbents require sub-millisecond latency guarantees and 99.999% availability for core network functions. India's TRAI quality-of-service mandates now require granular latency reporting at the district level, forcing continuous probe-based measurement systems.
- Internet Service Providers:Fiber and cable operators prioritize bandwidth optimization and congestion management for residential broadband aggregation.
- Technology Vendors:Equipment manufacturers seeking IT service partnerships for integrated solution delivery.
- Content Providers:Streaming platforms and CDN operators requiring edge cache deployment and traffic engineering.
- Government Agencies:National security and critical infrastructure communications with sovereign data requirements.
Procurement scale peaks with Telecommunication Operators. Fastest contract growth is appearing in Government Agencies.
Application Area:
Technology maturity and investment priority diverge across operational domains, with network-facing applications commanding larger budgets than customer-facing systems.
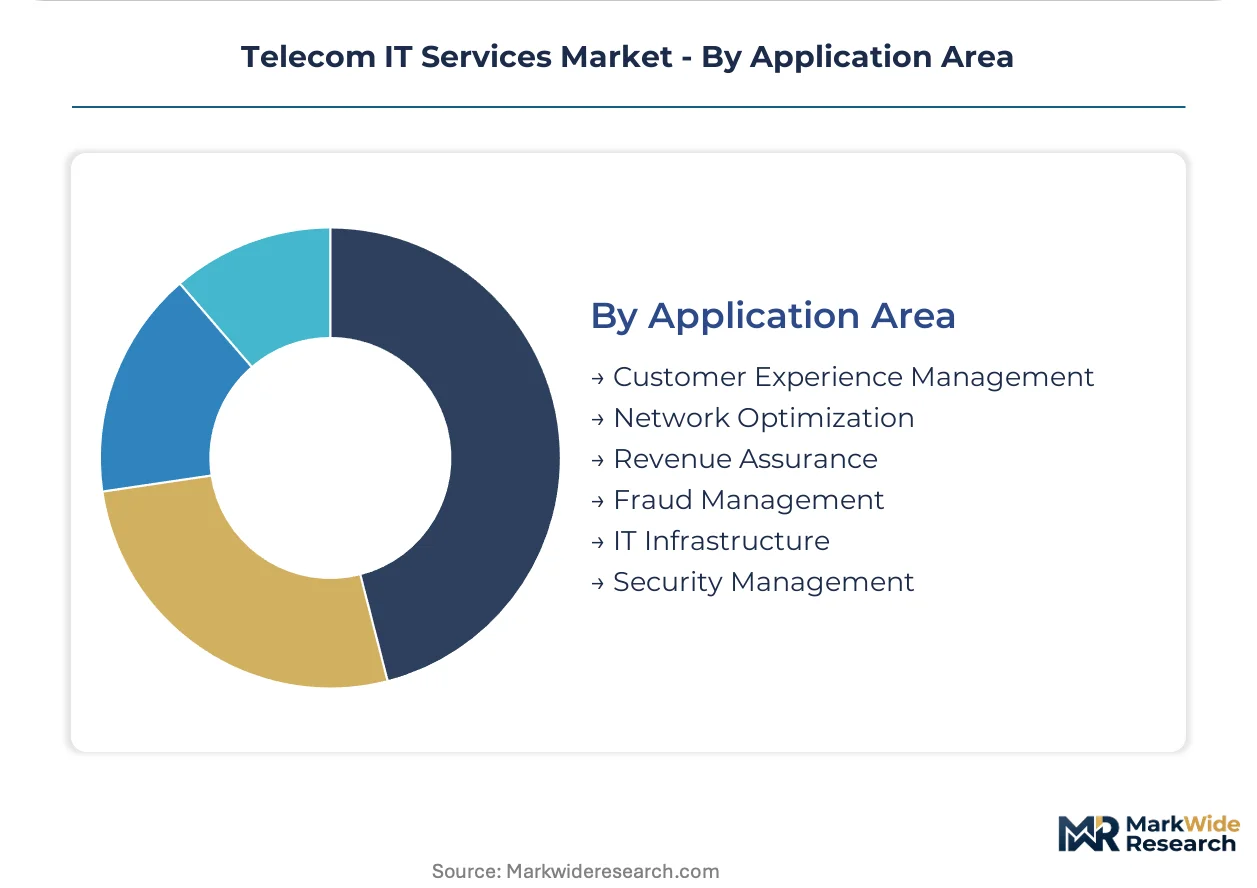
- Network Optimization:Real-time radio resource management and 5G densification planning tools address mid-band deployment requirements in urban India. Continuous analytics engines embedded directly into transport layer equipment replace periodic drive tests under evolving regulatory mandates.
- Security Management:Zero-trust architectures for 5G core networks protect against signaling vulnerabilities and subscriber data exfiltration. FCC net neutrality rulings and EU GDPR frameworks shape how vendors architect cross-border traffic management and subscriber data platforms.
- Customer Experience Management:Mature segment with stable recurring revenue from churn prediction and personalized service delivery.
- Revenue Assurance:Fraud detection and billing integrity systems for complex 5G service chaining.
- Fraud Management:Real-time signaling analysis to detect SIM cloning and international revenue share fraud.
- IT Infrastructure:Server, storage, and virtualization layer management for network function hosting.
Investment maturity sits with Customer Experience Management. Accelerating deployment is concentrated in Network Optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's special economic zones for telecom equipment manufacturing are concentrating IT service delivery capacity under India's PLI scheme. TRAI quality-of-service mandates drive granular latency reporting requirements. Jio and Airtel anchor large-scale digital infrastructure investments.
United States
Verizon and AT&T are accelerating 5G standalone core migrations. FCC equipment authorization delays constrain software-defined radio certification timelines. Dallas-Fort Worth hosts concentrated vendor integration centers serving southwestern operators.
Germany
BMW and Siemens are contracting private 5G campus networks in Bavaria's industrial corridor. EU GDPR frameworks mandate subscriber data localization within sovereign network cores. Stuttgart engineering clusters demand carrier-grade reliability without vendor-tied support contracts.
India
Jio and Airtel are driving cloud migrations from owned data centers to sovereign edge architectures. TRAI mandates continuous probe-based measurement systems replacing periodic drive tests. Bengaluru and Hyderabad concentrate container orchestration expertise for Kubernetes-orchestrated workloads.
South Korea
SK Telecom and KT are migrating subscriber management to distributed edge nodes. METI-aligned industrial automation standards shape latency requirements for smart factory deployments. Seoul Capital Area anchors real-time radio optimization platform development.
Japan
NTT Docomo is deploying AI-driven network automation for predictive maintenance contracts. METI regulations on critical infrastructure communications enforce carrier-grade availability standards. Nagoya's industrial zones reduce backhaul costs through edge computing for video traffic.
Telecom IT Services Market Key Industry Players
Top-tier vendors anchor 5G core modernization programs, while mid-tier specialists capture managed services contracts from capital-constrained operators. The vendor base stratifies across integrated equipment providers, IT consulting houses, and cloud-native software specialists. Strategic archetypes include infrastructure incumbents defending routing layers, systems integrators bridging legacy billing with API-native platforms, and emerging edge computing pure-plays. Competitive moves concentrate on vendor consolidation partnerships and captive development center establishment under production-linked incentive schemes.
Within the infrastructure tier, Cisco and Ericsson exemplify divergent geographic positioning strategies. Cisco dominates enterprise routing and security layers for North American service providers. Ericsson anchors European 5G core modernization programs under GDPR-compliant architectures. Huawei occupies a price-performance position in emerging market deployments despite trade restriction headwinds. Accenture and Capgemini represent the IT consulting archetype, capturing strategic advisory contracts for standalone migration and vendor consolidation programs.
| Leading Market Players |
|---|
| Huawei |
| Cisco |
| Accenture |
| Capgemini |
| NTT Data |
| IBM |
| Nokia |
| Infosys |
| Ericsson |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up managed services specialists now dominate mid-tier procurement, compressing margins through scale-based pricing discipline while locking in multi-year operator contracts that reshape vendor consolidation economics across Indian and European deployment corridors.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent 5G standalone core deployments from standard migration timelines, with Indian operators under TRAI mandates paying premiums for accelerated delivery while European carriers negotiate discounts on phased rollouts. Three-tier pricing structure across premium carrier-grade, standard enterprise, and economy managed service levels reflects certification tier and after-sales bundling intensity. Cost compression in the economy tier intensifies because Open RAN interoperability gaps inflate integration overhead. Tier-two operators in emerging markets exhibit highest price sensitivity; hyperscale cloud providers demonstrate least.
Supply Chain Analysis
Advanced node semiconductor supply rests on Taiwanese foundry capacity, Korean memory fabrication, and Japanese specialty substrate producers, creating concentrated dependency for baseband processors and AI inference accelerators. Container orchestration software draws from Bangalore and Stockholm engineering clusters, while sovereign cloud hardware sources from EU-certified European foundries. Single-source vulnerability in 7nm and below chip fabrication constrains European equipment vendor output. Distribution runs through direct vendor-operator contracts for core network elements, with systems integrators intermediating managed services layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vendor consolidation pressure from 5G standalone migration complexity and capital intensity compression will force sub-scale IT service providers into distressed exits or acquisition.
For Market Incumbents: Anticipate margin erosion from cloud-native specialists by deepening backward integration into container orchestration talent pools in Bangalore and Hyderabad. Lock in exclusive managed services contracts with Indian operators before PLI scheme incentives attract additional captive development centers. Prioritize GDPR-compliant sovereign cloud architectures to defend European positioning against emerging edge computing pure-plays.
For New Entrants and Emerging Players: Capture white-space in private 5G campus network integration for German automotive manufacturers in Bavaria's industrial corridor, where factory automation demands carrier-grade reliability without vendor-tied support contracts. Target government agencies with sovereign data requirements as fastest-contract-growth segment. Lead with AI-driven predictive maintenance service offerings to differentiate from infrastructure-heavy incumbents.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier managed services specialists with established European operator relationships but strained balance sheets from Open RAN integration cost overruns. Long-term viability hinges on Kubernetes-orchestrated workload migration capabilities and captive access to Bangalore container orchestration talent. Watch TRAI enforcement intensity on district-level latency reporting as inflection indicator for Indian real-time analytics platform demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Development Center Establishment | PLI scheme incentives in Gujarat and Tamil Nadu concentrate IT service delivery capacity for Indian operator contracts. |
| Kubernetes-Orchestrated Workload Migration | South Korean and Finnish operator deployments compress hardware vendor lock-in and accelerate multi-vendor procurement cycles. |
| AI-Driven Predictive Maintenance Service Launch | NTT Docomo deployments in Nagoya industrial zones create reference architecture for latency-sensitive video traffic optimization. |
| Sovereign Cloud Architecture Certification | EU GDPR frameworks mandate subscriber data localization, favoring vendors with compliant European core network deployments. |
| Private 5G Campus Network Integration Partnership | BMW and Siemens contracting patterns in Stuttgart engineering clusters validate turnkey IT service model for industrial automation. |
Research Approach
Document review covered FCC equipment authorization filings, EU GDPR implementation guidance, TRAI quality-of-service mandates, and operator capex disclosures, complemented by interviews with network operations executives at tier-one mobile operators, procurement leads at European equipment vendors, cloud architects at Indian IT service providers, and regulatory affairs specialists at telecommunications standards bodies. Secondary validation drew from SEC 10-K infrastructure spending disclosures, EU 5G observatory deployment trackers, and Indian PLI scheme beneficiary announcements. Bottom-up contract value aggregation and top-down market sizing triangulated segment-level estimates.
Model outputs project service-type and deployment-model splits across the analysis window, with segmentation dimensions spanning cloud-native versus legacy managed services, sovereign versus hybrid cloud architectures, and telecommunication operator versus government agency end-use. CAGRs derived from operator-reported infrastructure spending trajectories, vendor backlog analysis, and regulatory mandate implementation timelines. Forecast inputs incorporated 5G standalone core migration schedules, container orchestration adoption curves, and sovereign data localization compliance deadlines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor supply normalization, Open RAN interoperability specification maturation, and FCC equipment authorization timeline volatility. Forecasts reflect documented assumptions on operator capital intensity preferences and regulatory enforcement intensity. A small set of triggers—Taiwan foundry capacity allocation shifts, EU AI Act network infrastructure provisions, and Indian PLI scheme expansion scope—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Automotive Operating Systems Market
Software & Services
Europe Human Resource (HR) Technology Market
Software & Services
US Content Services Platform Market
Software & Services
Data Compression Software Market
Software & Services
Global Microscopy Software Market
Software & Services
Europe Digital Signage Software Market
Software & Services
Hackathon Management Software Market
Software & Services
Global Referral Software Market
Software & Services
Collaboration Tools Market
Software & Services
UK Applicant Tracking System Market
Software & Services
Enterprise Backup and Recovery Software Market
Software & Services
Global Brain Training Software Market
Software & Services
Global Retail Sourcing and Procurement Software Market
Software & Services
Staffing Software Market
Software & Services
Global Audience Response Software Market
Software & Services
Multiexperience Development Platforms Market