
 Banking Team Collaboration Software Market | 2026-2036
Banking Team Collaboration Software Market Size, Share, and Industry Trends Forecast 2026-2036
Banking Team Collaboration Software Market Outlook
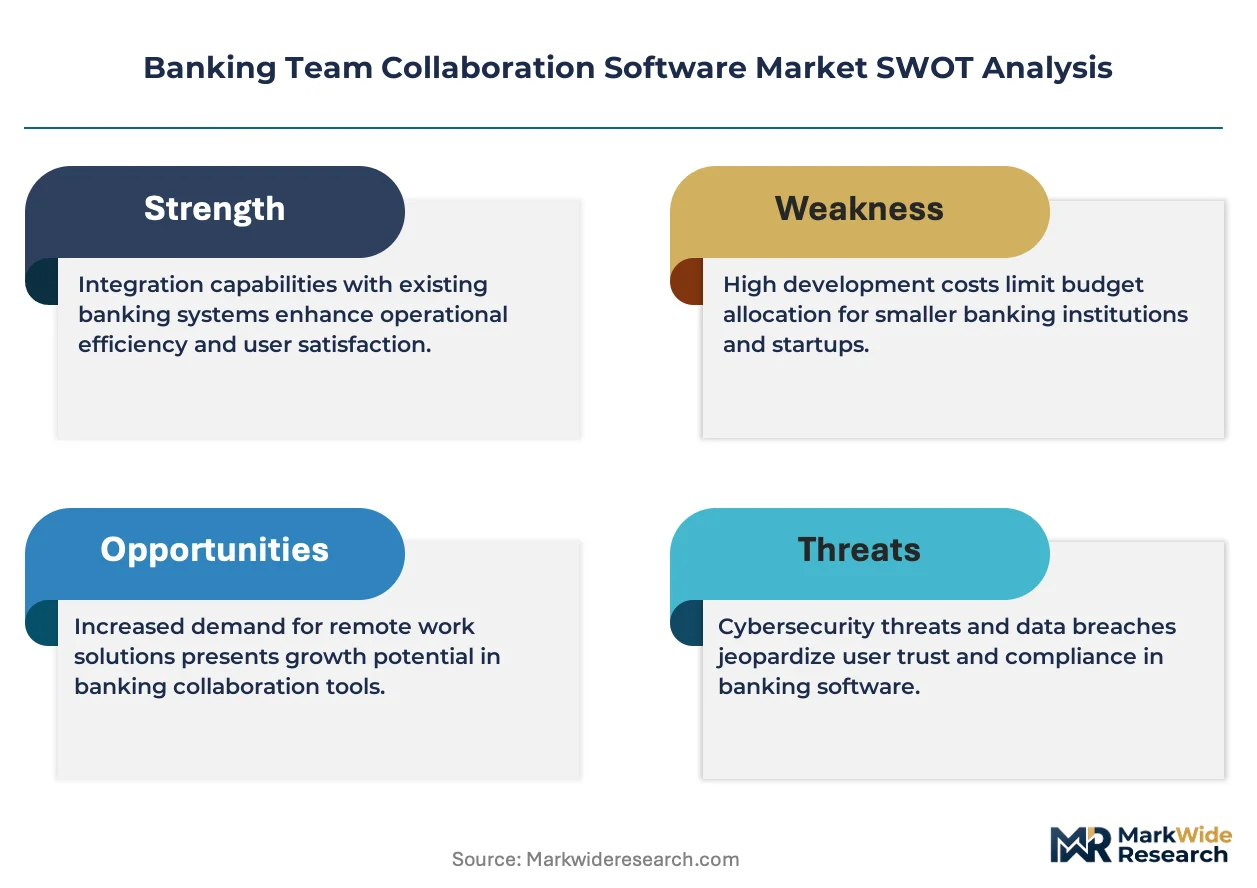
Enterprise-grade security certification is rotating from optional to mandatory in banking procurement cycles. Microsoft Corporation leverages its Azure compliance portfolio to anchor large institutional deployments across North America and Europe. Cisco Systems differentiates through hardened video infrastructure that sustains regulatory audit trails for trader communications. Slack Technologies competes by embedding workflow automation directly into messaging layers, occupying a niche among agile fintech teams.
Banking team collaboration software denotes integrated digital platforms enabling secure real-time communication, document co-authoring, and task orchestration across geographically dispersed financial personnel, typically architected with AES-256 encryption, role-based access controls, and API-first design for core banking system interoperability. Its primary commercial purpose is reducing operational latency in loan processing, trade settlement, and client onboarding while preserving immutable compliance records. Cloud-based solutions lead by deployment volume due to elastic scaling during quarterly reporting surges, while hybrid architectures capture margin pools from institutions with data residency requirements. Video conferencing features within wealth management segments show the fastest functional expansion as high-net-worth advisors prioritize faceless digital relationship continuity.
The Federal Reserve's operational resilience guidelines, SEC recordkeeping rules under Rule 17a-4, and the EU's GDPR and DORA framework collectively shape product roadmaps by mandating granular data lineage, retention policies, and cross-border transfer protocols. FINRA examination priorities further tighten vendor selection criteria around message archiving integrity and supervisory oversight capabilities. Stakeholders must monitor evolving jurisdictional fragmentation between US federal banking regulators and state-level privacy statutes when architecting multi-tenant platform strategies.
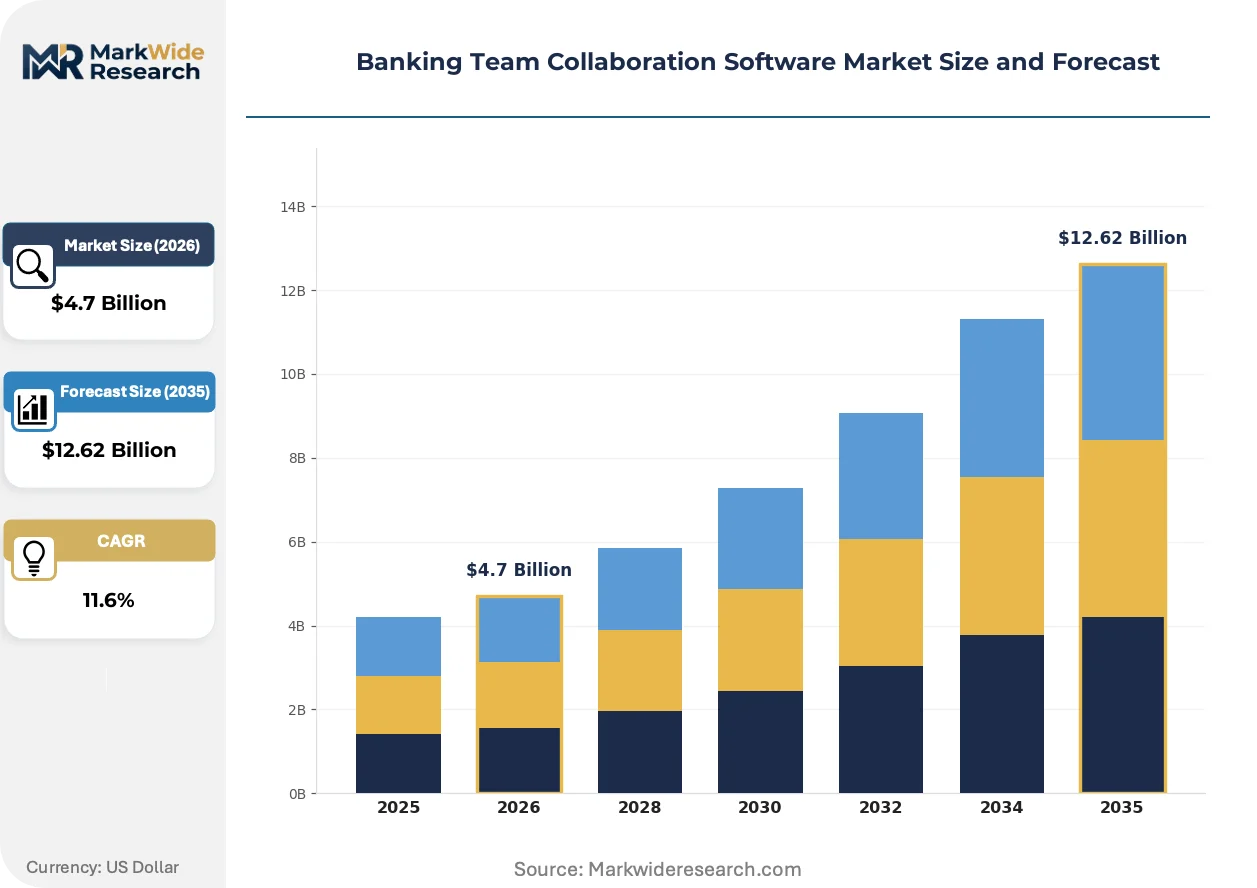
Market Dynamics
Cloud migration mandates under the EU AI Act and SEC recordkeeping rules are compressing procurement cycles, forcing banks to prioritize compliance-certified vendors over feature-rich alternatives. This regulatory gravity is restructuring competitive positioning around audit-ready infrastructure rather than collaboration functionality alone.
Growth Catalysts
- EU AI Act compliance deadlines:Financial institutions must deploy auditable AI systems by 2025, accelerating replacement of legacy messaging platforms with lineage-tracked alternatives.
- Wealth management digitization:High-net-worth advisors demand video-enabled relationship continuity without branch visits, expanding functional requirements for faceless advisory workflows.
- Hybrid work institutionalization:JPMorgan Chase and Goldman Sachs have normalized distributed deal teams, creating structural demand for real-time document co-authoring across time zones.
Market Restraints
- Data residency fragmentation:Divergent national data localization laws in Germany, France, and Singapore force costly multi-region infrastructure replication for global banks.
- Encryption export controls:AES-256 implementation faces licensing friction in jurisdictions with cryptographic restrictions, limiting vendor addressable markets.
- Legacy core system entrenchment:Mainframe-dependent regional banks face integration costs exceeding collaboration software license fees by factors of three to five.
Strategic Opportunities
- DORA implementation tailwinds:The EU's Digital Operational Resilience Act mandates operational continuity testing, creating demand for resilient collaboration infrastructure with guaranteed uptime SLAs.
- Embedded workflow automation:Convergence of RPA and messaging layers enables straight-through processing for loan approvals without human handoffs.
- India's GIFT City expansion:International banking units in Gujarat International Finance Tec-City require compliant collaboration tools for cross-border deal execution.
Industry Challenges
- FINRA examination intensity:Message archiving integrity failures trigger supervisory oversight penalties, requiring vendor-side forensic audit capabilities most platforms lack.
- Cross-functional talent scarcity:Banks struggle to hire engineers with simultaneous expertise in financial compliance, zero-trust architecture, and real-time systems engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Banking Team Collaboration Software Market |
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $12.62 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Cloud-Based, On-Premise, Hybrid, Mobile End User: Retail Banks, Investment Firms, Credit Unions, Wealth Management Feature: Document Sharing, Video Conferencing, Task Management, Messaging Deployment Model: Private Cloud, Public Cloud, Community Cloud, Hybrid Solution |
| Companies Covered | Microsoft Corporation, Slack Technologies, Cisco Systems, Google LLC, IBM Corporation, Oracle Corporation, Citrix Systems, AT&T Intellectual Property, Zoom Video Communications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Banking Team Collaboration Software Market Strategic Shifts
Artificial intelligence is decomposing traditional collaboration boundaries, embedding predictive task routing and automated compliance tagging directly into communication flows. This convergence is compressing the distinction between productivity software and core banking infrastructure.
API-first architecture is decomposing monolithic collaboration suites into composable microservices. Tier-one investment banks now assemble custom stacks from specialized vendors rather than accepting unified platform constraints. This modularity is enabling rapid reconfiguration during quarterly reporting surges without vendor lock-in penalties.
GDPR Article 17 right-to-erasure requirements are forcing architectural redesigns of message retention systems. Financial institutions must now maintain immutable audit trails while simultaneously enabling complete data deletion upon client request. Wealth management divisions face the steepest compliance costs as high-net-worth clients exercise privacy rights most aggressively.
Subscription fatigue among mid-market banks is displacing seat-based pricing with consumption-metered models tied to actual document processing volumes. Procurement teams at regional institutions now demand cost predictability aligned with transaction cyclicality rather than fixed annual commitments. This shift is most visible in the United States, where credit union consortiums negotiate collective purchasing agreements.
Banking Team Collaboration Software Market Segmentation
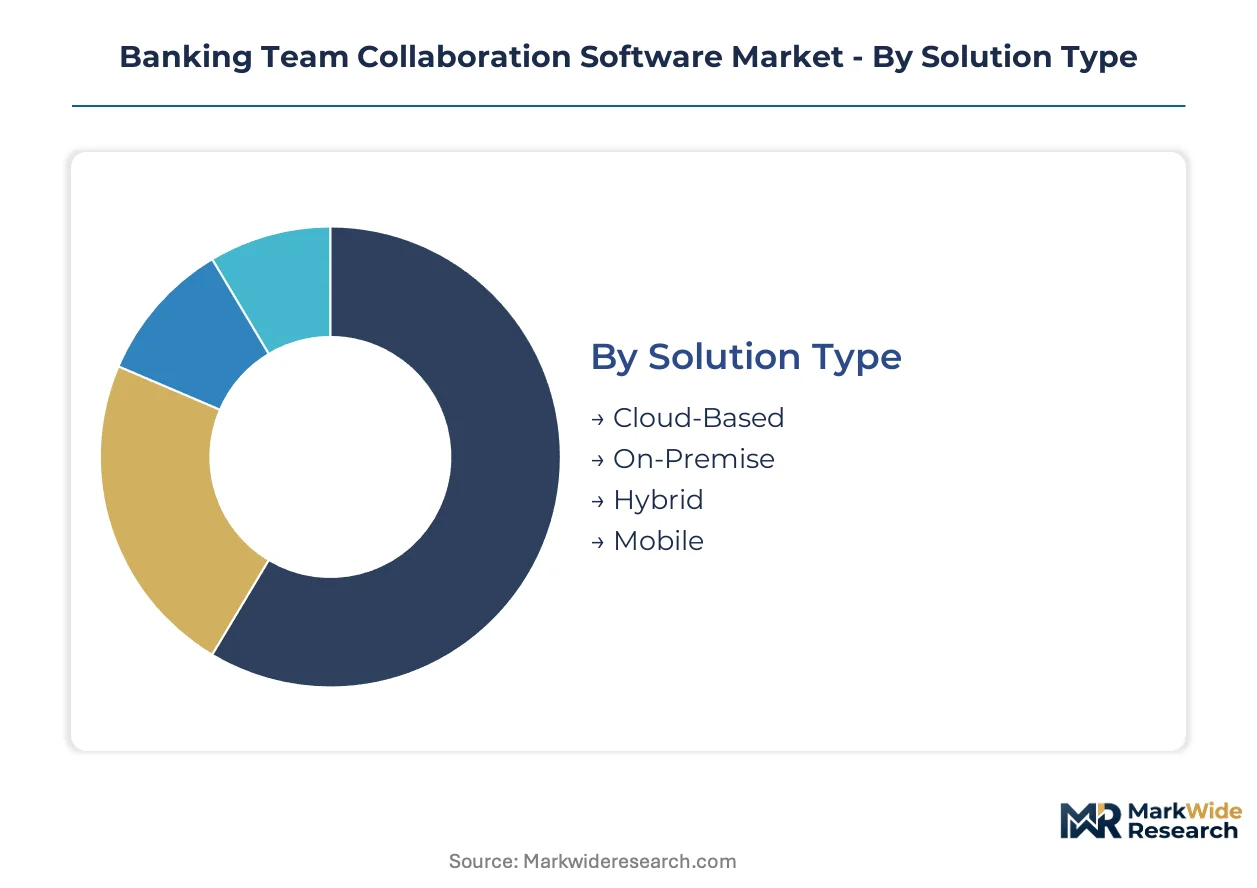
Segmentation in banking collaboration software reveals how procurement priorities diverge between compliance-heavy institutions and agility-driven teams. Deployment architecture and feature packaging determine vendor selection more than price in this regulated sector.
Solution Type:
Channel mix varies sharply: cloud solutions flow through systems integrators serving mid-market banks, while hybrid deployments require direct vendor relationships with tier-one institutions managing data residency constraints.
- Cloud-Based:Multi-tenant architectures with elastic scaling handle quarterly reporting surges at JPMorgan Chase and Goldman Sachs. Demand concentrates in the United States where Fed operational resilience guidelines permit off-premise infrastructure for non-core systems.
- Hybrid:Split-stack designs keep client PII on-premise while routing collaboration traffic through cloud edge nodes. European banks under GDPR Article 44 cross-border transfer rules drive procurement here, with Frankfurt and Paris-based institutions leading adoption.
- On-Premise:Air-gapped deployments serve defense-sector banking units and sanctions-screening teams requiring physical network isolation.
- Mobile:Hardened iOS and Android clients with biometric authentication extend trader workflows beyond dealing floors.
Cloud-Based dominates installed base. Hybrid is where expansion concentrates as DORA implementation deadlines approach.
End User:
Cost tier stratification separates enterprise-grade platforms for investment banks from standardized offerings priced for credit union consortiums.
- Investment Firms:Deal execution platforms integrate with order management systems and require sub-50 millisecond latency for trader communications. Goldman Sachs and boutique M&A advisors in Manhattan and London drive feature roadmaps here.
- Wealth Management:Video-enabled relationship continuity tools support high-net-worth advisors serving clients across time zones without branch visits. Singapore and Geneva private banks are expanding fastest.
- Retail Banks:Branch coordination and loan processing workflows prioritize document co-authoring over real-time messaging.
- Credit Unions:Cost-constrained institutions leverage consortium purchasing to access enterprise security certifications at reduced per-seat rates.
Investment Firms dominate installed base. Wealth Management is climbing the fastest as advisor digitization accelerates.
Feature:
Application maturity determines pricing power: video infrastructure commands premium margins while messaging commoditizes toward freemium models.
- Messaging:End-to-end encrypted channels with FINRA-compliant archiving replace Bloomberg Terminal chat for internal communications. Regional banks in the United States are displacing legacy email threads fastest.
- Video Conferencing:Hardened infrastructure sustaining regulatory audit trails differentiates vendor offerings for trader supervision requirements.
- Document Sharing:Co-authoring with granular permission matrices and immutable version control supports loan committee workflows.
- Task Management:Workflow automation embedding compliance checkpoints directly into approval chains reduces operational latency.
Messaging dominates installed base. Video Conferencing is gaining share fastest as wealth management digitization deepens.
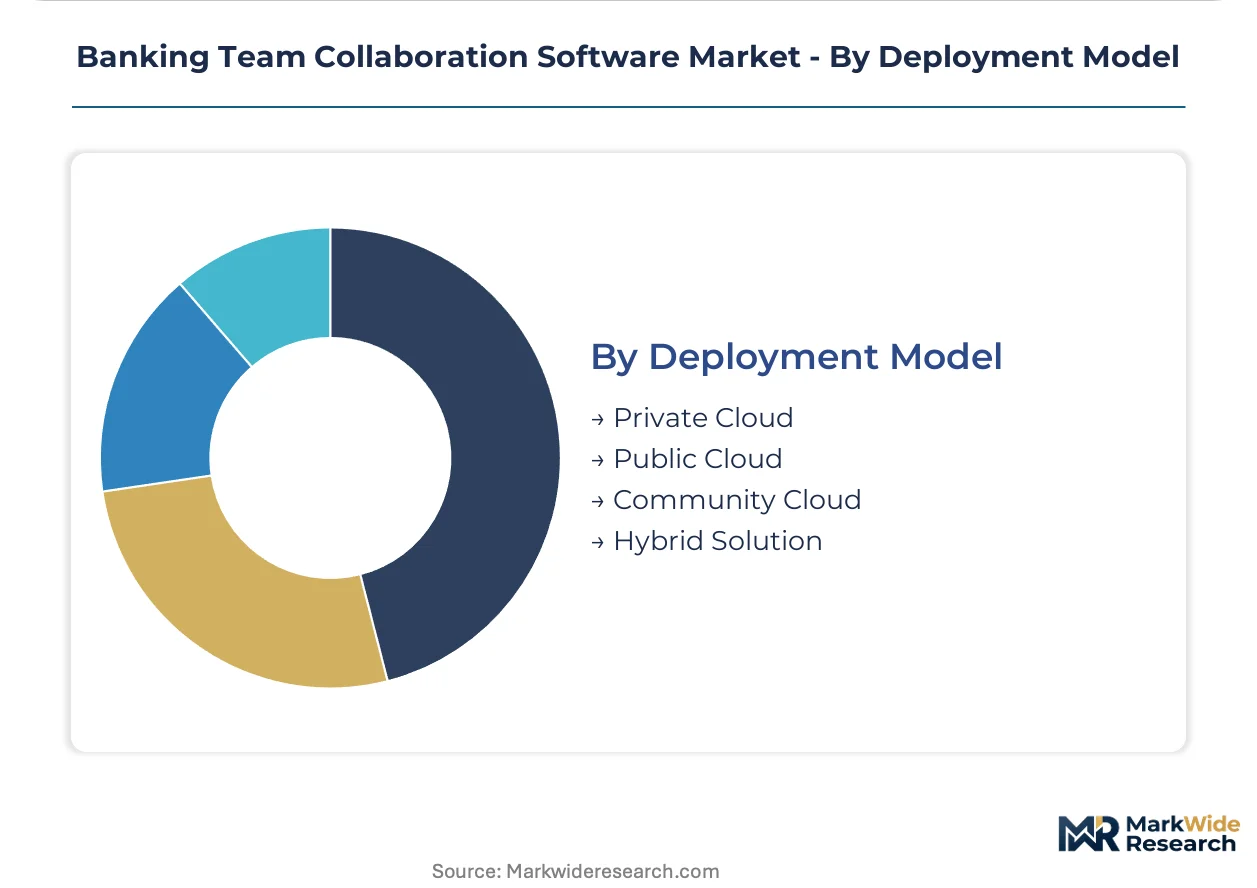
Deployment Model:
Volume concentration follows data residency mandates: private cloud captures German and French banking procurement while public cloud serves US institutions with lighter localization requirements.
- Private Cloud:Single-tenant infrastructure with dedicated hardware meets Bundesbank and Banque de France guidance on critical system isolation. Deutsche Bank and BNP Paribas operations in Frankfurt and Paris anchor demand.
- Public Cloud:Shared infrastructure with FedRAMP or equivalent certification serves regional US banks without dedicated security teams.
- Community Cloud:Banking consortium-specific instances enable credit unions and cooperative banks to share compliance-certified infrastructure.
- Hybrid Solution:Dynamic workload placement between private and public nodes optimizes cost during cyclical demand spikes.
Private Cloud dominates installed base. Hybrid Solution is where expansion concentrates as institutions seek operational flexibility without sacrificing control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor infrastructure concentrates in jurisdictions with mature cloud compliance frameworks. Procurement patterns diverge sharply between FedRAMP-certified US deployments and GDPR-bound European configurations.
United States
JPMorgan Chase and Goldman Sachs drive demand for hybrid architectures balancing regulatory compliance with trader mobility. SEC Rule 17a-4 and Fed operational resilience guidelines mandate granular message archiving with sub-second retrieval latency. Manhattan and Chicago trading floors anchor procurement volume for sub-50 millisecond communication infrastructure.
Germany
Bundesbank guidance on critical system isolation pushes Deutsche Bank and Commerzbank toward private cloud configurations. GDPR Article 44 cross-border transfer restrictions complicate multi-tenant platform strategies for Frankfurt-based institutions. The Mainhattan financial district concentrates demand for single-tenant infrastructure with dedicated hardware segregation.
United Kingdom
Post-Brexit regulatory divergence forces Barclays and HSBC to maintain parallel compliance architectures for EU and UK jurisdictions. The Financial Conduct Authority's operational resilience expectations tighten vendor selection criteria around guaranteed uptime SLAs. London's Square Mile and Canary Wharf clusters drive feature roadmaps for real-time document co-authoring across time zones.
Singapore
Wealth management digitization accelerates fastest among Geneva-competing private banks operating from the city-state. The Monetary Authority of Singapore's technology risk management guidelines emphasize audit trail integrity for high-net-worth advisory workflows. Marina Bay financial district institutions prioritize video-enabled relationship continuity tools for faceless client engagement.
India
GIFT City expansion creates compliant collaboration demand for international banking units executing cross-border deals. RBI guidelines on data localization push HDFC Bank and ICICI Bank toward domestic cloud infrastructure with encryption key sovereignty. Mumbai and Bengaluru technology corridors anchor systems integrator partnerships serving mid-market regional banks.
Banking Team Collaboration Software Market Competitive Environment
Concentration sits with hyperscale cloud providers possessing pre-built compliance certifications. Microsoft and Google leverage FedRAMP and GDPR-ready infrastructure to compress procurement cycles for tier-one institutions. Three archetypes dominate: compliance-anchored hyperscalers, security-specialized communication vendors, and workflow-native messaging platforms. Competitive moves center on M&A to fill archiving capability gaps and strategic partnerships with core banking system vendors.
Within the compliance-anchored hyperscaler tier, Microsoft Corporation exemplifies large institutional deployment patterns across North America and Europe. Cisco Systems occupies a position among security-specialized vendors with hardened video infrastructure sustaining regulatory audit trails. Slack Technologies sits within the workflow-native archetype, embedding automation directly into messaging layers for agile fintech teams. These three anchors illustrate how vendor selection prioritizes certification breadth over feature depth in compressed procurement cycles.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Slack Technologies |
| Cisco Systems |
| Google LLC |
| IBM Corporation |
| Oracle Corporation |
| Citrix Systems |
| AT&T Intellectual Property |
| Zoom Video Communications |
| Others |
Value Chain & Pricing Dynamics
Hyperscale cloud infrastructure investments by Microsoft Azure and Google Cloud Platform create nonlinear unit economics that compress price floors for mid-market banking software vendors while elevating barriers for challengers lacking FedRAMP certification at scale. This concentration dynamic forces regional banks into consortium purchasing arrangements that aggregate negotiating leverage against dominant suppliers.
Pricing Analysis
SEC Rule 17a-4 and GDPR Article 44 dictate the pricing tier structure across the banking collaboration software landscape. Three-tier pricing structure across premium, standard, and economy levels separates FedRAMP High-certified hyperscaler deployments from credit union consortium rates and air-gapped on-premise configurations. Price differentiation rests on certification depth and data residency guarantees rather than feature breadth. Cost compression in the standard tier is intensifying because mid-market banks are consolidating vendor relationships to reduce compliance audit overhead. Credit unions exhibit highest price sensitivity due to fixed IT budgets, while tier-one investment banks prioritize latency guarantees over per-seat costs.
Supply Chain Analysis
Trans-Pacific cable latency and Frankfurt-London fiber capacity constraints elevate infrastructure provisioning costs for real-time financial messaging networks. Hardware supply concentrates in Taiwan for specialized encryption accelerators, the United States for FedRAMP-certified server assemblies, and Ireland for GDPR-aligned data center equipment. Component dependencies draw from AES-256 cryptographic modules, low-latency network interface cards, and immutable storage arrays. Single-source vulnerability sits with specialized financial compliance middleware vendors whose archival engines anchor audit trail integrity. Distribution runs through systems integrators serving mid-market banks and direct enterprise relationships for tier-one institutions managing data sovereignty requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Banking team collaboration software demand tracks quarterly earnings cycles and regulatory implementation deadlines, creating predictable procurement surges that favor vendors with elastic capacity. Institutions front-load replacement investments ahead of EU AI Act compliance windows and DORA operational continuity mandates.
For Market Incumbents: Compound certification breadth into platform stickiness by embedding FINRA-compliant archiving and GDPR Article 17 erasure workflows as native capabilities rather than bolt-on modules. Acquire specialized messaging forensics vendors to close supervisory oversight gaps that examination failures expose. Prioritize vertical integration into core banking system interoperability layers to deepen switching costs for JPMorgan Chase and Goldman Sachs deployment archetypes. For New Entrants and Emerging Players: Differentiate on embedded workflow automation for agile fintech teams underserved by monolithic hyperscaler platforms. Target India's GIFT City international banking units requiring compliant cross-border collaboration infrastructure with lighter legacy integration burdens. Pursue partnership-first go-to-market strategies with regional systems integrators possessing existing Bundesbank or MAS regulatory relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among workflow-native messaging platforms serving wealth management digitization workflows with consumption-metered pricing models. Five-to-ten year viability favors vendors with pre-built compliance certifications across multiple jurisdictions rather than feature-rich challengers facing procurement cycle compression. Monitor FINRA examination priority shifts around AI-generated communication supervision as the critical inflection signal for platform obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Certification Expansion | FedRAMP High and GDPR Article 44 readiness accelerates tier-one procurement cycles at JPMorgan Chase and Deutsche Bank. |
| Embedded Workflow Automation | RPA-messaging convergence enables straight-through loan processing without human handoffs at regional institutions. |
| Geographic Infrastructure Localization | Frankfurt and Mumbai data center deployments satisfy Bundesbank and RBI data sovereignty mandates. |
| Forensic Archiving Capability Acquisition | Message integrity verification tools address FINRA examination priorities around supervisory oversight gaps. |
| API-First Architecture Investment | Composable microservices allow tier-one banks to assemble custom stacks without vendor lock-in penalties. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with bank CTOs, compliance officers at tier-one institutions, fintech platform engineers, channel partners, and integration specialists. Secondary validation drew from SEC 10-K infrastructure disclosures, FedRAMP certification databases, EBA stress test documentation, and hyperscaler capex filings. Bottom-up deployment volume estimates triangulated against top-down IT spending allocations from banking industry associations.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning deployment architecture, end-user institution type, functional feature category, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves and compliance deadline acceleration effects. Forecast inputs incorporated DORA implementation timelines, wealth management advisor digitization rates, and hybrid work institutionalization patterns at major investment banks.
Material uncertainties — jurisdictional regulatory fragmentation, encryption export control shifts, and legacy core system integration cost volatility — sit outside the modeled envelope. Forecasts reflect documented assumptions about procurement cycle compression and certification prioritization. Practitioners should keep alternative scenarios live as EU AI Act enforcement intensity and FINRA examination scope evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Poultry Farm Management Software Market
Software & Services
Global Molecular Modeling Software for Chemistry Market
Software & Services
Global UIUX Software Market
Software & Services
K8s Market
Software & Services
Partner Ecosystem Platform Software Market
Software & Services
Global Retail Inventory Management Software Market
Software & Services
Point Cloud Processing Software Market
Software & Services
Global Intranet Software Market
Software & Services
Global Polling Software Market
Software & Services
Landscaping Engineering Software Market
Software & Services
Content Curation Software Market
Software & Services
Global Church Management Software Market
Software & Services
France Digital Marketing Software Market
Software & Services
Lab Automation Software Market
Software & Services
Global Referral Software Market
Software & Services
Blogger Outreach Software Market