
 Global Food Traceability Software Market | 2026-2036
Global Food Traceability Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Food Traceability Software Market Foresight
North American software engineering capacity is reshaping competitive dynamics in food traceability platforms. IBM Corporation leverages blockchain architecture to anchor enterprise-grade provenance verification across multi-tier supply networks. SAP SE sustains market presence through deep ERP integration that connects farm-level data to retail analytics dashboards. Oracle Corporation competes via cloud-native traceability stacks that unify quality control workflows for food processors managing complex ingredient portfolios.
Food traceability software comprises digital systems that record, store, and transmit granular product movement data across agricultural and food manufacturing value chains, typically incorporating GS1 standards, RFID encoding, and distributed ledger protocols to establish immutable chain-of-custody records. These platforms serve the primary commercial purpose of enabling rapid contamination source identification, automating regulatory documentation, and validating label claims for consumers and enforcement agencies. Cloud-based deployment models are capturing disproportionate growth momentum as mid-sized food processors abandon capital-intensive on-premises infrastructure. Supply chain tracking solutions within the solution offering layer command the deepest margin pools due to recurring subscription structures and API-driven integration complexity. Farm to fork compliance applications attract the steepest investment flows as certification bodies mandate auditable digital trails for organic and allergen-controlled product categories.
The FDA's Food Safety Modernization Act traceability rules, the EU's General Food Law requirements administered by EFSA, and China's SAMR food safety standards are collectively elevating software functionality minimums across export-oriented food manufacturers. Japan's METI has introduced supply chain digitization incentives that accelerate platform procurement by seafood exporters serving premium retail segments. Stakeholders must monitor how regulatory divergence between major trading blocs fragments data format standards and multiplies compliance architecture costs for multinational food enterprises.
Market Dynamics
Blockchain-enabled immutable recordkeeping is compressing audit timelines and forcing legacy paper-based traceability systems into obsolescence across multi-tier food supply networks.
Growth Catalysts
- EU Green Deal labeling mandates:EFSA-administered requirements under the General Food Law are compelling food processors to deploy digital audit trails for organic and allergen-controlled categories.
- Cloud migration:Mid-sized food processors are abandoning capital-intensive on-premises infrastructure in favor of subscription-based SaaS traceability platforms with API-driven integration.
- Supermarket transparency expectations:Retail chains in Germany and France are demanding farm-to-fork verification systems to satisfy consumer scrutiny of ingredient provenance.
Market Restraints
- Data format fragmentation:Regulatory divergence between FDA traceability rules, EU EFSA standards, and China's SAMR requirements multiplies compliance architecture costs for multinational enterprises.
- Integration complexity:Legacy ERP systems in established food manufacturers require expensive middleware development to connect with modern traceability APIs.
- Specialized talent scarcity:Shortages of professionals skilled in GS1 standards implementation and distributed ledger protocol configuration constrain deployment velocity.
Strategic Opportunities
- Japan METI digitization incentives:Seafood exporters serving premium retail segments are accelerating platform procurement under government-backed supply chain modernization programs.
- RFID-GS1 convergence:The integration of radio-frequency identification encoding with standardized data carriers is opening automated batch-tracking applications in cold chain logistics.
- Farm-level sensor networks:IoT-enabled agricultural monitoring systems in Brazil and Australia are creating upstream data capture opportunities for traceability platform vendors.
Industry Challenges
- Interoperability gaps:Proprietary blockchain architectures from competing vendors prevent seamless data exchange across supply chain tiers, forcing buyers into single-platform lock-in.
- Certification timeline compression:Organic and fair-trade certification bodies are shortening audit windows, requiring real-time data availability that strains legacy system architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Food Traceability Software Market |
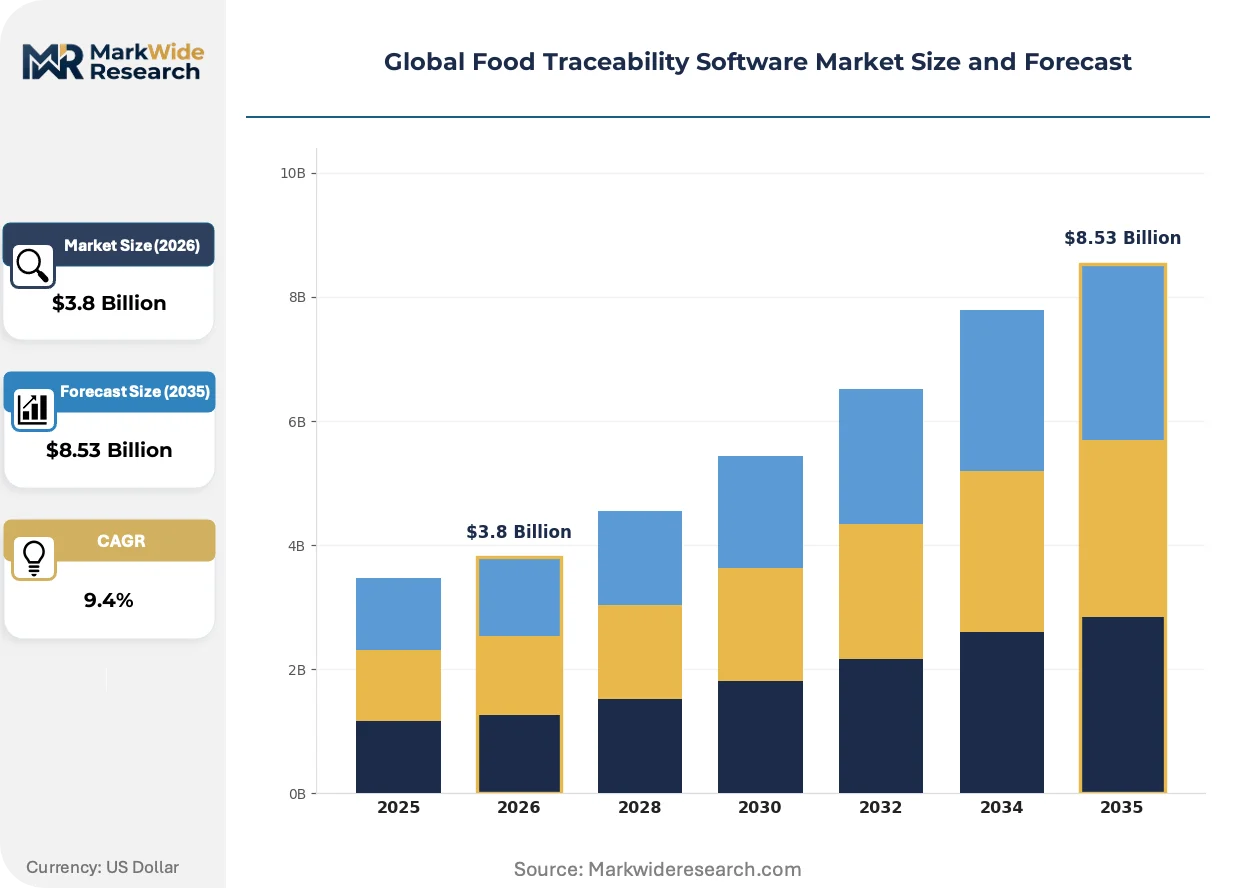
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-premises, Hybrid, SaaS Solution Offering: Ingredient Authentication, Supply Chain Tracking, Quality Control, Recall Management Application: Farm to Fork Compliance, Shelf Life Monitoring, Waste Reduction, Counterfeit Prevention End User: Food Processors, Retail Chains, Foodservice Operators, Certification Bodies |
| Companies Covered | IBM Corporation, SAP SE, Oracle Corporation, Honeywell International Inc., Zebra Technologies Corp., FoodLogiQ LLC, Trimble Inc., Siemens AG, C.H. Robinson Worldwide Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Food Traceability Software Market Shifts & Advancements
Distributed ledger protocols are actively displacing centralized database architectures as the trust layer for multi-party food supply verification. Three converging developments are compressing implementation timelines and reconfiguring competitive positioning.
Blockchain-based immutable recordkeeping is rendering obsolete paper-based chain-of-custody documentation and siloed ERP traceability modules. Large food manufacturers managing complex ingredient portfolios are piloting enterprise-grade distributed ledger deployments at accelerated procurement cycles. The technology is rendering obsolete the 30-90 day audit preparation windows that previously dominated regulatory compliance workflows.
The FDA's Food Safety Modernization Act traceability rules are mandating electronic sortable format records for designated high-risk foods. Food processors serving US export markets are reconfiguring data capture workflows to satisfy the FDA's compressed response-time requirements for contamination events. Seafood and fresh produce categories are experiencing the steepest compliance investment flows as they fall under the initial enforcement tranches.
Subscription-based API integration models are displacing perpetual-license software procurement in mid-tier food processing. Buyers are unbundling traceability functionality from monolithic ERP suites and procuring best-of-breed cloud solutions with modular pricing. Germany's food processing sector digitization is exhibiting the most pronounced shift toward recurring-revenue platform relationships over capital-intensive infrastructure ownership.
Global Food Traceability Software Market Segmentation
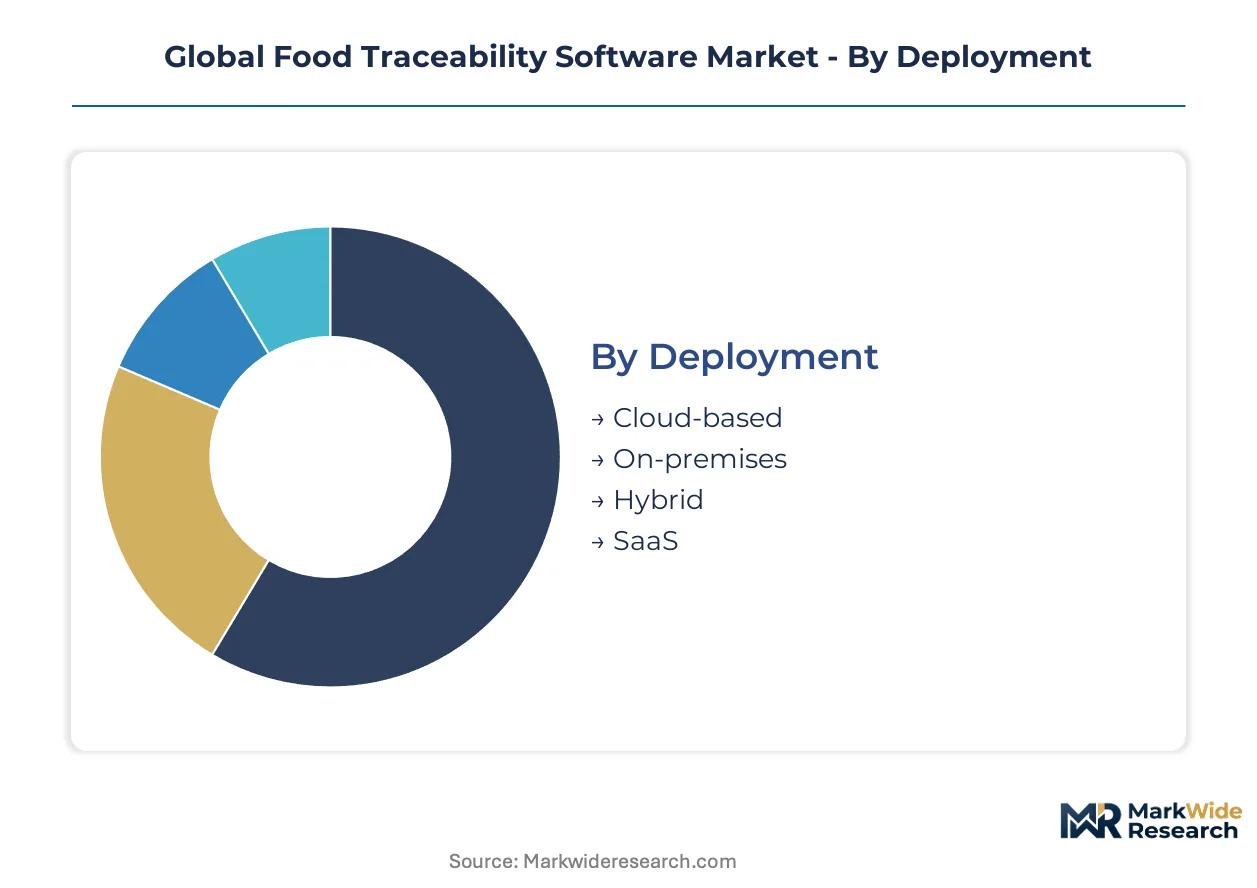
Segmentation in food traceability software reveals distinct technical and commercial requirements across deployment architectures, solution layers, and user workflows. Procurement patterns diverge sharply between multinational exporters seeking harmonized compliance and domestic operators prioritizing cost efficiency. Understanding these segment boundaries enables vendors to align product roadmaps with buyer willingness-to-pay and implementation complexity tolerance.
Deployment:
After-sales-service intensity varies dramatically across deployment modes, with cloud-native architectures demanding continuous technical support while on-premises installations require sporadic but specialized intervention.
- Cloud-based:Multi-tenant architectures with automatic updates and API-driven integration dominate procurement by mid-sized food processors in Germany and France. Subscription models align vendor incentives with long-term customer success, driving intensive customer success functions. Momentum sits with this segment as processors abandon capital-intensive infrastructure ownership.
- SaaS:Modular, pay-per-function platforms with rapid deployment timelines attract specialty food manufacturers managing seasonal product lines. The segment's low-code configuration requirements reduce implementation bottlenecks for buyers lacking dedicated IT departments.
- On-premises:Perpetual-license software hosted within buyer data centers persists among large enterprises with strict data sovereignty requirements or legacy ERP dependencies. These installations demand periodic vendor visits for version upgrades and security patching.
- Hybrid:Split architectures combining cloud analytics with local edge computing serve cold chain operators requiring real-time processing without full connectivity dependency.
Cloud-based holds the largest share; momentum sits with SaaS as procurement unbundles from monolithic ERP suites.
Solution Offering:
Cost tier stratification separates premium solutions with predictive analytics from baseline compliance modules, with integration complexity driving pricing spreads.
- Supply Chain Tracking:End-to-end visibility platforms incorporating GS1 standards, RFID encoding, and blockchain anchoring command the deepest recurring revenue pools. German retail chains and seafood exporters in Japan under METI digitization programs drive concentrated demand for multi-tier network coverage.
- Ingredient Authentication:Spectral analysis and molecular verification systems validate provenance claims for organic and premium product categories. Certification bodies in the EU and US mandate these capabilities for label integrity enforcement.
- Quality Control:Automated inspection workflows with deviation alerting reduce manual sampling labor for high-volume processors.
- Recall Management:Rapid batch isolation and stakeholder notification systems compress response timelines during contamination events.
Supply Chain Tracking commands premium pricing; Ingredient Authentication climbs fastest as certification standards tighten.
Application:
Volume concentration in compliance-driven applications reflects regulatory enforcement priority, with farm-to-fork systems capturing disproportionate investment flows.
- Farm to Fork Compliance:Comprehensive audit trail platforms satisfying EU EFSA requirements, FDA FSMA rules, and China's SAMR standards attract the steepest investment from export-oriented manufacturers. The segment requires continuous data availability as organic and fair-trade certification bodies compress audit windows.
- Shelf Life Monitoring:Dynamic expiry prediction based on temperature exposure and handling history reduces retail shrinkage for perishable categories.
- Counterfeit Prevention:Cryptographic verification systems protect premium product categories against diversion and substitution in complex distribution networks.
- Waste Reduction:Inventory optimization algorithms aligned with demand forecasting minimize spoilage for processors with volatile input quality.
Farm to Fork Compliance dominates procurement budgets; Counterfeit Prevention gains share fastest as premium segment fraud escalates.
End User:
Customer type determines functional requirements, with retail chains demanding consumer-facing transparency while processors prioritize backward integration into supplier networks.
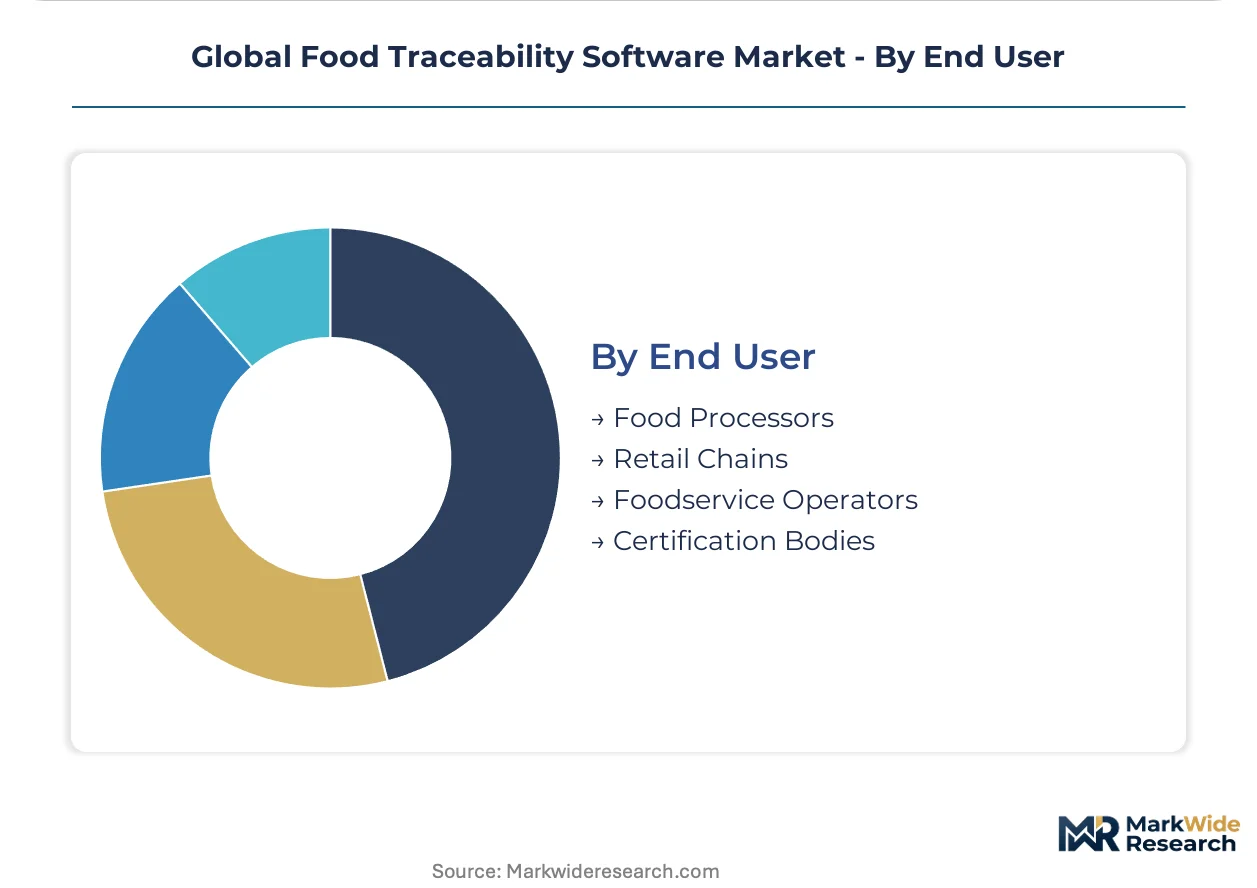
- Food Processors:Enterprise-grade platforms managing complex ingredient portfolios require deep ERP integration and multi-facility coordination. Large manufacturers pilot blockchain deployments at accelerated procurement cycles to satisfy compressed audit preparation demands.
- Retail Chains:Supermarket operators in Germany and France deploy farm-to-fork verification to satisfy consumer scrutiny of ingredient provenance and support premium private label positioning.
- Certification Bodies:Audit automation platforms with real-time data access replace periodic site inspections for organic and allergen-controlled categories.
- Foodservice Operators:Simplified tracking systems with mobile-first interfaces support distributed kitchen networks with limited technical staff.
Food Processors represent the largest installed base; Retail Chains expand fastest as transparency expectations harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software engineering capacity concentrates in the United States, Germany, and Japan, with each market exhibiting distinct procurement patterns tied to regulatory enforcement intensity and retail channel structure.
United States
FDA Food Safety Modernization Act traceability rules are mandating electronic sortable format records for designated high-risk foods. Seafood and fresh produce processors in California and Florida are reconfiguring data capture workflows to satisfy compressed response-time requirements for contamination events. Large food manufacturers in the Midwest pilot blockchain deployments at accelerated procurement cycles.
Germany
EU Green Deal labeling mandates under EFSA-administered General Food Law requirements are compelling food processors to deploy digital audit trails for organic and allergen-controlled categories. Supermarket retail chains in Bavaria and North Rhine-Westphalia demand farm-to-fork verification systems to satisfy consumer scrutiny of ingredient provenance. The country's food processing sector digitization exhibits pronounced shift toward recurring-revenue platform relationships.
Japan
METI supply chain digitization incentives are accelerating platform procurement by seafood exporters serving premium retail segments. Tokyo-based food manufacturers integrate traceability systems to satisfy compressed audit preparation demands from organic certification bodies. Kansai region processors leverage government-backed modernization programs to upgrade legacy ERP dependencies.
China
SAMR food safety standards are elevating software functionality minimums across export-oriented food manufacturers. Food processors in Yangtze River Delta and Pearl River Delta regions reconfigure compliance architecture to satisfy both domestic enforcement and import market requirements. Large agricultural conglomerates pilot enterprise-grade distributed ledger deployments for multi-tier network coverage.
Australia
Farm-level sensor networks in Queensland and New South Wales are creating upstream data capture opportunities for traceability platform vendors. Beef and wine exporters deploy comprehensive audit trail platforms to satisfy EU EFSA requirements and US FDA rules simultaneously. Sydney and Melbourne-based technology integrators specialize in cold chain logistics applications combining RFID encoding with GS1 standards.
Global Food Traceability Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower functional scope. The market exhibits consolidated structure at the enterprise tier alongside fragmented mid-market competition. Three archetypes dominate: ERP-embedded traceability modules, standalone cloud-native platforms, and hardware-software bundled offerings. Competitive moves concentrate on API ecosystem expansion and vertical partnership networks with certification bodies.
Within the enterprise platform tier, IBM Corporation, SAP SE, and Oracle Corporation occupy positions representing distinct architectural philosophies. IBM Corporation anchors blockchain-native approaches to multi-party verification. SAP SE exemplifies deep ERP integration strategies connecting farm-level data to retail analytics. Oracle Corporation sits within cloud-native deployment models unifying quality control workflows. Each represents a competing vision for how provenance data flows through complex ingredient portfolios.
| Leading Market Players |
|---|
| IBM Corporation |
| SAP SE |
| Oracle Corporation |
| Honeywell International Inc. |
| Zebra Technologies Corp. |
| FoodLogiQ LLC |
| Trimble Inc. |
| Siemens AG |
| C.H. Robinson Worldwide Inc. |
| Others |
Supply & Pricing Matrix
Cloud infrastructure concentration in the United States and Germany concentrates margin capture with SaaS platform vendors, while mid-sized food processors in France and Japan face escalating total cost of ownership as API integration complexity compounds subscription fees.
Pricing Analysis
EU Green Deal labeling mandates dictate the pricing tier structure across the food traceability software landscape. Three-tier pricing stratifies across enterprise-grade blockchain deployments, mid-market SaaS subscriptions, and baseline compliance modules for domestic operators. Price differentiation rests on certification grade alignment with FDA FSMA and EFSA audit requirements, plus geographic delivery cost differentials for on-premises installations. Cost compression in the mid-tier is intensifying because API-driven integration demands are unbundling functionality from legacy ERP suites. Domestic food processors lacking dedicated IT departments exhibit the highest price sensitivity, while multinational exporters serving premium retail segments in Germany and Japan demonstrate the lowest.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for hardware-dependent traceability deployments. Component sourcing concentrates in Taiwan for semiconductor inputs, Germany for industrial automation systems, and China for RFID encoding equipment. Raw material dependencies span gallium nitride chips for edge computing nodes, lithium-ion cells for cold chain sensors, and specialized polymers for food-grade RFID tags. Single-source vulnerability in blockchain protocol development talent constrains deployment velocity across export-oriented manufacturers. Distribution runs through systems integrators in North Rhine-Westphalia, California's Central Valley, and Tokyo's Shinagawa technology corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food traceability software functions as a service-attach opportunity where recurring subscription revenue and continuous API integration support are expanding faster than perpetual-license hardware sales.
For Market Incumbents: Entrench blockchain-native architectures through deep certification body partnerships that lock in audit automation workflows for organic and allergen-controlled categories. Expand API ecosystem coverage to capture integration complexity premiums as mid-sized processors abandon monolithic ERP suites. The threat of standalone cloud-native platforms unbundling traceability functionality demands defensive moves into modular SaaS tiering. For New Entrants and Emerging Players: Pursue farm-level sensor network integration in Brazil and Australia where upstream data capture remains underpenetrated by incumbent platforms. Target seafood exporters in Japan under METI digitization incentives as the most penetrable segment, leveraging low-code configuration requirements to bypass IT department bottlenecks. A vertical partnership go-to-market with cold chain logistics specialists accelerates reference customer acquisition. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed ERP-embedded traceability modules facing displacement by best-of-breed cloud solutions. The five-to-ten year viability window favors platforms with demonstrated GS1 standards implementation depth and distributed ledger protocol configuration expertise. Acquisition target archetypes include IoT-enabled agricultural monitoring specialists in Queensland and New South Wales. The signal to watch is compressed audit preparation timelines from organic certification bodies forcing real-time data availability investments.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Protocol Expansion | Immutable recordkeeping architectures displace paper-based chain-of-custody documentation across multi-tier supply networks. |
| API Ecosystem Development | Modular integration capabilities capture recurring revenue from mid-sized processors abandoning monolithic ERP suites. |
| Certification Body Partnership | Audit automation alliances with EU organic and allergen-control bodies secure platform lock-in for compliance workflows. |
| Farm-Level Sensor Integration | IoT-enabled agricultural monitoring in Brazil and Australia creates upstream data capture differentiation. |
| Cold Chain Logistics Specialization | RFID-GS1 convergence applications in perishable distribution command premium pricing from seafood exporters. |
Research Methodology
Initial hypotheses were tested against primary input from food safety compliance officers, supply chain directors at multinational processors, certification body audit managers, and SaaS procurement leads at mid-sized manufacturers, and refined through secondary validation spanning FDA FSMA guidance documents, EFSA regulatory filings, METI digitization program disclosures, and GS1 standards implementation case studies. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled span deployment architecture, solution layer depth, application workflow, and end-user type, with regional regulatory enforcement intensity as an additional cross-cutting variable. CAGRs were derived from growth driver elasticity analysis calibrated to procurement cycle acceleration patterns observed in Germany and Japan. Industry-specific forecast inputs include compressed audit preparation timeline requirements from organic certification bodies and cloud migration velocity among mid-tier food processors.
Sensitivities concentrate around regulatory divergence between FDA, EFSA, and SAMR standards fragmenting data format requirements, plus specialized talent scarcity in GS1 implementation and distributed ledger protocol configuration constraining deployment velocity. Forecasts reflect assumptions about enforcement timeline adherence and cloud adoption curves without guaranteed realization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Asia-Pacific Database Management Software Market
Software & Services
Global Auto Dealer Software Market
Software & Services
Global Gamification Software Market
Software & Services
Inventory Management Software Market
Software & Services
Photo Editor App Market
Software & Services
North America IT Services Market
Software & Services
ID Photo Software Market
Software & Services
App Building Software Market
Software & Services
Australia HR Payroll Software Market
Software & Services
Cemetery Software Market
Software & Services
Cemetery Management Software Market
Software & Services
Global Electronic Data Capture Software Market
Software & Services
Employee Wellness Software Market
Software & Services
Server Software Market
Software & Services
Time Series Databases Software Market
Software & Services
Automotive Digital Retailing Software Market