
 Global Automotive Software Market | 2026-2036
Global Automotive Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Software Market Analysis
Platform licensing revenue is reshaping competitive economics in automotive software as recurring subscription models displace one-time hardware sales. NVIDIA Corporation leverages its GPU-accelerated compute platforms to dominate autonomous driving development stacks. Robert Bosch GmbH anchors its position through deep vertical integration spanning ECU hardware to middleware layers. BlackBerry Limited specializes in cybersecurity-certified operating systems that tier-1 suppliers require for regulatory compliance.
Automotive software encompasses the programmable instructions, middleware stacks, and application layers that govern vehicle powertrain control, infotainment rendering, and advanced driver assistance computations, typically executing on multi-core SoCs with functional safety ratings up to ASIL-D per ISO 26262. Its primary purpose is to enable real-time vehicle functions while permitting remote feature upgrades throughout a vehicle's operational life. Embedded Software commands the largest revenue share due to its ubiquity across every electronic control unit, while Artificial Intelligence within the Technology dimension represents the fastest-expanding margin pool as neural network inference shifts from cloud to edge deployment. Cloud-Based deployment architectures are gaining traction among fleet operators seeking centralized vehicle telemetry management.
UN ECE WP.29 cybersecurity regulations, the EU AI Act, and ISO 26262 functional safety standards collectively mandate formal verification processes and traceable software supply chains for market access across Europe and aligned jurisdictions. The U.S. NHTSA and Japan's METI have issued complementary guidance on automated driving system validation that OEMs must address for type approval. Stakeholders must monitor how regulatory divergence between UNECE-aligned and non-aligned markets fragments certification requirements and influences R&D allocation across their development pipelines.
Market Dynamics
Over-the-air update platforms are collapsing the traditional vehicle lifecycle, enabling OEMs to monetize software features years after initial sale and shifting capital allocation from hardware tooling to cloud infrastructure.
Growth Catalysts
- UNECE WP.29 cybersecurity mandates:European regulators now require certified secure software architectures for type approval, forcing OEM procurement toward pre-validated middleware stacks.
- Edge AI inference migration:Neural network processing is shifting from cloud data centers to vehicle-mounted SoCs, expanding addressable silicon content per automobile.
- Germany's automotive cluster density:Stuttgart and Munich host concentrated tier-1 engineering centers that accelerate validation cycles for functional safety software.
Market Restraints
- Semiconductor supply concentration:Advanced node fabrication for automotive SoCs depends on Taiwan-based foundries, creating geographic vulnerability in processor availability.
- ISO 26262 certification timelines:ASIL-D functional safety validation requires 18-36 months of documented testing, compressing competitive windows for new entrants.
- Legacy ECU integration friction:Decade-old controller architectures resist software-defined reconfiguration, trapping OEMs in dual-stack maintenance costs.
Strategic Opportunities
- India's domestic EV production incentives:PLI scheme subsidies for electric vehicle manufacturing are attracting software localization investments from multinational suppliers.
- Subscription-based feature unlocking:Heated seats, autonomous parking, and battery preconditioning are migrating to recurring revenue models that extend customer lifetime value.
- Digital twin convergence with physical validation:Virtual ECU simulation is compressing hardware-in-the-loop testing cycles by 40-60% for powertrain calibration teams.
Industry Challenges
- Functional safety engineer scarcity:ASIL-certified software architects command premium compensation that strains R&D budgets at mid-tier suppliers.
- Multi-domain integration complexity:Consolidating infotainment, ADAS, and powertrain stacks onto unified compute platforms requires reconciling conflicting real-time requirements.
- Software supply chain traceability:SBOM documentation mandates under EU cybersecurity rules impose documentation burdens on open-source dependent development teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Software Market |
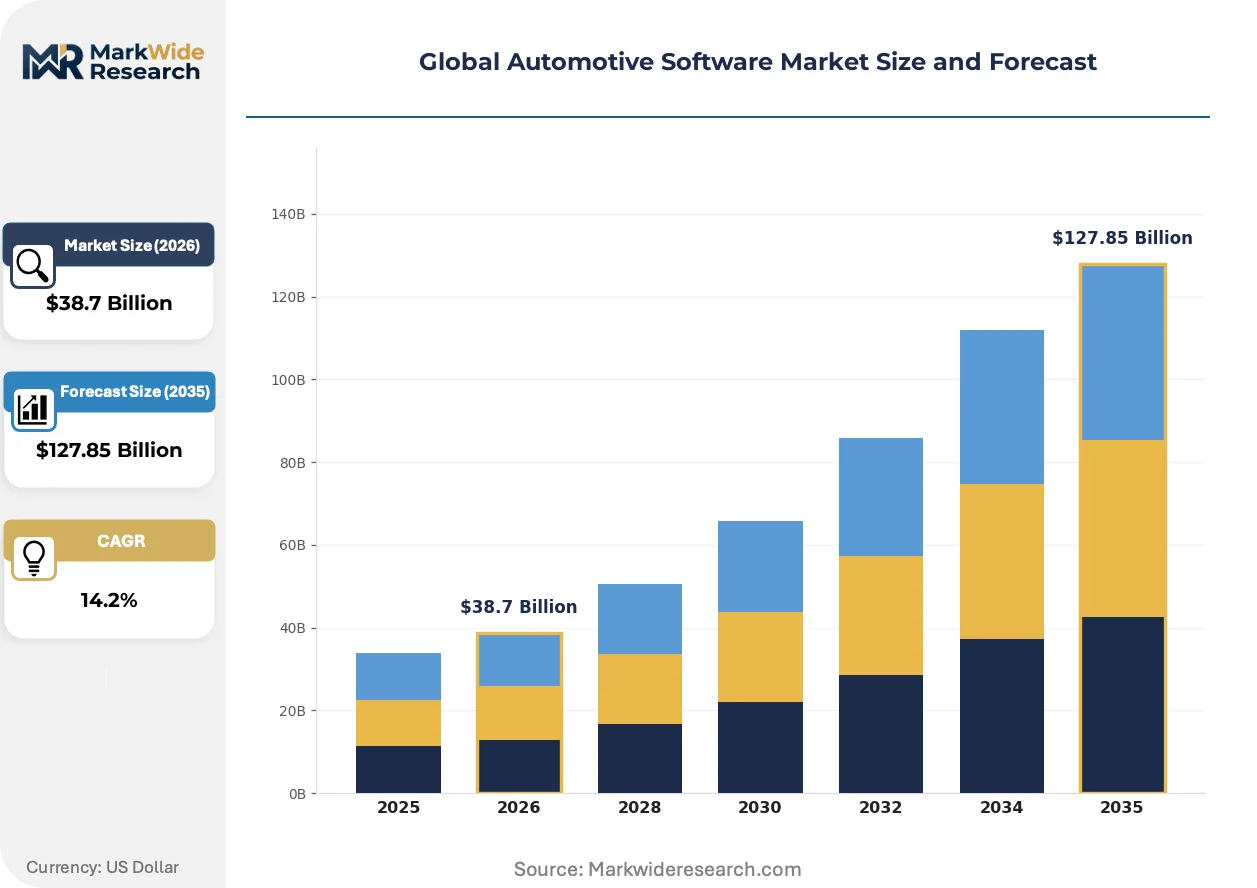
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded Software, Vehicle Management Systems, Driver Assistance Systems, Infotainment Systems Technology: Cloud Computing, Artificial Intelligence, Blockchain, Connectivity Solutions End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fleet Operators Deployment: On-Premise, Cloud-Based, Hybrid, Others |
| Companies Covered | Robert Bosch GmbH, NVIDIA Corporation, NXP Semiconductors, Continental AG, BlackBerry Limited, Elektrobit, Aptiv PLC, Renesas Electronics Corporation, DENSO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Software Market Emerging Trajectories
Automotive software architecture is abandoning federated ECU networks in favor of zonal compute consolidation, compressing hardware variety while expanding software complexity per domain controller.
Containerized middleware is collapsing the boundary between development and production environments, enabling Tesla and Rivian to push firmware updates weekly rather than annually. Tier-1 suppliers including Bosch and Continental are containerizing legacy stacks to match this velocity. The structural consequence is collapsing differentiation between premium and mass-market software release cadences.
The EU AI Act's risk classification system for automated driving functions is forcing OEMs to restructure algorithm documentation and human oversight protocols. Germany's KBA has aligned type approval procedures with these requirements, creating a compliance template that France and Italy are adopting. Level 3 highway automation systems face the steepest documentation burdens, with BMW and Mercedes-Benz restructuring validation teams to address conformity assessments.
Fleet operators are consolidating vendor relationships around vertically integrated platform providers, displacing the traditional multi-tier procurement of discrete ECU software modules. Amazon's Zoox and Waymo are negotiating directly with NVIDIA and Qualcomm for full-stack solutions, bypassing established tier-1 middleware suppliers. This concentration is most visible in California and Arizona, where autonomous fleet deployments are scaling fastest.
Global Automotive Software Market Segmentation
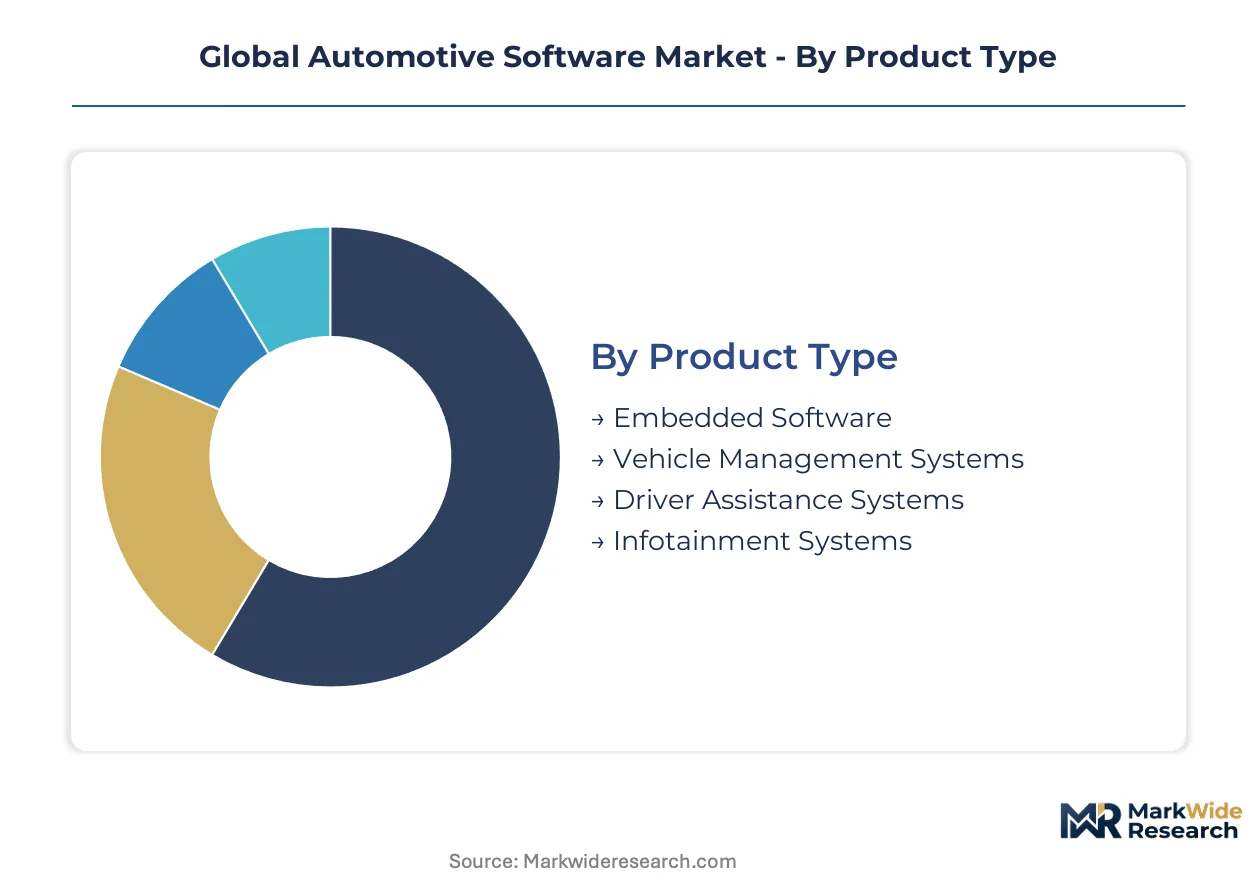
Automotive software segmentation reveals divergent margin structures across product architectures, with embedded stacks commanding hardware-linked pricing while cloud and AI layers shift toward recurring revenue models. Technology choices determine regulatory exposure, as ISO 26262 functional safety requirements apply selectively across deployment modes and end-user categories.
Product Type:
Mature powertrain control architectures coexist with emerging software-defined vehicle platforms, creating tiered investment requirements across the product spectrum.
- Embedded Software:Low-level firmware executing directly on microcontroller units governs engine timing, braking modulation, and transmission shifting with deterministic latency guarantees. Demand concentrates in Germany's Stuttgart engineering corridor, where Bosch and Continental procurement teams require ASIL-D certified stacks for powertrain ECUs under KBA type approval timelines.
- Vehicle Management Systems:Centralized domain controllers orchestrate cross-functional coordination between powertrain, chassis, and thermal subsystems via automotive Ethernet backbones. Fleet operators in Arizona and California negotiate directly with NVIDIA for zonal compute platforms that collapse legacy ECU proliferation.
- Driver Assistance Systems:Sensor fusion algorithms process camera, radar, and lidar inputs for lane-keeping and collision avoidance.
- Infotainment Systems:Android Automotive and proprietary Linux distributions render navigation, media, and third-party application interfaces.
Embedded Software handles the majority of throughput; Artificial Intelligence-enabled stacks are gaining share fastest as neural inference migrates to vehicle-mounted silicon.
Technology:
Cost tier stratification separates capital-intensive edge deployment from subscription-accessible cloud infrastructure, with mid-range hybrid configurations capturing fleet operator procurement.
- Cloud Computing:Centralized data centers process vehicle telemetry, map updates, and fleet optimization algorithms with elastic compute scaling. Amazon Web Services and Microsoft Azure capture procurement from mobility-as-a-service providers in Singapore and Dubai, where over-the-air update latency requirements remain permissive.
- Artificial Intelligence:Deep learning inference engines execute object detection, trajectory prediction, and natural language processing on GPU-accelerated silicon. Edge deployment in Japan's Nagoya automotive cluster accelerates under METI automated driving validation guidelines that mandate local processing for cybersecurity resilience.
- Blockchain:Distributed ledger architectures verify software supply chain integrity and secure over-the-air update authentication.
- Connectivity Solutions:Cellular V2X and 5G modules enable vehicle-to-infrastructure communication for cooperative maneuvering.
Cloud Computing anchors current infrastructure spending; Artificial Intelligence shows the steepest expansion trajectory as OEMs restructure R&D toward autonomous capability stacks.
End User:
Customer type determines procurement sophistication, with integrated OEMs demanding full-stack control while fragmented aftermarket channels prioritize interoperability certification.
- OEMs:Volkswagen, Toyota, and Ford maintain captive software engineering centers that develop proprietary middleware and application layers. Internal development in Detroit and Wolfsburg accelerates as UNECE WP.29 cybersecurity mandates require documented supply chain control that vertically integrated organizations can demonstrate more readily.
- Tier-1 Suppliers:Bosch, Denso, and Magna deliver pre-validated ECU software bundles to OEM assembly programs with guaranteed functional safety certification.
- Aftermarket Providers:Independent diagnostic tool vendors and infotainment upgrade specialists serve vehicle aging populations.
- Fleet Operators:Uber, Didi, and commercial logistics consortia procure unified telematics platforms that centralize predictive maintenance and route optimization.
OEMs direct the majority of R&D procurement; Fleet Operators are expanding most quickly as mobility-as-a-service models scale autonomous vehicle deployment.
Deployment:
Volume concentration favors on-premise ECU execution for safety-critical functions, while hybrid architectures emerge for infotainment and convenience features with relaxed latency requirements.
- On-Premise:Software executes locally on vehicle-mounted controllers without external network dependency, ensuring deterministic response for braking and steering functions. Regulatory mandates from the U.S. NHTSA and Germany's KBA effectively require on-premise execution for Level 3+ automated driving systems where connectivity interruption risks safety outcomes.
- Cloud-Based:Processing and storage reside in off-vehicle data centers accessed via cellular or satellite links.
- Hybrid:Critical functions execute locally while non-time-sensitive workloads offload to cloud infrastructure.
- Others:Edge computing nodes at cellular base stations and fog computing architectures for V2X coordination.
On-Premise deployment retains the dominant installed base; Hybrid configurations are climbing the fastest as zonal E/E architectures partition workload distribution dynamically.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advanced node semiconductor fabrication concentrates in Taiwan-based foundries, creating geographic chokepoints that automotive software vendors must navigate through distributed engineering centers and regional compliance investments.
United States
Detroit engineering corridors and Silicon Valley development hubs drive procurement of autonomous driving stacks and zonal compute platforms. NHTSA automated driving system validation guidelines mandate documented testing protocols for Level 3+ deployment. Arizona and California host concentrated autonomous fleet testing operations where Waymo and Amazon's Zoox negotiate directly with silicon vendors for full-stack solutions.
Germany
Stuttgart and Munich automotive clusters accelerate validation cycles for functional safety software under KBA type approval timelines. UNECE WP.29 cybersecurity regulations require certified secure software architectures for European market access. Bosch and Continental procurement teams dominate ECU middleware sourcing, anchoring tier-1 supplier consolidation across Baden-Württemberg and Bavaria.
Japan
Nagoya automotive engineering centers and Tokyo metropolitan R&D facilities concentrate edge AI inference development for automated driving systems. METI validation guidelines mandate local processing for cybersecurity resilience in connected vehicle deployments. Denso and Renesas anchor semiconductor and software integration across the Chubu and Kanto industrial belts.
China
Domestic EV OEM procurement of over-the-air update platforms accelerates software localization investments. MIIT cybersecurity standards and GB certification requirements structure compliance pathways for foreign suppliers. Yangtze River Delta and Pearl River Delta engineering centers concentrate tier-1 supplier joint ventures with local technology partners.
India
PLI scheme subsidies for electric vehicle manufacturing attract software engineering investments from multinational suppliers. BIS certification requirements and CDSCO regulatory frameworks structure quality assurance protocols for automotive components. Bangalore and Hyderabad technology corridors host expanding captive development centers serving European and North American OEM programs.
Global Automotive Software Market Vendor Landscape
Vertically integrated platform providers and specialized middleware developers split the market between full-stack control and component-level certification. The vendor base concentrates around three strategic archetypes: semiconductor-origin compute platform vendors, tier-1 automotive suppliers with captive software divisions, and cybersecurity-focused operating system specialists. Dominant competitive moves include strategic partnerships for zonal compute consolidation and technology licensing for regulatory pre-certification.
Within the vertically integrated tier, Robert Bosch GmbH and Continental AG exemplify European automotive supplier archetypes spanning ECU hardware through middleware layers. NVIDIA Corporation anchors the semiconductor-origin platform provider segment with GPU-accelerated autonomous driving development stacks. BlackBerry Limited occupies a specialized position in cybersecurity-certified operating systems required for UNECE WP.29 compliance.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| NVIDIA Corporation |
| NXP Semiconductors |
| Continental AG |
| BlackBerry Limited |
| Elektrobit |
| Aptiv PLC |
| Renesas Electronics Corporation |
| DENSO Corporation |
| Others |
Supply Flow & Price Mechanics
Taiwan's advanced-node foundry cluster in Hsinchu anchors silicon availability for automotive SoCs, translating wafer capacity tightness directly into tier-1 supplier pricing leverage. OEMs purchasing zonal compute platforms face compressed negotiation windows when TSMC allocation cycles tighten, forcing procurement teams toward long-term capacity reservations.
Pricing Analysis
UNECE WP.29 cybersecurity mandates dictate the pricing tier structure across automotive software procurement, separating ASIL-D certified stacks from uncertified alternatives. Pricing stratifies across premium, standard, and economy tiers based on functional safety grade and volume commitment scale. Cost compression in mid-tier embedded firmware is intensifying because tier-1 suppliers consolidate ECU sourcing around pre-validated middleware bundles. Fleet operators exhibit the highest price sensitivity due to per-vehicle software content multiplication across thousand-unit deployments, while luxury OEMs remain least sensitive when procuring autonomous driving stacks.
Supply Chain Analysis
Export controls on advanced semiconductor manufacturing equipment restrict technology flows into Chinese fabs, concentrating automotive-grade silicon sourcing across Taiwan, South Korea, and the United States. Supply chains draw from EUV lithography systems, automotive-grade substrate materials, and cobalt-bearing battery management components. Single-source vulnerability concentrates in Taiwan-based 3nm and 5nm capacity for ADAS processors. Distribution runs through tier-1 supplier consolidation programs that bundle software licensing with ECU hardware procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation around vertically integrated platform providers has shifted procurement leverage toward buyers capable of negotiating full-stack solutions directly with silicon vendors. This concentration fragments the traditional multi-tier supplier hierarchy.
For Market Incumbents: Insulate certification-backed revenue streams by deepening ASIL-D validation investments ahead of EU AI Act enforcement timelines. Captive middleware development in Stuttgart and Nagoya engineering centers defends against direct OEM-silicon vendor negotiations. Priority lever: software supply chain traceability documentation that satisfies emerging SBOM mandates. For New Entrants and Emerging Players: India's PLI-subsidized EV manufacturing corridors represent the most penetrable entry point for software localization investments serving European and North American OEM programs. Aftermarket diagnostic tool vendors in aging vehicle populations offer secondary white-space with lower certification barriers. Go-to-market angle: containerized middleware solutions matching Tesla and Rivian release velocities without legacy ECU integration friction. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cybersecurity-certified operating system specialists with UNECE WP.29 pre-certification assets. Long-term viability hinges on regulatory compliance moats widening as functional safety engineer scarcity intensifies. Signal to watch: tier-1 supplier divestiture of non-core software divisions under margin pressure from direct OEM-silicon negotiations.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | NVIDIA's GPU-accelerated stacks enable zonal compute consolidation that collapses legacy ECU proliferation. |
| Platform Standardization | Android Automotive and proprietary Linux distributions reduce infotainment fragmentation across OEM portfolios. |
| Battery Supply Agreement | Integrated battery management software procurement secures thermal control algorithms for preconditioning monetization. |
| Geographic Manufacturing Footprint | Bangalore and Hyderabad captive centers serve European OEM programs under India's PLI scheme incentives. |
| Charging Infrastructure Partnership | Vehicle-to-grid software integration creates recurring revenue from bidirectional power management services. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, vehicle production databases, and IHS Markit registration data across tier-1 supplier procurement, OEM platform engineering, and aftermarket distribution channels. Conversations with Bosch and Continental procurement leads, NVIDIA platform engineers, and BlackBerry cybersecurity specialists informed demand-side validation. Bottom-up unit economics triangulate against top-down market sizing from regulatory filing analysis.
Forecast inputs span propulsion architecture, content per vehicle, and regional production cluster segmentation across the projection horizon. CAGRs derive from modeled adoption curves for autonomous driving software stacks and over-the-air update platform penetration. Industry-specific variables include UNECE WP.29 compliance timelines, METI validation guideline evolution, and semiconductor foundry capacity allocation cycles.
Practitioners should monitor regulatory divergence between UNECE-aligned and non-aligned markets for early signals of certification requirement fragmentation. Forecasts reflect documented assumptions on autonomous fleet deployment scaling and functional safety engineer availability. Material shifts in Taiwan-based foundry capacity allocation or EU AI Act enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Professional Service Automation (PSA) Software Market
Software & Services
Electronic Data Interchange (EDI) Software Market
Software & Services
Global Time and Attendance Management Software Market
Software & Services
Global Client Portal Software Market
Software & Services
Global Lead Capture Software Market
Software & Services
Global Mindfulness Meditation Apps Market
Software & Services
Appointment Scheduling Software Market
Software & Services
Game Development Software Market
Software & Services
Library Management Software Market
Software & Services
Content Creation Software Market
Software & Services
Building Information Modeling (BIM) Extraction Software Market
Software & Services
Global Employee Engagement and Feedback Software Market
Software & Services
Telecom Billing Software Market
Software & Services
United States Human Resource (HR) Technology Market
Software & Services
Independent Software Vendors (Isvs) Market
Software & Services
Online Lottery Software Market