
 Global Call Center Software Market | 2026-2036
Global Call Center Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Call Center Software Market Foresight
Subscription-based financing and usage-based SaaS licensing are reshaping competitive entry barriers in call center software, allowing mid-market buyers to access enterprise-grade capabilities without capital expenditure. Five9 leverages cloud-native architecture to sustain recurring revenue growth across North American financial services deployments. Zendesk anchors its position through deep integration with e-commerce support workflows. Avaya competes in hybrid deployment environments where on-premises legacy infrastructure requires gradual cloud migration paths.
Call center software encompasses integrated platforms that manage inbound and outbound voice, digital messaging, and workforce scheduling through automatic call distributor algorithms, interactive voice response trees, and real-time analytics dashboards. These systems route customer interactions to appropriate agents based on skills-based logic, queue depth, and sentiment analysis while recording performance metrics for operational optimization. Cloud-based deployment leads solution uptake as telecom providers and utilities replace aging hardware with elastic capacity models. Analytics software represents the fastest-growing solution type as e-commerce platforms demand predictive churn scoring and conversation intelligence. Workforce management tools remain mature with stable margins concentrated among large financial services firms with complex shift-planning requirements.
The EU AI Act imposes risk-classification requirements on automated decision systems in customer interactions, while the FCC enforces telemarketing consent frameworks under TCPA in the United States. India's TRAI mandates caller identification and spam-mitigation protocols that shape outbound dialing software specifications. ISO standards for information security management constrain vendor qualification for utilities and healthcare-adjacent help desk applications. Stakeholders must monitor how emerging algorithmic accountability rules in the European Union and evolving data-localization requirements across Asia-Pacific jurisdictions affect cross-border cloud hosting architectures and vendor selection criteria.
Market Dynamics
Cloud-native architecture is compressing deployment timelines and forcing legacy on-premises vendors to accelerate SaaS transitions or cede mid-market share to elastic-capacity competitors.
Growth Catalysts
- EU AI Act compliance mandates:Risk-classification requirements for automated decision systems are compelling financial services firms to upgrade routing algorithms and audit trails, creating replacement demand across European banking contact centers.
- Skills-based routing algorithms:Machine learning models matching caller intent to agent expertise are reducing average handle times and improving first-contact resolution rates in telecom and utilities sectors.
- India's captive center expansion:Domestic IT services providers building proprietary technology stacks for insourced operations are driving localized procurement of workforce management and analytics modules.
Market Restraints
- Data localization mandates:Asia-Pacific jurisdictions requiring in-country cloud hosting are fragmenting vendor architectures and inflating operational complexity for cross-border service delivery.
- Legacy telephony infrastructure:Hybrid deployment environments in North American financial services prolong migration timelines and constrain full-feature adoption of cloud-native platforms.
- Specialized AI talent scarcity:Shortage of conversation intelligence engineers and natural language processing specialists is throttling rollout velocity for predictive analytics deployments.
Strategic Opportunities
- Conversational AI convergence:Integration of large language models with real-time sentiment analysis is opening white space for proactive churn intervention in subscription-based e-commerce support.
- Brazil's outbound dialing modernization:Telemarketing consent framework evolution under ANVISA-aligned consumer protection rules is creating demand for compliant automated dialing and recording systems.
- API-first distribution channels:Embedded finance and embedded insurance models are requiring white-label contact center capabilities accessible through developer marketplaces rather than traditional enterprise sales.
Industry Challenges
- ISO 27001 certification timelines:Healthcare-adjacent help desk applications face extended vendor qualification periods that delay contract execution and compress implementation windows.
- Workforce scheduling algorithm integration:Complex shift-planning requirements at large financial services firms demand bespoke configuration of workforce management tools, inflating professional services dependency.
- Real-time analytics latency:Sub-second conversation intelligence processing requires edge computing investments that strain capex budgets at mid-market buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Call Center Software Market |
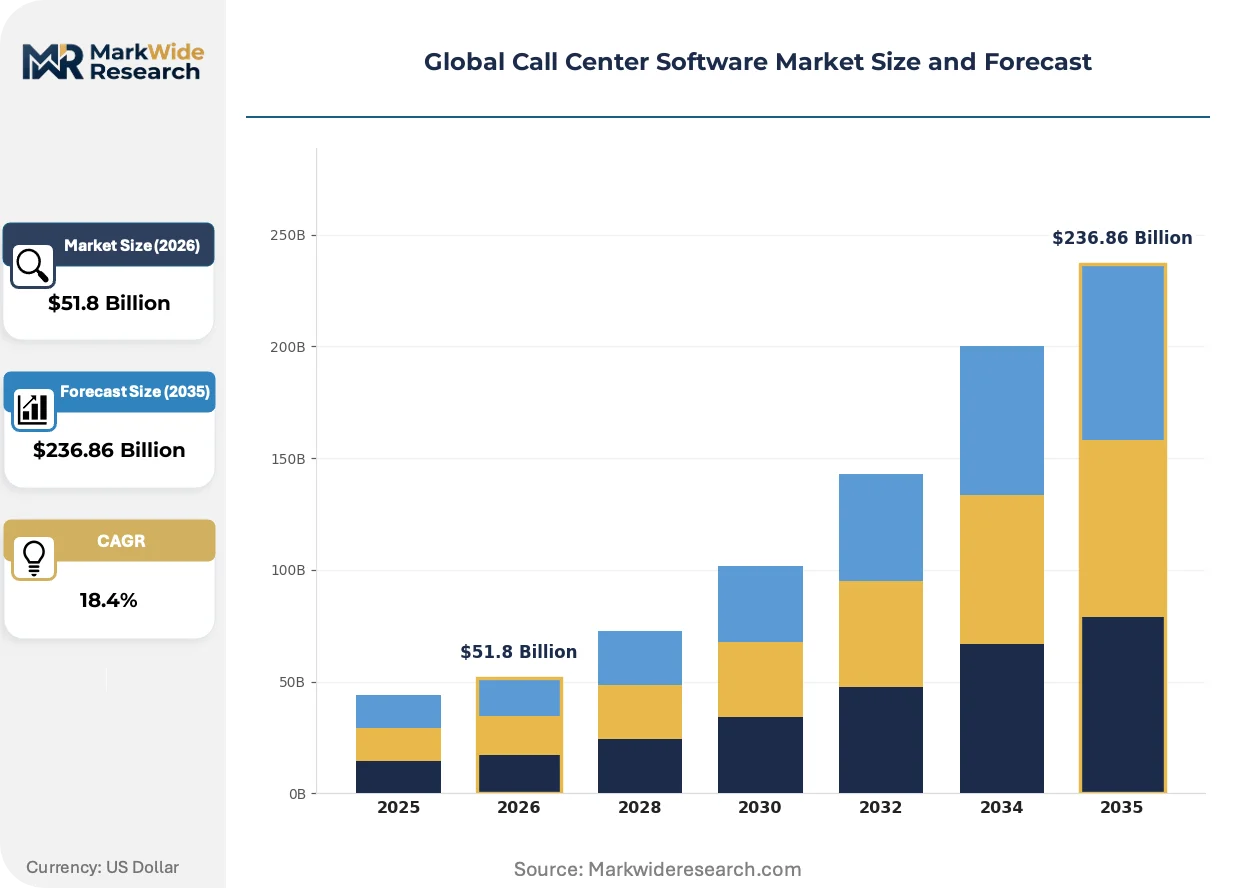
| Market Size in 2026 | $51.8 Billion |
| Market Size in 2035 | $236.86 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Hosted, Virtual Solution Type: Automatic Call Distributor, Interactive Voice Response, Workforce Management, Customer Relationship Management, Analytics Software Application: Customer Support, Telemarketing, Help Desk, Technical Assistance, Order Processing End User: Telecom Providers, E-Commerce Platforms, Financial Services Firms, Travel Agencies, Utilities |
| Companies Covered | Salesforce Service Cloud, Nextiva, Udesk, CloudTalk, Talkdesk, Avaya, Five9, RingCentral, Zendesk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Call Center Software Market Shifts & Advancements
Agent-assist copilots and generative response suggestions are redefining productivity benchmarks while regulatory pressure on algorithmic transparency accelerates investment in explainable routing logic.
Large language model-powered agent copilots are surfacing contextual knowledge articles and draft responses during live customer interactions. E-commerce platforms and digital-native retailers are deploying these tools most aggressively, with pilot programs expanding to full queue coverage within six-month windows. The technology is rendering obsolete static knowledge bases that required manual search and copy-paste workflows.
The EU AI Act's risk-tier classification system is imposing documentation and human-oversight requirements on automated call routing decisions. Vendors must now maintain algorithmic impact assessments and audit trails for high-risk deployments in credit and insurance contexts. European banking contact centers are responding by demanding vendor-provided compliance tooling and pre-certified model architectures.
Consumption-based licensing is displacing seat-based subscriptions as the dominant commercial model. Mid-market buyers in telecommunications and utilities are negotiating metered pricing tied to actual interaction volumes rather than licensed agent counts. This shift is most pronounced in Germany and the United Kingdom, where procurement teams prioritize operational expenditure flexibility over capital commitment.
Global Call Center Software Market Segmentation
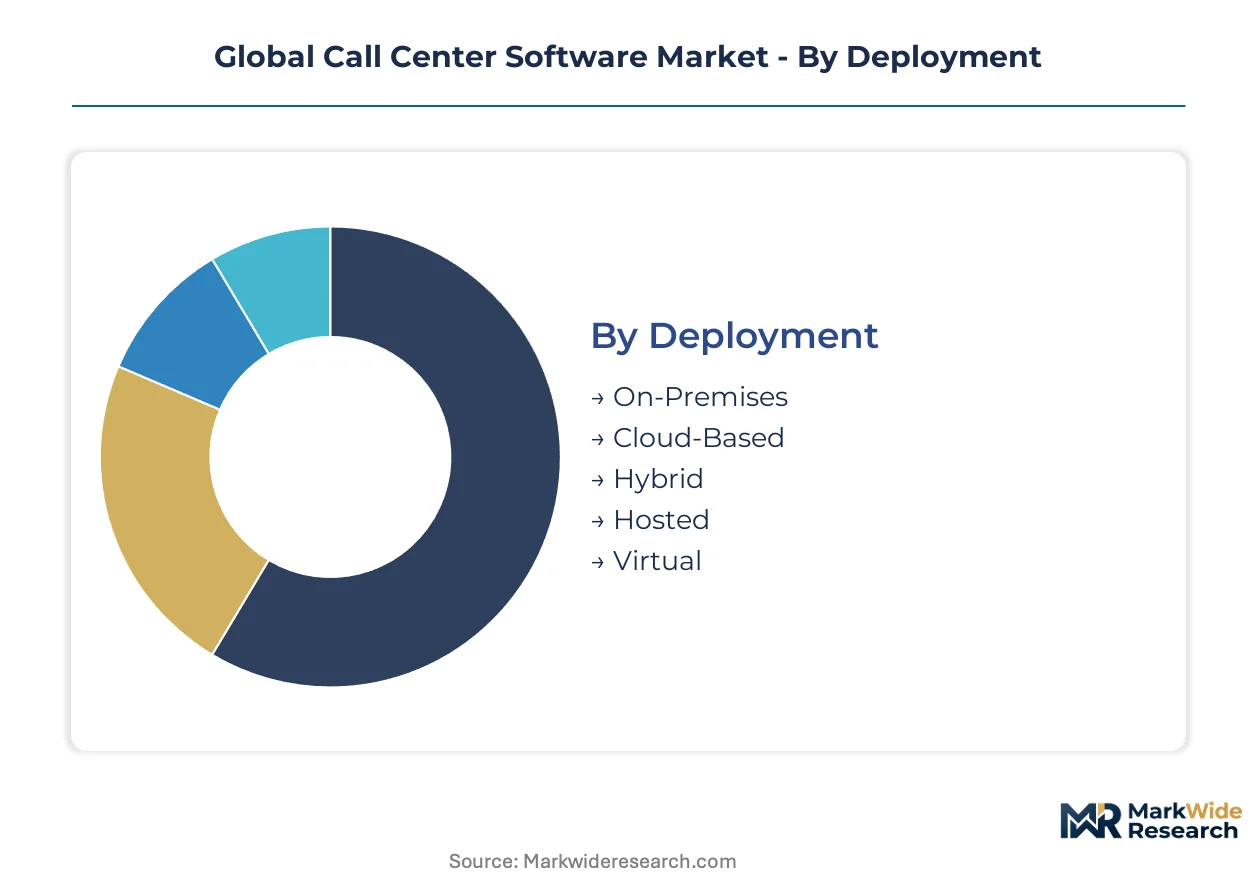
Call center software segmentation reveals how deployment architectures, solution modules, and industry-specific workflows create distinct competitive arenas with divergent margin profiles and vendor qualification requirements.
Deployment:
Maturity varies sharply across deployment modes, with legacy on-premises installations coexisting alongside nascent serverless architectures.
- Cloud-Based:Elastic capacity models provision compute resources on demand through multi-tenant SaaS platforms. Telecom providers in Germany and utilities across the United Kingdom are replacing fixed infrastructure with consumption-metered subscriptions that align costs to interaction volatility.
- Hybrid:Split architectures maintain sensitive voice recording on local servers while routing logic and analytics execute in cloud environments. Financial services firms in Switzerland and the United States prolong migration timelines to preserve compliance with data residency requirements.
- On-Premises:Dedicated hardware installations with perpetual licensing remain entrenched in regulated healthcare-adjacent help desks requiring air-gapped security.
- Hosted:Single-tenant managed services delivered from vendor-operated data centers serve mid-market buyers seeking administrative offload without multi-tenant risk exposure.
- Virtual:Containerized deployments using desktop virtualization protocols enable remote agent access to centralized systems without endpoint software installation.
Cloud-Based retains volume leadership; Virtual holds the steepest expansion curve.
Solution Type:
Application sophistication determines pricing tier boundaries, with basic routing modules commoditizing while predictive intelligence commands premium positioning.
- Analytics Software:Conversation intelligence platforms transcribe voice interactions and apply natural language processing to extract sentiment scores, topic clustering, and churn risk signals. E-commerce platforms in Japan and subscription retailers in South Korea deploy predictive scoring to intervene before cancellation requests.
- Automatic Call Distributor:Skills-based routing engines match caller intent to agent expertise using real-time queue depth and proficiency matrices. Banking contact centers in France and insurance operations in Italy demand algorithmic audit trails to satisfy EU AI Act documentation requirements.
- Workforce Management:Shift-planning and adherence-tracking systems optimize staffing levels against forecasted interaction volumes. Large financial services firms in Canada and Australia require bespoke configuration for complex multi-skill scheduling.
- Interactive Voice Response:Self-service menu trees and speech recognition front-ends deflect routine inquiries from live agents.
- Customer Relationship Management:Case management and interaction history repositories integrate voice, chat, and email channels into unified agent desktops.
Automatic Call Distributor anchors installed base; Analytics Software is climbing the fastest.
Application:
Workflow complexity separates high-velocity transactional queues from relationship-intensive advisory interactions with divergent technology requirements.
- Customer Support:Post-purchase inquiry handling across voice, chat, and social channels requires omnichannel routing and unified agent desktops. Digital-native retailers in Brazil and marketplace operators in India prioritize first-contact resolution metrics over average handle time.
- Telemarketing:Outbound dialing campaigns with predictive algorithms and compliance recording face tightening consent frameworks. Contact centers in the United States navigate FCC TCPA restrictions while Brazilian operations adapt to ANVISA-aligned consumer protection rules.
- Help Desk:Internal IT service delivery and employee support functions emphasize knowledge base integration and ticket escalation workflows.
- Technical Assistance:Product troubleshooting and warranty support demands remote diagnostic tooling and parts ordering integration.
- Order Processing:Transaction completion and payment verification queues prioritize PCI-DSS compliance and fraud detection overlays.
Customer Support dominates transaction volumes; Telemarketing faces the steepest regulatory headwinds.
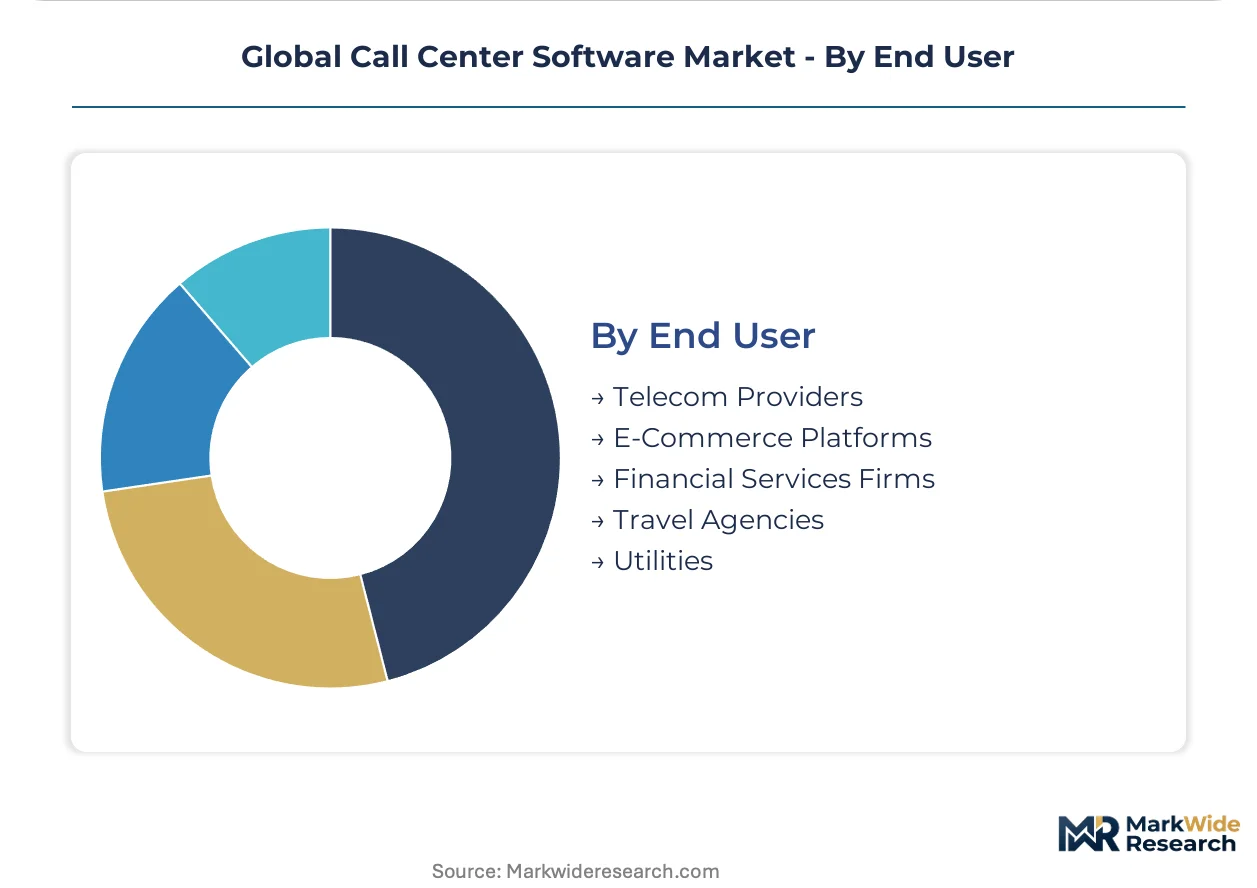
End User:
Vertical-specific compliance requirements and interaction patterns fragment vendor go-to-market strategies across buyer categories.
- Financial Services Firms:Banking, insurance, and wealth management contact centers demand ISO 27001 certification, algorithmic transparency documentation, and encrypted recording storage. Institutions in the Netherlands and Singapore require vendor-provided compliance tooling for EU AI Act and MAS technology risk management guidelines.
- E-Commerce Platforms:Peak-season elasticity and subscription churn management drive cloud-native procurement with API-first integration requirements. Marketplace operators in the United Kingdom and direct-to-consumer brands in the United States embed contact center capabilities through developer marketplaces.
- Telecom Providers:High-volume subscriber service and network fault reporting necessitate resilient infrastructure with geographic redundancy.
- Utilities:Outage notification and billing inquiry handling prioritize interactive voice response deflection and workforce scheduling for emergency mobilization.
- Travel Agencies:Booking modification and disruption management workflows require global distribution system integration and multi-currency payment processing.
Telecom Providers maintain the largest seat counts; E-Commerce Platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Call center software trade flows reflect asymmetric demand patterns, with the United States and Germany running substantial technology import surpluses while India and the Philippines export contact center services that drive domestic platform procurement.
United States
Financial services modernization and FCC TCPA compliance upgrades fuel replacement cycles across banking and insurance contact centers. The FCC enforces telemarketing consent frameworks that reshape outbound dialing specifications. New York and Chicago house dense clusters of enterprise buyers negotiating consumption-based SaaS contracts with elastic capacity terms.
Germany
Telecom provider infrastructure refresh and utility customer service digitization drive cloud migration at Deutsche Telekom and municipal energy cooperatives. The EU AI Act imposes risk-classification documentation requirements on automated routing systems deployed in Frankfurt and Munich banking hubs. Berlin hosts a growing cadre of workforce management specialists serving DAX-listed financial institutions.
India
Domestic IT services providers expanding captive contact center operations create localized demand for proprietary technology stacks. TRAI mandates caller identification and spam-mitigation protocols that constrain outbound dialing software architecture. Bangalore and Hyderabad concentrate engineering talent developing conversation intelligence modules for insourced banking and e-commerce operations.
United Kingdom
E-commerce platform subscription churn management and API-first embedded finance integration accelerate procurement of predictive analytics modules. GDPR and emerging algorithmic accountability rules constrain cross-border data routing for London-based fintech contact centers. Manchester and Edinburgh host mid-market buyers negotiating metered pricing tied to interaction volumes rather than seat counts.
Brazil
Telemarketing consent framework evolution under ANVISA-aligned consumer protection rules modernizes outbound dialing and recording compliance. São Paulo concentrates demand from retail banking and subscription service providers replacing legacy hardware with cloud-native platforms. Rio de Janeiro utilities deploy interactive voice response deflection for outage notification queues.
Global Call Center Software Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct strategic tiers: cloud-native specialists with consumption-based pricing, legacy vendors managing hybrid migration paths, and embedded platform providers integrating contact center capabilities through API distribution. Archetypes include elastic-capacity SaaS pure-plays, on-premises incumbents with gradual cloud transitions, and developer-marketplace enablers serving embedded finance use cases. Dominant competitive moves encompass strategic partnerships with telecom carriers and portfolio diversification into conversational AI modules.
Within the cloud-native tier, Five9 and Talkdesk exemplify elastic-capacity specialists targeting North American financial services with recurring revenue architectures. Avaya occupies a position among legacy vendors navigating hybrid deployment environments where gradual cloud migration preserves compliance with data residency requirements. Zendesk anchors the embedded integration segment, with its platform representing the archetype of deep e-commerce workflow penetration through developer marketplace distribution.
| Leading Market Players |
|---|
| Salesforce Service Cloud |
| Nextiva |
| Udesk |
| CloudTalk |
| Talkdesk |
| Avaya |
| Five9 |
| RingCentral |
| Zendesk |
| Others |
Supply & Pricing Matrix
Trans-Pacific fiber-optic cable capacity costs shape competitive positioning for cloud-native vendors serving North American financial services buyers, concentrating pricing power among hyperscaler-backed platforms while forcing mid-tier providers toward consumption-metered SaaS tiers to defend margin positions against elastic-capacity competitors.
Pricing Analysis
Financial services firms anchor pricing stratification across three consumption tiers: enterprise-grade subscriptions with dedicated infrastructure, standard multi-tenant SaaS with API integration bundles, and economy self-service tiers with limited customization. Price differentiation rests on ISO 27001 certification level and geographic data residency guarantees, with EU AI Act compliance tooling commanding substantial premiums. Pricing pressure stems from seat-based licensing displacement by metered interaction-volume models, particularly among telecommunications buyers in Germany and utilities across the United Kingdom. Mid-market buyers in Brazil and India exhibit acute price sensitivity, while Swiss banking contact centers prioritize compliance over cost.
Supply Chain Analysis
Upstream compute infrastructure feeds from concentrated hyperscaler facilities in the United States, Ireland, and Singapore, with specialized GPU clusters for conversation intelligence training anchored in Taiwan and South Korea. Raw material dependencies span silicon wafers for edge computing hardware, rare earth elements for data center power management systems, and lithium-ion storage for backup facilities. Single-source vulnerability concentrates in Taiwan-based semiconductor foundries serving real-time analytics processing requirements. Distribution runs through direct enterprise sales teams for large financial services contracts, supplemented by developer marketplaces and telecom carrier partnerships for embedded finance use cases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise software capital expenditure cycles are recovering from cyclical compression, with cloud migration backlogs and EU AI Act compliance deadlines creating replacement demand across European banking contact centers.
For Market Incumbents: Entrench position through backward integration into proprietary large language model training infrastructure, reducing dependency on hyperscaler API pricing volatility. Accelerate ISO 27001 pre-certification programs for healthcare-adjacent help desk segments where extended vendor qualification timelines threaten contract execution velocity. Defend against API-first challengers by embedding contact center capabilities directly into core banking and insurance platforms through white-label distribution partnerships.
For New Entrants and Emerging Players: Build out conversational AI copilot modules targeting e-commerce subscription churn management, where pilot-to-production timelines compress within six-month windows and incumbent knowledge base architectures face technical obsolescence. Prioritize Brazil's outbound dialing modernization wave under ANVISA-aligned consumer protection rules, where legacy hardware replacement creates immediate procurement opportunities. Pursue developer-marketplace distribution over traditional enterprise sales to reduce customer acquisition costs and accelerate embedded finance integration timelines.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cloud-native specialists with consumption-based recurring revenue architectures over legacy vendors managing protracted hybrid migration paths. Long-term viability hinges on conversation intelligence differentiation and EU AI Act compliance tooling integration rather than basic routing commoditization. Acquisition target archetypes include workforce management boutiques with bespoke configuration capabilities for large financial services firms and edge computing specialists addressing real-time analytics latency constraints. Monitor hyperscaler capex disclosure patterns as the primary inflection indicator for infrastructure cost compression timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified agent desktops combining voice, chat, and CRM reduce context-switching friction for e-commerce support teams. |
| Strategic Partnership | Telecom carrier alliances embed contact center capabilities into subscriber service bundles across Deutsche Telekom and BT Group. |
| Acquisition of Specialist Firm | Conversation intelligence boutiques bring natural language processing talent scarce in generalist vendor engineering pools. |
| Geographic Expansion | India captive center buildouts by domestic IT services providers localize procurement for insourced banking operations. |
| Product Launch | EU AI Act-compliant routing algorithms with pre-certified audit trails accelerate European financial services sales cycles. |
Research Methodology
Initial hypotheses were tested against primary input from contact center operations directors, CIOs at financial services institutions, telecom network planning officers, and cloud procurement leads, and refined through secondary validation across SEC 10-K filings, hyperscaler capex disclosures, EU regulatory impact assessments, and TRAI technical standards documentation. Bottom-up segment sizing triangulated against top-down market boundary analysis from trade flow data and vendor revenue attribution.
Demand-supply balance dynamics across deployment models, solution types, and vertical applications structured the analytical framework over the projection horizon. Segmentation dimensions modeled encompass cloud-native versus hybrid versus on-premises architectures, organization size tiers, integration complexity levels, and regional regulatory adoption patterns. CAGRs derived from interaction volume elasticity coefficients, seat-count migration trajectories, and pricing model transition rates, with conversation intelligence module attach rates and EU AI Act compliance investment schedules serving as key forecast inputs.
Stress conditions across data localization mandate enforcement intensity, hyperscaler infrastructure cost inflation, and specialized AI talent availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding cloud migration velocity and regulatory implementation timelines. Cross-checking against vendor earnings call commentary and enterprise software procurement survey benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Configuration Management (CM) Tools Market
Software & Services
Digital Illustration App Market
Software & Services
Sales Compensation Software Market
Software & Services
Saas for Spa Management Market
Software & Services
Legal Software Market
Software & Services
Telecom Billing Software Market
Software & Services
Enterprise Resource Planning Market
Software & Services
Disk Space Analyzer Software Market
Software & Services
3PL Software Market
Software & Services
Europe Application Modernization Services Market
Software & Services
Vertical Software Market
Software & Services
Africa Financial Services Software Market
Software & Services
POS Software Market
Software & Services
Product Optimization Software Market
Software & Services
Global Data Entry Software Market
Software & Services
Global Employee Engagement Software Market