
 Instant Messaging Software Market | 2026-2036
Instant Messaging Software Market Size, Share, and Industry Trends Forecast 2026-2036
Instant Messaging Software Market Outlook
Platform unbundling is decoupling core messaging from adjacent collaboration tools, forcing buyers to assemble best-of-breed stacks rather than accept monolithic suites. Microsoft Teams sustains deep integration with productivity software to anchor enterprise retention. Slack differentiates through channel-based workflow automation that appeals to technology and media verticals. Discord operates at the consumer-enterprise boundary, leveraging its gaming roots to capture community-driven business use cases.
Instant messaging software comprises real-time text, voice, and video communication applications delivered via internet protocol networks with end-to-end encryption, message persistence, and API extensibility as core functional parameters. These systems serve commercial and institutional users by replacing asynchronous communication with synchronous, searchable interaction records. Cloud-based deployment leads in scalability and update velocity, while on-premises solutions retain dominance in financial services and defense sectors where data residency governs procurement. Enterprise user types command the deepest integration budgets, though educational institutions represent an emerging segment as hybrid learning normalizes persistent digital campuses.
The Federal Risk and Authorization Management Program in the United States restricts federal procurement to audited platforms, reshaping vendor certification roadmaps. Europe's GDPR and the Digital Markets Act impose interoperability and data portability obligations that erode platform lock-in advantages. China's Personal Information Protection Law mandates localized data storage for domestic messaging traffic, fragmenting global architecture strategies. Stakeholders must weigh compliance investment against market access trade-offs as regulatory fragmentation intensifies.
Market Dynamics
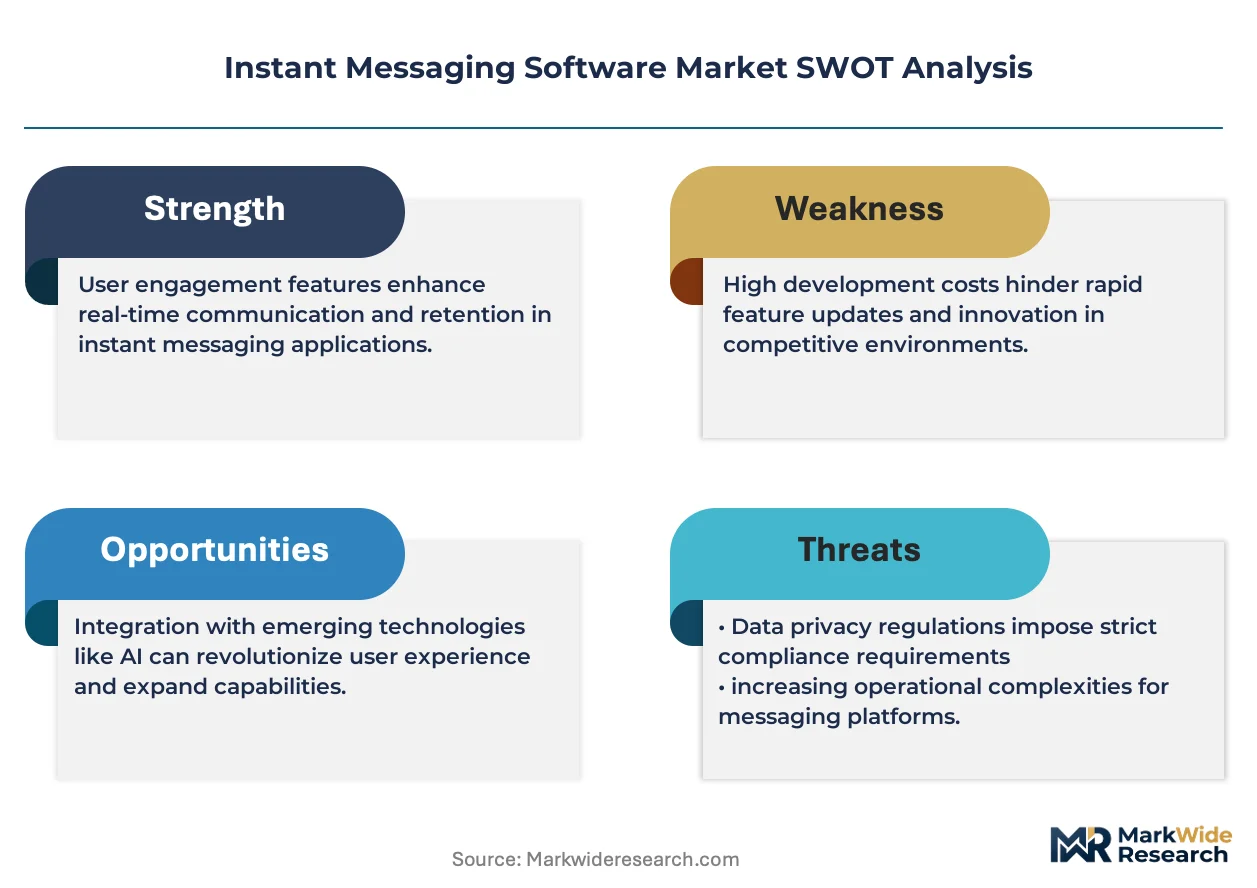
Platform unbundling is fragmenting enterprise software procurement as organizations reject monolithic suites in favor of modular, API-first communication stacks that interoperate across vendor boundaries.
Growth Catalysts
- FedRAMP Authorization:Federal agencies in the United States mandate audited communication platforms, creating a certification moat that funnels procurement toward compliant vendors and accelerates enterprise sales cycles.
- Channel-Based Workflow Automation:Technology and media verticals demand persistent, searchable conversation threads integrated with CI/CD pipelines and incident response systems.
- Hybrid Learning Normalization:Educational institutions across North America and Europe are deploying persistent digital campuses that require real-time messaging infrastructure for synchronous and asynchronous instruction.
Market Restraints
- Data Residency Compliance Costs:China's Personal Information Protection Law and Europe's GDPR impose localized storage mandates that fragment global architecture strategies and inflate infrastructure expenditure.
- Encryption Export Controls:Cross-border message routing faces technical restrictions from national security frameworks that limit end-to-end encryption deployment in regulated jurisdictions.
- Legacy Email System Entrenchment:Financial services and defense sectors maintain asynchronous communication protocols due to archival compliance requirements and institutional inertia.
Strategic Opportunities
- Community-Driven Business Use Cases:Discord's gaming infrastructure is being repurposed for creator economies and fan engagement platforms that blend consumer virality with B2B monetization.
- API-First Ecosystem Expansion:Workflow automation vendors are embedding messaging capabilities into vertical SaaS applications for healthcare, legal, and construction project management.
- India's Digital Public Infrastructure:The country's unified payments interface and stack architecture create tailwinds for messaging platforms that integrate with government identity and payment rails.
Industry Challenges
- Interoperability Standardization Delays:Europe's Digital Markets Act mandates message portability, but technical implementation timelines remain undefined, forcing vendors to architect speculative compliance pathways.
- End-to-End Encryption Talent Scarcity:Cryptographic engineering expertise concentrates at a handful of specialized firms, constraining secure messaging product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Instant Messaging Software Market |
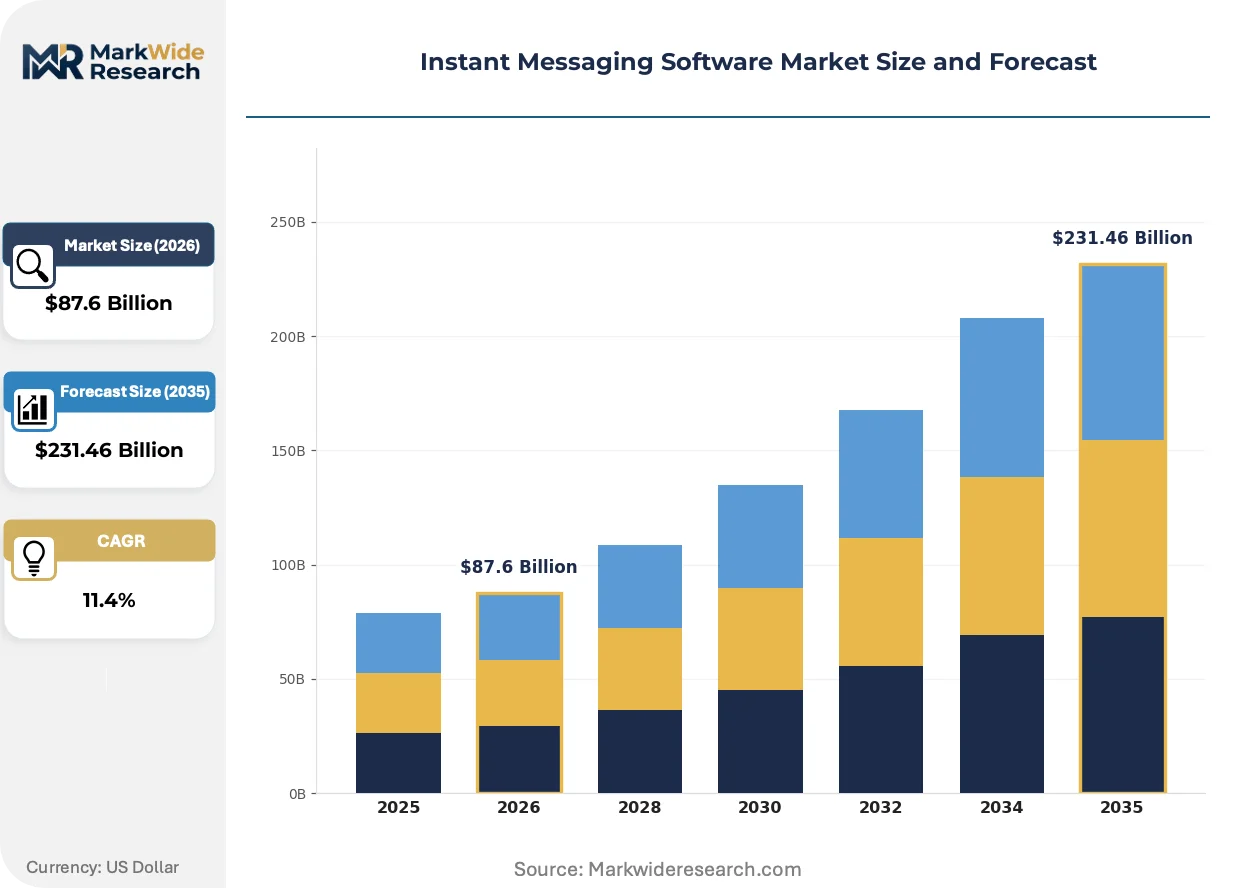
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $231.46 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS User Type: Individuals, Enterprises, Government, Educational Institutions Feature Set: Text Chat, Voice Calling, Video Conferencing, File Sharing Integration: API, Third-Party Tools, CRM, Social Media |
| Companies Covered | WhatsApp, Telegram, Facebook Messenger, WeChat, Microsoft Teams, Slack, Discord, Twilio MessagingX, Zendesk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Instant Messaging Software Market Strategic Shifts
Artificial intelligence is embedding itself into message routing, content moderation, and predictive response generation, compressing the latency between communication intent and action.
Large language models are rewriting how enterprise users interact with messaging platforms by generating contextual replies, summarizing thread histories, and surfacing relevant documents without explicit search queries. Technology firms and professional services organizations are deploying these capabilities across Slack, Microsoft Teams, and API-connected custom interfaces. The structural consequence is a compression of decision cycles as asynchronous deliberation gives way to AI-mediated real-time resolution.
Europe's Digital Markets Act imposes interoperability obligations on dominant messaging platforms, forcing gatekeepers to open their APIs to rival services. This regulatory intervention erodes platform lock-in advantages that historically anchored enterprise retention strategies. Messaging vendors serving European multinationals are now engineering federation protocols that enable cross-platform thread continuity while preserving end-to-end encryption guarantees.
Enterprise buyers are unbundling communication procurement from adjacent productivity software, selecting best-of-breed messaging tools independent of suite vendors. This behavioral shift disrupts the bundling strategies that anchored Microsoft Teams' market penetration. The phenomenon is most pronounced in technology and media verticals where engineering teams prioritize API extensibility over integrated feature breadth.
Instant Messaging Software Market Segmentation
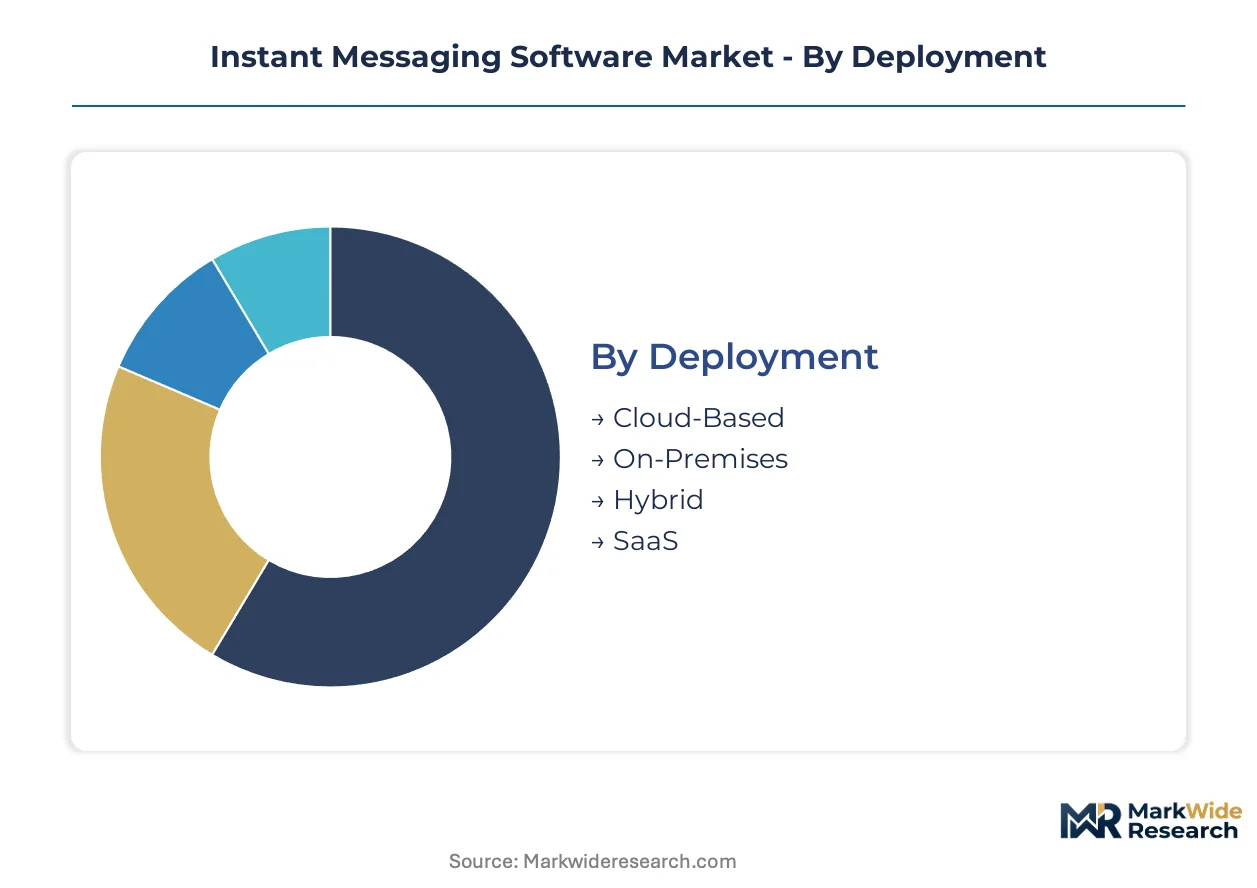
Deployment architecture determines data sovereignty compliance and infrastructure ownership for messaging platforms. User type segmentation reveals divergent procurement patterns between consumer virality and enterprise retention models. Feature integration depth separates workflow automation leaders from basic communication utilities.
Deployment:
Supply concentration tilts toward cloud-native architectures that accelerate update velocity and reduce capital expenditure for buyers.
- Cloud-Based:Multi-tenant infrastructure delivers elastic scaling across geographic regions with automatic security patching. United States federal agencies and defense contractors are mandating FedRAMP-authorized cloud platforms, concentrating demand among audited vendors. Cloud-Based absorbs the bulk of installed capacity; SaaS is expanding most quickly.
- On-Premises:Dedicated hardware installations within organizational data centers enforce complete data residency and offline operation. Financial services institutions in Germany and Switzerland maintain on-premises dominance due to archival compliance requirements and institutional inertia toward asynchronous protocols.
- Hybrid:Split architectures route sensitive traffic through local infrastructure while leveraging cloud elasticity for non-critical workloads. Healthcare systems in Canada deploy hybrid models to segment patient data under Health Canada privacy frameworks from administrative communications.
- SaaS:Subscription-delivered software abstracts infrastructure management to vendor operations teams. Technology startups in India favor SaaS procurement to align messaging costs with variable revenue streams under RBI digital payment integration requirements.
Cloud-Based absorbs the bulk of installed capacity; SaaS is expanding most quickly.
User Type:
Cost tier stratification separates high-integration enterprise budgets from freemium consumer acquisition models.
- Individuals:Consumer-grade applications prioritize network effects and cross-platform mobile synchronization. India's Digital Public Infrastructure creates tailwinds for individual messaging integrated with UPI payment rails and government identity verification.
- Enterprises:Organizational deployments demand administrative controls, audit logging, and API extensibility for workflow automation. Technology and media verticals in the United States concentrate enterprise demand through channel-based CI/CD pipeline integration.
- Government:Sovereign communication requirements mandate air-gapped or certified infrastructure with domestic data routing. China's Personal Information Protection Law funnels government procurement toward localized storage architectures that fragment global vendor strategies.
- Educational Institutions:Hybrid learning normalization drives persistent digital campus infrastructure for synchronous and asynchronous instruction. North American universities deploy real-time messaging to replace legacy learning management system discussion forums.
Enterprises command the deepest integration expenditure; Educational Institutions are gaining share fastest.
Feature Set:
Application-driven differentiation separates synchronous voice-video suites from persistent text-based workflow platforms.
- Text Chat:Persistent, searchable message threads form the foundational layer of enterprise communication records. GDPR's data portability requirements in Europe are reshaping text archive export capabilities for multinational compliance.
- Voice Calling:Real-time audio sessions with noise cancellation and transcription integration support remote field operations. Construction project management in Australia leverages voice calling for site coordination under TGA-regulated safety documentation protocols.
- Video Conferencing:Screen sharing and virtual whiteboarding replicate physical meeting dynamics for distributed teams. Professional services organizations in the United Kingdom deploy video suites under FCA record-keeping rules for client consultations.
- File Sharing:In-message document collaboration with version control and permission inheritance streamlines approval workflows. Legal verticals in France require file sharing under CNIL data minimization guidelines for client matter documentation.
Text Chat retains the largest active user base; Video Conferencing shows the steepest expansion trajectory.
Integration:
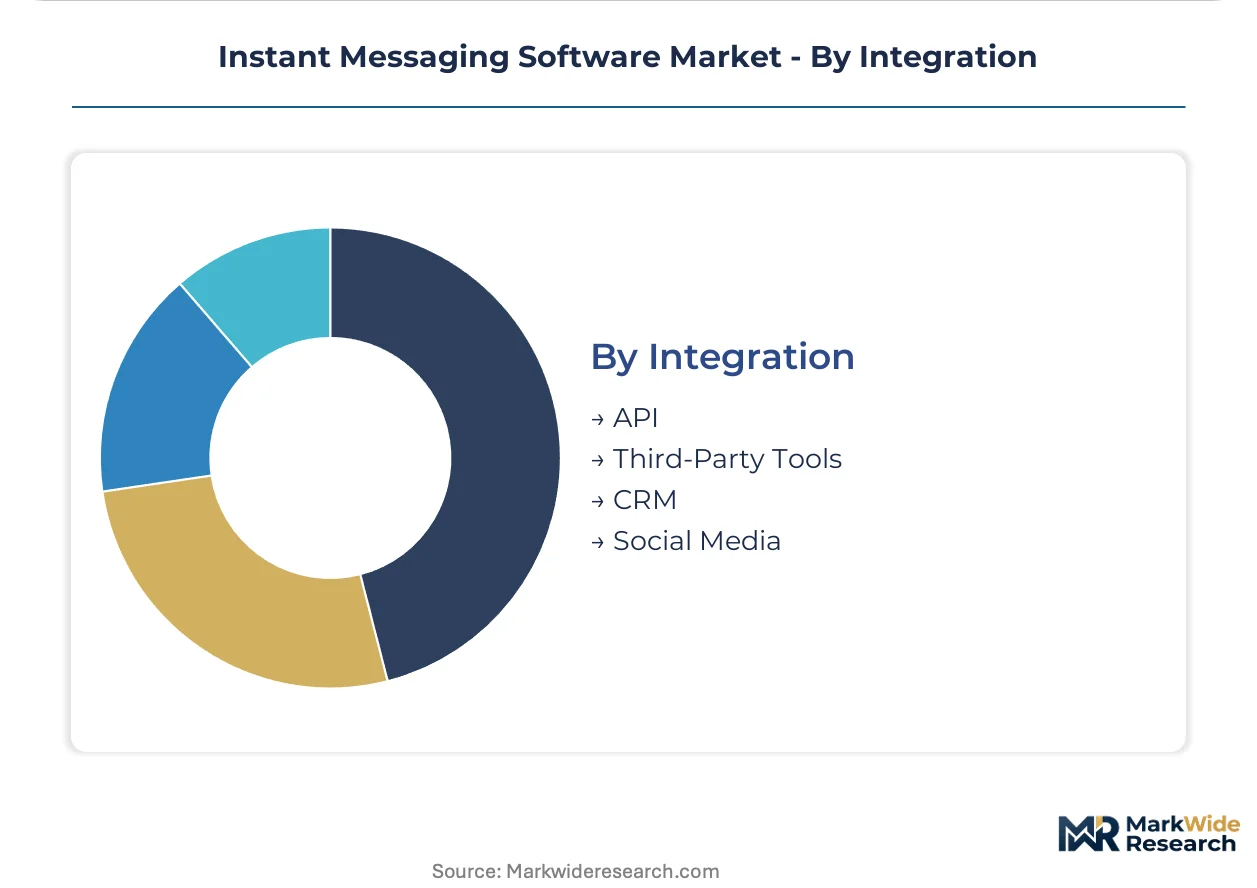
Margin concentration favors API-first platforms that capture developer ecosystem loyalty over closed-suite alternatives.
- API:Programmable interfaces enable custom bot development and webhook automation for vertical-specific workflows. Brazil's fintech sector embeds messaging APIs into ANVISA-regulated healthcare payment platforms.
- Third-Party Tools:Pre-built connectors to project management and DevOps suites reduce implementation friction. South Korean manufacturing firms integrate messaging with MFDS-tracked supply chain visibility tools.
- CRM:Customer relationship management synchronization embeds conversation history into sales pipeline records. UAE retail conglomerates deploy CRM-linked messaging under MOHAP commercial licensing frameworks.
- Social Media:Cross-platform publishing and inbound message aggregation unify external engagement channels. Creator economies in Saudi Arabia leverage social media integration for SFDA-compliant product promotion workflows.
API connections dominate developer-led procurement; CRM integration is climbing the fastest among enterprise sales cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software production concentrates in the United States and China while consumption spreads across enterprise clusters in Germany, India, and Brazil. The regulatory fragmentation around data sovereignty is forcing vendors to architect region-specific deployment strategies rather than unified global platforms.
United States
Federal agencies and defense contractors mandate FedRAMP-authorized communication tools, funneling procurement toward audited vendors. The SEC and FTC impose record-keeping obligations on financial services messaging that shape enterprise feature roadmaps. Silicon Valley technology firms and Washington DC government contractors anchor demand for channel-based workflow automation integrated with CI/CD pipelines.
Germany
Industrial manufacturing clusters in Bavaria and Baden-Württemberg drive enterprise adoption for supply chain coordination. The BSI and GDPR impose strict data residency and encryption standards that fragment global architecture strategies. Frankfurt's financial services sector maintains on-premises dominance due to BaFin archival compliance requirements and institutional preference for asynchronous protocols.
China
Domestic technology giants and government agencies require localized data storage under the Personal Information Protection Law. The MIIT and SAMR regulate cross-border message routing with technical restrictions on end-to-end encryption deployment. Shenzhen and Beijing anchor production of messaging infrastructure while Shanghai's financial district consumes hybrid deployment models for administrative communications.
India
Technology startups and educational institutions deploy SaaS messaging to align costs with variable revenue streams. The RBI and TRAI regulate digital payment integration with messaging platforms under the Digital Public Infrastructure initiative. Bangalore and Hyderabad's software engineering clusters demand API-first platforms for bot development and webhook automation.
Brazil
Fintech and healthcare payment platforms embed messaging APIs into regulated transaction workflows. ANVISA and the central bank impose data localization requirements for patient and financial communications. São Paulo's financial services sector and Rio de Janeiro's creative economy anchor demand for consumer-enterprise boundary platforms repurposed from community-driven use cases.
Instant Messaging Software Market Competitive Environment
The competitive structure tilts toward platform unbundling as organizations reject monolithic suites in favor of modular, API-first communication stacks. Consolidation pressures concentrate among productivity software giants, communication specialists, and consumer-platform crossovers. Strategic archetypes include suite-anchored incumbents, channel-based workflow specialists, and community-driven boundary platforms. Dominant competitive moves encompass M&A for API capability acquisition and geographic expansion for data sovereignty compliance.
Among suite-anchored incumbents, Microsoft Corporation exemplifies deep productivity integration that anchors enterprise retention. Within the workflow automation tier, Slack Technologies represents channel-based specialization that appeals to technology and media verticals. At the consumer-enterprise boundary, Discord Inc. occupies a position leveraging gaming infrastructure for creator economy and fan engagement monetization.
| Leading Market Players |
|---|
| Telegram |
| Facebook Messenger |
| Microsoft Teams |
| Slack |
| Discord |
| Twilio MessagingX |
| Zendesk |
| Others |
Value Chain & Pricing Dynamics
FedRAMP certification mandates from United States federal agencies are compressing vendor selection pools and forcing supply-side specialization toward audited cloud infrastructure providers, which stratifies pricing power between compliant and non-compliant tiers.
Pricing Analysis
Margin tightening in enterprise SaaS tiers reflects the cost burden of multi-region data residency compliance under GDPR and China's Personal Information Protection Law. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation anchored in FedRAMP authorization status and API call volume allowances. Cost compression in the standard tier accelerates because hyperscaler bundling pressures standalone messaging vendors. Educational institutions exhibit highest price sensitivity due to budget variability, while defense contractors demonstrate lowest sensitivity given security-driven procurement mandates.
Supply Chain Analysis
Regional distribution centers for cloud infrastructure concentrate in Northern Virginia, Frankfurt, and Singapore to minimize latency for enterprise workloads. Software production draws from engineering talent pools in the United States, India, and China, with cryptographic engineering expertise resting on a narrow base of specialized firms. Single-source vulnerability concentrates in encryption protocol libraries maintained by open-source foundations. Distribution runs through hyperscaler marketplaces and direct enterprise sales channels with professional services overlays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation around data sovereignty is forcing consolidation as smaller vendors lack capital to architect multi-jurisdiction compliance pathways.
For Market Incumbents: Lock in enterprise retention through FedRAMP High authorization investment and deep API ecosystem development that raises switching costs. Acquire specialized encryption engineering teams to address talent scarcity constraining secure product roadmaps. Counter emerging workflow automation entrants by embedding channel-based CI/CD integration deeper into DevOps toolchains. For New Entrants and Emerging Players: Europe's Digital Markets Act interoperability mandates in Germany and France open a window for federation-protocol specialists that enable cross-platform message threading. Target India's educational technology sector under RBI digital payment integration requirements for fastest penetration. Pursue vertical SaaS embedding strategy in healthcare and legal project management where messaging is workflow-embedded rather than standalone. For Investors and Strategic Acquirers: The window for entry favors API-first workflow automation specialists with established developer ecosystems and regional data sovereignty compliance. Long-term viability hinges on multi-jurisdiction certification portfolios rather than single-market dominance. Monitor Digital Markets Act technical implementation timelines as signal for interoperability-enabling acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Investment | Unlocks United States federal procurement pipelines that mandate audited cloud platforms. |
| API-First Platform Expansion | Captures developer loyalty in technology verticals prioritizing webhook automation over suite bundling. |
| Regional Data Center Buildout | Satisfies China's Personal Information Protection Law storage mandates for domestic traffic routing. |
| Encryption Talent Acquisition | Addresses cryptographic engineering scarcity constraining secure messaging development timelines. |
| Vertical SaaS Partnership | Embeds messaging capabilities into healthcare payment platforms under ANVISA regulatory frameworks. |
Study Parameters
SEC filings, hyperscaler capex disclosures, and App Annie mobile engagement data formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with CTOs, IT procurement officers at Fortune 500 enterprises, platform engineers at technology startups, and channel partners validated deployment trend assumptions. Bottom-up triangulation across user type segments and top-down validation against cloud infrastructure expenditure trends ensured convergence.
Historical trendline analysis across deployment models, organization size tiers, vertical industries, and regional adoption patterns established baseline growth trajectories. CAGRs were derived through regression analysis of installed base expansion and average revenue per user evolution. Forecast inputs incorporated FedRAMP authorization pipeline timelines, Digital Markets Act implementation milestones, and educational institution digital campus investment cycles.
Caveats apply where encryption export control tightening or interoperability standardization delays could materially shift the outlook. Forecasts reflect documented assumptions around regulatory implementation schedules and enterprise procurement cycle normalization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Indoor Cycling Software Market
Software & Services
Global App Store Optimization Tools Software Market
Software & Services
Towing Software Market
Software & Services
Asia-Pacific Digital Signage Software Market
Software & Services
Service Resource Planning (SRP) Saas Solutions Market
Software & Services
Supply Chain Visibility (SCV) Software Market
Software & Services
Global Virtual Desktop Market
Software & Services
Parks and Playground Inspection Software Market
Software & Services
Account-Based Direct Mail Software Market
Software & Services
Airline Route Profitability Software Market
Software & Services
Client Virtualization Software Market
Software & Services
Metal Recycling Software Market
Software & Services
Customer Revenue Optimization Software Market
Software & Services
Contract Abstraction Software Market
Software & Services
Customer Advocacy Software Market
Software & Services
Discount Management Software Market