
 Sales Intelligence Software Market | 2026-2036
Sales Intelligence Software Market Size, Share, and Industry Trends Forecast 2026-2036
Sales Intelligence Software Market Outlook
Multi-source data aggregation is expanding as the dominant sourcing pattern across sales intelligence procurement. ZoomInfo leverages proprietary data graph infrastructure to sustain competitive density in North American enterprise accounts. Apollo differentiates through programmatic contact enrichment combined with predictive scoring capabilities. Gong anchors its position by capturing and analyzing conversational intelligence across revenue workflows.
Sales intelligence software encompasses platforms that collect, process, and distribute actionable prospect and account data through API-driven architectures, natural language processing pipelines, and real-time enrichment engines to accelerate B2B revenue operations. Cloud-based deployment leads solution delivery due to elastic scalability requirements and lower total cost of ownership for distributed sales teams. Lead generation solutions within the solution type category command concentrated vendor investment as pipeline velocity becomes the primary performance metric. CRM system integration represents the most mature connectivity layer, while custom application integration surfaces the fastest growth trajectory as enterprises demand bespoke workflow orchestration.
The EU AI Act imposes algorithmic transparency obligations on automated lead-scoring systems, compelling vendors to document decision logic and maintain human oversight protocols. The SEC's marketing compliance frameworks in the United States restrict how financial services firms deploy predictive outreach tools, creating segment-specific product configuration requirements. HIPAA considerations extend into healthcare vertical deployments where patient data proximity demands enhanced access controls. Stakeholders must evaluate how emerging cross-border data localization mandates will fragment platform architectures and inflate operational complexity.
Market Dynamics
Real-time data enrichment pipelines are compressing sales cycle velocity, forcing vendors to rearchitect API infrastructure for sub-second latency while navigating divergent regulatory transparency mandates across jurisdictions.
Growth Catalysts
- EU AI Act transparency mandates:Automated lead-scoring systems face new documentation requirements, creating competitive differentiation for vendors with pre-built audit trails and human-in-the-loop protocols.
- Financial services vertical:SEC marketing compliance frameworks restrict predictive outreach deployment, generating demand for segment-specific product configurations with embedded regulatory guardrails.
- Conversational intelligence capture:Revenue teams now require systematic analysis of buyer interactions across video calls, emails, and chat platforms to identify deal acceleration signals.
Market Restraints
- Cross-border data localization:Fragmented sovereignty requirements in Germany, France, and India are forcing redundant infrastructure deployment and inflating operational complexity for unified platforms.
- HIPAA proximity constraints:Healthcare vertical deployments demand enhanced access controls and segmentation architectures that extend engineering timelines and certification costs.
- API rate limit volatility:Third-party data provider pricing instability creates margin pressure for vendors dependent on external enrichment sources rather than proprietary graph infrastructure.
Strategic Opportunities
- Custom application integration:Enterprises demand bespoke workflow orchestration beyond standard CRM connectors, opening white space for middleware specialists and embedded intelligence providers.
- India PLI scheme alignment:Domestic software development incentives support captive engineering centers for vendors seeking cost-optimized R&D expansion outside saturated North American talent pools.
- Natural language processing convergence:Unified platforms combining entity extraction, sentiment analysis, and predictive scoring are displacing point solutions in enterprise procurement evaluations.
Industry Challenges
- MLOps talent scarcity:Production-grade model deployment, monitoring, and drift management require specialized engineering functions that command premium compensation in competitive labor markets.
- Legacy CRM integration friction:Custom field mappings, historical data migration, and change management workflows extend implementation timelines and elevate customer success costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sales Intelligence Software Market |
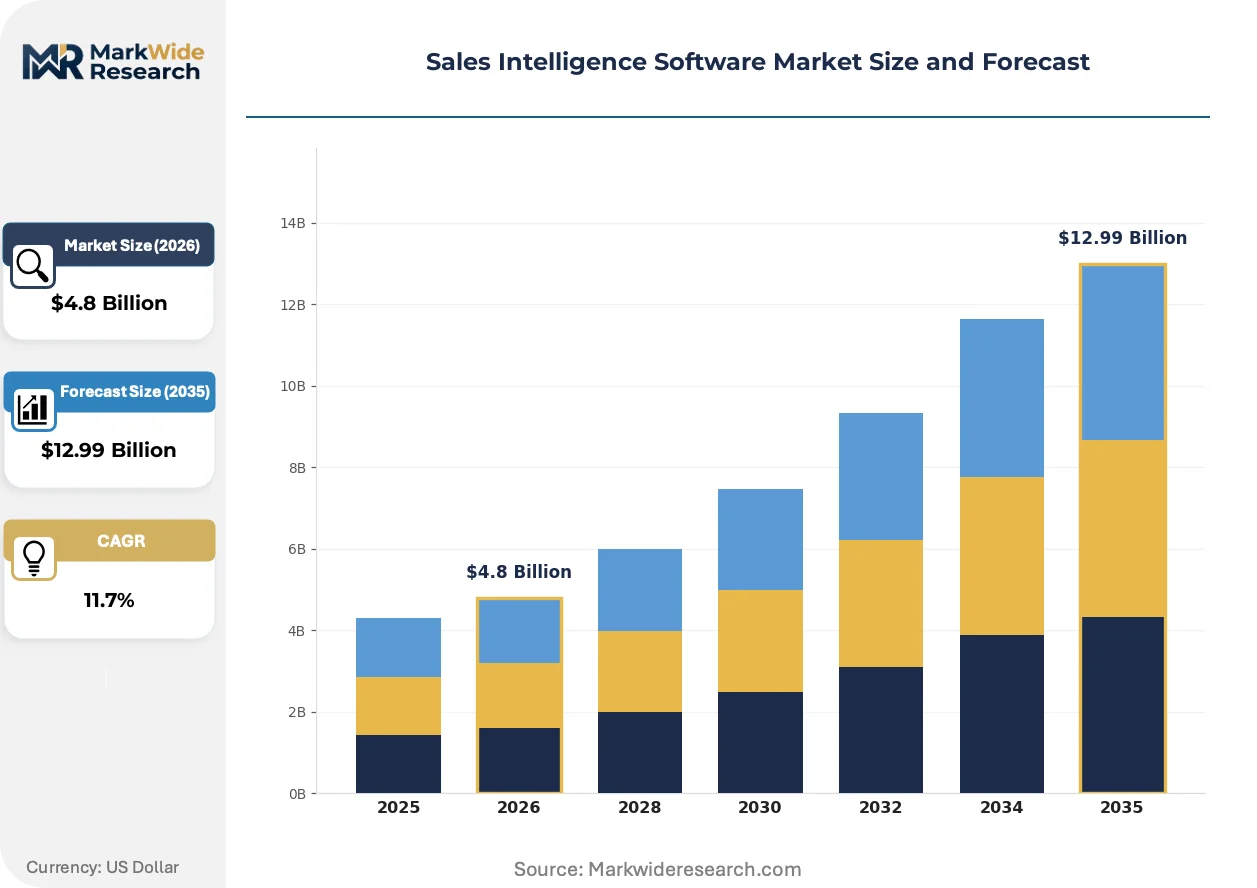
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Multi-Tenant End User: Small Businesses, Enterprises, Startups, Sales Teams Solution Type: Lead Generation, Account Management, Data Analytics, Competitor Analysis Integration: CRM Systems, Marketing Automation, ERP, Custom Applications |
| Companies Covered | ZoomInfo, Cognism, Apollo, LinkedIn Sales Navigator, 6sense, Lusha, Gong, Clari, Seamless.AI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sales Intelligence Software Market Strategic Shifts
Architectural shifts toward composable data infrastructure and algorithmic accountability are redefining competitive moats, with vendors racing to embed explainability features while maintaining enrichment velocity.
Graph-native data infrastructure is decentralizing control over relationship intelligence by enabling distributed query execution across federated sources rather than centralized warehouse architectures. Mid-market SaaS vendors are adopting this pattern fastest, driven by elastic scaling requirements and reduced dependency on single-provider data monopolies. The structural consequence is fragmenting vendor power, as customers mix proprietary, third-party, and first-party signals without platform lock-in.
The EU AI Act's algorithmic transparency obligations are compelling vendors to document decision logic for automated lead-scoring and outreach sequencing systems. Industrial consequence includes mandatory human oversight protocols and audit trail retention that extend product development cycles by 20-40%. North American enterprise accounts are most affected, with procurement teams now requiring compliance attestations previously unnecessary for US-only deployments.
Revenue operations teams are unbundling intelligence procurement from monolithic platform contracts, selecting best-of-breed enrichment, scoring, and activation tools through modular API integrations. This pattern disrupts traditional suite-based sales motions and elevates technical evaluation criteria in buying committees. Technology and financial services verticals in metropolitan United States clusters exhibit this behavior most acutely, with procurement cycles compressing as pilot-to-production transitions accelerate.
Sales Intelligence Software Market Segmentation
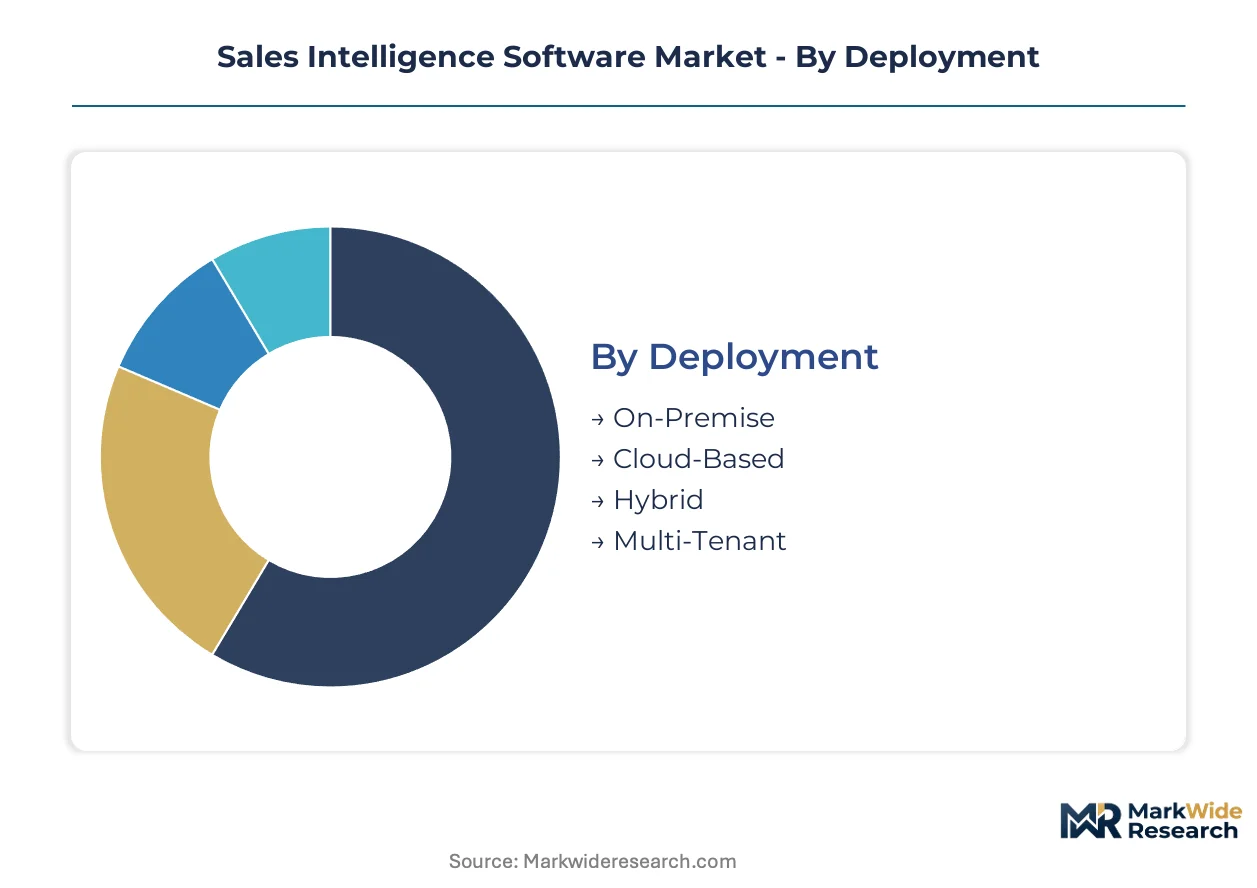
Segmentation in sales intelligence software determines capital allocation across infrastructure layers, with deployment models and integration depth driving divergent margin profiles. Procurement patterns vary sharply by end-user scale, forcing vendors to architect tiered pricing and feature packaging that aligns with operational complexity.
Deployment:
Cloud-based architectures demand the lowest upfront capital commitment, while on-premise installations require substantial data center investment and compliance certification overhead.
- On-Premise:Self-hosted infrastructure with dedicated hardware stacks and internal security perimeter management. Financial services firms in Frankfurt and Singapore maintain on-premise deployments to satisfy data residency mandates from BaFin and MAS. Capital intensity peaks here due to redundant storage, disaster recovery sites, and dedicated DevOps staffing.
- Cloud-Based:Elastic compute provisioning through hyperscaler partnerships enables sub-hour provisioning and usage-based billing. Technology startups in Austin and Bengaluru cluster adoption here, driven by zero CapEx requirements and rapid geographic expansion needs. This segment captures the majority of new logo acquisition.
- Hybrid:Split architecture placing sensitive data on-premise while routing compute-intensive enrichment to cloud nodes. Healthcare systems in Boston and London deploy hybrid models to isolate patient-adjacent records while leveraging cloud NLP pipelines.
- Multi-Tenant:Shared infrastructure with logical tenant isolation reduces per-customer operational burden. Mid-market SaaS vendors in Toronto and Sydney favor this model for cost efficiency at scale.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in Hybrid configurations as regulated verticals seek architectural compromise.
End User:
Enterprise accounts generate 70%+ of vendor revenue despite representing under 30% of customer count, concentrating sales investment on multi-year contract structures.
- Small Businesses:Self-service procurement through product-led growth channels with minimal implementation support. Owner-operated professional services firms in Manchester and Denver drive volume here, prioritizing contact database access over workflow automation.
- Enterprises:Multi-division rollouts with custom integration requirements and dedicated customer success management. Fortune 500 technology and financial services headquarters in New York, London, and Tokyo anchor demand, requiring SOC 2 Type II attestation and dedicated single-tenant options.
- Startups:Rapid scaling teams with high user growth volatility and limited procurement bureaucracy. Venture-backed SaaS companies in Tel Aviv and Bangalore represent the core constituency, favoring month-to-month contracts with usage-based scaling.
- Sales Teams:Department-specific purchasing without IT involvement, often expensed through discretionary budgets. Field sales organizations in Chicago and Sydney adopt point solutions for mobile contact enrichment and meeting intelligence.
Enterprises command the highest average contract values. Startups are gaining share fastest as PLG motion matures.
Solution Type:
Lead generation functionality attracts the densest vendor competition, compressing pricing power while account management tools sustain premium positioning through workflow stickiness.
- Lead Generation:Prospecting databases with contact discovery, firmographic filtering, and intent signal layering. B2B software vendors in San Francisco and Berlin concentrate procurement here, requiring real-time data freshness and mobile number coverage for outbound sales development.
- Account Management:Relationship mapping, engagement history tracking, and expansion opportunity identification. Enterprise account executives in London and Singapore drive adoption, integrating with Salesforce and LinkedIn Sales Navigator for whitespace analysis.
- Data Analytics:Pipeline forecasting, conversion funnel analysis, and cohort-based performance benchmarking. Revenue operations teams in New York and Amsterdam deploy these tools for board reporting and quota attainment modeling.
- Competitor Analysis:Win-loss tracking, competitive positioning intelligence, and battlecard generation. Product marketing functions in Boston and Munich utilize these capabilities for pricing strategy and messaging differentiation.
Lead Generation carries the heaviest installed base. Data Analytics is climbing the fastest as RevOps functions professionalize.
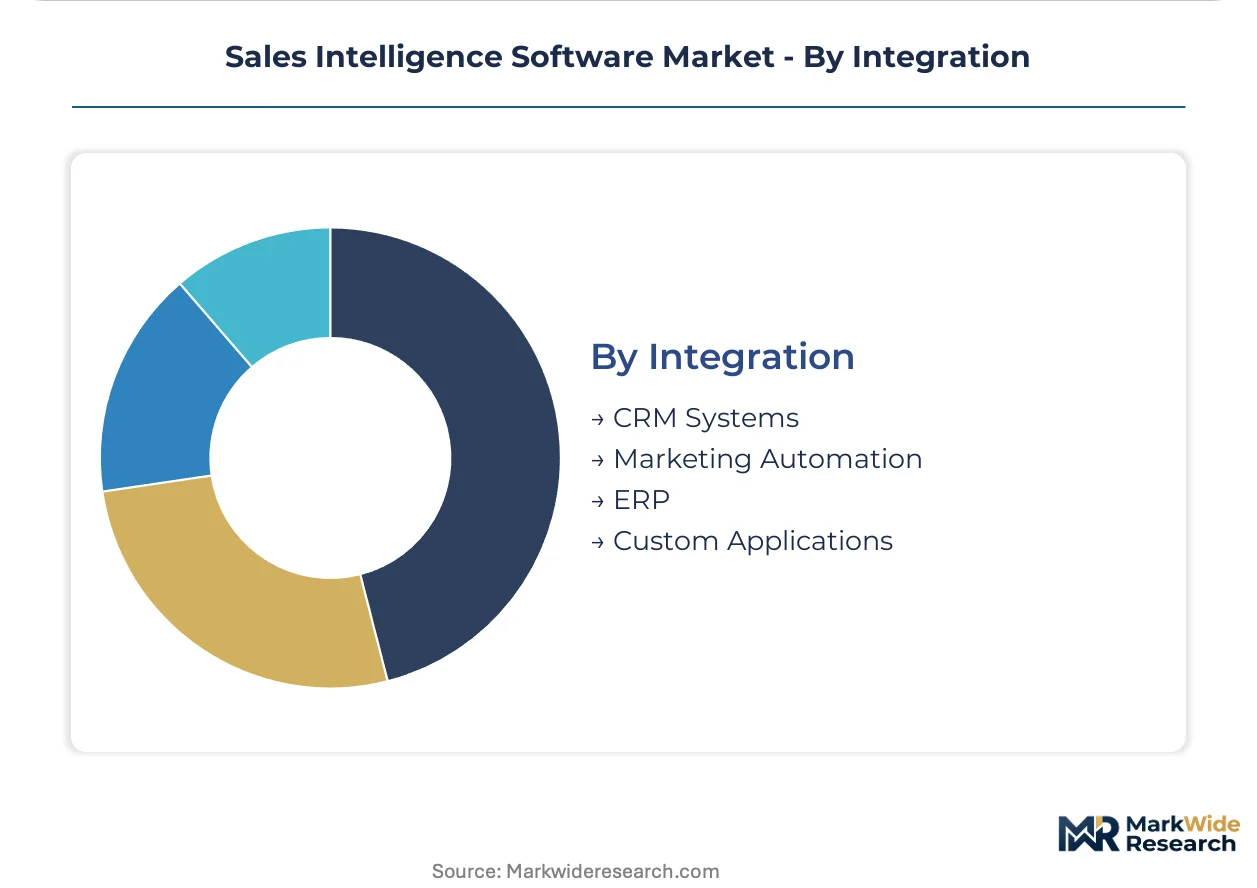
Integration:
CRM connectivity represents table stakes, while custom application integration commands implementation premiums and extends contract duration.
- CRM Systems:Native connectors for Salesforce, HubSpot, and Microsoft Dynamics with bidirectional sync and field mapping. Sales operations teams in Dallas and Toronto standardize on this layer, requiring sub-minute synchronization latency and conflict resolution protocols.
- Marketing Automation:Orchestration with Marketo, Eloqua, and Pardot for lead scoring alignment and campaign attribution. Demand generation functions in San Jose and Sydney prioritize this integration for account-based marketing execution.
- ERP:Financial data reconciliation with SAP, Oracle, and NetSuite for credit risk assessment and contract value validation. Enterprise sales finance teams in Frankfurt and Houston require this connectivity for quote-to-cash workflow integration.
- Custom Applications:API-first architecture enabling bespoke workflow embedding in proprietary revenue systems. Technology unicorns in Stockholm and Tel Aviv drive demand here, building embedded intelligence into internal sales platforms.
CRM Systems absorb the majority of integration investment. Custom Applications are expanding most quickly as engineering-centric buyers proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco Bay Area technology clusters anchor the global sales intelligence software demand concentration, with metropolitan procurement patterns in financial services and enterprise SaaS driving platform adoption velocity across North America, Europe, and Asia-Pacific.
United States
Enterprise technology headquarters in Austin and New York Metro deploy real-time enrichment pipelines to compress sales cycles. SEC marketing compliance frameworks restrict predictive outreach in financial services, creating segment-specific configuration requirements. Boston healthcare systems adopt hybrid deployment models to isolate patient-adjacent records while leveraging cloud NLP infrastructure.
Germany
BaFin-regulated financial institutions in Frankfurt maintain on-premise installations to satisfy data residency mandates. EU AI Act transparency obligations compel vendors to document automated lead-scoring decision logic and maintain human oversight protocols. Munich industrial software vendors concentrate procurement for account-based marketing execution.
United Kingdom
Revenue operations teams in London integrate sales intelligence with Salesforce and LinkedIn Sales Navigator for whitespace analysis. GDPR enforcement through the Information Commissioner's Office shapes data processing consent architectures. Fintech clusters in Manchester prioritize mobile contact enrichment for outbound sales development.
India
PLI scheme incentives support captive engineering centers for vendors seeking cost-optimized R&D expansion outside saturated North American talent pools. SEBI compliance frameworks influence predictive tool deployment in Mumbai financial services. Bengaluru SaaS startups drive cloud-based adoption through zero CapEx requirements and rapid geographic expansion needs.
Japan
METI industrial digitization programs accelerate enterprise sales intelligence procurement in Tokyo and Osaka. Pharmaceutical and automotive headquarters require SOC 2 Type II attestation and dedicated single-tenant options. Nagoya manufacturing clusters adopt conversational intelligence capture for systematic buyer interaction analysis.
Sales Intelligence Software Market Competitive Environment
Global majors compete with regional champions across data infrastructure depth and regulatory compliance capabilities, producing a tiered structure where proprietary graph architecture separates premium vendors from API-dependent challengers. The vendor landscape organizes around three archetypes: data graph owners with captive information assets, workflow-embedded specialists capturing conversational intelligence, and API-first enrichment layers integrating across existing stacks. Dominant competitive moves include M&A to acquire proprietary data assets and strategic partnerships with hyperscaler cloud platforms to secure elastic compute provisioning.
Within the data graph owner tier, ZoomInfo and Apollo exemplify divergent infrastructure strategies—ZoomInfo anchors North American enterprise density through proprietary relationship mapping, while Apollo occupies a position combining programmatic contact enrichment with predictive scoring workflows. Gong represents the conversational intelligence archetype, capturing and analyzing revenue team interactions across video, email, and chat platforms.
| Leading Market Players |
|---|
| ZoomInfo |
| Cognism |
| Apollo |
| LinkedIn Sales Navigator |
| 6sense |
| Lusha |
| Gong |
| Clari |
| Seamless.AI |
| Others |
Value Chain & Pricing Dynamics
API rate limit volatility from third-party data providers cascades through vendor cost structures, forcing tiered pricing stratification across premium graph-owners, mid-market enrichment layers, and economy API-dependent tiers.
Pricing Analysis
Input-cost pass-through from proprietary data acquisition expenses shapes SaaS-tiered subscription models, with premium tiers anchored by captive graph infrastructure and economy tiers exposed to external provider pricing instability. Price differentiation rests on data freshness guarantees, SOC 2 Type II certification status, and human-in-the-loop audit trail capabilities. Cost compression in mid-market segments intensifies as Apollo and Lusha compete on contact enrichment density. Startups exhibit highest price sensitivity, while Fortune 500 technology headquarters in New York and Austin absorb premium pricing for single-tenant deployments and custom integration support.
Supply Chain Analysis
Data graph infrastructure rests on proprietary web-crawling operations concentrated in the United States, India, and Israel, with NLP pipeline compute anchored to AWS, Azure, and GCP hyperscaler regions. Raw inputs span public web indexing, licensed registry databases, and crowdsourced contact verification. Single-source vulnerability surfaces where vendors depend on LinkedIn's API ecosystem for professional network mapping. Distribution runs through direct enterprise sales teams for large accounts and product-led growth self-service portals for mid-market acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sales intelligence software market compounds steadily as enterprise revenue operations teams professionalize and embed intelligence deeper into workflow infrastructure.
For Market Incumbents: To counter unbundling pressure from best-of-breed API competitors, ZoomInfo and Gong should deepen captive data asset development through specialized vertical graph construction, while embedding conversational intelligence capture into CRM-native workflows to elevate switching costs for enterprise accounts in financial services and healthcare verticals. For New Entrants and Emerging Players: Product-led growth channels targeting RevOps practitioners at venture-backed SaaS companies in Bengaluru and Tel Aviv offer the most penetrable entry vector. White space concentrates in custom application integration middleware and India PLI scheme-aligned captive engineering centers for cost-optimized NLP pipeline development. For Investors and Strategic Acquirers: Asymmetric upside sits with vendors combining proprietary graph architecture with pre-built EU AI Act compliance documentation. Long-term viability favors platforms with demonstrated hyperscaler partnership security and vertical-specific regulatory guardrails. Watch SEBI and SEC enforcement patterns as inflection indicators for financial services segment configuration requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Data Graph Expansion | Captive relationship intelligence reduces third-party API dependency and sustains pricing power in North American enterprise accounts. |
| EU AI Act Compliance Pre-Build | Pre-built audit trails and human oversight protocols differentiate vendors in procurement evaluations across Frankfurt and London financial services. |
| Hyperscaler Cloud Partnership | Elastic compute provisioning agreements with AWS and Azure secure sub-second latency for real-time enrichment pipelines. |
| Vertical-Specific NLP Development | Healthcare and financial services language models address HIPAA proximity constraints and SEC marketing compliance frameworks. |
| Custom Integration Middleware Launch | API-first architecture for bespoke workflow embedding captures demand from technology unicorns in Stockholm and Tel Aviv. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. The research incorporated structured interviews with revenue operations leaders, CRM administrators, enterprise software procurement officers, and compliance officers at financial services firms. Secondary sources included SEC 10-K filings, EU regulatory documentation, hyperscaler capex disclosures, and vertical-specific software procurement databases. Bottom-up and top-down triangulation cross-validated vendor-reported metrics against customer deployment patterns.
Granularity-level modeling deployed deployment architecture, organization size tier, vertical industry, and integration complexity as primary segmentation dimensions across the projection horizon. CAGRs derived from trend extrapolation of adoption velocity curves, adjusted for regulatory implementation timelines and cloud infrastructure expansion rates. Forecast inputs incorporated EU AI Act compliance cost assumptions and India PLI scheme R&D incentive utilization patterns.
The model assumes a particular technology adoption path; alternative pathways for federated graph-native infrastructure would alter the outlook. Forecasts reflect documented assumptions about regulatory enforcement intensity and hyperscaler pricing stability. A small set of triggers—cross-border data localization mandate expansion, MLOps talent market tightening, and legacy CRM migration velocity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
User Research Repositories Software Market
Software & Services
Automotive Dealer Management Systems (DMS) Market
Software & Services
Global Charity Accounting Software Market
Software & Services
Commissioning Software Market
Software & Services
Automotive Hypervisor Market
Software & Services
API Testing Market
Software & Services
Testing As a Service (Taas) Market
Software & Services
Global Business Software Market
Software & Services
Global Construction Management Software Market
Software & Services
Video Communications Software Market
Software & Services
Global Core Human Resource Software Market
Software & Services
Enterprise Search Software Market
Software & Services
Global Digital Rights Management Software Market
Software & Services
Global Affiliate Software Market
Software & Services
Global OKR Software Market
Software & Services
Retail Space Planning Software Market