
 Driver Updater Software Market | 2026-2036
Driver Updater Software Market Size, Share, and Industry Trends Forecast 2026-2036
Driver Updater Software Market Insights
Enterprise procurement of driver updater tools is broadening from individual IT administrators toward centralized managed services providers. Systweak Software leverages its Windows specialization to sustain channel partnerships with OEM bundling agreements. IObit competes through freemium distribution that anchors consumer-to-business upgrade funnels across Asia-Pacific markets.
Driver updater software automates detection, download, and installation of hardware driver packages across operating systems, typically interfacing with manufacturer APIs and Windows Update catalogs to resolve version conflicts and security vulnerabilities. Windows deployments dominate product type revenue due to legacy hardware fragmentation and enterprise patch management mandates, while cloud-based delivery represents the fastest-expanding segment as IT departments prioritize remote fleet administration over on-premise agents. Real-time scanning technology captures the largest margin pool among technology segments because continuous monitoring commands premium subscription pricing against scheduled or manual alternatives.
FDA cybersecurity guidance for networked medical devices and FCC equipment authorization requirements indirectly shape driver integrity standards for connected hardware ecosystems. The EU AI Act and GDPR impose audit trail obligations on automated software distribution systems, compelling vendors to document driver provenance and consent mechanisms. Stakeholders must monitor how NIST's software supply chain security framework propagates into procurement criteria for federal contractors and their downstream vendors.
Market Dynamics
Enterprise IT departments are consolidating driver management under centralized MSP contracts, compressing vendor count while elevating security audit requirements above feature breadth in procurement scoring.
Growth Catalysts
- EU AI Act compliance mandates:Automated driver distribution systems must maintain documented provenance trails, creating recurring revenue for vendors with built-in audit capabilities.
- Medical device cybersecurity:FDA guidance for networked healthcare hardware extends liability to driver integrity, forcing hospital systems toward managed update services.
- Remote fleet administration:Cloud-native deployment architectures are absorbing IT department capital previously allocated to on-premise patch management infrastructure.
Market Restraints
- Windows Update substitution:Microsoft's native driver catalog improvements reduce differentiation for third-party tools in consumer segments.
- Hardware vendor API fragmentation:Proprietary driver delivery mechanisms from GPU and peripheral manufacturers complicate universal scanning accuracy.
- GDP cost volatility:Subscription pricing pressure from freemium competitors compresses average revenue per user in emerging markets.
Strategic Opportunities
- Japan's manufacturing automation:Industrial IoT deployments in automotive and electronics sectors require specialized driver lifecycle management for non-Windows embedded systems.
- FCC equipment authorization alignment:Driver integrity verification becomes a compliance checkpoint for connected device certification, opening federal contractor procurement channels.
- AI-powered conflict resolution:Machine learning models predicting driver-hardware compatibility failures before installation reduce support ticket volume for enterprise subscribers.
Industry Challenges
- Legacy system integration:Windows 7 and 8.1 end-of-life transitions force vendors to maintain parallel driver databases for unsupported hardware.
- Cross-platform talent scarcity:Engineering teams with simultaneous expertise in Windows driver architecture and Linux kernel modules command premium compensation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Driver Updater Software Market |
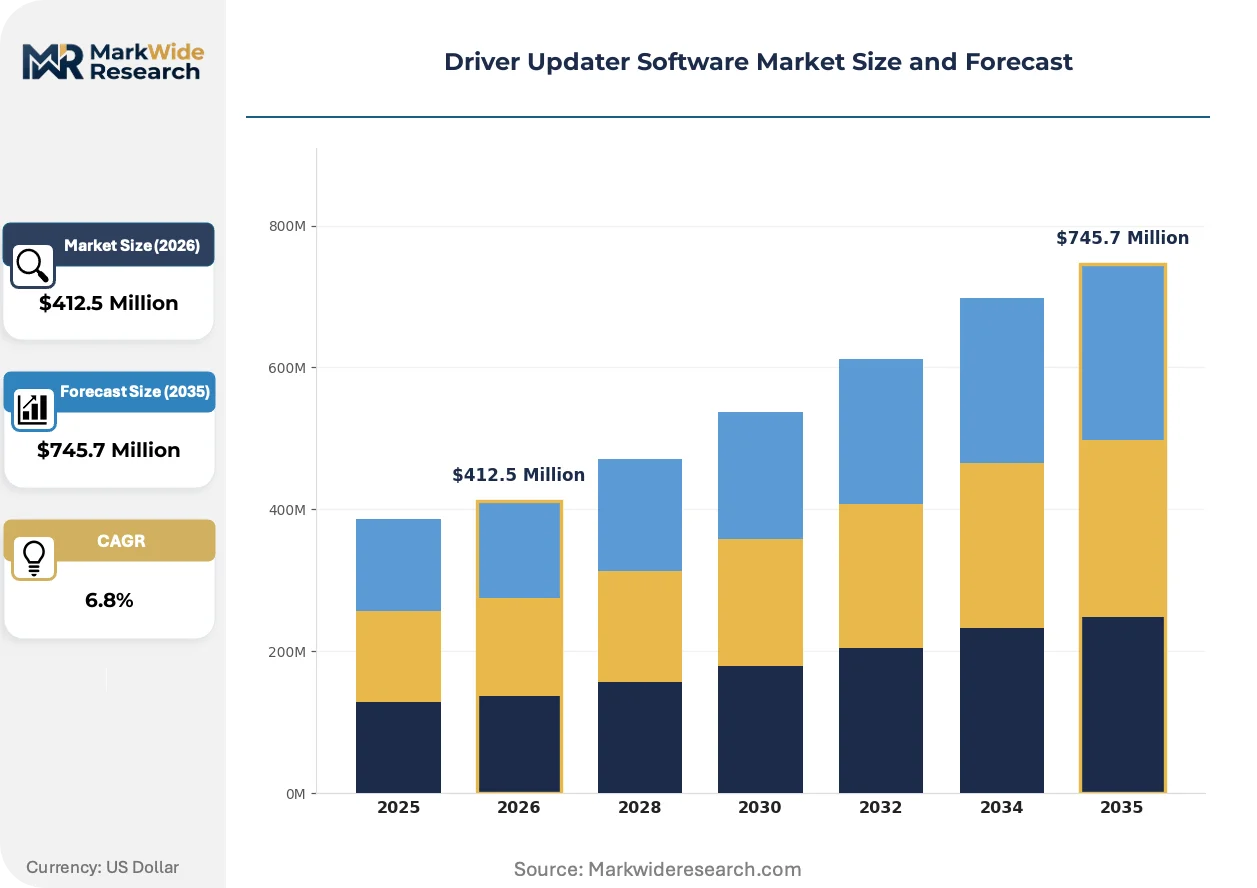
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Windows, Mac, Cloud-Based, Portable Technology: Real-Time Scanning, Automatic Backup, Driver Rollback, Scheduled Updates End User: Individual Users, Businesses, IT Support, Managed Services Distribution Channel: Online, Retail, Subscription, Bundled Software |
| Companies Covered | Systweak Software, IObit, Driver Easy, Driver Talent, Driver Checker, Avanquest Software, Rahim Soft, Fortect, WinZip Computing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Driver Updater Software Market Trends and Innovations
Continuous monitoring architectures are displacing scheduled scanning as the default enterprise configuration, embedding driver management deeper into zero-trust security frameworks.
Real-time scanning technology is absorbing premium subscription pricing power from scheduled alternatives by enabling immediate vulnerability response. Enterprise security teams in financial services and healthcare are adopting continuous monitoring as a baseline requirement. This shift is compressing revenue from perpetual-license models while expanding annual recurring revenue pools.
The EU AI Act and GDPR impose documented consent mechanisms on automated software distribution systems. Vendors must now maintain immutable logs of driver provenance, installation authorization, and rollback capabilities. Germany's Federal Office for Information Security is incorporating these audit requirements into federal procurement criteria.
IT departments are unbundling driver management from broader endpoint management suites, creating standalone procurement categories. Managed service providers are capturing this spend by offering driver lifecycle management as a discrete service line. This pattern is most visible in United States healthcare systems undergoing HIPAA security rule compliance overhauls.
Driver Updater Software Market Segmentation
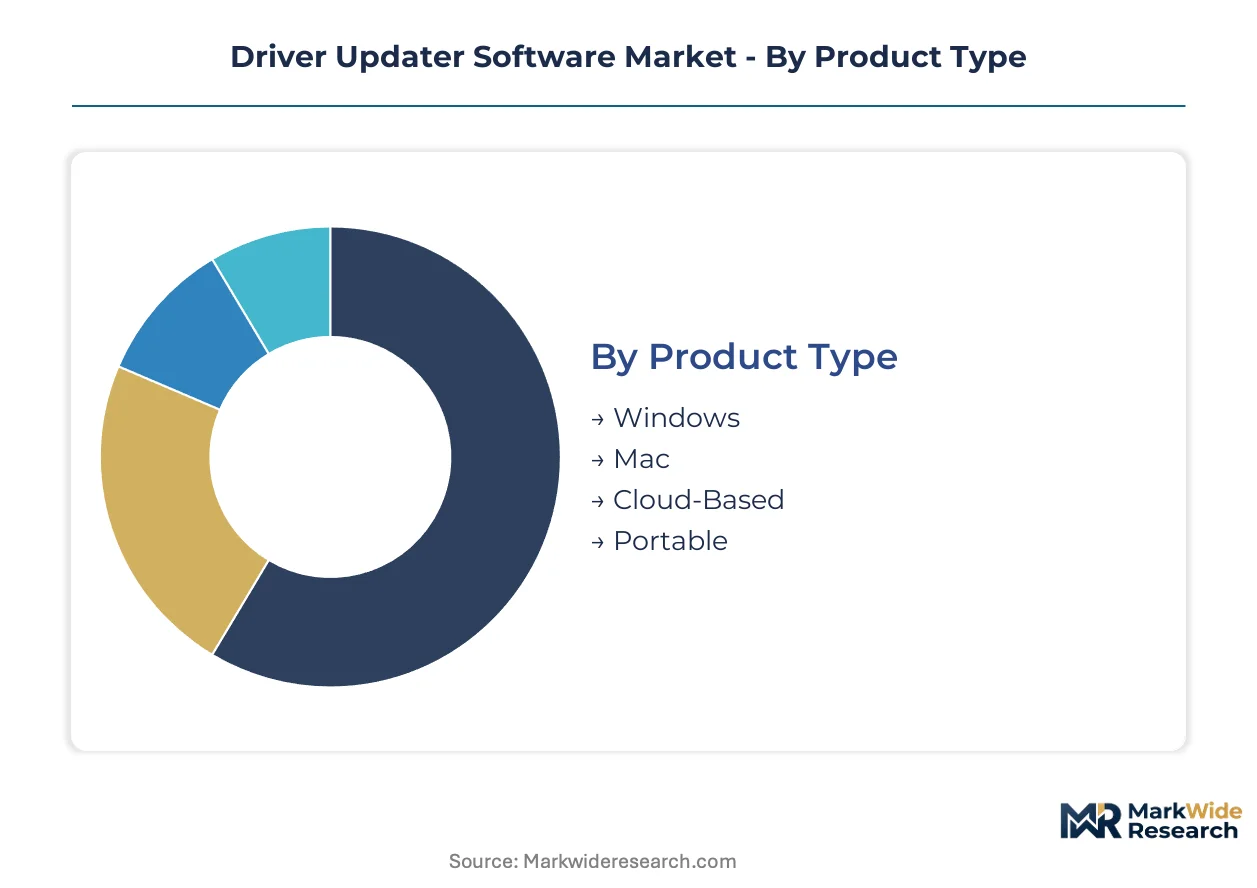
Segmentation in driver updater software reveals how procurement criteria diverge between consumer convenience and enterprise compliance mandates. Vendors must architect separate certification pathways for each category, as FDA cybersecurity guidance applies to healthcare deployments while GDPR audit trails govern European business sales.
Product Type:
FDA guidance for networked medical devices and FCC equipment authorization requirements create divergent compliance burdens across operating system platforms, with Windows deployments facing the most complex legacy hardware fragmentation.
- Windows:Dominates enterprise procurement due to legacy hardware fragmentation and patch management mandates from NIST frameworks. Hospital systems and federal contractors prioritize Windows-specific tools for HIPAA and supply chain security compliance.
- Cloud-Based:Remote fleet administration capabilities absorb IT capital previously allocated to on-premise infrastructure. Germany's Federal Office for Information Security and United States healthcare systems drive fastest adoption through zero-trust security frameworks.
- Mac:Narrower addressable market constrained by Apple's integrated driver distribution, with demand concentrating in creative industry clusters.
- Portable:USB-bootable solutions serve field technicians and air-gapped industrial environments without network connectivity.
Leading the category by volume: Windows. Growing fastest: Cloud-Based.
Technology:
Margin structures correlate directly with monitoring frequency, as continuous architectures command premium subscription pricing against scheduled alternatives.
- Real-Time Scanning:Continuous monitoring embeds driver management into zero-trust security frameworks. Financial services and healthcare enterprises in the United States and Germany mandate immediate vulnerability response.
- Automatic Backup:Immutable rollback capabilities satisfy EU AI Act and GDPR audit trail obligations. German federal procurement criteria explicitly require documented driver provenance.
- Driver Rollback:Critical for FDA-regulated medical devices where driver integrity failures trigger liability exposure.
- Scheduled Updates:Compressed to economy-tier pricing by Windows Update substitution and freemium competition.
Highest margin capture: Real-Time Scanning. Steepest expansion trajectory: Automatic Backup.
End User:
Procurement authority is consolidating from individual administrators toward centralized contracts with managed service providers.
- Managed Services:MSPs capture unbundled driver lifecycle management as discrete service lines. United States healthcare systems undergoing HIPAA compliance overhauls represent concentrated demand.
- Businesses:Enterprise IT departments elevate security audit requirements above feature breadth in vendor scoring.
- IT Support:Channel partners bundle driver tools with broader endpoint management suites.
- Individual Users:Freemium distribution anchors consumer-to-business upgrade funnels, particularly across Asia-Pacific markets.
Fastest contract value growth: Managed Services. Largest installed base: Individual Users.
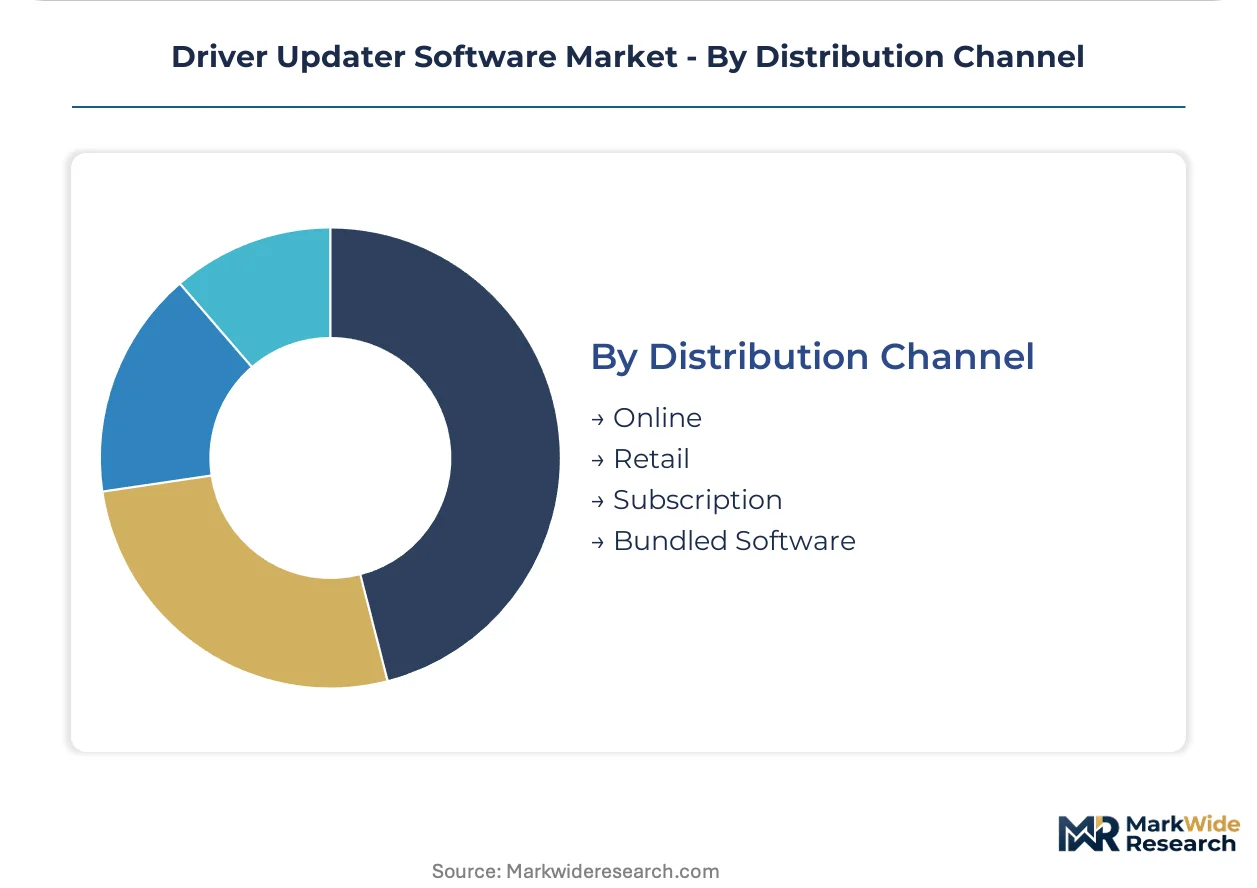
Distribution Channel:
Revenue recognition timing and customer acquisition costs vary dramatically between perpetual licenses and recurring subscription models.
- Subscription:Annual recurring revenue pools expand as continuous monitoring architectures displace perpetual licenses. EU AI Act compliance mandates create sticky renewal dynamics.
- Bundled Software:OEM pre-installation agreements with hardware manufacturers capture consumer segments at point-of-sale.
- Online:Direct digital distribution minimizes channel margin capture for vendor profitability.
- Retail:Physical box sales concentrate in emerging markets with limited credit card penetration.
Dominant revenue model: Subscription. Highest customer lifetime value: Bundled Software.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise IT spending on driver lifecycle management concentrates in Germany, the United States, and Japan, where complex device fleets and stringent compliance mandates sustain premium subscription pricing against freemium alternatives.
United States
Hospital systems undergoing HIPAA security rule compliance overhauls represent concentrated demand for managed driver services. FDA cybersecurity guidance for networked medical devices extends liability to driver integrity, pushing healthcare providers toward automated update platforms with immutable audit trails. The Greater Boston biotech corridor and Austin semiconductor clusters anchor specialized deployments for FDA-regulated hardware ecosystems.
Germany
Industrial IoT deployments in automotive and electronics manufacturing drive specialized driver lifecycle management for embedded systems. The Federal Office for Information Security incorporates EU AI Act audit requirements into federal procurement criteria, mandating documented driver provenance and consent mechanisms. Bavaria's automotive supplier network and Baden-Württemberg's machinery clusters absorb cloud-native fleet administration tools.
Japan
Manufacturing automation in automotive and electronics sectors requires specialized driver management for non-Windows embedded systems. METI industrial cybersecurity frameworks elevate driver integrity verification as a compliance checkpoint for connected factory equipment. The Chubu region around Nagoya and Kyushu's semiconductor fabrication facilities anchor enterprise subscription growth.
United Kingdom
Financial services security teams in London mandate continuous driver monitoring as a baseline zero-trust requirement. GDPR audit trail obligations compel vendors to document installation authorization and rollback capabilities for automated software distribution. The Southeast tech corridor and Edinburgh fintech cluster drive cloud-based deployment adoption.
India
IT support channel partners bundle driver tools with broader endpoint management suites for SME segments. BIS cybersecurity guidelines for critical infrastructure indirectly shape procurement criteria for automated patch management systems. Bangalore's technology services hub and Hyderabad's pharmaceutical manufacturing belt represent emerging subscription markets.
Driver Updater Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue freemium distribution and OEM bundling to anchor consumer-to-business upgrade funnels. The vendor base arranges across three strategic tiers: Windows-specialized incumbents with channel partnerships, Asia-Pacific freemium distributors scaling through volume, and cloud-native entrants targeting MSP contracts. Competitive moves concentrate on strategic partnerships with hardware manufacturers and portfolio diversification into continuous monitoring architectures.
Among Windows-specialized developers, Systweak Software occupies a position exemplifying channel-centric market presence, while IObit represents the freemium-distribution archetype across Asia-Pacific markets. Driver Easy anchors the cloud-native tier targeting remote fleet administration. These three companies illustrate the strategic divergence between bundling agreements, volume-driven consumer acquisition, and enterprise subscription migration.
| Leading Market Players |
|---|
| Systweak Software |
| IObit |
| Driver Easy |
| Driver Talent |
| Driver Checker |
| Avanquest Software |
| Rahim Soft |
| Fortect |
| WinZip Computing |
| Others |
Pricing and Supply Chain Analysis
Engineering talent costs for Windows driver architecture specialists flow from labor markets in Germany and the United States through subscription pricing tiers, compressing margins in economy segments while sustaining premium capture for continuous monitoring architectures.
Pricing Analysis
Volume concentrates in scheduled-update economy tiers where freemium competitors anchor consumer acquisition, while margin pools shift toward real-time scanning subscriptions commanding premium positioning. Price differentiation hinges on audit-trail certification levels satisfying EU AI Act mandates and deployment complexity across cloud-native versus on-premise architectures. Pricing pressure stems from Windows Update substitution eroding third-party differentiation in consumer segments. Individual users exhibit highest price sensitivity, whereas hospital systems and federal contractors demonstrate lowest sensitivity due to liability exposure and compliance mandates.
Supply Chain Analysis
Single-source vulnerability sits with proprietary driver delivery APIs from GPU and peripheral manufacturers concentrated in Taiwan, South Korea, and the United States. Software vendors draw from manufacturer API access, cloud infrastructure services, and cybersecurity audit tooling as core inputs. Supply chain risk centers on hardware vendor API fragmentation complicating universal scanning accuracy. Distribution runs through direct digital channels for enterprise contracts, OEM bundling agreements for consumer segments, and managed service provider intermediaries for healthcare and federal deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU AI Act audit trail mandates erect barrier-to-entry moats favoring vendors with pre-built provenance documentation capabilities.
For Market Incumbents: Anticipate MSP contract consolidation compressing vendor counts by deepening vertical integration into cloud-native continuous monitoring architectures. OEM bundling channel control and AI-powered conflict resolution R&D investment defend against freemium entrants eroding consumer-to-business upgrade funnels. For New Entrants and Emerging Players: Direct digital distribution routes unlock white-space penetration in Japan's manufacturing automation sector and India's SME IT support channel. Japan's industrial IoT embedded systems segment offers lowest competitive density, while freemium-to-subscription conversion models anchor Asia-Pacific go-to-market positioning. For Investors and Strategic Acquirers: FDA cybersecurity guidance publication for networked medical devices is the leading indicator that hospital system procurement will accelerate toward managed driver services with immutable audit capabilities. Long-term viability favors cloud-native platforms with zero-trust security framework integration. Acquisition targets should demonstrate EU AI Act-compliant provenance logging. MSP contract win announcements signal inflection toward enterprise subscription stickiness.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding driver management into zero-trust security frameworks satisfies German Federal Office for Information Security procurement criteria. |
| Strategic Partnership | OEM bundling agreements with hardware manufacturers capture consumer segments at point-of-sale with lowest acquisition cost. |
| Acquisition of Specialist Firm | Buying AI-powered conflict resolution capabilities reduces enterprise support ticket volume and deepens subscription renewal rates. |
| Geographic Expansion | Japan's METI industrial cybersecurity frameworks elevate driver integrity verification as compliance checkpoint for factory equipment. |
| Product Launch | Cloud-native continuous monitoring architectures absorb IT capital previously allocated to on-premise patch management infrastructure. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs combining primary interviews with IT procurement officers, MSP contract managers, platform engineers, and channel partners. FDA guidance documents, EU AI Act implementation texts, NIST framework publications, and hyperscaler capex disclosures provided validation layers. Bottom-up segment sizing and top-down macro constraint triangulation cross-checked volume and value estimates.
Data-stream reconciliation across deployment model, organization size, vertical industry, and regional adoption pattern dimensions shaped the analytical framework. CAGRs derived from segment-level growth rate interpolation across the analysis window. Forecast inputs incorporated MSP contract velocity, EU AI Act compliance timeline acceleration, and Windows end-of-life transition pacing.
The model holds under sustained regulatory enforcement of EU AI Act and FDA cybersecurity guidance; deviation in harmonization timing or hardware vendor API standardization would shift subscription conversion trajectories. Forecasts reflect documented assumptions about compliance cost pass-through and cloud infrastructure cost curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Software-Defined Machine Market
Software & Services
Asia-Pacific ERP Software Market
Software & Services
Asia-Pacific Accounting Software Market
Software & Services
Enterprise Intellectual Property (IP) Management Software Market
Software & Services
Global Charity Accounting Software Market
Software & Services
Home Design Software Market
Software & Services
Contract Abstraction Software Market
Software & Services
Payroll - HR Solutions and Services Market
Software & Services
Software Release Management Tools Market
Software & Services
Enterprise Resource Planning (ERP) Software Market
Software & Services
Dental Practice Management Software Market
Software & Services
3D Animation Software Market
Software & Services
Middle East and Africa Workforce Management Software Market
Software & Services
Service Resource Planning (SRP) Saas Solutions Market
Software & Services
Construction Equipment Fleet Management Software Market
Software & Services
Global SAP S-4HANA Application Market