
 Global Managed File Transfer Software Market | 2026-2036
Global Managed File Transfer Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Managed File Transfer Software Market Outlook
The managed file transfer software market is restructuring around a widening capability gap between enterprise-grade platforms with embedded governance and lightweight cloud utilities lacking centralized policy enforcement. IBM Aspera leverages its high-speed transfer protocol to dominate media and entertainment workflows requiring terabyte-scale movement. GoAnywhere MFT sustains its position through deep integration with legacy enterprise resource planning systems in regulated industries. Axway Managed File Transfer differentiates via API-centric architectures that bridge modern microservices with mainframe-era batch processes.
Managed file transfer software encompasses enterprise solutions that automate, secure, and audit the movement of structured and unstructured data across heterogeneous networks, typically supporting protocols such as SFTP, FTPS, AS2, and HTTPS with AES-256 encryption at rest and in transit. Its primary commercial purpose is to replace ad-hoc consumer file-sharing tools with auditable, policy-driven pipelines that satisfy data residency and chain-of-custody requirements. Cloud-based deployment is capturing the fastest expansion as organizations retire on-premises data centers, though hybrid configurations retain the deepest margin pools where customers demand local encryption gateways paired with elastic cloud bursting. File security solutions within the solution type dimension command premium pricing due to mandatory breach-notification statutes across multiple jurisdictions.
The US HIPAA Security Rule and the EU GDPR jointly shape product roadmaps by mandating access logging, encryption standards, and data localization controls that only purpose-built MFT platforms reliably satisfy. Japan's METI guidelines on cross-border data flows add a third compliance vector for vendors serving multinational manufacturing clients. Stakeholders must monitor whether emerging quantum-resistant encryption standards prompt premature replacement cycles in high-sensitivity installations.
Market Dynamics
The managed file transfer software market is bifurcating around a governance-capability divide, where platforms with embedded compliance automation capture regulated industries while lightweight utilities serve low-stakes workflows.
Growth Catalysts
- GDPR and EU AI Act mandates:Breach-notification statutes and algorithmic accountability rules require auditable data lineage that only purpose-built MFT platforms deliver.
- Healthcare data exchange:HIPAA Security Rule enforcement drives hospital systems to replace consumer file-sharing tools with encrypted, access-logged transfer infrastructure.
- Industrial automation clusters:Germany's automotive supply chains demand high-throughput managed file transfer to synchronize just-in-time manufacturing across tiered supplier networks.
Market Restraints
- Encryption gateway hardware costs:On-premises deployment requires dedicated appliances for AES-256 processing, elevating total cost of ownership versus cloud-native alternatives.
- Legacy ERP integration complexity:Mainframe-era batch processes resist API-centric connectivity, extending implementation timelines and professional services dependency.
- Skills concentration in cybersecurity:Shortage of personnel certified in secure protocol configuration (SFTP, AS2, FTPS) constrains enterprise deployment velocity.
Strategic Opportunities
- Hybrid cloud bursting architectures:Elastic cloud capacity paired with local encryption gateways addresses data residency requirements in financial services and government.
- Quantum-resistant encryption migration:NIST post-quantum cryptographic standards create replacement-cycle demand in defense and intelligence installations.
- API-microservices bridging:Axway and competitors enable real-time data flows between containerized applications and mainframe systems, capturing digital transformation budgets.
Industry Challenges
- Multi-jurisdiction compliance stacking:Simultaneous adherence to HIPAA, GDPR, and Japan METI cross-border guidelines requires configurable policy engines that few vendors have perfected.
- Protocol standardization fragmentation:Competing secure transfer standards (SFTP, FTPS, AS4, HTTPS) force customers to maintain multiple client implementations, elevating support overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Managed File Transfer Software Market |
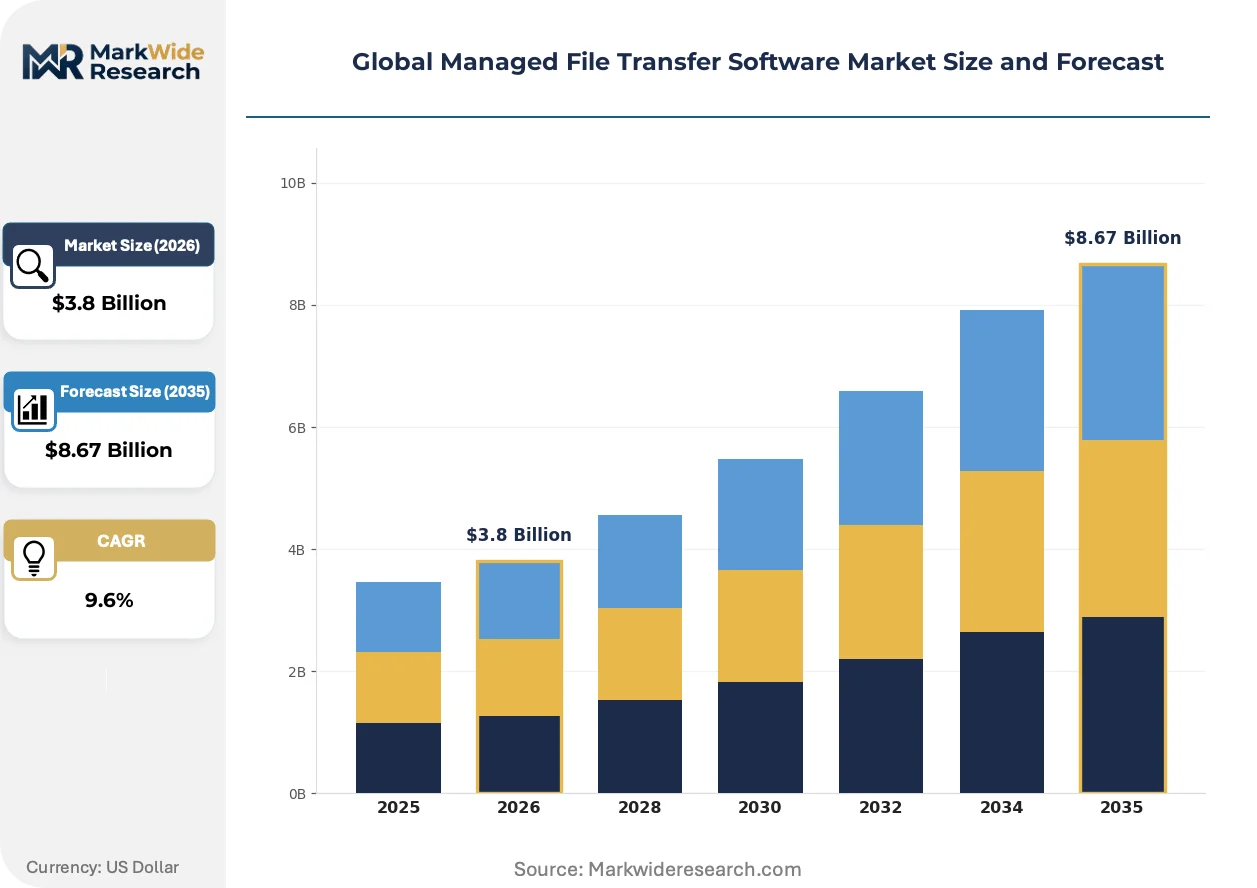
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.67 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud-Based, Hybrid, Private Cloud End User: Healthcare, BFSI, Telecommunications, Government Solution Type: File Security, File Transfer Automation, File Sharing, Integration Services Industry Vertical: Retail, Manufacturing, Education, Media |
| Companies Covered | IBM Aspera, Citrix ShareFile, GoAnywhere MFT, Diplomat MFT, Signiant Media Shuttle, Axway Managed File Transfer, Globalscape EFT, JSCAPE MFT Server, Progress MOVEit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Managed File Transfer Software Market Strategic Shifts
Zero-trust security architectures are electrifying product roadmaps across the managed file transfer landscape, compressing deployment models and redefining vendor evaluation criteria.
Post-quantum cryptographic modules are electrifying high-sensitivity installations, with NIST-standardized algorithms replacing RSA and elliptic-curve implementations in defense, healthcare, and financial services deployments. Government agencies and critical infrastructure operators are accelerating procurement cycles to preempt harvest-now-decrypt-later threats. This migration is compressing replacement timelines and elevating certification requirements that disqualify legacy platforms lacking algorithmic agility.
REACH and EU AI Act compliance obligations are forcing chemical and pharmaceutical manufacturers to implement immutable audit trails for every data exchange touching regulated substances or algorithmic decision systems. The European Medicines Agency's data integrity guidelines now explicitly reference secure transfer protocols with chain-of-custody documentation. German automotive suppliers are responding by mandating AS4 connectivity with embedded digital signatures across their tiered supply networks.
Consumption-based licensing models are displacing perpetual seat-based contracts as cloud-native MFT platforms penetrate mid-market accounts previously priced out of enterprise solutions. Channel partners are unbundling implementation and managed security services from core software subscriptions, creating new revenue pools in compliance consulting. This shift is most visible in US healthcare, where hospital systems favor operational expenditure treatment for cybersecurity infrastructure under constrained capital budgets.
Global Managed File Transfer Software Market Segmentation
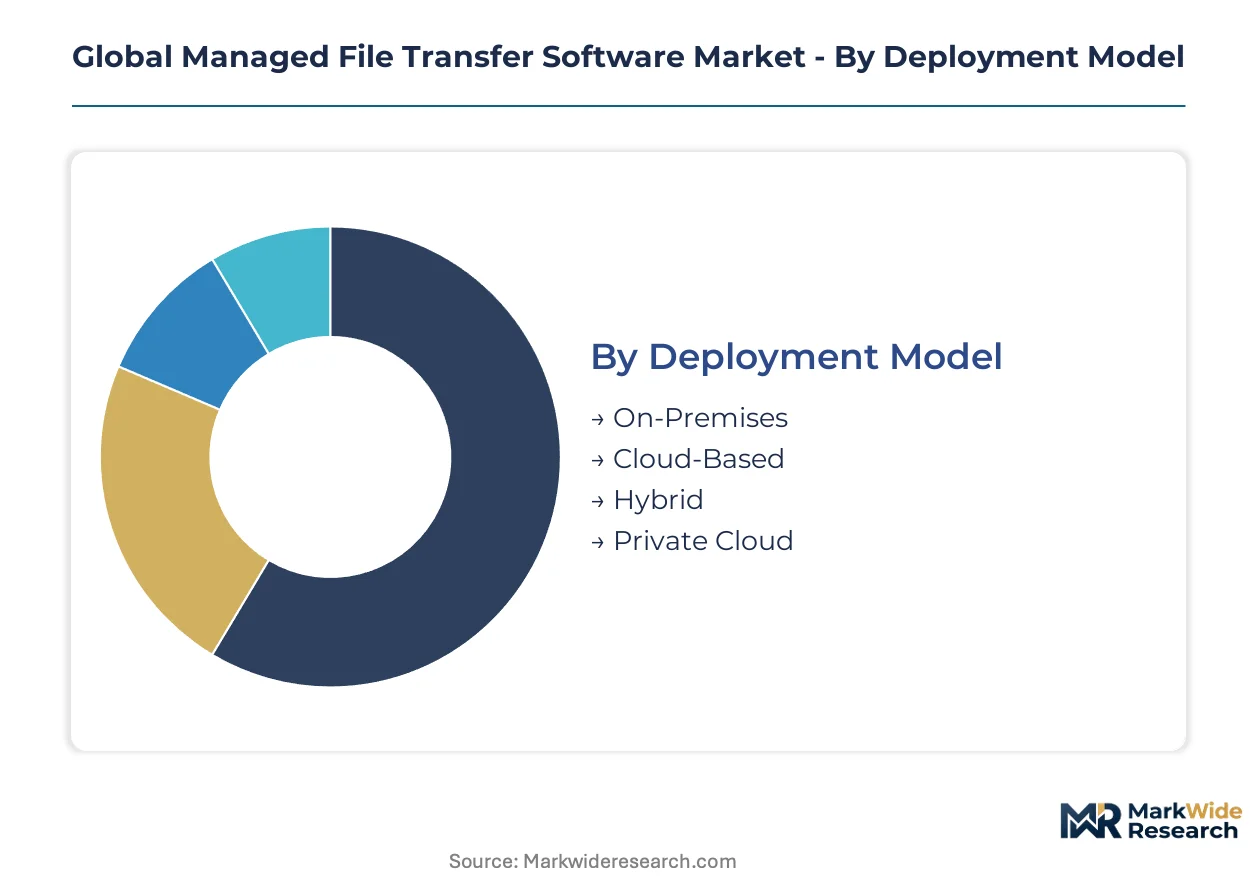
Segmentation in managed file transfer software reveals how compliance burden, infrastructure maturity, and data sensitivity reshape procurement patterns across deployment models and end-use verticals. Certification requirements from HIPAA, GDPR, and sector-specific regulators fragment the addressable market into tiers with radically different technical specifications and pricing power.
Deployment Model:
HIPAA Security Rule and GDPR data-localization mandates force distinct certification pathways across deployment architectures, with on-premises installations requiring hardware-based encryption validation while cloud variants face ISO 27001 and SOC 2 Type II scrutiny.
- On-Premises:Dedicated infrastructure with local AES-256 encryption gateways satisfies HIPAA and GDPR data-residency requirements. Demand concentrates in German automotive supply chains and US hospital systems where audit trails must remain within jurisdictional boundaries.
- Cloud-Based:Elastic capacity with shared-tenancy encryption serves mid-market healthcare and retail with constrained capital budgets. Consumption-based licensing accelerates fastest in US hospital systems replacing legacy FTP servers.
- Hybrid:Local encryption paired with cloud bursting addresses financial services data-residency rules. Japanese manufacturing clients under METI cross-border guidelines favor this architecture for regional data sovereignty.
- Private Cloud:Single-tenant dedicated instances serve defense and intelligence with NIST post-quantum cryptographic requirements. Government procurement cycles dominate this segment.
Leading the category by volume: Cloud-Based. Growing fastest: Hybrid.
End User:
Regulatory enforcement intensity varies sharply across end-user categories, with HIPAA and EU AI Act penalties driving replacement cycles in healthcare while BFSI faces overlapping SEC, FINRA, and GDPR obligations.
- Healthcare:HIPAA Security Rule breach-notification statutes mandate encrypted, access-logged transfer infrastructure replacing consumer file-sharing tools. US hospital systems under OCR enforcement pressure represent concentrated demand.
- BFSI:Overlapping SEC record-keeping, FINRA surveillance, and GDPR data-lineage requirements demand immutable audit trails. Swiss private banking and German commercial lenders lead procurement.
- Telecommunications:FCC net-neutrality documentation and GDPR subscriber-data portability rules drive API-centric MFT adoption. Tower-sharing agreements between European operators require standardized AS4 connectivity.
- Government:NIST post-quantum cryptographic standards and FedRAMP authorization compress replacement timelines. Defense and civilian agencies maintain separate procurement streams.
Dominating procurement volume: Healthcare. Expanding most quickly: Government.
Solution Type:
Margin structures diverge across solution types based on mandatory breach-notification exposure, with file security commanding premium pricing due to statutory liability while automation tools compete on operational efficiency metrics.
- File Security:AES-256 encryption at rest and in transit with tamper-evident logging satisfies HIPAA, GDPR, and EU AI Act chain-of-custody requirements. Premium pricing persists in pharmaceutical manufacturing under EMA data-integrity guidelines.
- File Transfer Automation:Scheduled batch processing with exception handling replaces legacy mainframe FTP scripts. German automotive tier-1 suppliers use this for just-in-time inventory synchronization.
- File Sharing:Ad-hoc collaboration tools with policy-enforced expiration and watermarking displace consumer Dropbox deployments. US healthcare clinics favor this for physician-to-physician case consultation.
- Integration Services:API gateways bridging microservices and mainframe systems capture digital transformation budgets. Axway and competitors target this segment for ERP modernization projects.
Highest revenue concentration: File Security. Steepest expansion trajectory: Integration Services.
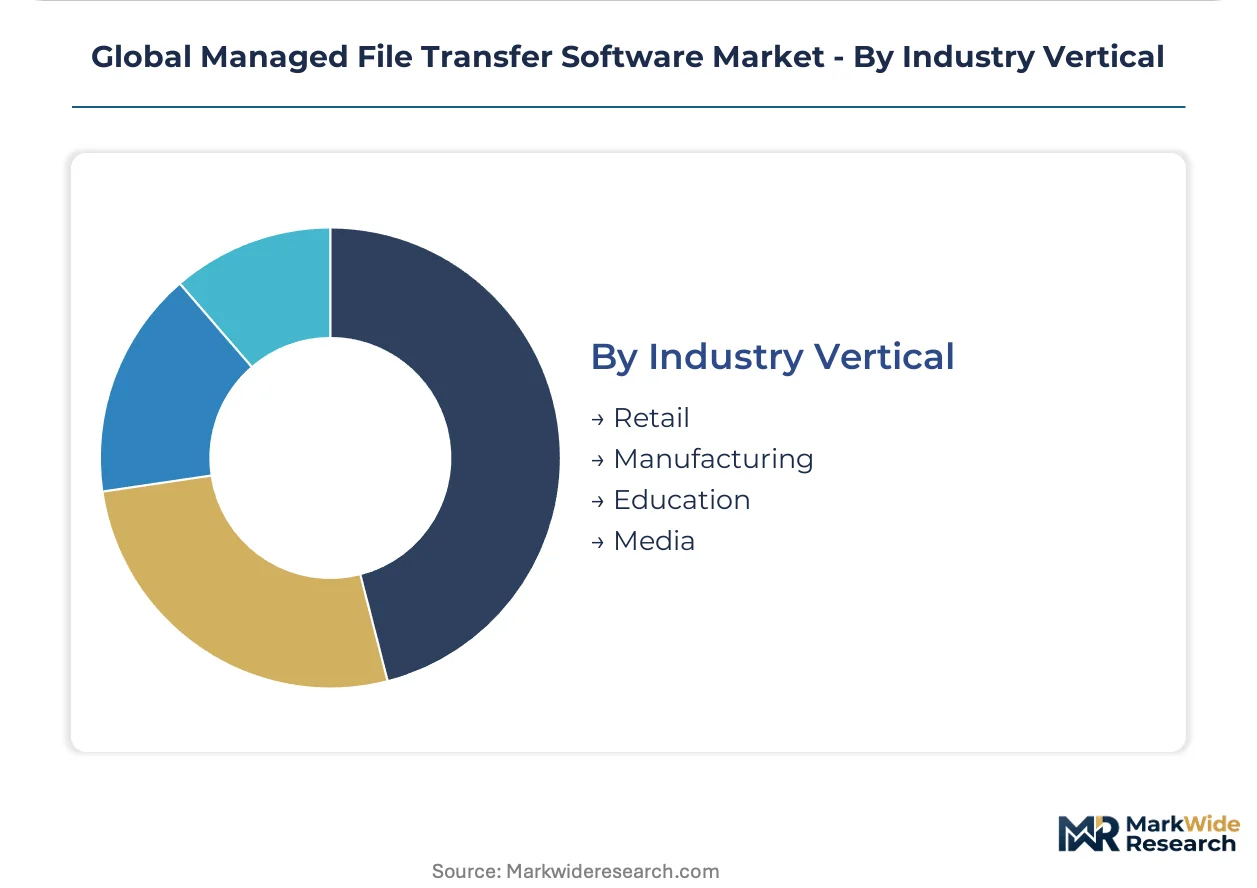
Industry Vertical:
Supply-chain digitization maturity and regulatory exposure create tiered demand patterns, with retail and manufacturing prioritizing throughput velocity while education and media emphasize cost containment.
- Retail:High-frequency inventory synchronization between distribution centers and e-commerce platforms demands low-latency transfer protocols. US omnichannel retailers under PCI-DSS pressure drive cloud-native adoption.
- Manufacturing:AS4 connectivity with embedded digital signatures satisfies German automotive OEM mandates for tiered supplier traceability. REACH compliance documentation for chemical inputs requires immutable audit trails.
- Education:FERPA-protected student records and research-data sharing with limited IT budgets favor lightweight cloud solutions. US public university systems consolidate ad-hoc tools into centralized MFT platforms.
- Media:Terabyte-scale raw footage movement requires high-throughput protocols like IBM Aspera's FASP. Hollywood studios and post-production houses in Los Angeles and London dominate this segment.
Largest addressable base: Manufacturing. Gaining share fastest: Media.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors terabyte-scale media workflows where Hollywood studios and post-production houses demand high-throughput protocols for raw footage movement. Stuttgart and Wolfsburg industrial corridors synchronize just-in-time automotive supply chains through AS4 connectivity with embedded digital signatures. Tokyo's metropolitan data centers process cross-border manufacturing flows under METI guidelines.
United States
US hospital systems under OCR enforcement pressure replace consumer file-sharing tools with encrypted, access-logged transfer infrastructure. HIPAA Security Rule breach-notification statutes mandate immutable audit trails for patient data exchange. Los Angeles media clusters and Boston healthcare networks drive divergent procurement patterns for high-throughput versus compliance-heavy deployments.
Germany
German automotive OEMs mandate AS4 connectivity across tiered supplier networks for traceability and REACH compliance documentation. EU AI Act algorithmic accountability rules require auditable data lineage that purpose-built MFT platforms deliver. Stuttgart and Wolfsburg industrial corridors concentrate demand for high-throughput infrastructure synchronizing just-in-time manufacturing.
Japan
Japanese manufacturing clients under METI cross-border data flow guidelines favor hybrid architectures for regional data sovereignty. NIST post-quantum cryptographic standards accelerate procurement cycles in defense and intelligence installations. Tokyo metropolitan data centers and Osaka industrial zones process sensitive flows between multinational manufacturing headquarters and regional facilities.
United Kingdom
UK financial services face overlapping SEC record-keeping, FINRA surveillance, and GDPR data-lineage requirements demanding immutable audit trails. Swiss private banking and German commercial lenders influence procurement patterns for London-based institutions. The City of London and Canary Wharf clusters drive API-centric adoption for real-time trading data flows.
India
Indian IT services hubs support global enterprise MFT deployments through remote management and compliance consulting capabilities. BIS certification requirements and RBI data-localization mandates shape product specifications for domestic financial institutions. Bangalore and Hyderabad technology corridors host implementation partners serving multinational healthcare and BFSI clients.
Global Managed File Transfer Software Market Competitive Environment
Capital-heavy producers compete with asset-light designers across a bifurcated vendor landscape where governance-capability divides determine competitive positioning. The market consolidates around three strategic archetypes: high-speed protocol specialists serving media workflows, compliance-embedded platforms capturing regulated industries, and API-centric bridges modernizing legacy ERP connectivity. Dominant competitive moves include strategic partnerships with cloud hyperscalers and portfolio diversification into adjacent cybersecurity segments.
Within the high-throughput media tier, IBM Aspera and Signiant Media Shuttle exemplify protocol-optimized positioning for terabyte-scale entertainment workflows. GoAnywhere MFT and Axway Managed File Transfer occupy the compliance-automation archetype, anchoring regulated-industry deployments with embedded governance engines. These four entities collectively represent the capability spectrum from raw performance velocity to policy-driven audit rigor.
| Leading Market Players |
|---|
| IBM Aspera |
| Citrix ShareFile |
| GoAnywhere MFT |
| Diplomat MFT |
| Signiant Media Shuttle |
| Axway Managed File Transfer |
| Globalscape EFT |
| JSCAPE MFT Server |
| Progress MOVEit |
| Others |
Value Chain & Pricing Dynamics
Encryption gateway hardware costs cascade through pricing tiers as on-premises AES-256 processing appliances anchor premium deployments while cloud-native alternatives strip out capital expenditure burdens for mid-market buyers.
Pricing Analysis
Throughput-based pricing anchors enterprise contracts, with terabyte-scale transfer volumes commanding subscription premiums against seat-based models serving smaller healthcare clinics. Price differentiation hinges on certification grade—FedRAMP authorization and ISO 27001 validation separate premium tiers from standard offerings—and vertical integration depth where bundled compliance consulting elevates contract value. Cost compression in cloud-native tiers is intensifying because hyperscaler infrastructure commoditizes storage and compute, forcing pure-play vendors toward hybrid positioning. Hospital systems under capital budget constraints exhibit highest price sensitivity, while defense installations prioritize cryptographic agility over unit economics.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Japan anchor hub-and-spoke delivery patterns for encryption hardware and professional services deployment. Software licensing draws from Ireland's data center cluster for EU regulatory coverage, Singapore for Asia-Pacific latency optimization, and Virginia for FedRAMP proximity. Single-source vulnerability concentrates in NIST-certified cryptographic module suppliers, where post-quantum algorithm validation creates certification bottlenecks. Distribution runs through value-added resellers and systems integrators who bundle implementation with ongoing managed security services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
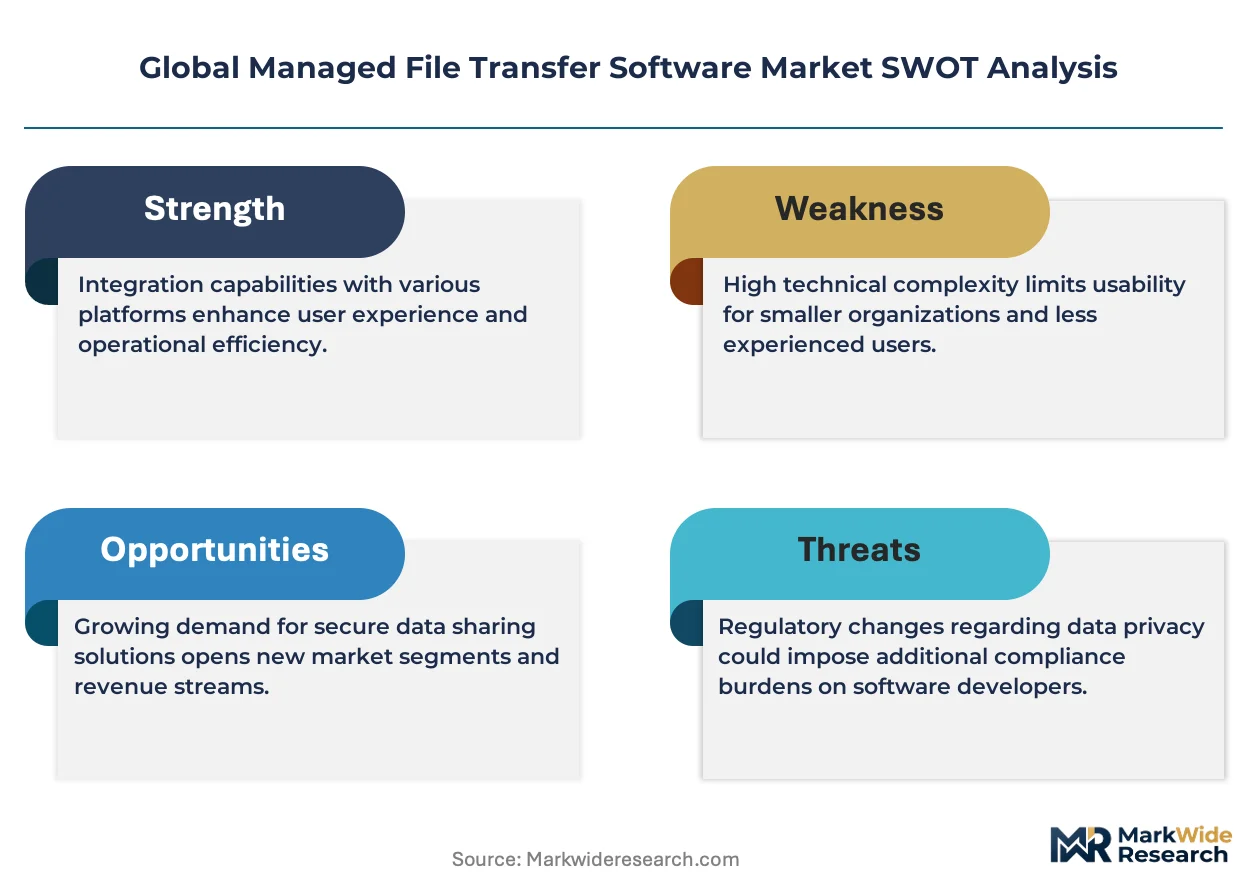
This market consolidates around compliance-automation capabilities, with multi-jurisdiction policy engine complexity forcing subscale vendors toward acquisition or exit.
For Market Incumbents: Acquire post-quantum cryptographic certification assets to preempt defense procurement cycles and anchor replacement demand. Deepen API-microservices bridging capabilities to capture ERP modernization budgets, while embedding EU AI Act audit trail automation to defend against lightweight cloud utilities lacking governance depth. Threat substitution from consumer-grade file-sharing tools with policy wrappers demands continuous compliance differentiation. For New Entrants and Emerging Players: Channel partners specializing in healthcare IT security represent the fastest path to scaled distribution. White-space concentrates in mid-market US hospital systems retiring legacy FTP infrastructure, where consumption-based SaaS pricing penetrates accounts previously priced out of enterprise platforms. Go-to-market should emphasize HIPAA Security Rule audit preparedness as the immediate procurement trigger. For Investors and Strategic Acquirers: NIST post-quantum cryptographic standard finalization is the leading indicator that defense and intelligence replacement cycles will accelerate, compressing valuation multiples for algorithmically agile targets. Long-term viability favors platforms with embedded governance engines over point-solution transfer utilities. Acquisition target archetype: compliance-embedded vendors with existing FedRAMP authorization and healthcare customer concentration. Signal to watch: government procurement bulletins referencing quantum-resistant requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Cryptographic Migration | NIST standardization creates replacement demand in defense and healthcare installations requiring algorithmic agility. |
| Hybrid Cloud Bursting Architecture | Local encryption gateways paired with elastic cloud capacity satisfy financial services data-residency requirements. |
| API-Microservices Bridge Development | Real-time data flows between containerized applications and mainframe systems capture digital transformation budgets. |
| Consumption-Based Licensing Transition | Operational expenditure treatment attracts hospital systems under constrained capital budgets. |
| Multi-Jurisdiction Policy Engine Investment | Configurable compliance automation addresses simultaneous HIPAA, GDPR, and METI adherence requirements. |
Study Parameters
Independent corroboration across CTO interviews, IT procurement officer surveys, and channel partner assessments underwrites the qualitative findings in this study. Primary fieldwork engaged platform engineers, integration specialists, and managed security service providers across deployment scenarios. Secondary validation drew from SEC filings of publicly traded vendors, hyperscaler capex disclosures revealing infrastructure investment patterns, and ISO 27001 certification databases tracking compliance posture. Bottom-up sizing of individual vendor revenues triangulates against top-down addressable market estimates derived from enterprise software spending benchmarks.
Rate-of-change decomposition separates volume expansion from value migration across deployment models, organization size tiers, vertical industries, integration complexity levels, and regional adoption patterns. CAGRs emerge from segment-level growth rate aggregation weighted by current revenue concentration. Forecast inputs include HIPAA enforcement action frequency, EU AI Act implementation timelines, and NIST post-quantum cryptographic standard adoption curves across the projection horizon.
Several conditions sit outside the modeled scope, including vendor-specific product roadmap execution, hyperscaler entry into native MFT services, and unforeseen regulatory harmonization between jurisdictions. Forecasts reflect documented assumptions about compliance burden trajectory and cloud migration velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Time and Attendance Management Software Market
Software & Services
Global Servicenow Store Apps Market
Software & Services
General Ledger Accounting Software Market
Software & Services
Web Development Market
Software & Services
Non-Profit Software Market
Software & Services
Construction Software As A Service Market
Software & Services
Europe Pharmacy POS Software Market
Software & Services
Global Core Human Resource Software Market
Software & Services
Computer Backup Software Market
Software & Services
Family Law Software Market
Software & Services
Global Portal Software Market
Software & Services
North America Restaurant Management Software Market
Software & Services
School Timetable Software Market
Software & Services
Global Architecture Software Market
Software & Services
Global Sales Engagement Platform Market
Software & Services
Over-The-Air Software Update Market