
 Global ITSM Software Market | 2026-2036
Global ITSM Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global ITSM Software Market Foresight
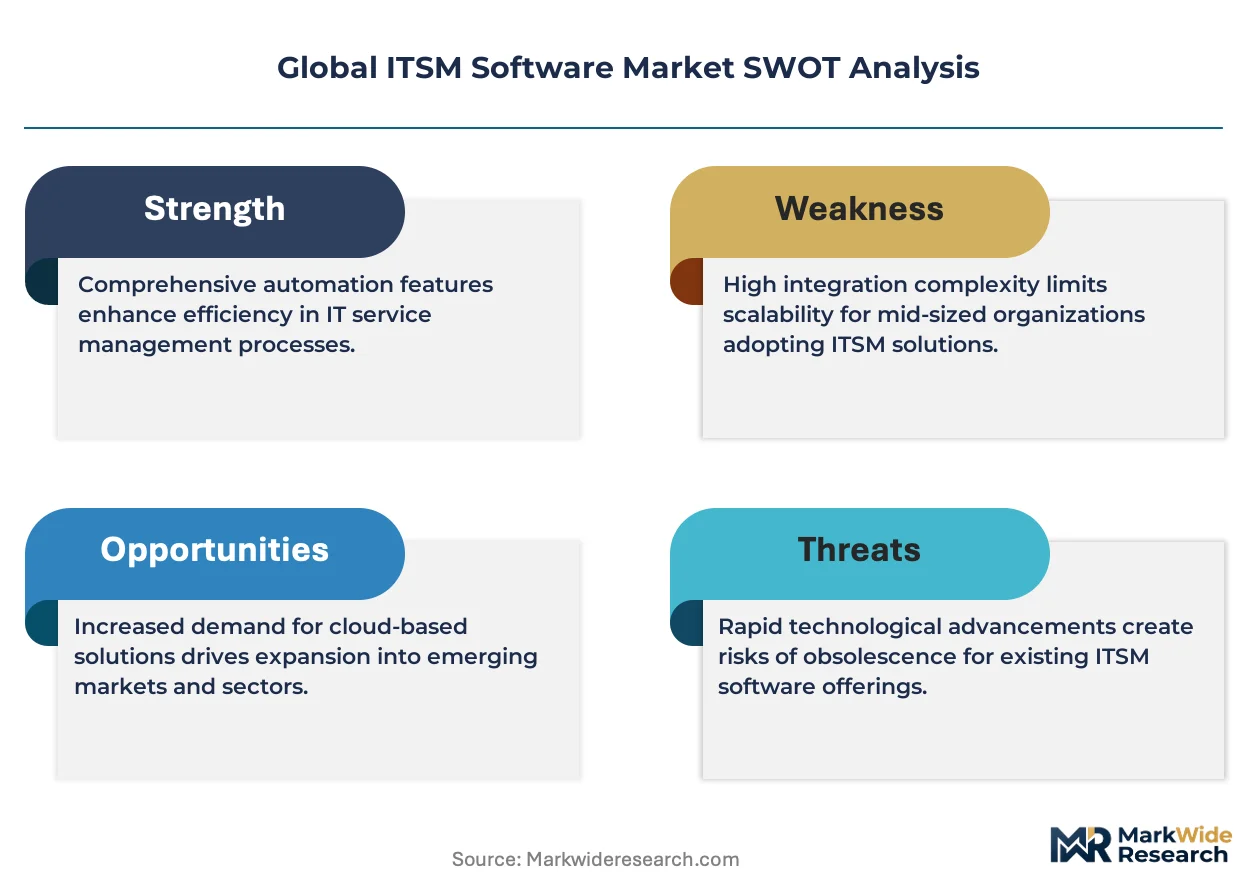
Convergence between IT service management and AI-driven automation is narrowing the gap between incident detection and autonomous resolution. ServiceNow leverages its workflow engine dominance to anchor enterprise accounts seeking unified platform architectures. BMC Software competes through deep mainframe and hybrid infrastructure specialization, while Freshworks sustains momentum among mid-market buyers with simplified deployment models.
ITSM software encompasses integrated platforms that orchestrate service delivery through ticket routing, asset tracking, and SLA enforcement, typically exposing REST APIs and CMDB federation protocols to interoperate with monitoring stacks. The primary commercial purpose is reducing mean time to resolution while maintaining audit trails for compliance accountability. Cloud deployment now captures the fastest expansion trajectory as organizations retire on-premises footprints, though incident management retains the largest margin pool due to its position as the entry-point solution category. Change management is gaining share among regulated industries where CAB automation reduces approval cycle friction.
FDA 21 CFR Part 11, EU GDPR, and ISO 20000 collectively shape product roadmaps by mandating immutable audit logs, data residency controls, and certified process frameworks. HIPAA and SEC record-keeping rules extend these requirements to healthcare and financial services buyers, forcing vendors to maintain multi-tenant isolation architectures. Stakeholders must weigh sovereign cloud requirements against platform consolidation economics as jurisdictional data rules proliferate.
Market Dynamics
AI-driven automation is compressing resolution timelines and forcing vendors to rearchitect platforms around autonomous workflow engines rather than ticket-centric interfaces. This structural shift rewards unified-platform providers while fragmenting point-solution specialists.
Growth Catalysts
- EU AI Act compliance mandates:European enterprises must deploy automated audit trails and decision-logging capabilities, accelerating replacement of legacy ticketing systems with AI-native platforms.
- Hybrid infrastructure complexity:Financial services firms operating across on-premises mainframes and multi-cloud environments require federated CMDB architectures that unified ITSM platforms uniquely deliver.
- Germany's industrial digitization:Manufacturing conglomerates in Baden-Württemberg and Bavaria are procuring premium ITSM suites to orchestrate Industry 4.0 service operations at scale.
Market Restraints
- Implementation cost barriers:Enterprise-grade ITSM deployments require 18-24 month integration cycles with specialized systems integrators, freezing out mid-market buyers.
- Cloud concentration risk:Hyperscaler infrastructure dependencies in Ireland and Frankfurt create single-point-of-failure exposure for EU data residency requirements.
- Skills scarcity:Certified ITIL 4 practitioners command premium compensation, constraining internal platform administration capacity.
Strategic Opportunities
- Sovereign cloud expansion:France's ANSSI-certified cloud zones and Germany's Gaia-X infrastructure create compliant deployment venues for security-conscious buyers.
- Healthcare ITSM penetration:HIPAA-covered entities remain underpenetrated for automated change management, presenting greenfield expansion potential.
- Edge-to-core convergence:Integration between ITSM platforms and IoT device management stacks opens new service orchestration revenue pools.
Industry Challenges
- Legacy system entanglement:Mainframe-based incident management workflows resist API-based modernization, prolonging hybrid operation periods.
- Multi-framework compliance:Simultaneous ISO 20000, SOC 2, and GDPR audits create documentation overhead that strains platform configurability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global ITSM Software Market |
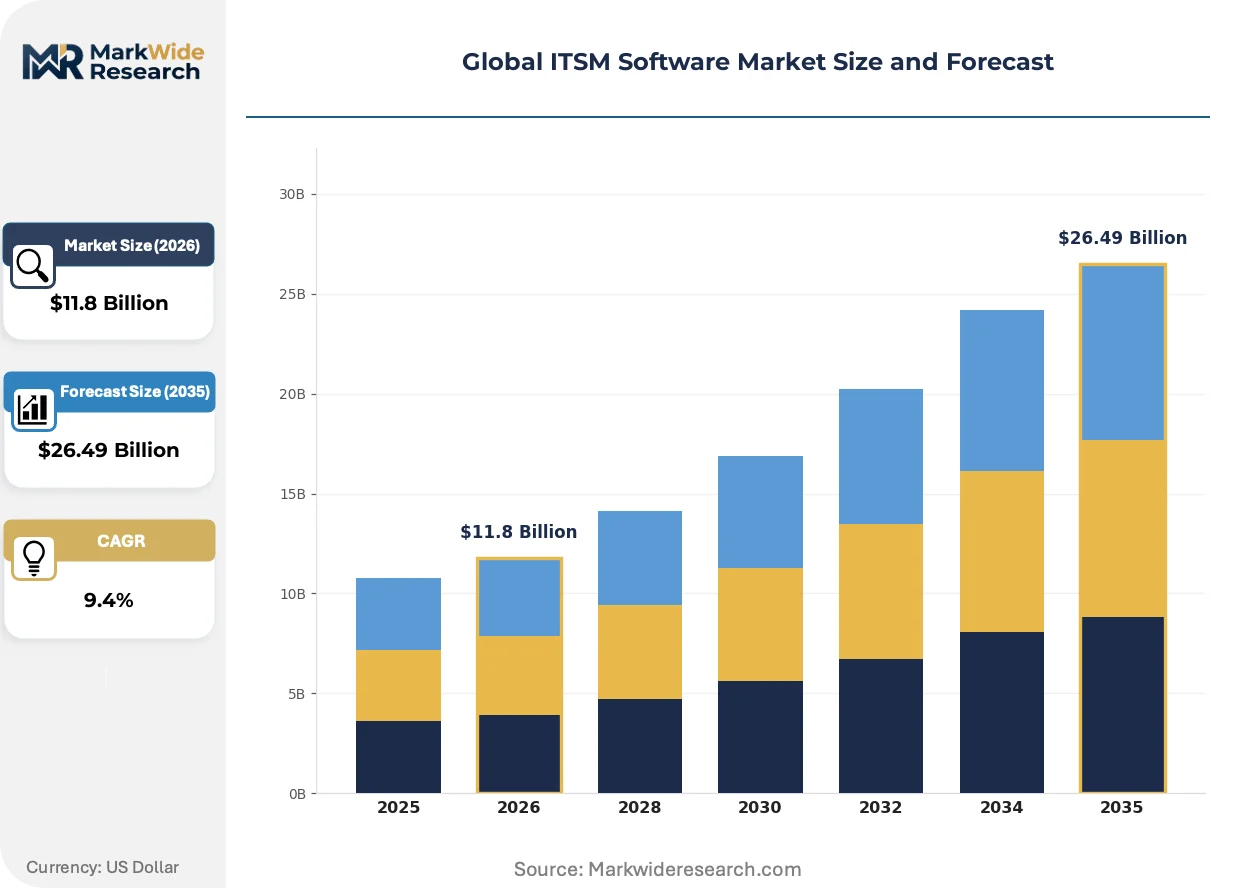
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $26.49 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud, Hybrid, Managed Services Solution Offering: Incident Management, Change Management, Asset Management, Problem Management, Service Catalog Application: Customer Support, IT Operations, Compliance Management, Knowledge Management, SLA Management End User Industry: Telecommunications, Education, Government Agencies, Manufacturing, Transportation |
| Companies Covered | ServiceNow, Atlassian, BMC Software, GoTo, Ivanti, Broadcom, Microsoft, Freshworks, ManageEngine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global ITSM Software Market Shifts & Advancements
Agentic AI architectures are displacing rules-based automation, enabling platforms to execute remediation sequences without human approval loops. This capability divergence is separating next-generation vendors from workflow-heritage incumbents.
Generative AI copilots embedded within ITSM interfaces are digitizing tier-1 support interactions previously handled by human agents. Large healthcare systems in the United States are deploying these tools to deflect password resets and access provisioning requests. The technology is digitizing first-line response capacity while compressing headcount expansion plans.
EU GDPR Article 32 security requirements and FDA 21 CFR Part 11 electronic record rules are mandating immutable audit architectures with cryptographic verification. Vendors must engineer tamper-evident logging layers that satisfy both European data protection authorities and US healthcare regulators. Financial services buyers in London and New York are prioritizing platforms with pre-certified compliance modules to accelerate procurement cycles.
Subscription-to-outcome contracting is replacing seat-based pricing in enterprise renewals. Buyers in Australia's banking sector now demand MTTR guarantees and availability credits written into master service agreements. This shift transfers operational risk to vendors and rewards predictive analytics investments over feature breadth.
Global ITSM Software Market Segmentation
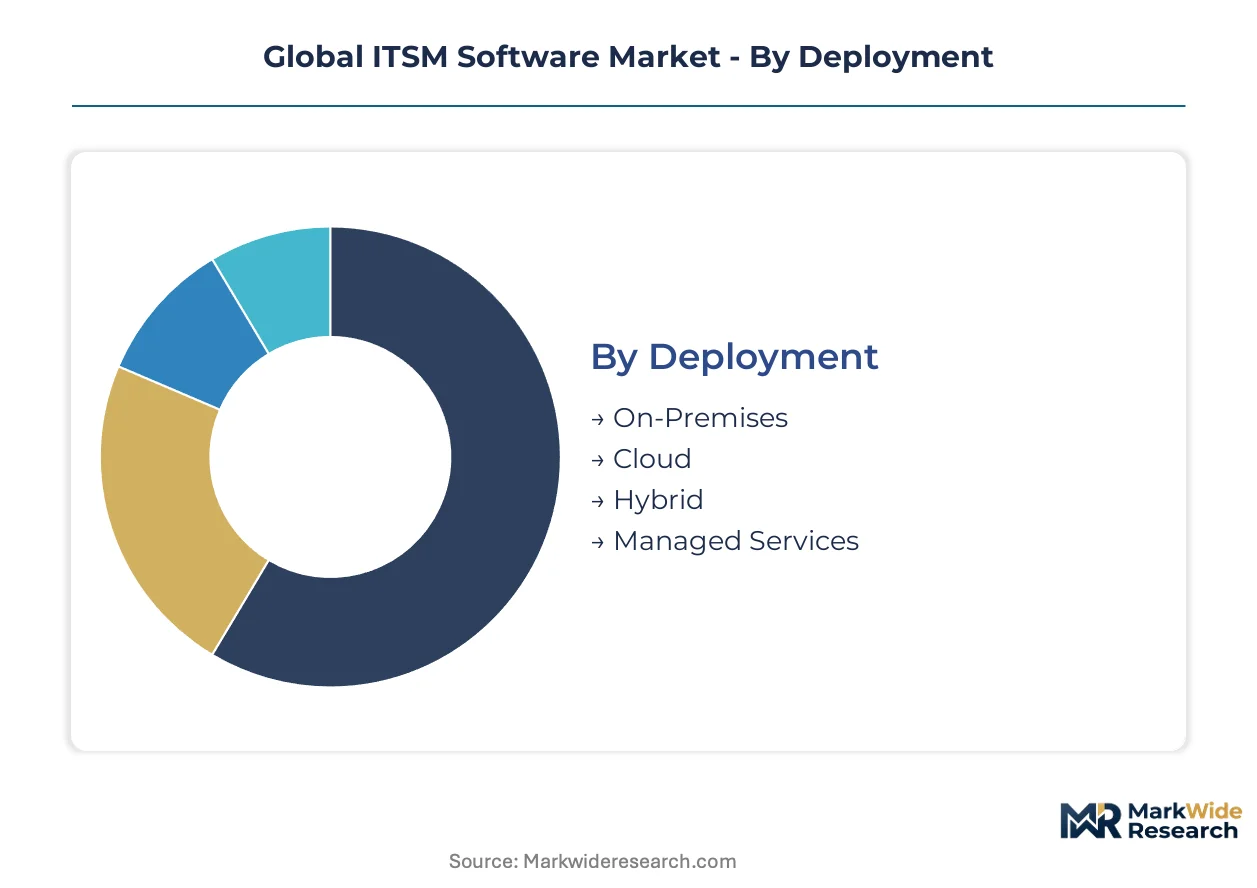
ITSM software segmentation reveals how deployment architectures, solution depth, and industry-specific compliance requirements create distinct purchasing patterns. Buyers select configurations based on data sovereignty constraints, integration complexity, and regulatory exposure rather than feature checklists alone.
Deployment:
Deployment choice maps directly to data residency mandates and legacy infrastructure entanglement across the use-case spectrum.
- Cloud:Multi-tenant SaaS architectures with automatic patching and elastic scaling dominate among organizations retiring capital-intensive data center footprints. Financial services firms in Singapore and Australia's banking sector prioritize cloud deployment to satisfy APRA CPS 234 and MAS TRM-G1 guidelines while accelerating provisioning cycles.
- On-Premises:Self-hosted installations maintain air-gapped environments for classified government networks and defense contractors requiring CMMC Level 3 compliance. German automotive manufacturers in Stuttgart and Wolfsburg retain on-premises stacks to satisfy TISAX information security audits for supplier data protection.
- Hybrid:Split workloads between private infrastructure and public cloud zones accommodate phased migration timelines without service disruption. Healthcare systems in the United States deploy hybrid models to keep PHI within HIPAA-compliant local instances while leveraging cloud analytics for population health dashboards.
- Managed Services:Third-party operated platforms outsource administrative overhead to specialized providers with ISO 20000-certified process frameworks. Mid-market enterprises in Canada contract managed ITSM to bypass ITIL skills scarcity without building internal competency centers.
The dominant share belongs to Cloud deployment, while Hybrid architectures are closing the gap fastest as organizations sequence retirement of critical legacy systems.
Solution Offering:
Solution depth correlates with organizational maturity and audit exposure rather than enterprise size alone.
- Incident Management:Ticket routing, escalation matrices, and SLA countdown engines form the foundational capability layer. Telecommunications operators in South Korea deploy advanced incident correlation to maintain 99.999% availability commitments for 5G network slices under strict KCC reliability mandates.
- Change Management:CAB automation, risk scoring algorithms, and deployment windows enforce controlled modification of production environments. Pharmaceutical manufacturers in Switzerland leverage change management modules to satisfy Swissmedic validation requirements for computerized systems in GMP-regulated facilities.
- Asset Management:CMDB federation, discovery scanning, and depreciation tracking consolidate hardware and software inventory visibility. Federal agencies in Washington DC utilize asset management to meet OMB M-19-21 records management directives for electronic information governance.
- Problem Management:Root cause analysis workflows and known error databases prevent incident recurrence through structural remediation. Airlines in Dubai apply problem management to reduce aircraft-on-ground delays by identifying recurring avionics configuration failures.
- Service Catalog:Self-service portals with automated fulfillment pipelines reduce tier-1 support volume through consumerized request experiences. Universities in the United Kingdom deploy service catalogs to manage faculty onboarding, software licensing, and equipment provisioning through standardized digital workflows.
Incident Management commands the largest installed base, though Change Management is expanding most quickly among regulated industries automating compliance documentation.
Application:
Functional application priorities diverge sharply between cost-center efficiency targets and revenue-protection imperatives.
- IT Operations:Infrastructure monitoring integration, event correlation, and automated remediation orchestrate technical service delivery. Mining conglomerates in Western Australia deploy IT operations modules to manage remote site connectivity and autonomous vehicle fleet telemetry across Pilbara iron ore operations.
- Compliance Management:Audit trail generation, control mapping, and regulatory reporting package satisfy external assessment requirements. Insurance carriers in Germany utilize compliance management to demonstrate BaFin MaRisk conformity for IT governance and information security documentation.
- Customer Support:Omnichannel case routing, sentiment analysis, and satisfaction surveying extend service management beyond internal IT. Retail banks in Brazil integrate customer support modules with central bank complaint resolution timelines under BCB resolution requirements.
- Knowledge Management:Article repositories, search optimization, and community contribution workflows capture institutional expertise. Engineering consultancies in the Netherlands deploy knowledge management to preserve retiring workforce expertise on legacy industrial control systems.
- SLA Management:Multi-party obligation tracking, penalty calculation, and performance dashboards govern contractual service commitments. Outsourcing providers in India leverage SLA management to demonstrate adherence to client master service agreements and avoid credit provisions.
IT Operations retains the deepest penetration, while Compliance Management is climbing the fastest as GDPR, SEC, and sector-specific audit frequencies intensify.
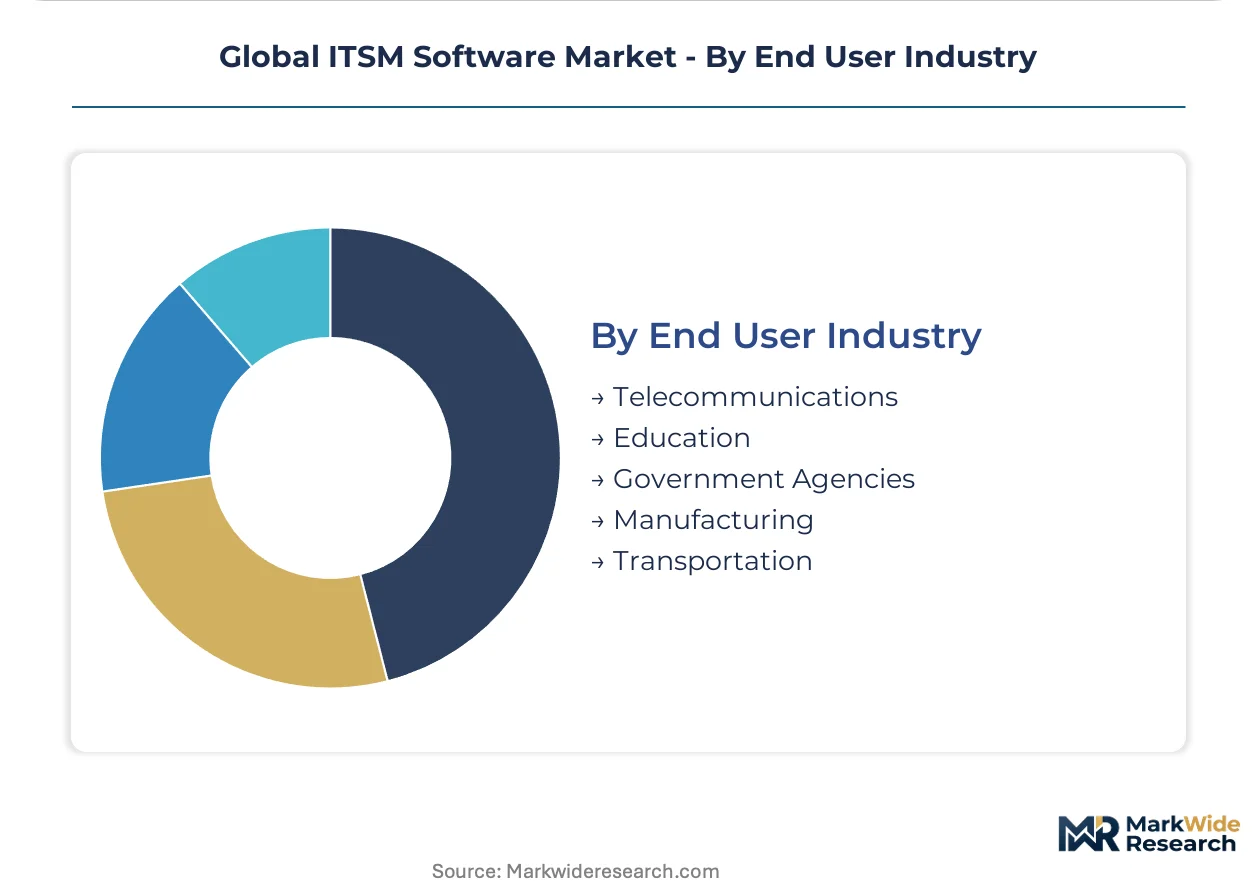
End User Industry:
Industry verticals exhibit distinct procurement patterns shaped by regulatory density and infrastructure heterogeneity.
- Telecommunications:Network operations centers require real-time incident correlation across radio access, core, and OSS/BSS layers. Operators in Finland deploy ITSM platforms to manage multi-vendor 5G infrastructure under Traficom cybersecurity certification requirements.
- Government Agencies:Classified and unclassified network segmentation demands FedRAMP-authorized or equivalent sovereign cloud deployments. Municipal governments in Ontario procure ITSM solutions through OECM cooperative purchasing to satisfy procurement fairness and transparency regulations.
- Manufacturing:Industry 4.0 integration between ITSM and OT device management enables unified service orchestration. Precision toolmakers in Japan connect ITSM platforms to MTConnect-enabled machine tools for predictive maintenance workflow automation.
- Transportation:Fleet management, passenger information systems, and logistics coordination require geographically distributed service desks. Rail operators in France integrate ITSM with SCADA maintenance scheduling to minimize RATP network disruption during infrastructure renewal programs.
- Education:Semester-cycle demand spikes, multi-campus coordination, and research grant compliance create unique workflow requirements. Community college systems in Texas deploy ITSM to manage distributed campus IT support while satisfying state auditor reporting standards for technology expenditures.
Telecommunications holds the dominant share, though Manufacturing is gaining share fastest as industrial digitization programs mandate IT-OT convergence platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German ITSM vendors export premium compliance-oriented platforms to financial services buyers in London and Singapore, establishing a trade corridor anchored by regulatory technology transfer.
United States
Financial services conglomerates in New York and healthcare systems in Boston drive demand for AI-native incident correlation. SEC record-keeping rules and HIPAA audit mandates force vendors to maintain FedRAMP-authorized cloud zones. Silicon Valley enterprise software clusters concentrate R&D investment for agentic workflow automation.
Germany
Automotive manufacturers in Stuttgart and industrial conglomerates in Munich procure federated CMDB architectures for Industry 4.0 integration. EU AI Act compliance deadlines and BaFin outsourcing guidelines accelerate replacement of legacy ticketing systems. Baden-Württemberg precision engineering clusters demand sovereign cloud deployments under TISAX certification.
United Kingdom
London-based insurance carriers and asset managers require immutable audit trails for FCA operational resilience directives. GDPR Article 32 security requirements intersect with post-Brexit data adequacy negotiations, complicating cross-border service desk operations. Edinburgh fintech clusters adopt subscription-to-outcome contracting models with MTTR guarantees.
Japan
Tokyo telecommunications operators and Osaka manufacturing groups prioritize IT-OT convergence for predictive maintenance workflows. METI cybersecurity framework certifications and JIS Q 27001 audits shape procurement specifications. Nagoya automotive supplier networks deploy hybrid architectures to satisfy customer TISAX data residency requirements.
Australia
Sydney banking consortia and Melbourne healthcare networks mandate APRA CPS 234-compliant cloud deployments with domestic data residency. MAS TRM-G1 guidelines from Singapore influence regional procurement standards for financial services ITSM. Perth mining conglomerates integrate platforms with autonomous vehicle fleet telemetry across Pilbara operations.
Global ITSM Software Market Competitive Landscape
Channel-controlling players compete with product-specialist players across deployment architecture, compliance certification depth, and workflow engine sophistication. The vendor base stratifies into three tiers: unified-platform incumbents with workflow engine dominance, infrastructure specialists with mainframe and hybrid cloud integration capabilities, and mid-market challengers with rapid-deployment SaaS models. Dominant competitive moves include M&A activity targeting AI-native automation startups and strategic partnerships with hyperscaler cloud providers to satisfy sovereign data requirements.
Within the unified-platform tier, ServiceNow and BMC Software exemplify contrasting strategic positions. ServiceNow anchors enterprise accounts seeking consolidated workflow architectures across IT and business operations. BMC Software occupies a specialized position serving organizations with deep mainframe entanglement and complex hybrid infrastructure footprints. Freshworks represents the mid-market challenger archetype, targeting buyers prioritizing simplified deployment timelines over deep customization.
| Leading Market Players |
|---|
| ServiceNow |
| Atlassian |
| BMC Software |
| GoTo |
| Ivanti |
| Broadcom |
| Microsoft |
| Freshworks |
| ManageEngine |
| Others |
Supply & Pricing Matrix
Overcapacity in Ireland's hyperscaler cloud zones compresses margins for SaaS delivery infrastructure while simultaneously pressuring vendors toward premium compliance-certified tiers to recover yield. This utilization dynamic shapes supplier consolidation toward sovereign-certified facilities and accelerates pricing stratification between commodity cloud instances and regulatory-hardened deployments.
Pricing Analysis
The technology-generation pricing gap separates AI-native autonomous workflow platforms from rules-based legacy systems and emerging agentic architectures still in beta programs. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation driven by FedRAMP authorization grade and EU GDPR data residency certification. Pricing pressure stems from hyperscaler infrastructure commoditization in Frankfurt and Dublin zones. Mid-market buyers exhibit highest price sensitivity, while financial services firms in New York and London absorb premium tiers for pre-certified compliance modules.
Supply Chain Analysis
Contract-manufacturing concentration rests with Accenture, TCS, and Infosys for implementation services, while AWS, Azure, and GCP hold infrastructure capacity. Geographic supply concentration centers on Ireland, Germany, and Singapore for compliant data center operations. Raw material dependencies include GPU compute clusters, cryptographic security modules, and API gateway licensing. Single-source vulnerability runs through hyperscaler concentration in Frankfurt for EU data residency. Distribution runs through direct enterprise sales teams and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. Compliance certification costs and audit trail immutability requirements create switching friction that protects incumbent positions.
For Market Incumbents: Entrench platform dominance through backward integration into sovereign cloud infrastructure and deepening FedRAMP authorization portfolios. AI-native challengers threaten workflow engine relevance, necessitating acquisition of autonomous automation specialists. Certification investment in EU AI Act compliance modules defends European account control against emerging competitors.
For New Entrants and Emerging Players: Pursue healthcare ITSM penetration where HIPAA-covered entities remain underautomated for change management workflows. Australia's APRA CPS 234-compliant banking sector offers greenfield expansion with outcome-based contracting appetite. Partner with regional systems integrators in Germany for TISAX-certified deployment credibility.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue compounding play because subscription-to-outcome contracting transfers operational risk to vendors and locks in decade-long relationships. Target acquisition profile centers on AI-native automation startups with pre-built compliance modules. Watch sovereign cloud certification timelines as inflection signal for European competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies ITSM workflows with ERP and CRM systems for consolidated enterprise architectures. |
| Acquisition of Specialist Firm | Captures AI-native automation capabilities and pre-certified compliance module expertise. |
| Strategic Partnership | Aligns with AWS, Azure, or GCP sovereign cloud zones for EU data residency requirements. |
| Product Launch | Introduces agentic AI architectures with autonomous remediation and cryptographic audit trails. |
| Geographic Expansion | Establishes ANSSI-certified operations in France and Gaia-X infrastructure participation in Germany. |
Research Methodology
A spread of perspectives from CTOs, IT procurement officers, platform engineers, and channel partners converged on the working assumptions underlying this analysis. Primary interviews with integration specialists and ITIL practitioners combined with secondary validation from SEC filings, hyperscaler capex disclosures, App Annie platform analytics, and EU regulatory filings. Bottom-up deployment modeling and top-down market sizing triangulated volume estimates across the projection horizon.
Demand-supply-balance framing anchored the analytical approach throughout the modeling period. Segmentation dimensions included deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern. CAGRs derived from cohort-based growth rate analysis applied to baseline penetration data. Industry-specific forecast inputs incorporated EU AI Act compliance deadline impacts and sovereign cloud certification velocity.
Macroeconomic conditions sit as an overlay; deviation in interest rate trajectories and enterprise software budget cycles would shift the trajectory. Forecasts reflect underlying assumptions about regulatory enforcement intensity and cloud migration pace. Quarterly review of hyperscaler infrastructure expansion announcements and compliance certification timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Open Stack Service Market
Software & Services
Global Server Management Software Market
Software & Services
Entity Management Software Market
Software & Services
Deck Software Market
Software & Services
Problem Management Software Market
Software & Services
Italy HR Payroll Software Market
Software & Services
Global Java Web Frameworks Software Market
Software & Services
In-Memory Data Grids Software Market
Software & Services
Java Integrated Development Environment (IDE) Market
Software & Services
Dental Practice Management Software Market
Software & Services
Global Intelligent Apps Market
Software & Services
Background Removal Software Market
Software & Services
Specification Management Software Market
Software & Services
Time Series Databases Software Market
Software & Services
Point Cloud Processing Software Market
Software & Services
Talent Acquisition Software Market