
 Switzerland Data Center Storage Market | 2026-2036
Switzerland Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Switzerland Data Center Storage Market Insights
Switzerland is reconfiguring its data center landscape through sustained capacity builds in the Zurich-West and Geneva-Cointrin corridors. Dell Technologies leverages extensive channel partnerships across Swiss banking infrastructure. Hewlett Packard Enterprise anchors enterprise workloads with specialized all-flash arrays. NetApp Inc. differentiates through cloud-adjacent software-defined storage architectures.
Data center storage encompasses electromechanical and solid-state systems engineered for persistent digital retention, typically operating at latency thresholds below ten milliseconds for enterprise flash tiers and millisecond-to-second ranges for mechanical disk subsystems. These systems serve commercial and institutional functions including transaction logging, analytics warehousing, and regulatory archive retention. Flash Storage commands premium positioning as financial services in Zurich and Geneva demand sub-millisecond response for real-time trading platforms. Object Storage extends fastest across hybrid deployments as Swiss enterprises reconcile on-premises sovereignty with cloud elasticity. Hyper-Converged Infrastructure occupies expanding share among mid-tier telecommunications operators consolidating compute and storage footprints.
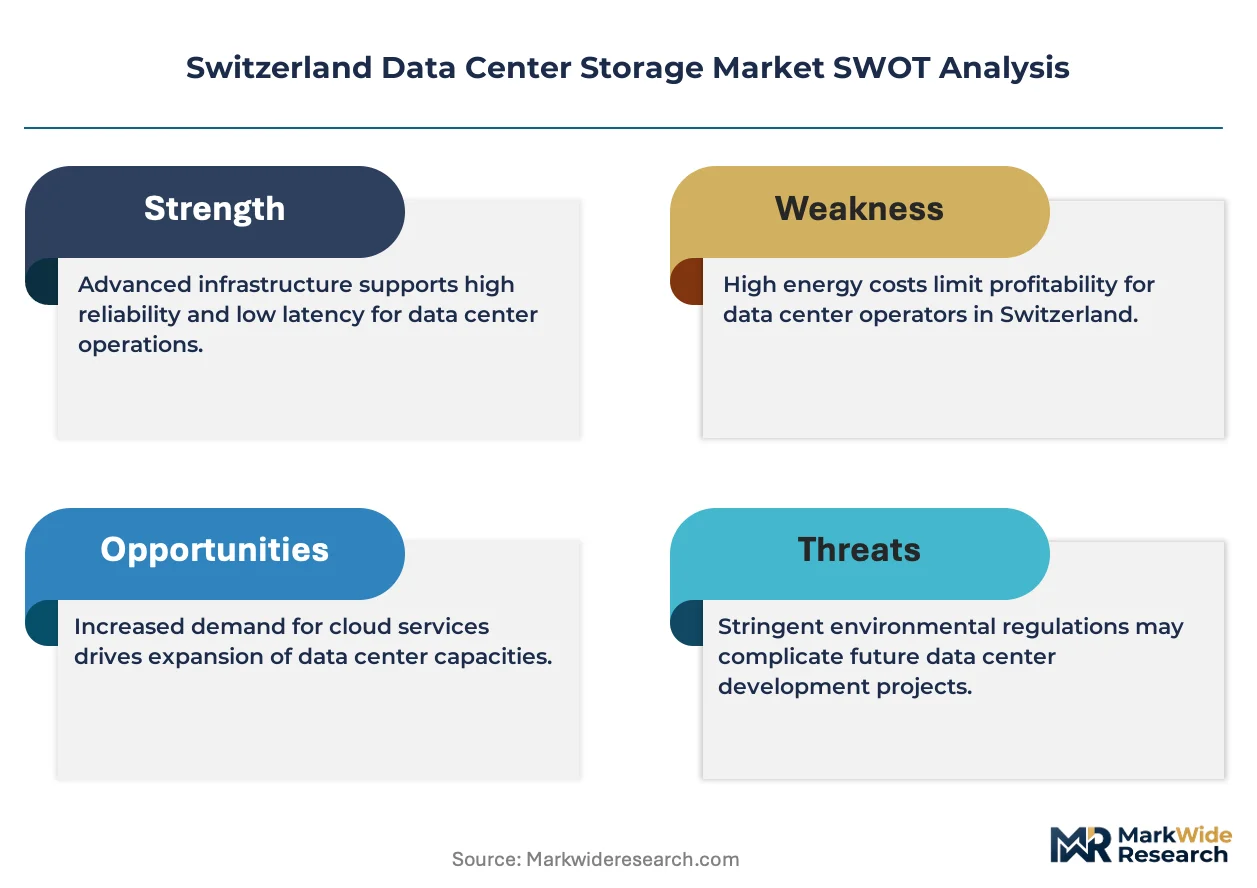
Swissmedic guidelines for clinical data integrity and FINMA operational resilience requirements shape procurement specifications for audit trails and encryption standards. The Federal Act on Data Protection revision imposes data localization constraints that redirect storage investment toward domestic colocation facilities. Stakeholders must evaluate how emerging EU AI Act interoperability rules will cascade into Swiss federal ordinances governing cross-border data flows.
Market Dynamics
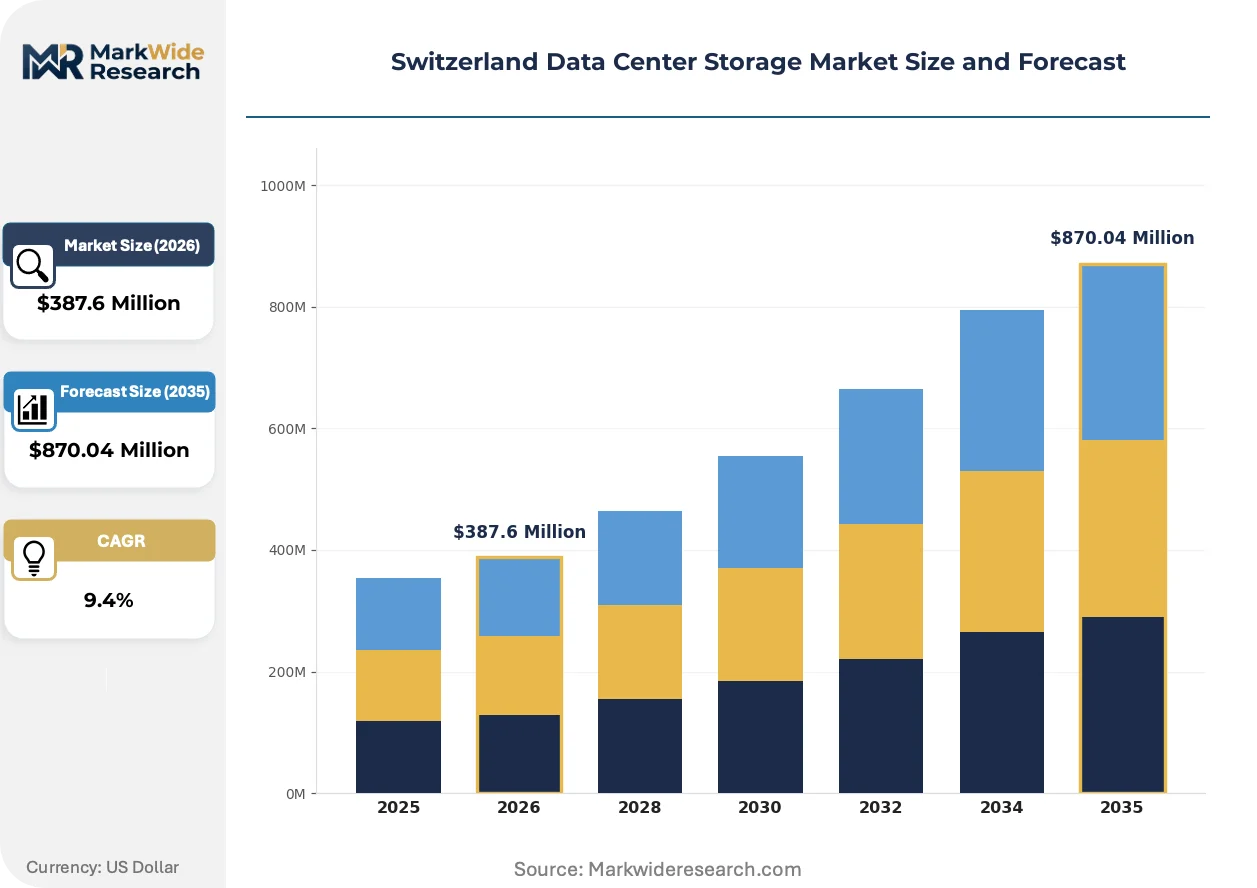
FINMA operational resilience mandates and the revised Federal Act on Data Protection are compressing procurement cycles while forcing infrastructure sovereignty investments across Swiss banking and pharmaceutical sectors.
Growth Catalysts
- FINMA data governance rules:Swiss financial institutions must maintain compliant audit trails and encryption standards, compelling enterprise storage upgrades for transaction logging and regulatory archive retention.
- Flash storage technology:Sub-millisecond latency requirements from Zurich and Geneva trading platforms drive premium positioning of solid-state systems for real-time analytics.
- Zurich-West corridor concentration:Domestic colocation facility expansion redirects investment toward localized infrastructure to satisfy data localization constraints.
Market Restraints
- Specialized engineering talent scarcity:Deep expertise in software-defined storage architectures and hybrid cloud integration remains concentrated among limited Swiss technical workforces.
- Input cost volatility:NAND flash memory pricing fluctuations and semiconductor supply chain constraints create margin pressure for all-flash array deployments.
- Technical limitation of legacy mechanical systems:Millisecond-to-second latency thresholds of disk subsystems disqualify them from real-time trading workloads, fragmenting procurement across incompatible tiers.
Strategic Opportunities
- Geneva-Cointrin corridor builds:Western Switzerland pharmaceutical clusters generate demand for clinical data integrity systems compliant with Swissmedic guidelines.
- Object storage hybrid deployments:Cloud-adjacent architectures enable enterprises to reconcile on-premises sovereignty with elasticity, extending fastest across mid-tier telecommunications consolidation.
- EU AI Act interoperability cascade:Emerging cross-border data flow ordinances will create compliance infrastructure demand before formal Swiss federal adoption.
Industry Challenges
- Integration complexity with mechanical disk estates:Financial institutions face operational friction migrating petabyte-scale archives from legacy tape and disk systems to unified flash-object tiers.
- Certification timeline compression:Swissmedic and FINMA audit requirements demand accelerated validation cycles that strain vendor documentation and testing bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Switzerland Data Center Storage Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $870.04 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Storage Arrays, Hyper-Converged Infrastructure, Object Storage, Flash Storage Deployment Model: On-Premises, Cloud-Based, Hybrid, Colocation End User: Retail, BFSI, Telecommunications, Government Storage Capacity: Petabyte Scale, Exabyte Scale, Terabyte Scale, Zettabyte Scale |
| Companies Covered | Dell Technologies, Hewlett Packard Enterprise, NetApp Inc., Pure Storage Inc., IBM Corporation, Hitachi Vantara LLC, Huawei Technologies Co. Ltd., Swisscom AG, Equinix Switzerland, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Switzerland Data Center Storage Market Trends and Innovations
Storage architectures across Swiss data centers are converging toward software-defined layers that abstract physical media from application workloads, enabling policy-driven data placement across sovereign and elastic environments.
All-flash arrays are migrating from niche high-frequency trading deployments to standard enterprise infrastructure across Swiss private banking and wealth management operations. Tier-one institutions in Zurich now specify sub-millisecond response as baseline for customer-facing analytics platforms. This migration is compressing mechanical disk procurement to pure archival tiers while elevating flash to primary workload default.
The Federal Act on Data Protection revision imposes strict data localization constraints that redirect storage investment toward domestic colocation facilities. Pharmaceutical manufacturers must now maintain clinical trial data within Swiss territorial boundaries, disqualifying pure public cloud strategies for regulated workloads. Geneva-based biotech firms are responding by deploying hybrid object storage with cryptographic residency controls.
Mid-tier telecommunications operators are unbundling storage procurement from compute refresh cycles, separating infrastructure decisions to optimize consolidation timelines. Swisscom and Sunrise are adopting hyper-converged infrastructure with disaggregated storage scaling, replacing traditional three-tier architectures. This pattern is most visible in Bern and Basel where regional operators seek footprint reduction without trading performance sovereignty.
Switzerland Data Center Storage Market Segmentation
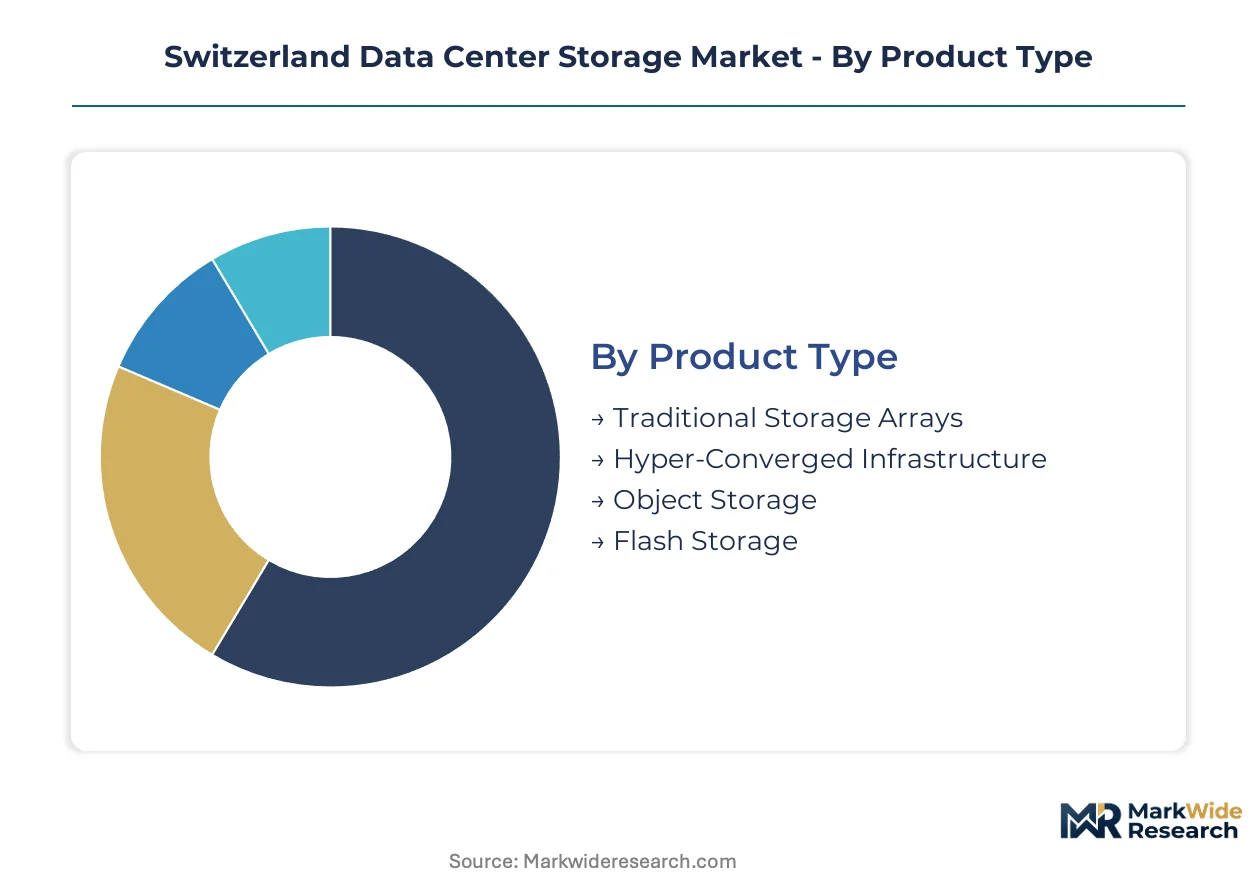
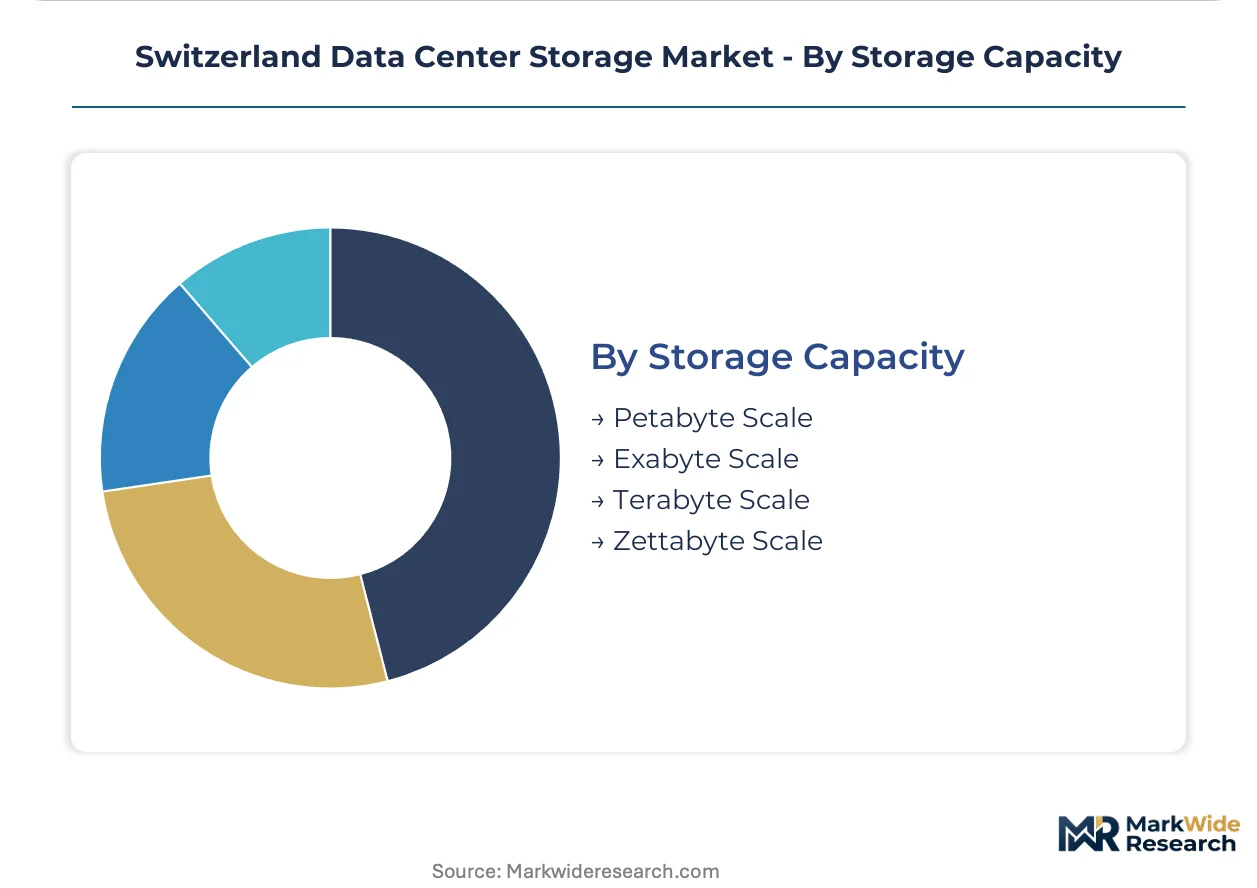
Storage procurement across Swiss data centers fragments across four distinct taxonomies. Each dimension reveals how FINMA compliance, latency thresholds, and sovereignty mandates reshape infrastructure investment patterns.
Product Type:
Mature mechanical systems anchor archival workloads while emerging software-defined architectures capture growth from hybrid sovereignty requirements.
- Flash Storage:Solid-state subsystems deliver sub-millisecond latency for Zurich trading platforms and real-time analytics. Swiss private banks specify these arrays as baseline infrastructure for customer-facing platforms, compressing mechanical disk procurement to pure archive tiers.
- Object Storage:Cloud-adjacent architectures enable cryptographic residency controls for clinical trial data under Swissmedic guidelines. Geneva-based biotech firms deploy these systems to reconcile on-premises sovereignty with elastic capacity scaling.
- Traditional Storage Arrays:Electromechanical disk systems retain dominance in long-term regulatory archive retention where millisecond-to-second latency thresholds suffice.
- Hyper-Converged Infrastructure:Mid-tier telecommunications operators in Bern and Basel adopt disaggregated storage scaling to consolidate compute and storage footprints.
Flash Storage handles the majority of throughput; Object Storage is the fastest mover on share.
Deployment Model:
Cost tier stratification separates sovereign infrastructure investments from elasticity-seeking workloads across Swiss regulated sectors.
- Colocation:Domestic facilities in Zurich-West and Geneva-Cointrin corridors absorb redirected investment under Federal Act on Data Protection localization constraints. Banking and pharmaceutical sectors specify these deployments for audit trail sovereignty.
- Hybrid:Enterprises combine on-premises residency with cloud burst capacity for seasonal analytics workloads. This model extends fastest across telecommunications consolidation timelines.
- On-Premises:Fully captive infrastructure remains mandatory for Swissmedic clinical data integrity and FINMA operational resilience certification.
- Cloud-Based:Pure public strategies face disqualification for regulated workloads, limiting adoption to non-sensitive development environments.
Colocation absorbs the dominant share of new capacity; Hybrid deployments are expanding most quickly among mid-tier operators.
End User:
Application-specific latency and compliance requirements segment procurement across Swiss institutional verticals.
- BFSI:Zurich financial institutions drive enterprise storage upgrades for transaction logging and regulatory archive retention under FINMA data governance rules. Sub-millisecond response specifications dominate primary workload procurement.
- Telecommunications:Swisscom and Sunrise unbundle storage decisions from compute refresh cycles, adopting hyper-converged infrastructure for footprint reduction in regional markets.
- Government:Federal and cantonal authorities mandate data localization for citizen records and administrative systems.
- Retail:E-commerce platforms and payment processors seek cost-optimized tiers for customer analytics and inventory management.
BFSI commands the largest infrastructure commitment; Telecommunications is gaining share fastest through consolidation mandates.
Storage Capacity:
Volume thresholds correlate directly with customer type scale and regulatory retention duration across Swiss data center estates.
- Petabyte Scale:Standard enterprise tier for mid-sized financial institutions and regional pharmaceutical manufacturers consolidating distributed archives.
- Exabyte Scale:Tier-one Zurich banks and national telecommunications operators specify these thresholds for multi-year transaction logging and analytics warehousing.
- Terabyte Scale:Small-cap wealth managers and municipal government systems deploy these configurations for core operational databases.
- Zettabyte Scale:Hyperscale colocation providers and federal data aggregation projects represent nascent demand at this threshold.
Petabyte Scale handles the majority of current deployments; Exabyte Scale is climbing the fastest as archival retention periods extend.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Storage consumption patterns diverge sharply across Swiss sub-regions, with financial centers prioritizing sub-millisecond flash arrays while pharmaceutical clusters emphasize cryptographic residency controls for clinical data sovereignty.
Zurich-West Corridor
Private banking and high-frequency trading platforms anchor demand for all-flash primary storage. FINMA operational resilience mandates compress procurement cycles for transaction logging infrastructure. Tier-one institutions along Hardbrücke and Altstetten specify sub-millisecond response as baseline for customer-facing analytics.
Geneva-Cointrin Corridor
Biotech manufacturers and clinical research organizations drive object storage deployment for trial data integrity. Swissmedic guidelines impose strict territorial data boundaries that disqualify pure cloud strategies. Geneva-based firms deploy hybrid architectures with cryptographic residency controls at Cointrin-adjacent colocation facilities.
Basel Region
Pharmaceutical headquarters and chemical conglomerates consolidate petabyte-scale archives under revised Federal Act on Data Protection localization constraints. Novartis and Roche supplier ecosystems generate secondary demand for compliant infrastructure. The Rhine corridor attracts domestic colocation investment to serve cross-border research data flows.
Bern Metropolitan Area
Federal administrative systems and cantonal government data centers mandate fully captive on-premises storage for citizen records. Mid-tier telecommunications operators in the region adopt hyper-converged infrastructure to unbundle storage decisions from compute refresh cycles. Swisscom maintains sovereign facilities for federal cloud-adjacent deployments.
Ticino
Cross-border financial services and Italian-speaking commercial banks create hybrid demand bridging Swiss compliance with EU market access. The region's data centers serve as failover nodes for Milan-based institutions seeking FINMA-aligned backup architectures. Lugano's emerging technology cluster attracts blockchain and digital asset custody providers requiring localized cold storage.
Switzerland Data Center Storage Market Competitive Landscape
Capability concentration sits with specialized flash array architects; scale advantage sits with diversified infrastructure conglomerates. The vendor base stratifies across three tiers: integrated technology holding companies with broad enterprise portfolios, pure-play storage specialists with software-defined architectures, and telecommunications operators with captive colocation assets. Dominant competitive moves include channel partnership deepening in regulated verticals and disaggregated storage scaling for mid-tier consolidation.
Among US-based diversified technology holding companies, Dell Technologies and Hewlett Packard Enterprise occupy positions anchoring enterprise workload infrastructure across Swiss banking estates. NetApp Inc. exemplifies the software-defined specialist archetype, representing cloud-adjacent architectural approaches. Pure Storage Inc. sits within the all-flash pure-play tier, exemplifying sub-millisecond latency specialization for trading platform deployments.
| Leading Market Players |
|---|
| Dell Technologies |
| Hewlett Packard Enterprise |
| NetApp Inc. |
| Pure Storage Inc. |
| IBM Corporation |
| Hitachi Vantara LLC |
| Huawei Technologies Co. Ltd. |
| Swisscom AG |
| Equinix Switzerland |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Zurich-West flash array fabrication is compressing supplier margins while elevating buyer power for Swiss financial institutions negotiating enterprise storage contracts. This utilization asymmetry rewards vendors with captive NAND supply while punishing pure-play integrators exposed to spot memory markets.
Pricing Analysis
Long-term offtake agreements dominate Swiss banking procurement, with tier-one Zurich institutions locking in three-to-five-year flash storage contracts to insulate against NAND volatility. Price differentiation hinges on FINMA certification tier and volume scale, with sub-millisecond latency arrays commanding substantial premiums over standard enterprise tiers. Cost compression in mid-market mechanical disk tiers is intensifying because hyperscale cloud providers are dumping refurbished equipment into European secondary markets. Municipal government buyers exhibit highest price sensitivity, while private wealth managers prioritize latency guarantees over unit economics.
Supply Chain Analysis
Extended payment terms from Swisscom and Sunrise are forcing component distributors to absorb working capital strain through supply-chain finance facilities. Flash memory production concentrates in South Korea, Taiwan, and Japan, while mechanical disk assembly feeds from Thailand, Malaysia, and China. NAND wafer supply, controller silicon, and enterprise-grade capacitors constitute critical input dependencies. Single-source vulnerability around advanced controller ASICs poses structural risk given export control friction. Distribution runs through Dell Technologies and Hewlett Packard Enterprise channel partners serving regulated verticals, with direct procurement remaining rare outside hyperscale colocation operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against hyperscale cloud providers encroaching on Swiss financial services through compliant sovereign cloud offerings that satisfy FINMA data residency mandates.
For Market Incumbents: Harden software-defined storage architectures against cloud-native substitutes by deepening FINMA-certified encryption integration. Secure captive NAND supply through backward integration into flash controller design or exclusive foundry partnerships. Channel control in Zurich-West banking corridors remains the critical defensive lever against hyperscale entrants. For New Entrants and Emerging Players: Pursue white-space opportunity in Geneva-Cointrin clinical data sovereignty, where Swissmedic guidelines disqualify incumbent cloud strategies. Mid-tier pharmaceutical CROs represent the most penetrable segment given their hybrid infrastructure gap. A compliance-first go-to-market emphasizing cryptographic residency controls bypasses established vendor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across all-flash array manufacturing as advanced node NAND requires specialized packaging investment. Long-term viability favors vendors with sovereign cloud adjacency and software-defined architectural control. Acquisition targets should demonstrate FINMA audit trail certification and existing Zurich banking relationships. The signal to watch is hyperscaler capex allocation toward European sovereign cloud builds.| Strategic Initiative | Industry Significance |
|---|---|
| FINMA Certification Investment | Validates encryption and audit trail standards for Zurich banking procurement. |
| Hybrid Cloud Partnership | Enables Geneva biotech firms to reconcile sovereignty with elastic capacity scaling. |
| Channel Partnership Deepening | Secures preferential access to Swisscom and Sunrise infrastructure refresh cycles. |
| Software-Defined Architecture Migration | Abstracts physical media from workloads for policy-driven data placement. |
| Domestic Colocation Expansion | Captures redirected investment under Federal Act on Data Protection localization constraints. |
Research Methodology
Desk research of SEC 10-K filings, hyperscaler capex disclosures, and FINMA regulatory guidance preceded structured interviews with data center infrastructure directors, storage procurement officers at Swiss banks, pharmaceutical IT leads, and colocation facility operators. Primary fieldwork combined with secondary validation across customs trade data and vendor channel reports. Bottom-up deployment volume estimates triangulated against top-down addressable market calculations.
Assumptions held fixed include FINMA operational resilience mandate timelines and Federal Act on Data Protection localization requirements, while NAND pricing trajectories and semiconductor supply availability were modeled as variable inputs. Segmentation dimensions spanned product type, deployment model, end-user vertical, and storage capacity tier, with geographic concentration patterns across Zurich-West and Geneva-Cointrin corridors incorporated as industry-specific modifiers. CAGRs were derived from slope analysis of capacity deployment curves against sovereign compliance investment cycles.
Sensitivities concentrate around NAND flash memory pricing volatility, Swiss federal ordinance adoption of EU AI Act interoperability rules, and hyperscaler sovereign cloud entry timing. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and enterprise refresh cycle duration. Macroeconomic contraction, accelerated cross-border data flow liberalization, or breakthrough in DNA storage technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Global Virtual Data Storage Market
Storage Solutions
Global Enterprise File Sharing and Synchronization (EFSS) Market
Storage Solutions
Disk-Based Backup System Market
Storage Solutions
UK Data Center Storage Market
Storage Solutions
Public Cloud Storage Services Market
Storage Solutions
Virtual Machine Backup and Recovery Market
Storage Solutions
Software Defined Storage Market
Storage Solutions
Global Ethernet Storage Fabric Market
Storage Solutions
Indonesia Data Center Storage Market
Storage Solutions
Europe in-Memory Database Market
Storage Solutions
Copy Data Management Software Market
Storage Solutions
Sweden Data Center Storage Market
Storage Solutions
Enterprise File Sync and Share Platform Market
Storage Solutions
Italy Data Center Storage Market
Storage Solutions
Saudi Arabia Data Center Storage Market
Storage Solutions
Global Data Erasure Solutions Market