
 Application Hosting Market | 2026-2036
Application Hosting Market Size, Share, and Industry Trends Forecast 2026-2036
Application Hosting Market Analysis
GDPR is decoupling data residency from processing flexibility across European application hosting contracts. Amazon Web Services sustains infrastructure breadth across sovereign cloud zones. Microsoft Azure leverages enterprise licensing gravity to anchor hybrid deployment pipelines. Google Cloud specializes in container-native orchestration for analytics-intensive workloads.
Application hosting delivers compute, storage, and middleware resources from centralized or distributed data center facilities, typically provisioned through virtualized environments with guaranteed uptime thresholds measured in nines. The architecture enables organizations to deploy software without capital expenditure on physical servers. Public cloud deployment dominates volume while private cloud and hybrid configurations capture premium margin pools. Managed hosting services are expanding fastest as enterprises outsource operational complexity rather than infrastructure ownership alone.
The EU AI Act, GDPR, and ISO 27001 collectively reshape where sensitive workloads may execute and how providers must certify their control environments. NIS2 directives in member states extend incident reporting obligations to hosting intermediaries. Stakeholders must weigh sovereignty requirements against latency optimization when selecting regional provider footprints.
Market Dynamics
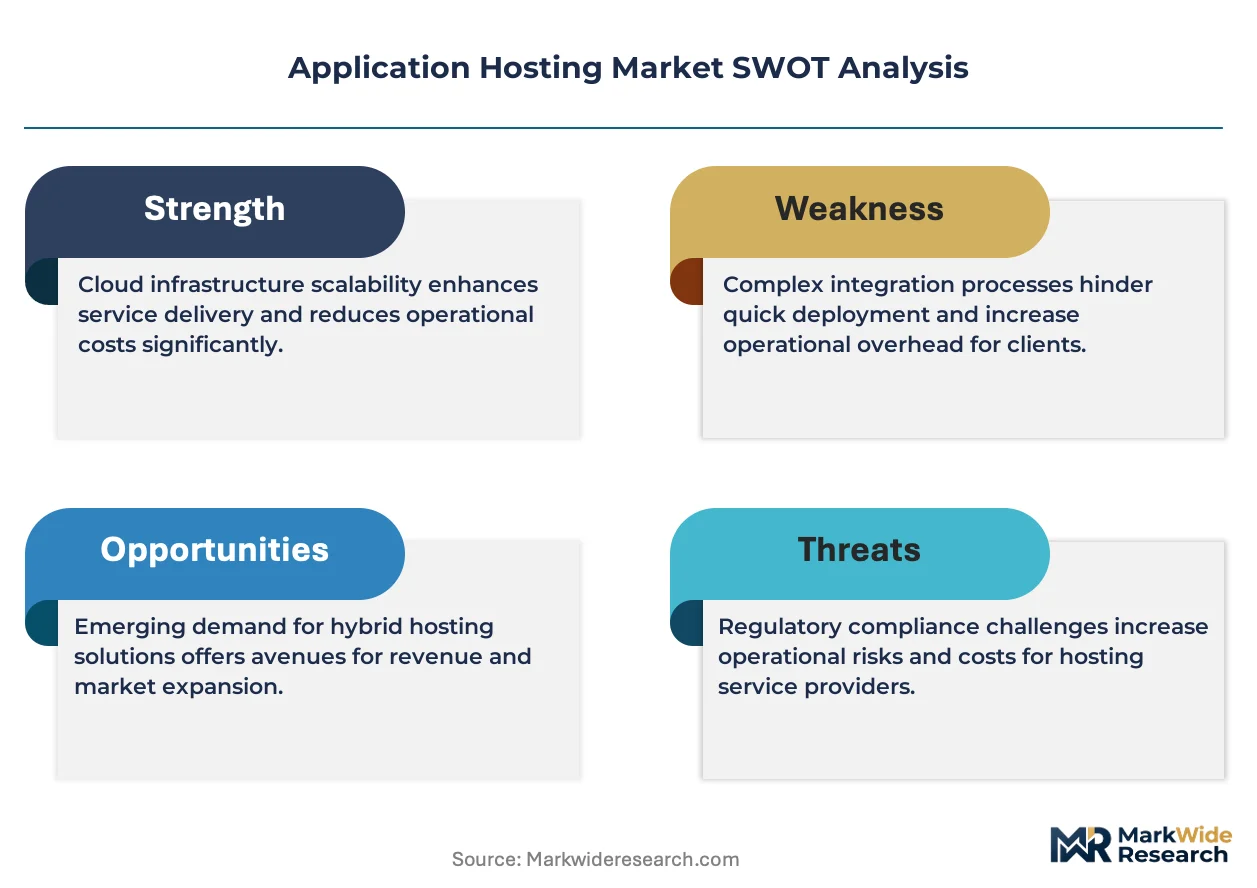
Sovereign data requirements under the EU AI Act and GDPR are fragmenting cloud deployment architectures, forcing providers to replicate control environments across national jurisdictions rather than consolidating at continental scale.
Growth Catalysts
- Real-time transaction workloads:Financial services firms in Frankfurt, London, and Singapore are expanding hosted footprints to support sub-millisecond payment processing. Latency-sensitive banking APIs now demand edge-adjacent compute clusters.
- EU AI Act compliance infrastructure:Automated decision-making workloads require auditable hosting environments with documented model lineage. Providers certifying against these obligations capture regulated enterprise demand.
- Container-native orchestration:Kubernetes-based deployment pipelines are displacing monolithic virtual machine provisioning. Analytics-intensive workloads benefit from granular resource allocation and auto-scaling elasticity.
Market Restraints
- Energy input cost volatility:Data center power purchase agreements face renewal pressure as European grid pricing diverges from long-term baselines. Frankfurt and Amsterdam facilities report contracted capacity constraints.
- Supply concentration in sovereign cloud:Certified provider pools remain shallow in France, Italy, and Spain. National security clearance requirements limit viable vendor shortlists for defense and healthcare workloads.
- Cross-border data friction:GDPR adequacy decisions with third countries remain contested. Transatlantic workload portability encounters legal uncertainty under evolving Privacy Shield replacements.
Strategic Opportunities
- Underpenetrated manufacturing vertical:Industrial IoT telemetry in Germany's Mittelstand sector remains largely on-premises. Predictive maintenance workloads represent a greenfield hosted application segment.
- Green hosting certification:EU Green Deal alignment and CSRD disclosure requirements create preference for carbon-neutral data center operations. Renewable energy matching commands contract premiums.
- Confidential computing convergence:Hardware-based trusted execution environments combined with zero-trust networking enable sensitive workload migration to multi-tenant infrastructure previously deemed non-viable.
Industry Challenges
- Site reliability engineering talent scarcity:NIS2 incident response timelines demand 24/7 operational coverage. Qualified personnel pools lag facility expansion in secondary European markets.
- Legacy system integration complexity:Mainframe-hosted core banking systems resist API-first modernization. Hybrid middleware layers introduce failure modes that erode uptime guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Application Hosting Market |
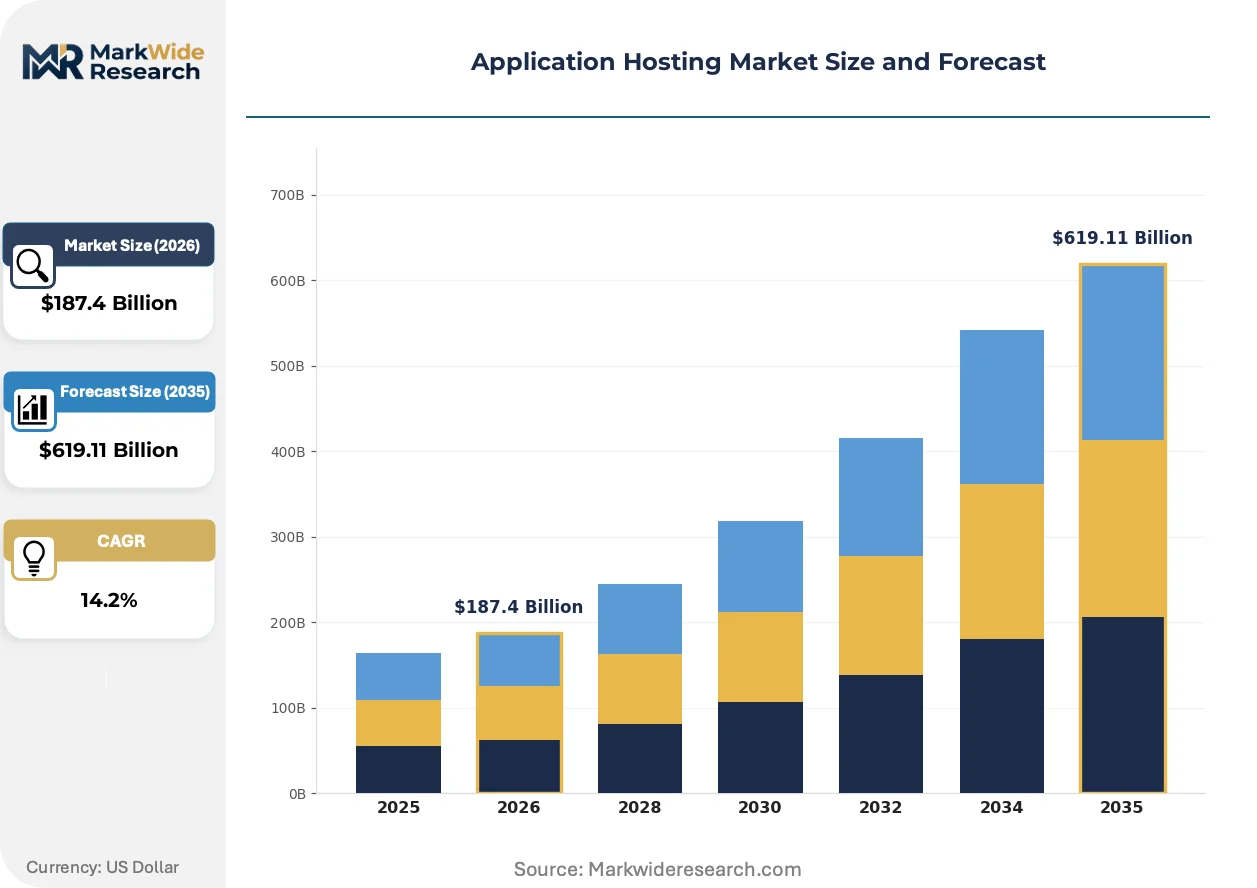
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $619.11 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Service Type: Dedicated Hosting, Shared Hosting, Managed Hosting, VPS Hosting Operating System: Linux, Windows, UNIX, BSD End User: SMEs, Large Enterprises, Government, Non-Profit |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud, IBM Cloud, Oracle Cloud, Rackspace Technology, DXC Technology, DigitalOcean, Alibaba Cloud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Application Hosting Market Emerging Trajectories
Workload portability requirements and sovereignty mandates are converging to reshape how compute capacity is architected, provisioned, and governed across European jurisdictions.
Edge computing infrastructure is decentralizing application hosting topology. Manufacturing and autonomous vehicle developers in Stuttgart and Wolfsburg are deploying micro-data centers within 10 milliseconds of operational sites. This architecture compresses reliance on centralized hyperscale regions for latency-critical processing.
The EU AI Act's risk classification framework is recalibrating compliance obligations for automated decision-making workloads. High-risk application categories must demonstrate human oversight mechanisms and algorithmic transparency. Financial services and healthcare providers in France and Germany are restructuring hosting contracts to embed these attestations.
Consumption-based billing models are displacing reserved instance commitments among mid-market enterprises. Finance teams in the Netherlands and Belgium prefer operational expenditure alignment with actual utilization patterns. Channel partners are unbundling managed services from infrastructure charges to capture this preference shift.
Application Hosting Market Segmentation
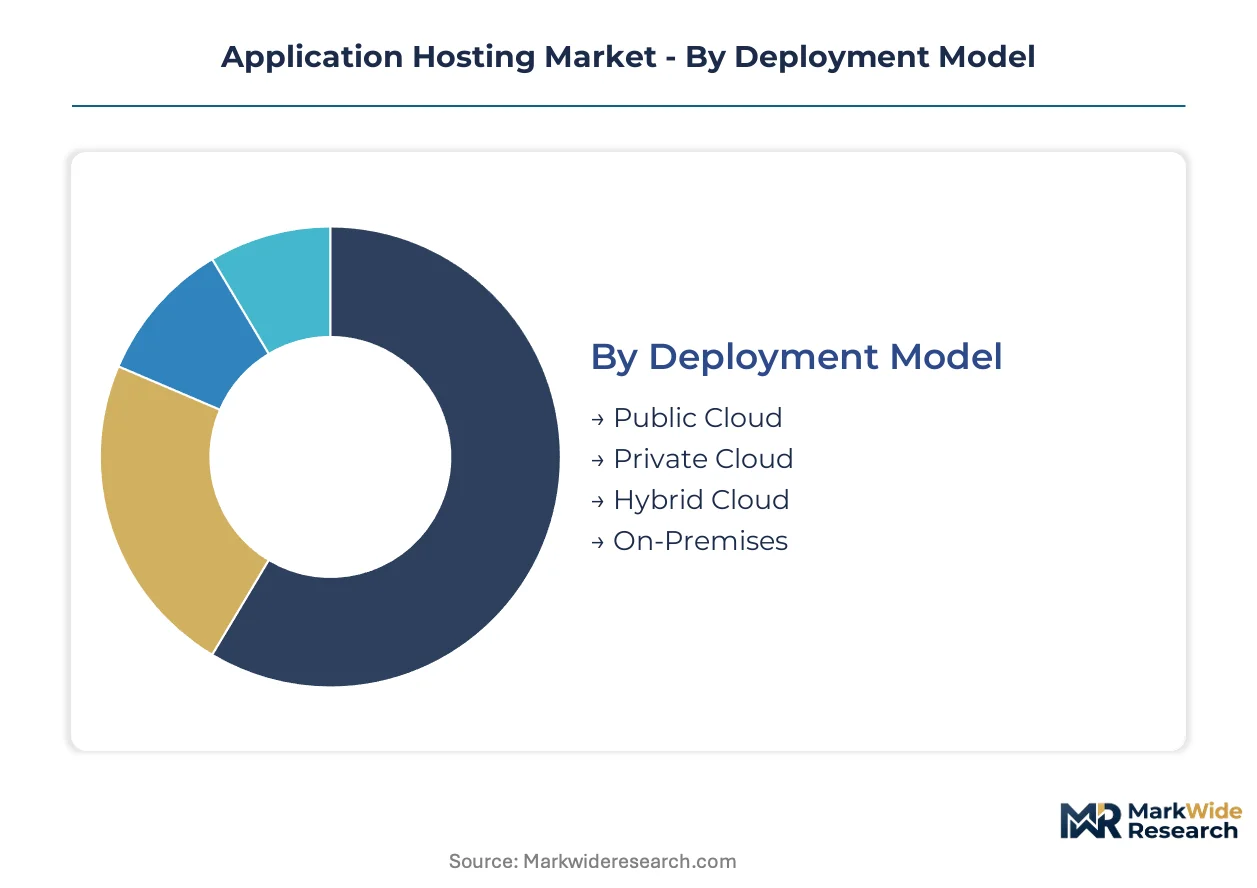
Application hosting architectures fragment across deployment sovereignty, operational control, and workload sensitivity. Procurement patterns diverge sharply between regulated financial institutions seeking certified environments and mid-market enterprises prioritizing consumption elasticity.
Deployment Model:
Supply concentration in hyperscale regions is reshaping how organizations balance latency against data residency mandates.
- Public Cloud:Multi-tenant infrastructure pools compute and storage across geographically distributed availability zones. Frankfurt and Amsterdam hyperscale clusters absorb the bulk of European financial services workloads demanding sub-millisecond connectivity to payment networks.
- Private Cloud:Single-tenant dedicated environments provision virtualized resources within client-controlled security perimeters. German automotive manufacturers in Stuttgart and Wolfsburg deploy these configurations to isolate proprietary design data under GDPR Article 32 encryption requirements.
- Hybrid Cloud:Orchestrated workload portability spans on-premises and off-premises capacity. French healthcare providers leverage this architecture to burst patient analytics to public infrastructure while retaining diagnostic imaging in sovereign-certified local facilities.
- On-Premises:Legacy colocation and self-managed data centers persist in defense and classified government workloads. Spain's national security clearance requirements restrict certain workloads to physically controlled environments.
Public cloud absorbs the bulk of installed capacity; hybrid cloud is expanding most quickly as sovereignty mandates fragment deployment architectures.
Service Type:
Cost tier differentiation separates infrastructure-only provisioning from full operational outsourcing.
- Dedicated Hosting:Exclusive physical server allocation guarantees resource isolation for compliance-sensitive workloads. Italian banking consortiums in Milan specify these arrangements to satisfy EBA guidelines on outsourcing critical functions.
- Managed Hosting:Providers assume 24/7 operational responsibility including patching, monitoring, and incident response under NIS2-mandated timelines. Belgian mid-market enterprises favor this model to address site reliability engineering talent scarcity without internal hiring.
- Shared Hosting:Multi-tenant server partitioning delivers lowest unit economics for lightweight web applications. Dutch e-commerce startups utilize these configurations for pre-revenue validation before committing to reserved capacity.
- VPS Hosting:Virtual private servers simulate dedicated environments through hypervisor-level isolation. Polish software developers deploy these for staging environments requiring root access without physical hardware procurement.
Managed hosting absorbs the bulk of new contract value; VPS hosting is climbing the fastest among developer-centric procurement patterns.
Operating System:
Volume concentration in open-source platforms is displacing proprietary licensing models across container-native workloads.
- Linux:Open-source kernel distributions dominate cloud-native orchestration and Kubernetes deployments. German industrial IoT platforms in the Mittelstand sector standardize on Ubuntu and RHEL for predictive maintenance workloads at manufacturing sites.
- Windows:Microsoft licensing gravity anchors enterprise application portfolios dependent on .NET frameworks and Active Directory integration. French public sector contracts frequently specify Windows Server environments for legacy administrative system compatibility.
- UNIX:Proprietary variants persist in mission-critical banking and telecommunications infrastructure. Swiss financial institutions in Zurich maintain AIX and Solaris deployments for core transaction processing systems resisting containerization.
- BSD:Berkeley Software Distribution derivatives occupy niche network appliance and security-focused hosting. Dutch internet exchange points utilize FreeBSD for routing infrastructure requiring license permissiveness and code auditability.
Linux dominates provisioned instance hours; Windows maintains entrenched position in public sector and regulated enterprise segments.
End User:
Customer type determines compliance burden sophistication and contract structure complexity.
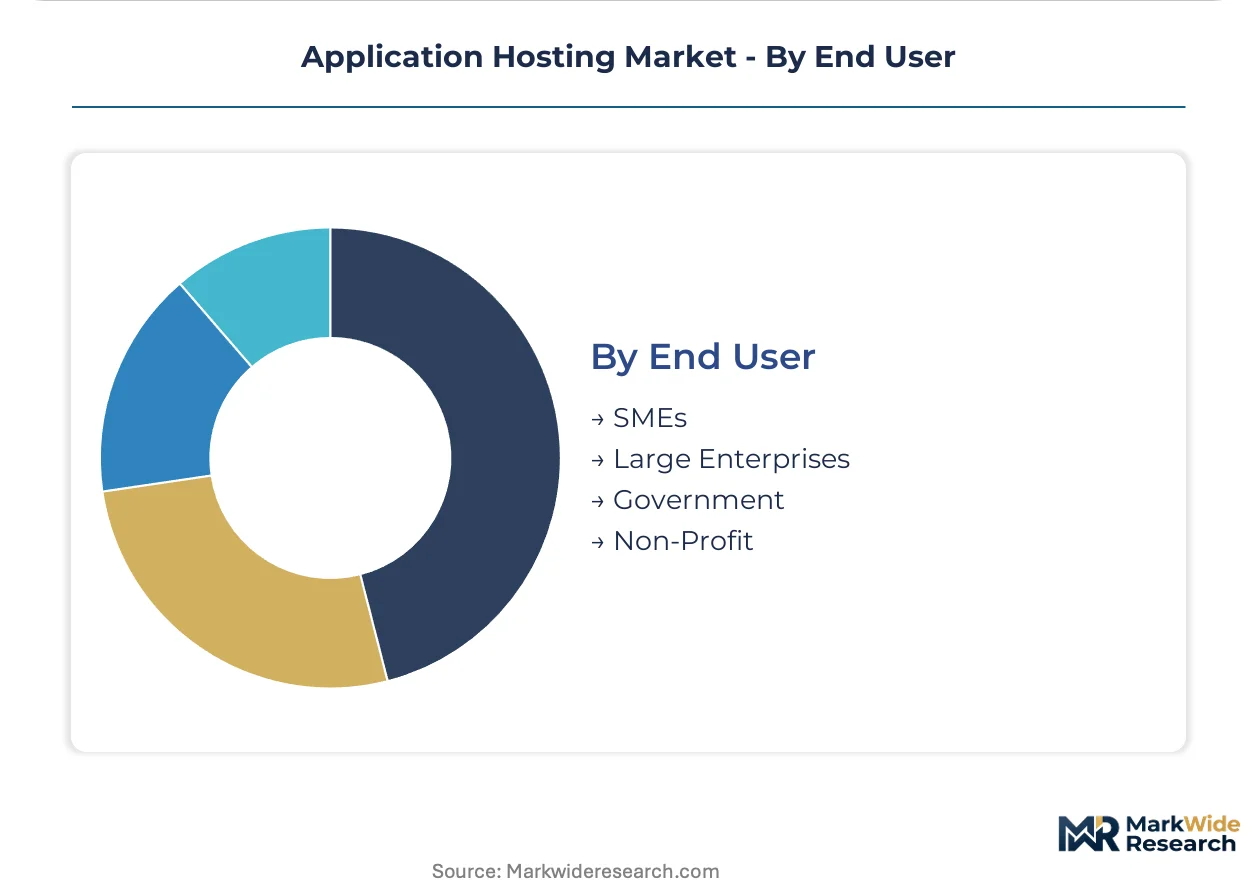
- Large Enterprises:Multi-year framework agreements negotiate custom SLAs, dedicated support tiers, and audit rights. German automotive OEMs and chemical conglomerates in BASF's Ludwigshafen corridor command preferential pricing through volume commitments exceeding ten thousand cores.
- SMEs:Consumption-based billing without minimum commitments aligns operational expenditure with cash flow constraints. Netherlands and Belgium mid-market firms increasingly unbundle managed services from infrastructure charges.
- Government:Sovereign cloud certification and national security clearance requirements constrain vendor pools. French defense procurement through ANSSI-certified providers exemplifies the compliance overhead.
- Non-Profit:Grant-funded organizations prioritize cost minimization over performance guarantees. European research institutions leverage academic pricing tiers for compute-intensive simulation workloads.
Large enterprises absorb the bulk of provider revenue; government vertical is gaining share fastest under NIS2 and EU AI Act compliance mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt's data center cluster anchors continental cloud capacity through Germany's enhanced depreciation allowances for digital infrastructure investments. Tax-advantaged zones in Hesse and Bavaria concentrate hyperscale facility development.
Germany
Automotive OEMs in Stuttgart and Wolfsburg demand sub-millisecond connectivity for autonomous vehicle telemetry. The EU AI Act mandates auditable hosting environments for automated manufacturing decisions. Frankfurt's Rhine-Main cluster hosts the densest concentration of financial services workloads in continental Europe.
United Kingdom
London's fintech sector expands edge-adjacent compute for real-time payment processing. The Financial Conduct Authority's operational resilience rules impose strict uptime thresholds on critical banking infrastructure. The Thames Valley corridor attracts sovereign cloud investments from defense contractors seeking national security clearance.
France
Healthcare providers in Paris and Lyon restructure contracts for EU AI Act compliance on diagnostic algorithms. ANSSI certification requirements constrain vendor pools for sensitive government workloads. The Île-de-France region concentrates managed hosting demand from aerospace and luxury goods exporters.
Netherlands
Amsterdam's internet exchange drives colocation demand from content delivery networks and trading platforms. The Dutch Authority for Digital Infrastructure enforces NIS2 incident reporting timelines on hosting intermediaries. Rotterdam's port logistics sector adopts container-native orchestration for supply chain analytics.
India
Bengaluru's SaaS startups and Mumbai's financial institutions drive managed hosting consumption. RBI data localization guidelines mandate domestic processing for payment systems. The Hyderabad-Chennai corridor attracts hyperscale investments targeting ASEAN market latency requirements.
Application Hosting Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered service categories. Hyperscale providers with enterprise software ecosystems anchor premium contract value, while regional specialists capture sovereignty-sensitive workloads. Three archetypes dominate: infrastructure-integrated platforms, managed services specialists, and sovereign-certified national champions. Competitive moves concentrate on M&A for operational talent and strategic partnerships for edge facility deployment.
Within the infrastructure-integrated tier, Amazon Web Services, Microsoft Azure, and Google Cloud exemplify platform gravity strategies. These entities anchor hybrid deployment pipelines through enterprise licensing entrenchment and container-native orchestration capabilities. Their positioning reflects capital-intensive facility replication across national jurisdictions to satisfy data residency mandates.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud |
| IBM Cloud |
| Oracle Cloud |
| Rackspace Technology |
| DXC Technology |
| DigitalOcean |
| Alibaba Cloud |
| Others |
Supply Flow & Price Mechanics
European power purchase agreement indices cascade through data center operating costs into tiered hosting rate cards. Frankfurt's grid pricing volatility feeds through hyperscale facility economics, compressing margins on standard compute tiers while sovereign-certified environments command resilience premiums.
Pricing Analysis
Short lead-time provisioning commands substantial premiums as enterprises accelerate cloud migrations under NIS2 compliance deadlines. Three-tier pricing structure across premium, standard, and economy levels separates managed hosting with 24/7 site reliability engineering from self-service infrastructure pools. Price differentiation hinges on GDPR certification grade and renewable energy matching credentials. Pricing pressure stems from energy input cost volatility in Hesse and Bavaria facilities. Mid-market enterprises in Belgium and the Netherlands exhibit highest price sensitivity, preferring unbundled consumption-based billing.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German automotive OEMs and French aerospace contractors, while value-added resellers serve mid-market segments. Supply concentrates in Germany, the Netherlands, and Ireland for European data center capacity. Raw material dependencies center on lithium-ion battery storage systems, advanced cooling equipment, and high-purity silicon for semiconductor fabrication. Single-source vulnerability in specialized HVAC equipment creates chokepoint exposure. Distribution runs through certified systems integrators for sovereign cloud workloads requiring ANSSI or BSI clearance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Application hosting architectures are transitioning from monolithic virtual machines to container-native orchestration, with Kubernetes displacing legacy provisioning pipelines across European financial services and manufacturing verticals.
For Market Incumbents: Lock in hybrid cloud anchoring through enterprise licensing gravity and sovereign zone facility replication. Defend against emerging pure-play specialists by deepening managed services attach rates. Prioritize certification investment for EU AI Act high-risk workload attestation. Vertical integration into edge micro-data centers secures latency-critical manufacturing telemetry contracts.
For New Entrants and Emerging Players: Capture underpenetrated predictive maintenance workloads in Germany's Mittelstand industrial IoT sector. Green hosting certification aligned with CSRD disclosure requirements opens premium contract access. Target confidential computing convergence for sensitive multi-tenant migration previously blocked by security constraints.
For Investors and Strategic Acquirers: Distressed-cycle entries favor managed services specialists with NIS2-ready operational cadences in secondary European markets. Long-term viability favors providers with demonstrated sovereign cloud certification velocity and renewable energy matching capabilities. Site reliability engineering talent scarcity serves as the critical inflection signal for operational quality differentiation.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | ANSSI and BSI clearance unlocks French and German government contract pools under NIS2 mandates. |
| Edge Facility Deployment | Micro-data centers within 10 milliseconds of Stuttgart manufacturing sites capture autonomous vehicle telemetry workloads. |
| Managed Services Unbundling | Operational expenditure alignment with actual utilization patterns attracts Belgian and Dutch mid-market procurement. |
| Confidential Computing Integration | Hardware-based trusted execution environments enable sensitive workload migration to multi-tenant infrastructure. |
| Renewable Energy Matching | EU Green Deal alignment commands contract premiums from carbon-conscious enterprise buyers. |
Methodological Framework
Document review covered hyperscaler capex disclosures, EU regulatory filings, and data center industry association reports, complemented by interviews with cloud infrastructure architects, managed services procurement officers, and sovereign cloud compliance leads. Secondary validation drew from NIS2 implementation guidance, EU AI Act technical standards, and facility energy consumption benchmarks. Bottom-up capacity modeling triangulated against top-down enterprise IT spending surveys.
Segment-level outputs across deployment model, service type, operating system, and end user dimensions were calibrated against actual contract value flows. CAGRs were derived from facility expansion pipelines, enterprise workload migration surveys, and regulatory compliance timeline acceleration. Container-native adoption curves and edge compute investment trajectories served as industry-specific forecast inputs across the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act enforcement consistency and transatlantic data adequacy rulings. Forecasts reflect assumptions regarding grid pricing stability and sovereign certification reciprocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
United States Cloud Computing Market
Cloud Computing
Cloud Continuum Market
Cloud Computing
Canada Cloud Computing Market
Cloud Computing
Global Mobile Cloud Market
Cloud Computing
Bare Metal Cloud Market
Cloud Computing
Global Public Cloud Service Market
Cloud Computing
Hyperscale Cloud Market
Cloud Computing
Cloud Infrastructure-As-A-Service Market
Cloud Computing
Global Cloud/Mobile Backend AS a Service (Baas) Market
Cloud Computing
Asia Pacific Multi-Cloud Management Market
Cloud Computing
Cloud IT Service Management (ITSM) Market
Cloud Computing
Public Cloud Market
Cloud Computing
Community Cloud Market
Cloud Computing
Global Cloud Management Software Market
Cloud Computing
Data Virtualization Cloud Market
Cloud Computing
Global Cloud Computing Iaas in Life Science Market