
 Global Gamification Software Market | 2026-2036
Global Gamification Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gamification Software Market Foresight
Workforce analytics talent scarcity is reorganizing competitive dynamics as vendors race to build behavioral science and machine learning capabilities. Microsoft Corporation leverages its Azure cloud infrastructure and Office 365 integration to dominate enterprise deployment channels. SAP SE anchors its position through deep ERP connectivity and pre-built HR process modules. Cognizant Technology Solutions Corp. competes by combining implementation services with proprietary platform customization for Fortune 500 clients.
Gamification software comprises configurable platforms that apply game mechanics—points, badges, leaderboards, and narrative progression—to non-game contexts, typically delivered through API-connected cloud architectures with real-time analytics dashboards. The primary commercial purpose centers on measurable behavior modification for workforce productivity, customer retention, and learning outcomes. Cloud-Based deployment leads absolute revenue contribution due to lower upfront infrastructure costs and faster implementation cycles, while Employee Engagement solutions capture disproportionate margin pools as organizations prioritize retention metrics. Training & Development applications are expanding fastest within regulated industries requiring certified competency tracking.
The EU AI Act and GDPR impose algorithmic transparency and data governance requirements on European deployments, compelling vendors to build explainable recommendation engines and localized data residency options. In the United States, OSHA guidelines on workplace stress monitoring and SEC climate disclosure rules indirectly shape how gamification metrics integrate with broader corporate reporting frameworks. Stakeholders must monitor evolving cross-border data localization mandates and emerging neuroethics standards governing dopamine-loop design patterns in enterprise software.
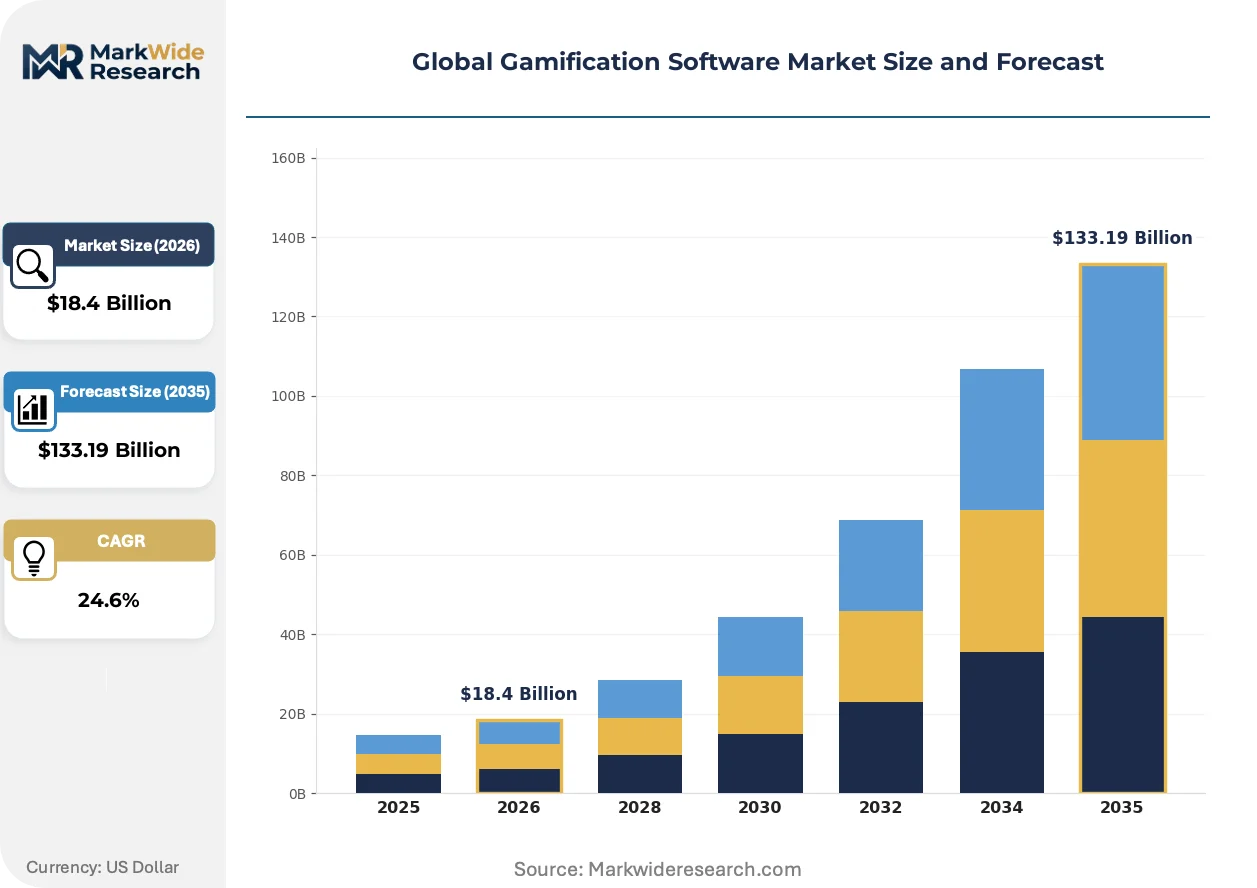
Market Dynamics
AI-driven personalization engines are compressing implementation timelines and forcing vendors to rearchitect cloud-native platforms around real-time behavioral inference rather than static rule-based mechanics.
Growth Catalysts
- OSHA workplace stress guidelines:US employers deploy gamification metrics to document psychosocial safety compliance, creating procurement pull for certified engagement platforms.
- Hybrid workforce retention mandates:German industrial conglomerates require measurable productivity tools for distributed engineering teams, accelerating enterprise license expansion.
- API-first cloud architectures:Microservices integration with existing HRIS stacks reduces deployment friction and expands addressable mid-market accounts.
Market Restraints
- GDPR algorithmic transparency requirements:EU deployments require explainable recommendation engines, adding 15-20% to platform development costs and extending sales cycles.
- Behavioral science talent scarcity:Machine learning engineers with organizational psychology expertise command premium compensation, constraining vendor R&D scaling.
- Legacy ERP integration complexity:On-premise SAP and Oracle installations in Japanese manufacturing create technical debt that slows cloud migration timelines.
Strategic Opportunities
- India's PLI scheme for IT/ITES:Domestic software development incentives attract platform engineering centers serving Asia-Pacific mid-market demand.
- Neuroethics-compliant dopamine-loop design:Emerging ISO standards for ethical engagement mechanics create first-mover advantage for certified vendors.
- Convergence of AR/VR with spatial computing:Immersive training modules for hazardous environment simulation open regulated industry verticals.
Industry Challenges
- Cross-functional implementation expertise:Deployments require coordinated HR, IT, and legal stakeholder alignment that most organizations lack internally.
- EU AI Act compliance timelines:Risk classification documentation and human oversight protocols demand specialized regulatory technology investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gamification Software Market |
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $133.19 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Private Cloud Solution Type: Employee Engagement, Customer Loyalty, Training & Development, Marketing Campaigns, Productivity Enhancement Application: Education & E-Learning, Human Resource Management, Healthcare Motivation, Corporate Innovation, Financial Services Incentives End User: Enterprises, Small & Medium Businesses, Nonprofits, Government Agencies, Educational Institutions |
| Companies Covered | Microsoft Corporation, SAP SE, Cognizant Technology Solutions Corp., Aon plc, Axonify Inc., Centrical, Hoopla, Influitive, BI Worldwide, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gamification Software Market Shifts & Advancements
Generative AI is compressing content production cycles for personalized challenge narratives, while neuroadaptive interfaces and federated learning architectures reshape how platforms balance engagement intensity with cognitive load management.
Adaptive difficulty algorithms powered by reinforcement learning are displacing static point-and-badge systems in enterprise training deployments. Financial services and healthcare organizations in the United States adopt these engines fastest, driven by SEC climate disclosure requirements that gamify ESG compliance tracking. The structural consequence is collapsing content refresh cycles from quarterly to real-time.
The EU AI Act's risk-based classification system imposes documentation burdens on high-stakes workforce monitoring applications. Vendors must implement human-in-the-loop oversight and algorithmic impact assessments for predictive performance scoring. German automotive and French pharmaceutical manufacturers face the steepest compliance costs, prompting localized data residency investments.
Subscription unbundling is fragmenting traditional platform licensing into modular capability purchases. Mid-market buyers in Japan and South Korea procure standalone analytics dashboards without full engagement suites, forcing vendors to restructure pricing around API call volumes rather than seat counts. This pattern is most visible in professional services and technology consulting verticals.
Global Gamification Software Market Segmentation
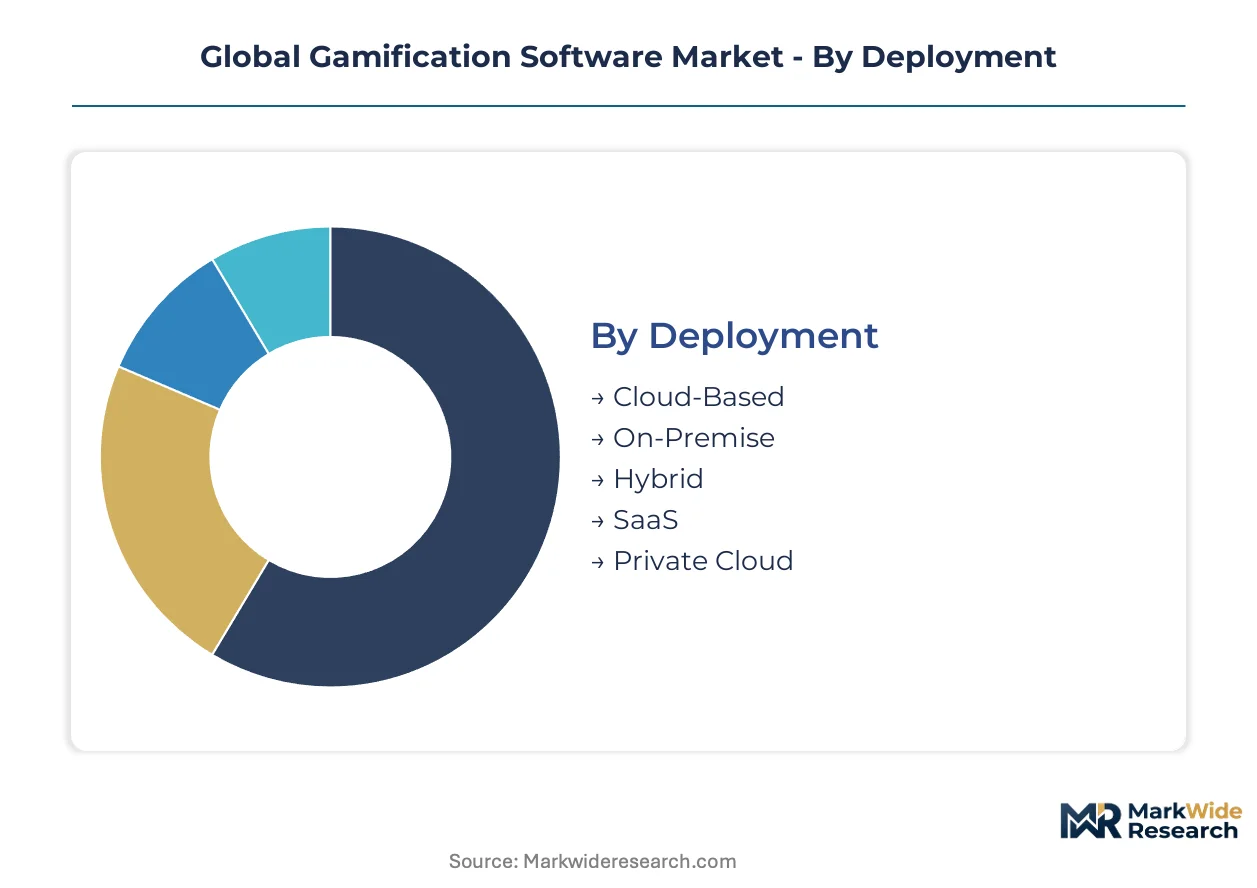
Gamification software architectures diverge sharply across deployment models, solution types, and end-user sophistication levels. Procurement patterns in Germany, Japan, and the United States reveal how regulatory environments and IT maturity reshape segment prioritization across enterprise accounts.
Deployment:
Cloud-Based and SaaS deployments concentrate demand in export-led technology hubs, while On-Premise and Private Cloud solutions serve data-sovereignty-sensitive domestic markets in Japan and EU member states.
- Cloud-Based:Multi-tenant architectures with API-native integration reduce implementation cycles for mid-market buyers. Demand clusters in United States technology corridors and German industrial regions where hybrid workforce mandates accelerate procurement.
- SaaS:Subscription licensing with automatic feature updates dominates professional services verticals. French consulting firms and United Kingdom financial services deploy these solutions fastest to bypass internal IT bottlenecks.
- On-Premise:Air-gapped installations serve Japanese automotive manufacturers with legacy ERP dependencies and strict data localization requirements.
- Hybrid:Split processing architectures balance sensitive workforce data on-site with analytics workloads in cloud environments; German pharmaceutical conglomerates favor this model for GDPR compliance.
- Private Cloud:Single-tenant dedicated instances address United States defense contractors and healthcare systems under HIPAA constraints.
Cloud-Based holds the largest share; momentum sits with SaaS as procurement decentralizes to line-of-business buyers.
Solution Type:
Cost tier stratification separates enterprise-grade platforms with behavioral science teams from self-serve tools targeting budget-constrained segments.
- Employee Engagement:Comprehensive platforms integrating pulse surveys, recognition systems, and predictive attrition scoring command premium pricing. United States Fortune 500 accounts and German automotive suppliers drive procurement volume under hybrid retention mandates.
- Training & Development:Adaptive learning paths with certification tracking expand fastest in regulated United States healthcare and financial services verticals facing SEC climate disclosure and OSHA competency documentation requirements.
- Customer Loyalty:Points-based retention mechanics with real-time redemption APIs serve Japanese retail banking and United States e-commerce marketplaces.
- Marketing Campaigns:Campaign-specific challenge modules with social sharing mechanics attract mid-market consumer brands in South Korea and Brazil.
- Productivity Enhancement:Task-level gamification with workflow integration targets professional services firms in the United Kingdom and Australia.
Employee Engagement commands the steepest pricing tier; Training & Development gains share fastest as compliance documentation requirements harden.
Application:
Volume concentration varies by regulatory intensity, with Human Resource Management and Financial Services Incentives scaling through enterprise accounts while Healthcare Motivation remains constrained by FDA and EMA oversight timelines.
- Human Resource Management:Performance management, onboarding, and succession planning modules with predictive analytics. German industrial conglomerates and United States technology firms deploy these at scale for distributed engineering teams.
- Financial Services Incentives:ESG compliance tracking and advisor certification gamification. United States asset managers adopt these fastest under SEC climate disclosure rules requiring documented engagement metrics.
- Education & E-Learning:K-12 and higher education credentialing platforms with competency-based progression; adoption concentrates in United States charter school networks and Indian technical institutes.
- Healthcare Motivation:Patient adherence and clinical trial participation incentives; EU AI Act risk classifications slow European deployment timelines.
- Corporate Innovation:Ideation platforms with crowd-sourced challenge mechanics serve Japanese electronics manufacturers and United States pharmaceutical R&D divisions.
Human Resource Management dominates absolute deployment volume; Financial Services Incentives climbs fastest as regulatory disclosure frameworks expand.
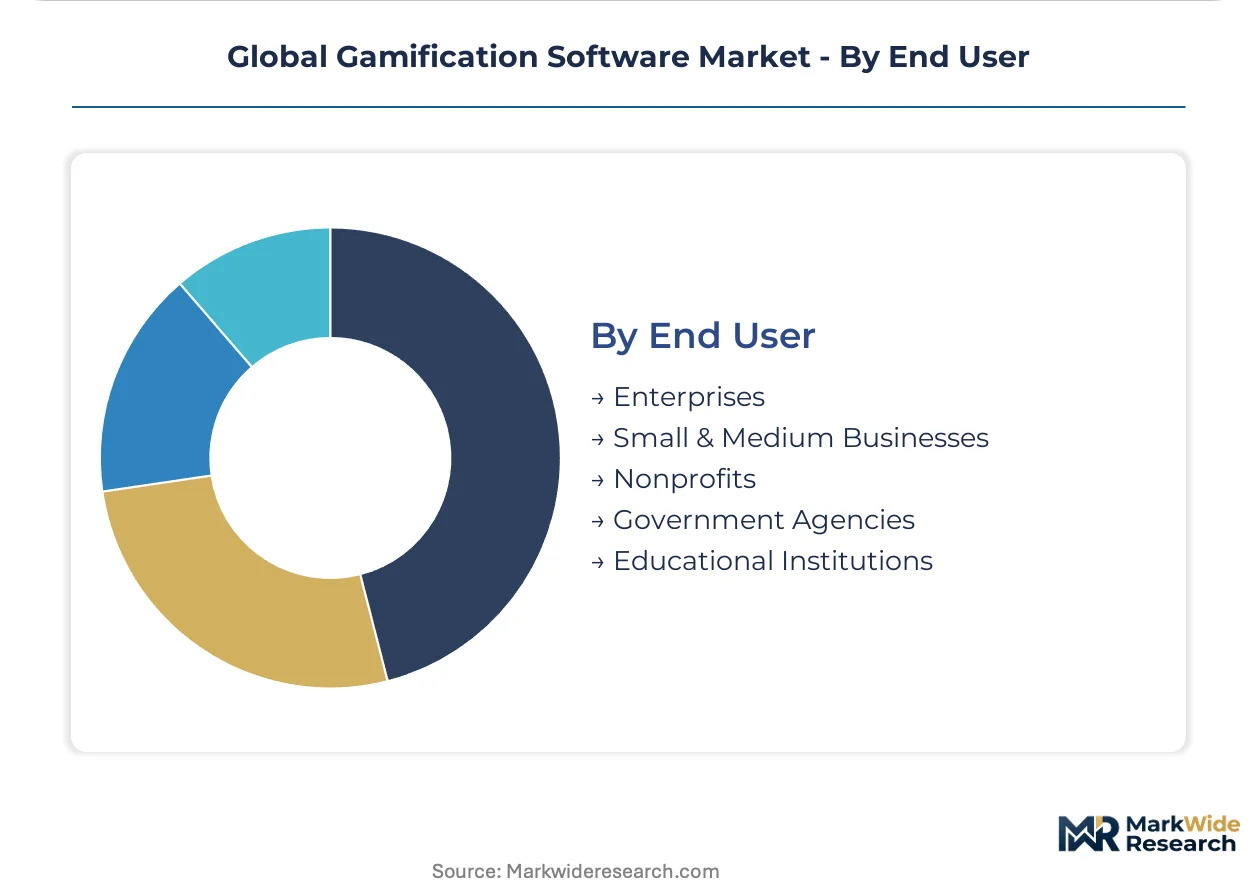
End User:
Customer maturity stratification separates Enterprises with dedicated change management functions from Small & Medium Businesses purchasing through channel partners.
- Enterprises:Global deployments requiring multi-language support, SSO integration, and custom behavioral science consulting. United States and German headquarters drive standardization across regional subsidiaries.
- Small & Medium Businesses:Self-serve configurations with pre-built templates and limited customization; fastest adoption in United Kingdom professional services and Australian technology consultancies.
- Government Agencies:Federal and state workforce development programs with accessibility compliance requirements; United States and Canadian public sector accounts lead procurement.
- Educational Institutions:University and K-12 systems with FERPA and GDPR student data constraints; adoption clusters in United States public university systems and Nordic vocational training networks.
- Nonprofits:Volunteer retention and donor engagement platforms with discounted licensing; deployment concentrates in United States healthcare charities and international development organizations.
Enterprises capture the largest revenue pool; Small & Medium Businesses expand addressable market fastest as channel partnerships mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA workplace stress guidelines and SEC climate disclosure rules anchor procurement momentum in the United States, while GDPR and the EU AI Act reshape European deployment architectures. Cloud-native platforms concentrate in technology corridors across three continents, with regulatory fragmentation driving localized data residency investments.
United States
Fortune 500 enterprises deploy employee engagement platforms under hybrid workforce retention mandates, with financial services firms adopting ESG compliance tracking fastest. SEC disclosure rules require documented engagement metrics for climate risk reporting. Silicon Valley technology corridors and New York financial centers drive standardization across regional subsidiaries.
Germany
Industrial conglomerates require measurable productivity tools for distributed engineering teams, accelerating enterprise license expansion. GDPR algorithmic transparency requirements and EU AI Act risk classifications compel explainable recommendation engine investments. Automotive suppliers in Baden-Württemberg and pharmaceutical manufacturers in Bavaria favor hybrid cloud architectures for data sovereignty.
Japan
Manufacturing headquarters deploy gamification for succession planning and technical certification tracking amid demographic workforce constraints. METI productivity initiatives and strict data localization requirements sustain on-premise and private cloud demand. Automotive clusters in Toyota City and electronics manufacturers in Osaka-Kobe prioritize legacy ERP integration over cloud migration.
United Kingdom
Professional services firms and financial institutions adopt SaaS deployments to bypass internal IT bottlenecks, with consulting verticals driving fastest subscription growth. Post-Brexit data adequacy arrangements influence cloud provider selection for EU-facing operations. London financial services and Manchester technology consultancies procure standalone analytics dashboards without full engagement suites.
India
Domestic IT/ITES sectors and technical training institutes expand platform adoption under PLI scheme incentives for software development centers. BIS standards and RBI data localization guidelines shape cloud architecture decisions for banking deployments. Bengaluru technology corridors and Hyderabad IT hubs serve Asia-Pacific mid-market demand through engineering centers.
Global Gamification Software Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with cloud infrastructure incumbents and ERP-anchored platforms commanding enterprise deployment channels. The upper tier consolidates around behavioral science capabilities and real-time analytics engines, while mid-market specialists compete through API-first architectures and modular pricing. Three archetypes dominate: hyperscale cloud integrators, ERP-connected platform builders, and implementation-heavy service bundlers. Competitive moves center on M&A for machine learning talent and strategic partnerships to compress cross-functional deployment timelines.
Within the integrated leader tier, Microsoft Corporation and SAP SE exemplify contrasting anchoring strategies—one through cloud infrastructure dominance, the other through deep ERP connectivity. Cognizant Technology Solutions Corp. occupies a distinct position combining implementation services with platform customization for complex enterprise deployments. These three entities represent the primary competitive vectors reshaping how vendors address workforce analytics talent scarcity and regulatory compliance burdens.
| Leading Market Players |
|---|
| Microsoft Corporation |
| SAP SE |
| Cognizant Technology Solutions Corp. |
| Aon plc |
| Axonify Inc. |
| Centrical |
| Hoopla |
| Influitive |
| BI Worldwide |
| Others |
Supply & Pricing Matrix
Multi-year enterprise licensing with automatic renewal clauses locks in both cloud infrastructure access and predictable cost visibility for buyers navigating GDPR compliance burdens and AI Act documentation requirements. This contract structure concentrates pricing power with vendors possessing localized data residency capabilities while forcing mid-market buyers into modular API consumption models that fragment traditional seat-based economics.
Pricing Analysis
Geographic price spreads of 40-60% separate North American enterprise deployments from Asia-Pacific mid-market configurations, reflecting divergent regulatory compliance costs and behavioral science consulting depth. Three-tier pricing structure across premium, standard, and economy levels anchors on integration complexity and explainable AI certification status rather than raw feature count. Cost compression in the economy tier is intensifying because Indian IT hubs and Southeast Asian consultancies are repackaging open-source gamification engines with minimal customization. Small and medium businesses exhibit highest price sensitivity, while German automotive conglomerates and United States defense contractors accept premium tiers for hybrid cloud sovereignty guarantees.
Supply Chain Analysis
Machine learning engineering talent pipelines in India, Poland, and Vietnam constitute the primary chokepoint constraining vendor R&D scaling and implementation service expansion. Platform development draws from cloud infrastructure provisioning, behavioral science research partnerships, and API middleware integration rather than physical component assembly. Single-source vulnerability concentrates in hyperscaler cloud dependencies, where Microsoft Azure, Amazon Web Services, and Google Cloud control compute access for 80% of enterprise deployments. Distribution runs through direct enterprise sales teams for Fortune 500 accounts, systems integrators for mid-market penetration, and regional value-added resellers in data-sovereignty-sensitive markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in the mid-market segment, where subscription unbundling and API-first procurement patterns are dismantling incumbent platform bundling strategies and creating entry points for specialized vendors with targeted compliance capabilities.
For Market Incumbents: Compound defensive positioning through acquisition of behavioral science boutiques with EU AI Act documentation expertise and accelerated investment in explainable recommendation engine architectures. The threat of modular pricing erosion from Indian engineering centers demands preemptive channel control through exclusive systems integrator partnerships. Vertical integration into federated learning infrastructure represents the critical lever for maintaining margin differentiation against API-only competitors. For New Entrants and Emerging Players: ISO neuroethics certification fast-track offers regulatory legitimacy without multi-year incumbent compliance debt, opening immediate access to German pharmaceutical and French healthcare verticals. White-space targets concentrate on United Kingdom professional services firms purchasing standalone analytics dashboards and Japanese manufacturing suppliers requiring legacy ERP integration without full platform replacement. Channel partnership with regional IT consultancies provides the most penetrable go-to-market angle against direct sales-heavy incumbents. For Investors and Strategic Acquirers: API-native mid-market specialists with pre-built HRIS connectors and modular pricing infrastructure represent the priority acquisition archetype for platform consolidation plays. Long-term viability across the analysis window hinges on regulatory technology capabilities that transform compliance burden into competitive moat. The signal to watch is accelerated procurement velocity in India's PLI-subsidized IT corridors, indicating whether Asia-Pacific demand can sustain independent vendor economics outside hyperscaler shadow.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Behavioral Science Boutique | EU AI Act documentation capabilities differentiate enterprise sales cycles in German automotive verticals. |
| Federated Learning Infrastructure Investment | Privacy-preserving model training satisfies GDPR data residency requirements without cloud migration. |
| API-First Platform Unbundling | Modular consumption models capture mid-market buyers bypassing full-suite procurement approvals. |
| Neuroethics Certification Program | ISO-compliant engagement mechanics preempt regulatory scrutiny on dopamine-loop design patterns. |
| Regional Systems Integrator Partnership | Localized implementation expertise compresses deployment timelines for Japanese legacy ERP environments. |
Research Methodology
The analysis maps cloud deployment architectures, solution type configurations, and end-user sophistication tiers, each validated through CTOs, HR technology procurement officers, platform engineers, and channel partners across primary interview programs. Secondary validation incorporates SEC 10-K filings, hyperscaler capex disclosures, EU regulatory impact assessments, and industry association workforce technology surveys. Bottom-up sizing of vendor revenue pipelines and top-down triangulation against enterprise software spending benchmarks ensure cross-method consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with particular attention to cloud migration velocity in Japanese manufacturing and compliance-driven procurement acceleration in German industrial sectors. Segmentation dimensions modeled include deployment model, organization size, vertical industry, integration complexity, and regional regulatory cluster. CAGRs were derived through logistic diffusion curves applied to enterprise adoption saturation levels, incorporating AI personalization engine penetration rates and behavioral science talent supply constraints as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained hybrid workforce mandates, stable cross-border data flow arrangements, and continued hyperscaler infrastructure investment would require recalibration. Forecasts reflect documented assumptions regarding regulatory timeline adherence and talent pipeline expansion. Practitioners should keep alternative scenarios live as EU AI Act enforcement intensity and OSHA workplace stress guideline implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Embedded Hypervisor Software Market
Software & Services
Tech Support Services Market
Software & Services
Global Content Management Software Market
Software & Services
Application Development and Modernization (ADM) Market
Software & Services
Global Online Assessment Software Market
Software & Services
Latin America Human Resource (HR) Technology Market
Software & Services
Video Management Software (VMS) Market
Software & Services
Animation Design Software Market
Software & Services
Team Collaboration Software Market
Software & Services
Ad Creation Software Market
Software & Services
Sales Performance Management (SPM) Software Market
Software & Services
Global Self-Service BI Market
Software & Services
Global App Builder Software Market
Software & Services
Lead-To-Account Matching and Routing Software Market
Software & Services
Lawn Care Software Market
Software & Services
Open Stack Service Market