
 Membrane Bioreactor Market | 2026-2036
Membrane Bioreactor Market Size, Share, and Industry Trends Forecast 2026-2036
Membrane Bioreactor Market Intelligence
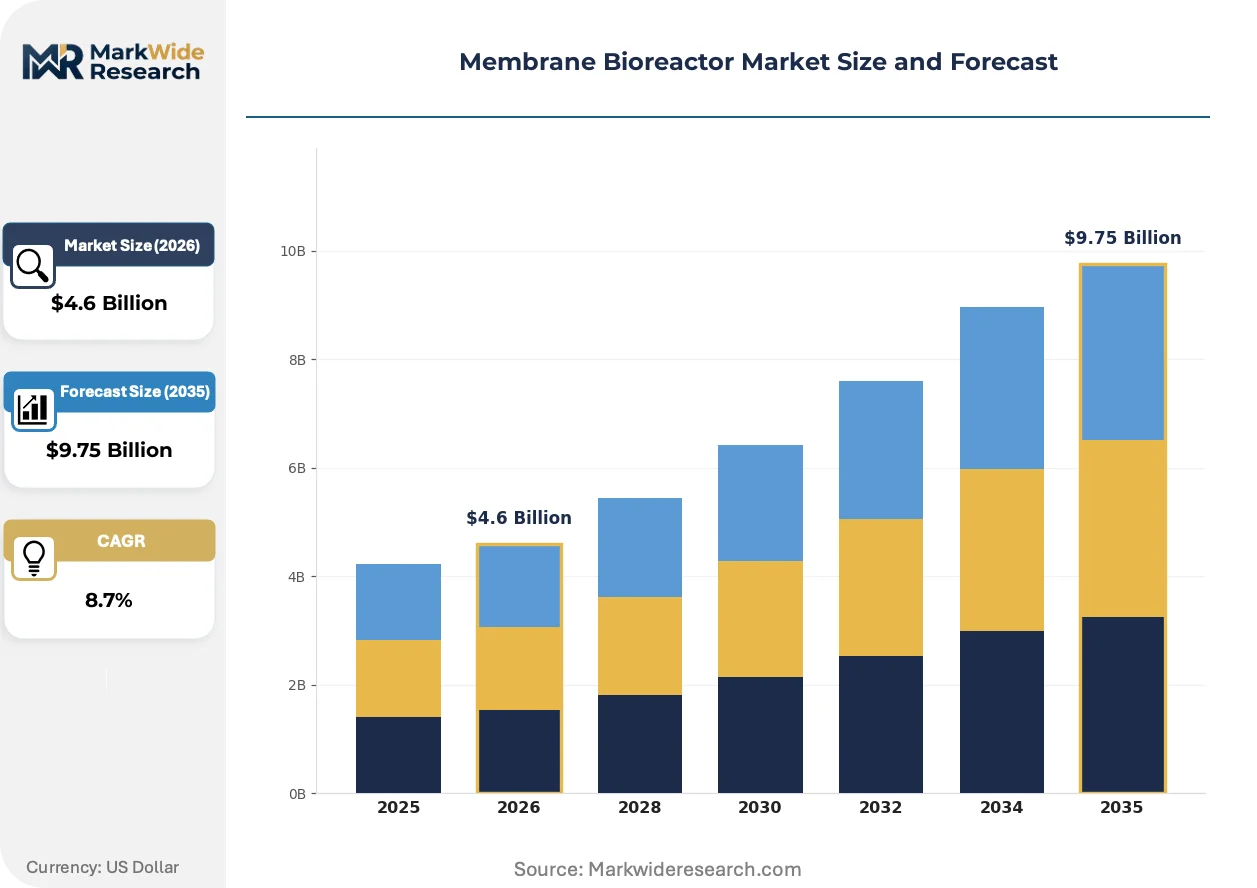
Ultra-low transmembrane pressure specifications is collapsing the cost barrier between conventional activated sludge and membrane bioreactor installations. TORAY INDUSTRIES, INC. leverages its hollow-fiber manufacturing depth to dominate Japanese municipal retrofits. Veolia sustains project finance capabilities that anchor large-scale European build-operate-transfer contracts. Pentair competes through packaged system standardization that reduces commissioning timelines for North American industrial buyers.
A membrane bioreactor integrates suspended growth biological treatment with membrane filtration, typically operating at flux rates of 15–40 liters per square meter per hour to retain biomass while producing clarified effluent. The process eliminates secondary clarifiers and enables direct reuse-grade water output from compact footprints. Submerged configurations lead system type demand due to lower energy intensity and reduced cleaning frequency versus side-stream alternatives. Polymeric membranes anchor material volume, though ceramic segments attract interest from pharmaceutical end users seeking thermal sterilization compatibility and extended chemical cleaning tolerance.
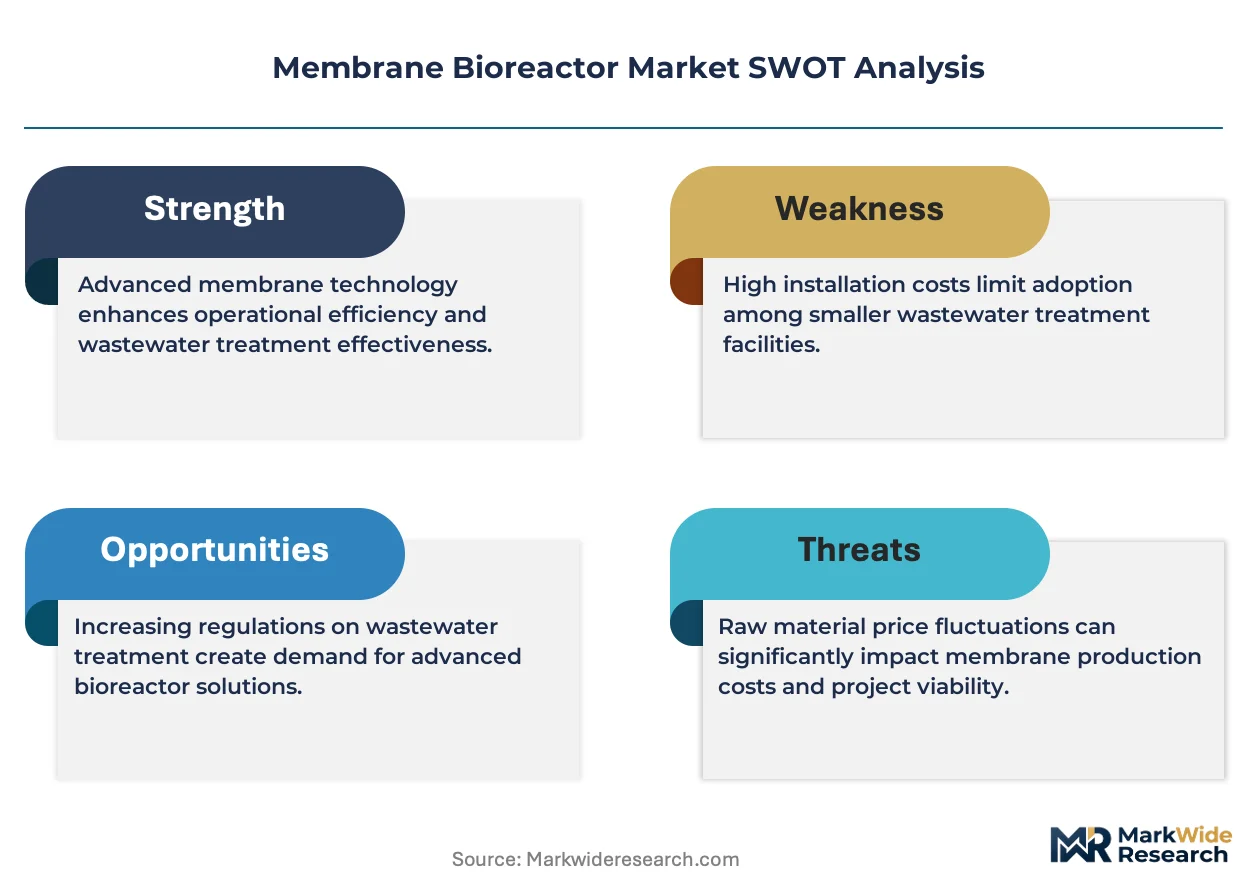
EPA effluent limitation guidelines in the United States, EU Urban Wastewater Treatment Directive revisions, and China's MEE surface water quality standards are collectively tightening biochemical oxygen demand and total nitrogen discharge thresholds. These frameworks force municipalities and industrial facilities toward advanced biological treatment with membrane-based solids separation. Stakeholders must monitor regulatory timeline acceleration in water-stressed regions where membrane bioreactor capex premiums compress against escalating non-compliance penalties.
Market Dynamics
Ultra-low transmembrane pressure specifications are collapsing the cost barrier between conventional activated sludge and membrane bioreactor installations, forcing municipal utilities and industrial facilities toward membrane-based solids separation as the default upgrade path.
Growth Catalysts
- EU Urban Wastewater Treatment Directive revisions:Tightening biochemical oxygen demand and total nitrogen discharge thresholds across Germany, France, and the Netherlands are accelerating municipal retrofit timelines.
- Zero-liquid-discharge mandates:China's MEE surface water quality standards in coastal provinces are concentrating demand for submerged system configurations with reduced energy intensity.
- Hollow-fiber membrane manufacturing:Advances in polymeric membrane production are lowering unit costs and enabling direct reuse-grade water output from compact footprints.
Market Restraints
- Polymer feedstock volatility:Specialized fluoropolymer and PVDF resin prices fluctuate with petrochemical cycles, compressing module manufacturer margins during input spikes.
- Technical fouling limitations:Irreversible membrane fouling in high-strength industrial streams shortens operational lifespans and increases chemical cleaning frequency.
- Side-stream substitution:Conventional activated sludge with tertiary filtration retains cost advantages for low-reuse applications in budget-constrained municipalities.
Strategic Opportunities
- Pharmaceutical thermal sterilization:Ceramic membrane segments attract sterile manufacturing applications requiring extended chemical cleaning tolerance and steam sterilization compatibility.
- Build-operate-transfer contracts:European water utilities are outsourcing capital-intensive upgrades to project finance specialists under long-term service agreements.
- Industrial packaged systems:Standardized skid-mounted configurations reduce commissioning timelines for North American food and beverage processors seeking rapid deployment.
Industry Challenges
- Membrane integrity testing protocols:Automated fiber-break detection and regulatory compliance documentation require specialized technician training that outpaces workforce development.
- Legacy clarifier integration:Retrofitting existing activated sludge infrastructure with submerged membrane cassettes demands complex hydraulic rebalancing and civil modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Membrane Bioreactor Market |
| Market Size in 2026 | $4.6 Billion |
| Market Size in 2035 | $9.75 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Submerged, Suspended, Side-stream, Hybrid Membrane Material: Polymeric, Ceramic, Composite, Others Application: Wastewater Treatment, Water Reclamation, Industrial Processes, Aquaculture End User: Municipalities, Food & Beverage, Pharmaceuticals, Mining |
| Companies Covered | TORAY INDUSTRIES, INC., Dupont, Veolia, Pentair, Xylem, KUBOTA Corporation, Kovalus Separation Solutions, Mann+Hummel, Mitsubishi Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Membrane Bioreactor Market Strategic Shifts & Innovations
Membrane bioreactor technology is converging with digital process control and advanced materials science, creating new performance tiers that separate premium system integrators from commodity module suppliers.
Membrane cassette design is miniaturizing through enhanced packing density and optimized aeration scouring patterns. Pharmaceutical manufacturers in Switzerland and Germany are adopting these compact configurations for onsite wastewater reclamation. The technology is miniaturizing footprint requirements by forty percent versus first-generation submerged systems, enabling installation in dense urban sites previously excluded from membrane bioreactor deployment.
EPA effluent limitation guidelines in the United States are tightening nutrient discharge thresholds for municipal treatment plants serving populations above ten thousand. These rules force secondary clarifier replacement with membrane-based solids separation in aging infrastructure corridors. Industrial facilities in the Great Lakes basin are responding fastest, driven by watershed-specific total phosphorus caps.
Service unbundling is fragmenting traditional equipment-procurement relationships. North American industrial buyers now separate membrane module supply from biological process design and long-term operations contracts. Chemical processors in the Texas Gulf Coast cluster are pioneering this multi-vendor approach, using competitive bidding for each lifecycle phase rather than single-source turnkey agreements.
Membrane Bioreactor Market Segmentation
Membrane bioreactor purchasing decisions cascade across four interlocking dimensions—system architecture, membrane chemistry, application severity, and end-user capital cycles. Each axis carries distinct margin profiles and technical validation requirements that reshape vendor positioning.
System Type:
Margin pools concentrate in submerged configurations where energy efficiency and reduced cleaning frequency command pricing premiums over side-stream alternatives.
- Submerged:Membrane cassettes sit directly within the bioreactor tank, enabling lower transmembrane pressure operation and reduced aeration energy. Demand concentrates in coastal Chinese provinces facing MEE zero-liquid-discharge mandates where footprint constraints and power costs dominate procurement criteria.
- Side-stream:External membrane loops handle higher solids concentrations and enable modular capacity expansion. Food and beverage processors in Germany favor this architecture for variable wastewater loads requiring operational flexibility without full-scale tank reconstruction.
- Suspended:Free-floating membrane carriers reduce fouling through enhanced scouring motion. Mining operations in Australia deploy suspended systems for high-total-suspended-solids tailings water where conventional cassette fouling rates prove prohibitive.
- Hybrid:Combinations integrate submerged biological stages with side-stream polishing for reuse-grade output. Pharmaceutical manufacturers in Switzerland adopt hybrid flows to balance compact footprint against validated sterile filtration requirements.
The dominant share belongs to Submerged, while Hybrid is closing the gap fastest as water-stressed regions tighten reuse specifications.
Membrane Material:
Material selection tracks directly against chemical cleaning tolerance requirements and thermal sterilization needs across end-use verticals.
- Polymeric:PVDF and PES hollow-fiber matrices dominate unit economics through scalable extrusion manufacturing. Municipal utilities in Japan prioritize polymeric modules for retrofit projects where capital constraints override extended-lifecycle considerations.
- Ceramic:Aluminum oxide and silicon carbide structures withstand steam sterilization and aggressive chemical cleaning protocols. Pharmaceutical sterile manufacturing applications in Germany and Switzerland anchor ceramic demand despite three-to-five-x capital cost premiums.
- Composite:Polymeric substrates with ceramic coatings balance cost and chemical resistance. Industrial processors in the Texas Gulf Coast cluster evaluate composites for refinery wastewater containing intermittent hydrocarbon spikes.
- Others:Metallic membranes and emerging graphene-based materials occupy niche high-temperature or extreme-pH applications. Research installations in the Netherlands pilot these alternatives for thermophilic anaerobic MBR configurations.
Polymeric modules capture the volume base, though Ceramic is expanding most quickly as biopharma manufacturing scales.
Application:
Application segmentation reflects divergent regulatory stringency and water value recovery potential across discharge and reuse scenarios.
- Wastewater Treatment:Biological oxygen demand and nutrient removal for compliant discharge. Municipal utilities in France accelerate deployment under EU Urban Wastewater Treatment Directive revisions tightening total nitrogen thresholds.
- Water Reclamation:Direct potable and non-potable reuse applications requiring pathogen and trace contaminant barriers. Singapore's NEWater program and California's Title 22 regulations drive specification convergence.
- Industrial Processes:Closed-loop water systems for cooling, boiler feed, and process integration. Semiconductor fabs in Taiwan deploy MBR pretreatment for ultrapure water generation where particulate loading threatens downstream reverse osmosis membranes.
- Aquaculture:Recirculating aquaculture system water quality management with ammonia and solids control. Norwegian salmon farming operations integrate MBR for land-based hatchery effluent treatment.
Wastewater Treatment retains the installed base majority, while Water Reclamation is gaining share fastest as scarcity economics intensify.
End User:
End-user segmentation reveals distinct procurement patterns between public-sector capital cycles and industrial operational expenditure frameworks.
- Municipalities:Public financing, long asset lifecycles, and regulatory compliance drivers dominate. Build-operate-transfer contracting structures in the Netherlands and Germany transfer construction risk to private operators.
- Food & Beverage:High-organic-strength wastewater with seasonal variability and water reuse potential. Dairy processors in Wisconsin and brewing operations in Belgium prioritize packaged systems with rapid commissioning.
- Pharmaceuticals:Validated processes, batch discharge variability, and thermal sterilization requirements. Swiss and German sterile manufacturing sites specify ceramic membranes with full steam-in-place capability.
- Mining:High-salinity, metal-laden, and remote-location challenges with tailings management pressures. Copper operations in Chile and gold extraction in Western Australia deploy MBR for process water recovery.
Municipalities command the largest revenue pool, though Pharmaceuticals is climbing the fastest on sterilization-grade specification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for hollow-fiber membrane modules concentrates procurement leverage in Japanese and German manufacturing clusters. Export flows of ceramic membrane systems from Switzerland and packaged skid configurations from the United States shape regional competitive positioning.
China
Zero-liquid-discharge mandates from MEE in coastal provinces are concentrating submerged system deployments. The Yangtze River Delta manufacturing belt is retrofitting chemical parks with membrane-based solids separation. Jiangsu and Zhejiang province utilities are consolidating procurement under provincial water groups to negotiate module supply contracts.
Germany
EU Urban Wastewater Treatment Directive revisions are accelerating municipal retrofit timelines in the Rhine-Ruhr industrial corridor. Build-operate-transfer structures dominate capital-intensive upgrades in North Rhine-Westphalia. Bavarian pharmaceutical manufacturers are specifying ceramic membranes with full steam-in-place validation for sterile manufacturing sites.
Japan
METI efficiency standards for municipal water infrastructure are forcing secondary clarifier replacement in aging treatment plants. Hollow-fiber module manufacturing depth concentrates in the Kanto region around Tokyo. Osaka-Kansai industrial clusters are deploying compact submerged configurations for semiconductor fab process water pretreatment.
United States
EPA effluent limitation guidelines are tightening nutrient discharge thresholds for Great Lakes basin municipalities. Industrial processors in the Texas Gulf Coast chemical corridor are unbundling procurement across module supply and operations contracts. California Title 22 regulations are driving specification convergence for direct potable reuse applications in Los Angeles and San Diego counties.
Switzerland
Swissmedic pharmaceutical manufacturing standards are mandating thermal sterilization compatibility in wastewater reclamation systems. Basel-region biopharma clusters are adopting hybrid membrane configurations balancing compact footprint against validated sterile filtration. Cantonal water authorities are consolidating under federal frameworks that prioritize ceramic membrane procurement for high-reuse applications.
Membrane Bioreactor Market Key Industry Players
Concentration sits with diversified environmental engineering conglomerates and specialized membrane module fabricators. The vendor base splits between integrated system providers capturing municipal build-operate-transfer contracts and component specialists supplying standardized modules for industrial integration. Three archetypes dominate: hollow-fiber manufacturing specialists with polymer extrusion depth, project finance platforms anchoring long-term service agreements, and packaged system integrators compressing commissioning timelines. Competitive dynamics center on technology licensing partnerships and geographic expansion through local assembly licensing.
Within the diversified engineering tier, Veolia and Xylem occupy positions spanning full-system integration to operations contracting. TORAY INDUSTRIES, INC. exemplifies the manufacturing-specialist archetype with hollow-fiber production depth. Pentair represents the packaged-system vector standardizing skid-mounted configurations for rapid industrial deployment.
| Leading Market Players |
|---|
| TORAY INDUSTRIES, INC. |
| Dupont |
| Veolia |
| Pentair |
| Xylem |
| KUBOTA Corporation |
| Kovalus Separation Solutions |
| Mann+Hummel |
| Mitsubishi Chemical Corporation |
| Others |
Cost & Logistics Intelligence
Polymeric membrane substitution for ceramic alternatives in municipal retrofits simultaneously redraws procurement geography toward Japanese and German manufacturing clusters and compresses unit economics at the standard-system tier. Hollow-fiber PVDF production scale in the Kanto region anchors cost-down trajectories that ripple through European build-operate-transfer contracting structures.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Ceramic membrane modules command premiums driven by Swissmedic thermal sterilization validation and extended chemical cleaning tolerance. Cost compression in polymeric hollow-fiber tiers intensifies because Chinese provincial water groups consolidate procurement under volume aggregation frameworks. Municipal utilities in budget-constrained regions exhibit highest price sensitivity, while pharmaceutical sterile manufacturers demonstrate lowest elasticity due to regulatory compliance mandates.
Supply Chain Analysis
Strategic stockpiling of fluoropolymer resin feedstocks dominates procurement behavior among module fabricators facing petrochemical cycle volatility. Hollow-fiber manufacturing concentrates in Japan, Germany, and the United States. Polymeric membrane production draws from specialized PVDF and PES resin streams tethered to global petrochemical networks. Single-source vulnerability sits with concentrated hollow-fiber extrusion equipment suppliers. Distribution runs through direct OEM relationships for large municipal projects and specialized distributors for industrial packaged systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Chinese provincial water groups and European municipal outsourcing consortia, fragmenting traditional single-source vendor relationships into unbundled procurement across module supply, biological design, and long-term operations.
For Market Incumbents: Shield installed-base revenue by securing exclusive hollow-fiber module supply contracts with Japanese municipal utilities under METI efficiency standard retrofits. Deepen backward integration into PVDF resin production to offset polymer feedstock volatility compressing margins. Prioritize certification investment for EU Urban Wastewater Treatment Directive compliance to lock out non-validated competitors from Rhine-Ruhr municipal upgrade cycles.
For New Entrants and Emerging Players: Anchor in suspended membrane configurations for Australian mining tailings applications where conventional cassette fouling rates exclude established submerged-system vendors. Target ceramic membrane aftermarket service contracts for Swiss and German pharmaceutical sterile manufacturing sites requiring steam-in-place validation. Pursue direct sales to Texas Gulf Coast chemical processors unbundling procurement across lifecycle phases.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed European water service platforms holding build-operate-transfer contract portfolios. Long-term viability hinges on regulatory timeline acceleration in water-stressed regions where membrane bioreactor capex premiums compress against non-compliance penalties. Watch for MEE zero-liquid-discharge mandate expansion beyond coastal Chinese provinces as inflection indicator for submerged system demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PVDF Resin Production | Captive supply of fluoropolymer feedstock insulates margin compression from petrochemical price cycles. |
| Ceramic Membrane Steam-in-Place Validation | Swissmedic compliance certification unlocks sterile pharmaceutical manufacturing premium pricing tiers. |
| Provincial Water Group Consolidation | Jiangsu and Zhejiang procurement aggregation shifts bargaining power toward volume discount frameworks. |
| Hybrid System Configuration Development | Submerged-side-stream integration balances compact footprint against reuse-grade validation requirements. |
| Automated Fiber-Break Detection Deployment | Membrane integrity testing protocols reduce specialized technician training bottlenecks constraining workforce expansion. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with municipal utility procurement directors, pharmaceutical facility engineering managers, membrane module manufacturing executives, and water service platform project finance leads. Secondary validation drew from EPA effluent limitation guideline filings, EU Urban Wastewater Treatment Directive revision documents, China MEE surface water quality standard publications, and hollow-fiber membrane patent filings. Bottom-up installation tracking across coastal Chinese provinces, Rhine-Ruhr corridor municipalities, and Japanese Kanto-region utilities was triangulated against top-down revenue estimates from environmental engineering conglomerate disclosures.
Across the analysis window, value projections were derived from segment-level modeling spanning system architecture, membrane chemistry, application severity, and end-user capital cycle dimensions. Modeled inputs included municipal retrofit timelines under regulatory deadline pressure, industrial reuse-grade water value recovery economics, and ceramic versus polymeric membrane substitution elasticities. CAGRs reflect installation volume trajectories weighted by regional pricing differentials and technology mix shifts.
Material uncertainties — polymer feedstock price spikes, irreversible fouling rate variability in high-strength industrial streams, and regulatory timeline acceleration or delay — sit outside the modeled envelope. Forecasts reflect assumptions regarding hollow-fiber manufacturing scale economies and ceramic membrane validation adoption curves. Revision becomes warranted when zero-liquid-discharge mandate geographic expansion crosses thresholds triggering demand inflection beyond baseline regulatory compliance timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Global Nanomembrane Market
Membrane Materials
Global Bitumen Membranes Market
Membrane Materials
Global Ceramic Membrane Market
Membrane Materials
Expansion Vessel Membrane Market
Membrane Materials
Breather Membranes Market
Membrane Materials
Membranes Market
Membrane Materials
Bitumen Waterproofing Membrane Market
Membrane Materials
APP and SBS Modified Bitumen Membrane Market
Membrane Materials
Breathable Films and Membranes Market
Membrane Materials
Industrial Solvent Separation Membranes Market
Membrane Materials
Global Roofing Membranes Market
Membrane Materials
Polysulfone Market
Membrane Materials
Global Track Etched Membrane Market
Membrane Materials
TPO Roofing Membrane Market
Membrane Materials
Fuel Cell Gas Diffusion Layer Market
Membrane Materials
Nanoporous Membranes Market