
 Specialty Breathable Membranes Market | 2026-2036
Specialty Breathable Membranes Market Size, Share, and Industry Trends Forecast 2026-2036
Specialty Breathable Membranes Market Analytics
Healthcare textile demand is realigning the Specialty Breathable Membranes landscape as surgical drapes, wound dressings, and infection-control fabrics absorb higher volumes of microporous films. Covestro AG leverages its polyurethane chemistry leadership to supply medical-grade breathable layers across European hospital networks. Freudenberg SE anchors the hygiene and medical segments with spunbond-meltblown composites engineered for viral barrier performance. W. L. Gore & Associates differentiates through expanded PTFE membranes that dominate protective clothing for hazardous material handling.
Specialty breathable membranes are thin, engineered barriers—typically 10–50 micrometers thick—composed of microporous polymers or monolithic films that block liquid water and particulates while permitting water vapor transmission at rates exceeding 5,000 g/m²/day. These structures serve critical functions in moisture management, thermal comfort, and contamination control across industrial, medical, and consumer applications. Polyurethane dominates product type volumes due to its tunable hydrophilicity and compatibility with thermoplastic processing, while polytetrafluoroethylene commands premium positioning in extreme-chemical-exposure environments. Film lamination technology leads manufacturing throughput for automotive and sportswear applications, whereas coating processes retain margin concentration in medical textiles where lot-to-lot consistency determines regulatory approval.
FDA 21 CFR Part 177 indirect food additive regulations and ISO 10993 biocompatibility standards govern medical membrane commercialization in the United States, while REACH compliance and the EU MDR reshape material selection for European healthcare applications. The EPA's emerging scrutiny of per- and polyfluoroalkyl substances is accelerating fluoropolymer substitution programs among membrane developers. Stakeholders must monitor regulatory timelines for PFAS restrictions and align product roadmaps with bio-based certification schemes before compliance deadlines harden procurement specifications.
Market Dynamics
The EU Green Deal's fluorinated polymer restrictions are compressing incumbent supply chains while bio-based polyurethane R&D accelerates, creating asymmetric pressure on membrane developers with legacy PTFE portfolios versus those pivoting to plant-derived alternatives.
Growth Catalysts
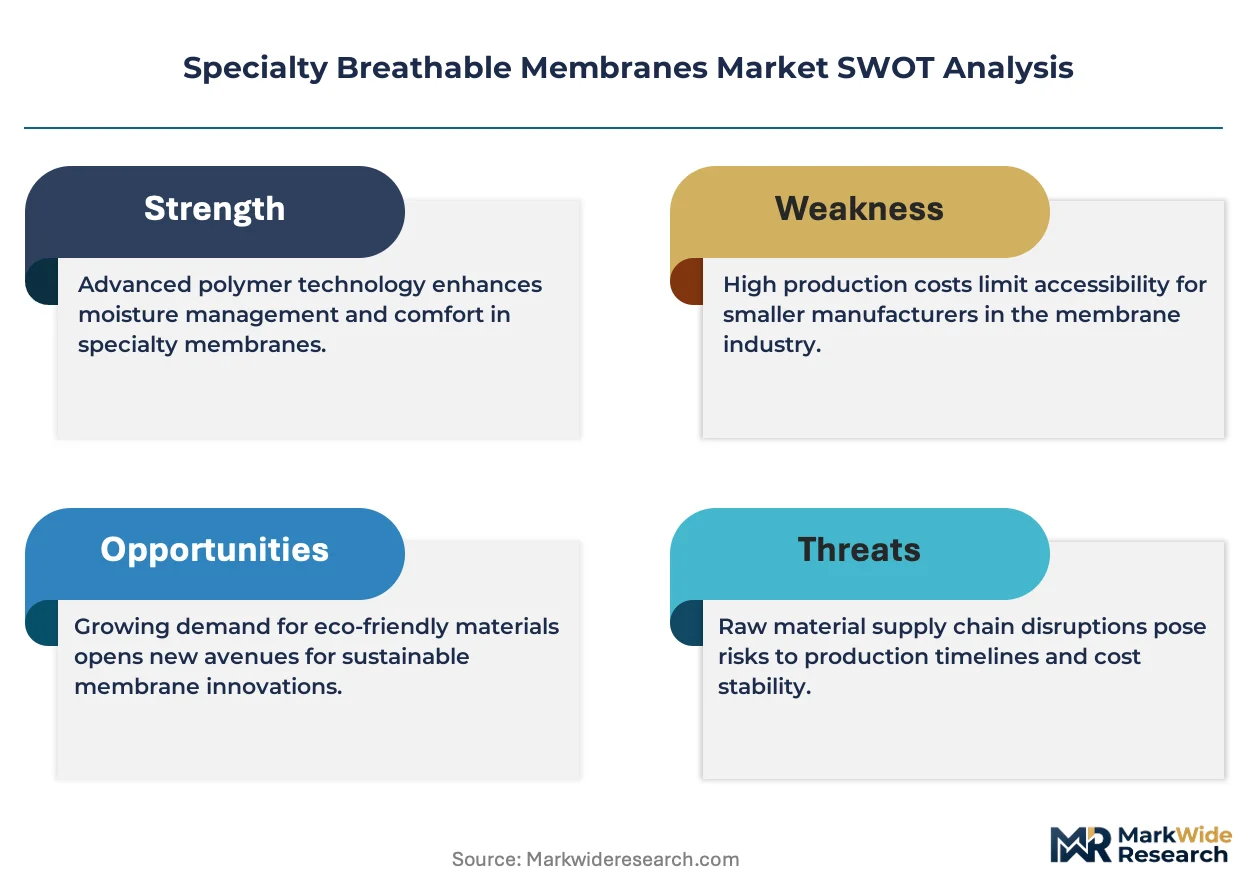
- EU MDR biocompatibility mandates:Medical device manufacturers are sourcing ISO 10993-certified breathable layers for wound dressings and surgical drapes, tightening specification standards across European hospital procurement networks.
- Automotive seating comfort engineering:German OEM clusters are specifying microporous polyurethane laminates for climate-controlled seats, absorbing higher membrane volumes per vehicle platform.
- Film lamination throughput gains:Continuous roll-to-roll processing advances are reducing unit costs for sportswear and industrial protective clothing applications.
Market Restraints
- Fluoropolymer input cost volatility:PTFE resin prices swing with fluorspar concentrate availability, compressing margins for extreme-chemical-barrier membrane producers.
- German supply concentration:Automotive and medical device clusters in Baden-Württemberg and Bavaria dominate premium specification demand, creating geographic dependency risk for membrane suppliers.
- REACH registration timelines:Novel bio-based polyurethfaces face multi-year substance evaluation delays before achieving commercial scale in European healthcare applications.
Strategic Opportunities
- Underpenetrated Indian medical textile demand:CDSCO regulatory harmonization with ISO standards is opening import pathways for surgical drape membranes into tertiary hospital networks.
- EPA PFAS restriction tailwinds:Emerging federal scrutiny of per- and polyfluoroalkyl substances is accelerating substitution programs toward fluorine-free alternatives.
- Coating-dispersion technology convergence:Aqueous polyurethane dispersions paired with precision slot-die coating are enabling thinner, higher-MVTR medical membranes with improved lot consistency.
Industry Challenges
- Polymer chemistry talent scarcity:Formulation scientists with expertise in hydrophilic-hydrophobic balance tuning command premium compensation, constraining R&D expansion at mid-scale membrane developers.
- ISO 10993 certification timeline compression:Cytotoxicity and sensitization testing protocols extend product commercialization cycles, delaying revenue recognition for new medical-grade film launches.
- Legacy lamination asset reconfiguration:Solvent-based adhesive lines require capital-intensive retrofitting to handle waterborne polyurethane dispersions, stranding capacity for non-adopters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Specialty Breathable Membranes Market |
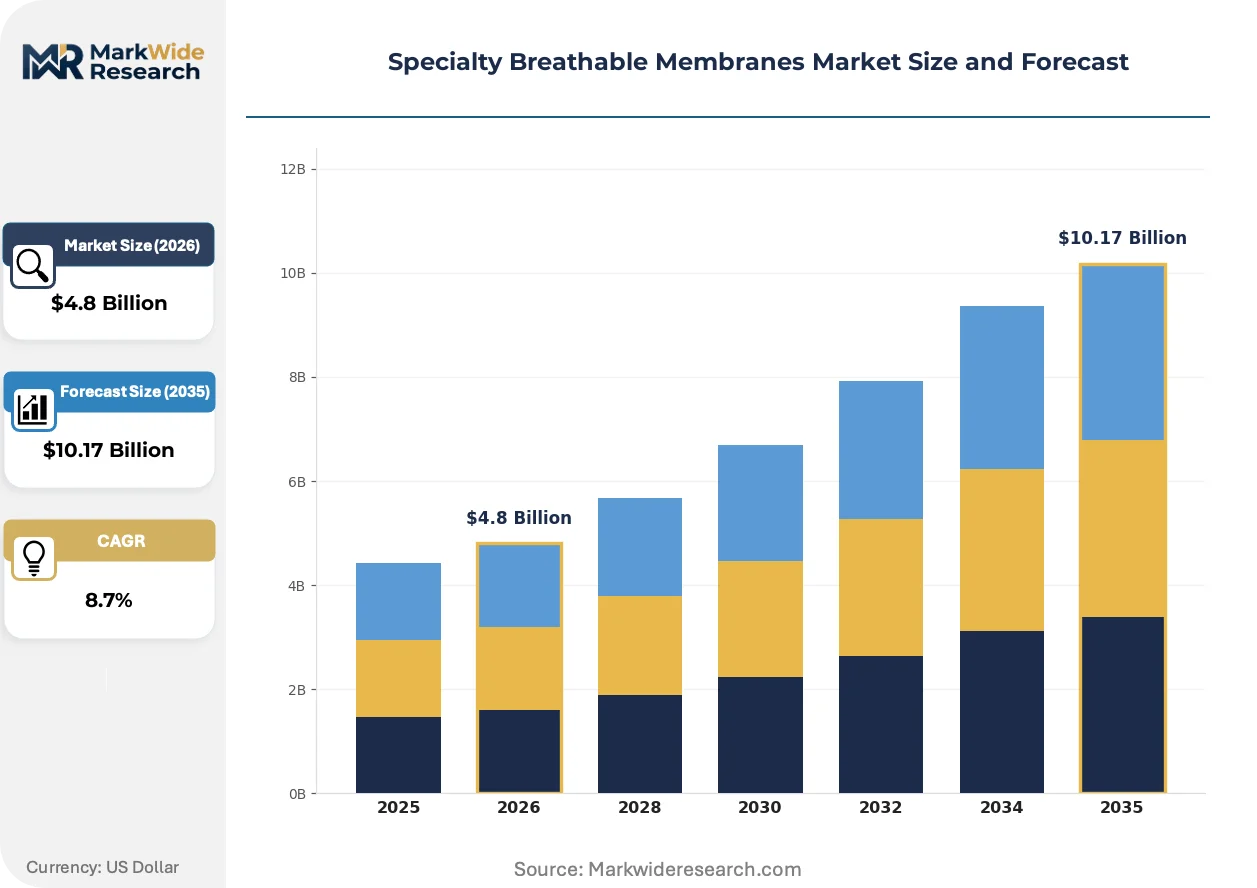
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Polytetrafluoroethylene, Polyvinyl Chloride, Polyester Application: Protective Clothing, Medical Textiles, Building Materials, Footwear End User: Construction, Healthcare, Sportswear, Automotive Technology: Micro Porous, Non-Woven, Film Lamination, Coating |
| Companies Covered | Covestro AG, Arkema SA, Berry Global Group, Toray Industries, RKW Group, Schweitzer-Mauduit International, Sympatex Technologies GmbH, W. L. Gore & Associates, Freudenberg SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Specialty Breathable Membranes Market Evolving Landscape
Material substitution pressures and processing advances are fragmenting established competitive positions, with regulatory chemistry restrictions and buyer specification upgrades operating as simultaneous forcing mechanisms across end-use verticals.
Waterborne polyurethane dispersion technology is decentralizing manufacturing footprints for medical-grade breathable membranes. Tier-two textile converters in Portugal and Romania are adopting aqueous coating lines previously restricted to solvent-based operations. This diffusion is compressing the geographic monopoly of incumbent Western European membrane laminators.
REACH restrictions on perfluorinated substances are eliminating PTFE membrane options from consumer apparel segments while preserving niche industrial protective clothing exemptions. Outdoor equipment brands are reformulating product lines around microporous polyurethanes ahead of substance restriction deadlines. German sportswear manufacturers are absorbing the highest compliance costs given their historical reliance on fluoropolymer weatherproofing.
Hospital procurement consortia are consolidating supplier panels for surgical drape and wound dressing materials, displacing fragmented distributor networks with direct manufacturer contracts. Group purchasing organizations in France and Italy are centralizing breathable membrane specifications to reduce variation in viral barrier performance. This concentration is most visible in tertiary care networks where infection control liability exposure drives standardization.
Specialty Breathable Membranes Market Segmentation
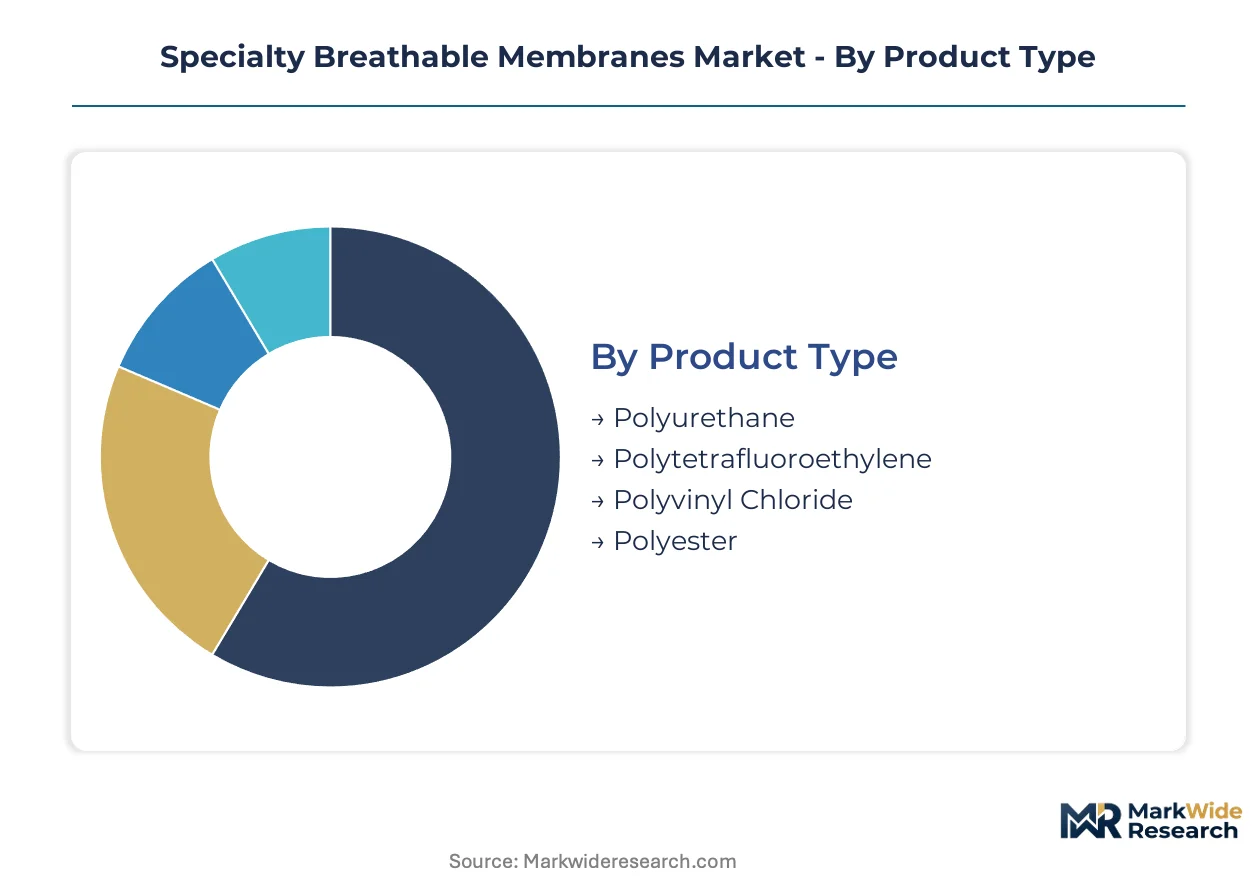
Specialty breathable membranes fragment across four intersecting dimensions—chemistry, application, buyer type, and manufacturing method—each governing margin structure and regulatory exposure differently. Procurement specifications in German automotive seating and French hospital networks demonstrate how end-use requirements cascade into material selection and technology choices.
Product Type:
Supply concentration varies sharply by polymer chemistry, with polyurethane commanding volume leadership and PTFE retaining premium positioning despite fluoropolymer headwinds.
- Polyurethane:Tunable hydrophilicity enables moisture vapor transmission rates exceeding 8,000 g/m²/day in medical-grade formulations. German automotive seating clusters absorb the highest specification volumes, driven by climate-controlled seat programs at Baden-Württemberg OEM platforms. REACH-compliant bio-based feedstocks are redirecting R&D investment toward plant-derived polyols.
- Polytetrafluoroethylene:Expanded microporous structures deliver extreme chemical resistance for hazardous material handling applications. Industrial protective clothing in Bavaria maintains demand despite EU Green Deal fluoropolymer restrictions compressing consumer apparel adoption.
- Polyvinyl Chloride:Cost-positioned monolithic films serve construction weather barriers where breathability requirements remain modest.
- Polyester:Hydrophilic co-polyesters occupy niche medical packaging segments requiring gamma sterilization compatibility.
Today's leader: Polyurethane. Tomorrow's challenger: Bio-based polyurethane alternatives.
Application:
End-use specifications diverge across moisture management intensity, contamination control stringency, and regulatory certification burden.
- Medical Textiles:Surgical drapes and wound dressings require ISO 10993-certified viral barrier performance with lot-to-lot consistency. French hospital procurement consortia are consolidating supplier panels around standardized membrane specifications, displacing fragmented distributor networks.
- Protective Clothing:Hazardous material handling drives demand for extreme chemical resistance. REACH perfluorinated substance restrictions are eliminating PTFE options from consumer segments while preserving industrial exemptions.
- Building Materials:Roof underlayments and wall wraps prioritize cost-efficient moisture management over precision breathability tuning.
- Footwear:Sportswear manufacturers in Germany absorb the highest compliance costs as fluoropolymer weatherproofing faces substitution mandates.
Medical textiles are climbing the fastest as infection control liability reshapes hospital procurement.
End User:
Buyer sophistication and specification authority concentrate differently across construction, healthcare, sportswear, and automotive verticals.
- Healthcare:Tertiary hospital networks in France and Italy centralize breathable membrane specifications through group purchasing organizations. EU MDR biocompatibility mandates tighten procurement standards for wound dressing and surgical drape suppliers.
- Automotive:German OEM clusters specify microporous polyurethane laminates for climate-controlled seating, absorbing higher membrane volumes per vehicle platform than global averages.
- Construction:Regional building codes govern specification authority, with moisture management requirements varying by climate zone.
- Sportswear:Brand-led sustainability commitments accelerate fluorine-free reformulation ahead of regulatory deadlines.
Healthcare procurement concentrates specification power most intensely; automotive offers the steepest volume expansion trajectory.
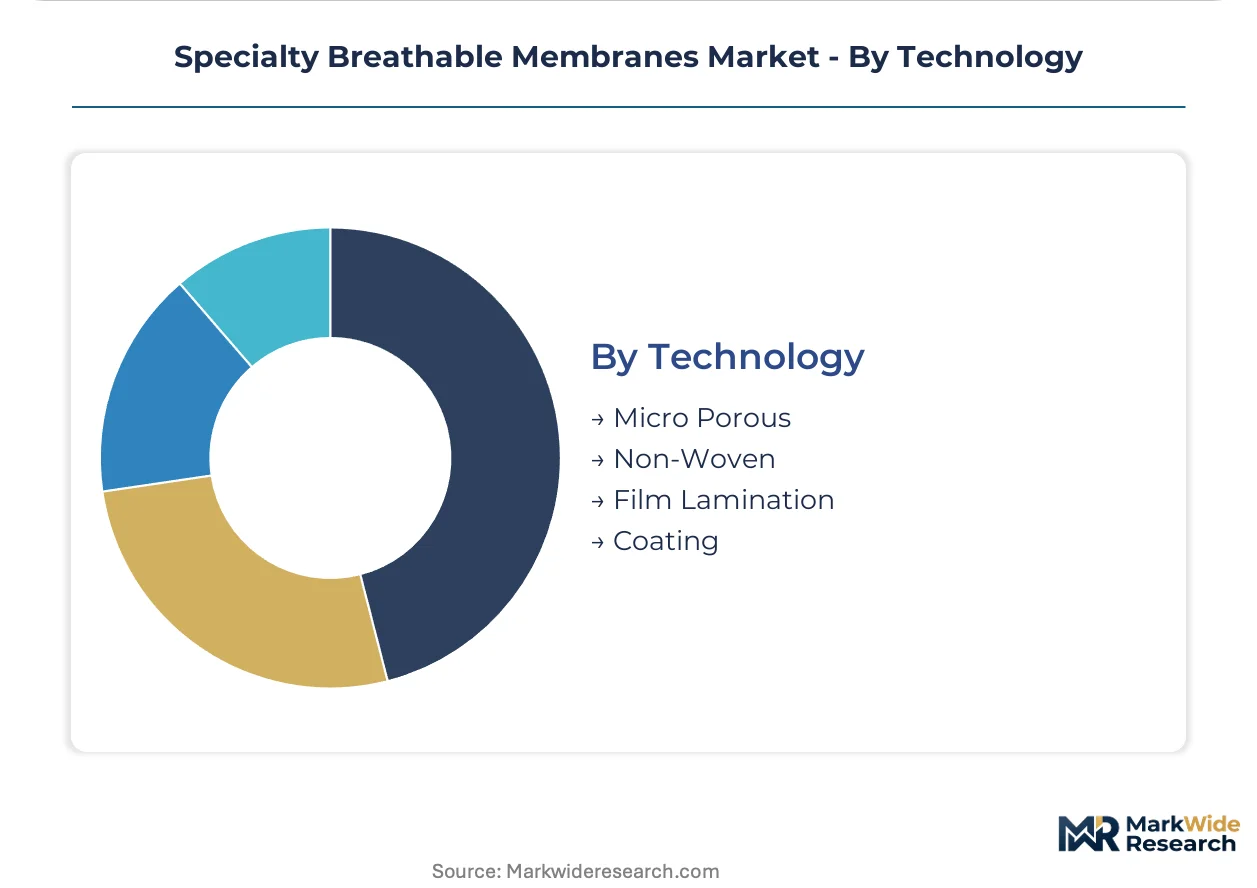
Technology:
Manufacturing method determines capital intensity, geographic diffusion potential, and margin capture across continuous processing versus batch coating operations.
- Film Lamination:Roll-to-roll throughput dominates automotive and sportswear volume production. Continuous processing advances in Portugal and Romania are decentralizing manufacturing footprints previously concentrated in Western European laminators.
- Coating:Aqueous polyurethane dispersions paired with precision slot-die coating enable thinner, higher-MVTR medical membranes. Lot-to-lot consistency requirements preserve margin concentration in healthcare applications despite higher capital intensity.
- Micro Porous:Stretch-and-void formation creates controlled pore structures for extreme breathability applications.
- Non-Woven:Spunbond-meltblown composites anchor hygiene and medical segments with viral barrier performance.
Film lamination retains volume leadership; coating technology offers the fastest margin expansion pathway.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's automotive seating clusters absorb the highest specification volumes of microporous polyurethane membranes worldwide. German OEM climate-control seat programs drive per-vehicle membrane consumption above global averages. REACH-compliant bio-based feedstock development redirects R&D investment toward plant-derived polyols across European supply chains.
Germany
Automotive seating comfort engineering and medical device manufacturing absorb premium membrane volumes. The EU Green Deal's fluorinated polymer restrictions compress incumbent PTFE supply chains while accelerating bio-based polyurethane alternatives. Baden-Württemberg and Bavaria clusters dominate specification authority for climate-controlled seats and surgical drape materials.
United States
EPA scrutiny of per- and polyfluoroalkyl substances accelerates fluoropolymer substitution programs among membrane developers. FDA 21 CFR Part 177 indirect food additive regulations govern medical membrane commercialization alongside ISO 10993 biocompatibility standards. Industrial protective clothing demand in the Gulf Coast petrochemical corridor sustains extreme-chemical-barrier membrane consumption.
France
Hospital procurement consortia consolidate supplier panels for surgical drape and wound dressing materials through group purchasing organizations. EU MDR biocompatibility mandates tighten procurement standards for tertiary care networks. The Île-de-France region anchors infection-control textile specification authority, displacing fragmented distributor networks with direct manufacturer contracts.
India
CDSCO regulatory harmonization with ISO standards opens import pathways for surgical drape membranes into tertiary hospital networks. Underpenetrated medical textile demand creates expansion opportunities for breathable membrane suppliers. Maharashtra and Gujarat textile manufacturing corridors adopt aqueous coating technologies previously restricted to Western European operations.
Japan
Industrial protective clothing for electronics manufacturing and hazardous material handling sustains premium membrane demand. METI standards for chemical protective equipment govern specification requirements in the Kanto region. Tokyo-Osaka industrial corridors concentrate demand for high-MVTR membranes in cleanroom applications.
Specialty Breathable Membranes Market Competitive Landscape
Portfolio diversification dominates the current landscape as membrane developers reconfigure around fluoropolymer substitution mandates and bio-based certification requirements. The vendor base concentrates around three strategic tiers: integrated chemical conglomerates with polyurethane chemistry leadership, specialized membrane laminators with medical-grade certification capabilities, and regional textile converters adopting aqueous dispersion technologies. Competitive positioning hinges on M&A activity targeting ISO 10993-certified production assets and strategic partnerships with automotive OEM specification engineers.
Within the integrated chemical tier, Covestro AG and Arkema SA occupy positions defined by polymer chemistry depth and regulatory compliance infrastructure. Freudenberg SE and W. L. Gore & Associates exemplify specialized membrane developers with differentiated technology platforms. Sympatex Technologies GmbH represents the sustainability-focused segment with fluorine-free alternatives. These company groupings illustrate how competitive advantage increasingly depends on regulatory chemistry expertise rather than manufacturing scale alone.
| Leading Market Players |
|---|
| Covestro AG |
| Arkema SA |
| Berry Global Group |
| Toray Industries |
| RKW Group |
| Schweitzer-Mauduit International |
| Sympatex Technologies GmbH |
| W. L. Gore & Associates |
| Freudenberg SE |
| Others |
Value Network & Pricing Analysis
The EU Green Deal's fluorinated polymer restrictions gate qualified supply and premium-tier pricing access, compressing legacy PTFE portfolios while bio-based polyurethane alternatives command certification-linked premiums. Buyers in German automotive seating and French hospital networks face bifurcated sourcing economics as REACH-compliant feedstocks reshape membrane cost structures.
Pricing Analysis
Distributor margins absorb compression as hospital procurement consortia in France and Italy consolidate supplier panels around direct manufacturer contracts. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10993-certified medical grades from industrial protective clothing specifications and construction weather barriers. Pricing pressure stems from fluorspar concentrate volatility feeding PTFE resin costs, while German OEM climate-control seat programs demonstrate the least price sensitivity due to performance-locked specifications.
Supply Chain Analysis
Dual-sourcing requirements from German automotive OEMs and French hospital GPOs mandate multi-supplier qualification for microporous polyurethane membranes. Manufacturing concentrates in Germany, Portugal, and Romania as aqueous coating technology diffuses beyond Western European incumbents. Raw material dependencies center on plant-derived polyols, fluorspar concentrates, and precision coating equipment. Single-source vulnerability risks concentrate in Baden-Württemberg automotive clusters. Distribution runs through tier-two textile converters adopting slot-die coating lines previously restricted to solvent-based operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Specialty Breathable Membranes Market functions as a stable compounder, with regulatory chemistry mandates driving steady specification upgrades across European healthcare and automotive procurement networks.
For Market Incumbents: Deploy certification depth as the defensive anchor. Covestro AG and Freudenberg SE should accelerate ISO 10993-certified production asset acquisition to lock out mid-scale competitors facing timeline compression from cytotoxicity testing protocols. Backward integration into plant-derived polyol supply secures REACH-compliant feedstock access before substance evaluation deadlines harden procurement specifications. For New Entrants and Emerging Players: Regional textile converters in Portugal and Romania represent the most penetrable channel partner type for aqueous dispersion technology adoption. White-space targets concentrate in Indian tertiary hospital networks where CDSCO regulatory harmonization opens import pathways, and in German sportswear manufacturers absorbing fluoropolymer substitution costs. A coating-dispersion technology convergence strategy enables thinner, higher-MVTR medical membranes with improved lot consistency. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale membrane laminators with medical-grade certification capabilities because hospital procurement consolidation displaces fragmented distributor networks with direct manufacturer contracts. Long-term viability centers on regulatory chemistry expertise rather than manufacturing scale alone. The signal to watch is EPA PFAS restriction enforcement accelerating fluoropolymer substitution program timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Polyols | Secures REACH-compliant feedstock access ahead of EU Green Deal substance restriction deadlines. |
| ISO 10993 Certification Investment | Enables direct contracting with French and Italian hospital procurement consortia consolidating supplier panels. |
| Aqueous Coating Capacity Expansion | Captures margin expansion in medical membranes as Portuguese and Romanian converters adopt dispersion technology. |
| Automotive OEM Specification Partnership | Locks in climate-controlled seat programs at Baden-Württemberg OEM platforms absorbing premium membrane volumes. |
| Fluorine-free Product Line Repositioning | Anticipates EPA PFAS restrictions while preserving industrial protective clothing exemptions under REACH. |
Research Methodology
Bottom-up medical textile and automotive seating modeling reconciled against top-down polymer chemistry supply tracking forms the analytical core. Primary interviews with membrane formulation scientists, hospital GPO contracts managers, OEM platform engineers, and tier-two textile converter operations directors combined with secondary validation from ECHA substance restriction databases, FDA 510(k) filings, EU MDR technical documentation, and German automotive production registries. Triangulation across stakeholder inputs and regulatory filing analysis ensures segmentation integrity.
Input-output matrices map microporous polyurethane and expanded PTFE production volumes through film lamination and coating technology pathways across the analysis window. Segmentation dimensions include polymer chemistry, application vertical, end-user procurement sophistication, and manufacturing method. CAGRs derive from specification upgrade trajectories in German climate-controlled seating and French infection-control textile procurement. Forecast inputs incorporate REACH registration timeline assumptions and EPA PFAS restriction probability weightings.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR biocompatibility mandate enforcement intensity and fluorspar concentrate supply disruptions. Deviation in EPA PFAS restriction timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Global Gas Separation Membranes Market
Membrane Materials
Polytetrafluoroethylene (PTFE) Filter Membranes Market
Membrane Materials
SBS Modified Bitumen Membrane Market
Membrane Materials
Global Transfer Membrane Market
Membrane Materials
Polysulfone Market
Membrane Materials
Membrane Bioreactor Market
Membrane Materials
Nafion Market
Membrane Materials
Membrane Separation Market
Membrane Materials
Membrane Polymers Market
Membrane Materials
Global Membrane Separation Technology Market
Membrane Materials
North America Transparent Conductive Films Market
Membrane Materials
Hollow Fibers Membrane Market
Membrane Materials
Membrane Filter Cartridge Market
Membrane Materials
Breather Membranes Market
Membrane Materials
Global Breathable Membranes Market
Membrane Materials
PTFE Membrane Market