
 Membrane Separation Market | 2026-2036
Membrane Separation Market Size, Share, and Industry Trends Forecast 2026-2036
Membrane Separation Market Analytics
ISO 9001 certification for membrane manufacturing quality management is collapsing the supplier base as smaller fabricators fail audit cycles. DuPont leverages its fluoropolymer chemistry heritage to sustain dominance in high-pressure reverse osmosis elements. Toray Industries anchors its position through vertical integration from polymer synthesis to module assembly, competing primarily in Asia-Pacific desalination tenders.
Membrane separation employs semi-permeable barriers with pore sizes ranging from 0.1 nanometers to 10 micrometers to selectively filter molecules based on size, charge, or affinity, operating under transmembrane pressures of 1 to 80 bar depending on the technology. Reverse osmosis commands the largest value share due to energy-intensive seawater desalination applications, while nanofiltration grows fastest in food processing for selective ion removal and dairy protein fractionation. Ceramic membranes occupy premium industrial niches where thermal and chemical resistance justifies higher capital outlay against polymeric alternatives in pharmaceutical sterile filtration.
The EPA's Clean Water Act enforcement shapes US industrial membrane demand through discharge limit compliance, while REACH registration requirements in Europe restrict certain polymeric precursor chemistries. China's MEE mandates drive municipal upgrading cycles. Stakeholders must monitor how evolving drinking water standards in multiple jurisdictions alter membrane replacement frequencies and material specifications.
Market Dynamics
Water scarcity pressures and tightening discharge regulations are compressing replacement cycles for industrial membrane systems while concentrating procurement among certified fabricators capable of meeting multi-jurisdictional compliance requirements.
Growth Catalysts
- Desalination infrastructure:Saudi Arabia and the UAE are expanding reverse osmosis capacity to address groundwater depletion, with procurement volumes accelerating for high-pressure seawater elements.
- EU Urban Waste Water Treatment Directive:Industrial discharge limits are mandating tertiary treatment upgrades across German and Dutch chemical clusters, pulling advanced ceramic membranes into food and pharmaceutical applications.
- Food processing ion selectivity:Nanofiltration systems are capturing dairy protein fractionation demand in France and New Zealand as processors seek precise mineral separation without thermal damage.
Market Restraints
- Fluoropolymer precursor concentration:Perfluorinated membrane feedstock supply concentrates among three chemical conglomerates, exposing RO element manufacturers to input volatility and qualification delays.
- REACH registration friction:ECHA restrictions on certain polymeric chemistries are extending new material approval timelines by 18-24 months for European membrane fabricators.
- Thermal limitation of polymeric alternatives:Polyethersulfone and PVDF membranes degrade above 85°C, ceding high-temperature industrial process streams to cost-prohibitive ceramic systems.
Strategic Opportunities
- India municipal upgrading:Smart Cities Mission funding is channeling membrane bioreactor procurement into secondary treatment plants across Maharashtra and Gujarat with limited incumbent supplier presence.
- Carbon capture solvent regeneration:Gas separation membranes are penetrating amine scrubbing loops at US and Norwegian CCS pilot facilities, creating a performance-specification entry point distinct from water treatment.
- China MEE enforcement:Ministry of Ecology and Environment mandates are accelerating replacement of legacy tubular systems with spiral-wound configurations in Shandong and Jiangsu industrial zones.
Industry Challenges
- ISO 9001 audit attrition:Smaller membrane module assemblers are failing certification cycles due to inadequate traceability systems, collapsing the qualified supplier base and extending lead times for specification-critical projects.
- Legacy control system integration:Brownfield water treatment facilities in the UK and Australia require costly SCADA retrofitting to accommodate smart membrane monitoring, slowing adoption of predictive maintenance platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Membrane Separation Market |
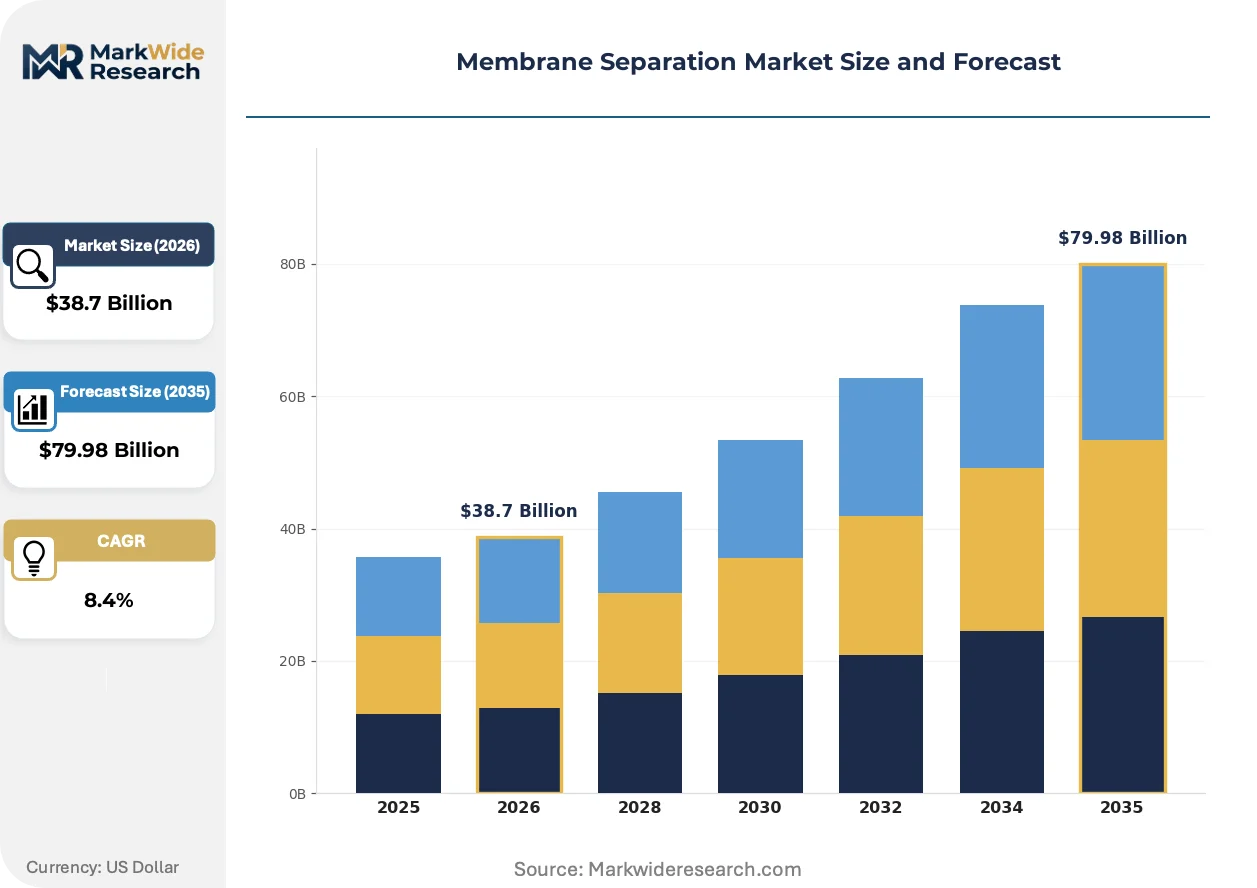
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Reverse Osmosis, Ultrafiltration, Microfiltration, Nanofiltration Application: Water Treatment, Food Processing, Biotechnology, Pharmaceutical End User: Municipal, Industrial, Agricultural, Residential Material: Polymeric, Ceramic, Composite, Metal |
| Companies Covered | DuPont, Toray Industries Inc., SUEZ, 3M Company, Pentair plc, Koch Membrane Systems, Pall Corporation, Asahi Kasei Corporation, GEA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Membrane Separation Market Evolving Landscape
Membrane manufacturing is bifurcating between commodity polymeric production scaling in Asia and precision ceramic fabrication consolidating in European industrial clusters, with digital monitoring layers becoming standard on premium system offerings.
Graphene oxide composite membranes are decomposing the performance-cost tradeoff that has protected polyamide thin-film composites in brackish water applications. Israeli and Singaporean desalination operators are piloting these materials at 40% lower energy intensity. The technology is decomposing incumbent supplier pricing power in mid-pressure reverse osmosis segments where energy recovery device compatibility now dominates procurement scoring.
REACH authorization requirements for per- and polyfluoroalkyl substances are forcing reformulation of hydrophobic membrane coatings across EU pharmaceutical filtration applications. German and Swiss sterile filtration suppliers are accelerating fluorine-free surface chemistry development to maintain CE marking eligibility. The F-Gas Regulation's phasedown is compressing timelines for alternative membrane materials in HVAC dehumidification systems where PTFE previously dominated.
Power purchase agreements are reshaping how industrial water treatment operators acquire membrane capacity, with energy-intensive RO plants in Texas and Queensland now bundled with behind-the-meter solar installations. EPC contractors are unbundling membrane replacement services from initial capital contracts, creating standalone aftermarket revenue streams. This model is concentrating in Australian mining camps and Chilean copper concentrate processing where remote location logistics previously favored bundled procurement.
Membrane Separation Market Segmentation
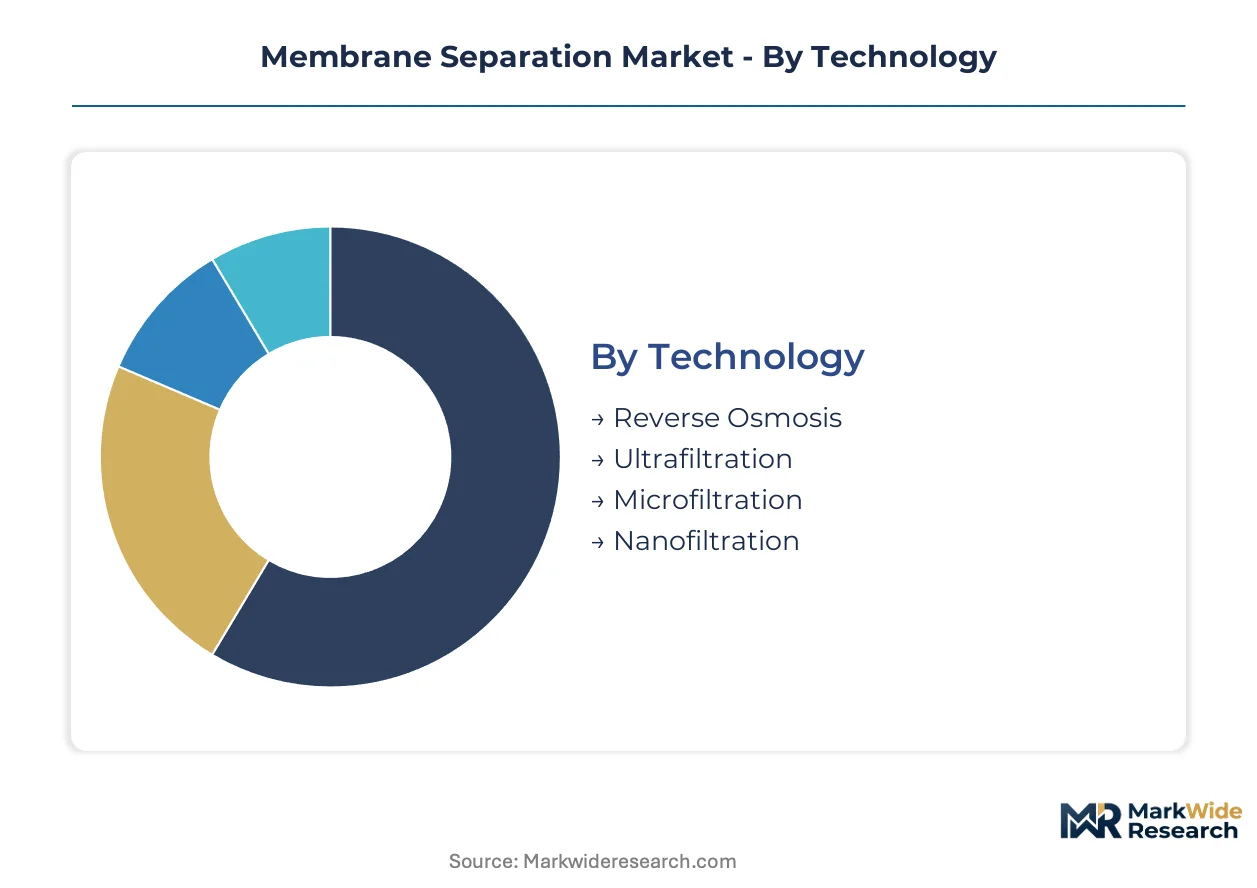
Membrane separation technology exhibits divergent adoption patterns across material classes and pressure regimes, with procurement decisions driven by thermal tolerance requirements, energy recovery compatibility, and regulatory discharge specifications. Segment boundaries blur as hybrid ceramic-polymeric composites penetrate premium industrial niches.
Technology:
Reverse osmosis and nanofiltration segments concentrate export demand from Middle Eastern desalination tenders, while microfiltration and ultrafiltration serve predominantly domestic municipal upgrading cycles in Europe and North America.
- Reverse Osmosis:Polyamide thin-film composite layers on polysulfone supports achieve 99.5% salt rejection at 55-80 bar operating pressure. Saudi Arabia and UAE procurement for seawater desalination concentrates demand for high-pressure seawater elements with energy recovery device integration.
- Nanofiltration:Divalent ion selectivity at 5-20 bar distinguishes this segment from RO, enabling dairy protein fractionation without thermal denaturation. French and New Zealand processors drive specification tightening for mineral separation precision in whey concentration applications.
- Ultrafiltration:1-100 kDa molecular weight cutoff separates macromolecules in biotechnology harvest and clarification processes, with German pharmaceutical clusters specifying endotoxin retention.
- Microfiltration:0.1-10 micrometer pore ratings target bacterial and suspended solid removal in wine and beer clarification, with Italian and Spanish beverage producers dominating European procurement volumes.
Reverse osmosis holds the largest share; momentum sits with nanofiltration as food processors seek selective separation without phase change energy penalties.
Application:
Water treatment applications span the widest cost tiers from commodity municipal procurement to precision semiconductor ultrapure systems, while pharmaceutical and biotechnology segments command premium pricing through validation documentation requirements.
- Water Treatment:Municipal secondary and tertiary upgrading, industrial process water, and semiconductor ultrapure production constitute the volume base. China's MEE mandates accelerate spiral-wound replacement of legacy tubular systems in Shandong industrial zones.
- Food Processing:Dairy fractionation, juice concentration, and wine clarification drive ceramic membrane adoption where steam sterilization compatibility justifies capital outlay. REACH restrictions on fluorinated coatings are forcing reformulation in EU dairy applications.
- Biotechnology:Cell harvest, protein purification, and viral clearance steps require validated sterile filtration trains with extractables documentation for FDA submission packages.
- Pharmaceutical:Parenteral drug sterile filtration and active pharmaceutical ingredient isolation specify 0.1-0.2 micrometer ratings with integrity test correlation to bacterial challenge data.
Water treatment commands absolute volume; pharmaceutical applications expand most quickly as biologic drug pipelines lengthen validation membrane replacement cycles.
End User:
Municipal procurement concentrates in developing economy infrastructure expansion, while industrial end users fragment across chemical, power, electronics, and mining verticals with divergent specification requirements.
- Municipal:Secondary treatment membrane bioreactors and tertiary filtration for potable reuse specification dominate procurement. India's Smart Cities Mission channels MBR procurement into Maharashtra and Gujarat treatment plants.
- Industrial:Process water, wastewater discharge compliance, and cooling tower blowdown recovery span chemical, power generation, and electronics manufacturing. German and Dutch chemical clusters face EU Urban Waste Water Treatment Directive tertiary upgrade mandates.
- Agricultural:Irrigation water treatment and livestock wastewater nutrient recovery represent emerging specification development, with Israeli kibbutz cooperatives piloting brackish water RO for desert agriculture.
- Residential:Point-of-use drinking water systems and whole-house softening pretreatment constitute a price-sensitive replacement market with shorter membrane lifecycles.
Industrial end users generate the highest value per module; agricultural applications are gaining share fastest as water stress intensifies irrigation source treatment requirements.
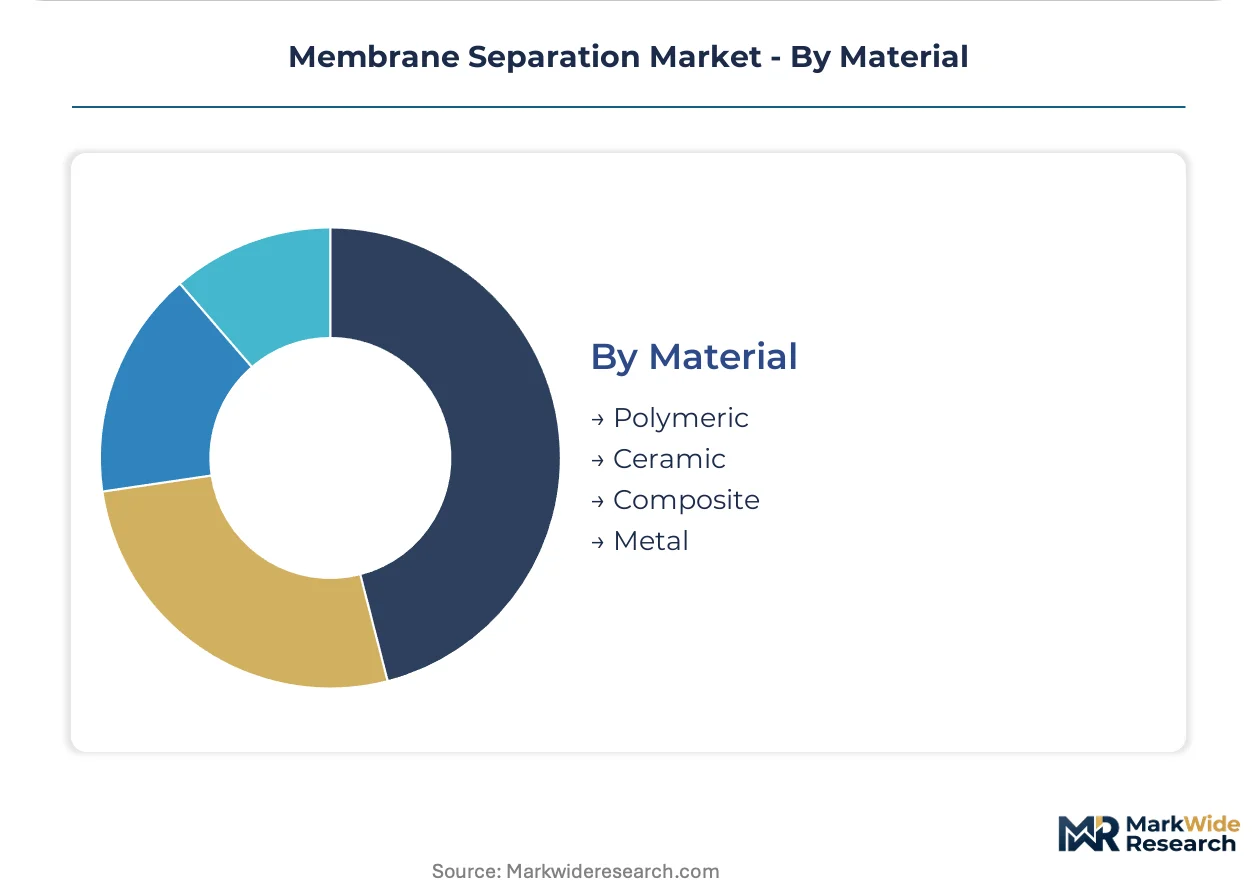
Material:
Polymeric production scales in Asian manufacturing clusters, while ceramic fabrication concentrates in European industrial valleys with precision sintering heritage.
- Polymeric:Polyethersulfone, PVDF, and polyamide chemistries dominate through solution casting and interfacial polymerization. Thermal ceiling at 85°C limits high-temperature process stream access.
- Ceramic:Alpha-alumina, zirconia, and titania sintered layers achieve steam sterilization compatibility and chemical resistance for pharmaceutical sterile filtration. German and Swiss suppliers anchor European precision fabrication.
- Composite:Graphene oxide-polyamide thin-film composites are decomposing energy intensity benchmarks in Israeli and Singaporean desalination pilots.
- Metal:Stainless steel and titanium porous substrates serve high-pressure gas separation and specialized corrosive environment applications with limited volume.
Polymeric materials retain volume dominance; composite formulations are climbing the fastest as graphene oxide integration disrupts incumbent thin-film composite pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Desalination operators and municipal water utilities concentrate procurement authority across distinct national clusters, with regulatory enforcement intensity determining membrane replacement velocity and specification grade.
United States
Industrial discharge compliance and semiconductor ultrapure water specifications drive membrane demand. EPA Clean Water Act enforcement shapes procurement for chemical and power generation facilities. Texas and Arizona industrial zones are expanding brackish water reverse osmosis capacity for process water security.
Germany
EU Urban Waste Water Treatment Directive mandates tertiary treatment upgrades across chemical clusters. ECHA REACH registration requirements restrict certain polymeric precursor chemistries, extending qualification timelines. The Rhine-Ruhr industrial corridor is retrofitting membrane bioreactors into legacy municipal treatment infrastructure.
China
MEE enforcement accelerates replacement of legacy tubular systems with spiral-wound configurations in industrial zones. Municipal water treatment infrastructure expansion drives ceramic and polymeric membrane procurement at scale. Shandong and Jiangsu provinces are upgrading secondary treatment plants under tightening discharge standards.
Saudi Arabia
Groundwater depletion pressures are expanding reverse osmosis capacity for seawater desalination. SFDA pharmaceutical filtration standards are tightening sterile membrane validation requirements. The Eastern Province industrial cluster is procuring high-pressure seawater elements with integrated energy recovery devices.
India
Smart Cities Mission funding channels membrane bioreactor procurement into secondary treatment plants. BIS certification requirements are compressing the qualified supplier base for municipal tenders. Maharashtra and Gujarat treatment facilities are expanding capacity with limited incumbent supplier presence.
Membrane Separation Market Competitive Landscape
Player mix skews toward diversified chemical conglomerates with fluoropolymer heritage and vertically integrated polymer specialists. Market structure concentrates around three to five dominant fabricators capable of ISO 9001 certification maintenance and multi-jurisdictional regulatory compliance. Strategic archetypes include chemistry-anchored conglomerates, backward-integrated polymer specialists, and precision ceramic fabricators. Competitive moves center on capacity expansion in Asian manufacturing clusters and technology licensing for graphene oxide composite formulations.
Among chemistry-anchored conglomerates, DuPont exemplifies the fluoropolymer heritage archetype, while Toray Industries occupies a position representing backward-integrated polymer control from synthesis through module assembly. SUEZ sits within the municipal water solutions tier, anchoring European utility relationships. These three fabricators represent distinct strategic positions: materials science dominance, vertical manufacturing control, and systems integration capability.
| Leading Market Players |
|---|
| DuPont |
| Toray Industries Inc. |
| SUEZ |
| 3M Company |
| Pentair plc |
| Koch Membrane Systems |
| Pall Corporation |
| Asahi Kasei Corporation |
| GEA Group |
| Others |
Value Network & Pricing Analysis
ISO 9001 certification gates both supplier qualification and price differentiation simultaneously, collapsing the fabricator base into three to five certified entities capable of multi-jurisdictional compliance while forcing procurement premiums for specification-critical projects.
Pricing Analysis
Cost-plus contracts with fluoropolymer precursor indexation dominate high-pressure reverse osmosis element procurement. Three-tier pricing structure across premium seawater desalination elements, standard brackish water modules, and economy municipal configurations reflects certification grade and energy recovery device compatibility. Pricing pressure stems from graphene oxide composite pilots in Israeli and Singaporean facilities decomposing incumbent thin-film composite pricing power. Municipal utilities exhibit highest price sensitivity; semiconductor ultrapure systems show lowest.
Supply Chain Analysis
China and Japan anchor polymeric membrane casting and module assembly at scale. Germany and Switzerland concentrate precision ceramic sintering for pharmaceutical sterile filtration. Raw material flows draw from perfluorinated precursor specialists, polyethersulfone resin producers, and alpha-alumina powder suppliers. Single-source vulnerability concentrates in fluoropolymer feedstock among three chemical conglomerates. Distribution runs through EPC contractors unbundling replacement services from initial capital contracts in Australian mining and Chilean copper processing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane procurement is shifting toward platform-economics dynamics as predictive maintenance layers and energy recovery device interoperability create ecosystem lock-in effects around integrated system suppliers.
For Market Incumbents: Fortify backward integration into fluoropolymer precursor supply to offset input volatility from concentrated chemical conglomerates. Expand ceramic fabrication capacity in German and Swiss industrial clusters before REACH authorization timelines compress further. Graphene oxide composite disruption threatens polyamide thin-film composite margins in mid-pressure segments.
For New Entrants and Emerging Players: Anchor in India's Smart Cities Mission membrane bioreactor tenders where BIS certification requirements have compressed incumbent presence. Target Maharashtra and Gujarat municipal upgrading cycles with spiral-wound configurations replacing legacy tubular systems. Lead with bundled predictive maintenance platforms to differentiate from commodity module suppliers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across ceramic membrane fabrication as precision sintering equipment and cleanroom infrastructure requirements escalate. Acquire mid-cap specialists with established ECHA registration dossiers and CE marking pathways to bypass 18-24 month qualification delays. Watch graphene oxide composite scale-up timelines as the signal for thin-film composite displacement velocity.
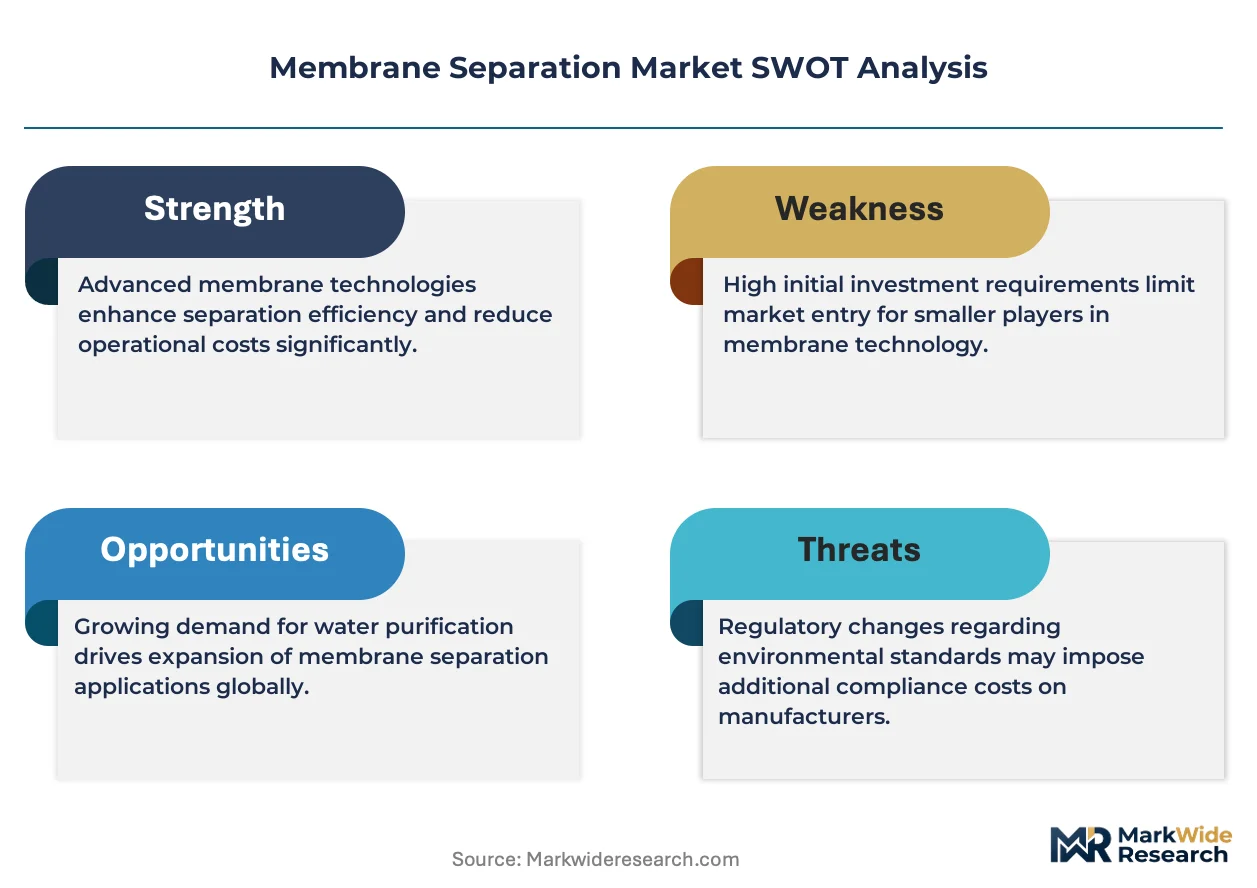
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Precursors | Captive supply of perfluorinated feedstock insulates DuPont and Toray from three-conglomerate concentration risk. |
| Graphene Oxide Composite Scale-Up | Israeli and Singaporean pilot data at 40% lower energy intensity threatens polyamide thin-film composite pricing power. |
| REACH-Compliant Fluorine-Free Coating Development | German and Swiss sterile filtration suppliers accelerate reformulation to maintain CE marking eligibility under tightening ECHA restrictions. |
| Smart Membrane Monitoring Platform Deployment | Predictive maintenance layers create aftermarket revenue streams and ecosystem lock-in around premium system offerings. |
| India Municipal MBR Capacity Expansion | Smart Cities Mission funding channels procurement into Maharashtra and Gujarat with limited incumbent supplier presence. |
Research Methodology
A spread of perspectives from membrane module procurement managers at municipal utilities, technical directors at desalination operators, pharmaceutical sterile filtration validation leads, EPC contractor project engineers, and ceramic fabrication plant managers converged on the working assumptions. Primary fieldwork combined with secondary validation from ECHA registration databases, EPA Clean Water Act enforcement records, MEE discharge standard filings, and customs trade data for fluoropolymer precursor flows. Bottom-up membrane element shipment tallies triangulated against top-down water treatment infrastructure investment tracking.
Segmentation dimensions modeled span technology class, material composition, application vertical, end-user category, and regional regulatory cluster across the projection horizon. CAGRs derived from install-base replacement velocity analysis and greenfield capacity announcement tracking. Forecast inputs incorporated energy recovery device compatibility scoring and graphene oxide pilot scale-up timelines.
Underlying assumptions cover REACH authorization progression, MEE enforcement intensity, and fluoropolymer precursor supply stability, with deviation risk concentrated in regulatory timeline compression and substitute material qualification acceleration. Recalibration cycles align with material shifts in ECHA restriction schedules and desalination tender award patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Single-Ply Membranes Market
Membrane Materials
Membranes Market
Membrane Materials
Global Nanomembrane Market
Membrane Materials
Inorganic Ion Exchange Materials Market
Membrane Materials
Global Bitumen Membranes Market
Membrane Materials
Expansion Vessel Membrane Market
Membrane Materials
Polyarylsulfone (PAS) Market
Membrane Materials
Global Geomembrane Market
Membrane Materials
Membrane Filter Cartridge Market
Membrane Materials
Global Track Etched Membrane Market
Membrane Materials
Global Membrane Structures Market
Membrane Materials
Polysulfone Market
Membrane Materials
Vapor Barrier Films Market
Membrane Materials
US Commercial Restoration Waterproofing Membranes Market
Membrane Materials
Membrane Separation Materials Market
Membrane Materials
Polymer Electrolyte Membrane Fuel Cells (Pemfcs) Market