
 SBS Modified Bitumen Membrane Market | 2026-2036
SBS Modified Bitumen Membrane Market Size, Share, and Industry Trends Forecast 2026-2036
SBS Modified Bitumen Membrane Market Insights
Multi-source procurement for styrene-butadiene-styrene polymer feedstock is pivoting toward captive and near-shore arrangements as volatility in butadiene spot markets pressures membrane economics. Soprema Group leverages backward integration into bitumen refining across its European production footprint. Carlisle sustains manufacturing scale through dedicated roofing membrane facilities in the southeastern United States. Johns Manville anchors North American supply reliability via controlled logistics networks serving commercial roofing distributors.
SBS modified bitumen membrane consists of asphalt blended with styrene-butadiene-styrene block copolymer, reinforced with polyester or fiberglass carriers, and manufactured to thicknesses typically ranging from 3.0 to 5.0 millimeters for waterproofing and weatherproofing of low-slope roofs and below-grade structures. The material's elastomeric modification provides low-temperature flexibility down to minus 20 degrees Celsius and fatigue resistance under thermal cycling. Torch-Applied product types dominate volume in European commercial roofing due to established contractor training and faster installation cycles, while Self-Adhering formats are gaining specification share among US architects prioritizing open-flame elimination on occupied buildings. Waterproofing applications for plaza decks and tunnels carry higher margin pools than standard roofing due to complex detailing requirements and longer warranty terms.
EPA cool roof reflectivity standards, the EU Green Deal building renovation wave, and Germany's KBA-adjacent energy efficiency codes for commercial envelopes collectively tighten product certification requirements and specification thresholds across major demand centers. REACH compliance for SBS polymer additives and bitumen processing chemicals shapes formulation decisions and supplier qualification timelines for membrane producers serving European contractors. Stakeholders must monitor evolving polymer substitution economics as bio-based modifier trials advance and regional carbon border adjustments begin affecting imported asphalt feedstock costs.
Market Dynamics
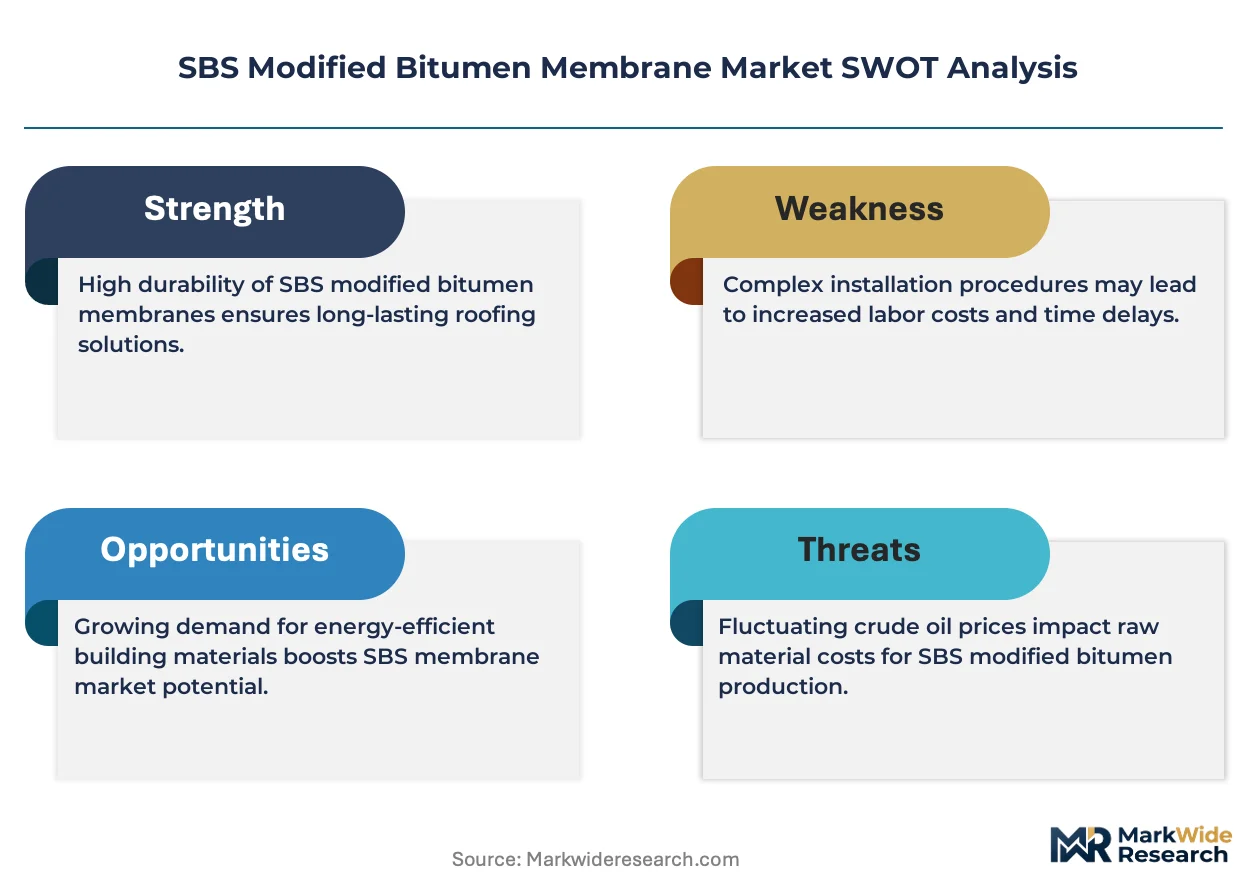
Butadiene spot market volatility is compressing membrane margins and forcing feedstock procurement restructuring across the SBS modified bitumen value chain. Producers are accelerating captive polymer arrangements and near-shore bitumen sourcing to defend formulation economics against petrochemical price swings.
Growth Catalysts
- EPA Cool Roof Standards:Reflectivity mandates for low-slope commercial envelopes in the United States are accelerating specification of white-surfaced SBS membranes. Roofing contractors in the Sun Belt report reroofing cycle compression as building owners pursue energy retrofit compliance.
- German Industrial Corridor Retrofit Mandates:KBA-adjacent energy efficiency codes are tightening thermal performance thresholds for commercial roofing assemblies. Industrial facility managers across Baden-Württemberg and Bavaria are specifying multi-layer SBS systems with enhanced insulation integration.
- Self-Adhering Membrane Technology:Open-flame elimination on occupied buildings is driving architect preference for peel-and-stick SBS formats. Urban healthcare and educational construction projects in dense metropolitan zones are prioritizing torch-free installation protocols.
Market Restraints
- Butadiene Feedstock Volatility:Styrene-butadiene-styrene block copolymer prices track naphtha and crude differentials with limited producer hedging capability. Membrane manufacturers lack forward pricing power to pass through polymer cost swings on six-month commercial roofing contracts.
- European Supply Concentration:REACH-compliant SBS polymer production clusters in Belgium and the Netherlands create geographic single-point vulnerability. Disruption at Antwerp-Rotterdam chemical hubs would strand membrane lines across German and French roofing plants.
- Thermoplastic Polyolefin Substitution:TPO single-ply membranes are capturing specification share in US commercial roofing for applications below minus 15 degrees Celsius flexibility requirements. SBS modified bitumen faces displacement risk in warm-climate warehouse and retail construction segments.
Strategic Opportunities
- Waterproofing Application Expansion:Plaza deck and tunnel envelope projects carry higher margin pools than standard roofing due to complex detailing requirements. German infrastructure stimulus programs are accelerating below-grade waterproofing specification for urban transit systems.
- Bio-Based Modifier Trials:Bio-styrene and renewable butadiene pilot programs are advancing polymer substitution economics for carbon-conscious specification. European membrane producers are qualifying bio-attributed SBS grades to anticipate EU carbon border adjustment mechanics on imported asphalt feedstock.
- Direct Contractor Channel Development:Bypassing traditional roofing distributor networks through certified installer programs is compressing channel economics. US commercial roofing contractors in Texas and Florida are accepting manufacturer-direct training and warranty administration to secure project margin.
Industry Challenges
- Torch-Applied Certification Bottlenecks:Qualified welder scarcity for hot-air and open-flame SBS installation is extending project timelines. European roofing trade associations report eighteen-month apprenticeship backlogs for membrane torch-applied proficiency credentials.
- Multi-Jurisdictional Compliance Complexity:REACH additive restrictions, EPA volatile organic compound limits, and state-level fire code variations create formulation fragmentation. Membrane producers maintain seventeen distinct product SKUs across regulatory regimes for functionally equivalent roofing performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SBS Modified Bitumen Membrane Market |
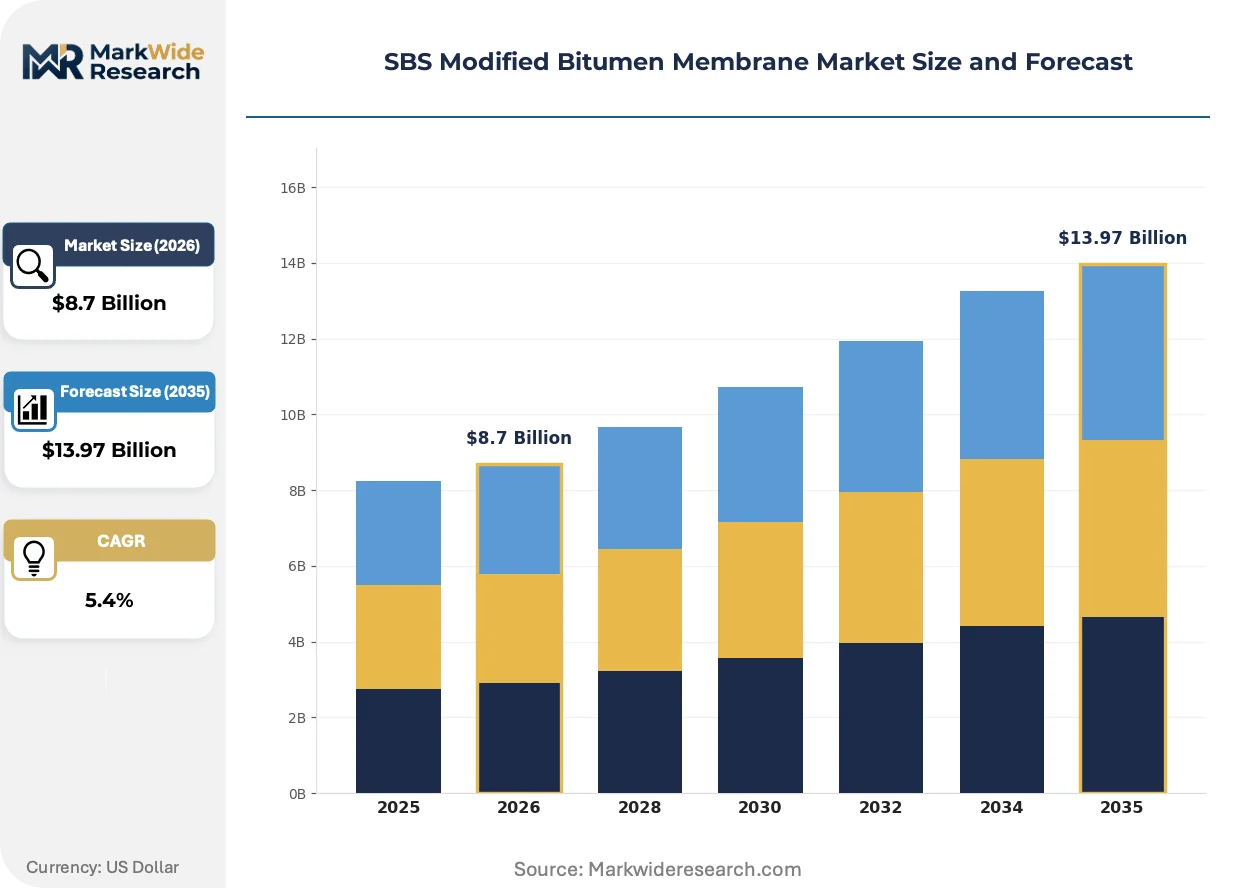
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Adhering, Torch-Applied, Cold-Applied, Peel-and-Stick Application: Residential Roofing, Commercial Roofing, Industrial Roofing, Waterproofing End User: Contractors, Builders, Architects, Property Owners Installation Method: Hot Bonding, Cold Bonding, Mechanical Fastening, Self-Adhesive |
| Companies Covered | TehnoNICOL, Carlisle, Soprema Group, Johns Manville, IKO Industries Ltd, Sika, Polyglass, Bauder, GAF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SBS Modified Bitumen Membrane Market Trends and Innovations
Automation of membrane manufacturing and installation workflows is compressing cost structures while regulatory chemistry restrictions are reformulating product architectures. Three convergent developments are restructuring competitive positioning across the SBS modified bitumen value chain.
Robotic membrane welding systems for torch-applied SBS installation are automating seam quality control on large commercial roofing projects. German industrial roofing contractors are deploying automated hot-air welding platforms on warehouse envelope projects exceeding 50,000 square meters. This technology is automating labor cost compression while reducing warranty claim incidence from human welding inconsistency.
REACH restrictions on polycyclic aromatic hydrocarbon content in bitumen processing chemicals are forcing reformulation of SBS polymer compatibility agents. Membrane producers serving European contractors are qualifying alternative fluxing agents and extraction solvents to maintain elastomeric performance thresholds. German and French roofing plants are most affected, with qualification timelines extending twelve to eighteen months for revised product certifications.
Building information modeling integration is restructuring contractor-preferred membrane specification around digital compatibility and warranty data accessibility. US commercial roofing architects are embedding SBS membrane thermal performance parameters directly into envelope energy models. Texas and Florida construction markets exhibit the strongest BIM-driven specification compression, with membrane selection increasingly contingent on open API data exchange capabilities.
SBS Modified Bitumen Membrane Market Segmentation
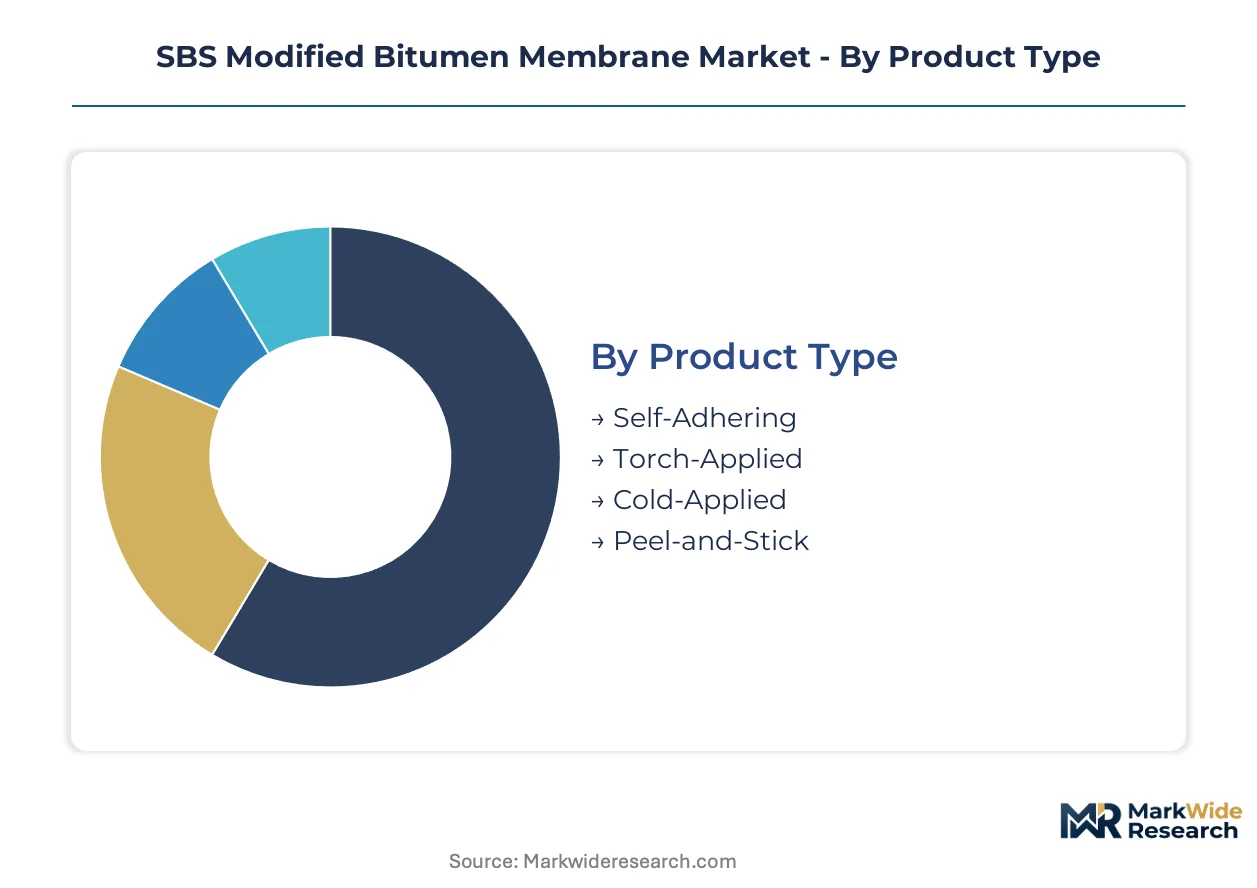
SBS modified bitumen membrane specification fragments across installation protocols, building types, and procurement channels. Understanding these divisions reveals where formulation investments concentrate and which customer relationships command premium positioning.
Product Type:
Supply concentration for polymer-modified asphalt formulations tilts toward installation-specific performance requirements rather than generic waterproofing grades.
- Torch-Applied:Open-flame installation demands SBS formulations with optimized melt viscosity and reinforced polyester carriers. German commercial roofing contractors specify this format for warehouse envelopes exceeding 50,000 square meters where automated hot-air welding platforms compress labor cycles.
- Self-Adhering:Peel-and-stick membranes eliminate torch hazards on occupied buildings through factory-applied adhesive layers and release liners. US healthcare and educational construction in dense metropolitan zones drives specification as architects prioritize open-flame elimination protocols.
- Cold-Applied:Liquid-applied SBS formulations serve complex detailing requirements at penetrations and terminations.
- Peel-and-Stick:Pre-cut membrane sheets with aggressive tack properties accelerate installation on smaller commercial retrofits.
Today's leader: Torch-Applied. Tomorrow's challenger: Self-Adhering.
Application:
Margin pools diverge sharply between exposed roofing assemblies and buried waterproofing systems with extended warranty obligations.
- Waterproofing:Plaza deck and tunnel envelope applications carry premium pricing due to complex detailing, multi-layer redundancy requirements, and 20-year warranty terms. German infrastructure stimulus programs for urban transit systems are accelerating below-grade specification.
- Commercial Roofing:Low-slope building envelopes dominate volume consumption across US Sun Belt reroofing cycles and German industrial corridor retrofits. EPA cool roof reflectivity mandates and KBA-adjacent energy efficiency codes tighten thermal performance thresholds for multi-layer SBS systems.
- Industrial Roofing:Manufacturing facilities and logistics centers demand fatigue-resistant membranes under thermal cycling stress.
- Residential Roofing:Steeper-slope applications and smaller project scales limit SBS penetration against asphalt shingle alternatives.
Waterproofing commands the steepest margin expansion trajectory. Commercial Roofing anchors absolute revenue scale.
End User:
Procurement authority is shifting from traditional distributor networks toward direct manufacturer-contractor relationships.
- Contractors:Certified roofing installers in Texas and Florida are accepting manufacturer-direct training and warranty administration to secure project margin and bypass distributor markups.
- Architects:Building information modeling integration drives specification around digital compatibility and open API data exchange capabilities for envelope energy modeling.
- Builders:Production homebuilders and commercial general contractors prioritize cost certainty and installation speed over performance customization.
- Property Owners:Industrial facility managers across Baden-Württemberg and Bavaria specify multi-layer SBS systems with enhanced insulation integration to comply with tightening thermal performance mandates.
Contractors control today's project flow. Architects are gaining tomorrow's specification authority.
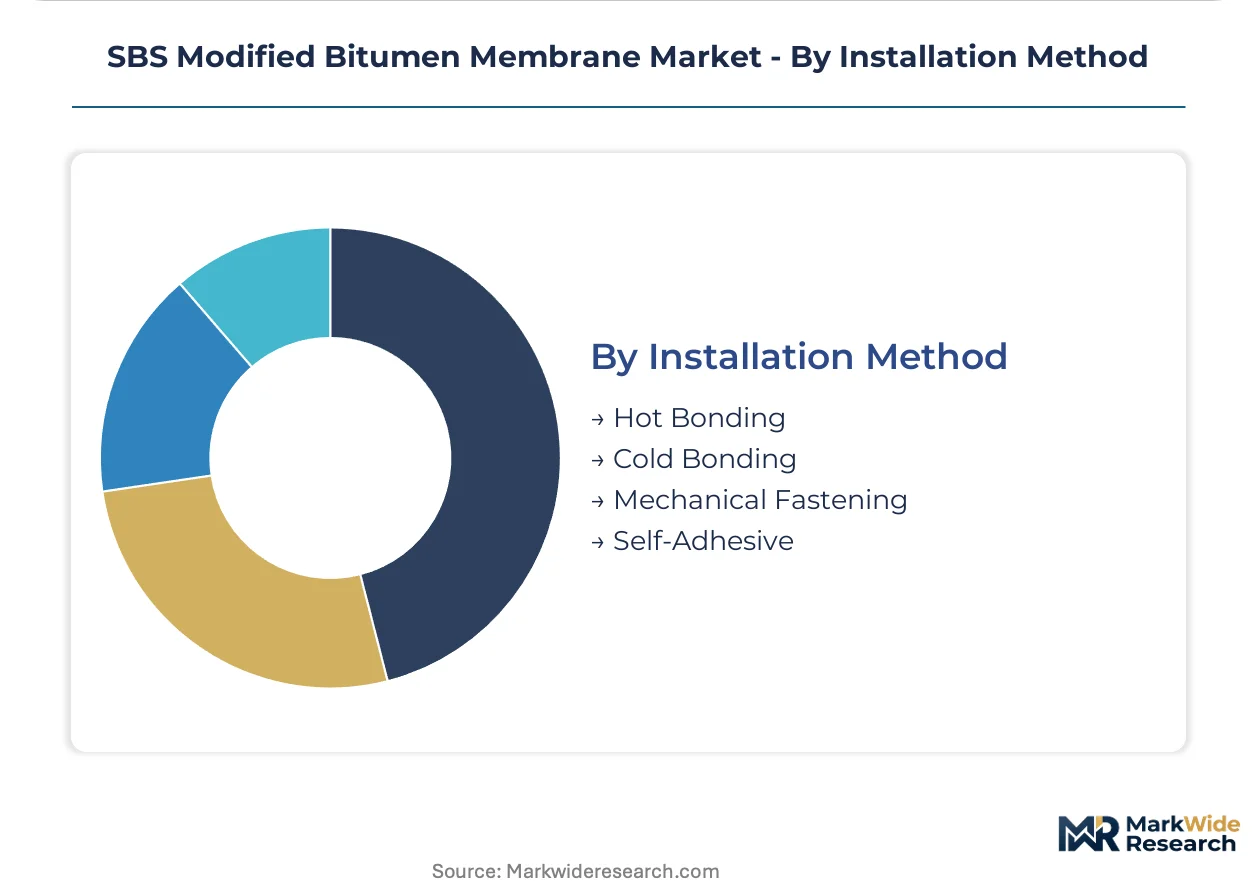
Installation Method:
Certification bottlenecks and labor scarcity are restructuring competitive advantage around installation technology rather than membrane formulation alone.
- Hot Bonding:Torch-applied and hot-air welding methods dominate European commercial roofing through established contractor training infrastructure. Robotic welding systems are automating seam quality control on large-format German warehouse projects.
- Self-Adhesive:Factory-applied adhesive layers eliminate field mixing and open-flame hazards. US urban construction markets exhibit fastest adoption where fire codes restrict torch operations.
- Cold Bonding:Solvent-based and water-based adhesives serve temperature-restricted installation windows.
- Mechanical Fastening:Screw and plate systems anchor membranes on steel decks and high-wind zones.
Hot Bonding retains today's volume dominance. Self-Adhesive formats are climbing the fastest on safety-driven specification shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The German industrial corridor anchors SBS membrane specification intensity, with reroofing cycles and energy retrofit mandates overlapping across Baden-Württemberg and Bavaria. Demand concentrates in four national markets where building envelope regulations and contractor infrastructure create distinct competitive environments.
United States
Commercial roofing contractors across the Sun Belt are compressing reroofing cycles as building owners pursue EPA cool roof compliance. The EPA's reflectivity mandates for low-slope commercial envelopes accelerate specification of white-surfaced SBS membranes. Texas and Florida construction markets exhibit strongest demand concentration, with contractors accepting manufacturer-direct training to bypass distributor markups.
Germany
Industrial facility managers across Baden-Württemberg and Bavaria specify multi-layer SBS systems with enhanced insulation integration. KBA-adjacent energy efficiency codes tighten thermal performance thresholds for commercial roofing assemblies. The Antwerp-Rotterdam chemical hub supplies REACH-compliant SBS polymer to membrane plants serving German contractors.
France
Warehouse envelope projects exceeding 50,000 square meters drive torch-applied membrane volume through automated hot-air welding platforms. ECHA REACH restrictions on polycyclic aromatic hydrocarbon content force reformulation of polymer compatibility agents. Roofing plants in northern France face eighteen-month qualification timelines for revised product certifications.
United Kingdom
Urban healthcare and educational construction in dense metropolitan zones prioritizes self-adhering formats for open-flame elimination. The country's building safety regulator enforces strict fire performance standards for occupied building envelopes. London commercial roofing contractors report specification shifts toward peel-and-stick protocols on high-rise retrofits.
Canada
Cold-climate flexibility requirements down to minus 20 degrees Celsius sustain SBS specification against thermoplastic polyolefin substitution. Health Canada's environmental protection standards govern volatile organic compound limits in membrane adhesives. Ontario and Quebec commercial roofing markets concentrate demand for multi-layer systems on industrial logistics facilities.
SBS Modified Bitumen Membrane Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based modifier qualification and direct contractor channel development. The market structure tilts toward consolidation among bitumen refiners with backward integration into polymer supply, while regional specialists defend position through certified installer networks. Three archetypes dominate: integrated petrochemical-bitumen producers, membrane-focused fabricators with captive logistics, and technology licensors specializing in self-adhesive formats. Competitive moves concentrate on M&A for polymer supply security and capacity expansion in southeastern US and central European production zones.
Among integrated European producers, Soprema Group and Johns Manville exemplify contrasting supply architectures. Soprema's backward integration into bitumen refining across its European footprint defends formulation economics against feedstock volatility. Johns Manville anchors North American supply reliability through controlled logistics networks serving commercial roofing distributors. Carlisle sustains manufacturing scale through dedicated roofing membrane facilities in the southeastern United States, representing the regional scale-driven archetype.
| Leading Market Players |
|---|
| TehnoNICOL |
| Carlisle |
| Soprema Group |
| Johns Manville |
| IKO Industries Ltd |
| Sika |
| Polyglass |
| Bauder |
| GAF |
| Others |
Pricing and Supply Chain Analysis
Commercial roofing contractors in the US Sun Belt and German industrial corridor concentrate procurement authority, locking the market into project-based contract pricing with six-month fixed terms that limit polymer cost pass-through.
Pricing Analysis
Input-cost pass-through from butadiene spot volatility compresses membrane margins before contract renegotiation windows open. Pricing stratifies across REACH-compliant premium grades, standard commercial roofing tiers, and economy warehouse specifications. Price differentiation hinges on certification level and thermal performance tier. Cost compression in standard commercial tiers is intensifying because SBS polymer producers lack forward hedging instruments. Warehouse facility managers exhibit highest price sensitivity; tunnel waterproofing contractors show least.
Supply Chain Analysis
Single-source vulnerability sits with the Antwerp-Rotterdam chemical hub supplying REACH-compliant SBS polymer to European membrane plants. Manufacturing concentrates in Belgium, the Netherlands, and Germany. Raw material dependencies include styrene-butadiene-styrene block copolymer, oxidized bitumen flux, and polyester reinforcement carriers. Tariff exposure on imported asphalt feedstock under EU carbon border adjustment mechanics threatens formulation economics. Distribution runs through certified roofing distributor networks, though direct contractor channels are gaining share in Texas and Florida.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA cool roof reflectivity mandates and EU Green Deal renovation targets mechanically expand specification volume.
For Market Incumbents: Acquire captive polymer production capacity or near-shore bitumen refining assets to defend margins against feedstock volatility. Secure backward integration into SBS polymer supply or establish dedicated logistics networks serving Sun Belt distributors. Thermoplastic polyolefin substitution in warm-climate warehouse segments and emerging bio-based modifier entrants threaten volume share. Certification investment in REACH-compliant reformulations represents the critical defensive lever. For New Entrants and Emerging Players: The price-point gap between premium waterproofing tiers and economy commercial roofing creates entry space for mid-market specialists. Target self-adhering membrane specification in US urban healthcare and educational construction where torch-applied certification bottlenecks constrain incumbent response. Below-grade waterproofing for German transit infrastructure stimulus programs offers the most penetrable application vertical. Pursue certified installer program partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Bitumen refiners with membrane fabrication capability are the most active acquirer in this space, consolidating polymer supply security and geographic production footprint. The five-to-ten year viability window favors producers with demonstrated REACH qualification timelines and established contractor certification infrastructure. Acquisition target archetype: regional membrane fabricators with captive logistics networks in southeastern US or central European production zones. Monitor bio-based SBS modifier pilot program advancement as the signal for polymer substitution inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Supply | Defends formulation economics against Antwerp-Rotterdam hub disruption and butadiene volatility. |
| Capacity Expansion in Southeastern US | Positions supply proximity to Texas and Florida contractor direct-channel development. |
| REACH-Compliant Reformulation Program | Qualifies alternative fluxing agents ahead of ECHA polycyclic aromatic hydrocarbon restrictions. |
| Certified Installer Network Development | Bypasses traditional distributor markups to capture margin in manufacturer-direct relationships. |
| Bio-Based Modifier Qualification | Anticipates EU carbon border adjustment mechanics on imported asphalt feedstock costs. |
Research Methodology
Multiple input streams — primary interviews with commercial roofing contractors, membrane plant operations managers, and polymer procurement leads; secondary validation through ECHA REACH filings, EPA cool roof compliance databases, and customs trade data — were reconciled through bottom-up and top-down triangulation. Conversations with German industrial facility managers and US Sun Belt distributors captured specification dynamics. SEC 10-K disclosures from integrated bitumen producers and Cefic chemical industry reports provided production capacity benchmarks.
Data-stream reconciliation across product type, application vertical, installation method, and regional regulatory cluster generated volume and value outputs throughout the forecast period. Segmentation dimensions modeled include torch-applied versus self-adhering formats, commercial roofing versus waterproofing applications, and US Sun Belt versus German industrial corridor demand centers. CAGRs were derived from reroofing cycle compression rates and energy retrofit mandate implementation timelines. Forecast inputs incorporated butadiene price elasticity coefficients and contractor certification backlog durations.
Caveats apply where butadiene feedstock volatility, REACH additive restriction amendments, or TPO substitution acceleration could materially shift the outlook. Forecasts reflect assumptions about regulatory implementation pacing and polymer substitution economics. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Polyvinyl Butyral (PVB) Films and Sheets Market
Membrane Materials
Polymer Electrolyte Membrane Fuel Cells (Pemfcs) Market
Membrane Materials
Membrane Skinners Market
Membrane Materials
Nafion Market
Membrane Materials
Geosynthetic Clay Liner Market
Membrane Materials
North America Transparent Conductive Films Market
Membrane Materials
Polyarylsulfone (PAS) Market
Membrane Materials
Thermoplastic Polyolefin Membranes Market
Membrane Materials
Membrane Filter Cartridge Market
Membrane Materials
Microporous Materials Market
Membrane Materials
Global Transfer Membrane Market
Membrane Materials
Global Tubular Membranes Market
Membrane Materials
Global Breathable Membranes Market
Membrane Materials
Global Waterproofing Membrane Market
Membrane Materials
Polysulfone Market
Membrane Materials
Gas Barrier Membranes Market