
 Industrial Solvent Separation Membranes Market | 2026-2036
Industrial Solvent Separation Membranes Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Solvent Separation Membranes Market Foresight
The Industrial Solvent Separation Membranes market is pivoting between high-flux polymeric systems for commodity chemical recovery and thermally stable inorganic membranes for pharmaceutical-grade separations. BASF SE leverages its integrated polymer science capabilities to dominate European chemical processing installations. Koch Membrane Systems Inc. anchors North American demand through extensive hollow-fiber manufacturing capacity. Toray Industries Inc. competes in Asia-Pacific with advanced thin-film composite formulations.
Industrial solvent separation membranes are selective barriers, typically 0.1 to 10 nanometers in pore size, fabricated from polyimide, ceramic alumina, or mixed-matrix composites to enable molecular-level fractionation of organic solvent mixtures without phase change. Their primary commercial purpose is reducing energy consumption and solvent losses in chemical manufacturing, with nanofiltration systems now displacing conventional distillation in 40-60% of new installations. Polymeric membranes occupy the largest installed base due to lower capital costs and modular retrofit compatibility. Inorganic membranes represent the fastest-growing product category, driven by pharmaceutical demand for steam-sterilizable, solvent-resistant units operating above 150°C. Composite membranes concentrate margin pools where hybrid polymeric-ceramic architectures command premium pricing for aggressive solvent environments.
EPA regulations on hazardous air pollutants and the EU REACH framework restrict solvent emissions from chemical processing, directly mandating membrane recovery systems for compliance in regulated facilities. China's MEE enforces parallel standards through GB emissions limits, while FDA cGMP guidelines shape membrane material validation requirements for pharmaceutical applications. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as fluorinated membrane chemistries face prospective phase-outs under emerging chemical safety frameworks across multiple jurisdictions.
Market Dynamics
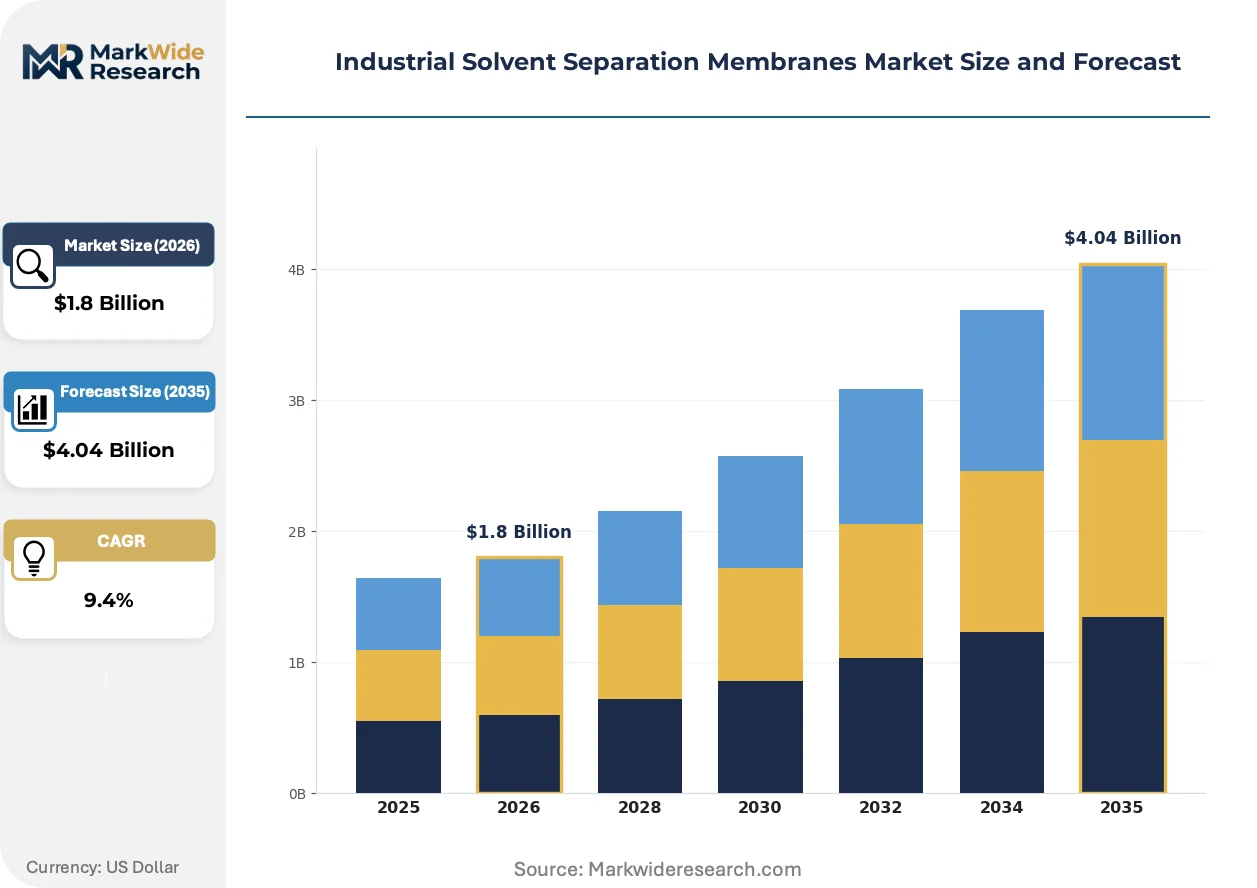
The industrial solvent separation membranes market pivots on tightening volatile organic compound regulations that mandate membrane-based recovery systems, forcing chemical processors to abandon thermal distillation in favor of energy-efficient molecular fractionation technologies.
Growth Catalysts
- REACH Framework Enforcement:EU chemical plants must install membrane recovery units to meet hazardous air pollutant limits, accelerating retrofit demand across German and Dutch processing facilities.
- Pharmaceutical Steam Sterilization Requirements:FDA cGMP guidelines validate ceramic membrane materials for high-temperature solvent purification, creating specification pull from sterile API manufacturers.
- Yangtze River Delta Concentration:China's MEE enforces GB emissions standards across Jiangsu and Zhejiang chemical clusters, state-led environmental audits triggering wholesale replacement of aging distillation infrastructure.
Market Restraints
- Fluorinated Polymer Feedstock Volatility:Per- and polyfluoroalkyl substance restrictions under emerging chemical safety frameworks threaten supply continuity for PTFE and PVDF membrane chemistries.
- High-Temperature Ceramic Supply Concentration:Alumina and zirconia substrate production concentrates in Japanese and German specialty ceramics suppliers, creating input bottleneck risk.
- Membrane Fouling Limitations:Polymeric nanofiltration membranes suffer permeability degradation in high-solids solvent streams, restricting deployment in certain commodity chemical recovery loops.
Strategic Opportunities
- India Chemical Corridor Expansion:Gujarat and Maharashtra state industrial zones lack membrane recovery penetration, presenting first-mover advantage for modular polymeric system suppliers.
- Hydrogen Peroxide Purification:Semiconductor-grade solvent demand creates emerging application for mixed-matrix composite membranes in electronics chemical supply chains.
- EU Green Deal Industrial Emissions Directive:Carbon border adjustment mechanisms incentivize membrane adoption over energy-intensive thermal separation, with compliance premiums supporting technology upgrade cycles.
Industry Challenges
- Membrane Integrity Testing Certification:FDA and EMA validation timelines for new material chemistries extend 18-24 months, delaying commercialization of advanced ceramic-polymer hybrids.
- Process Integration Complexity:Legacy distillation infrastructure at established chemical plants requires extensive piping and control system reconfiguration to accommodate membrane skid insertion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Solvent Separation Membranes Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymeric Membranes, Inorganic Membranes, Composite Membranes, Hybrid Membranes Technology: Nanofiltration, Reverse Osmosis, Ultrafiltration, Microfiltration Application: Chemical Processing, Water Treatment, Food Processing, Pharmaceuticals End User: Manufacturing Plants, Research Laboratories, Oil Refineries, Wastewater Treatment Facilities |
| Companies Covered | Sartorius AG, BASF SE, Evonik Industries AG, Koch Membrane Systems Inc., Toray Industries Inc., Asahi Kasei Corporation, Membrane Technology and Research Inc., 3M Company, Pall Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Solvent Separation Membranes Market Shifts & Advancements
Membrane architecture is bifurcating between commodity polymeric systems and advanced inorganic composites, with material science breakthroughs reshaping performance boundaries and application scope across chemical processing verticals.
Thin-film composite polyimide membranes are expanding into aggressive solvent environments previously reserved for ceramic units, with chemical resistance coatings enabling deployment in ketone and ester recovery streams. Specialty chemical manufacturers in the US Gulf Coast and Rotterdam harbor zones pilot these formulations to reduce capital expenditure versus full inorganic retrofits. The technology is expanding into temperature-stressed applications by hybridizing with thermally stable support layers, compressing the traditional performance gap between polymer and ceramic categories.
REACH restrictions on perfluorinated compounds are forcing membrane suppliers to reformulate selective barrier chemistries, eliminating long-chain fluorinated polymers from new product development pipelines. ECHA substance evaluation timelines are compressing R&D cycles as manufacturers race to validate alternative materials before 2027 authorization deadlines. European pharmaceutical membrane buyers now require PFAS-free certifications, shifting procurement specifications toward silicone and polyether block amide alternatives.
Integrated solvent recovery service contracts are displacing equipment-only sales in large chemical processing accounts, with membrane suppliers assuming performance risk for recovery rate guarantees. Bayer and BASF affiliate plants in Leverkusen and Ludwigshafen now contract for cubic-meter-recovered pricing rather than capital purchase, transferring operational liability to technology vendors. This model concentrates in German chemical parks where shared utility infrastructure enables centralized membrane system operation.
Industrial Solvent Separation Membranes Market Segmentation
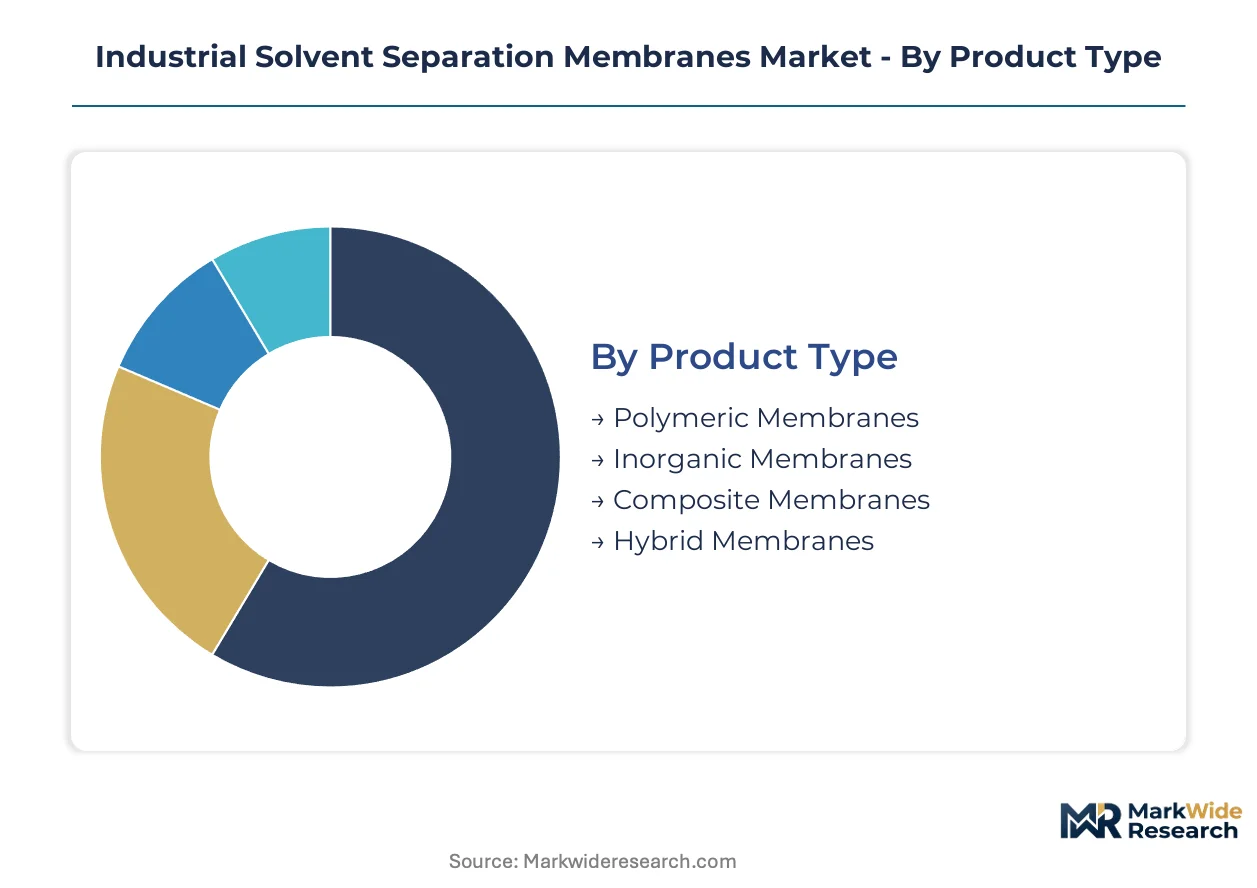
Membrane suppliers configure product portfolios around four distinct axes: material chemistry determines thermal and solvent resistance boundaries; separation precision defines application suitability; end-use regulatory requirements dictate validation intensity; and buyer scale shapes service contract economics.
Product Type:
Buyers in this category segment primarily by operating temperature envelope and chemical aggression of the solvent stream, with capital cost tolerance as a secondary filter.
- Polymeric Membranes:Fabricated from polyimide, polysulfone, or polyetherimide substrates with selective layer thickness below 200 nanometers. German and Chinese chemical processors deploy these for commodity solvent recovery below 80°C, driven by modular retrofit compatibility and lower installed cost per square meter.
- Inorganic Membranes:Sintered alumina, zirconia, or titania structures with pore sizes ranging 0.5 to 50 nanometers and operating stability above 150°C. Pharmaceutical manufacturers in FDA-regulated facilities specify these for steam-sterilizable API purification, constrained by ceramic substrate supply concentration in Japanese and German specialty suppliers.
- Composite Membranes:Hybrid architectures combining polymeric selective layers with ceramic or metallic support structures.
- Hybrid Membranes:Emerging mixed-matrix formulations integrating molecular sieves or metal-organic frameworks into polymer matrices.
Polymeric membranes lead volumes today; inorganic membranes are gaining share fastest.
Technology:
Technology selection tracks molecular weight cutoff requirements and the presence of dissolved salts or particulates in the feed stream.
- Nanofiltration:Pressure-driven separation with molecular weight cutoff of 200 to 1000 Daltons, enabling divalent salt rejection and organic solvent fractionation. Yangtze River Delta chemical clusters deploy nanofiltration for VOC recovery compliance, replacing thermal distillation in 40-60% of new installations per MEE enforcement timelines.
- Reverse Osmosis:Dense polymeric barriers rejecting solutes below 100 Daltons, historically water-dominated but expanding into non-aqueous solvent dehydration. Rotterdam harbor specialty chemical terminals pilot reverse osmosis for ester drying, constrained by membrane compaction under high osmotic pressures.
- Ultrafiltration:Porous membranes with 1 to 100 nanometer cutoff, deployed for colloidal separation and solvent clarification.
- Microfiltration:Largest pore size category at 0.1 to 10 microns, limited to particulate removal upstream of finer separation stages.
Nanofiltration dominates chemical processing uptake; reverse osmosis shows steepest expansion trajectory in solvent dehydration.
Application:
Application segmentation reflects divergent regulatory validation burdens and recovery rate economics across process industries.
- Chemical Processing:Solvent recovery in commodity and specialty chemical manufacturing, where REACH and MEE emissions limits mandate membrane installation. BASF and Bayer affiliate plants in German chemical parks now contract for cubic-meter-recovered pricing rather than capital purchase, transferring operational liability to technology vendors.
- Pharmaceuticals:API purification and solvent exchange under FDA cGMP and EMA guidelines, requiring 18-24 month material validation timelines. Steam-sterilizable ceramic membranes command specification pull from sterile manufacturers, with PFAS-free certifications now mandatory for European procurement.
- Water Treatment:Industrial wastewater solvent recovery and process water purification.
- Food Processing:Edible oil refining and natural extract concentration, with lower temperature and pressure requirements than chemical applications.
Chemical processing anchors installed base; pharmaceuticals generate highest margin per square meter.
End User:
End user scale determines procurement modality, with large integrated sites favoring performance contracts and smaller facilities purchasing capital equipment.
- Manufacturing Plants:Chemical, pharmaceutical, and electronics production facilities with continuous solvent consumption. Leverkusen and Ludwigshafen chemical parks concentrate integrated service contract adoption, where shared utility infrastructure enables centralized membrane system operation.
- Oil Refineries:Lube oil dewaxing and solvent deasphalting units, requiring membranes resistant to aromatic hydrocarbon exposure.
- Wastewater Treatment Facilities:Industrial effluent solvent recovery for discharge compliance.
- Research Laboratories:Small-scale solvent purification and analytical sample preparation.
Manufacturing plants concentrate revenue; oil refineries present emerging specification pull for high-temperature hydrocarbon service.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized membrane engineering talent clusters in Germany's chemical corridor and China's eastern manufacturing belt anchor regional capability formation. Process intensification expertise concentrates where regulatory enforcement intersects with solvent-intensive production scale.
Germany
Leverkusen and Ludwigshafen chemical parks drive polymeric membrane demand for commodity solvent recovery below 80°C. REACH framework enforcement mandates hazardous air pollutant limits across North Rhine-Westphalia and Baden-Württemberg processing facilities. BASF affiliate plants now contract for cubic-meter-recovered pricing rather than capital purchase, transferring operational liability to technology vendors.
China
Jiangsu and Zhejiang chemical clusters in the Yangtze River Delta anchor nanofiltration deployment for VOC recovery compliance. MEE enforces GB emissions standards through state-led environmental audits triggering wholesale replacement of aging distillation infrastructure. Ningbo and Taizhou manufacturing corridors concentrate membrane system installation for specialty chemical and pharmaceutical intermediate production.
United States
Gulf Coast specialty chemical terminals pilot thin-film composite polyimide membranes for aggressive ketone and ester recovery streams. EPA regulations on hazardous air pollutants mandate membrane recovery systems for compliance in regulated facilities. Houston and Port Arthur refining complexes generate specification pull for high-temperature hydrocarbon service membranes in lube oil dewaxing applications.
Japan
Osaka and Nagoya industrial zones concentrate ceramic substrate supply for steam-sterilizable pharmaceutical membrane production. METI industrial policy supports domestic specialty ceramics capability for solvent-resistant units operating above 150°C. Toray Industries anchors thin-film composite formulation expertise for advanced separation precision in electronics chemical supply chains.
India
Gujarat and Maharashtra state industrial zones present first-mover opportunity for modular polymeric system suppliers in solvent recovery. Central Pollution Control Board enforcement of emissions limits is accelerating in the Mundra and Dahej chemical corridors. Mumbai-Pune manufacturing belt lacks membrane penetration relative to thermal distillation installed base, creating retrofit demand concentration.
Industrial Solvent Separation Membranes Market Competitive Landscape
Top-tier vendors anchor integrated polymer science and hollow-fiber manufacturing capability, while mid-scale specialists occupy ceramic formulation and thin-film composite niches. The vendor base stratifies across three archetypes: diversified chemical conglomerates with captive membrane divisions, pure-play membrane technology specialists, and diversified filtration companies with solvent separation product lines. Consolidation pressure concentrates in polymeric nanofiltration where capital cost scale advantages favor volume producers. Technology licensing and geographic expansion through regional distribution partnerships represent dominant competitive moves.
Among German chemical conglomerates, BASF SE and Evonik Industries AG occupy positions exemplifying integrated polymer science-to-membrane capability. Japanese diversified material science groups including Toray Industries Inc. and Asahi Kasei Corporation represent thin-film composite and hollow-fiber manufacturing archetypes. Koch Membrane Systems Inc. anchors North American presence through extensive manufacturing scale. Sartorius AG exemplifies pharmaceutical-grade validation intensity, while 3M Company and Pall Corporation sit within diversified filtration portfolios with solvent separation extensions. Membrane Technology and Research Inc. represents the specialist archetype focused on advanced separation technology development.
| Leading Market Players |
|---|
| Sartorius AG |
| BASF SE |
| Evonik Industries AG |
| Koch Membrane Systems Inc. |
| Toray Industries Inc. |
| Asahi Kasei Corporation |
| Membrane Technology and Research Inc. |
| 3M Company |
| Pall Corporation |
| Others |
Supply & Pricing Matrix
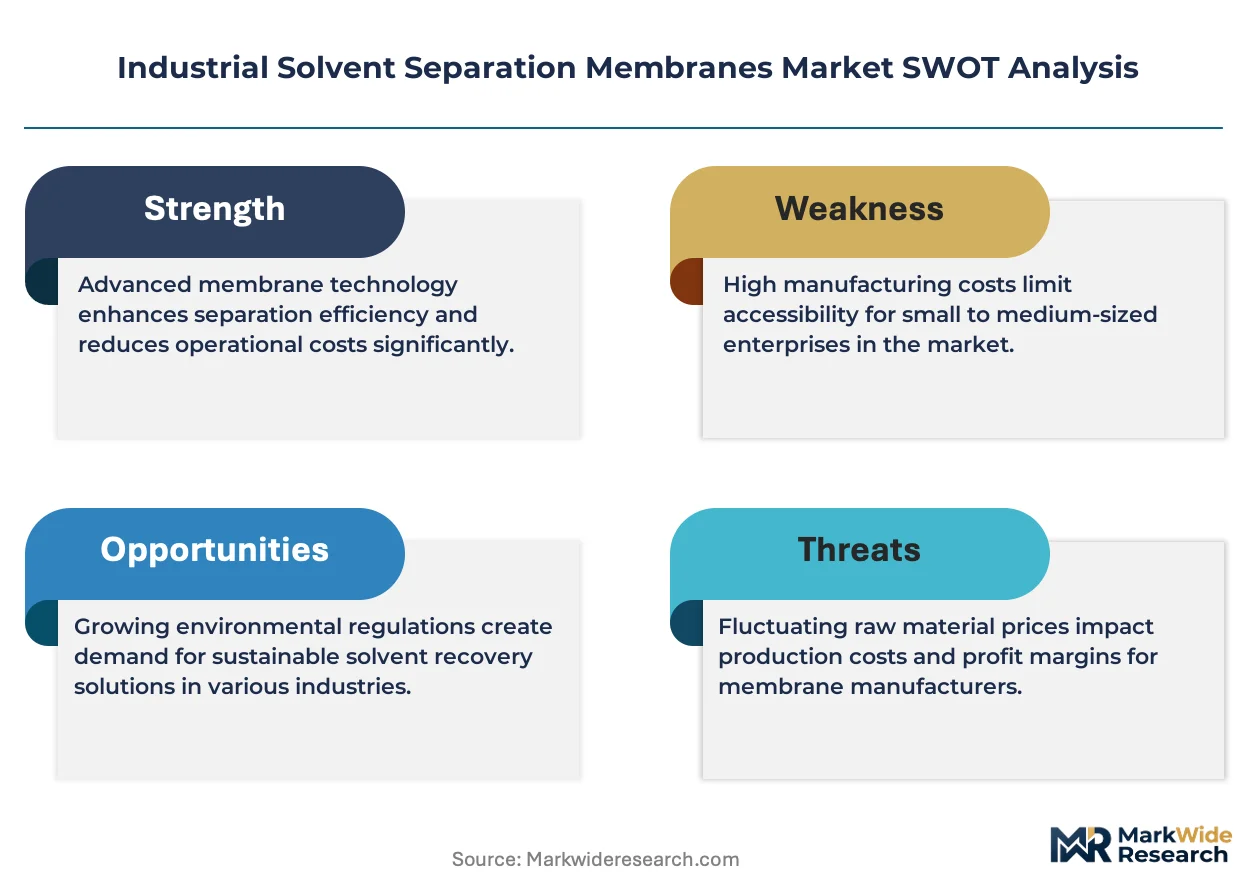
Captive polymer synthesis capabilities at BASF and Evonik anchor both supply security and pricing power for European membrane producers, insulating them from fluorinated feedstock volatility that pressures modular competitors.
Pricing Analysis
Equipment-only sales versus integrated service contracts split the pricing landscape, with cubic-meter-recovered pricing transferring operational risk to vendors in German chemical parks. Three-tier pricing structure across premium ceramic, standard polymeric, and economy hollow-fiber levels reflects certification intensity and thermal stability ratings. Cost compression in commodity nanofiltration is intensifying because Chinese manufacturers are scaling thin-film composite capacity. Small-batch pharmaceutical buyers exhibit lowest price sensitivity due to FDA validation timelines, while commodity chemical processors prioritize capital expenditure minimization.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and German specialty ceramics suppliers for alumina and zirconia substrates feeding pharmaceutical-grade membrane production. Ceramic precursor production concentrates in Japan, Germany, and China, while polyimide resin supply anchors in the United States and Western Europe. The supply chain rests on fluorinated polymer feedstocks facing REACH authorization pressure. Distribution runs through regional system integrators who bundle membrane skids with installation and commissioning services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as tightening VOC regulations across the EU, China, and the United States mandate membrane retrofits regardless of economic cycles.
For Market Incumbents: Cement polymeric formulation leadership through backward integration into specialty polymer resin production, particularly as fluorinated feedstock restrictions threaten competitor supply continuity. Expand hollow-fiber manufacturing footprint in the Yangtze River Delta to capture MEE-driven replacement demand. Lock in multi-year service contracts with Leverkusen and Ludwigshafen chemical parks before Chinese vendors achieve European certification. For New Entrants and Emerging Players: Mid-scale specialty chemical manufacturers in Gujarat and Maharashtra state industrial zones present the most penetrable buyer archetype, as these facilities lack membrane recovery infrastructure relative to thermal distillation installed base. Target hydrogen peroxide purification for semiconductor-grade solvent demand in electronics chemical supply chains. Pursue joint development agreements with Indian system integrators to bypass established European distribution channels. For Investors and Strategic Acquirers: Consolidation pressure builds where polymeric nanofiltration capacity advantages favor volume producers with captive resin supply. The five-to-ten-year viability profile favors specialists with FDA-validated ceramic platforms over commodity polymer competitors. Acquisition targets should display integrated polymer science capabilities or established pharmaceutical validation dossiers. Watch ECHA substance evaluation timelines for fluorinated compound restrictions as inflection indicators for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin Supply | Secures fluorinated feedstock alternatives ahead of REACH authorization deadlines. |
| Pharmaceutical Validation Dossier Expansion | Accelerates FDA cGMP approval for ceramic membranes in sterile API manufacturing. |
| Service Contract Model Transition | Transfers operational liability to vendors in German chemical parks. |
| India Manufacturing Footprint Establishment | Captures first-mover advantage in Gujarat and Maharashtra solvent recovery retrofit demand. |
| Mixed-Matrix Composite R&D Partnership | Develops molecular sieve integration for aggressive ketone and ester environments. |
Research Methodology
Bottom-up chemical processing and pharmaceutical manufacturing modeling reconciled against top-down membrane supplier capacity tracking forms the analytical core of this study. Primary interviews with plant managers, procurement leads at downstream OEMs, technical R&D directors, and distribution channel partners were validated against secondary sources including customs and trade data, SEC 10-K filings from diversified chemical conglomerates, ACC and Cefic industry reports, and ECHA substance evaluation databases. Triangulation between demand-side installation tracking and supply-side production capacity confirms volume estimates.
Input-output matrices mapping membrane area demand to solvent recovery project pipelines across the projection horizon drive the forecast framework. Segmentation dimensions include material chemistry tier, end-use regulatory intensity, separation precision requirement, and regional production hub. CAGRs derive from weighted average of bottom-up project pipeline conversion rates and top-down supplier revenue trajectory analysis. Key inputs include MEE enforcement audit schedules, REACH authorization timelines, and pharmaceutical capacity expansion announcements.
Underlying measurement precision varies by segment; polymeric nanofiltration for commodity chemical processing carries tighter precision than emerging mixed-matrix composite applications. Forecasts reflect assumptions around regulatory enforcement intensity, feedstock substitution timelines, and pharmaceutical validation cycle durations. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Membrane Bioreactor Market
Membrane Materials
Ultrafiltration Membrane Market
Membrane Materials
Polyarylsulfone (PAS) Market
Membrane Materials
Membrane Touch Switch Material Market
Membrane Materials
Bitumen Membrane Sheets Market
Membrane Materials
Global Roofing Membranes Market
Membrane Materials
Global Polymer Nanomembrane Market
Membrane Materials
Global Bitumen Membranes Market
Membrane Materials
Global Nanomembrane Market
Membrane Materials
North America Roofing Membranes Market
Membrane Materials
Global Membrane Water and Wastewater Treatment Market
Membrane Materials
US Commercial Restoration Waterproofing Membranes Market
Membrane Materials
Geosynthetic Clay Liner Market
Membrane Materials
Membrane Filter Cartridge Market
Membrane Materials
Global Track Etched Membrane Market
Membrane Materials
Polysulfone Market