
 North America Ceramic Membranes Market | 2026-2036
North America Ceramic Membranes Market Size, Share, and Industry Trends Forecast 2026-2036
North America Ceramic Membranes Market Analytics
Aftermarket service revenue is reconfiguring margin capture across the North America ceramic membranes landscape. TAMI Industries leverages its tubular membrane refurbishment network to sustain recurring income streams. Nanostone anchors its position through advanced silicon carbide flat-sheet architectures that command premium positioning.
Ceramic membranes are inorganic filtration barriers, typically composed of alumina, zirconia, or silicon carbide sintered at temperatures exceeding 1,600°C, designed to separate particulates and macromolecules from liquid streams under high thermal and chemical stress. Ultrafiltration product lines currently dominate installed base value, while nanofiltration segments are gaining traction in pharmaceutical process water applications where organic rejection requirements are tightening. Ceramic membrane bioreactor technology is displacing conventional activated sludge in municipal retrofits, creating new equipment-plus-service contract structures.
EPA effluent limitation guidelines, NSF/ANSI 61 drinking water system component standards, and state-level PFAS maximum contaminant levels are collectively elevating membrane performance verification burdens and shortening replacement cycles. The U.S. Department of Energy's industrial efficiency directives are pushing chemical processors toward crossflow ceramic systems that reduce thermal regeneration energy. Stakeholders must monitor how emerging per- and polyfluoroalkyl substance regulations reshape membrane material qualification pathways and supplier certification requirements.
Market Dynamics
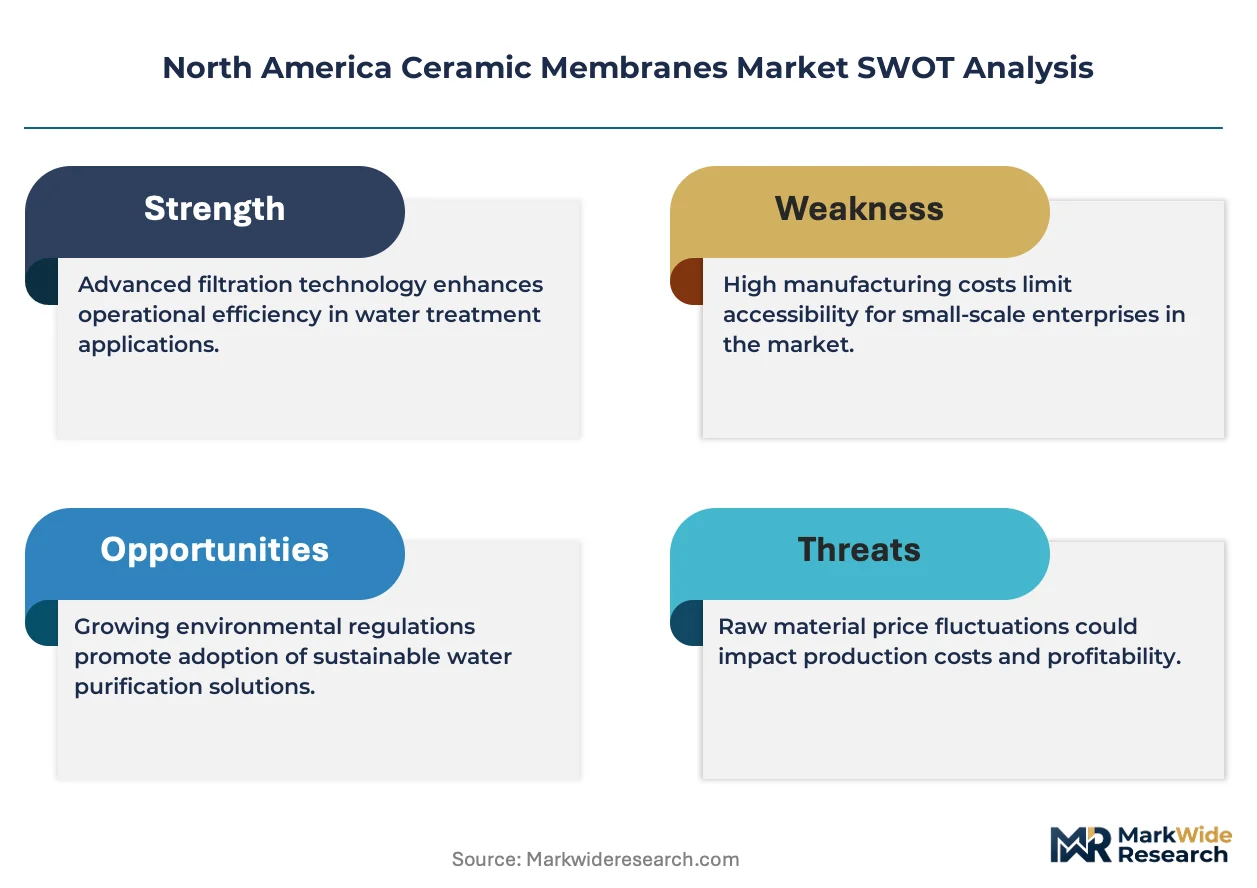
EPA effluent limitation guidelines and state-level PFAS mandates are compressing membrane replacement cycles across municipal and industrial water treatment infrastructure, forcing capital redeployment toward higher-rejection ceramic architectures.
Growth Catalysts
- Tertiary wastewater mandates:EPA effluent standards for nitrogen and phosphorus removal are compelling U.S. municipal facilities to retrofit conventional activated sludge systems with ceramic membrane bioreactors.
- Silicon carbide flat-sheet adoption:Chemical processors are specifying advanced silicon carbide geometries for high-temperature crossflow applications under Department of industrial efficiency directives.
- Great Lakes infrastructure renewal:Aging water treatment plants across Michigan, Ohio, and Ontario are triggering concentrated capital deployment for ceramic ultrafiltration upgrades.
Market Restraints
- Alumina feedstock volatility:Sintered alumina membrane production faces input cost pressure from bauxite refining capacity concentration in specific supplier geographies.
- High capital intensity:Ceramic membrane bioreactor installations require substantially higher upfront expenditure than polymeric hollow-fiber alternatives, extending municipal procurement cycles.
- Technical limitation in organic solvent nanofiltration:Current silicon carbide and zirconia formulations exhibit limited solvent stability in aggressive pharmaceutical process streams.
Strategic Opportunities
- Pharmaceutical process water:Tightening organic rejection requirements in drug manufacturing are opening nanofiltration segments previously served by polymeric membranes.
- Canada municipal expansion:Underpenetrated water treatment infrastructure in Prairie provinces presents whitespace for ceramic membrane adoption as federal infrastructure funding flows.
- Membrane refurbishment services:Tubular ceramic membrane regeneration networks are creating recurring revenue streams distinct from original equipment sales.
Industry Challenges
- NSF/ANSI 61 certification timelines:Drinking water system component verification processes are extending product qualification periods for new ceramic formulations.
- Integration complexity:Retrofitting ceramic membranes into legacy polymeric membrane plants requires custom engineering that strains installer capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Ceramic Membranes Market |
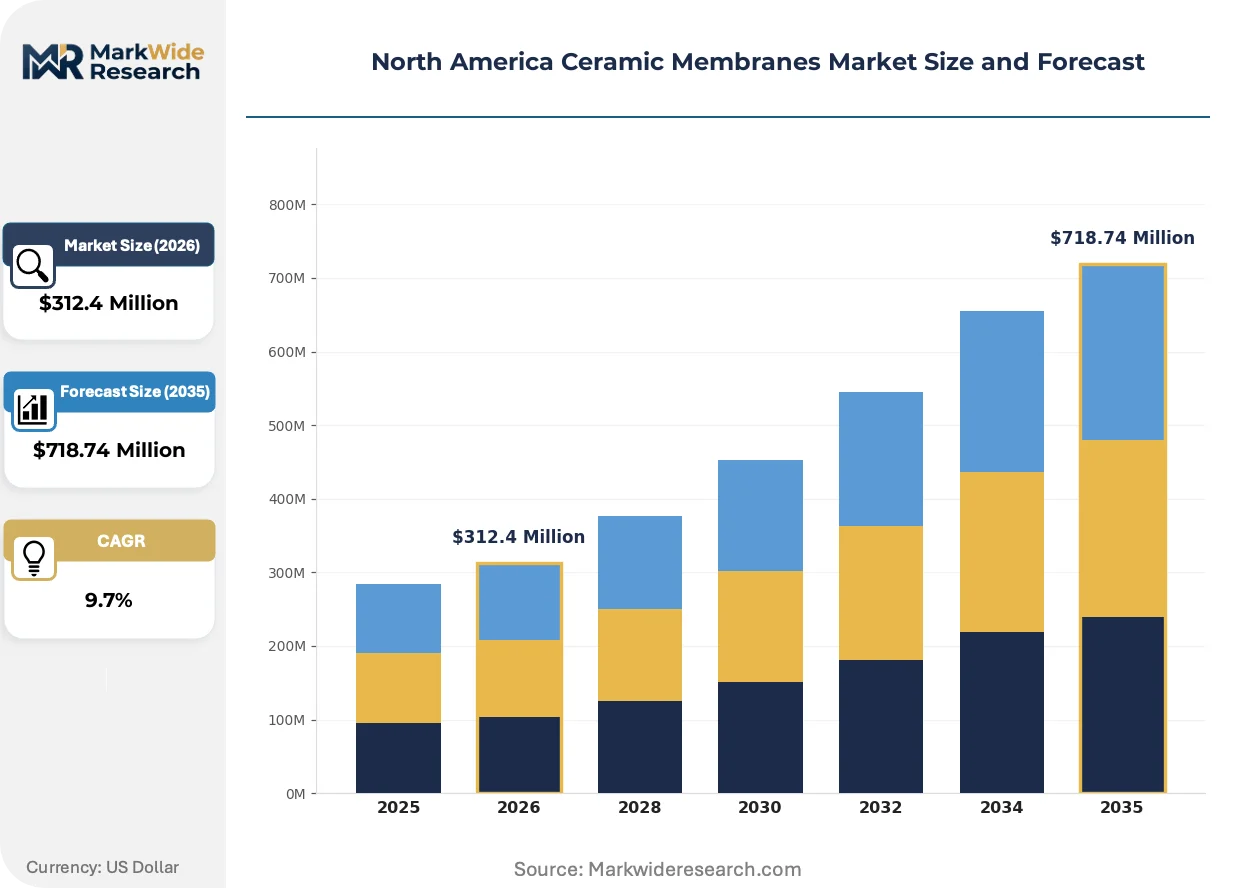
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $718.74 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microfiltration, Ultrafiltration, Nanofiltration, Reverse Osmosis End User: Water Treatment Facilities, Food and Beverage, Pharmaceutical, Chemical Processing Technology: Ceramic Ultrafiltration, Ceramic Membrane Bioreactor, Crossflow Filtration, Dead-End Filtration Application: Wastewater Treatment, Drinking Water Purification, Industrial Process Water, Desalination |
| Companies Covered | TAMI Industries, atechn innovations gmbh, GEA Group Aktiengesellschaft, Nanostone, LiqTech Holding A/S, Qua Group LLC, TORAY INDUSTRIES, INC., METAWATER Co., LTD., Aquatech International LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Ceramic Membranes Market Evolving Landscape
Material science advances and service model reinvention are restructuring how ceramic membrane value is captured across the North American water treatment landscape.
Silicon carbide flat-sheet architectures are penetrating pharmaceutical and chemical processing sectors where thermal and chemical resistance thresholds exceed alumina capabilities. Biopharmaceutical manufacturers are specifying these materials for continuous manufacturing process water loops. This substrate transition is virtualizing the traditional equipment-plus-chemical consumables revenue model toward membrane-as-a-service structures.
EPA per- and polyfluoroalkyl substance maximum contaminant level proposals are elevating membrane performance verification burdens for drinking water applications. Municipal utilities must now demonstrate rejection capabilities for emerging contaminants beyond conventional turbidity and pathogen targets. Ultrafiltration product lines with demonstrated PFAS rejection are commanding preference in U.S. Great Lakes region procurement cycles.
Aftermarket refurbishment networks are unbundling from original equipment manufacturers, creating independent service channels for tubular membrane regeneration. Industrial end-users are separating membrane replacement decisions from capital equipment procurement, compressing switching cycles. This pattern is most visible in U.S. chemical processing corridors where operational uptime premiums exceed brand loyalty considerations.
North America Ceramic Membranes Market Segmentation
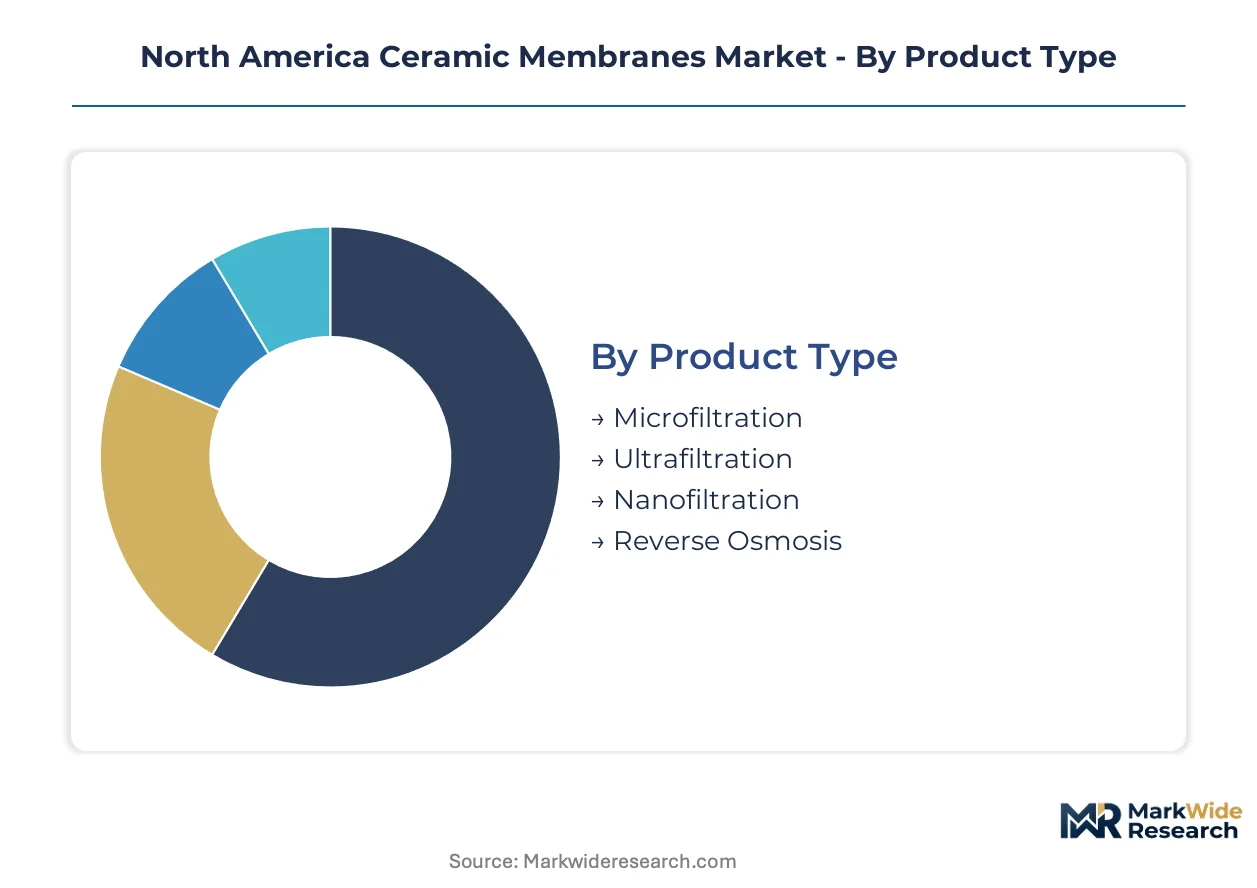
Ceramic membrane purchasing decisions in North America fragment across technical specifications, regulatory compliance tiers, and operational scale. Understanding how demand concentrates within each dimension reveals where capital deployment and margin capture diverge across the value chain.
Product Type:
Cost tier stratification in ceramic membranes separates municipal procurement from premium industrial specifications, with pore size precision and thermal tolerance commanding price premiums.
- Ultrafiltration:Alumina and zirconia formulations with 0.01–0.1 micron pore ranges dominate installed base value across U.S. municipal tertiary treatment retrofits. EPA nitrogen and phosphorus effluent mandates in the Great Lakes region are accelerating membrane bioreactor specifications in this tier.
- Nanofiltration:Silicon carbide architectures achieve molecular weight cutoffs below 1,000 Daltons for pharmaceutical organic rejection requirements. Tightening FDA process water standards for continuous drug manufacturing are opening substitution opportunities against polymeric membranes in New Jersey and Massachusetts biopharma corridors.
- Microfiltration:Larger pore structures serve pre-treatment stages in Canadian oil sands produced water applications.
- Reverse Osmosis:Ceramic-supported polyamide thin-film composites address high-salinity industrial brines where thermal stability exceeds polymer limits.
Ultrafiltration commands the established base. The steepest expansion runs through nanofiltration.
End User:
Application context determines ceramic membrane specification intensity, with pharmaceutical and chemical sectors tolerating premium pricing for thermal and chemical resistance.
- Water Treatment Facilities:Municipal utilities across Michigan, Ohio, and Ontario deploy ceramic ultrafiltration for combined sewer overflow and tertiary wastewater compliance. Aging infrastructure replacement cycles and state-level PFAS maximum contaminant level proposals are compressing procurement timelines in this segment.
- Chemical Processing:Texas and Louisiana Gulf Coast petrochemical complexes specify silicon carbide crossflow systems under Department of Energy industrial efficiency directives for high-temperature solvent recovery. Operational uptime premiums in this segment sustain membrane-as-a-service contract structures.
- Pharmaceutical:FDA process water validation requirements and USP <643> total organic carbon standards drive ceramic adoption for WFI (Water for Injection) generation.
- Food and Beverage:Dairy protein concentration and juice clarification applications in Wisconsin and California tolerate lower specification thresholds than pharmaceutical or chemical tiers.
Water treatment facilities absorb the highest absolute volume. Chemical processing delivers the fastest margin expansion.
Technology:
Deployment architecture separates continuous-flow industrial operations from batch municipal treatment, with bioreactor integration commanding integrated equipment-plus-service contracts.
- Ceramic Membrane Bioreactor:Immersed or sidestream configurations combine biological treatment with ceramic ultrafiltration, displacing conventional activated sludge in U.S. municipal retrofits. Extended sludge age operation and smaller physical footprints justify premium capital outlays against polymeric hollow-fiber alternatives in land-constrained Great Lakes facilities.
- Crossflow Filtration:Tangential flow geometries minimize fouling in high-solids chemical processing streams. Texas petrochemical corridors and Alberta oil sands operations specify these systems for thermal regeneration energy reduction under federal efficiency mandates.
- Ceramic Ultrafiltration:Standalone pressure-driven modules serve drinking water purification in Canadian Prairie provinces with underpenetrated infrastructure.
- Dead-End Filtration:Direct-flow configurations address low-solids applications with reduced energy requirements but higher fouling susceptibility.
Crossflow filtration holds the revenue concentration. Ceramic membrane bioreactor deployments are climbing the fastest.
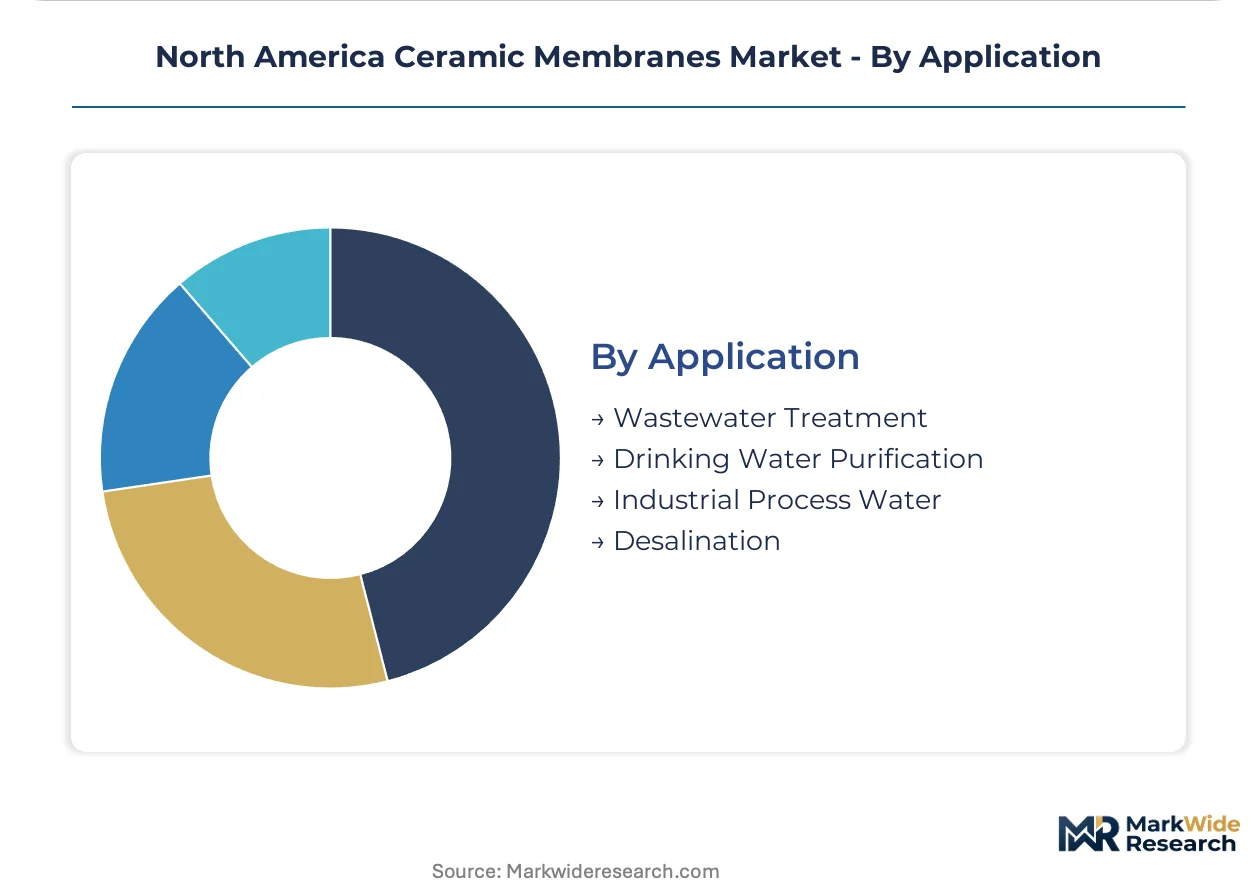
Application:
Geography and regulatory stringency concentrate demand within each application tier, with emerging contaminant mandates reshaping specification priorities.
- Wastewater Treatment:Tertiary filtration for nitrogen, phosphorus, and suspended solids removal dominates capital deployment across U.S. municipal infrastructure. EPA effluent limitation guidelines and state-level nutrient credit trading programs are standardizing ceramic membrane bioreactor specifications in Chesapeake Bay and Great Lakes watersheds.
- Industrial Process Water:Closed-loop purification for chemical, pharmaceutical, and electronics manufacturing tolerates higher operating costs for thermal and chemical stability. Silicon carbide flat-sheet architectures are penetrating this tier where regeneration energy and solvent compatibility constraints exclude alumina alternatives.
- Drinking Water Purification:NSF/ANSI 61 certification requirements and emerging PFAS maximum contaminant level proposals are elevating performance verification burdens for municipal utilities in Michigan and Ontario.
- Desalination:Seawater and brackish water applications concentrate in California and Florida coastal utilities with limited alternative supply options.
Wastewater treatment anchors current installations. Industrial process water is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Membrane fabrication capacity clusters in specific supplier geographies, while municipal procurement concentrates in watersheds facing the most stringent effluent mandates. The United States absorbs the dominant share of regional demand, though Canadian infrastructure renewal and Mexican industrial expansion create distinct growth vectors.
United States
Municipal utilities across the Great Lakes watershed deploy ceramic membrane bioreactors for nitrogen and phosphorus removal under EPA effluent limitation guidelines. The Department of Energy's industrial efficiency directives push Texas and Louisiana Gulf Coast petrochemical complexes toward silicon carbide crossflow systems. Michigan and Ohio water treatment facilities compress replacement cycles as state-level PFAS maximum contaminant level proposals advance.
Canada
Prairie provinces present underpenetrated whitespace for ceramic ultrafiltration adoption as federal infrastructure funding flows toward aging water treatment plants. Health Canada drinking water guidelines and emerging contaminant monitoring requirements elevate membrane performance verification burdens. Ontario municipalities along Lake Erie and Lake Ontario shorelines prioritize tertiary filtration upgrades for combined sewer overflow compliance.
Mexico
Industrial process water demand concentrates in Nuevo León and the Bajío Region where automotive and electronics manufacturing clusters expand. Mexican environmental regulators tighten discharge standards for industrial effluent, creating specification pressure for high-rejection ceramic architectures. Monterrey-area chemical processors pilot silicon carbide flat-sheet systems for closed-loop solvent recovery.
North America Ceramic Membranes Market Competitive Landscape
Specialized ceramic membrane fabricators and diversified filtration conglomerates split the market across distinct value capture models. The vendor base organizes around three strategic archetypes: tubular membrane specialists with refurbishment service networks, silicon carbide flat-sheet technology leaders, and integrated water treatment engineering firms with captive membrane supply. Competitive moves concentrate on technology licensing partnerships and aftermarket service unbundling rather than capacity expansion.
Among European-anchored specialists, TAMI Industries exemplifies the tubular membrane archetype with established refurbishment networks, while atech innovations gmbh occupies a position within German-engineered precision fabrication. Nanostone anchors the silicon carbide flat-sheet premium tier. These three represent divergent strategic postures: service-anchored recurring revenue, precision manufacturing scale, and advanced materials premium positioning.
| Leading Market Players |
|---|
| TAMI Industries |
| atechn innovations gmbh |
| GEA Group Aktiengesellschaft |
| Nanostone |
| LiqTech Holding A/S |
| Qua Group LLC |
| TORAY INDUSTRIES, INC. |
| METAWATER Co., LTD. |
| Aquatech International LLC |
| Others |
Value Network & Pricing Analysis
The Houston Ship Channel freight corridor carries sintered alumina feedstock from Gulf Coast refineries to ceramic membrane fabricators, with bunker fuel surcharges amplifying cost differentials between tubular and flat-sheet architectures while EPA certification timelines compress procurement cycles for NSF/ANSI 61-compliant systems.
Pricing Analysis
NSF/ANSI 61 certification dictates the pricing tier structure across the North American ceramic membranes landscape. Three-tier pricing separates silicon carbide flat-sheet premium architectures from alumina tubular standard systems and zirconia economy configurations. Price differentiation hinges on thermal tolerance ratings and after-sales refurbishment bundling. Cost compression in municipal ultrafiltration tiers is intensifying because polymeric hollow-fiber alternatives extend procurement comparison windows. Water treatment facilities exhibit highest price sensitivity; pharmaceutical processors demonstrate lowest.
Supply Chain Analysis
Sintered alumina feedstock draws from bauxite refining capacity concentrated in China, Australia, and Guinea, with ceramic membrane production anchored in German-engineered precision fabrication and U.S.-based silicon carbide substrate development. Critical inputs include high-purity alumina powder, zirconia stabilizers, and silicon carbide wafers. Single-source vulnerability runs through Chinese rare earth processing for zirconia dopants. Distribution runs through integrated water treatment engineering firms with captive membrane supply and independent refurbishment service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized silicon carbide fabrication expertise and NSF/ANSI 61 certification infrastructure represent scarce capabilities that constrain market entry and sustain incumbent pricing power across high-rejection membrane tiers.
For Market Incumbents: Insulate premium positioning by deepening backward integration into silicon carbide substrate production and locking long-term service contracts with Great Lakes municipal utilities before state-level PFAS mandates accelerate replacement cycles. Ceramic membrane bioreactor refurbishment networks represent a defensible moat against polymeric hollow-fiber substitution threats in tertiary wastewater retrofits. For New Entrants and Emerging Players: Build out nanofiltration service capabilities targeting pharmaceutical process water applications in New Jersey and Massachusetts biopharma corridors where FDA validation requirements and USP standards create specification barriers for commodity membrane suppliers. Prairie province municipal infrastructure in Canada presents the most penetrable whitespace for ceramic ultrafiltration adoption. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors silicon carbide flat-sheet specialists with demonstrated pharmaceutical qualification pathways over legacy alumina tubular fabricators facing feedstock cost volatility. Long-term viability hinges on membrane-as-a-service contract structures that decouple replacement revenue from capital equipment cycles. Watch for EPA finalization of PFAS maximum contaminant levels as inflection indicator for accelerated municipal procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Substrate Backward Integration | Captive supply of high-purity SiC wafers reduces TAMI Industries' exposure to Chinese ceramic powder volatility. |
| Membrane-as-a-Service Contract Structure | Nanostone's flat-sheet regeneration subscriptions convert capital sales into recurring revenue streams with municipal utilities. |
| NSF/ANSI 61 Certification Fast-Track | Accelerated drinking water component verification compresses product launch timelines for emerging PFAS-rejection formulations. |
| Prairie Province Municipal Partnership | Canadian federal infrastructure funding flows position early entrants for ceramic ultrafiltration adoption in underpenetrated Saskatchewan and Manitoba plants. |
| Pharmaceutical Process Water Qualification | FDA validation for continuous manufacturing WFI generation opens substitution opportunities against polymeric membranes in Massachusetts biopharma clusters. |
Research Methodology
Initial hypotheses were tested against primary input from municipal utility engineering directors, ceramic membrane fabrication plant managers, pharmaceutical process water validation specialists, and aftermarket refurbishment service operators, and refined through secondary validation against EPA effluent limitation guidelines, NSF/ANSI 61 certification databases, Department of Energy industrial efficiency directive filings, and U.S. customs trade data for alumina and zirconia imports. Bottom-up installed base estimates triangulated with top-down capital expenditure projections across the Great Lakes watershed and Gulf Coast petrochemical corridors.
Demand-supply balance modeling anchored the analytical framework across the projection horizon, with segmentation dimensions spanning membrane pore size architecture, end-use industry vertical, deployment technology configuration, and regional regulatory stringency tier. CAGRs were derived from replacement cycle compression rates and infrastructure funding flow trajectories. Forecast inputs included municipal nutrient credit trading program adoption curves and pharmaceutical continuous manufacturing penetration assumptions.
Stress conditions across alumina feedstock price volatility, EPA PFAS rulemaking acceleration, and Canadian federal infrastructure disbursement timing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding membrane replacement cycle elasticity and state-level regulatory adoption patterns. Cross-checking against EPA Clean Watersheds Needs Survey capital improvement benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
APP and SBS Modified Bitumen Membrane Market
Membrane Materials
North America Roofing Membranes Market
Membrane Materials
Bitumen Waterproofing Membrane Market
Membrane Materials
Breathable Films and Membranes Market
Membrane Materials
Global Membrane Technology Market
Membrane Materials
Polyarylsulfone (PAS) Market
Membrane Materials
Global Transfer Membrane Market
Membrane Materials
Thermoplastic Polyolefin Membranes Market
Membrane Materials
US Commercial Restoration Waterproofing Membranes Market
Membrane Materials
Global Membrane Structures Market
Membrane Materials
Global Medical Membranes Market
Membrane Materials
Europe Gas Barrier Membrane Market
Membrane Materials
Polyvinyl Chloride Membranes Market
Membrane Materials
Global Membrane Filters Market
Membrane Materials
Membranes Market
Membrane Materials
Global Ceramic Membrane Market