
 Nanofiltration Membrane Market | 2026-2036
Nanofiltration Membrane Market Size, Share, and Industry Trends Forecast 2026-2036
Nanofiltration Membrane Market Intelligence
Asset-light membrane leasing and performance-based water service contracts is reconfiguring competitive entry barriers for smaller utilities and industrial operators. DuPont Water Solutions leverages its integrated polymer science platform to sustain captive supply of proprietary thin-film chemistries. Hydranautics anchors its position through deep specialization in high-rejection seawater and brackish water nanofiltration configurations. NX Filtration differentiates via its direct nanofiltration platform that eliminates pre-treatment stages in select wastewater streams.
Nanofiltration membranes are pressure-driven separation barriers with pore structures typically between reverse osmosis and ultrafiltration, commonly manufactured as thin-film composites with polyamide active layers on polysulfone support substrates achieving molecular weight cut-offs of 200-1000 Daltons. These membranes selectively reject multivalent ions, organic micropollutants, and specific solutes while permitting monovalent salt passage, serving primary roles in water softening, color removal, and targeted contaminant separation. Polyamide thin-film composite formulations dominate installed capacity due to superior permeability-selectivity tradeoffs, though polysulfone variants retain structural importance as chemically resistant support substrates. Water purification applications command the largest value share given municipal and industrial potable treatment mandates, while pharmaceutical processing represents a concentrated margin pool where validation requirements and regulatory compliance create pricing premiums.
EPA drinking water regulations and the EU Drinking Water Directive enforce contaminant-specific removal mandates that directly stimulate membrane replacement cycles and technology upgrades. China's Ministry of Ecology and Environment enforces increasingly stringent discharge limits for industrial effluent, compelling chemical manufacturers and food processors toward advanced nanofiltration retrofits. Stakeholders must monitor evolving per- and polyfluoroalkyl substance regulatory thresholds across multiple jurisdictions, as these emerging contaminant limits will determine membrane specification requirements and create new certification barriers for suppliers lacking validated rejection performance data.
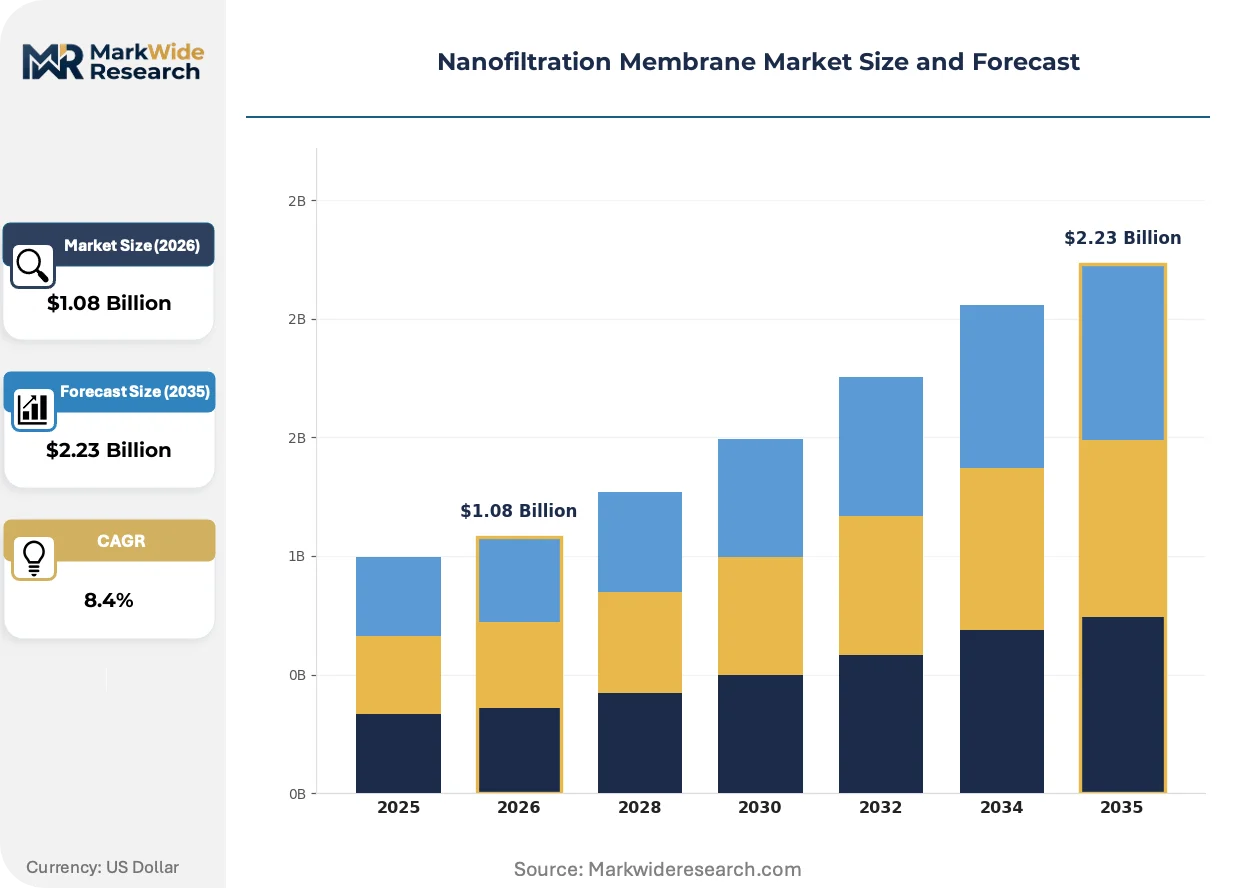
Market Dynamics
Thin-film composite polyamide chemistry is displacing legacy cellulose acetate configurations across high-flux municipal and industrial installations, compressing replacement cycles and reshaping supplier capability requirements.
Growth Catalysts
- EPA Drinking Water Standards:Municipal authorities across the United States are scaling membrane-based treatment capacity to comply with contaminant-specific removal mandates, directly stimulating technology upgrades and replacement demand.
- Yangtze River Economic Belt Retrofits:China's Ministry of Ecology and Environment enforcement of stringent industrial effluent discharge limits is compelling chemical manufacturers and food processors toward advanced nanofiltration installations.
- Per- and Polyfluoroalkyl Substance Thresholds:Emerging regulatory limits for PFAS compounds across multiple jurisdictions are creating new certification barriers that favor suppliers with validated rejection performance data.
Market Restraints
- Specialty Polymer Supply Concentration:Proprietary thin-film chemistries depend on captive supply chains controlled by integrated polymer science platforms, limiting second-source availability for smaller system integrators.
- High-Rejection Configuration Cost Structure:Seawater and brackish water nanofiltration membranes require precision manufacturing of polyamide active layers on polysulfone supports, elevating unit economics relative to ultrafiltration alternatives.
- Monovalent Salt Permeation Limitation:Nanofiltration's selective rejection profile—blocking multivalent ions while permitting monovalent passage—restricts deployment in applications requiring complete desalination, where reverse osmosis dominates.
Strategic Opportunities
- Pharmaceutical Processing Validation:Regulatory compliance requirements and validation protocols in drug manufacturing create concentrated margin pools where membrane suppliers can command pricing premiums through certified performance data.
- Asset-Light Service Contracts:Performance-based water service agreements and membrane leasing models are reconfiguring competitive entry barriers for smaller utilities and industrial operators lacking upfront capital.
- Direct Nanofiltration Platforms:Elimination of pre-treatment stages in select wastewater streams through advanced membrane architecture reduces system footprint and operational complexity for food and beverage processors.
Industry Challenges
- Integration Complexity with Legacy Infrastructure:Retrofitting nanofiltration trains into existing water treatment plants requires custom engineering to match pressure vessel specifications and cleaning-in-place protocols.
- Thin-Film Defect Detection Skill Gap:Quality assurance for polyamide active layers demands specialized microscopy and surface characterization expertise that concentrates in a limited pool of technical specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanofiltration Membrane Market |
| Market Size in 2026 | $1.08 Billion |
| Market Size in 2035 | $2.23 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyamide Thin-Film Composite, Cellulose Acetate, Polysulfone, Polyethersulfone Application: Water Purification, Wastewater Treatment, Food & Beverage Processing, Pharmaceutical Processing End User: Municipal Water Authorities, Chemical Manufacturers, Food Processing Plants, Research Laboratories Technology: Pressure-Driven, Electrochemical, Thermal, Biological |
| Companies Covered | Alfa Laval AB, Hydranautics, DuPont Water Solutions, Pall Corporation, NX Filtration, Toray Industries, Inc., GEA Group AG, Vontron Technology Co., Ltd., Veolia Environnement S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanofiltration Membrane Market Strategic Shifts & Innovations
Membrane architecture is converging with digital monitoring and predictive maintenance platforms, compressing the traditional separation between equipment supply and ongoing water service delivery.
Thin-film composite nanofiltration membranes with tuned molecular weight cut-offs between 200-1000 Daltons are hybridizing with ultrafiltration pre-treatment stages in zero-liquid-discharge systems. Chemical manufacturers along China's industrial corridors are deploying these integrated trains at accelerating pace to meet MEE discharge mandates. This convergence is compressing the addressable market for standalone ultrafiltration suppliers while elevating system-level contract values.
REACH authorization requirements and the EU Drinking Water Directive are tightening contaminant-specific removal mandates for organic micropollutants. Industrial water users in Germany and the Netherlands face accelerated membrane replacement cycles to maintain compliance. Pharmaceutical processors are responding by demanding validated rejection data for endocrine-disrupting compounds, shifting procurement criteria toward certified performance documentation.
Leasing structures and throughput-based pricing are displacing traditional equipment purchase models among municipal utilities with constrained capital budgets. Water authorities in the United Kingdom and Australia are piloting these arrangements to access advanced membrane technology without upfront asset ownership. The shift is most visible in smaller utility districts where EPA compliance deadlines intersect with limited rate-base capacity.
Nanofiltration Membrane Market Segmentation
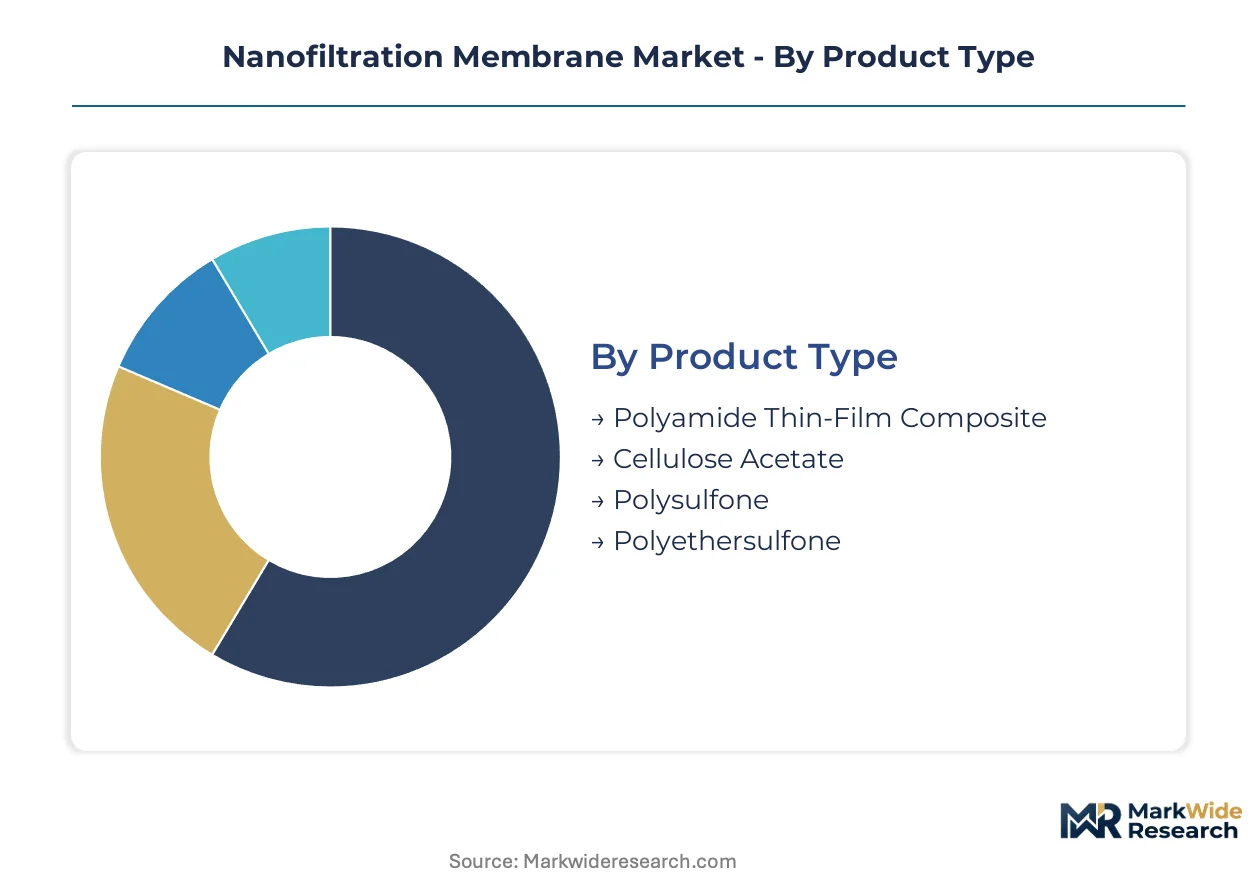
Membrane chemistry and application specificity dictate aftermarket service intensity in nanofiltration systems. Replacement cycles, cleaning protocols, and validation requirements vary sharply across product configurations and end-use environments.
Product Type:
Thin-film composite membranes demand intensive field service support for defect detection and layer integrity monitoring, driving recurring revenue attachment rates.
- Polyamide Thin-Film Composite:Polyamide active layers deposited on polysulfone substrates achieve molecular weight cut-offs of 200-1000 Daltons with superior permeability-selectivity tradeoffs. Municipal water authorities in the United States specify these configurations for EPA-compliant drinking water treatment, though specialized microscopy expertise for quality assurance concentrates among limited technical specialists.
- Cellulose Acetate:Legacy hydrophilic polymer chemistry retains installed base in older industrial facilities with less demanding flux requirements. Chemical manufacturers along China's Yangtze River Economic Belt continue operating cellulose acetate trains where capital replacement budgets remain constrained by MEE enforcement timelines.
- Polysulfone:Chemically resistant support substrates provide structural backbone for composite architectures in aggressive pH environments.
- Polyethersulfone:High-temperature stability variants serve pharmaceutical validation protocols requiring steam-in-place sterilization cycles.
By volume, Polyamide Thin-Film Composite leads. By growth pace, Polyethersulfone is ahead.
Application:
Regulatory compliance mandates reshape procurement criteria across application segments, with validation requirements determining margin structure.
- Water Purification:Municipal and industrial potable treatment mandates command the largest value share. EPA drinking water standards and the EU Drinking Water Directive enforce contaminant-specific removal requirements that directly stimulate membrane replacement cycles.
- Pharmaceutical Processing:Concentrated margin pools emerge where regulatory compliance and validation requirements create pricing premiums. Drug manufacturers demand certified rejection data for endocrine-disrupting compounds.
- Wastewater Treatment:Zero-liquid-discharge systems integrate nanofiltration with ultrafiltration pre-treatment stages.
- Food & Beverage Processing:Direct nanofiltration platforms eliminate pre-treatment stages, reducing system footprint for processors.
Water Purification dominates current installed value. Pharmaceutical Processing offers the steepest expansion trajectory.
End User:
Capital availability and technical staffing depth segment service contract penetration across customer categories.
- Municipal Water Authorities:Constrained rate-base capacity drives adoption of asset-light leasing and throughput-based pricing models. Water authorities in the United Kingdom and Australia pilot performance-based agreements to access advanced membrane technology without upfront asset ownership.
- Chemical Manufacturers:China's Ministry of Ecology and Environment enforcement compels retrofit investments along industrial corridors. MEE discharge mandates accelerate deployment of integrated membrane trains.
- Food Processing Plants:Direct nanofiltration adoption reduces operational complexity for color removal and selective ion separation.
- Research Laboratories:Small-batch validation requirements sustain demand for specialized molecular weight cut-off specifications.
Chemical Manufacturers lead absolute volume growth. Municipal Water Authorities show fastest service contract adoption.
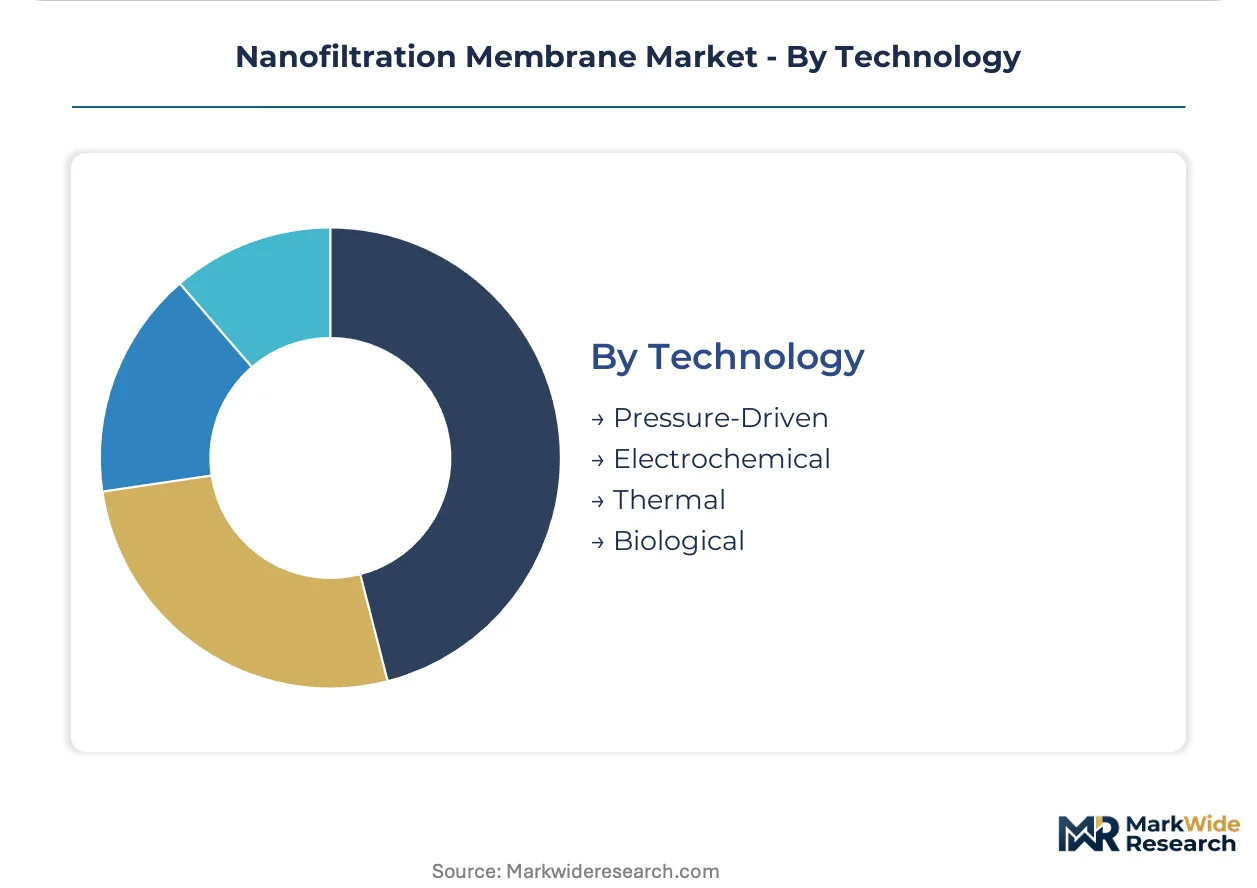
Technology:
Energy intensity and separation mechanism determine operational economics and retrofit feasibility.
- Pressure-Driven:Dominant installed base using transmembrane pressure to achieve selective solute rejection. Polyamide thin-film composites optimize permeability-selectivity tradeoffs for water softening and organic micropollutant removal.
- Electrochemical:Emerging configurations for selective ion separation with reduced energy inputs. Development concentrates on brackish water applications where monovalent salt permeation limitations of nanofiltration create hybrid opportunities.
- Thermal:Niche deployment in high-temperature process streams where membrane stability requirements exceed standard polyamide limits.
- Biological:Experimental integration with enzymatic treatment stages for specific micropollutant degradation.
Pressure-Driven retains volume leadership. Electrochemical approaches gain share fastest in pilot installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA enforcement timelines and China's MEE discharge mandates are accelerating membrane replacement cycles across municipal and industrial water treatment infrastructure. Capital constraints among smaller utilities are reshaping procurement toward service-based contract structures in multiple jurisdictions.
United States
Municipal water authorities in the Great Lakes region and Southwest are scaling membrane capacity to meet EPA drinking water standards for PFAS and organic micropollutants. The agency's contaminant-specific removal mandates compress replacement cycles for legacy cellulose acetate installations. Texas and California water districts concentrate retrofit demand where rate-base limitations intersect with compliance deadlines.
China
Chemical manufacturers and food processors along the Yangtze River Economic Belt are deploying advanced nanofiltration trains under MEE enforcement of stringent industrial effluent limits. The ministry's discharge mandates compel retrofit investments despite capital budget constraints. Shanghai and Jiangsu province clusters anchor accelerating installation activity for zero-liquid-discharge systems.
Germany
Industrial water users face accelerated membrane replacement cycles under REACH authorization requirements and the EU Drinking Water Directive's tightening organic micropollutant thresholds. Pharmaceutical processors in the Rhine-Ruhr and Baden-Württemberg regions demand validated rejection data for endocrine-disrupting compounds. Chemical manufacturers are upgrading treatment infrastructure to maintain export certification compliance.
United Kingdom
Water authorities are piloting asset-light leasing and throughput-based pricing models to access advanced membrane technology without upfront capital ownership. Municipal utilities in England and Wales concentrate service contract adoption where EPA-equivalent compliance pressures intersect with constrained rate bases. The Environment Agency's discharge permits are tightening nutrient removal requirements for industrial effluent.
Australia
Municipal utilities in New South Wales and Victoria are testing performance-based water service agreements to bridge capital availability gaps for membrane upgrades. The country's national water quality regulator is aligning contaminant thresholds with EU and US standards, stimulating technology refresh demand. Mining and resource processing corridors in Queensland and Western Australia are deploying high-rejection configurations for brackish water treatment.
Nanofiltration Membrane Market Key Industry Players
Channel-controlling players compete with product-specialist players across differentiated service intensity tiers. Integrated polymer science platforms hold captive supply advantages for proprietary thin-film chemistries, compressing second-source availability. Three archetypes dominate: integrated material-science conglomerates, membrane-specialist engineering firms, and direct-technology platform innovators. Competitive moves concentrate on backward integration into specialty polymer supply and geographic expansion through local system integrator partnerships.
Among integrated material-science conglomerates, DuPont Water Solutions and Toray Industries occupy positions defined by captive polymer platforms and high-flux formulation expertise. Hydranautics exemplifies the membrane-specialist archetype through deep configuration expertise in seawater and brackish water rejection specifications. NX Filtration represents the direct-technology platform model, eliminating pre-treatment complexity for select wastewater applications. These three anchors illustrate how supplier positioning stratifies across chemistry control, application specialization, and architectural innovation vectors.
| Leading Market Players |
|---|
| Alfa Laval AB |
| Hydranautics |
| DuPont Water Solutions |
| Pall Corporation |
| NX Filtration |
| Toray Industries, Inc. |
| GEA Group AG |
| Vontron Technology Co., Ltd. |
| Veolia Environnement S.A. |
| Others |
Cost & Logistics Intelligence
Shanghai-Ningbo port freight corridors transmit cost volatility from specialty polymer feedstock hubs directly into membrane module pricing, amplifying spreads between certified pharmaceutical-grade configurations and standard municipal installations while compressing margins for non-integrated system integrators.
Pricing Analysis
Certification level (ISO/CE/FDA-grade) creates the primary spread between membrane tiers, with validated pharmaceutical configurations commanding substantial premiums over municipal water treatment specifications. Three-tier pricing structure across premium, standard, and economy levels reflects rejection performance data availability and after-sales service bundling intensity. Cost compression in standard-grade municipal configurations is intensifying because China's MEE enforcement timelines compress procurement cycles for cellulose acetate replacements. Municipal water authorities exhibit highest price sensitivity due to constrained rate-base capacity, while pharmaceutical processors demonstrate lowest sensitivity given validation protocol requirements.
Supply Chain Analysis
Export-control regimes restricting advanced polymer synthesis equipment limit technology transfer into emerging membrane manufacturing jurisdictions, concentrating high-performance thin-film composite production in the United States, Japan, and Germany. Proprietary polyamide active layer chemistries draw from captive supply chains controlled by integrated material-science conglomerates, with polysulfone support substrates sourcing from specialized chemical manufacturers. Single-source vulnerability concentrates in precision coating equipment for molecular weight cut-off calibration. Distribution runs through authorized system integrator networks with regional service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA's contaminant-specific removal mandates for PFAS compounds constitute a regulatory inflection that will displace legacy membrane configurations faster than replacement cycles suggest, compressing the window for technology transition.
For Market Incumbents: Pre-empt certification barriers by accelerating validated rejection data generation for emerging micropollutants before regulatory thresholds finalize. Secure captive supply of specialty aromatic polyamide intermediates through backward integration or long-term offtake agreements to defend against second-source limitations. Expand high-rejection configuration manufacturing footprint in Jiangsu province to capture Yangtze River Economic Belt retrofit demand.
For New Entrants and Emerging Players: Build out direct nanofiltration platform deployments in food and beverage processing, where pre-treatment elimination creates immediate operational savings and procurement decisions concentrate at plant-engineering level. Target Australia's municipal utility pilot programs for performance-based service contracts, where capital constraints intersect with regulatory alignment to EU/US standards. Pursue membrane leasing models with throughput-based pricing to bypass incumbent equipment-sales relationships.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underoptimized water treatment divisions lacking integrated polymer science capabilities. Long-term viability hinges on positioning for pharmaceutical validation protocols and PFAS certification requirements rather than commodity municipal replacement cycles. Watch for MEE enforcement acceleration in China's interior provinces as the signal indicating retrofit demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Polymer Supply | Captive aromatic polyamide supply secures thin-film composite manufacturing continuity against feedstock volatility. |
| Pharmaceutical Validation Data Investment | FDA-grade rejection certification for endocrine-disrupting compounds unlocks concentrated margin pools in drug manufacturing. |
| Direct Nanofiltration Platform Expansion | Elimination of pre-treatment stages reduces system footprint for food processors seeking operational simplification. |
| Performance-Based Service Contract Piloting | Leasing structures bypass capital constraints among UK and Australian municipal utilities facing compliance deadlines. |
| Zero-Liquid-Discharge System Integration | Hybrid ultrafiltration-nanofiltration trains capture MEE-mandated retrofit demand along China's Yangtze industrial corridor. |
Research Approach
A standing panel of membrane plant engineers, municipal water authority procurement directors, pharmaceutical process validation specialists, and specialty polymer R&D leads provided ongoing calibration across primary interview rounds. Secondary validation drew from EPA enforcement documentation, China's MEE discharge permit databases, EU REACH authorization records, and SEC filings of listed membrane manufacturers. Bottom-up installation tracking across regional industrial clusters triangulated against top-down value estimates from equipment supplier revenue disclosures.
Scenario-bracketing framed projections across the analysis window, modeling membrane chemistry type, application specificity, end-user capital availability, and regional regulatory enforcement intensity as core segmentation dimensions. CAGRs derived from replacement cycle compression rates under evolving contaminant thresholds and retrofit investment timelines. Industry-specific inputs included MEE enforcement trajectory assumptions and PFAS regulatory threshold adoption patterns across multiple jurisdictions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated polymer science platforms to lock up specialty feedstock supply would shift outcomes materially. Regulatory acceleration beyond modeled EPA and MEE timelines, or breakthrough electrochemical separation technologies achieving pilot-scale validation, would force updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Global Vapor Permeability Films Market
Membrane Materials
Europe Gas Barrier Membrane Market
Membrane Materials
Geosynthetic Clay Liner Market
Membrane Materials
North America Ceramic Membranes Market
Membrane Materials
Liquid Applied Membranes Market
Membrane Materials
Global Breathable Membranes Market
Membrane Materials
Liquid Roofing Market
Membrane Materials
Polytetrafluoroethylene (PTFE) Filter Membranes Market
Membrane Materials
Global Ion Exchange Membrane Market
Membrane Materials
Vapor Barrier Films Market
Membrane Materials
Membranes Market
Membrane Materials
Polyvinyl Chloride Membranes Market
Membrane Materials
Polyvinyl Butyral (PVB) Films and Sheets Market
Membrane Materials
Global Roofing Membranes Market
Membrane Materials
Membrane Filter Cartridge Market
Membrane Materials
APP and SBS Modified Bitumen Membrane Market