
 Air Compressor Nebulizer Market | 2026-2036
Air Compressor Nebulizer Market Size, Share, and Industry Trends Forecast 2026-2036
Air Compressor Nebulizer Market Insights
Hospital-grade specifications is rotating toward home-compatible platforms without sacrificing particle size consistency. PARI GmbH leverages its German engineering heritage to sustain premium positioning in pediatric compressor systems. Omron Corporation anchors Asian distribution through pharmacy-channel relationships that dominate Japan and Taiwan. Drive DeVilbiss Healthcare competes on cost-engineered tabletop units that occupy the Medicare reimbursement tier in North America.
An air compressor nebulizer converts liquid medication into respirable aerosol via a piston-driven compressor generating airflow through a baffle or jet system, typically producing particle mass median aerodynamic diameters between one and five micrometers for deep lung deposition. The device serves primarily to deliver bronchodilators, corticosteroids, and antibiotics to patients with obstructive or infectious respiratory disease outside intravenous administration. Portable nebulizers are capturing share from tabletop units as lithium-ion power density improves and compressor miniaturization reduces device weight below five hundred grams. Homecare settings now represent the dominant end-user channel, though hospitals retain volume leadership in acute exacerbation protocols where continuous nebulization and wall-oxygen integration remain standard.
FDA 510(k) clearance requirements and ISO 18562 biocompatibility evaluation for breathing gas pathways shape product development timelines and material selection for compressor housings and nebulizer chambers. The EPA's emerging restrictions on persistent organic pollutants in plastics are forcing reassessment of polycarbonate formulations in disposable medication cups. Stakeholders must monitor how CMS durable medical equipment competitive bidding reshapes reimbursement thresholds for home-use compressor systems versus mesh alternatives.
Market Dynamics
Piston-compressor miniaturization and lithium-ion power density improvements are collapsing the boundary between hospital-grade aerosol performance and home-use portability, forcing manufacturers to revalidate particle size consistency across both platforms under tightening FDA and ISO 13485 protocols.
Growth Catalysts
- Medicare DME Reimbursement:CMS coverage for durable medical equipment sustains replacement cycles for home-use compressor systems among aging patient populations in the United States.
- ISO 18562 Biocompatibility Framework:Standardized breathing gas pathway evaluation accelerates regulatory clearance timelines for compressor housings and disposable medication cups.
- Homecare Channel Expansion:Patients with chronic obstructive pulmonary disease and asthma are migrating respiratory therapy from acute care facilities to residential settings.
Market Restraints
- Polycarbonate Reformulation Costs:EPA restrictions on persistent organic pollutants in plastics force reassessment of disposable medication cup materials.
- Compressor Assembly Validation Burden:FDA 510(k) clearance requirements extend product development timelines for piston-driven systems.
- Mesh Nebulizer Substitution:Piezoelectric membrane devices capture share in portable applications where silent operation outweighs particle size precision.
Strategic Opportunities
- CMS Competitive Bidding Reshaping:Reimbursement threshold adjustments for home-use compressor systems versus mesh alternatives create procurement channel openings.
- Pediatric Aerosol Delivery:Mask design and flow rate optimization for children under five remains underpenetrated relative to adult-focused platforms.
- Telehealth Integration:Connected compressor systems with usage monitoring and adherence tracking align with remote patient management reimbursement codes.
Industry Challenges
- ISO 13485 Quality System Maintenance:Small and mid-tier manufacturers face resource strain in sustaining validated manufacturing processes for piston-compressor assemblies.
- Particle Size Consistency Across Power Modes:Battery-operated portable units must replicate tabletop performance across voltage fluctuations and compressor wear cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Compressor Nebulizer Market |
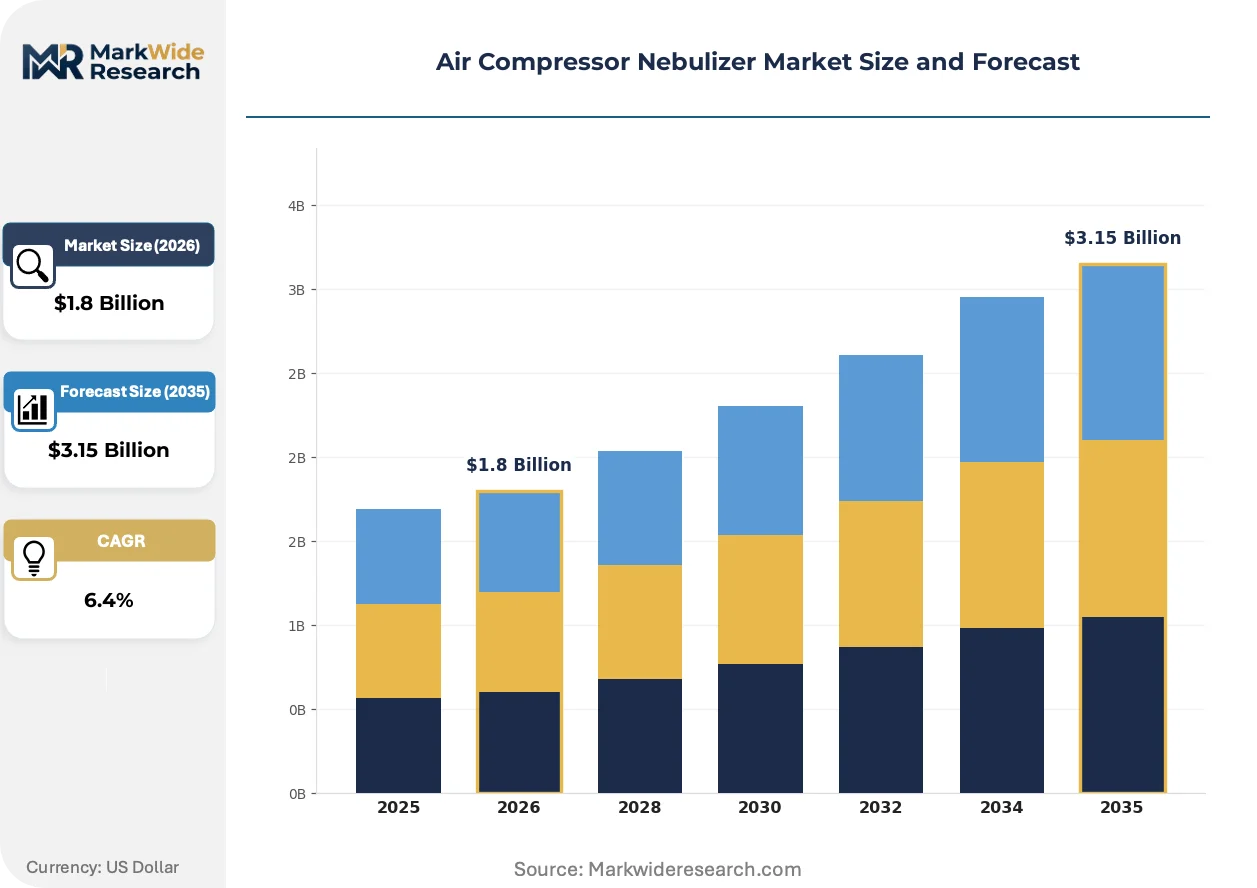
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Nebulizers, Tabletop Nebulizers, Electric Nebulizers, Battery-Operated Nebulizers End User: Hospitals, Homecare Settings, Clinics, Long-Term Care Facilities Distribution Channel: Online Retail, Pharmacy, Medical Supply Stores, Wholesalers Application: Asthma Management, COPD Treatment, Respiratory Infections, Cystic Fibrosis |
| Companies Covered | Omron Corporation, PARI GmbH, Philips Respironics, Drive DeVilbiss Healthcare, Medline Industries Inc., GF Health Products, Inc., Briggs Healthcare, Invacare Corporation, Rossmax International Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Compressor Nebulizer Market Trends and Innovations
Compressor nebulizer engineering is bifurcating between clinical-precision tabletop systems and consumer-portable devices, with particle size distribution validation becoming the common technical battleground across both trajectories.
Mesh nebulization technology is decomposing the traditional compressor market by delivering comparable particle mass median aerodynamic diameters through piezoelectric vibration rather than piston-driven airflow. Pediatric and geriatric homecare patients are adopting these silent, battery-operated units for nighttime and travel use. The structural consequence is compressing R&D investment into compressor miniaturization while elevating biocompatibility and connectivity as the remaining differentiation vectors.
EPA emerging restrictions on persistent organic pollutants in plastics are forcing polycarbonate reformulation in disposable medication cups across United States distribution channels. Manufacturers must revalidate material biocompatibility under ISO 18562 breathing gas pathway standards while maintaining cost structures compatible with Medicare reimbursement tiers. Compressor housing and chamber suppliers with early polymer substitution capabilities are securing preferred supplier status with branded device manufacturers.
Pharmacy-channel relationships now dominate compressor nebulizer distribution in Japan and Taiwan, displacing traditional durable medical equipment suppliers. Omron Corporation and regional pharmacy chains have built exclusive placement agreements that bundle device purchase with medication refill programs. This channel consolidation is most visible in East Asian markets where national health insurance reimbursement flows through retail pharmacy networks rather than home medical equipment dealers.
Air Compressor Nebulizer Market Segmentation
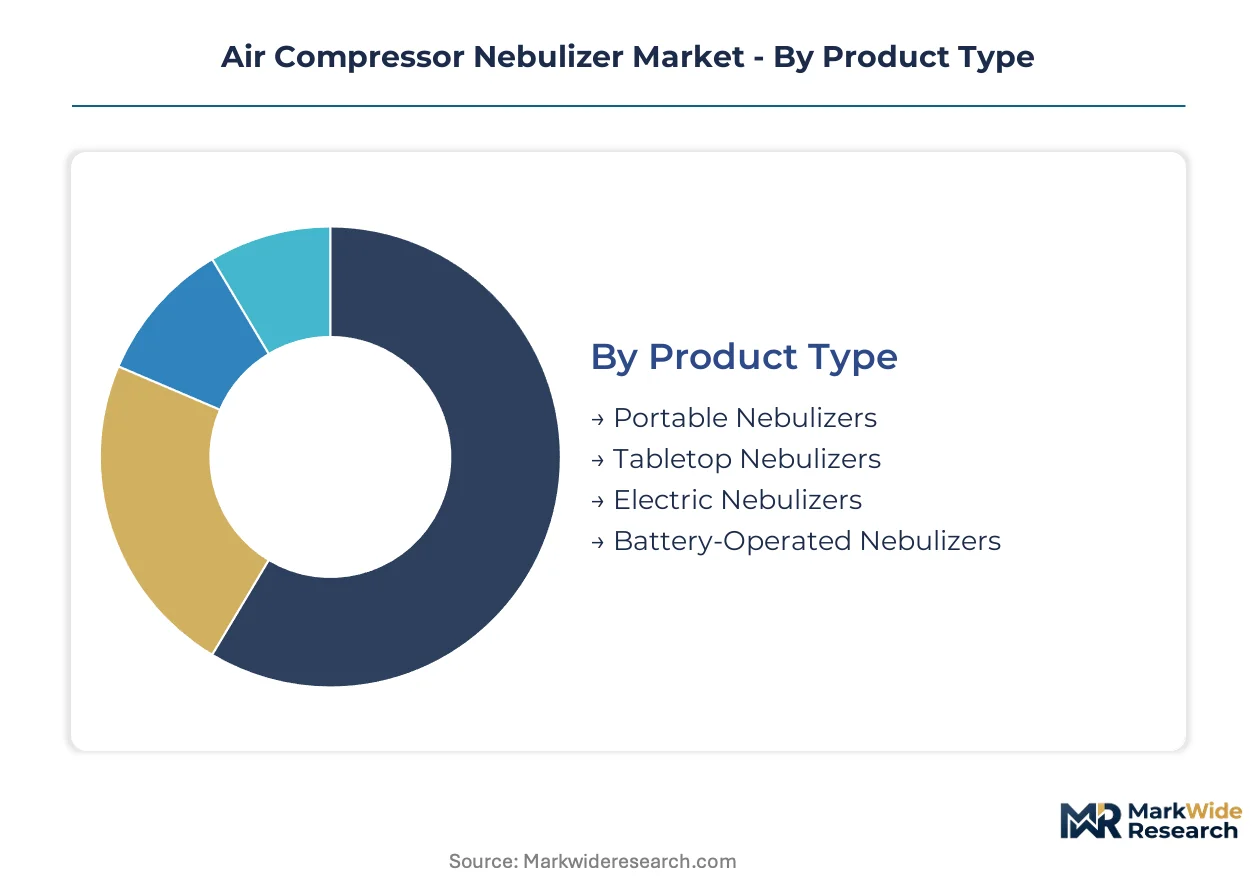
Segmentation in the air compressor nebulizer market reveals how device specifications, care settings, and procurement channels create distinct margin architectures. Manufacturers must align product development with reimbursement pathways and patient mobility requirements to capture value.
Product Type:
Margin pools concentrate in portable systems where lithium-ion miniaturization commands premium pricing over legacy tabletop platforms.
- Portable Nebulizers:Piston-compressor assemblies weighing under five hundred grams deliver particle mass median aerodynamic diameters of one to five micrometers through battery or USB power. Demand concentrates in the United States among Medicare-enrolled COPD patients seeking alternatives to hospital-based therapy, with CMS durable medical equipment reimbursement sustaining replacement cycles.
- Tabletop Nebulizers:AC-powered piston compressors with continuous nebulization capability and wall-oxygen integration serve acute exacerbation protocols. Homecare settings in Japan absorb volume through pharmacy-channel bundled programs with medication refill incentives.
- Electric Nebulizers:Mains-dependent compressor systems without battery backup occupy the cost-engineered tier for price-sensitive institutional procurement.
- Battery-Operated Nebulizers:Lithium-ion powered units with disposable alkaline fallback target travel and emergency preparedness segments.
The dominant share belongs to tabletop nebulizers, while portable nebulizers are expanding most quickly.
End User:
Volume distribution reflects the migration of respiratory therapy from acute facilities to residential environments.
- Hospitals:Wall-oxygen integrated compressor systems with continuous nebulization capability serve ICU and emergency department protocols for acute bronchospasm and respiratory failure.
- Homecare Settings:Patients with chronic obstructive pulmonary disease and asthma operate compressor or mesh nebulizers for daily bronchodilator and corticosteroid administration, with Medicare reimbursement sustaining device replacement cycles in the United States.
- Clinics:Outpatient respiratory therapy centers utilize multi-patient compressor systems with disposable medication cups for supervised treatment sessions.
- Long-Term Care Facilities:Skilled nursing facilities deploy cost-engineered tabletop units for geriatric populations with high nebulization frequency requirements.
Hospitals retain volume leadership in acute applications, though homecare settings are gaining share fastest.
Distribution Channel:
Channel economics diverge between reimbursement-driven institutional procurement and direct-to-consumer retail flows.
- Online Retail:Direct-to-patient platforms capture uninsured and cash-pay segments with price-transparent compressor comparisons and subscription medication cup replenishment.
- Pharmacy:Exclusive placement agreements in Japan and Taiwan bundle device purchase with prescription refill programs, displacing traditional durable medical equipment suppliers.
- Medical Supply Stores:Medicare-enrolled home medical equipment dealers handle prior authorization and competitive bidding compliance for compressor nebulizer distribution in the United States.
- Wholesalers:Institutional purchasing organizations aggregate hospital and long-term care facility volume for manufacturer-direct contracting.
Pharmacy channels dominate in East Asian markets, while online retail is climbing the fastest in North American direct-to-consumer segments.
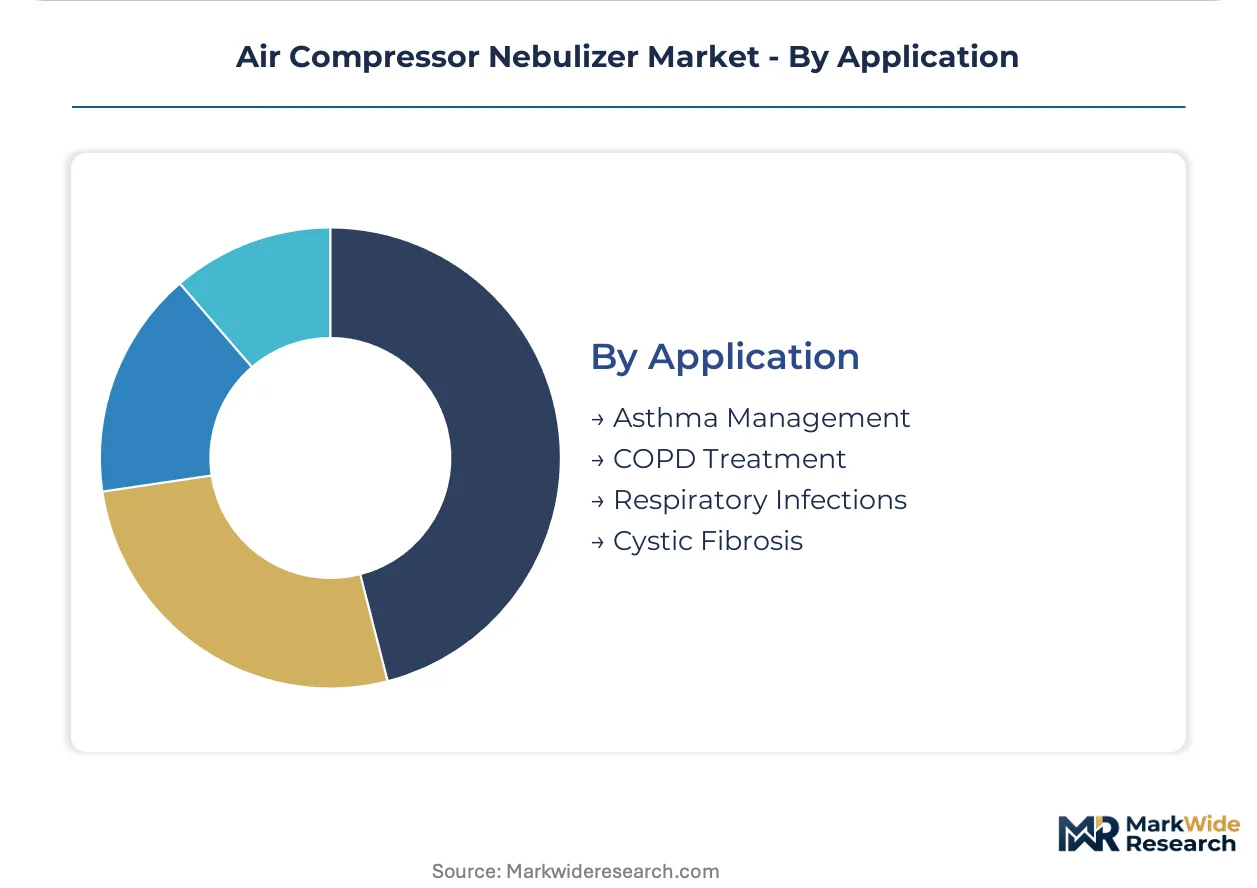
Application:
Therapeutic indication shapes device specification requirements and replacement frequency.
- Asthma Management:Pediatric and adult patients utilize compressor nebulizers for acute bronchodilator delivery during exacerbations, with mask design optimization for children under five remaining underpenetrated.
- COPD Treatment:Chronic corticosteroid and bronchodilator nebulization drives the highest device utilization rates and shortest replacement cycles among Medicare populations in the United States.
- Respiratory Infections:Antibiotic nebulization for hospital-acquired and community-acquired pneumonia requires sterilizable or disposable medication pathways under ISO 18562 biocompatibility standards.
- Cystic Fibrosis:High-frequency antibiotic and mucolytic nebulization demands hospital-grade particle size consistency in home-use portable formats.
COPD treatment commands the dominant share by volume, while cystic fibrosis applications show the steepest expansion trajectory in precision aerosol delivery requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Piston-compressor assembly manufacturing clusters in Germany and Japan, with FDA-regulated distribution networks concentrating device flow through Medicare reimbursement channels in the United States. Regulatory divergence between ISO 18562 biocompatibility frameworks and EPA polymer restrictions is fragmenting material sourcing strategies across major demand centers.
United States
Aging demographics and Medicare durable medical equipment reimbursement sustain replacement cycles for home-use compressor systems. FDA 510(k) clearance requirements and CMS competitive bidding protocols shape procurement thresholds for piston-driven nebulizers versus mesh alternatives. Minneapolis and Chicago host distribution hubs serving Medicare-enrolled home medical equipment dealers.
Germany
Precision engineering capabilities in pediatric compressor systems anchor premium positioning for export-oriented manufacturers. EU MDR compliance and ISO 13485 quality system requirements govern validation protocols for piston-compressor assemblies. Stuttgart and Munich concentrate R&D facilities for particle size distribution optimization.
Japan
Pharmacy-channel relationships dominate distribution, with national health insurance reimbursement flowing through retail pharmacy networks rather than home medical equipment dealers. METI industrial standards and PMDA device registration requirements structure market entry for compressor nebulizer imports. Tokyo and Osaka anchor exclusive placement agreements bundling device purchase with medication refill programs.
China
Domestic manufacturing scale for compressor housings and disposable medication cups supplies cost-engineered tiers for export markets. NMPA medical device registration and GB standards compliance shape product development timelines for lithium-ion portable units. Shenzhen and Shanghai concentrate assembly operations for battery-operated nebulizer platforms.
India
CDSCO medical device rules and BIS certification requirements are tightening import pathways for foreign-manufactured compressor systems. Price-sensitive institutional procurement drives demand for AC-powered tabletop units in outpatient respiratory therapy centers. Mumbai and Bangalore host distribution networks serving clinic and long-term care facility channels.
Air Compressor Nebulizer Market Competitive Landscape
Concentration sits with diversified medical device conglomerates and specialized respiratory equipment manufacturers, with tiered positioning across premium engineering and cost-engineered segments. The vendor base splits between German-engineered precision platforms, Asian pharmacy-channel specialists, and North American Medicare-reimbursement tier suppliers. Strategic archetypes include premium pediatric specialists, pharmacy-channel integrators, and cost-optimized tabletop manufacturers. Competitive moves center on lithium-ion miniaturization R&D and polymer substitution capabilities for disposable medication cups.
Among diversified medical device conglomerates, Omron Corporation anchors pharmacy-channel positioning in East Asian markets, while PARI GmbH exemplifies German-engineered premium tier specialization. Drive DeVilbiss Healthcare occupies the Medicare reimbursement tier in North America, representing cost-engineered tabletop manufacturing.
| Leading Market Players |
|---|
| Omron Corporation |
| PARI GmbH |
| Philips Respironics |
| Drive DeVilbiss Healthcare |
| Medline Industries Inc. |
| GF Health Products, Inc. |
| Briggs Healthcare |
| Invacare Corporation |
| Rossmax International Ltd. |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day lead times for piston-compressor assemblies from German and Japanese manufacturing clusters concentrate pricing power with validated suppliers, while Medicare reimbursement ceilings in the United States compress margin recovery for downstream device assemblers.
Pricing Analysis
CMS durable medical equipment competitive bidding dictates the pricing tier structure across home-use compressor systems, stratifying reimbursement thresholds that separate hospital-grade tabletop units from portable battery-operated alternatives. Price differentiation hinges on ISO 13485 certification status and FDA 510(k) clearance tier, with premium pediatric systems commanding brand premiums over cost-engineered Medicare-tier alternatives. Cost compression in the economy segment intensifies as Chinese manufacturers scale lithium-ion portable production, while hospital procurement committees exhibit lowest price sensitivity due to bundled wall-oxygen integration requirements.
Supply Chain Analysis
Inventory buffers for polycarbonate medication cups have compressed to thirty-day cycles as EPA restrictions on persistent organic pollutants force rapid polymer reformulation. Piston-compressor assembly manufacturing concentrates in Germany, Japan, and China, with precision-engineered components drawing from Stuttgart and Munich R&D clusters while cost-engineered tiers source from Shenzhen assembly operations. Single-source vulnerability persists in medical-grade lithium-ion cells, which rest on South Korean and Japanese cathode material supply. Distribution runs through pharmacy-channel exclusives in East Asia and Medicare-enrolled home medical equipment dealers in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as homecare migration splinters demand across pediatric precision, geriatric portability, and connected adherence monitoring niches that incumbent portfolios poorly cover.
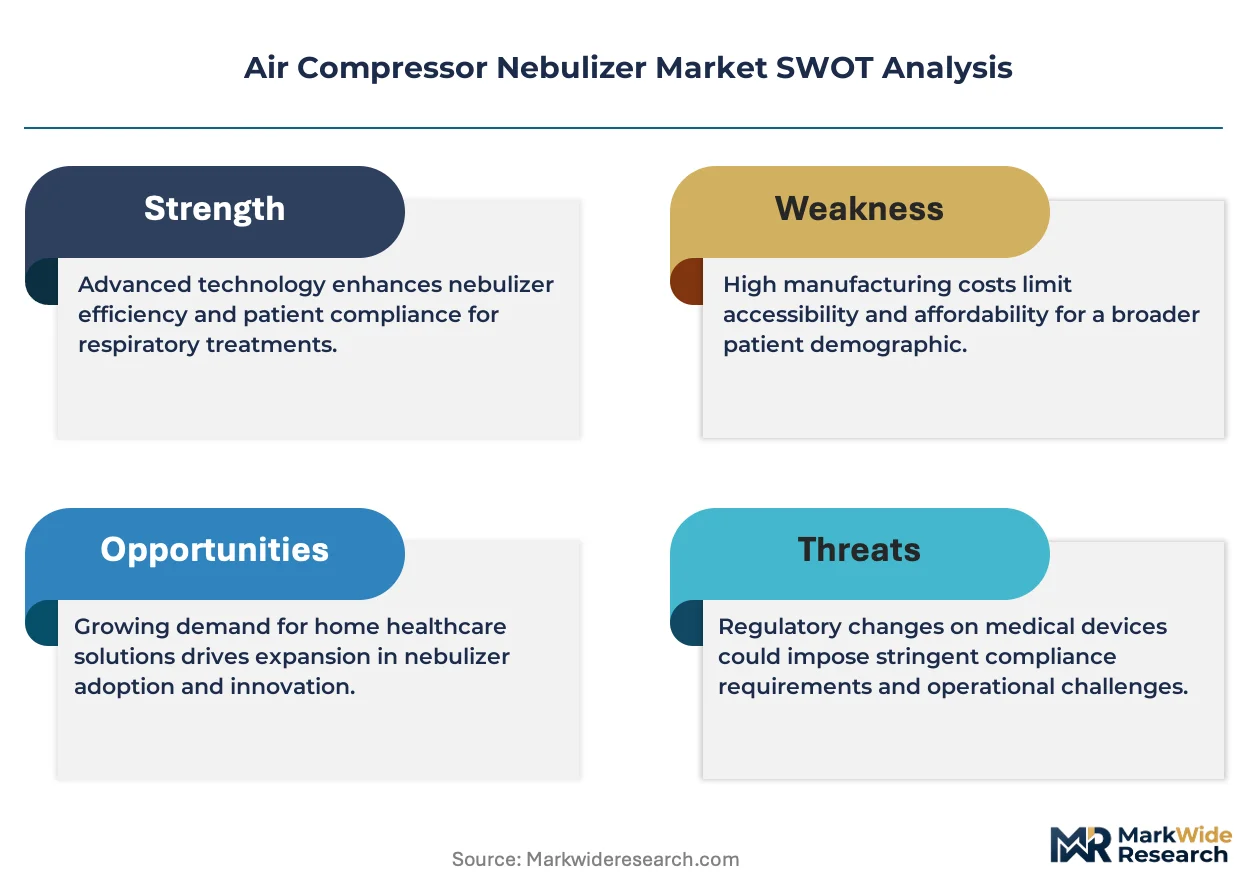
For Market Incumbents: Fortify validated manufacturing positions by deepening backward integration into compressor housing polymer production ahead of EPA reformulation deadlines, while securing exclusive pharmacy-channel placement in Japan and Taiwan against mesh nebulizer substitution threats. Prioritize ISO 18562 biocompatibility certification investment to sustain hospital procurement access as regulatory validation burdens intensify.
For New Entrants and Emerging Players: Differentiate on telehealth-connected compressor systems with usage monitoring capabilities, targeting the underpenetrated pediatric mask optimization segment for children under five where PARI GmbH's premium positioning leaves mid-tier openings. Pursue direct-to-consumer online retail go-to-market in North American cash-pay segments outside Medicare competitive bidding jurisdictions.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across lithium-ion portable nebulizer sub-segments as compressor miniaturization R&D and polymer substitution capabilities become table stakes. Long-term viability favors targets with early EPA-compliant material validation and established CMS reimbursement coding relationships. Monitor CMS competitive bidding threshold adjustments as the critical inflection signal for home-use compressor versus mesh technology substitution rates.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 18562 Biocompatibility Certification | FDA 510(k) clearance acceleration reduces time-to-revenue for compressor housings and medication cups. |
| Pharmacy-Channel Exclusive Placement | Omron-style bundling with medication refill programs displaces traditional durable medical equipment distribution in East Asia. |
| Telehealth Integration Development | Connected adherence monitoring aligns with remote patient management reimbursement codes expanding under CMS. |
| Polymer Substitution Capabilities | Early EPA-compliant polycarbonate alternatives secure preferred supplier status with branded device manufacturers. |
| Pediatric Mask Design Optimization | Flow rate and fit engineering for children under five addresses underpenetrated segment relative to adult-focused platforms. |
Research Methodology
A spread of perspectives from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and pharmacy-channel distribution heads converged on the working assumptions governing particle size validation protocols and reimbursement pathway evolution. Primary field engagement with these stakeholders combined with secondary validation against FDA 510(k) filings, CMS Medicare DME competitive bidding databases, ISO 13485 registration records, and hospital procurement contract repositories. Bottom-up unit economics across compressor assembly tiers triangulated with top-down reimbursement flow analysis.
Segmentation dimensions modeled encompass product type hierarchy, end-user care setting, distribution channel structure, and therapeutic application intensity across the projection horizon. CAGRs derived from replacement cycle analysis tied to Medicare enrollment demographics and COPD prevalence trajectories, with lithium-ion battery cost curves and EPA polymer restriction timelines as nebulizer-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained CMS reimbursement stability and ISO 18562 framework continuity; material deviation in competitive bidding thresholds or biocompatibility standards would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Syringe Pumps Market
Medical Devices
Corneal Cross Linking Devices Market
Medical Devices
Arthroscopic Shaver Market
Medical Devices
Medical Bionic Implants and Exoskeletons Market
Medical Devices
Foot Ulcer Sensors Market
Medical Devices
Vein Illumination Devices Market
Medical Devices
US Nurse Call Systems Market
Medical Devices
Pulmonology Lasers Market
Medical Devices
Condylar Plate Fixation System Market
Medical Devices
Automated Compounding Systems Market
Medical Devices
Electrocautery Devices Market
Medical Devices
Organ Care Market
Medical Devices
Global Hydrocephalus Shunts Market
Medical Devices
Veterinary Injectable Devices Market
Medical Devices
Lactation Massager Market
Medical Devices
Global Smart Biopsy Devices Market