
 Biaxially Oriented Polypropylene Market | 2026-2036
Biaxially Oriented Polypropylene Market Size, Share, and Industry Trends Forecast 2026-2036
Biaxially Oriented Polypropylene Market Analysis
The capital-intensity gap between integrated resin producers and standalone converters is collapsing as feedstock volatility erodes thin-margin operations. Taghleef Industries leverages captive polypropylene supply to sustain margin stability across European operations. Jindal Poly Films anchors its position through backward integration into resin production at its Indian manufacturing complexes. Cosmo Films Limited differentiates via specialized coating technologies for high-barrier food packaging applications.
Biaxially oriented polypropylene consists of polypropylene resin extruded and stretched in both machine and transverse directions to achieve tensile strength exceeding 150 MPa, dimensional stability, and optical clarity for demanding packaging environments. Films command the dominant product position due to their ubiquity in snack, confectionery, and tobacco wrapping where moisture barrier and printability converge. The 10-20 micron thickness band leads volume shipments for general-purpose flexible packaging, while sub-10 micron grades are gaining traction in label applications where material reduction meets sustainability targets. Food and beverage end users generate the largest demand block, though healthcare sterilizable wraps represent a higher-margin growth pocket.
FDA food contact regulations and EU REACH compliance frameworks govern resin additives and migration limits, directly influencing formulation choices and regional sourcing strategies for export-oriented producers. China's GB standards and SAMR labeling requirements add a separate compliance layer for Asia-Pacific market access. Stakeholders must monitor evolving extended producer responsibility schemes and chemical recycling infrastructure buildout to assess which production configurations retain cost advantage under tightening circular economy rules.
Market Dynamics
Feedstock volatility is compressing margins for standalone converters while integrated resin producers capture structural cost advantages through captive polypropylene supply chains. This margin asymmetry is accelerating consolidation across European and Asian production bases.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Tightening recyclability mandates across member states are forcing food processors toward mono-material BOPP films that simplify mechanical recycling streams and reduce compliance costs.
- Ready-to-eat meal packaging:Food processors in India's western industrial corridor are accelerating BOPP film adoption for flexible packaging that extends shelf life without refrigeration infrastructure.
- High-barrier coating technologies:Specialized metallization and ceramic coating processes are opening premium segments in pharmaceutical blister packs and retort pouches where oxygen transmission rates below 0.5 cc/m²/day command price premiums.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracker output fluctuations and PDH unit economics expose standalone converters to margin erosion when resin prices spike without corresponding film price pass-through mechanisms.
- Supply concentration in Middle Eastern resin:Integrated petrochemical complexes in Saudi Arabia and UAE control roughly half of export-oriented polypropylene supply, creating single-source vulnerability for European and Asian converters.
- Technical thickness floor:Sub-8 micron BOPP films exhibit pinhole defects and tear propagation risks that limit substitution opportunities in high-speed form-fill-seal lines running at over 600 packages per minute.
Strategic Opportunities
- Healthcare sterilizable wraps:Hospital sterilization departments are converting from woven textiles to BOPP-based SMS laminates that withstand gamma irradiation and steam autoclave cycles at lower per-use cost.
- Chemical recycling infrastructure:EU Green Deal funding for pyrolysis and depolymerization facilities creates circular feedstock pathways that qualify BOPP for extended producer responsibility bonus credits in France and Germany.
- Direct-to-brand digital print:Narrow-web UV inkjet systems are enabling converters to bypass traditional flexographic plate costs for short-run label orders from craft beverage and specialty cosmetic brands.
Industry Challenges
- Barrier coating chemist scarcity:Formulation expertise for vapor-deposited aluminum oxide and silicon oxide layers concentrates among a handful of European and Japanese technical specialists, constraining capacity expansion timelines.
- Multi-jurisdictional compliance synchronization:Simultaneous FDA food contact notification, EU REACH additive registration, and China GB standard testing extends product launch cycles by 14-18 months for export-oriented film grades.
- Legacy extrusion line retrofit costs:Tenter frame modifications for simultaneous biaxial stretching of bio-based polypropylene copolymers require capital outlays that strain mid-tier converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biaxially Oriented Polypropylene Market |
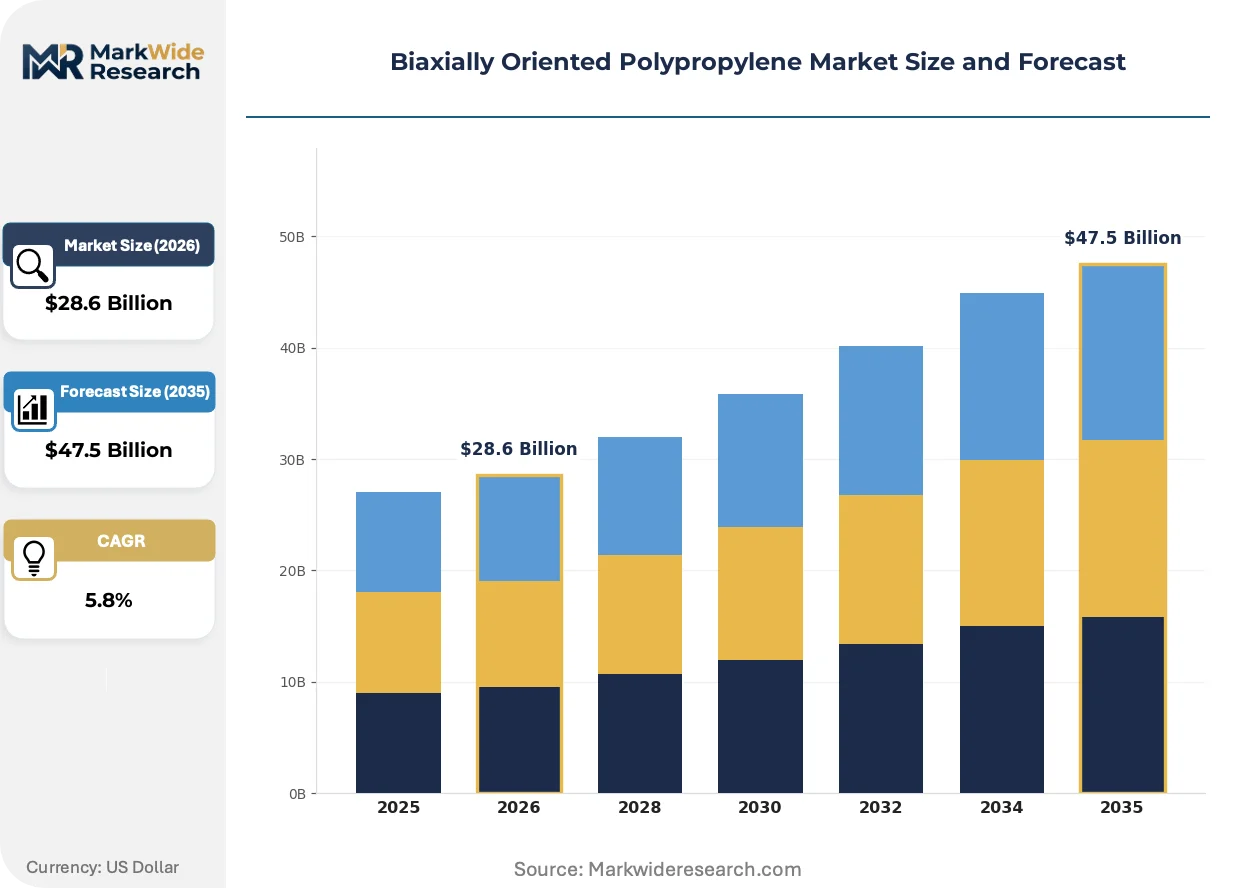
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Films, Sheets, Bags, Containers Application: Packing, Labels, Tapes, Printing End User: Food & Beverage, Consumer Goods, Electronics, Healthcare Thickness: Less than 10 Micron, 10-20 Micron, 20-30 Micron, More than 30 Micron |
| Companies Covered | Taghleef Industries, Cosmo Films Limited, Jindal Poly Films, CCL Industries, Inteplast Group, Sibur Holdings, Uflex Ltd., SRF Limited, Nan Ya Plastics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biaxially Oriented Polypropylene Market Emerging Trajectories
Digital printing and sustainable packaging mandates are converging to reconfigure how BOPP films are specified, decorated, and recovered across food, healthcare, and industrial end uses.
Machine-direction oriented (MDO) films with inline coating stations is supplanting traditional tenter-frame BOPP for label applications where 30-40% gauge reduction meets sustainability targets without sacrificing print fidelity. Narrow-web converters serving craft beverage brands are adopting this technology to eliminate adhesive lamination steps and reduce material usage. The structural consequence is compression in conventional cast PP label demand as MDO-BOPP captures mid-volume orders previously served by thicker constructions.
EU REACH restrictions on per- and polyfluoroalkyl substances (PFAS) are compelling reformulation of heat-seal layers and slip agents in food-contact BOPP films. The industrial consequence is accelerated qualification of silicone-based and long-chain fatty acid amide alternatives that maintain coefficient of friction below 0.3 for high-speed packaging lines. Snack and confectionery segments in Germany and Benelux markets are most affected, with major brand owners now requiring PFAS-free certifications from film suppliers by 2025.
Brand-owner sustainability scorecards are driving specification of certified circular and bio-based content in flexible packaging procurement. Food processors are replacing virgin BOPP with mass-balance certified grades traced through ISCC PLUS chain-of-custody systems. This shift is most visible in European ready-meal and fresh produce segments where retailers require packaging recyclability ratings displayed on shelf labels.
Biaxially Oriented Polypropylene Market Segmentation
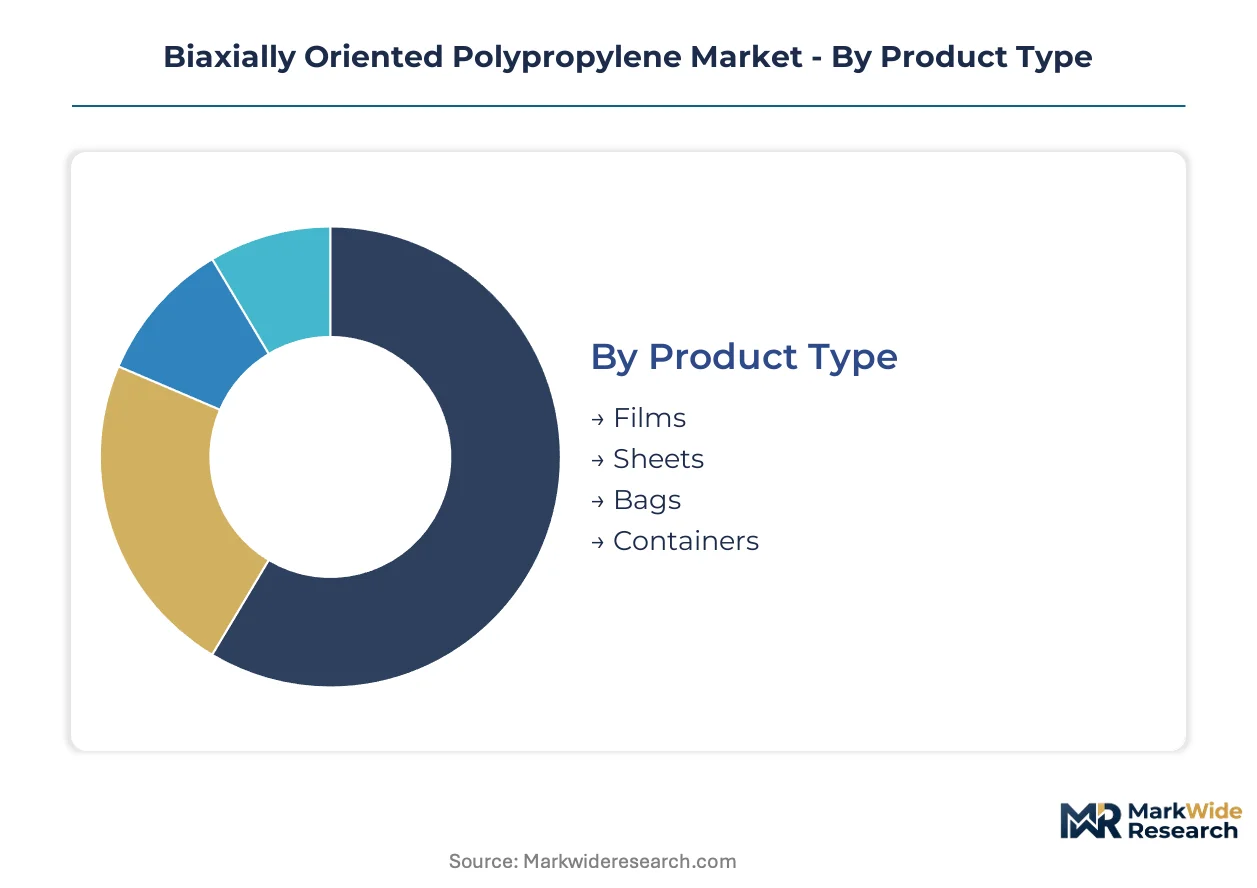
Segmentation in BOPP markets reveals how material specifications align with downstream channel requirements. Distinct thickness bands and product formats flow through specialized converter networks before reaching end-use applications.
Product Type:
Films dominate converter procurement channels serving flexible packaging, while sheets and containers access rigid packaging and thermoforming specialists through separate distribution pathways.
- Films:Extruded and biaxially stretched constructions achieve tensile strength exceeding 150 MPa with optical clarity for high-speed wrapping lines. Demand concentrates in India's western industrial corridor from Mumbai to Ahmedabad, where food processors serving ready-to-eat meal segments require moisture barrier performance without cold chain infrastructure.
- Sheets:Thicker gauge biaxially oriented constructions serve thermoforming applications requiring dimensional stability. Adoption is accelerating in healthcare sterilizable trays where gamma irradiation compatibility replaces PVC alternatives in European hospital supply chains.
- Bags:Pre-formed flexible packaging solutions integrate heat-seal layers for direct filling operations.
- Containers:Rigid thermoformed applications leverage BOPP clarity for retail display visibility in consumer goods segments.
By volume, Films leads. By growth pace, Sheets is ahead.
Application:
Cost tier differentiation separates commodity wrapping from premium barrier specifications, with coating technologies commanding price premiums in pharmaceutical and retort applications.
- Packing:General-purpose flexible packaging for snack, confectionery, and tobacco products where moisture barrier and printability converge. EU Packaging and Packaging Waste Regulation recyclability mandates are forcing food processors toward mono-material BOPP films that simplify mechanical recycling streams.
- Labels:Machine-direction oriented films with inline coating stations enable 30-40% gauge reduction for craft beverage brands. Narrow-web UV inkjet systems are displacing traditional flexographic plate costs for short-run orders.
- Tapes:Adhesive-coated constructions serve industrial and consumer sealing applications.
- Printing:Specialized surface treatments enhance ink adhesion for high-resolution graphics.
By volume, Packing leads. By margin expansion, Labels is climbing the fastest.
End User:
Customer type segmentation tracks how procurement sophistication varies across regulated versus unregulated end-use environments.
- Food & Beverage:Largest demand block generating volume procurement through integrated converters. India's food processors in the western industrial corridor are accelerating BOPP adoption for shelf-life extension without refrigeration.
- Healthcare:Sterilizable wraps and pharmaceutical blister packs command premium pricing. Hospital sterilization departments are converting from woven textiles to BOPP-based SMS laminates that withstand gamma irradiation and steam autoclave cycles.
- Consumer Goods:Retail packaging applications with sustainability scorecard requirements.
- Electronics:Static-dissipative films for component protection in cleanroom environments.
By volume, Food & Beverage leads. By value per kilogram, Healthcare shows the steepest expansion trajectory.
Thickness:
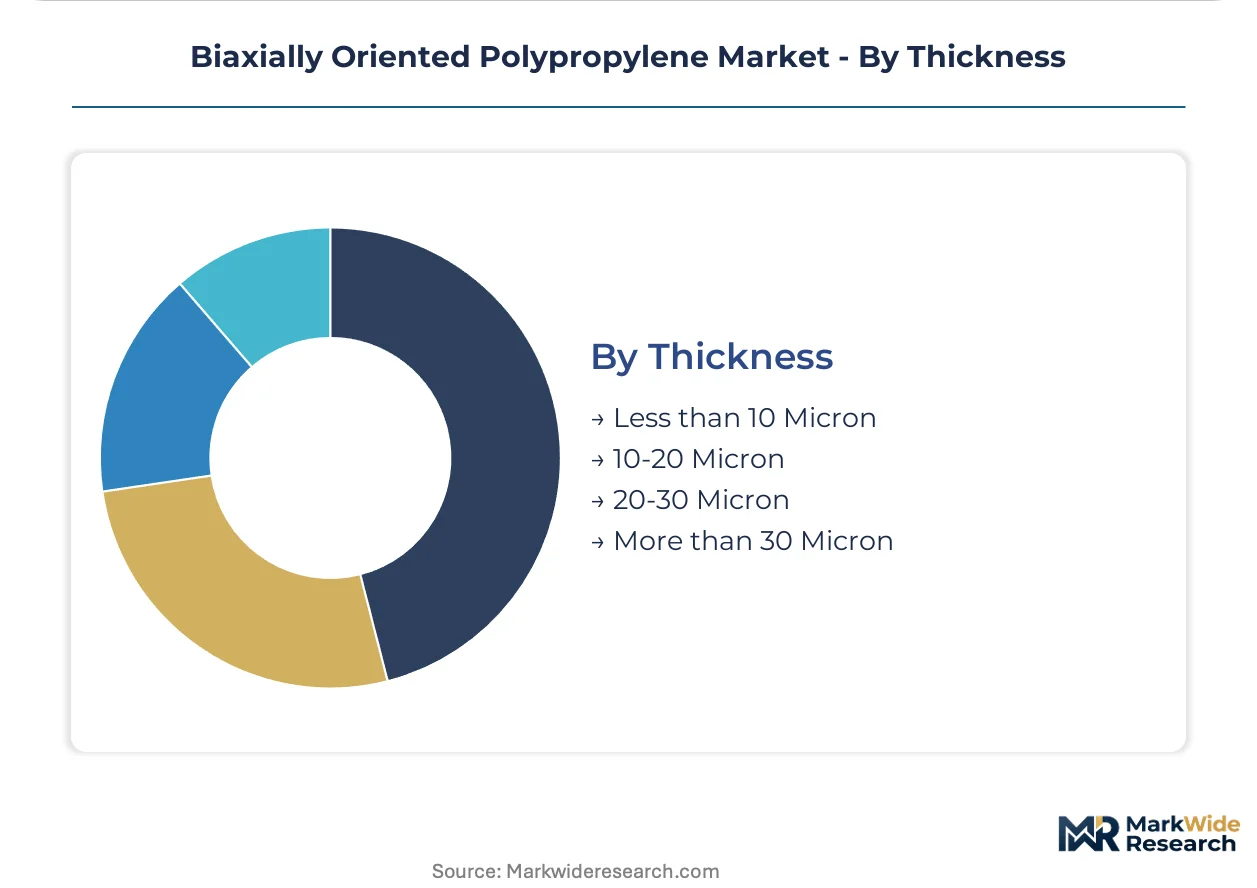
Supply concentration in general-purpose gauges creates margin pressure, while sub-10 micron and high-barrier specifications retain pricing power through technical differentiation.
- 10-20 Micron:General-purpose flexible packaging band leading volume shipments for snack and confectionery wrapping. Taghleef Industries and Jindal Poly Films anchor production capacity serving European and Asian converter networks.
- Less than 10 Micron:Sub-8 micron grades are gaining traction in label applications where material reduction meets sustainability targets, though pinhole defects limit substitution in high-speed form-fill-seal lines exceeding 600 packages per minute.
- 20-30 Micron:Medium gauge for applications requiring enhanced stiffness and barrier performance.
- More than 30 Micron:Heavy-duty specifications for industrial and specialty packaging.
By volume, 10-20 Micron leads. By sustainability-driven substitution, Less than 10 Micron is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converters in Saudi Arabia and the UAE command structural feedstock cost advantages that European standalone operators cannot match, compressing margin recovery windows during propylene price spikes. This pricing-power asymmetry is reshaping procurement patterns across packaging supply chains.
Germany
Snack and confectionery processors in the Rhine-Ruhr industrial zone are accelerating PFAS-free film qualification timelines ahead of EU REACH enforcement deadlines. The country's federal environment agency is tightening migration limit testing protocols for food-contact polypropylene grades. Converter networks in North Rhine-Westphalia are consolidating toll-coating capacity to serve pan-European brand owner sustainability scorecard requirements.
India
Food processors along the Mumbai-Ahmedabad western industrial corridor are expanding BOPP film procurement for ready-to-eat meal packaging that extends shelf life without cold chain infrastructure. FSSAI labeling mandates are driving specification of mono-material constructions that simplify mechanical recycling compliance. Converter clusters in Gujarat are backward-integrating into resin production to hedge against Middle Eastern feedstock price volatility.
China
Flexible packaging exporters in the Yangtze River Delta are reconfiguring formulation strategies to satisfy simultaneous FDA food contact notification and EU REACH additive registration requirements. SAMR labeling standards and GB testing protocols add compliance layers that extend product launch cycles. Converter operations in Jiangsu province are qualifying mass-balance certified grades through ISCC PLUS chain-of-custody systems for European retail channel access.
United States
Healthcare sterilization departments in the Great Lakes manufacturing belt are converting from woven textiles to BOPP-based SMS laminates that withstand gamma irradiation cycles. FDA device sterilization validation requirements are governing film specification for hospital supply chain contracts. Converter networks in Ohio and Michigan are expanding metallization capacity to serve pharmaceutical blister pack demand.
Saudi Arabia
Integrated petrochemical complexes in the Eastern Province control export-oriented polypropylene supply positions that dictate pricing benchmarks for Asian and European converters. The country's industrial development authority is channeling downstream investment toward specialty film coating capabilities. Production clusters near Jubail are expanding high-barrier metallization lines to capture premium segments in pharmaceutical and retort packaging applications.
Biaxially Oriented Polypropylene Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure where integrated resin producers sustain margin stability through captive feedstock supply while specialized converters compete on coating innovation and application engineering. The vendor base separates into three strategic tiers: petrochemical-integrated film producers with backward control over polypropylene resin, standalone converters with specialized barrier coating capabilities, and regional scale operators serving commodity flexible packaging segments. Dominant competitive moves include backward integration into resin production and strategic partnerships with brand owners for sustainability-certified film supply.
Among integrated producers, Taghleef Industries exemplifies the petrochemical-integrated archetype with captive resin supply supporting European operations. Jindal Poly Films occupies a comparable position in Asian markets through in-house polypropylene production at Indian manufacturing complexes. Cosmo Films Limited represents the specialized converter tier, differentiating through technical capabilities in high-barrier coating formulations for demanding food packaging applications. These three companies illustrate how competitive positioning splits between feedstock security and technical specialization vectors.
| Leading Market Players |
|---|
| Taghleef Industries |
| Cosmo Films Limited |
| Jindal Poly Films |
| CCL Industries |
| Inteplast Group |
| Sibur Holdings |
| Uflex Ltd. |
| SRF Limited |
| Nan Ya Plastics Corporation |
| Others |
Supply Flow & Price Mechanics
Capacity utilization rates above 85% at integrated Saudi and UAE petrochemical complexes compress margin recovery windows for European standalone converters during propylene price spikes. This scale asymmetry concentrates pricing power with feedstock-integrated producers while forcing toll-dependent operators toward contract-based offtake structures.
Pricing Analysis
Configured-to-order pricing for high-barrier metallized films commands 35-45% premiums over standard commodity grades. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and barrier performance. Pricing pressure stems from Middle Eastern resin export pricing benchmarks that limit pass-through elasticity for Asian converters. Brand-owner procurement teams exhibit highest price sensitivity in general-purpose snack packaging, while pharmaceutical blister pack specifications show inelastic demand.
Supply Chain Analysis
Strategic stockpiling of polypropylene resin dominates procurement behavior among Indian and Chinese converters hedging against Middle Eastern supply disruptions. Raw material flows draw from Saudi Arabia, UAE, and South Korean petrochemical complexes. Naphtha-cracker output fluctuations and PDH unit economics create single-source vulnerability for European toll-coating operations. Distribution runs through converter networks in Gujarat, Jiangsu, and North Rhine-Westphalia before reaching brand-owner filling lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Packaging and Packaging Waste Regulation recyclability mandates fragment procurement requirements across mono-material specifications, creating specialization niches for coating-capable converters.
For Market Incumbents: Secure captive resin supply through backward integration or long-term offtake agreements with Saudi and UAE producers to defend against margin erosion from propylene volatility. Invest in PFAS-free heat-seal layer qualification ahead of ECHA enforcement timelines. Prioritize metallization capacity expansion in European hospital supply corridors. For New Entrants and Emerging Players: Short-run digital print service gaps in craft beverage label segments offer white-space entry points. Target sub-10 micron MDO-BOPP gauge reduction for sustainability-driven brand owners. Pursue narrow-web UV inkjet partnerships bypassing flexographic plate cost barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized barrier coating specialists with pharmaceutical qualification pipelines. Five-to-ten year viability hinges on chemical recycling infrastructure access for circular feedstock credits. Monitor EU Green Deal pyrolysis facility commissioning as inflection signal for mass-balance certified grade premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Jindal Poly Films demonstrates margin stability through captive polypropylene supply at Indian complexes. |
| High-Barrier Coating Capacity Expansion | Taghleef Industries leverages metallization lines to capture pharmaceutical blister pack price premiums. |
| PFAS-Free Formulation Qualification | Cosmo Films Limited accelerates silicone-based heat-seal layer development for EU REACH compliance. |
| Chemical Recycling Infrastructure Partnership | ISCC PLUS chain-of-custody certification unlocks extended producer responsibility bonus credits in France and Germany. |
| Digital Print Service Capability | Narrow-web UV inkjet adoption eliminates flexographic plate costs for short-run craft beverage label orders. |
Methodological Framework
Desk research of trade flow databases, petrochemical capacity registries, and regulatory filing repositories preceded structured interviews with BOPP plant managers, food processor procurement leads, pharmaceutical packaging engineers, and toll-coating technical directors. Primary fieldwork across converter clusters in Gujarat, Jiangsu, and North Rhine-Westphalia validated secondary estimates. Bottom-up volume modeling triangulated against top-down resin consumption benchmarks.
Variance decomposition across thickness bands, coating technologies, and end-use applications shaped the analytical framework over the projection horizon. CAGRs derived from segment-level demand elasticity modeling and capacity expansion timelines. Forecast inputs incorporated EU Green Deal funding disbursement trajectories and FDA sterilization validation cycle durations.
Underlying assumptions cover sustained propylene feedstock availability, stable EU REACH enforcement timelines, and functional chemical recycling infrastructure buildout, with deviation risk concentrated in Middle Eastern export policy shifts and PFAS substitution formulation delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyalkylene Glycols (Pags) Market
Polymers & Resins
Europe Polypropylene Market
Polymers & Resins
Polyvinyl Butyral (PVB) Resins Market
Polymers & Resins
India Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Non-Ionic Polyacrylamide Market
Polymers & Resins
Synthetic Latex Polymers Market
Polymers & Resins
Flexible Polymer Foam Market
Polymers & Resins
Global Synthetic Polymers Market
Polymers & Resins
Polyethylene Terephthalate (PET) Foam Market
Polymers & Resins
Polyethylene Furanoate Market
Polymers & Resins
Vinyl Acetate Monomer (VAM) Market
Polymers & Resins
PE Resins Market
Polymers & Resins
GCC Vinyl Flooring Market
Polymers & Resins
Global One Component Polyurethane Foam Market
Polymers & Resins
Middle East Polyethylene Terephthalate (PET) Market
Polymers & Resins
Sustainable Polymers Market