
 South America Thermoplastics Market | 2026-2036
South America Thermoplastics Market Size, Share, and Industry Trends Forecast 2026-2036
South America Thermoplastics Market Analytics
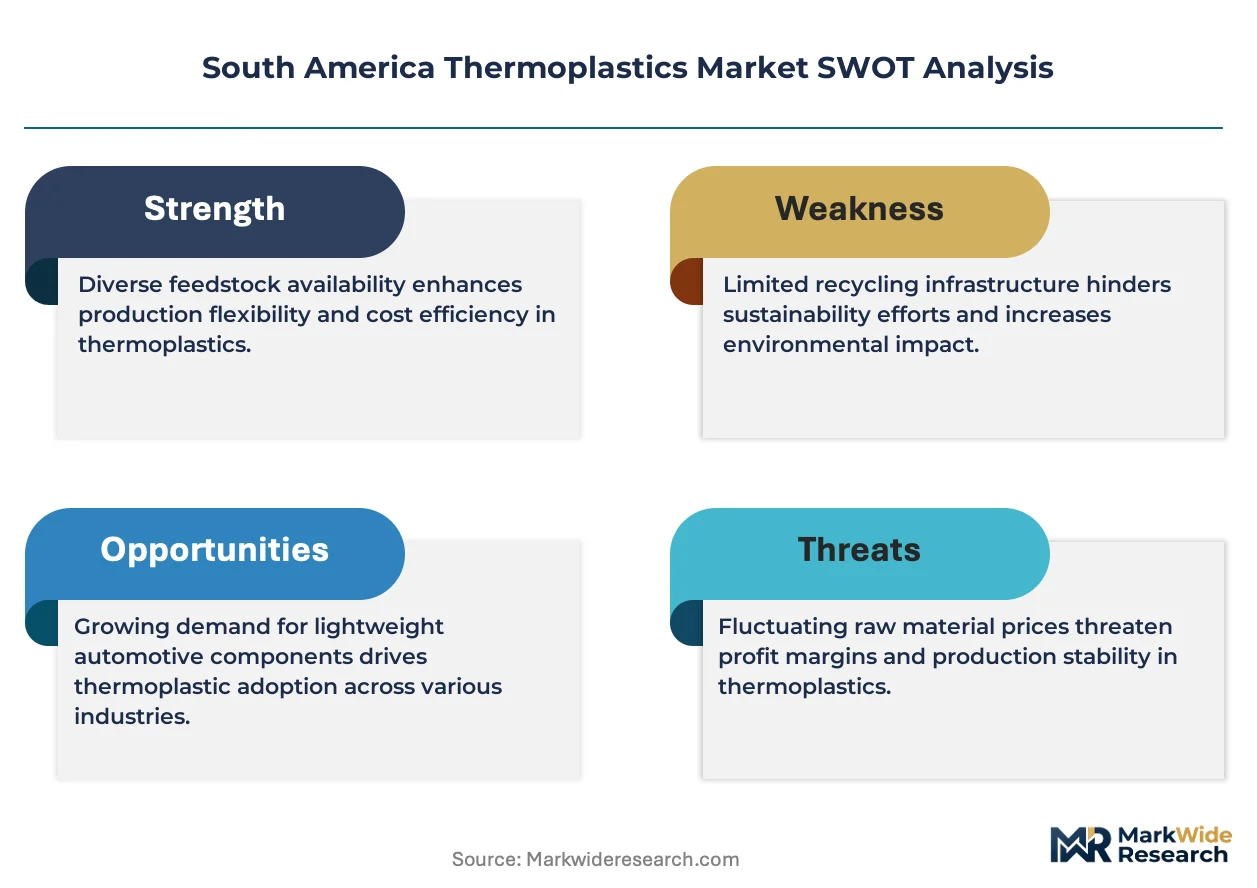
Engineered-grade polymer specifications is reorganizing competitive dynamics across the South America Thermoplastics Market. BASF SE leverages its Ludwigshafen-to-Guarulhos technology transfer pipeline to sustain formulation leadership in glass-filled polyamide compounds. DuPont anchors regional supply of high-performance fluoropolymers through its Brazilian compounding affiliate. SABIC competes on cost-optimized polyethylene grades tailored to Andean converter specifications.
Thermoplastics are polymers that soften upon heating and solidify when cooled, enabling repeated melt-processing via injection molding, extrusion, or thermoforming without significant chemical degradation; their molecular architecture lacks the cross-linked bonds characteristic of thermoset resins, permitting regrind and recycling in closed-loop manufacturing systems. Polyethylene dominates volume flows into flexible packaging films and blow-molded containers across Brazilian retail supply chains. Polypropylene captures expanding share in automotive under-hood components where heat resistance and dimensional stability outrank commodity alternatives. Polystyrene retains entrenched position in disposable foodservice applications despite sustainability-driven substitution pressures.
Brazil's ANVISA governs food-contact polymer compliance through Resolução RDC 326, while Argentina's national chemical regulator enforces migration-limit testing for imported thermoplastic resins. Mercosur's emerging technical regulation harmonization is forcing multinational suppliers to unify certification documentation across São Paulo, Buenos Aires, and Montevideo customs jurisdictions. Stakeholders must monitor pending bio-based content mandates that would redefine feedstock qualification criteria for regional polymer producers.
Market Dynamics
Automotive lightweighting mandates in Brazil are compressing metal-to-polymer substitution timelines, forcing compounders to certify glass-filled polyamide grades under ANVISA's accelerated migration-testing protocols.
Growth Catalysts
- ANVISA Resolução RDC 326:Food-contact compliance requirements for Brazilian packaging converters are pulling high-clarity polypropylene investments toward São Paulo state resin production.
- Automotive under-hood thermal management:Heat-stabilized polypropylene compounds are capturing duct and reservoir applications from glass-reinforced nylons in Curitiba assembly plants.
- Mercosur technical regulation harmonization:Unified certification documentation across São Paulo, Buenos Aires, and Montevideo customs jurisdictions is reducing re-testing costs for imported polymer compounds.
Market Restraints
- Naphtha feedstock volatility:Brazilian petrochemical complexes depend on imported naphtha indexed to Brent crude, compressing margin visibility for polyethylene producers.
- Argentine import licensing:Argentina's national chemical regulator enforces extended migration-limit testing timelines that delay resin release by 8-14 weeks.
- Recycled-content technical limitations:Post-consumer polypropylene exhibits inconsistent melt-flow indices, restricting its use in thin-wall injection molding for food containers.
Strategic Opportunities
- Colombian Andean converter base:Cost-optimized polyethylene grades tailored to Bogotá and Medellín specifications remain underserved by current Brazilian supply allocations.
- Bio-based content mandates:Pending Mercosur feedstock qualification criteria would advantage sugarcane-derived ethanol-to-polyethylene producers with existing Brazilian biorefinery infrastructure.
- Direct-to-converter digital platforms:São Paulo-based distributors are piloting blockchain-tracked resin lot certification to bypass traditional customs broker intermediation.
Industry Challenges
- Compounding technician scarcity:Glass-filled polyamide formulation expertise concentrates among retiring specialists at Guarulhos industrial parks.
- Multi-jurisdiction certification synchronization:REACH-aligned documentation for European-exporting Brazilian compounders must reconcile with ANVISA's distinct migration-limit protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Thermoplastics Market |
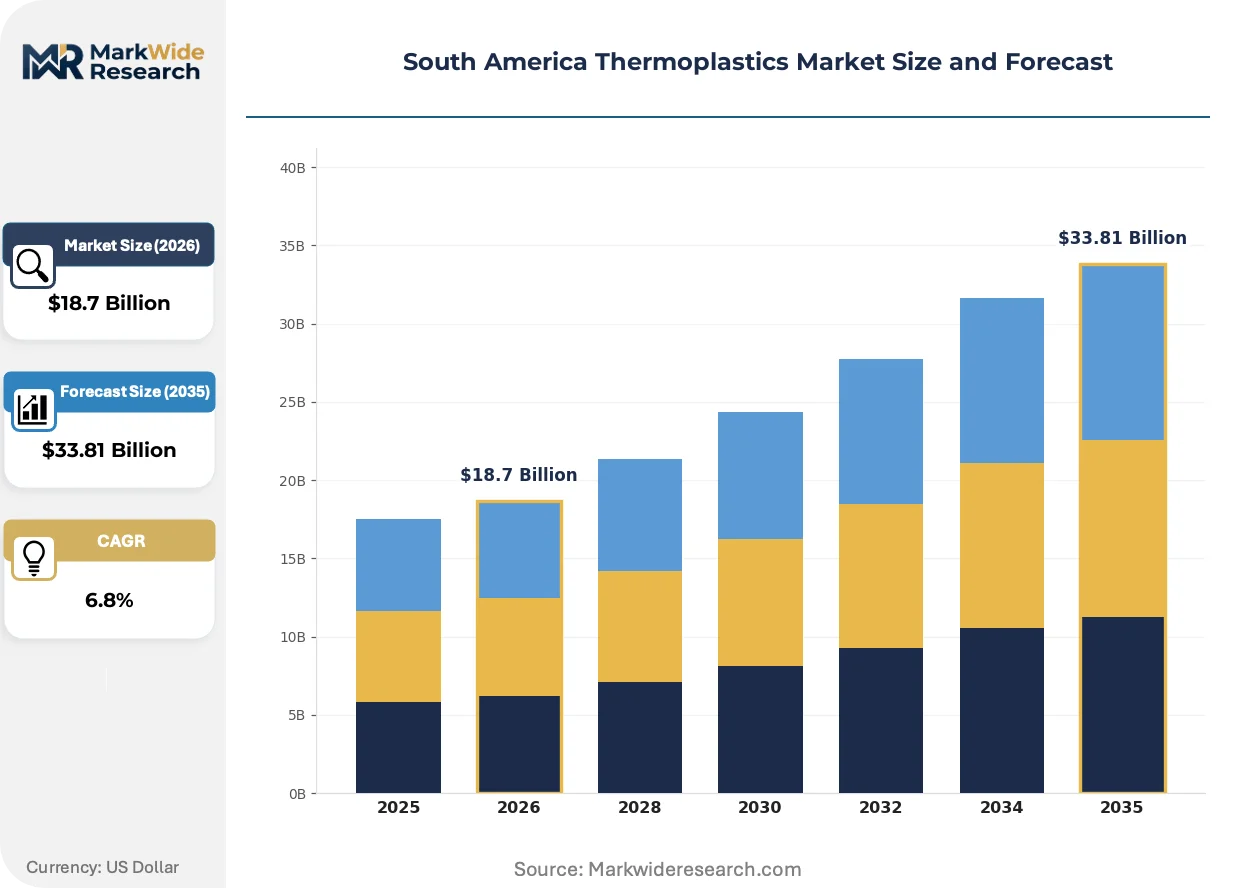
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene Application: Packaging, Automotive Components, Consumer Goods, Electrical Insulation End User: Manufacturers, Retailers, Contractors, Distributors Distribution Channel: Online Sales, Direct Sales, Wholesale, Retail |
| Companies Covered | BASF SE, DuPont, 3M, Arkema, SABIC, DSM, Eastman Chemical Company, Evonik Industries AG, INEOS AG, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Thermoplastics Market Evolving Landscape
Material substitution cascades and regulatory convergence are compressing traditional grade hierarchies across South American thermoplastics value chains. Compounders now prioritize certification velocity over portfolio breadth.
Long-fiber thermoplastic (LFT) polypropylene compounds are supplanting short-glass polyamide in structural automotive brackets. Tier-one suppliers in São Bernardo do Campo are qualifying these grades for front-end modules. The shift is compressing nylon 6/6 consumption volumes in Brazilian vehicle platforms while expanding local LFT compounding capacity.
ANVISA's pending alignment with EU REACH substance restrictions is forcing reformulation of phthalate plasticizers in flexible PVC compounds. Brazilian wire and cable producers face 18-month recertification timelines for existing product lines. The automotive harness segment is accelerating adoption of bio-based plasticizer alternatives to preempt compliance discontinuities.
Consolidated procurement by São Paulo retail chains is disintermediating traditional resin distributors. Large Brazilian converters now negotiate direct volume commitments with petrochemical producers, capturing freight optimization and lot-traceability advantages. This concentration is visible in flexible packaging film supply chains serving the Carrefour and GPA retail networks.
South America Thermoplastics Market Segmentation
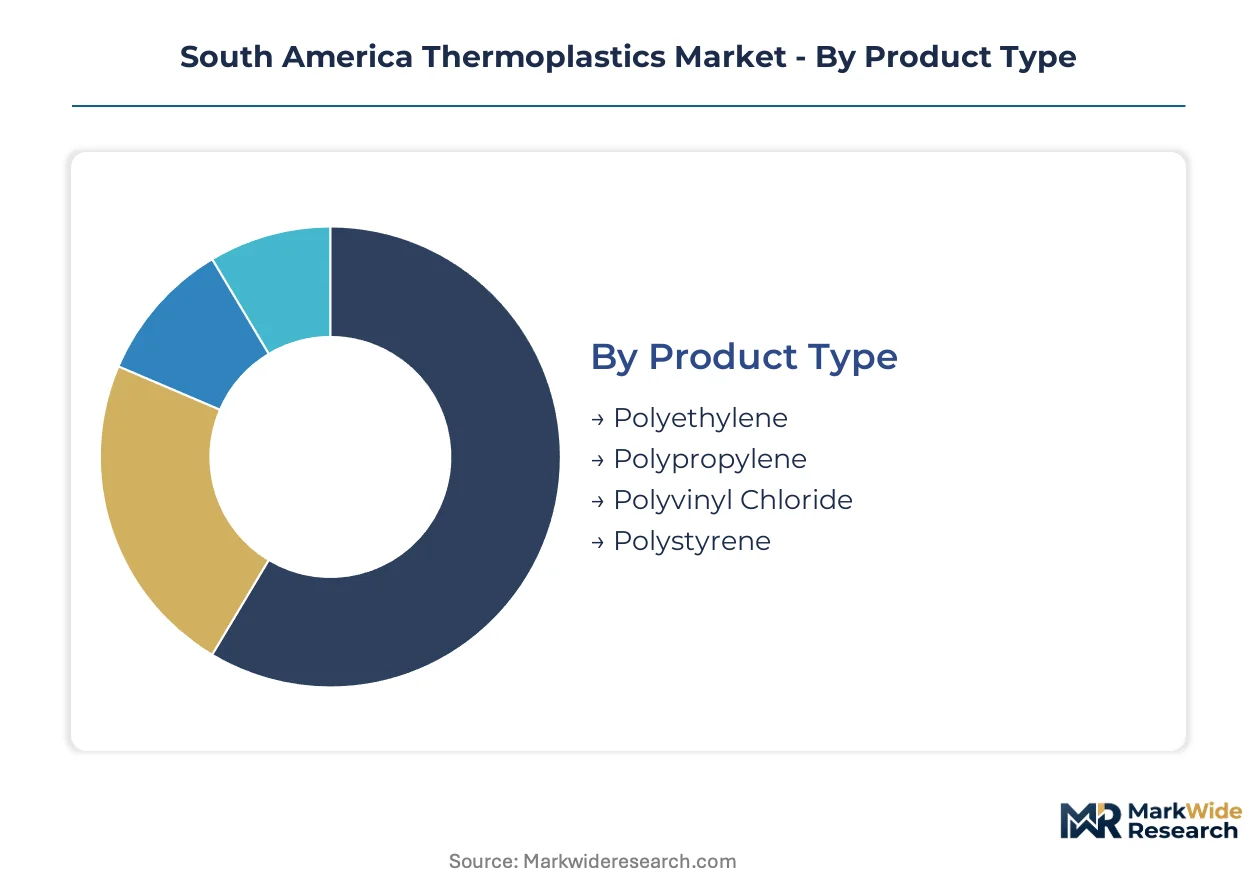
Segmentation in the South America Thermoplastics Market reveals how substitution pressures and regulatory convergence reshape procurement priorities across resin grades and conversion technologies. Distinct performance requirements in Brazilian automotive versus Argentine packaging applications fragment specification standards across the region.
Product Type:
Polyethylene faces the most acute substitution threat from bio-based alternatives and mechanical recycling mandates, while specialty grades in polypropylene defend pricing power through heat-stabilization premiums.
- Polyethylene:Linear low-density and high-density grades dominate flexible film and blow-molded container production. São Paulo retail supply chains concentrate demand for clarity-optimized LLDPE in food packaging, though ANVISA migration-testing protocols compress margin visibility for imported resin lots.
- Polypropylene:Homopolymer and copolymer specifications capture expanding automotive under-hood applications where heat resistance exceeds commodity polyethylene capabilities. Curitiba assembly plants are qualifying glass-filled and long-fiber thermoplastic compounds for structural brackets, displacing traditional nylon 6/6 in front-end modules.
- Polyvinyl Chloride:Flexible and rigid formulations serve wire insulation and construction piping across Brazilian infrastructure projects.
- Polystyrene:General-purpose and high-impact grades retain entrenched positions in disposable foodservice despite sustainability-driven substitution pressures from polypropylene alternatives.
Polyethylene anchors the volume base while polypropylene gains share at the steepest rate.
Application:
Cost-tier stratification separates specification-grade automotive compounds from commodity packaging resins, with certification burden driving margin dispersion across conversion technologies.
- Packaging:Flexible films, rigid containers, and thermoformed trays absorb the largest resin volumes across Brazilian retail networks. High-clarity polypropylene grades are capturing share from polystyrene in chilled-food applications, driven by ANVISA Resolução RDC 326 compliance requirements and Carrefour consolidated procurement specifications.
- Automotive Components:Under-hood thermal management, interior trim, and structural brackets demand engineered compounds with dimensional stability. Heat-stabilized polypropylene and glass-filled polyamide formulations compete for duct and reservoir applications, with long-fiber thermoplastic compounds expanding in São Bernardo do Campo tier-one supplier qualifications.
- Consumer Goods:Durable appliances and housewares utilize impact-modified polypropylene and ABS blends for aesthetic surface finishes.
- Electrical Insulation:Wire and cable sheathing depends on flexible PVC compounds facing REACH-aligned plasticizer reformulation timelines.
Packaging commands the volume base while automotive components expand most quickly.
End User:
Customer-type concentration determines procurement leverage, with large converters bypassing traditional distributor intermediation to capture freight optimization and lot-traceability advantages.
- Manufacturers:Tier-one automotive suppliers and large packaging converters in São Paulo state negotiate direct volume commitments with petrochemical producers. Blockchain-tracked resin lot certification pilots are disintermediating customs broker layers for these accounts.
- Retailers:Consolidated chains including Carrefour and GPA specify direct supply arrangements for private-label flexible packaging films, compressing distributor margins in Brazilian retail supply chains.
- Contractors:Construction and infrastructure project buyers source rigid PVC piping and geomembrane specifications through regional wholesale channels.
- Distributors:Traditional resin traders in Buenos Aires and Montevideo face margin compression as Mercosur harmonization reduces multi-jurisdiction certification arbitrage opportunities.
Manufacturers anchor the volume base while retailers gain procurement leverage fastest.
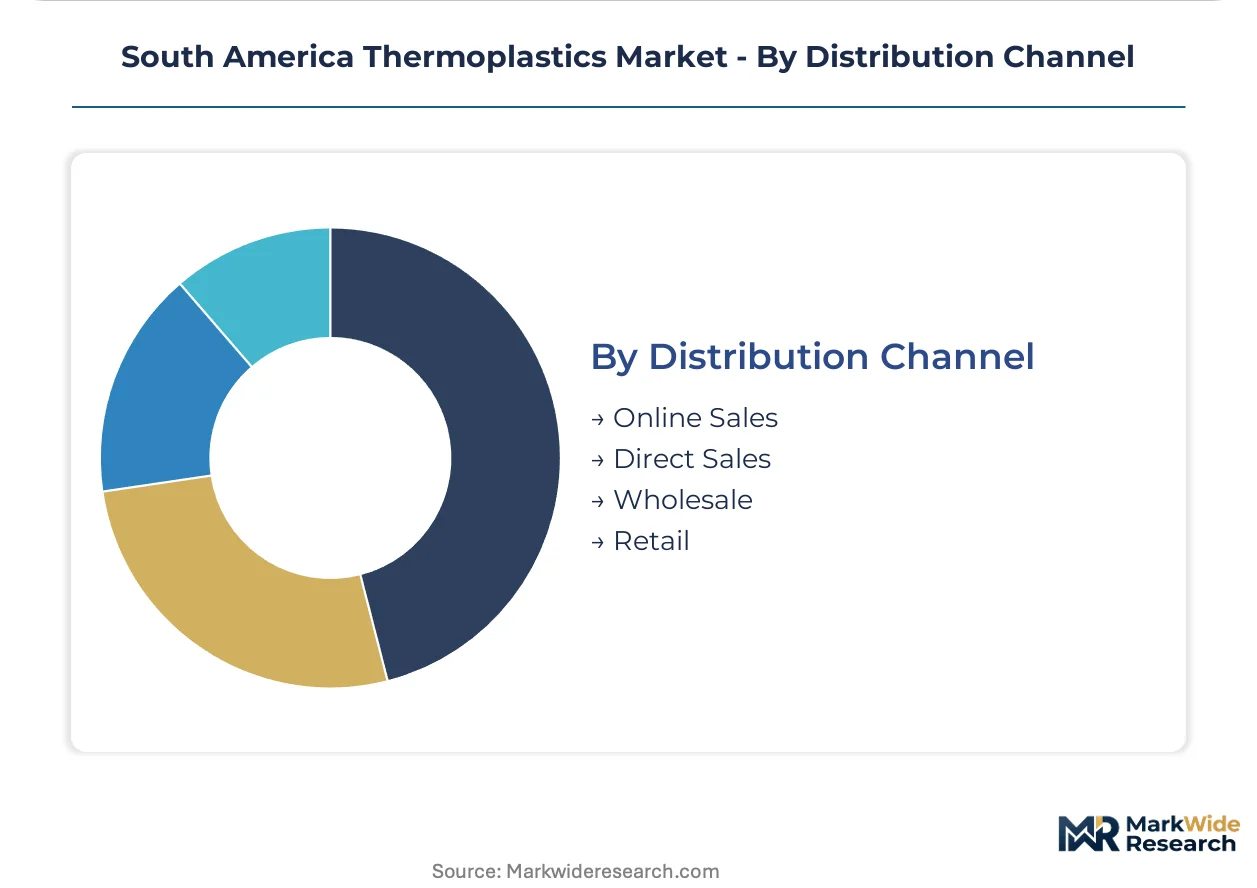
Distribution Channel:
Supply concentration in coastal Brazilian petrochemical complexes shapes channel economics, with digital platforms emerging to bypass traditional logistics intermediation.
- Direct Sales:Petrochemical producers maintain dedicated account teams for large São Paulo converters and automotive tier-ones. These relationships capture freight optimization through dedicated bulk liquid and railcar allocations from Guarulhos industrial park compounding facilities.
- Wholesale:Regional distributors serve mid-size Argentine and Colombian converters with fragmented order patterns. Argentine import licensing delays of 8-14 weeks compress inventory turns for these intermediaries.
- Online Sales:São Paulo-based platforms pilot blockchain-tracked certification to accelerate customs clearance documentation.
- Retail:Limited to small-volume specialty compound sales for maintenance and repair operations.
Direct sales anchors the volume base while online sales climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade imbalances between Brazilian resin production and Andean import dependency define regional thermoplastics flows. Brazilian petrochemical complexes export polyethylene and polypropylene to Argentina, Chile, and Colombia while importing specialty engineered compounds from European suppliers. Currency volatility and divergent regulatory timelines fragment procurement strategies across Mercosur and Andean Community jurisdictions.
Brazil
São Paulo state concentrates flexible packaging film production for Carrefour and GPA retail networks. ANVISA Resolução RDC 326 governs food-contact compliance, forcing high-clarity polypropylene investments toward Guarulhos industrial park compounding facilities. Curitiba automotive assembly plants qualify heat-stabilized polypropylene compounds for under-hood thermal management applications.
Argentina
Buenos Aires packaging converters drive demand for imported polyethylene grades despite extended import licensing timelines. The national chemical regulator enforces migration-limit testing protocols that delay resin release by 8-14 weeks. Mendoza province beverage bottlers source blow-molded container specifications through Brazilian cross-border supply arrangements.
Chile
Santiago-based construction contractors source rigid PVC piping for infrastructure projects amid copper mining investment cycles. The country's national chemical regulator maintains REACH-aligned substance restrictions that accelerate phthalate plasticizer reformulation in wire and cable compounds. Valparaíso port logistics concentrate resin import flows from Asian petrochemical producers.
Colombia
Bogotá and Medellín converters remain underserved by cost-optimized polyethylene grades tailored to Andean specifications. The national standards body enforces technical regulations that diverge from Brazilian ANVISA protocols, fragmenting certification documentation for multinational suppliers. Barranquilla industrial zones pilot direct-to-converter digital procurement platforms.
Uruguay
Montevideo customs jurisdictions participate in Mercosur technical regulation harmonization, reducing re-testing costs for Brazilian resin imports. The country's food-contact polymer compliance framework aligns with ANVISA migration-limit standards, enabling seamless cross-border packaging film supply chains. Punta del Este logistics corridors facilitate resin transshipment to Argentine markets.
South America Thermoplastics Market Competitive Landscape
Listed petrochemical majors compete with private compounders across formulation specialization and certification velocity. Market structure tilts toward consolidated upstream resin production and fragmented downstream compounding, with three strategic archetypes dominating: integrated petrochemical producers, regional compounding affiliates of global chemical groups, and independent specialty compounders. Capacity expansion and backward integration into captive resin supply represent the dominant competitive moves.
Within the integrated petrochemical tier, BASF SE and SABIC exemplify scale-driven positioning through technology transfer pipelines and cost-optimized grade portfolios. DuPont anchors the high-performance specialty segment through its Brazilian compounding affiliate, representing regional supply strategies for engineered fluoropolymers. Among European-origin chemical groups, DSM and Arkema occupy positions in advanced material formulations.
| Leading Market Players |
|---|
| BASF SE |
| DuPont |
| 3M |
| Arkema |
| SABIC |
| DSM |
| Eastman Chemical Company |
| Evonik Industries AG |
| INEOS AG |
| Others |
Value Network & Pricing Analysis
ANVISA Resolução RDC 326 gates both supply qualification and price differentiation across Brazilian thermoplastics procurement, forcing importers to absorb extended migration-testing costs while domestic compounders capture certification premiums. This regulatory barrier simultaneously restricts low-cost resin entry and stratifies pricing across compliant versus non-compliant supply tiers.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels, with certification grade and volume scale serving as primary differentiation drivers. Cost compression in commodity polyethylene intensifies as naphtha feedstock volatility squeezes margin visibility for Brazilian producers. Tier-one automotive suppliers exhibit lowest price sensitivity due to specification lock-in, while mid-size Argentine converters face acute budget constraints from currency depreciation.
Supply Chain Analysis
Brazil and Argentina anchor regional resin production and conversion respectively, with Brazilian petrochemical complexes drawing from imported naphtha indexed to Brent crude. Supply chain risk centers on Argentine import licensing delays that extend resin release timelines. Distribution runs through São Paulo-based direct sales teams for large accounts and regional wholesale channels for fragmented Andean demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South America Thermoplastics Market sits in cyclical recovery phase, with Brazilian automotive production cycles and packaging investment waves driving sequential demand improvement.
For Market Incumbents: Fortify formulation leadership in glass-filled polyamide compounds through captive compounding capacity additions in Guarulhos industrial parks. Deepen backward integration into sugarcane-derived ethanol feedstocks to preempt bio-based content mandates. Defend against long-fiber thermoplastic substitution by accelerating heat-stabilization certification velocity. For New Entrants and Emerging Players: Lead with cost-optimized polyethylene grades tailored to underserved Colombian Andean converter specifications in Bogotá and Medellín. Target direct-to-converter digital procurement platforms to bypass traditional distributor intermediation. Capture share through blockchain-tracked lot certification that accelerates customs clearance documentation. For Investors and Strategic Acquirers: ANVISA's pending REACH alignment reshapes the acquisition landscape toward compounders with pre-validated migration-limit documentation. Long-term viability favors specialists with dual-certification capability across Mercosur and European export markets. Watch bio-based feedstock qualification criteria as the inflection signal for ethanol-to-polyethylene asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Feedstocks | Sugarcane ethanol infrastructure positions Brazilian producers for pending Mercosur bio-content mandates. |
| Long-term Supply Agreement | Direct volume commitments with Carrefour and GPA retail networks compress distributor margins. |
| Joint Venture | European-Brazilian compounding partnerships accelerate REACH-ANVISA dual certification timelines. |
| Capacity Expansion | Long-fiber thermoplastic lines in São Bernardo do Campo capture automotive bracket substitution demand. |
| Green Manufacturing Transition | Phthalate-free plasticizer reformulation preempts ANVISA-EU alignment discontinuities in wire and cable. |
Research Methodology
Cross-validation between primary fieldwork and secondary trade data anchors the qualitative findings across the South America Thermoplastics Market. Plant managers at Brazilian petrochemical complexes, procurement leads at São Paulo packaging converters, distribution channel partners in Buenos Aires, and technical R&D directors at compounding facilities provided operational perspective. Secondary sources included ANVISA regulatory filings, Mercosur customs trade databases, SEC 10-K disclosures from listed chemical groups, and industry association production statistics. Bottom-up resin volume estimates triangulated against top-down macroeconomic consumption models.
Sensitivity analysis across feedstock price scenarios and regulatory timeline assumptions shaped the analytical framework. Segmentation dimensions modeled included product grade tier, end-use industry vertical, regional production hub, and certification complexity band. CAGRs derived from historical trajectory analysis adjusted for structural shift impacts. Key forecast inputs comprised automotive platform content specifications and retail packaging procurement consolidation patterns.
The analysis sits within stated boundaries; outcomes outside sustained naphtha price stability or accelerated Mercosur harmonization would require recalibration. Forecasts reflect documented assumptions regarding Brazilian industrial output and Argentine import regime continuity. Recalibration cycles align with material shifts in ANVISA regulatory pronouncements and automotive OEM platform refresh schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyphthalamide (PPA) Resin Market
Polymers & Resins
United Kingdom Engineering Plastics Market
Polymers & Resins
Canada Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Global Chlorinated Polyethylene Market
Polymers & Resins
Flame Retardant Thermoplastics Market
Polymers & Resins
Polyolefin Foam Market
Polymers & Resins
Germany Polymer Emulsion Market
Polymers & Resins
China Geopolymer Market
Polymers & Resins
Global Styrenic Polymers Market
Polymers & Resins
Thermoplastic Starch (TPS) Market
Polymers & Resins
Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
South America Epoxy Resins Market
Polymers & Resins
Liquid Saturated Polyester Resin Market
Polymers & Resins
Polycarbonate Glazing Market
Polymers & Resins
Polyvinyl Butyral (PVB) Market
Polymers & Resins
C5 Resin Market