
 Releasing Agents Market | 2026-2036
Releasing Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Releasing Agents Market Analytics
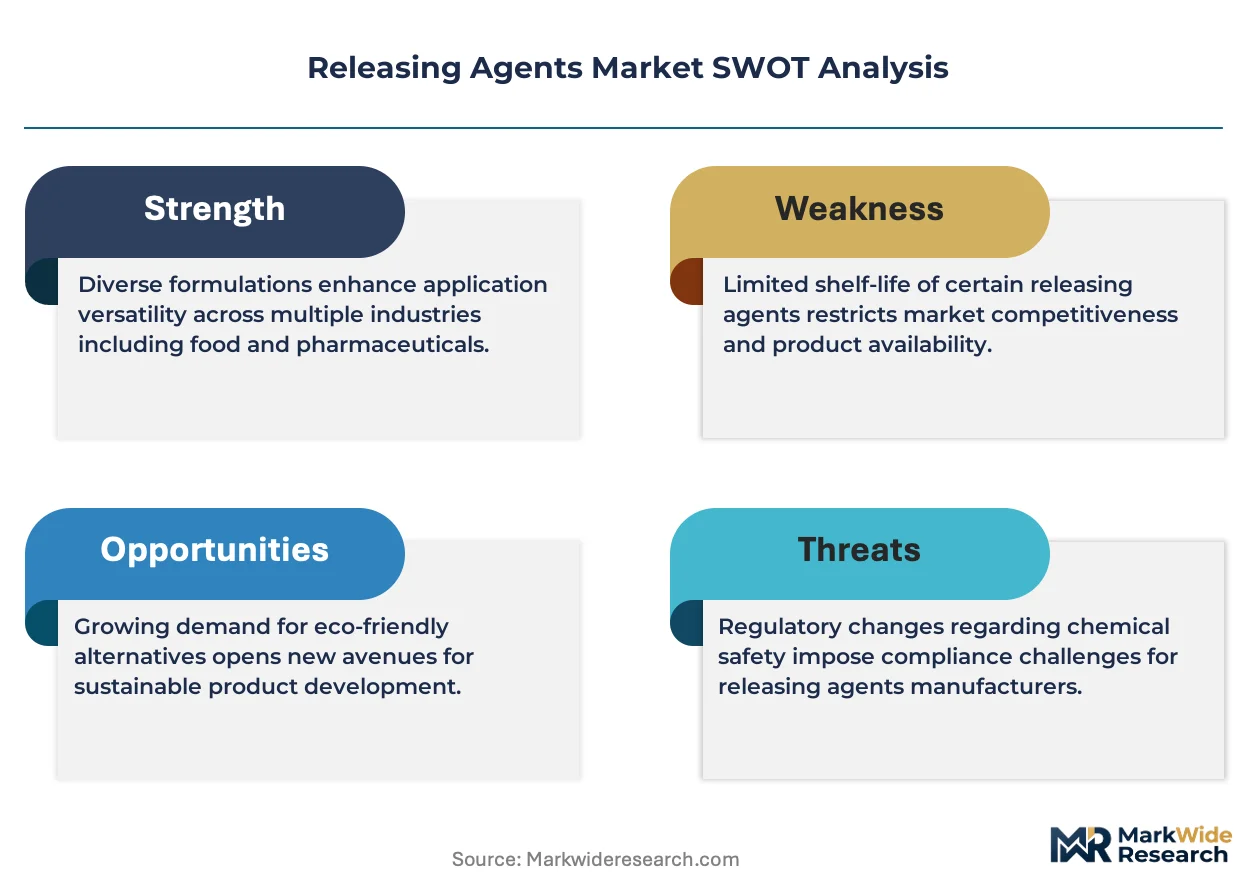
REACH is rebalancing the cost-of-entry calculus for specialty releasing agents in European food-contact applications. BASF SE leverages its integrated surfactant portfolio to sustain compliance leadership across solvent-free grades. Dow Inc. anchors its position through in-house silicone polymer production that navigates evolving residue limits.
Releasing agents are surface-active formulations—typically comprising vegetable oils, silicone emulsions, or synthetic esters—applied to molds, dies, or processing equipment to prevent adhesion and ensure clean product release at temperatures ranging from ambient to over 200°C. Their primary industrial purpose centers on yield protection, surface finish quality, and equipment longevity in continuous manufacturing environments. Oil-based formulations still occupy the largest share of volume demand in plastics molding, while water-based systems lead growth in food processing as clean-label requirements intensify. Spray delivery dominates convenience-oriented applications, though dip systems sustain relevance in high-throughput bakeries where coating uniformity governs throughput consistency.
The EPA regulates volatile organic compound content in solvent-based releasing agents through 40 CFR standards, while the FDA governs food-contact substances under 21 CFR 174-178. EFSA's evolving opinions on mineral oil saturated hydrocarbons in food-grade lubricants are forcing reformulation across European supply chains. Stakeholders must monitor regulatory divergence between jurisdictions to decide whether to standardize formulations globally or maintain region-specific product lines.
Market Dynamics
Clean-label mandates across food-contact applications are forcing a wholesale shift from solvent-based to water-based releasing agent formulations, compressing legacy product margins while opening premium positioning for compliant suppliers.
Growth Catalysts
- REACH residue thresholds:ECHA's tightening permissible limits for mineral oil saturated hydrocarbons in food-grade applications are accelerating reformulation investments toward bio-based esters and vegetable oil derivatives.
- Bakery automation:Continuous baking lines in Germany, China, and Brazil require precision spray systems that depend on specialized water-based releasing agents for throughput consistency.
- Silicone polymer advances:High-temperature stability above 200°C in platinum-cured silicone emulsions is expanding addressable applications into automotive composites and aerospace molding.
Market Restraints
- Palm oil price volatility:Vegetable oil feedstocks constitute 40-60% of raw material costs for bio-based formulations, exposing margins to agricultural commodity swings.
- Specialty surfactant concentration:European supply chains rely on a concentrated base of ethoxylated alcohol producers, creating single-source vulnerability for emulsion stability.
- Technical performance gaps:Water-based systems still exhibit inferior release efficiency in deep-draw thermoforming compared to solvent-based alternatives, limiting penetration in certain plastics segments.
Strategic Opportunities
- India food processing expansion:FSSAI's harmonization with Codex standards is creating compliance-ready demand from organized bakery and confectionery sectors in Maharashtra and Karnataka.
- Plant-based meat analogs:Extrusion cooking of high-protein formulations requires novel releasing agents compatible with allergen-free claims and clean-label positioning.
- Direct-to-bakery distribution:Bypassing traditional chemical distributors through tanker-truck delivery and on-site dilution systems captures margin from high-volume artisan and industrial bakeries.
Industry Challenges
- Formulation chemistry expertise:The intersection of food safety toxicology, polymer science, and high-temperature tribology requires rare cross-functional talent that suppliers struggle to recruit.
- Dual-registration burden:Maintaining separate dossiers for FDA food-contact notifications and EFSA safety assessments stretches regulatory affairs capacity without guaranteed commercial uptake.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Releasing Agents Market |
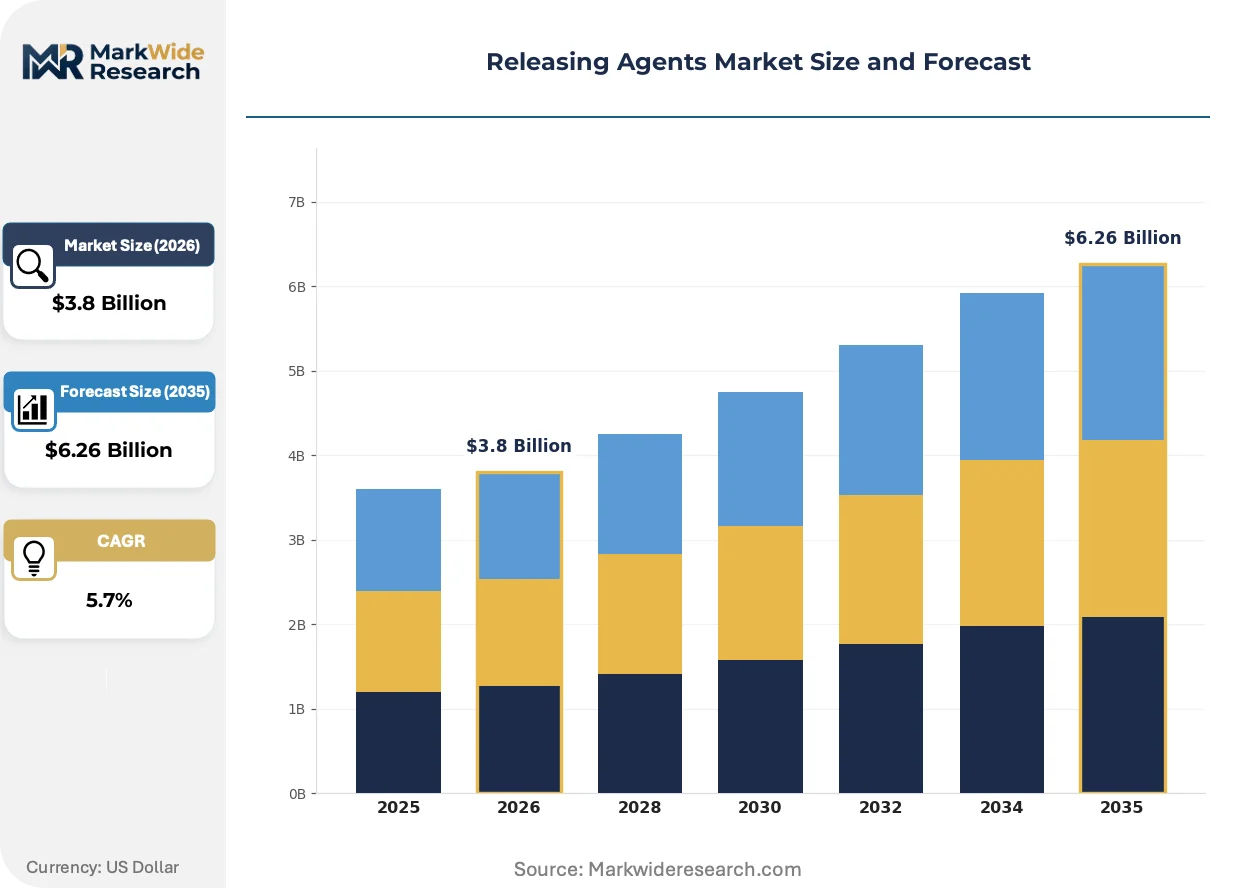
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Water-Based, Oil-Based, Solvent-Based, Powder-Based Application: Food Processing, Pharmaceuticals, Plastics Molding, Coatings End User: Bakers, Manufacturers, Laboratories, Chemical Processors Delivery Mode: Spray, Brush-On, Pump, Dip |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, Dow Inc., BASF SE, AAK AB, Lallemand Inc., Bunge Limited, Henkel AG & Co. KGaA, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Releasing Agents Market Evolving Landscape
Releasing agent technology is bifurcating between high-performance synthetic systems for industrial durability and bio-derived formulations for food-contact acceptability, with regulatory chemistry driving most R&D allocation.
Plasma-enhanced chemical vapor deposition of fluoropolymer release coatings is rewriting equipment maintenance economics in high-volume injection molding. Tier-one automotive suppliers in Germany and Japan are piloting these dry-film alternatives to eliminate spray booth contamination and reduce downtime cycles. The technology is compressing demand for traditional liquid releasing agents in precision polymer processing.
EFSA's 2023 update to mineral oil saturated hydrocarbon risk assessments is forcing European lubricant and release agent blenders toward Group III base oils and synthetic esters. Food-contact substance dossiers now require comprehensive migration testing that extends approval timelines by 18-24 months. Bakery and confectionery equipment manufacturers in Italy and France are accelerating qualification of compliant alternatives ahead of enforcement.
Consolidated bakery groups are unbundling releasing agent procurement from bundled maintenance contracts, establishing direct specification authority over formulation chemistry. Industrial bakers in Brazil and Mexico now conduct independent release-efficiency testing against internal throughput metrics rather than relying on distributor recommendations. This behavior is most visible in high-volume croissant and wafer production facilities where coating uniformity directly governs line speed.
Releasing Agents Market Segmentation
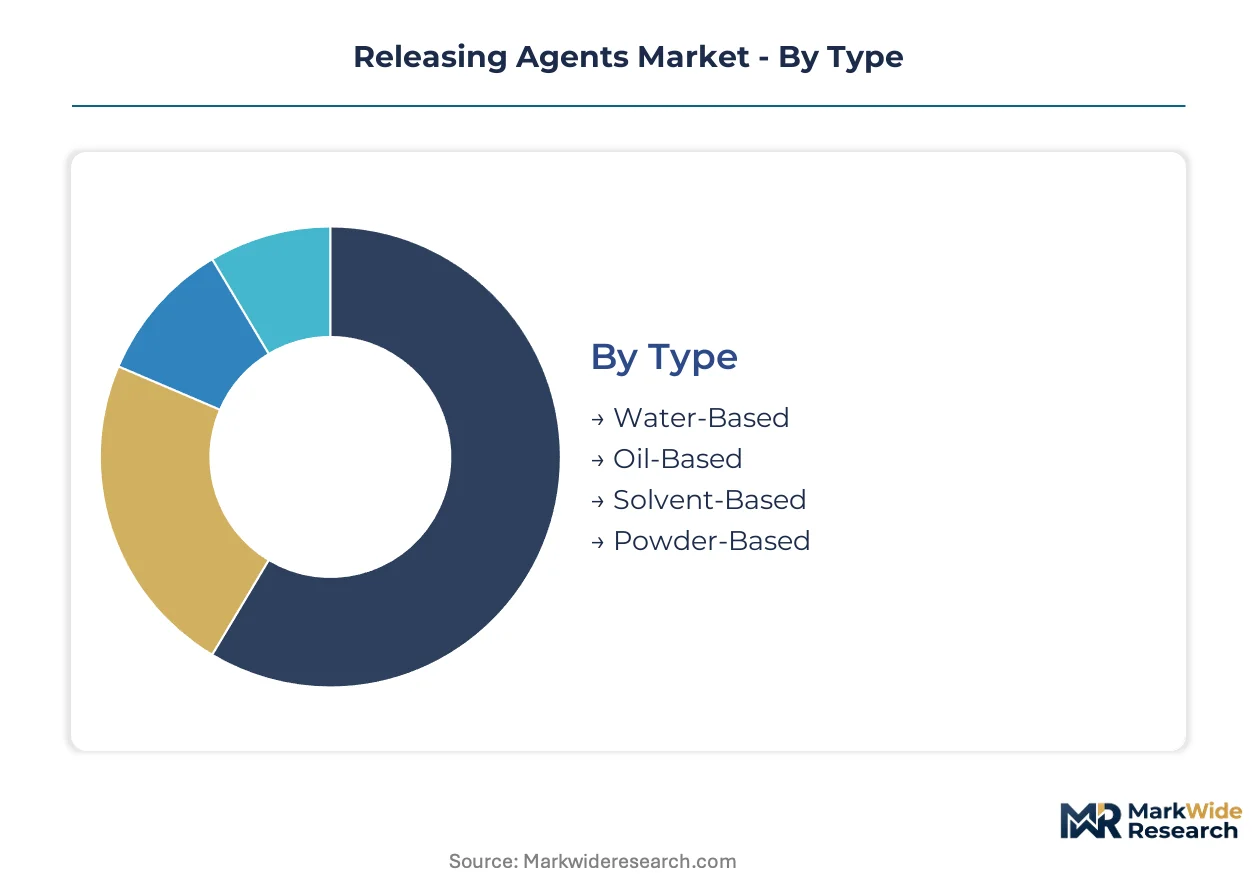
Releasing agent formulations diverge sharply between embedded process fluids and standalone surface treatments. Understanding where each segment sits on this integration spectrum clarifies procurement patterns and margin structures across food, pharmaceutical, and industrial end-uses.
Type:
Integration depth varies from fully embedded silicone polymer networks to standalone vegetable oil sprays that require reapplication between cycles.
- Water-Based:Emulsion systems disperse active release polymers in aqueous carriers for clean-label food-contact compliance. German industrial bakeries and Brazilian wafer manufacturers are consolidating specifications around these formulations as REACH residue thresholds tighten. Reformulation cycles now dominate supplier R&D allocation.
- Oil-Based:Vegetable oil and mineral oil derivatives remain embedded in high-temperature plastics molding where thermal stability exceeds 180°C. Demand concentrates in Chinese automotive component clusters where solvent-free operation meets factory emission controls. Palm oil price volatility compresses margin predictability for blenders.
- Solvent-Based:Hydrocarbon carriers deliver rapid film formation in aerospace composite tooling.
- Powder-Based:Dry lubricant dispersions serve pharmaceutical tablet compression where liquid contamination risks batch integrity.
Volume placements concentrate in oil-based systems; the faster expansion belongs to water-based formulations.
Application:
Cost tier stratification separates commodity process aids from validated pharmaceutical-grade release systems with dossier-backed compliance.
- Food Processing:Bakery, confectionery, and meat analog extrusion operations require food-contact substance notifications under FDA 21 CFR or EFSA safety assessments. Maharashtra and Karnataka bakery clusters in India are driving specification authority unbundling from equipment maintenance contracts. Clean-label mandates accelerate water-based adoption.
- Pharmaceuticals:Tablet and capsule manufacturing demands excipient-grade release agents with USP-NF or EP monograph compliance. Migration testing protocols extend qualification timelines, embedding suppliers deeply into customer quality systems. Platinum-cured silicone emulsions dominate high-value applications.
- Plastics Molding:Injection and blow molding operations balance release efficiency against surface finish requirements.
- Coatings:Industrial paint and varnish production uses release agents for drum and vessel cleaning.
Revenue concentrates in food processing; steepest expansion trajectory sits with pharmaceutical applications.
End User:
Customer type determines whether procurement flows through chemical distributors or direct tanker-truck supply relationships.
- Bakers:Artisan and industrial bakery operations specify releasing agents based on throughput consistency metrics rather than distributor recommendations. Brazilian croissant lines and German frozen dough facilities conduct independent release-efficiency testing. Direct dilution systems at plant sites are displacing packaged goods.
- Manufacturers:Tier-one automotive and appliance molders integrate release chemistry into preventive maintenance schedules. Japanese and German automotive suppliers pilot plasma-enhanced fluoropolymer coatings that compress traditional liquid agent demand.
- Laboratories:R&D and quality control facilities require small-batch release agents for prototyping.
- Chemical Processors:Specialty chemical and petrochemical operations use releasing agents for reactor vessel maintenance.
Procurement volume clusters with manufacturers; the fastest share gains belong to bakers.
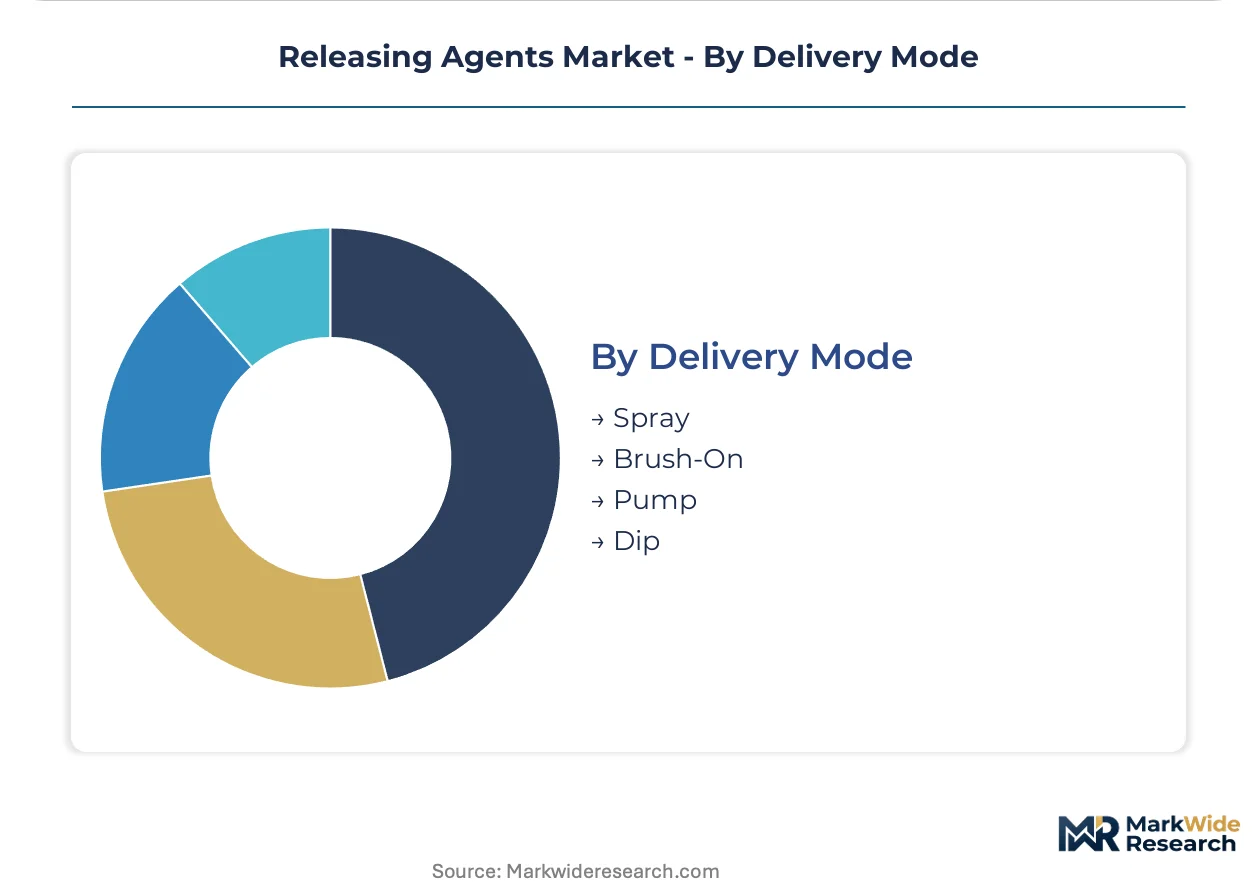
Delivery Mode:
Supply concentration in precision spray equipment creates dependency on specialized nozzle and pumping system suppliers.
- Spray:Atomized delivery dominates convenience-oriented applications where coating uniformity governs line speed. Continuous baking installations in China and Mexico require precision spray systems with automated feedback controls. Equipment-fluids bundling is unravelling as bakers assert independent specification authority.
- Brush-On:Manual application persists in prototype molding and small-batch pharmaceutical tooling where automation economics fail.
- Pump:Metered dispensing systems serve high-viscosity silicone emulsions in automotive composites molding.
- Dip:Immersion coating sustains relevance in high-throughput bakeries where full mold coverage is non-negotiable.
Installation base concentrates in spray systems; dip applications are climbing fastest in emerging market bakery automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany, China, and Brazil as manufacturing clusters expand. Food processing bakers in these markets drive rising consumption of water-based formulations. Regulatory divergence between jurisdictions forces suppliers to maintain region-specific product lines.
United States
EPA guidelines under 40 CFR standards are tightening permissible residue thresholds for volatile organic compounds in solvent-based formulations. Food-contact substance notifications under FDA 21 CFR govern bakery and confectionery applications. Industrial bakeries in the Midwest and Southeast are unbundling releasing agent procurement from equipment maintenance contracts.
Germany
REACH compliance and ECHA's tightening limits for mineral oil saturated hydrocarbons are accelerating reformulation toward bio-based esters. EFSA's evolving risk assessments extend approval timelines for food-contact substances by 18-24 months. Continuous baking lines in Bavaria and North Rhine-Westphalia require precision spray systems with specialized water-based releasing agents.
China
Automotive component clusters demand oil-based formulations where thermal stability exceeds 180°C and factory emission controls mandate solvent-free operation. GB standards and SAMR oversight shape food-contact compliance frameworks. Manufacturing gravity centers on Yangtze River Delta and Pearl River Delta plastics molding operations.
Brazil
ANVISA harmonization with Codex standards is creating compliance-ready demand from organized bakery and confectionery sectors. Croissant and wafer production facilities conduct independent release-efficiency testing against internal throughput metrics. São Paulo and Minas Gerais industrial bakeries are consolidating specifications around water-based systems.
India
FSSAI's harmonization with Codex standards is opening specification authority for organized bakery operations in Maharashtra and Karnataka. Central food safety regulations now require migration testing protocols for food-grade lubricants. Mumbai and Bangalore manufacturing clusters are accelerating qualification of REACH-compliant alternatives.
Releasing Agents Market Competitive Landscape
German producers anchor one tier; American and Scandinavian specialists hold formulation chemistry positions. The vendor base separates into integrated surfactant portfolios, in-house silicone polymer operations, and regional vegetable oil blenders. Three archetypes dominate: compliance-first multinationals with regulatory dossier depth, feedstock-integrated agribusinesses with cost position, and precision-spray equipment bundlers losing share to unbundled procurement. Competitive moves concentrate on backward integration into silicone polymer production and direct-to-bakery distribution bypassing traditional chemical distributors.
Within the integrated multinational tier, BASF SE and Dow Inc. occupy positions defined by captive supply of core chemistries. Cargill Incorporated exemplifies the feedstock-integrated archetype with agricultural commodity leverage. These three entities represent the structural fault lines between synthetic polymer control, surfactant integration, and vegetable oil feedstock security that shape margin durability across formulation types.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Dow Inc. |
| BASF SE |
| AAK AB |
| Lallemand Inc. |
| Bunge Limited |
| Henkel AG & Co. KGaA |
| Evonik Industries AG |
| Others |
Value Network & Pricing Analysis
Captive silicone polymer production anchors pricing power for integrated multinationals while locking out vegetable oil blenders from premium formulation tiers. BASF SE and Dow Inc. leverage in-house surfactant and polymer operations to absorb REACH compliance costs that fragment regional competitors.
Pricing Analysis
Volume placements cluster in commodity oil-based grades where palm oil feedstock volatility compresses margins; premium water-based formulations command pricing separation through FDA food-contact notification dossiers and EFSA safety assessment backing. Price differentiation rests on certification tier and volume scale, with industrial bakeries in Germany and Brazil negotiating direct tanker-truck supply contracts that bypass distributor markups. Cost compression in bio-based esters is intensifying because ECHA's tightening mineral oil saturated hydrocarbon limits force reformulation investments. Artisan bakeries exhibit highest price sensitivity; pharmaceutical tablet manufacturers demonstrate lowest sensitivity due to USP-NF monograph compliance requirements.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Houston feed hub-and-spoke patterns into manufacturing clusters across Germany, China, and Brazil. Raw material flows draw from Malaysian and Indonesian palm oil estates, German ethoxylated alcohol producers, and Japanese silicone monomer operations. Single-source vulnerability concentrates in European specialty surfactant supply where three producers dominate emulsion stability chemistries. Distribution runs through tanker-truck direct delivery for high-volume bakers and chemical distributors for small-batch pharmaceutical and laboratory customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into silicone polymer production and vegetable oil feedstock security defines competitive durability. Players without captive supply chains face margin compression as REACH residue thresholds tighten.
For Market Incumbents: To counter plasma-enhanced fluoropolymer coating substitution in automotive precision molding, BASF SE and Dow Inc. should deepen captive silicone emulsion capacity and accelerate direct-to-bakery distribution bypassing traditional chemical distributors. Securing long-term palm oil offtake agreements insulates bio-based formulation margins from agricultural commodity swings. For New Entrants and Emerging Players: Capture unbundled procurement authority in Maharashtra and Karnataka bakery clusters where FSSAI harmonization with Codex standards creates compliance-ready demand without entrenched supplier relationships. Plant-based meat analog extrusion applications offer penetrable white space requiring allergen-free clean-label formulations. Lead with tanker-truck dilution systems and on-site technical service to displace packaged goods incumbents. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to feedstock-integrated agribusinesses seeking downstream formulation capabilities. Long-term viability hinges on regulatory dossier depth rather than commodity blending scale. The signal to watch is EFSA enforcement timing on mineral oil saturated hydrocarbon limits, which will accelerate consolidation toward compliance-first multinationals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Polymer Production | Dow Inc.'s captive supply secures margin durability against specialty surfactant concentration risks. |
| Direct-to-Bakery Distribution Network | Tanker-truck delivery captures margin from Brazilian croissant lines unbundling from equipment contracts. |
| REACH-Compliant Reformulation Investment | Group III base oil and synthetic ester shifts position suppliers ahead of EFSA enforcement timelines. |
| Long-term Vegetable Oil Feedstock Agreement | Palm oil offtake security insulates bio-based blenders from Malaysian and Indonesian price volatility. |
| Precision Spray Equipment Partnership | Automated feedback control integration locks in continuous baking line specifications in China and Mexico. |
Research Methodology
Document review covered FDA 21 CFR food-contact substance notifications, EFSA safety assessment archives, and REACH registration dossiers, complemented by interviews with bakery operations managers, pharmaceutical quality control directors, automotive Tier 1 procurement leads, and specialty chemical distribution executives. Secondary validation drew from customs trade data, SEC 10-K filings, and industry association technical bulletins. Bottom-up formulation demand modeling and top-down manufacturing cluster analysis were cross-referenced for triangulation.
Historical volume trajectories were cross-referenced against expert panel input on regulatory enforcement timing and bakery automation capex cycles. Segmentation dimensions spanned formulation type, application sector, end-user procurement mode, and delivery system integration level. CAGRs were derived from elasticity-adjusted demand curves across the projection horizon, incorporating silicone polymer thermal stability advances and clean-label mandate penetration rates as industry-specific forecast inputs.
The model holds under stable REACH and EPA regulatory enforcement trajectories; deviation in EFSA mineral oil saturated hydrocarbon limit timing or palm oil supply disruption would shift volume trajectories between oil-based and water-based formulation categories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Fatliquoring Agents Market
Specialty Chemicals
Global Vinyl Sulfone Market
Specialty Chemicals
Polyacrylamide Gel Electrophoresis (PAGE) Market
Specialty Chemicals
Europe Hydroxypropyl Methylcellulose (HPMC) Market
Specialty Chemicals
Micronized PTFE Market
Specialty Chemicals
Acetyl Isovaleryl Market
Specialty Chemicals
Ethylhexane Diol Market
Specialty Chemicals
UV Filters Market
Specialty Chemicals
Phosphonate Market
Specialty Chemicals
Propyl Isovalerate Market
Specialty Chemicals
Stearyl Alcohol Market
Specialty Chemicals
Cellulose Ether Market
Specialty Chemicals
Global Chemical Vapor Deposition (CVD) Market
Specialty Chemicals
Africa Lactic Acid Market
Specialty Chemicals
Spiroglycol Market
Specialty Chemicals
Global Flame Retardants Market