
 Global PVC Additives Market | 2026-2036
Global PVC Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Global PVC Additives Market Foresight
Specialty fabricators is collapsing as a buyer archetype while OEMs gain procurement leverage through direct additive specification. BASF SE leverages its integrated stabilizer technology platform to anchor European supply relationships. Arkema SA competes through impact modifier specialization in automotive-grade compounds. Evonik Industries AG dominates high-performance processing aids for rigid PVC applications.
PVC additives encompass chemical modifiers—stabilizers, plasticizers, lubricants, impact modifiers, and processing aids—blended at 1-10 parts per hundred resin to enhance thermal stability, flexibility, or impact resistance during extrusion, calendering, or injection molding. Plasticizers retain the largest volume share across flexible applications, while stabilizers command premium pricing amid lead-substitution mandates. Construction materials represents the most mature application segment, whereas automotive components offers faster expansion as under-the-hood specifications tighten.
REACH in Europe, EPA regulations in the United States, and GB standards in China govern phthalate restrictions, heavy-metal limits, and emission thresholds across additive formulations. Compliance complexity is fragmenting supplier bases as regional certification requirements diverge. Stakeholders must monitor regulatory harmonization gaps between jurisdictions to anticipate reformulation timelines and qualification costs.
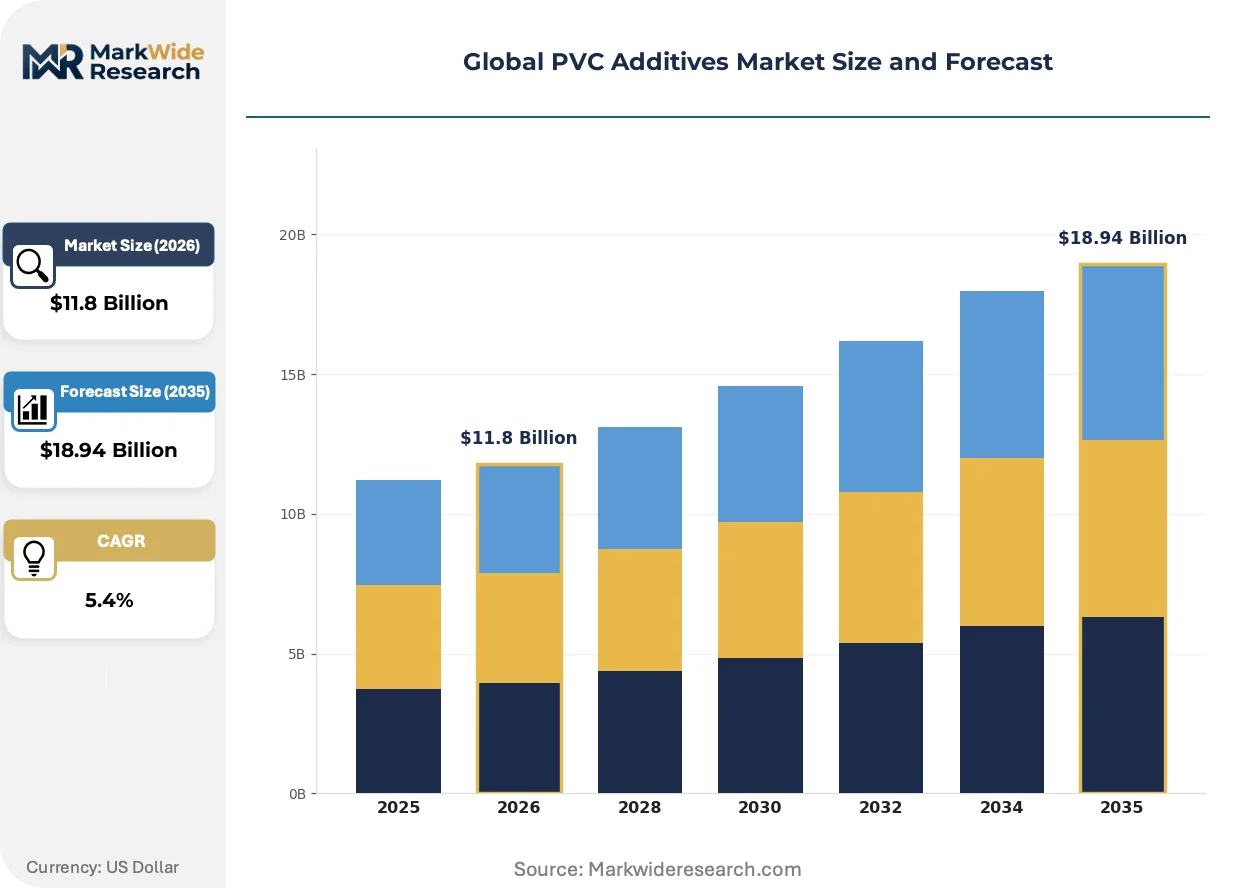
Market Dynamics
Lead-substitution mandates across Europe, China, and the United States are forcing simultaneous reformulation of stabilizer chemistries while construction-grade PVC processors consolidate supplier relationships to secure compliant additive supply.
Growth Catalysts
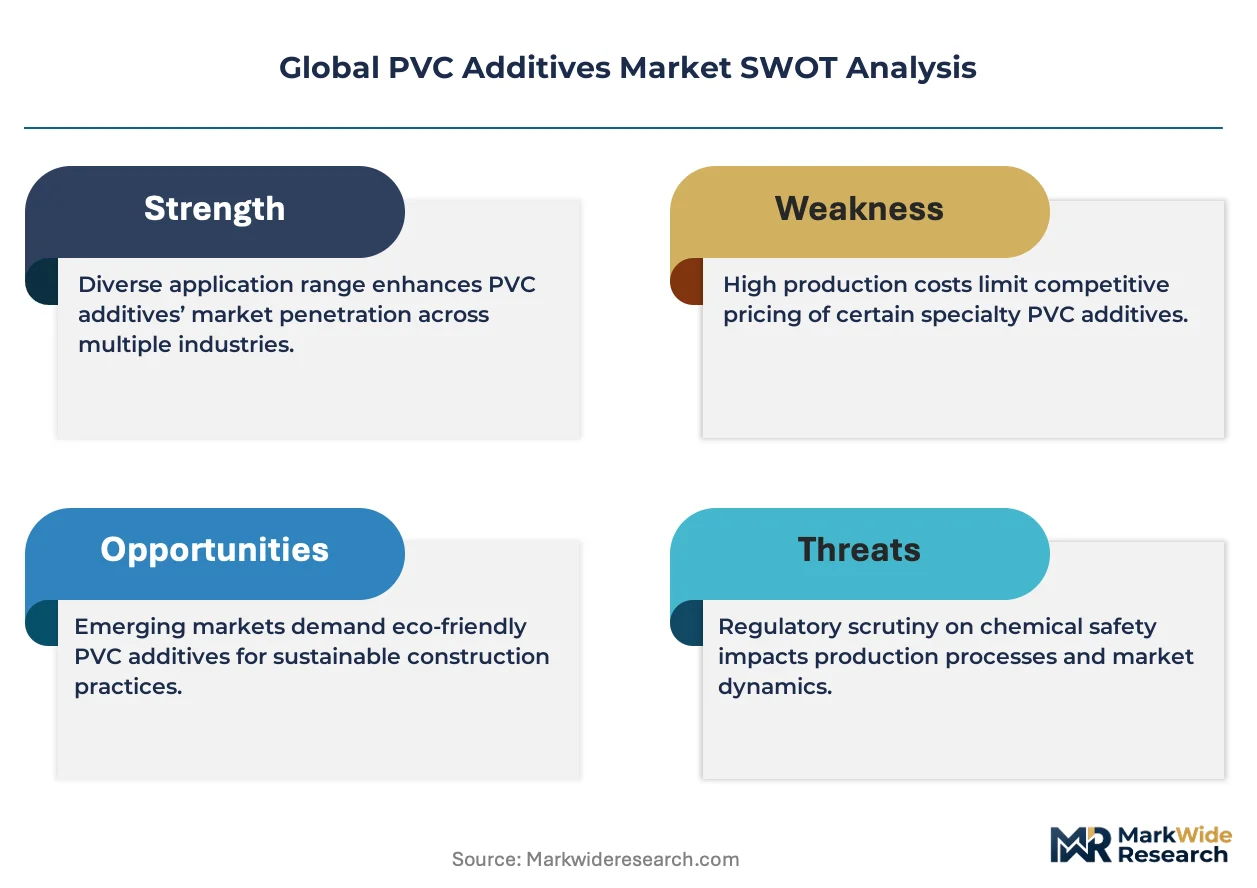
- REACH lead restrictions:European processors are accelerating calcium-zinc and organic stabilizer adoption to meet phased heavy-metal limits, creating sustained demand for compliant additive platforms.
- Automotive under-the-hood specifications:Thermal stability requirements for engine-bay PVC components are pulling high-performance processing aids into compound formulations at premium loadings.
- China domestic capacity scaling:Integrated PVC resin producers in Shandong and Xinjiang are backward-integrating into captive additive blending to serve regional construction material fabricators.
Market Restraints
- Epoxidized soybean oil price volatility:Bio-based plasticizer feedstock costs fluctuate with agricultural commodity cycles, compressing margins for flexible PVC compounders serving consumer goods.
- Specialty stabilizer supply concentration:German and Italian producers control organotin and mixed-metal stabilizer technology, exposing Asian processors to euro-denominated input cost exposure.
- Phthalate substitution technical limits:DINP and DIDP replacements in medical tubing fail to match low-temperature flexibility thresholds, constraining device manufacturer formulation freedom.
Strategic Opportunities
- India BIS certification pipeline:Domestic PVC pipe standards are tightening leachate requirements, opening qualification windows for lead-free stabilizer suppliers before local capacity matures.
- Recycled PVC feedstock integration:Mechanical recycling of post-consumer window profiles demands novel processing aids to restore thermal stability degraded by prior heat history.
- EU Green Deal carbon accounting:Construction product environmental product declarations are creating preference for additives with verified lifecycle emissions, rewarding early certifiers.
Industry Challenges
- Formulation chemist scarcity:Compounders struggle to recruit specialists capable of balancing multi-additive interactions across stabilizer, lubricant, and impact modifier combinations.
- Dual qualification timelines:Automotive OEMs require 18-24 month validation cycles for new additive packages, freezing supplier switches even when superior chemistries emerge.
- Legacy calendering equipment retrofit costs:Rigid film producers face capital outlays to modify roll configurations when transitioning from lead to calcium-zinc stabilizer systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global PVC Additives Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $18.94 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stabilizers, Plasticizers, Lubricants, Impact Modifiers, Processing Aids Application: Construction Materials, Electrical Insulation, Packaging Films, Automotive Components, Consumer Goods End User: Manufacturers, Fabricators, Distributors, OEMs, Contract Processors Form: Liquid, Powder, Granule, Paste, Resin |
| Companies Covered | BASF SE, Arkema SA, Clariant AG, Dow Inc., Evonik Industries AG, Akzo Nobel N.V., Songwon Industrial Co., Ltd., Kaneka Corporation, Adeka Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global PVC Additives Market Shifts & Advancements
Active ingredient innovation in stabilizer and modifier chemistries is compressing traditional formulation hierarchies while digital specification tools reshape how compounders validate additive performance.
Hybrid organic-inorganic stabilizer systems are fragmenting the traditional calcium-zinc versus organotin dichotomy in European rigid extrusion applications. Window profile processors in Germany and Poland are piloting these platforms to meet REACH lead limits without sacrificing weathering performance. The technology is fragmenting supplier tiers as specialty chemical houses bypass commodity stabilizer distributors to secure direct specification relationships with major extrusion groups.
EPA TSCA Section 6 restrictions on long-chain chlorinated paraffins are compelling US wire and cable compounders to reformulate flame-retardant plasticizer packages ahead of enforcement deadlines. Cable manufacturers serving data center and renewable energy infrastructure are accelerating qualification of phosphate ester alternatives. The regulatory pressure is most acute in Texas and California, where state-level environmental disclosure requirements add compliance layers beyond federal mandates.
Direct additive specification by automotive OEMs is displacing historical reliance on compounder-formulated masterbatches for interior and under-the-hood PVC components. Tier-1 suppliers in Michigan and Stuttgart report shrinking formulation autonomy as Volkswagen, Ford, and BMW centralize material approvals through proprietary digital platforms. This concentration is most visible in acoustic damping applications, where OEMs now mandate specific impact modifier grades to meet NVH targets across global vehicle programs.
Global PVC Additives Market Segmentation
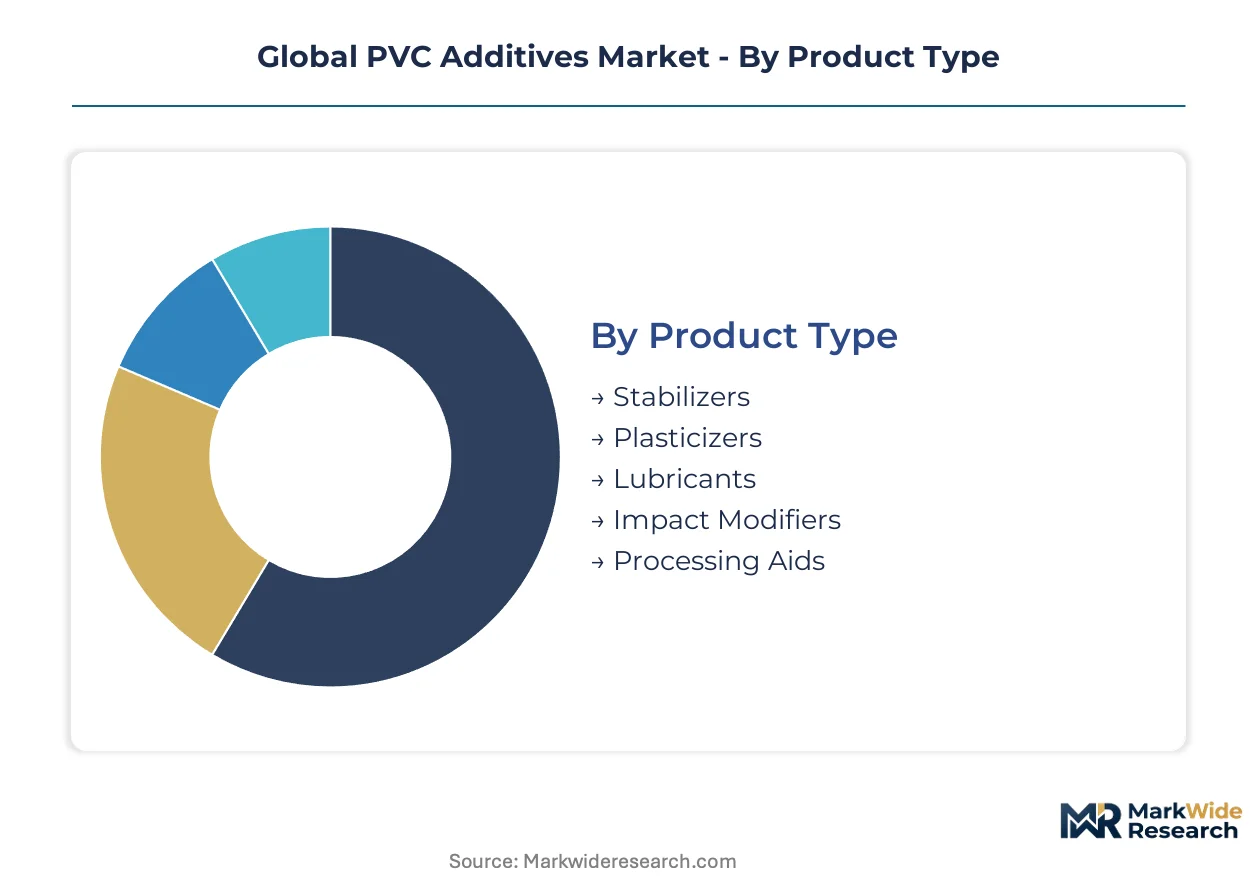
PVC additives serve distinct functional roles across processing technologies, with formulation complexity varying sharply by end-use thermal and mechanical requirements. Understanding where value concentrates within each dimension enables suppliers to prioritize R&D investment and qualification resources.
Product Type:
Margin pools concentrate in stabilizer technologies where regulatory substitution mandates command premium pricing power, while plasticizers compete on volume scale with compressed differentials.
- Stabilizers:Heat-stabilizing chemistries—calcium-zinc, organotin, and organic-based systems—prevent thermal degradation during PVC processing at 180-210°C. European window profile extruders in Germany and Poland are accelerating calcium-zinc adoption to satisfy REACH lead restrictions, creating sustained demand for compliant platforms despite reformulation costs.
- Plasticizers:Phthalate and bio-based alternatives impart flexibility to flexible PVC at 20-60 parts per hundred resin loadings. DINP and DIDP replacements face technical limits in medical tubing applications where low-temperature flexibility thresholds constrain device manufacturer formulation freedom.
- Lubricants:Internal and external lubricant packages reduce shear heating during extrusion and calendering operations.
- Impact Modifiers:Acrylic and MBS core-shell modifiers enhance toughness in rigid PVC applications.
- Processing Aids:High-molecular-weight acrylic additives improve melt homogeneity and surface finish in rigid extrusion.
The dominant share belongs to plasticizers by volume, while stabilizers are closing the gap fastest on value expansion.
Application:
Cost tier stratification separates mature construction segments from automotive specifications where thermal performance commands formulation premiums.
- Construction Materials:Pipe, siding, and window profiles consume the majority of stabilizer and processing aid volumes. China's domestic PVC processing capacity scaling in Shandong and Xinjiang is concentrating demand as integrated resin producers backward-integrate into captive additive blending.
- Automotive Components:Under-the-hood PVC applications—wire harnesses, gaskets, and acoustic damping—require thermal stability above 120°C. Volkswagen, Ford, and BMW now mandate specific impact modifier grades through proprietary digital platforms, stripping Tier-1 suppliers of historical formulation autonomy.
- Electrical Insulation:Wire and cable jacketing depends on flame-retardant plasticizer packages facing EPA TSCA Section 6 reformulation pressure.
- Packaging Films:Rigid and flexible calendered films for food and pharmaceutical applications.
- Consumer Goods:Toys, footwear, and household products where phthalate restrictions vary by jurisdiction.
Construction Materials retains the largest volume position, though Automotive Components is gaining share fastest on specification tightening.
End User:
Customer type determines procurement leverage, with OEMs increasingly displacing compounder intermediaries through direct additive specification.
- Manufacturers:Integrated PVC resin producers with captive compounding operations.
- Fabricators:Extrusion and calendering operations purchasing pre-formulated compounds.
- Distributors:Regional chemical distributors serving small-to-mid compounders.
- OEMs:Automotive and appliance manufacturers specifying additives directly. Michigan and Stuttgart-based Tier-1 suppliers report shrinking formulation autonomy as OEMs centralize material approvals through digital platforms.
- Contract Processors:Toll compounders serving specialty batch requirements.
Procurement concentration favors OEMs, while fabricators are losing specification influence most rapidly.
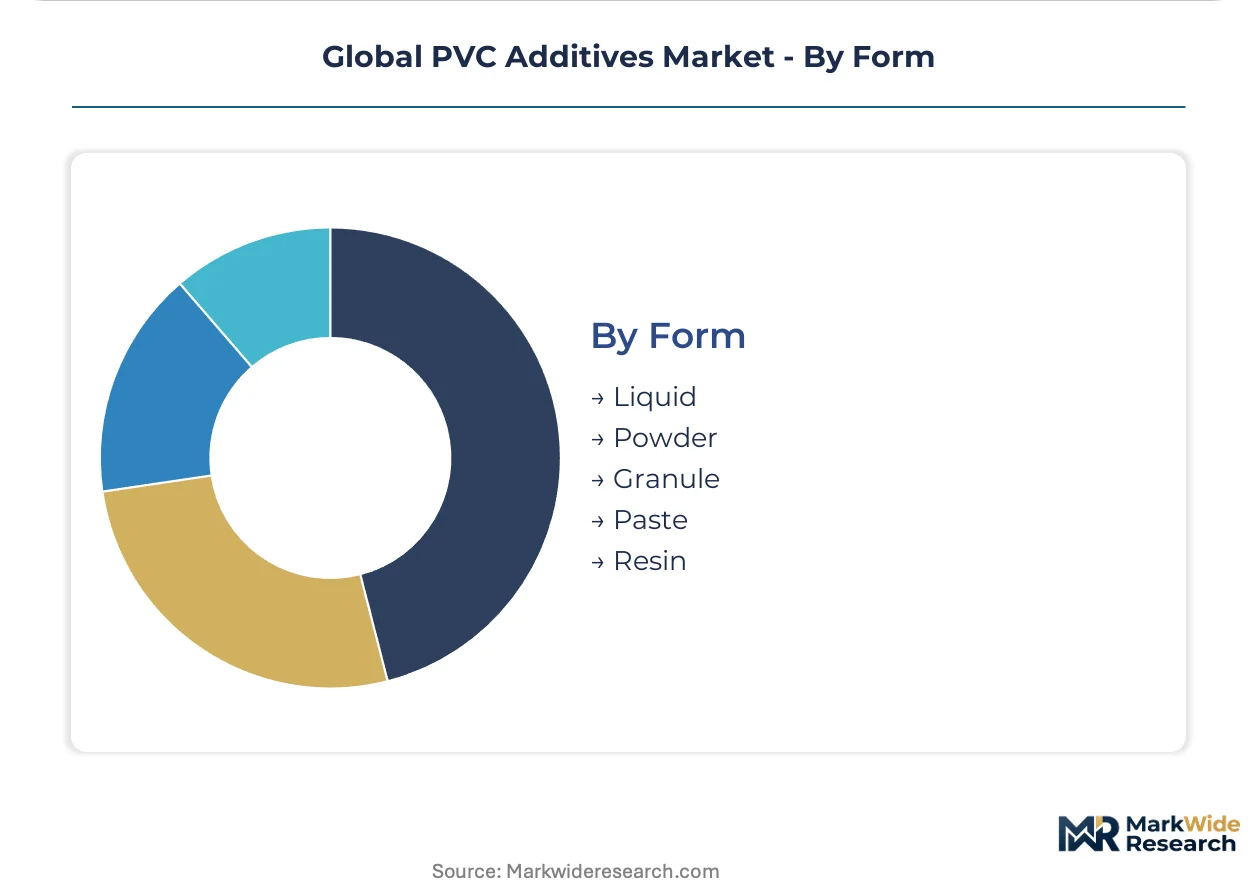
Form:
Supply concentration varies by physical state, with liquid plasticizer infrastructure concentrated near petrochemical complexes.
- Liquid:Dominant form for plasticizers and some stabilizer packages.
- Powder:Dry-blend stabilizers and lubricants for rigid PVC processors.
- Granule:Pre-dispersed additive concentrates reducing dust exposure.
- Paste:High-viscosity plasticizer dispersions for plastisol applications.
- Resin:Solid processing aids and impact modifiers in pellet form.
Liquid forms dominate plasticizer delivery, while powder stabilizers are expanding fastest on dry-blend processing efficiency gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German stabilizer exports supply Polish and Italian extrusion clusters while Chinese additive production scales to serve domestic construction demand and Southeast Asian pipe fabricators.
United States
Wire and cable compounders in Texas and California face EPA TSCA Section 6 deadlines for chlorinated paraffin phase-out. Data center infrastructure investment is pulling flame-retardant plasticizer demand toward phosphate ester alternatives. Houston petrochemical corridors host the largest liquid plasticizer blending capacity in North America.
Germany
Window profile extruders in Bavaria and North Rhine-Westphalia accelerate calcium-zinc stabilizer adoption to satisfy REACH lead restrictions. BASF SE and Evonik Industries AG anchor European supply relationships from Ludwigshafen and Essen production sites. German chemical houses control organotin and mixed-metal stabilizer technology exports to Asian processors.
China
Integrated PVC resin producers in Shandong and Xinjiang backward-integrate into captive additive blending to serve regional construction material fabricators. GB standards on heavy-metal limits are tightening leachate requirements for domestic pipe applications. Shanghai and Ningbo ports concentrate import logistics for specialty stabilizers not yet produced at domestic scale.
India
BIS certification pipelines for PVC pipe standards are opening qualification windows for lead-free stabilizer suppliers before local capacity matures. Maharashtra and Gujarat house the largest rigid PVC processing clusters for irrigation and drainage applications. Domestic compounders in Ahmedabad and Mumbai seek compliant additive supply as import substitution policies advance.
Japan
Automotive OEMs in Toyota City and Yokohama specify high-performance processing aids directly for under-the-hood PVC components. METI guidelines on chemical substance management influence formulation choices across electrical insulation applications. Osaka-based fabricators serve premium export markets for medical-grade flexible compounds.
Global PVC Additives Market Competitive Landscape
Listed leaders compete with private specialists across stabilizer technology platforms, creating a tiered structure where scale-driven commodity producers coexist with focused formulation houses. European chemical conglomerates anchor premium stabilizer supply through integrated technology platforms. Asian industrial groups compete on volume scale in plasticizer and lubricant segments. The dominant competitive moves center on backward integration into captive additive production and direct specification relationships with automotive OEMs.
Within the integrated technology tier, BASF SE and Evonik Industries AG exemplify European-listed leaders leveraging stabilizer and processing aid platforms to anchor regional supply relationships. Arkema SA represents the specialization archetype, with French-based operations occupying a position in impact modifier technology for automotive-grade compounds. Among Asian industrial groups, Songwon Industrial Co., Ltd. and Kaneka Corporation sit within the scale-driven segment, serving volume demand across stabilizer and modifier categories from Korean and Japanese production bases respectively.
| Leading Market Players |
|---|
| BASF SE |
| Arkema SA |
| Clariant AG |
| Dow Inc. |
| Evonik Industries AG |
| Akzo Nobel N.V. |
| Songwon Industrial Co., Ltd. |
| Kaneka Corporation |
| Adeka Corporation |
| Others |
Supply & Pricing Matrix
Lead-to-calcium-zinc stabilizer substitution across European extrusion operations is redrawing raw material sourcing maps while compressing margin structures for processors absorbing reformulation costs. This chemistry migration simultaneously elevates logistics expenses for organotin-dependent Asian compounders and creates pricing power for German and Italian specialty producers controlling compliant additive technology.
Pricing Analysis
Next-generation organic stabilizer platforms command 40-60% premiums over legacy lead-based systems, while mid-tier calcium-zinc formulations occupy a narrowing price band as Chinese capacity scales. Price differentiation rests on REACH certification tiers and thermal performance grades, with automotive-specified processing aids carrying the widest spreads. Cost compression in flexible PVC plasticizers is intensifying because epoxidized soybean oil feedstock volatility transfers directly to compounder margins. Construction-grade fabricators in Shandong and Xinjiang exhibit highest price sensitivity, whereas German window profile extruders prioritize compliance over unit cost.
Supply Chain Analysis
Inventory cycles for liquid plasticizers stretch 8-12 weeks at Houston and Rotterdam hub terminals, reflecting agricultural commodity harvest timing and ocean freight scheduling. German and Italian producers anchor organotin and mixed-metal stabilizer supply, while Chinese integrated resin operations in Shandong and Xinjiang backward-integrate into captive additive blending. Specialty stabilizer production draws from naphtha-derived chemical feedstocks and rare-earth catalyst systems, exposing Asian processors to euro-denominated input cost fluctuations. Single-source vulnerability concentrates in automotive-grade impact modifier supply from Japanese and Korean producers. Distribution runs through regional chemical distributors serving mid-tier compounders, with direct specification relationships increasingly displacing this channel for automotive OEM accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry expertise has become the constraining asset in this market, with qualified compounders capable of balancing multi-additive interactions across stabilizer-lubricant-impact modifier combinations commanding disproportionate value capture.
For Market Incumbents: Fortify specification relationships with automotive OEMs in Michigan and Stuttgart before digital platform centralization freezes supplier switches. Prioritize backward integration into calcium-zinc stabilizer precursor production to deflect euro-denominated input cost exposure from German and Italian technology licensors. Channel control through direct technical service teams represents the critical lever for defending margin position against emerging Chinese integrated producers. For New Entrants and Emerging Players: Lead with BIS certification support services for Indian PVC pipe manufacturers facing tightening leachate requirements, where domestic stabilizer capacity remains immature. Target Maharashtra and Gujarat processing clusters for irrigation and drainage applications as the most penetrable geography. A qualification-acceleration go-to-market angle—compressing 18-24 month automotive validation timelines through pre-approved additive platforms—creates differentiation against incumbent technical service models. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed European stabilizer specialists possessing REACH-compliant technology platforms but lacking Asian manufacturing footprint. The 5-10 year viability window favors acquisition targets with organic stabilizer R&D pipelines and existing automotive OEM direct relationships. The signal to watch is OEM digital platform adoption velocity—accelerating centralization of material approvals will strand compounder-intermediary business models and reward additive suppliers with pre-qualified specification status.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stabilizer Precursors | Captive supply of calcium-zinc intermediates insulates German extruders from euro-denominated cost volatility. |
| Automotive OEM Digital Platform Qualification | Pre-approved status on Volkswagen and Ford material systems locks out competitor switching for 18-24 month cycles. |
| India BIS Certification Pre-Positioning | Early qualification for lead-free stabilizer supply captures windows before domestic Shandong-style capacity matures. |
| Recycled PVC Processing Aid Development | Novel thermal stability restoration chemistries address mechanical recycling heat-history degradation in post-consumer window profiles. |
| EU Green Deal Carbon Accounting Certification | Verified lifecycle emissions documentation creates preference in construction product environmental declarations. |
Research Methodology
Initial hypotheses were tested against primary input from PVC compounding plant managers, automotive Tier 1 procurement leads, construction materials distribution channel partners, and specialty chemical R&D directors, then refined through secondary validation against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA regulatory dockets. Bottom-up volume modeling across additive product categories was triangulated with top-down market sizing from resin production and consumption correlations.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects within each segmentation dimension—stabilizer technology tier, end-use industry application, regional production hub, and customer procurement archetype. CAGRs were derived from regression-based trend extrapolation calibrated to historical regulatory substitution patterns and capacity expansion announcements. Forecast inputs incorporate REACH phase-out timelines, China domestic capacity scaling trajectories, and automotive OEM platform standardization roadmaps.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of lead restrictions or accelerated bio-based plasticizer cost convergence would require recalibration. Forecasts reflect documented assumptions regarding substitution elasticity and qualification timeline stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Propyl Gallate Market
Additives
Apocarotenal Market
Additives
Tire Additives Market
Additives
Europe Citric Acid Market
Additives
Caustic Sulphite Caramel Market
Additives
Global PVC Stabilizer Market
Additives
Plasticizer Concrete Admixtures Market
Additives
FD and C Lakes Market
Additives
Calcium Tartrate Market
Additives
Packaging Coating Additives Market
Additives
Tricalcium Citrate Market
Additives
Antiknock Agents Market
Additives
Dipotassium Guanylate Market
Additives
Spain Anti Caking Market
Additives
Pectin Market
Additives
Citrate Ester Market