
 Global Functional Fluids Market | 2026-2036
Global Functional Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
Global Functional Fluids Market Foresight
Aftermarket fluid analysis and condition monitoring services is rewriting profit allocation across the value chain, pulling margin pools away from commodity volume sales. FUCHS PETROLUB SE leverages its laboratory network to anchor premium service contracts in European industrial corridors. Shell International B.V. competes through digital fluid diagnostics platforms that extend customer retention in marine and power generation accounts. ExxonMobil Corporation dominates bulk supply agreements with North American energy producers through backward integration into Group II/III base oil production.
Functional fluids are engineered liquid formulations—typically comprising base oils with additive packages containing anti-wear agents, viscosity modifiers, and corrosion inhibitors—manufactured through controlled blending processes to deliver friction reduction, thermal stability, and contaminant suspension across extreme operating temperatures. Hydraulic fluids command the largest revenue share within the product type dimension due to universal deployment in construction and agricultural machinery, while heat transfer fluids represent the fastest-expanding category as data center cooling and concentrated solar power installations multiply. Within the application dimension, power generation systems generate the most intensive per-unit consumption because turbine and transformer fluids require scheduled replacement cycles under ISO 6743 and ASTM D4378 protocols.
The U.S. EPA regulates metalworking fluid discharge under the Clean Water Act, forcing reformulation toward bio-based emulsifiers, while EU REACH restricts polycyclic aromatic hydrocarbon content in lubricant base stocks and the EU F-Gas Regulation constrains heat transfer fluid selections in cooling applications. China's MEE enforces VOC emission limits on metalworking fluid mist in machining facilities, compelling local blenders toward semi-synthetic alternatives. Stakeholders must monitor regulatory divergence between OECD chemical hazard classifications and emerging economy enforcement capacities when configuring regional product portfolios.
Market Dynamics
The functional fluids sector is experiencing a fundamental margin migration from commodity volume sales toward integrated fluid management services, as condition monitoring technologies and predictive maintenance contracts restructure how industrial buyers procure lubrication solutions.
Growth Catalysts
- Data center cooling expansion:Hyperscale cloud infrastructure buildouts in the United States, Germany, and Singapore are multiplying demand for synthetic heat transfer fluids capable of operating at sub-ambient temperatures without fluorinated compound content.
- REACH chemical disclosure mandates:The EU's tightening polycyclic aromatic hydrocarbon limits in lubricant base stocks are accelerating reformulation investments, creating premium pricing power for compliant synthetic alternatives across European manufacturing.
- Concentrated solar power deployment:Molten salt and synthetic thermal fluid systems in Spain, Morocco, and Chile are requiring specialized heat transfer chemistries with extended thermal stability ranges.
Market Restraints
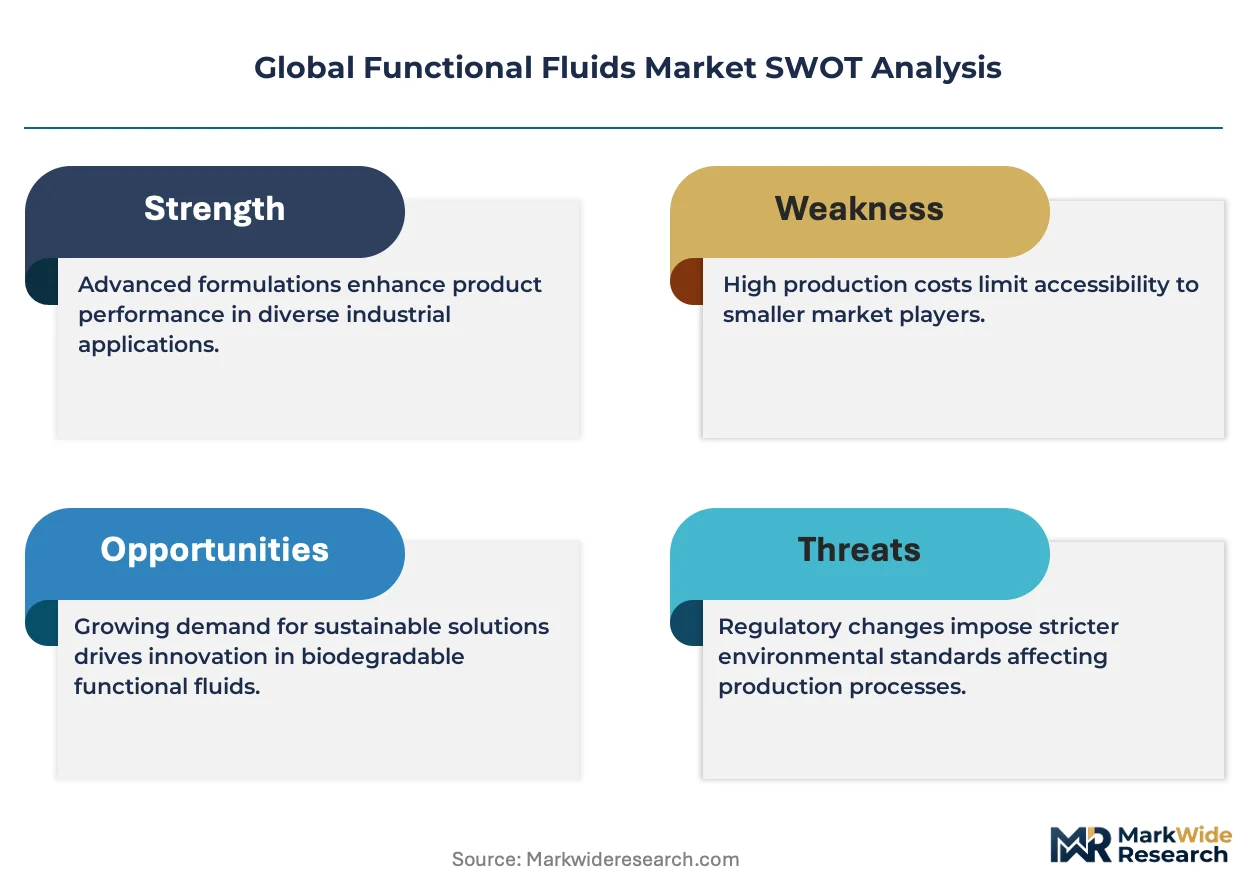
- Group II/III base oil supply concentration:North American and Middle Eastern refinery control over high-quality base stock output creates input cost volatility for independent blenders lacking backward integration into base oil production.
- EU F-Gas Regulation constraints:Phase-down schedules for fluorinated greenhouse gases are eliminating certain perfluorinated heat transfer fluid options, forcing rapid substitution toward less proven alternatives in precision cooling applications.
- Bio-based emulsifier performance gaps:Metalworking fluids formulated with plant-derived surfactants exhibit shorter sump life and microbial resistance issues compared to petroleum-based equivalents, limiting adoption in high-volume machining operations.
Strategic Opportunities
- Indian metalworking fluid modernization:India's Bureau of Indian Standards is implementing VOC emission protocols for machining facilities, creating first-mover advantage for semi-synthetic and synthetic fluid suppliers establishing local blending capacity.
- Marine lubricant service bundling:Condition monitoring platforms that combine onboard fluid analysis with predictive maintenance scheduling are penetrating deep-sea shipping fleets operating under International Maritime Organization sulfur regulations.
- China dual carbon policy alignment:The Ministry of Ecology and Environment's industrial efficiency mandates are accelerating heat pump and waste heat recovery installations, expanding demand for specialized thermal transfer chemistries in Jiangsu and Guangdong manufacturing clusters.
Industry Challenges
- Additive chemist talent scarcity:Formulation expertise combining tribology, thermal engineering, and regulatory compliance is concentrated among retiring specialists, constraining R&D pipeline velocity for mid-tier blenders.
- ISO 6743 certification timelines:Extended third-party testing protocols for turbine and hydraulic fluid approvals delay product launches by 18-24 months, compressing effective commercialization windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Functional Fluids Market |
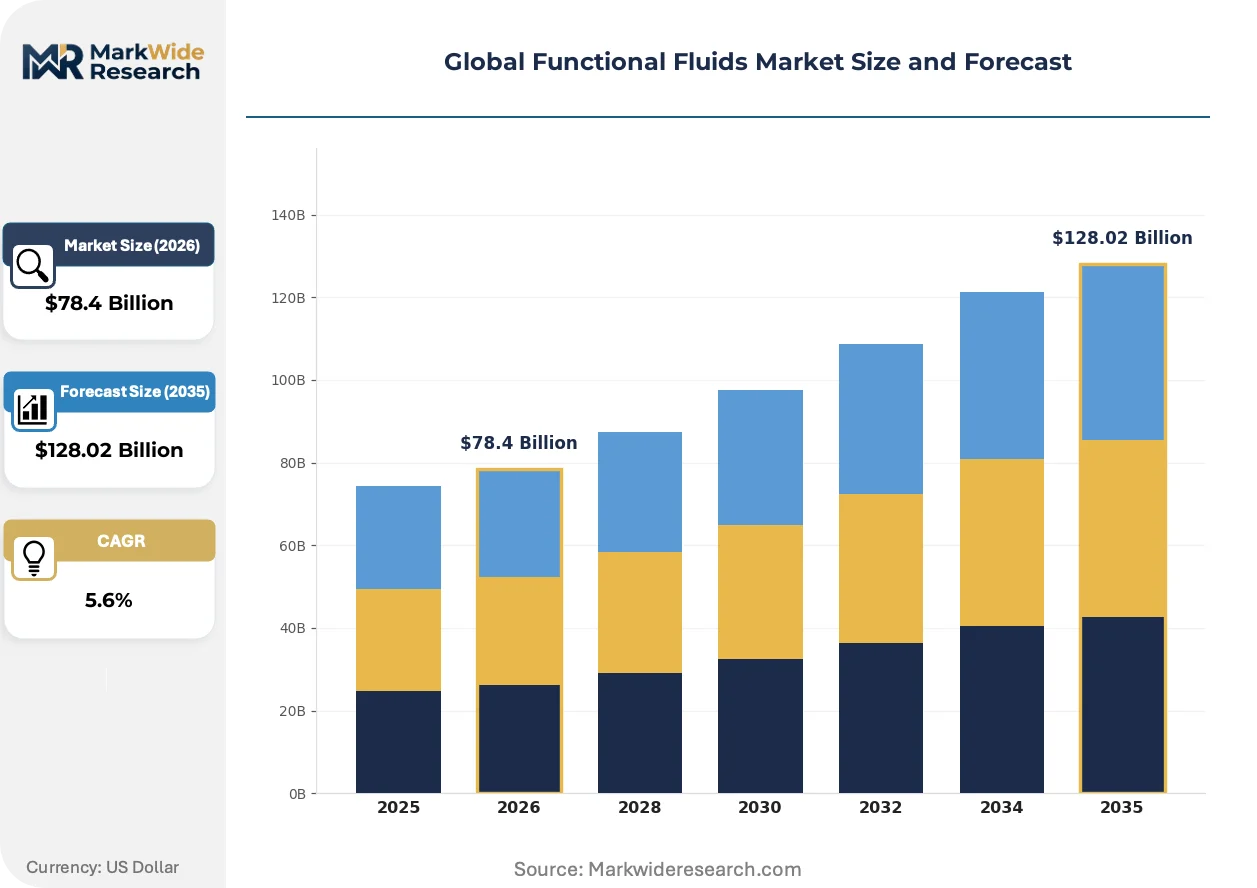
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $128.02 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Fluids, Heat Transfer Fluids, Metalworking Fluids, Compressor Oils, Gear Oils, Turbine Fluids Application: Manufacturing Equipment, Power Generation, Marine Systems, Aerospace Components, Construction Machinery, Agricultural Equipment End User Industry: Heavy Machinery Manufacturers, Aerospace Firms, Energy Producers, Marine Operators, Construction Companies, Agricultural Suppliers Packaging Type: Drums, Totes, Bulk Tanks, Carboys, Bottles, Cans |
| Companies Covered | BP International Limited, BASF SE, ExxonMobil Corporation, Idemitsu Kosan Co., Ltd., Petroliam Nasional Berhad, Shell International B.V., FUCHS PETROLUB SE, The Dow Chemical Company, Chevron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Functional Fluids Market Shifts & Advancements
Digital fluid diagnostics, regulatory chemistry restrictions, and procurement model restructuring are converging to transform how functional fluids are formulated, sold, and consumed across industrial end-uses.
Sensor-embedded lubrication systems is digitizing maintenance workflows across power generation and marine applications. Wind turbine operators in Denmark and offshore platforms in the North Sea are deploying real-time viscosity and particle-count monitors. This distributed sensing architecture is digitizing traditional scheduled-drain maintenance into condition-based intervention models.
REACH authorization procedures are systematically eliminating certain anti-wear additives from hydraulic fluid formulations. The European Chemicals Agency's sunset date enforcement is forcing zinc dialkyldithiophosphate substitution with ashless alternatives. Mobile construction equipment fleets operating across Germany and France are absorbing reformulation costs through extended drain interval claims.
Fluid analysis laboratories are unbundling from traditional distribution relationships to establish direct contractual ties with end-users. Independent testing networks in Texas, Rotterdam, and Singapore are capturing margin pools previously retained by bulk suppliers. Power plant operators in the United States and combined-cycle facilities in Japan are consolidating fluid procurement around integrated service agreements rather than spot volume purchases.
Global Functional Fluids Market Segmentation
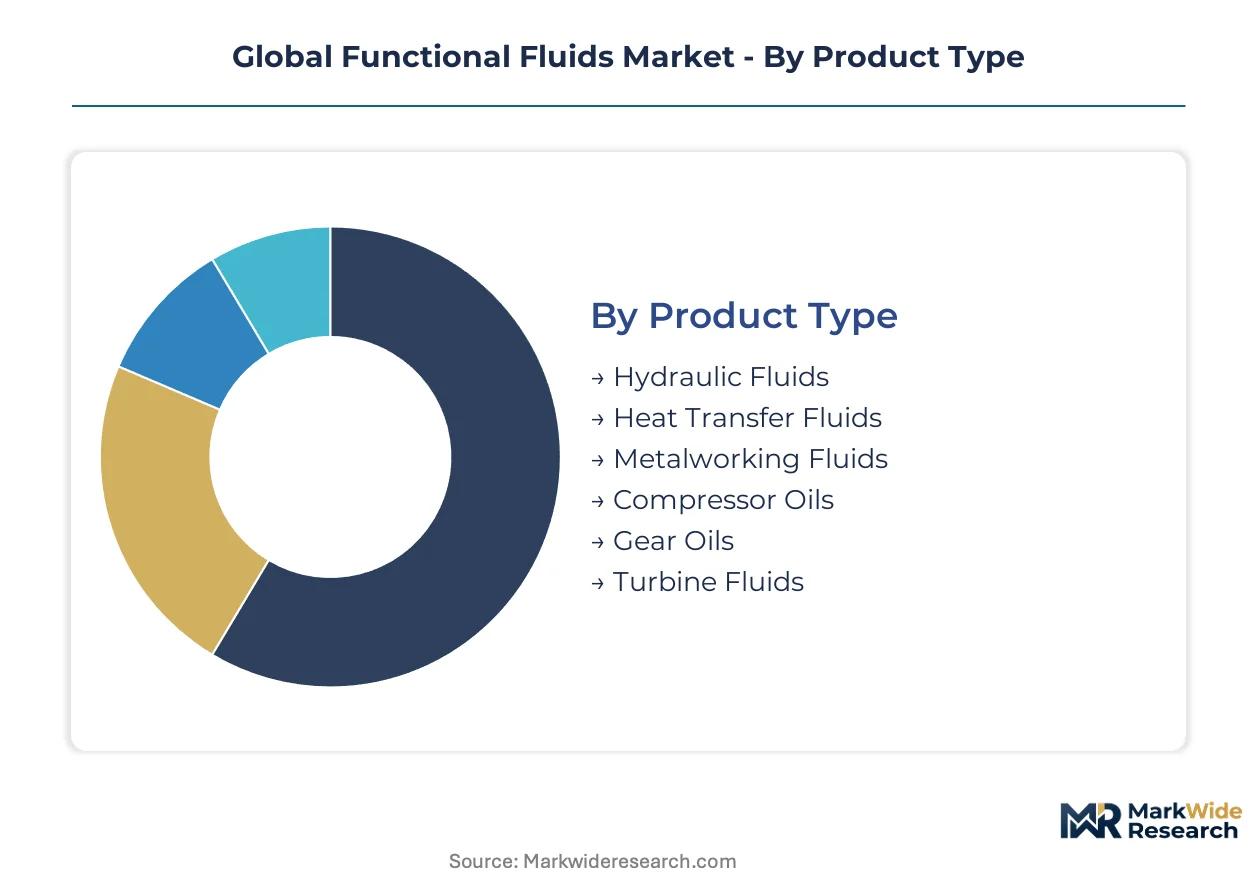
Segmentation in functional fluids reveals how formulation chemistry, equipment specifications, and procurement scale fragment demand across incompatible technical requirements. Buyers select fluid categories based on thermal operating ranges, contamination tolerance, and regulatory compliance rather than interchangeability.
Product Type:
Fluid chemistry spans hydraulic power transmission, thermal management, metal removal, and rotating equipment protection across incompatible viscosity and additive specifications.
- Hydraulic Fluids:Formulated with anti-wear additive packages and viscosity index improvers to transmit power in high-pressure piston and vane pump systems. Construction machinery fleets in Germany and agricultural equipment operators in Iowa generate concentrated bulk demand for zinc-containing and ashless variants under ISO 6743-4 classifications.
- Heat Transfer Fluids:Synthetic aromatic and silicone-based chemistries engineered for thermal stability across -40°C to 400°C operating windows. Data center cooling installations in Singapore and concentrated solar power facilities in Spain are multiplying demand for fluorinated-gas-free alternatives under EU F-Gas Regulation constraints.
- Metalworking Fluids:Emulsifiable oils and semi-synthetics delivering lubricity and chip flushing in machining operations.
- Compressor Oils:Oxidation-resistant formulations for rotary screw and reciprocating air compression systems.
- Gear Oils:Extreme-pressure lubricants for enclosed gearboxes in mining and wind turbine drivetrains.
- Turbine Fluids:Demulsible rust and oxidation inhibited oils meeting ASTM D4378 for steam and gas turbine lubrication.
Established volume favors hydraulic fluids; emerging adoption favors heat transfer fluids.
Application:
Equipment duty cycles and contamination exposure create divergent fluid consumption intensity and replacement scheduling.
- Power Generation:Turbine and transformer fluids require scheduled replacement under ISO 6743 and ASTM D4378 protocols, generating intensive per-unit consumption. Combined-cycle facilities in Japan and wind farms in Denmark anchor premium synthetic demand through condition-based maintenance contracts.
- Manufacturing Equipment:Metalworking and hydraulic systems in machining centers and stamping presses consume fluids through drag-out and mist emission.
- Marine Systems:Stern tube and cylinder lubricants for deep-sea shipping operate under IMO sulfur regulations.
- Aerospace Components:Precision machining and turbine engine testing require ultra-clean chemistries meeting SAE AS5780.
- Construction Machinery:Mobile hydraulic equipment in earthmoving and material handling drives seasonal bulk purchasing.
- Agricultural Equipment:Tractor hydraulics and combine harvester systems consume fluids through seasonal high-load operation.
Replacement intensity concentrates in power generation; fleet scale drives construction machinery volumes.
End User Industry:
Procurement sophistication separates integrated fluid management adopters from spot-volume purchasers.
- Energy Producers:Power utilities and independent generators consolidate procurement around laboratory-backed service agreements. Fluid analysis laboratories in Texas and Rotterdam capture margin pools through direct contractual relationships with combined-cycle and nuclear facility operators.
- Heavy Machinery Manufacturers:OEM factory-fill specifications and aftermarket service networks drive formulation lock-in.
- Aerospace Firms:AS9100-certified suppliers must demonstrate batch traceability and contamination control.
- Marine Operators:Deep-sea shipping fleets under IMO 2020 sulfur limits require cylinder oil reformulation.
- Construction Companies:Project-based purchasing favors spot market availability over technical service bundling.
- Agricultural Suppliers:Dealer networks and cooperative purchasing structures dominate rural fluid distribution.
Service integration advances fastest among energy producers; price sensitivity persists in construction procurement.
Packaging Type:
Logistics economics and contamination risk govern format selection across customer scale and access constraints.
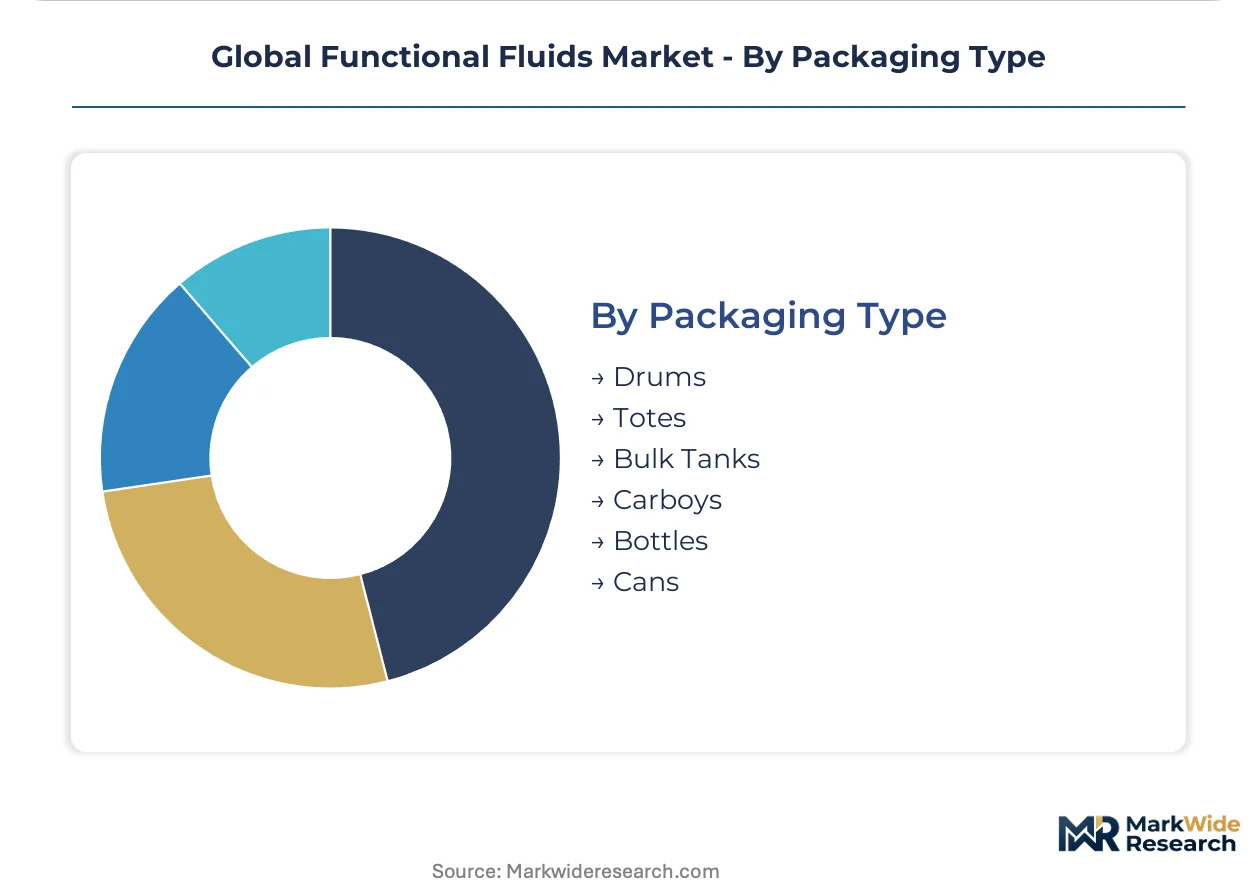
- Bulk Tanks:Direct-to-equipment delivery eliminates drum handling and disposal costs for high-volume consumers. Power plants in the United States and steel mills in India anchor regional distribution infrastructure through dedicated tankage and pipeline connections.
- Drums:55-gallon steel containers remain standard for mid-volume manufacturing and maintenance shops.
- Totes:Intermediate bulk containers reduce packaging waste for fluid changes in wind turbine nacelles.
- Carboys:Contamination-sensitive laboratory and aerospace applications require sealed glass or fluoropolymer vessels.
- Bottles:Small-volume top-up and sampling applications in field service operations.
- Cans:Retail and consumer-grade lubricant formats for light equipment maintenance.
Tankage dominates power generation intake; totes gain share in remote renewable installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Functional fluid consumption patterns diverge sharply by geography: European industrial corridors prioritize regulatory-compliant synthetics, Asian manufacturing clusters absorb bulk hydraulic volumes, and North American energy basins anchor premium turbine fluid demand through service-integrated procurement models.
United States
Power generation utilities and Permian Basin operators drive concentrated demand for turbine and hydraulic fluids. EPA enforcement of Clean Water Act discharge limits forces metalworking fluid reformulation toward bio-based emulsifiers. Texas and Louisiana host fluid analysis laboratories that capture margin pools through direct service contracts with combined-cycle facilities.
Germany
Automotive stamping presses and wind turbine drivetrains generate intensive metalworking and gear oil consumption. ECHA sunset date enforcement under REACH eliminates zinc dialkyldithiophosphate additives, accelerating ashless hydraulic fluid adoption. The Ruhr industrial corridor anchors FUCHS PETROLUB SE's laboratory network for premium service contracts.
China
Jiangsu and Guangdong manufacturing clusters multiply hydraulic fluid demand from construction machinery and metalworking operations. MEE enforcement of VOC emission limits on machining mist compels semi-synthetic fluid adoption. The dual carbon policy accelerates heat pump installations, expanding specialized thermal transfer chemistry demand.
India
Bureau of Indian Standards implementation of VOC protocols for machining facilities creates first-mover opportunity for synthetic fluid suppliers. Maharashtra and Gujarat industrial zones concentrate metalworking fluid consumption from automotive component manufacturing. Local blending capacity expansion targets import substitution in hydraulic and cutting fluid categories.
Japan
Combined-cycle power facilities and precision machining operations anchor premium synthetic demand through condition-based maintenance contracts. METI industrial efficiency mandates accelerate waste heat recovery system deployment. The Chubu and Kansai regions concentrate turbine fluid consumption from gas-fired generation infrastructure.
Global Functional Fluids Market Competitive Landscape
Capability concentration sits with specialty blenders commanding formulation chemistry expertise; scale advantage sits with integrated energy majors controlling captive base oil supply. The market structures around three tiers: multinational energy corporations with backward integration into Group II/III base stocks, European specialty lubricant houses with dense laboratory networks, and regional blenders serving price-sensitive construction and agricultural machinery fleets. Dominant competitive moves include laboratory service bundling to capture aftermarket margins and synthetic formulation investments to secure REACH compliance pricing power.
Within the integrated energy tier, ExxonMobil Corporation and Shell International B.V. occupy positions defined by captive base oil production and digital diagnostics platforms respectively. FUCHS PETROLUB SE exemplifies the specialty blender archetype through its European laboratory infrastructure. Among Asia-Pacific operators, Idemitsu Kosan Co., Ltd. and Petroliam Nasional Berhad represent national champion structures with regional distribution density.
| Leading Market Players |
|---|
| BP International Limited |
| BASF SE |
| ExxonMobil Corporation |
| Idemitsu Kosan Co., Ltd. |
| Petroliam Nasional Berhad |
| Shell International B.V. |
| FUCHS PETROLUB SE |
| The Dow Chemical Company |
| Chevron Corporation |
| Others |
Supply & Pricing Matrix
Single-source dependency on Group II/III base oil output from North American and Middle Eastern refineries determines both pricing tier spreads and supply chain shape in functional fluids. This concentration forces independent blenders into volatile spot purchasing while integrated majors capture margin through captive supply.
Pricing Analysis
Long-term offtake contracts dominate procurement among power generation utilities and energy producers, insulating these buyers from base oil price swings. Spot purchasing prevails in construction machinery and agricultural equipment segments where project-based consumption drives price sensitivity. Three-tier pricing structure across premium synthetic, standard mineral, and economy-grade fluids separates buyers by certification tier and service bundling intensity. Cost compression in economy-grade hydraulic fluids is intensifying because regional blenders in India and Southeast Asia compete on volume. Construction companies exhibit highest price sensitivity; power utilities demonstrate lowest sensitivity due to condition-based maintenance contracts.
Supply Chain Analysis
Export-control regimes on advanced additive chemistries and base stock refining technology limit technology transfer to emerging economy blenders. Geographic supply concentrates in the United States, Saudi Arabia, and South Korea for Group II/III base oil production. Raw material dependencies include polyalphaolefin synthetic base stocks, zinc dialkyldithiophosphate anti-wear additives, and viscosity index improvers derived from ethylene-propylene copolymers. Single-source vulnerability runs through concentrated refinery control over high-quality base stock output. Distribution runs through regional blending facilities co-located with industrial corridors, with bulk tankage serving high-volume consumers and drum/tote formats reaching remote renewable installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Functional fluids represent a service-attach opportunity where fluid analysis and condition monitoring contracts expand faster than commodity volume sales. Aftermarket laboratory services now capture margin pools previously retained by bulk suppliers.
For Market Incumbents: Build laboratory network density as the defensive moat against margin erosion. FUCHS PETROLUB SE's European infrastructure demonstrates how regional service coverage anchors premium contracts. Incumbents should deepen backward integration into Group II/III base oil production to neutralize input cost volatility threatening independent blenders. Digital diagnostics platforms extend customer retention in marine and power generation accounts where switching costs rise with integrated service bundling.
For New Entrants and Emerging Players: Establish a beachhead in India's metalworking fluid modernization wave as the Bureau of Indian Standards implements VOC emission protocols. First-mover advantage accrues to semi-synthetic and synthetic fluid suppliers building local blending capacity in Maharashtra and Gujarat. Target data center cooling applications in Singapore and Germany where fluorinated-gas-free heat transfer fluid demand multiplies under EU F-Gas Regulation constraints. Direct contractual ties with end-users bypass established distribution relationships.
For Investors and Strategic Acquirers: ECHA sunset date enforcement under REACH reshapes the acquisition landscape by eliminating zinc dialkyldithiophosphate additives and accelerating ashless formulation investments. Long-term viability favors specialty blenders with dense laboratory networks and synthetic formulation expertise over commodity volume players. Acquisition target archetype: mid-tier European or Asia-Pacific blenders with regional service infrastructure and REACH-compliant product pipelines. Signal to watch: consolidation announcements among independent blenders facing additive chemist talent scarcity and extended ISO 6743 certification timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Laboratory Network Expansion | Captures aftermarket margin pools through direct fluid analysis contracts with power utilities. |
| Backward Integration into Base Oil Production | Neutralizes input cost volatility for independent blenders lacking captive refinery supply. |
| Synthetic Formulation Investment | Secures REACH compliance pricing power as ECHA eliminates conventional anti-wear additives. |
| Digital Diagnostics Platform Deployment | Extends customer retention in marine and power generation through predictive maintenance contracts. |
| Local Blending Capacity in India | Positions for Bureau of Indian Standards VOC protocol implementation in metalworking fluids. |
Research Methodology
Initial hypotheses were tested against primary input from plant maintenance directors, OEM procurement teams, aftermarket service heads, and fluid analysis laboratory managers and refined through secondary validation. Primary research combined structured interviews with downstream industrial buyers and technical R&D directors at specialty blenders. Secondary sources included customs and trade data on base oil flows, SEC 10-K filings from integrated energy majors, American Chemistry Council and Cefic industry reports, and ASTM/ISO certification databases. Bottom-up demand modeling triangulated against top-down market sizing from refinery capacity and blending facility throughput data.
Demand-supply-balance framing anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product chemistry tier, end-use equipment category, procurement sophistication level, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to equipment installed base projections and fluid replacement interval assumptions. Industry-specific forecast inputs incorporated power generation capacity additions, data center cooling buildouts, and metalworking facility VOC compliance timelines.
Sensitivities concentrate around base oil price volatility, REACH authorization timelines for additive chemistries, and enforcement capacity variance between OECD and emerging economy regulators. Forecasts reflect assumptions on regulatory implementation schedules and equipment replacement cycles. Material shifts in EU F-Gas Regulation phase-down schedules or China's dual carbon policy enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Chemicals
Imidazole Market
Functional Chemicals
Paraformaldehyde Market
Functional Chemicals
L-Citrulline Market
Functional Chemicals
Ortho Phthalic Aldehyde Market
Functional Chemicals
Sodium Methylate Market
Functional Chemicals
Global Methylal Market
Functional Chemicals
Functional Polymer Market
Functional Chemicals
Jellyfish-Derived Peptide Ingredient Concepts Market
Functional Chemicals
Isophthaloyl Chloride Market
Functional Chemicals
2-Propylheptanol Market
Functional Chemicals
Tartrazine Market
Functional Chemicals
Ortho-Phthalaldehyde Market
Functional Chemicals
Paraben Market
Functional Chemicals
Succinimide Market
Functional Chemicals
Europe Formic Acid Market
Functional Chemicals
Succinic Acid Market