
 Food Grade Paraffin Market | 2026-2036
Food Grade Paraffin Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Paraffin Market Foresight
Confectionery manufacturing is repositioning toward higher-purity paraffin grades for chocolate and candy pan-coating applications. BASF Corporation leverages its technical-grade purification expertise to serve European confectionery accounts with food-contact certified outputs. ExxonMobil Corporation anchors North American supply through integrated refinery-to-specialty wax operations. Sasol Limited differentiates via Fischer-Tropsch derived microcrystalline wax with tighter oil content specifications than conventional slack wax routes.
Food grade paraffin denotes refined petroleum-derived saturated hydrocarbon mixtures meeting food-contact purity thresholds with oil content below 0.5% and congealing points typically ranging 52 to 66 degrees Celsius, manufactured via solvent dewaxing or hydrotreating of distillate feedstocks to serve moisture barrier and gloss functions in edible coatings. Fully refined paraffin commands the widest formulation acceptance among multinational confectioners due to superior color stability and neutral organoleptic profiles. Liquid paraffin represents the fastest-growing product type as beverage producers adopt it for bottle-sealing and anti-foam applications where pour-point depression matters. Microcrystalline wax captures concentrated margin pools in pharmaceutical coating where elastic film properties and adhesion exceed standard paraffin performance.
FDA food-contact substance notifications and EFSA food additive evaluations shape permissible migration limits and analytical certification requirements for paraffin used in direct food applications. China's SAMR enforces GB 1886.215 food additive standards that restrict polycyclic aromatic hydrocarbon content and mandate batch-level testing documentation for import clearance. REACH registration obligations within the European Union impose full toxicological dossier submission on paraffin wax manufacturers supplying volumes above one tonne annually. Stakeholders must monitor evolving purity thresholds across FDA, EFSA, and SAMR jurisdictions to preempt reformulation costs and supply qualification delays.
Market Dynamics
Confectionery manufacturers are repositioning procurement toward fully refined paraffin grades as FDA food-contact substance regulations tighten purity requirements for chocolate and candy coatings, compressing margins for slack wax suppliers while rewarding certified-refinery investments.
Growth Catalysts
- FDA Food-Contact Substance Notifications:Tightening migration limits for direct food applications are pulling multinational confectioners toward certified-refinery supply chains with documented analytical compliance.
- India's confectionery sector:Domestic brands scaling pan-coating operations are generating concentrated demand for food-grade coatings as modern retail penetration accelerates.
- Fischer-Tropsch synthesis:Synthetic wax production routes yielding tighter oil content specifications than conventional slack dewaxing are capturing formulation preference in pharmaceutical coatings.
Market Restraints
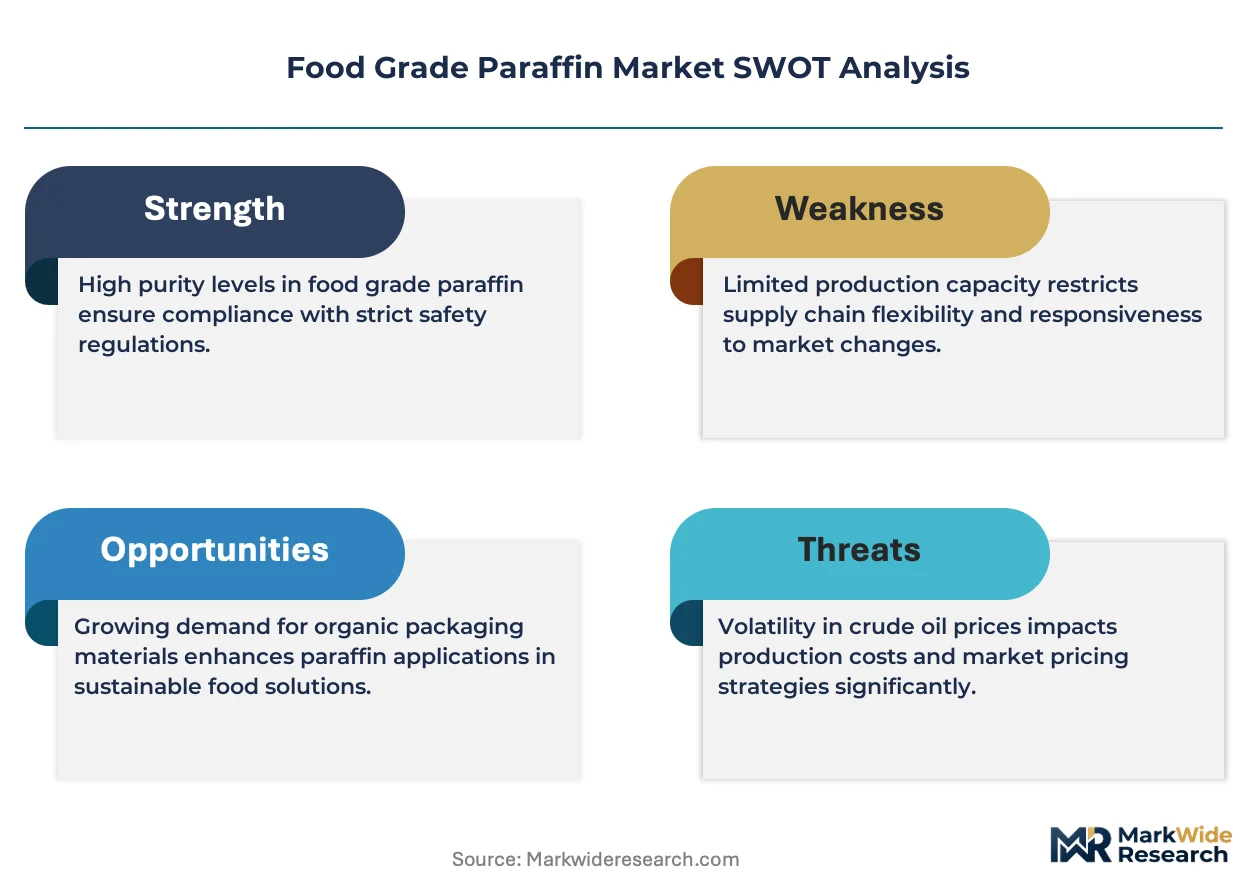
- Distillate feedstock volatility:Crude oil price swings transmit directly to paraffin base stock costs, squeezing margin stability for non-integrated compounders.
- Supply concentration in Gulf Coast refining:North American food-grade output clusters around integrated petrochemical complexes, creating geographic vulnerability to hurricane disruptions.
- Plant-based wax substitution:Carnauba and rice bran wax alternatives are displacing paraffin in premium confectionery segments where clean-label positioning commands price premiums.
Strategic Opportunities
- China's GB 1886.215 enforcement:Batch-level PAH testing mandates for import clearance are creating qualification barriers that certified-refinery suppliers can exploit to lock out uncertified competitors.
- Beverage anti-foam applications:Liquid paraffin pour-point depressants are penetrating bottle-sealing operations as craft brewing and functional beverage production scales.
- Pharmaceutical coating convergence:Elastic film properties of microcrystalline wax are opening formulation windows for controlled-release tablet coatings beyond standard paraffin performance envelopes.
Industry Challenges
- REACH toxicological dossier preparation:European manufacturers supplying volumes above one tonne annually face capital-intensive full dossier submission requirements under ECHA registration obligations.
- Multi-jurisdiction certification timelines:Simultaneous qualification across FDA, EFSA, and SAMR regimes stretches quality assurance bandwidth and delays product commercialization.
- Solvent dewaxing retrofit requirements:Legacy refineries must upgrade hydrotreating capacity to meet tightening color stability specifications for fully refined grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Paraffin Market |
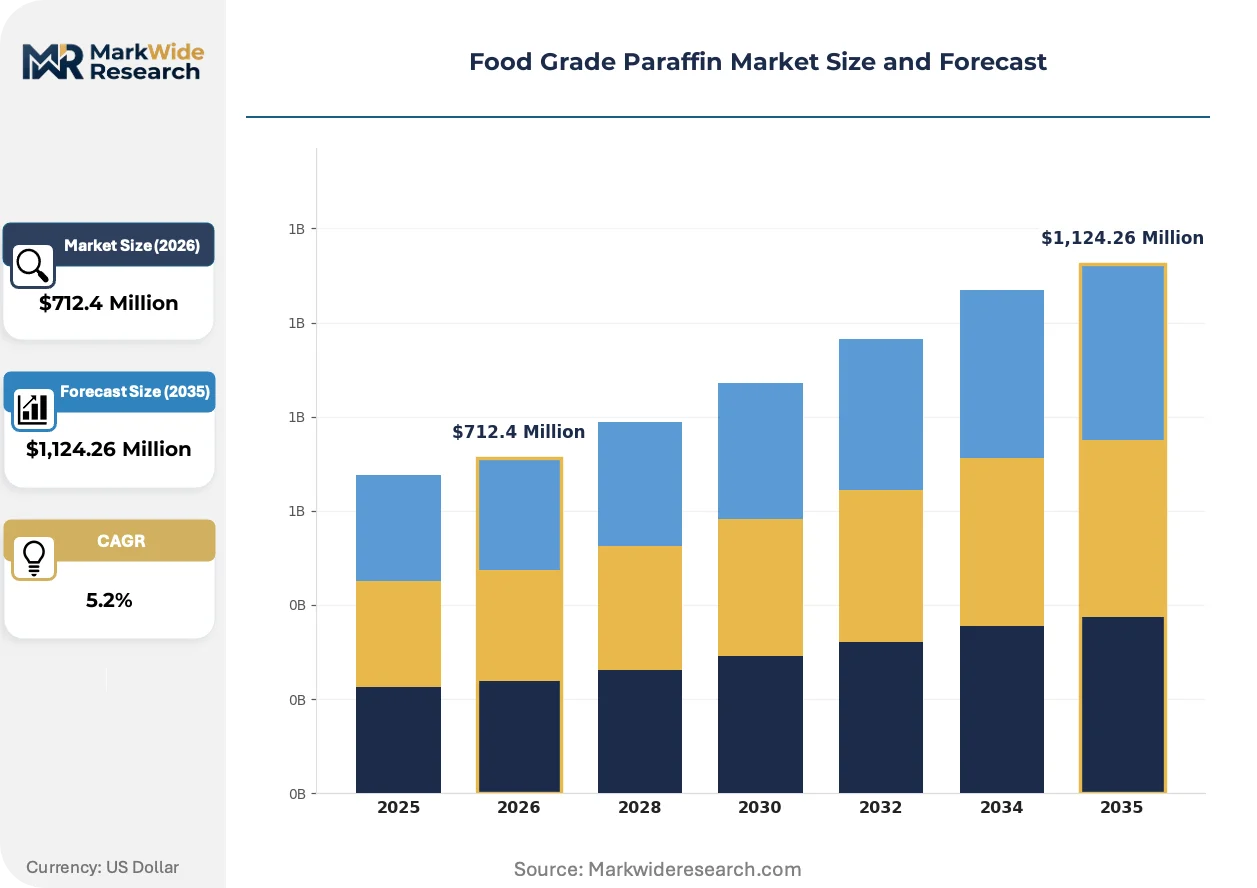
| Market Size in 2026 | $712.4 Million |
| Market Size in 2035 | $1,124.26 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Block Paraffin, Liquid Paraffin, Microcrystalline Wax, Fully Refined Paraffin, Semi-refined Paraffin Application: Food Coating, Packaging, Cosmetics, Pharmaceutical Coating, Candle Making, Lubricants End User Industry: Confectionery Manufacturers, Beverage Producers, Cosmetic Firms, Pharmaceutical Companies, Candle Manufacturers Packaging Type: Drums, Barrels, Tins, Bulk Containers, Pails |
| Companies Covered | BASF Corporation, The DOW Chemical Company, RADCO Industries, Solutia Inc., Huntsman Corporation, ExxonMobil Corporation, Sasol Limited, China Petrochemical Corporation (Sinopec), The International Group, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Paraffin Market Shifts & Advancements
Hydrotreating and solvent dewaxing technologies are advancing in parallel with regulatory purity thresholds, reshaping competitive advantage toward integrated refiners with in-house analytical certification capabilities.
Hydrotreating technology is consolidating quality differentiation in food-grade paraffin production. This catalytic hydrogenation process removes aromatic and sulfur compounds to sub-ppm levels, enabling congealing point precision within narrow bands. Major confectioners in Germany and Switzerland are mandating hydrotreated certificates for new supplier qualification. The technology is consolidating market position around refinery operators with captive hydrogen supply, compressing toll-processing margins for independent compounders.
EFSA food additive evaluations are tightening polycyclic aromatic hydrocarbon limits across direct food-contact applications. The 2023 updated guidance documents now require specific migration testing for benzo(a)pyrene and related compounds at ppb thresholds. European coating compounders are responding by dual-sourcing from refineries with demonstrated hydrotreating capability and third-party batch certification. This regulatory pressure is accelerating supplier consolidation toward integrated producers with established EFSA dossier histories.
Confectionery procurement patterns are rotating toward specification-driven supplier relationships with multi-year analytical transparency requirements. Brand manufacturers in India and Southeast Asia are displacing spot-market purchasing with contracted supply agreements tied to quarterly purity audits. This behavioral shift is most visible in Mumbai and Jakarta, where domestic chocolate brands building export capability must demonstrate FDA and EFSA alignment to access European and North American retail channels.
Food Grade Paraffin Market Segmentation
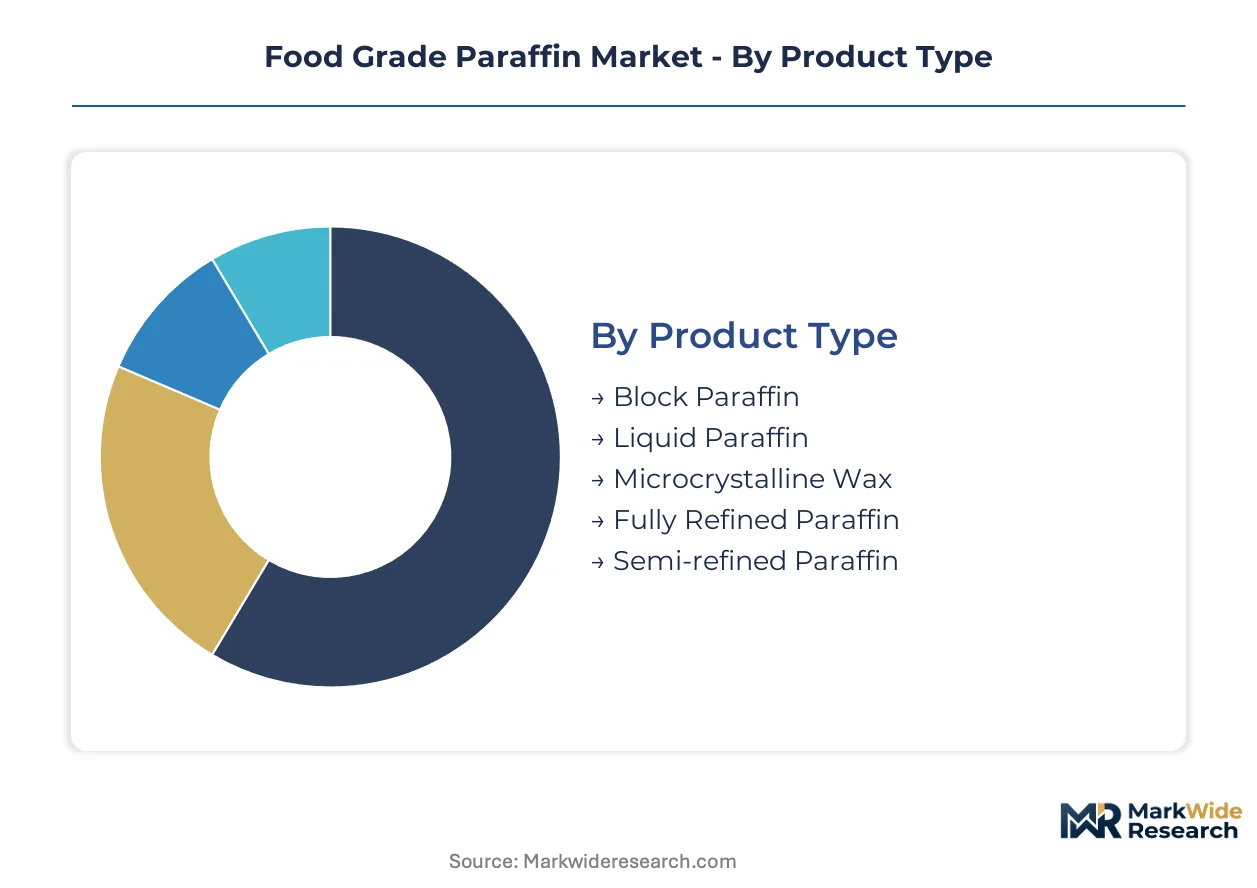
Paraffin procurement decisions hinge on purity certification, application temperature requirements, and regulatory jurisdiction alignment. Buyers evaluate hydrotreating documentation, oil content thresholds, and migration limit compliance before supplier qualification.
Product Type:
Confectionery procurement teams prioritize congealing point precision and color stability when selecting paraffin grades for direct food contact.
- Fully Refined Paraffin:Hydrotreated saturated hydrocarbons with oil content below 0.5% and congealing points of 52–66°C deliver superior color stability for chocolate pan-coating. German and Swiss confectioners mandate this grade for FDA and EFSA-aligned export formulations.
- Liquid Paraffin:Low-viscosity mineral oil with pour-point depression properties serves beverage bottle-sealing and anti-foam applications. Craft brewing operations in the United States and functional beverage producers in India are scaling procurement of this grade for process efficiency.
- Microcrystalline Wax:Fischer-Tropsch derived elastic films with tighter oil specifications than slack wax routes.
- Block Paraffin:Solid-form delivery for manual coating operations and small-batch confectionery.
- Semi-refined Paraffin:Intermediate purity grade facing margin compression from tightening FDA food-contact substance notifications.
Fully Refined Paraffin leads on scale; Liquid Paraffin leads on momentum.
Application:
End-use temperature exposure and regulatory scrutiny intensity determine formulation selection across coating and barrier functions.
- Food Coating:Moisture barrier and gloss functions for chocolate and candy pan-coating require fully refined grades with documented PAH compliance. India's domestic confectionery brands are expanding coated product lines for modern retail penetration.
- Pharmaceutical Coating:Controlled-release tablet films demand microcrystalline wax elasticity exceeding standard paraffin performance envelopes. EMA and FDA drug master file requirements drive supplier qualification toward integrated refiners with batch-level certification.
- Packaging:Direct food-contact barrier layers for paper and board applications.
- Cosmetics:Emollient and protective functions in lip care and skin formulations.
- Candle Making:Clean-burning properties for scented and decorative products.
- Lubricants:Food machinery applications requiring incidental contact approval.
Food Coating commands the largest volume commitment; Pharmaceutical Coating captures the steepest expansion trajectory.
End User Industry:
Regulatory export requirements and clean-label positioning drive divergent procurement strategies across consumer-facing sectors.
- Confectionery Manufacturers:Chocolate and candy producers require EFSA-aligned hydrotreated certificates for European market access. Mumbai-based domestic brands building export capability are displacing spot-market purchasing with multi-year analytical transparency contracts.
- Beverage Producers:Anti-foam and bottle-sealing applications favor liquid paraffin pour-point depressants. Functional beverage scaling in India and craft brewing expansion in the United States are generating concentrated demand for food-grade mineral oil.
- Pharmaceutical Companies:Controlled-release formulation houses seeking elastic film properties.
- Cosmetic Firms:Lip care and emollient applications with incidental ingestion pathways.
- Candle Manufacturers:Scented product lines requiring food-grade purity for premium positioning.
Confectionery Manufacturers anchor volume; Beverage Producers are climbing the fastest.
Packaging Type:
Volume scale and handling automation requirements determine container selection for refinery-to-compounder logistics.
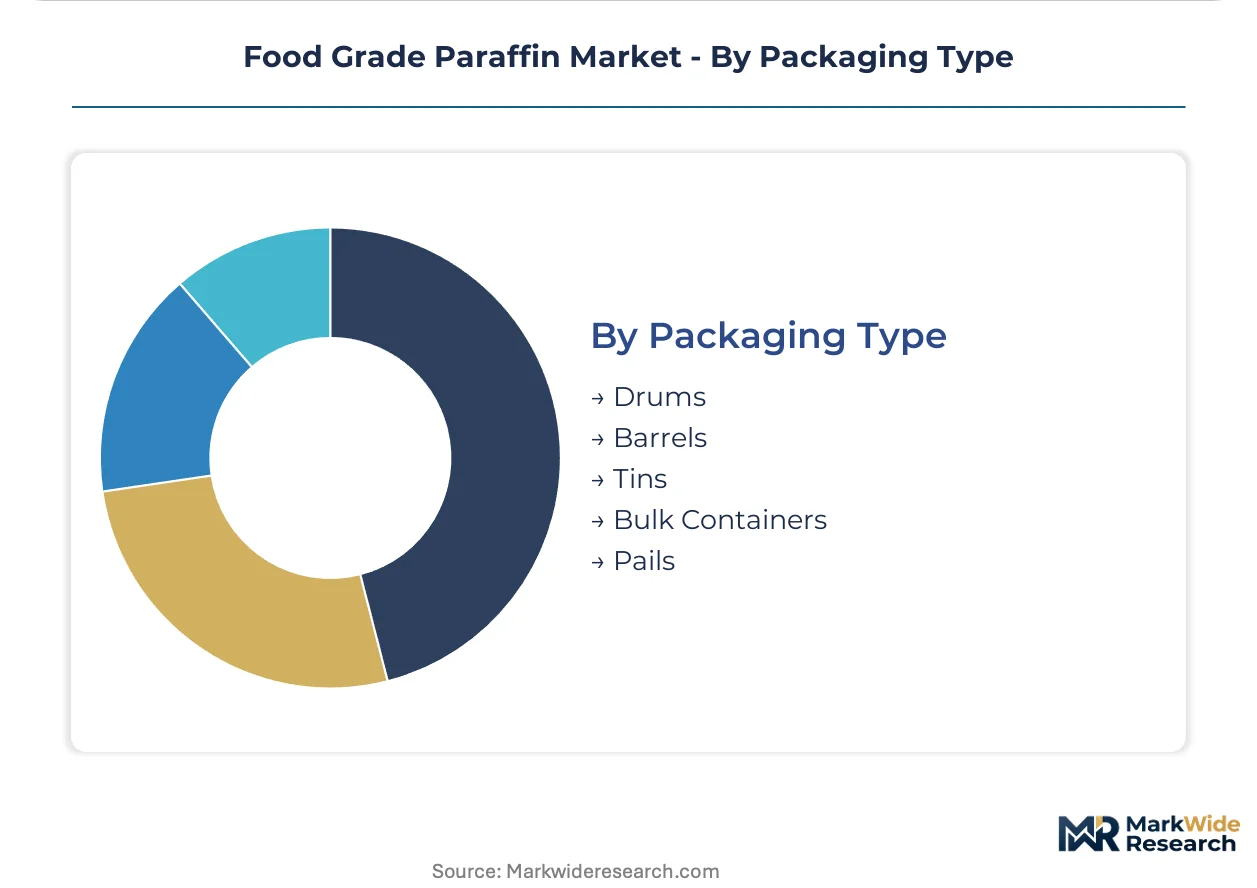
- Bulk Containers:Tank truck and railcar delivery for integrated confectionery operations with captive blending capacity. Gulf Coast refineries serving North American multinational accounts favor this format for cost efficiency at scale.
- Drums:Standard 200-liter steel containers for mid-volume compounders and regional distributors. European coating houses in Germany and Switzerland rely on drum formats for flexible inventory management across multi-product formulations.
- Barrels:Traditional wooden or fiber formats for artisanal and specialty applications.
- Pails:Small-batch access for R&D and pilot-scale production.
- Tins:Retail and direct-to-manufacturer specialty grades.
Bulk Containers dominate tonnage; Drums prevail across customer flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling food-grade paraffin production toward jurisdictions with lower compliance-cost structures, while tightening FDA and EFSA migration limits force reformulation investments in premium markets. This divergence rewards integrated refiners in cost-advantaged locations while squeezing independent compounders in high-regulation zones.
United States
Chocolate and candy manufacturers in Chicago and Pennsylvania are accelerating FDA food-contact substance notification submissions for fully refined grades. The FDA's tightening polycyclic aromatic hydrocarbon migration limits are compressing margins for non-integrated compounders. Gulf Coast integrated refineries around Houston anchor North American supply with captive hydrogen for hydrotreating.
Germany
EFSA-aligned confectioners in Cologne and Hamburg mandate hydrotreated certificates with batch-level benzo(a)pyrene testing for export formulations. REACH registration obligations impose capital-intensive toxicological dossier requirements on suppliers above one tonne annually. Bavarian coating houses are displacing spot-market purchasing with multi-year analytical transparency contracts.
China
SAMR enforcement of GB 1886.215 standards is creating import-clearance barriers for uncertified suppliers as domestic beverage producers scale liquid paraffin procurement. Yangtze River Delta refineries are upgrading hydrotreating capacity to meet tightening color stability specifications. Shanghai-based compounders are locking in certified-refinery supply chains to preempt qualification delays.
India
Mumbai and Delhi-NCR confectionery brands are expanding pan-coating operations for modern retail penetration, generating concentrated demand for food-grade coatings. FSSAI alignment with Codex standards is pulling procurement toward documented purity grades. Domestic brands building export capability must demonstrate FDA and EFSA compliance to access European and North American retail channels.
Brazil
São Paulo-based confectioners are adopting fully refined grades as ANVISA tightens food-contact substance purity requirements for chocolate exports. Craft brewing operations in Minas Gerais are scaling liquid paraffin procurement for bottle-sealing applications. Southeast Asian supply chain disruptions are pushing Brazilian compounders toward dual-sourcing from certified Gulf Coast refineries.
Food Grade Paraffin Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated refiners upgrade hydrotreating capability to capture tightening purity premiums. The market structures around three tiers: multinational petrochemical majors with captive feedstock, regional refiners with toll-processing flexibility, and specialized compounders with formulation expertise. Strategic archetypes include upstream-integrated hydrogen suppliers, certification-focused European specialists, and Asia-Pacific volume players. M&A activity and geographic licensing agreements represent the dominant competitive moves as players seek EFSA and FDA dossier coverage.
Among integrated petrochemical majors, BASF Corporation exemplifies the European certification-focused archetype with EFSA-aligned supply chains, while ExxonMobil Corporation anchors the North American upstream-integrated position through refinery-to-specialty wax operations. Sasol Limited occupies the synthetic production tier with Fischer-Tropsch derived positioning. These three entities represent the dominant competitive anchors across purity-tier, geography, and feedstock-strategy dimensions.
| Leading Market Players |
|---|
| BASF Corporation |
| The DOW Chemical Company |
| RADCO Industries |
| Solutia Inc. |
| Huntsman Corporation |
| ExxonMobil Corporation |
| Sasol Limited |
| China Petrochemical Corporation (Sinopec) |
| The International Group, Inc. |
| Others |
Supply & Pricing Matrix
Distillate feedstock indices on the Gulf Coast cascade through three pricing tiers for food-grade paraffin, compressing compounder margins when crude volatility spikes while rewarding integrated refiners with captive hydrogen supply. FDA certification premiums widen spreads between hydrotreated fully refined grades and semi-refined alternatives, redirecting procurement contracts toward certified-refinery supply chains.
Pricing Analysis
Distributor margins absorb the widest compression during feedstock volatility, forcing three-tier pricing structure across premium hydrotreated, standard solvent-dewaxed, and economy semi-refined levels. Price differentiation hinges on PAH certification documentation and volume scale, with multinational confectioners locking in annual contracts while spot buyers face escalating premiums. Pricing pressure stems from plant-based wax substitution in premium confectionery segments, eroding paraffin's share of clean-label formulations. Regional compounders exhibit highest price sensitivity due to toll-processing dependency, whereas integrated refiners with captive feedstock demonstrate lowest sensitivity.
Supply Chain Analysis
Refurbishment flows for industrial packaging containers circulate between Gulf Coast refineries and Midwest confectionery operations, reducing drum procurement costs for mid-volume compounders. Geographic supply concentrates in the United States, Germany, and China, with Yangtze River Delta refineries expanding hydrotreating capacity to serve domestic beverage producers. Raw material dependencies center on vacuum gas oil feedstocks, hydrogen supply for catalytic upgrading, and solvent recovery systems for dewaxing operations. Single-source vulnerability looms around hurricane disruptions to Texas refining complexes. Distribution runs through bulk tank trucks for integrated operations and drum networks for regional coating houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food-grade paraffin functions as a stable compounder market, with regulatory purity escalation driving steady value migration toward certified-refinery suppliers. Confectionery export requirements and pharmaceutical coating convergence sustain durable demand foundations.
For Market Incumbents: Anchor defensive positioning through backward integration into captive hydrogen supply and hydrotreating capacity at Gulf Coast or Yangtze River Delta hubs. Plant-based wax substitution in premium chocolate segments threatens margin pools; counter through EFSA-aligned batch certification investments that lock out uncertified competitors from European procurement channels. For New Entrants and Emerging Players: GB 1886.215 enforcement in China opens a window for qualified suppliers to capture import-clearance barriers that exclude uncertified competitors. Target liquid paraffin beverage applications in India's functional beverage scaling and Minas Gerais craft brewing expansion. Pursue toll-processing partnerships with established refineries to bypass capital-intensive hydrotreating investments. For Investors and Strategic Acquirers: Asymmetric upside sits with Fischer-Tropsch synthetic wax specialists possessing tighter oil specifications than conventional slack wax routes. Long-term viability favors producers with demonstrated FDA and EFSA dossier histories across the projection horizon. Monitor SAMR enforcement intensity for batch-level PAH testing mandates as inflection indicator for qualification-barrier profitability.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrotreating Capacity Expansion | Captures tightening FDA migration limits for fully refined grades in chocolate coatings. |
| Backward Integration into Hydrogen Supply | Secures cost advantage for catalytic upgrading at Gulf Coast refining complexes. |
| EFSA Dossier Certification Investment | Unlocks European confectionery procurement with documented benzo(a)pyrene compliance. |
| Long-term Supply Agreement with Beverage Producers | Locks in liquid paraffin volumes for India's functional beverage scaling. |
| Joint Venture with Pharmaceutical Formulators | Accesses controlled-release tablet coating demand for microcrystalline wax elasticity. |
Research Methodology
Bottom-up confectionery and beverage procurement modeling reconciled against top-down refinery capacity tracking forms the analytical core of this study. Primary interviews with plant managers at integrated petrochemical complexes, procurement leads at multinational confectioners, distribution channel partners in drum logistics, and technical R&D directors for coating formulations combined with secondary validation from FDA food-contact substance notifications, EFSA food additive evaluation databases, SAMR GB standards filings, and customs trade data for paraffin wax imports. Triangulation between demand-side consumption patterns and supply-side production capacities ensures cross-verified volume estimates.
Input-output matrices mapping distillate feedstock availability through hydrotreating and solvent dewaxing yields to end-use consumption by grade tier, application temperature requirements, packaging format, and regional regulatory cluster. Segmentation dimensions span fully refined versus liquid versus microcrystalline grades, food coating versus pharmaceutical coating versus beverage applications, and bulk versus drum distribution channels. CAGRs derive from regression analysis of historical procurement patterns against regulatory milestone timelines, incorporating crude oil price elasticity coefficients and substitution threat parameters from plant-based wax penetration rates.
Revisions become necessary when SAMR escalates GB 1886.215 enforcement timelines, EFSA tightens PAH migration thresholds, or hurricane disruptions exceed historical Gulf Coast outage frequencies. Forecasts reflect documented assumptions regarding regulatory alignment trajectories and feedstock cost transmission mechanisms. Practitioners should monitor FDA food-contact substance notification backlogs and FSSAI Codex alignment progress for early signals of qualification timeline compression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Organic Sulfur Market
Specialty Chemicals
Asia Pacific Methyl Glucose Market
Specialty Chemicals
Eco-Friendly Plasticizers Market
Specialty Chemicals
Distarch Phosphate Market
Specialty Chemicals
Erucic Acid Market
Specialty Chemicals
Bismuth Oxychloride Market
Specialty Chemicals
Medical Propellants Market
Specialty Chemicals
Organosilicon Electrolyte Market
Specialty Chemicals
L-Ergothioneine Market
Specialty Chemicals
Panthenol Market
Specialty Chemicals
Global Chitin Market
Specialty Chemicals
5-Hydroxymethylfurfural Market
Specialty Chemicals
Global Caffeic Acid Market
Specialty Chemicals
Biobased Propylene Glycol Market
Specialty Chemicals
Natural Insect Repellent Market
Specialty Chemicals
Hyaluronic Acid Products Market