
 United States Construction Chemicals Market | 2026-2036
United States Construction Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
United States Construction Chemicals Market Analytics
ASTM C494 certification for chemical admixtures is bifurcating the competitive landscape between qualified suppliers and commodity challengers. BASF leverages its backward integration into acrylic polymer intermediates to sustain formulation consistency across regional batch plants. Sika AG anchors its position through specialized distribution partnerships with ready-mix concrete producers in the Southeast and Southwest. GCP Applied Technologies differentiates via proprietary rheology-modifying technologies that meet stringent Department of Transportation specifications.
Construction chemicals encompass specialty formulations including concrete admixtures, bonding agents, protective coatings, and curing compounds engineered to enhance durability, workability, and environmental resistance of built structures. These products typically incorporate Portland cement, synthetic polymers such as styrene-butadiene or acrylic latex, and performance additives including superplasticizers, accelerators, and corrosion inhibitors to achieve specified compressive strengths, permeability coefficients, and service-life targets. Admixtures command the deepest margin pools as specification-grade polycarboxylate ethers and shrinkage-reducing compounds carry premium pricing tied to performance guarantees. Infrastructure applications represent the fastest-expanding demand channel as federal transportation reauthorization directs funding toward bridge deck rehabilitation and airport runway reconstruction. Residential contractors remain the most price-sensitive end-user segment, driving volume through standard-grade sealants and tile adhesives with limited technical differentiation.
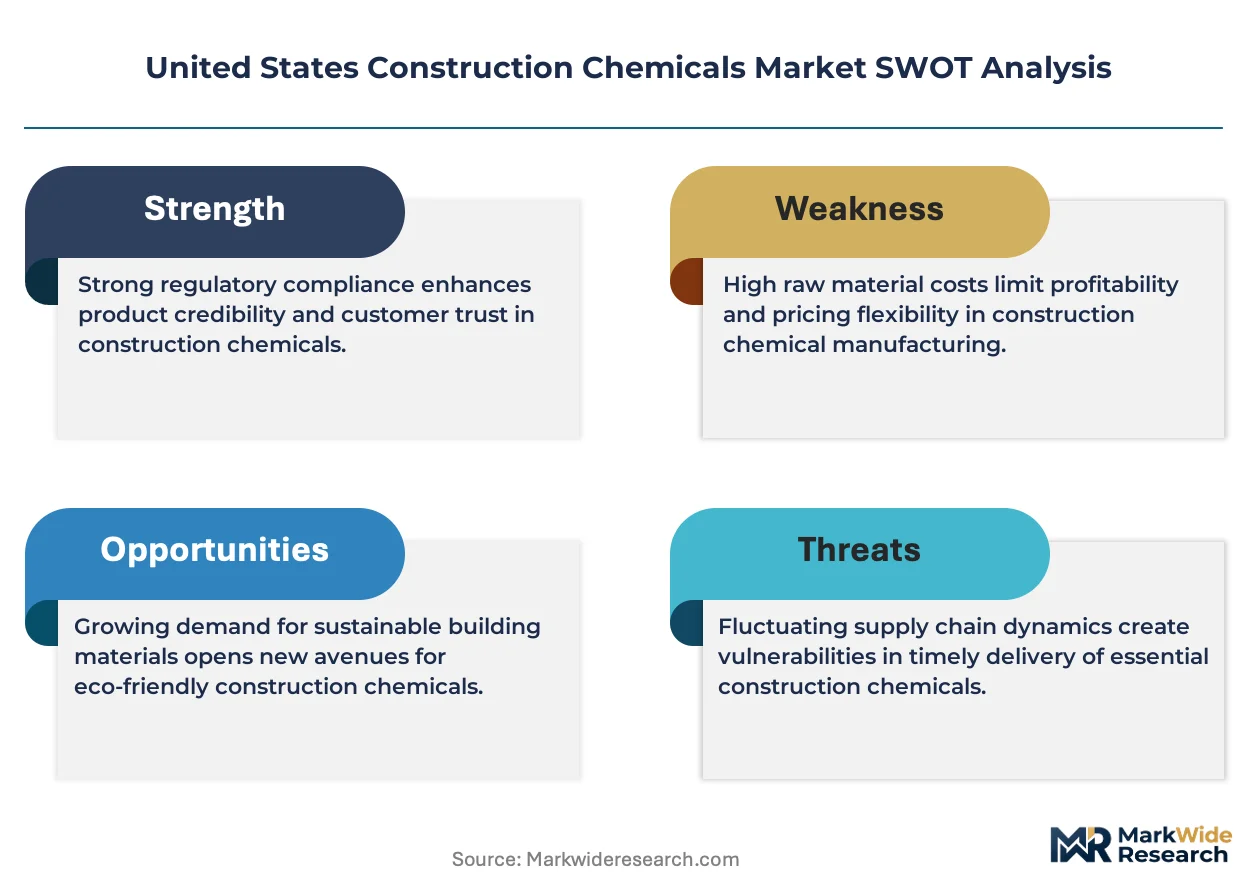
EPA regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent-based product formulations, while OSHA exposure limits on crystalline silica in cementitious products mandate dust-suppression admixtures at commercial job sites. State-level Buy America provisions embedded in infrastructure procurement rules restrict eligible sourcing for federally funded projects, reshaping supplier qualification requirements. Stakeholders must monitor evolving USGBC LEED v5 criteria and state-adopted International Green Construction Code amendments as these frameworks progressively embed embodied-carbon thresholds into material specifications.
Market Dynamics
EPA's tightening VOC limits on concrete sealants and coatings are forcing manufacturers toward water-based polymer reformulations, compressing margins for solvent-dependent producers while rewarding early movers with compliant product portfolios.
Growth Catalysts
- Infrastructure reauthorization:Federal transportation funding directs procurement toward bridge deck rehabilitation and airport runway reconstruction, expanding specification-grade admixture volumes.
- Coastal resilience mandates:Florida and Gulf Coast states prioritize structural longevity in public procurement, accelerating demand for corrosion inhibitors and waterproofing systems.
- OSHA crystalline silica rules:Exposure limits mandate dust-suppression admixtures at commercial job sites, creating pull-through for specialized formulation suppliers.
Market Restraints
- Acrylic monomer volatility:Petrochemical feedstock fluctuations compress formulation margins for water-based polymer producers unable to pass through input costs.
- Buy America provisions:State-level sourcing restrictions embedded in federally funded projects disqualify non-domestic suppliers from infrastructure procurement pools.
- Cement chemistry limitations:Incompatibility between certain superplasticizers and supplementary cementitious materials restricts specification flexibility in high-volume fly ash mixes.
Strategic Opportunities
- Texas metro corridor expansion:Population migration concentrates residential and commercial construction activity, creating procurement density for regional batch plant partnerships.
- LEED v5 embodied-carbon thresholds:USGBC criteria progressive embedding drives specification preference toward low-carbon admixture formulations with verified environmental product declarations.
- Ready-mix producer direct channels:Bypassing traditional distribution through specialized technical service partnerships captures margin and locks in specification influence.
Industry Challenges
- ASTM C494 certification timelines:Extended qualification periods for chemical admixtures delay market entry for reformulated products, favoring incumbents with existing approvals.
- Technical field service scarcity:Shortage of qualified concrete technologists capable of troubleshooting complex rheology modifications limits specification support capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Construction Chemicals Market |
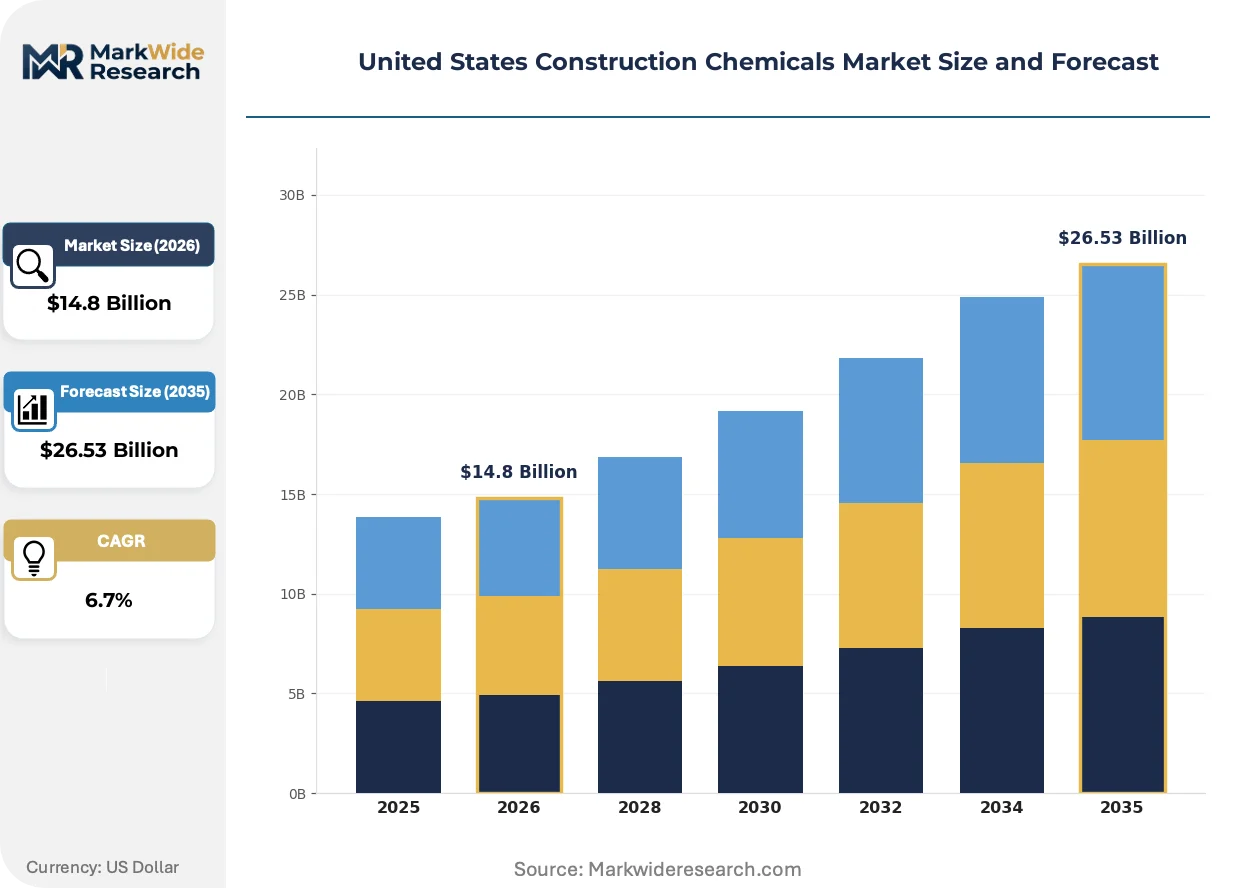
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Admixtures, Sealants, Adhesives, Coatings Application: Residential, Commercial, Infrastructure, Industrial Material Type: Polymer, Cement, Water, Additive End User: Contractors, Builders, Engineers, Architects |
| Companies Covered | BASF, Sika AG, MAPEI S.p.A., Saint-Gobain, RPM International, Dow Chemical Company, Huntsman Corporation, GCP Applied Technologies, 3M Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Construction Chemicals Market Evolving Landscape
Water-based polymer chemistry is displacing solvent systems across protective coatings and sealants, while specification-grade admixtures capture deeper margin pools through performance-guaranteed supply contracts.
Polycarboxylate ether superplasticizers with tailored side-chain architectures deliver extended slump retention without set retardation, enabling high-performance concrete placement in challenging ambient conditions. State DOTs in Texas and California specify these chemistries for infrastructure durability guarantees. The technology is bifurcating the admixture market between qualified suppliers with proprietary polymer synthesis capabilities and commodity challengers dependent on generic formulations.
EPA National Emission Standards for Hazardous Air Pollutants constrain solvent-based product formulations in manufacturing facilities, compelling capital investment in waterborne production lines and emission control systems. Manufacturers with coastal plant locations face additional state-level air quality management district rules. Protective coatings segment bears the heaviest compliance burden, with product reformulation cycles extending 18-24 months for full qualification.
Specification-driven procurement now embeds extended performance warranties into chemical admixture supply agreements, shifting risk from contractors to formulation suppliers. Ready-mix concrete producers in the Southeast negotiate multi-year technical service contracts bundling product supply with mix optimization support. California and Florida markets exhibit the most advanced warranty terms, with suppliers guaranteeing compressive strength and permeability coefficients at 56 and 91 days.
United States Construction Chemicals Market Segmentation
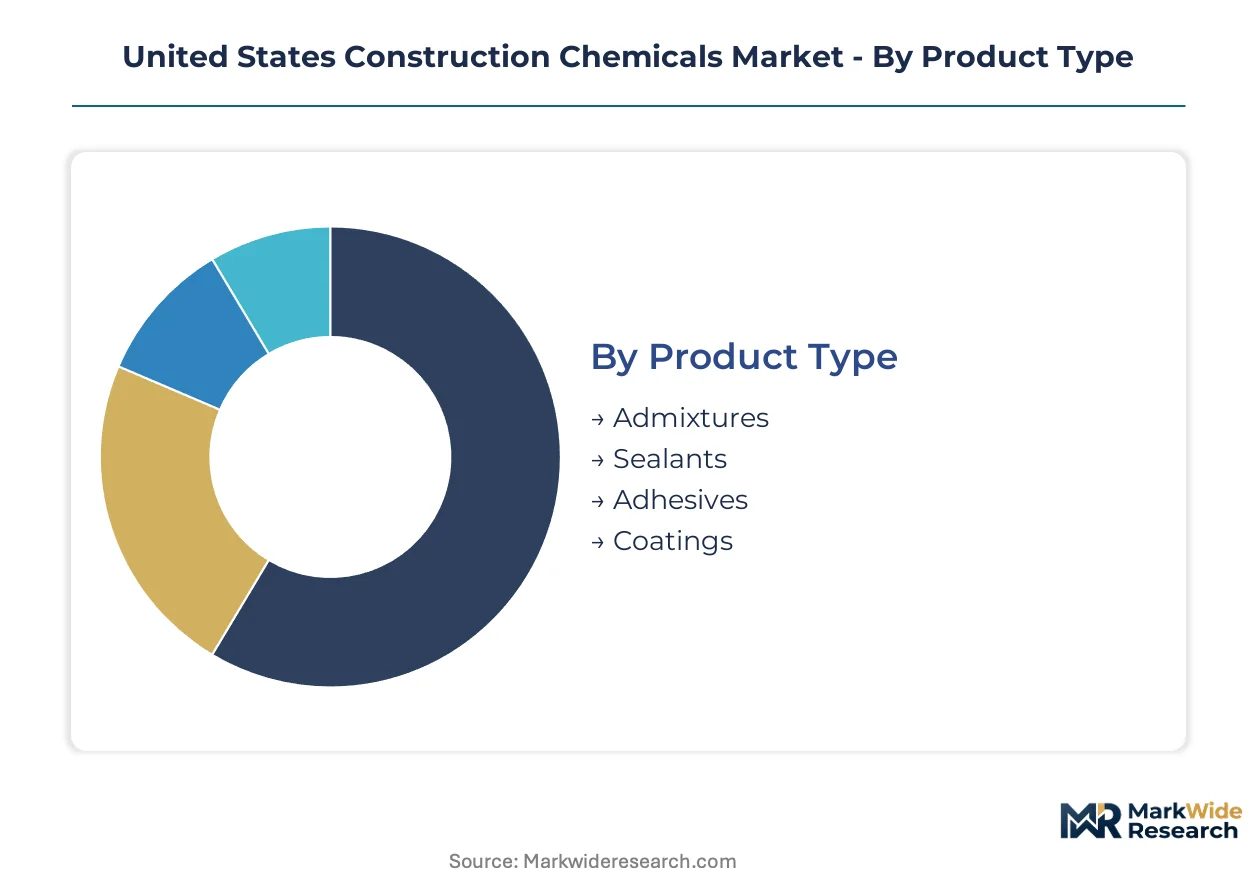
Construction chemicals fragment across multiple demand dimensions, with product chemistry and application context determining margin structure. Specification intensity varies sharply between infrastructure-grade admixtures and commodity residential sealants, reshaping how suppliers allocate technical service resources.
Product Type:
Domestic production dominates admixtures and sealants, while coatings sourcing includes imported specialty resins subject to tariff exposure.
- Admixtures:Polycarboxylate ether superplasticizers and shrinkage-reducing compounds incorporate synthetic polymer backbones engineered for slump retention and durability guarantees. State DOTs in Texas and California specify these chemistries for bridge deck and airport runway projects, with procurement tied to extended performance warranties.
- Sealants:Water-based acrylic and polyurethane formulations displace solvent systems under EPA VOC constraints, compressing margins for reformulation laggards while rewarding early movers with compliant portfolios. Florida coastal resilience spending accelerates demand for marine-grade waterproofing systems.
- Adhesives:Cementitious and epoxy-based bonding agents serve tile setting and structural anchoring applications with formulation flexibility for ambient cure conditions.
- Coatings:Protective systems for concrete and steel substrates face extended qualification cycles of 18-24 months under NESHAP compliance requirements.
Admixtures hold the largest share; momentum sits with sealants as regulatory pressure accelerates water-based conversion.
Application:
Cost stratification separates specification-grade infrastructure from price-sensitive residential procurement, with commercial occupying the contested middle tier.
- Infrastructure:Federal transportation reauthorization directs funding toward bridge rehabilitation and runway reconstruction, expanding volumes for certified admixture suppliers. Department of Transportation specifications mandate ASTM C494 compliance, creating qualification barriers for new entrants.
- Residential:Standard-grade tile adhesives and basement waterproofing systems drive volume through contractor channels with limited technical differentiation and compressed margins.
- Commercial:Mid-rise construction and retail fit-outs balance performance requirements against budget constraints, favoring regional batch plant partnerships.
- Industrial:Manufacturing facility floors and containment structures demand chemical-resistant epoxy systems with specialized installation protocols.
Infrastructure commands the deepest margin pools; residential delivers volume scale at thinner returns.
Material Type:
Feedstock volatility concentrates in petrochemical-derived polymers, while cement-based materials track construction activity cycles.
- Polymer:Acrylic latex and styrene-butadiene emulsions form the backbone of water-based sealants and coatings, with input costs tied to propylene and butadiene spot markets.
- Cement:Portland cement and supplementary cementitious materials serve as the mineral base for grouts, repair mortars, and cementitious waterproofing systems.
- Water:Carrier phase for waterborne formulations, with quality specifications affecting cure chemistry and final performance properties.
- Additive:Corrosion inhibitors, accelerators, and rheology modifiers deliver targeted performance enhancements at low dosage rates.
Polymer formulations capture premium positioning; cement-based products scale through volume efficiency.
End User:
Technical capability gaps separate engineer-driven specification from contractor-led procurement, determining channel strategy for suppliers.
- Contractors:Field installation crews prioritize workability and cure speed, driving demand for admixtures with extended slump retention and rapid-strength gain properties.
- Builders:Production home developers source standard-grade sealants and adhesives through distributor channels with consolidated purchasing leverage.
- Engineers:Structural and materials engineers embed performance guarantees into project specifications, shifting risk to formulation suppliers for infrastructure durability targets.
- Architects:Design professionals specify aesthetic and environmental performance criteria, including LEED v5 embodied-carbon thresholds and environmental product declarations.
Engineers control specification authority; builders concentrate procurement volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate Highway System and major port complexes anchor regional procurement patterns, with state transportation departments directing specification-grade admixture volumes toward bridge rehabilitation and coastal resilience projects.
Texas
Metro corridor expansion in Dallas-Fort Worth and Houston concentrates residential and commercial batch plant activity. State DOT specifications mandate ASTM C494-compliant polycarboxylate ether superplasticizers for highway infrastructure. The I-35 corridor from San Antonio to Dallas represents the densest regional procurement cluster for ready-mix partnerships.
California
Seismic retrofit mandates and airport runway reconstruction at LAX and SFO drive specification-grade waterproofing demand. Caltrans adopts stringent Department of Transportation specifications that extend performance warranties to 91-day permeability coefficients. The Los Angeles-Long Beach port complex anchors marine-grade coating procurement for coastal infrastructure.
Florida
Coastal resilience spending prioritizes corrosion inhibitors and waterproofing systems for bridge deck longevity in salt-air environments. State procurement rules embed extended durability guarantees into public infrastructure contracts. The Miami-Tampa-Orlando triangle concentrates demand for marine-grade sealant formulations.
Illinois
Chicago O'Hare runway reconstruction and freight rail intermodal expansion sustain specification-grade concrete volumes. IDOT bridge rehabilitation programs accelerate demand for shrinkage-reducing compounds in freeze-thaw cycling conditions. The Calumet industrial corridor hosts specialized batch plant technical service partnerships.
Washington
Seattle-Tacoma port modernization and earthquake preparedness spending drive high-performance concrete specifications. State DOTs specify low-carbon admixture formulations with environmental product declarations for public projects. The Puget Sound region leads Pacific Northwest adoption of LEED v5-aligned procurement criteria.
United States Construction Chemicals Market Competitive Landscape
Listed leaders compete with private specialists across formulation certification and technical service capabilities, producing a tiered structure where ASTM C494 qualification separates specification-grade suppliers from commodity challengers. Market concentration favors incumbents with backward integration into polymer intermediates and established state DOT approval portfolios. Three archetypes dominate: integrated chemical conglomerates with captive raw material supply, specialized construction material firms with regional batch plant partnerships, and diversified industrial coating suppliers pivoting toward water-based compliance. Competitive dynamics center on M&A activity targeting regional admixture formulators and strategic partnerships with ready-mix concrete producers that lock in specification influence.
Within the integrated chemical tier, BASF and Dow Chemical Company occupy positions defined by upstream control over acrylic polymer intermediates. Sika AG exemplifies the specialized construction material archetype through its technical service model. GCP Applied Technologies represents the specification-driven technology tier with proprietary rheology-modifying capabilities.
| Leading Market Players |
|---|
| BASF |
| Sika AG |
| MAPEI S.p.A. |
| Saint-Gobain |
| RPM International |
| Dow Chemical Company |
| Huntsman Corporation |
| GCP Applied Technologies |
| 3M Company |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory cycles at regional batch plants concentrate procurement leverage among ready-mix concrete producers with multi-site coverage, amplifying price compression on standard-grade sealants while insulating specification-grade admixture premiums. This lead-time band reflects the tension between just-in-time polymer sourcing and DOT-mandated stockpile requirements for certified products.
Pricing Analysis
Volume-discount tiering separates ASTM C494-certified polycarboxylate ether superplasticizers from commodity-grade alternatives, with state DOT qualification status commanding premium positioning. Price differentiation rests on certification investment and technical service bundling rather than raw material quality alone. Cost compression in water-based sealants is intensifying because acrylic monomer volatility prevents full cost pass-through. Residential contractors exhibit the highest price sensitivity, while infrastructure engineers prioritize performance guarantees over unit economics.
Supply Chain Analysis
Strategic stockpile preferences dominate specification-grade admixture procurement, with DOT-approved producers maintaining 60-90 day resin inventories to guarantee batch consistency across multi-year infrastructure contracts. Domestic polymer synthesis anchors supply for water-based formulations, while specialty epoxy resins for industrial coatings draw from German and Japanese chemical producers. Single-source vulnerability concentrates in propylene-derived acrylic intermediates. Distribution runs through ready-mix concrete producer direct channels and specialized construction chemical distributors serving contractor segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification-grade admixture supply contracts are evolving toward platform-economics structures where technical service bundling locks in multi-year procurement relationships, mirroring the interoperability shifts seen in software-defined infrastructure procurement.
For Market Incumbents: Fortify ASTM C494 certification portfolios against commodity challengers by accelerating water-based polymer reformulation timelines ahead of EPA NESHAP enforcement waves. Backward integration into acrylic monomer production secures margin control against petrochemical feedstock volatility. Prioritize technical service team expansion in Texas and Florida metro corridors where procurement density is accelerating. For New Entrants and Emerging Players: Anchor in dust-suppression admixture segments where OSHA crystalline silica compliance creates immediate specification pull-through without extended DOT qualification timelines. The Southeast ready-mix producer channel offers the most penetrable entry point through specialized technical service partnerships rather than distributor relationships. Lead with rapid-strength gain formulations targeting commercial mid-rise contractors facing schedule compression pressures. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because EPA and OSHA compliance burdens favor consolidated suppliers with capital-intensive reformulation capabilities over fragmented commodity producers. Target acquisition archetypes include regional admixture formulators with existing state DOT approval portfolios and technical service density in high-growth metro corridors. The signal to watch is LEED v5 embodied-carbon threshold adoption velocity in public procurement rules.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomers | BASF's captive polymer supply secures formulation consistency against propylene price volatility. |
| Water-Based Production Line Conversion | EPA NESHAP compliance requires 18-24 month qualification cycles for protective coatings reformulation. |
| Ready-Mix Producer Technical Partnerships | Sika AG's Southeast distribution alliances lock in specification influence at batch plant level. |
| ASTM C494 Certification Expansion | GCP Applied Technologies' proprietary rheology modifiers meet stringent DOT durability specifications. |
| LEED v5 Environmental Product Declaration Investment | Washington State DOT procurement rules already embed low-carbon admixture preferences. |
Research Methodology
Desk research of customs trade data, ACC industry reports, SEC 10-K filings, and state DOT procurement records preceded structured interviews with ready-mix concrete plant managers, construction chemical procurement leads at regional batch operators, technical R&D directors at formulation suppliers, and distribution channel partners serving contractor segments. Bottom-up volume triangulation across product-grade segments was cross-validated against top-down infrastructure spending allocation models.
Variance decomposition across the projection horizon isolates volume drivers by application segment, material chemistry tier, and end-user procurement authority. The analytical framework models specification-grade versus commodity-grade pricing stratification, regional batch plant density, and regulatory compliance cost pass-through. CAGRs were derived from infrastructure reauthorization allocation trajectories and residential construction permit velocity, with polycarboxylate ether adoption rates and water-based sealant conversion timelines serving as key forecast inputs.
Material uncertainties — petrochemical feedstock volatility, EPA enforcement timing, and state-level Buy America provision expansion — sit outside the modeled envelope. Forecasts reflect assumptions regarding continued federal transportation funding authorization and stable acrylic monomer supply chain configurations. Revision becomes warranted when OSHA crystalline silica rule enforcement intensity crosses thresholds that accelerate dust-suppression admixture specification mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global Anhydrous Aluminum Chloride Market
Chemicals
Maleic Acid Market
Chemicals
Calcium Hydride Market
Chemicals
Welding Chemicals Market
Chemicals
North America Isopropyl Alcohol Market
Chemicals
Sodium Azide Market
Chemicals
Germany Methanol Market
Chemicals
Catechol Market
Chemicals
Egypt Acidulants Market
Chemicals
Global Pine Chemicals Market
Chemicals
Laboratory Chemical Reagents Market
Chemicals
Spirodiclofen Market
Chemicals
Cold Phosphating Chemicals Market
Chemicals
Fungicide Active Ingredients Market
Chemicals
Glyoxal Market
Chemicals
Etidronic Acid Market