
 Global Methyl Cellulose Market | 2026-2036
Global Methyl Cellulose Market Size, Share, and Industry Trends Forecast 2026-2036
Global Methyl Cellulose Market Foresight
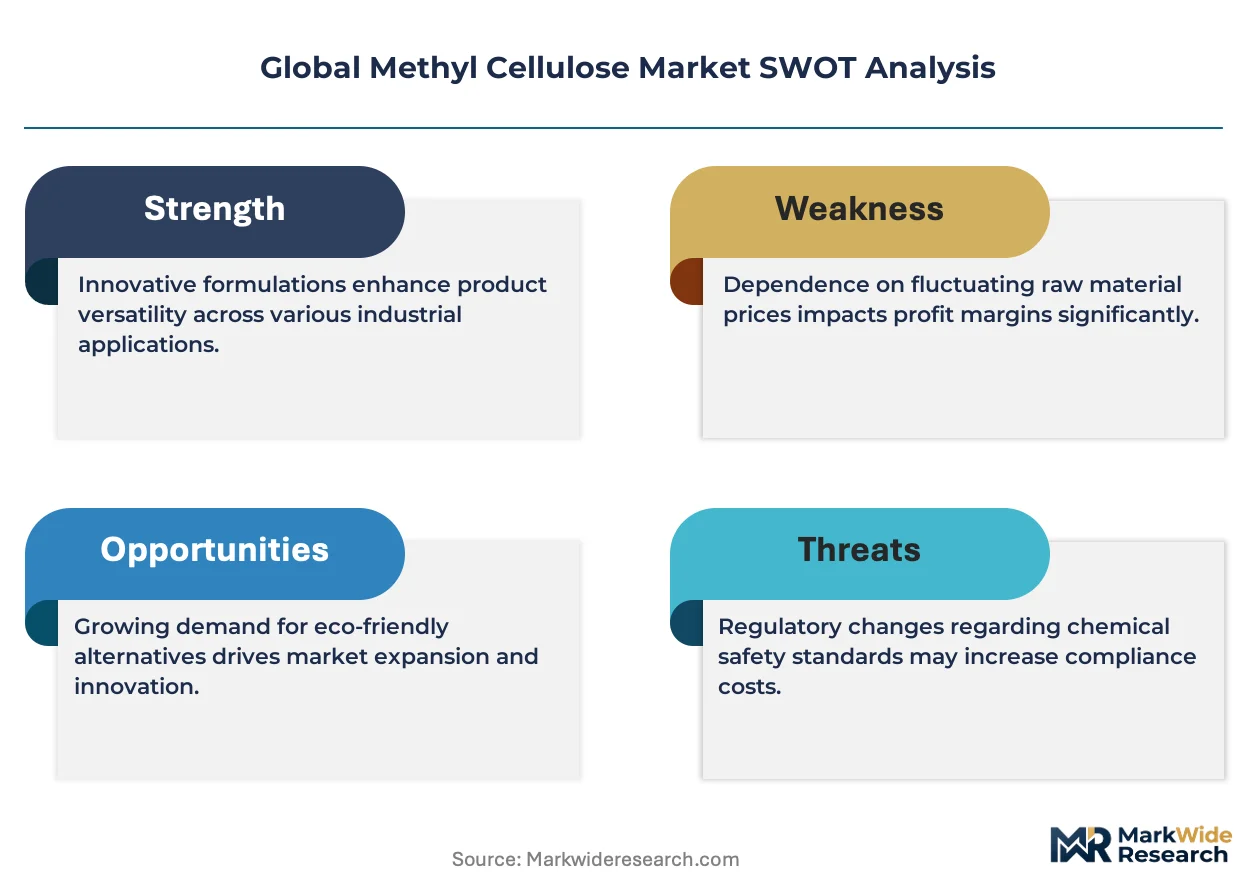
The methyl cellulose supply base is restructuring around a sharp split between pharmaceutical-grade purity tiers and commodity construction grades. Nouryon anchors the premium segment through captive etherification technology and stringent batch consistency for European and North American pharmaceutical buyers. Shandong Head competes aggressively on volume in Asia-Pacific construction chemicals, leveraging regional caustic soda and wood pulp access to compress delivered costs for cement admixture formulators.
Methyl cellulose is a cellulose ether synthesized through alkali-catalyzed etherification of cellulose with methyl chloride, yielding a water-soluble polymer with tunable viscosity grades from 4 to 100,000 mPa·s and methoxy substitution degrees between 27.5% and 31.5%. Its primary commercial purpose centers on rheology modification, water retention, and film-forming across construction mortars, tablet coatings, and personal care emulsions. Powder formulations dominate current revenue owing to shelf stability and metering precision in automated dry-mix plants, while emulsions represent the fastest-expanding format as ready-to-use construction admixtures displace on-site blending. Pharmaceutical applications command the deepest margin pools due to USP-NF and EP compliance burdens that screen out commodity producers.
FDA excipient monographs, REACH registration requirements under ECHA, and China's GB standards for construction additives collectively determine market access thresholds and testing cost structures for methyl cellulose suppliers. These frameworks push capital toward dedicated GMP lines for pharmaceutical grades while allowing toll-manufactured construction variants to compete on throughput. Stakeholders must monitor tightening VOC limits in EU construction products and evolving USP dissolution test standards, as either shift could abruptly revalue capacity across the purity spectrum.
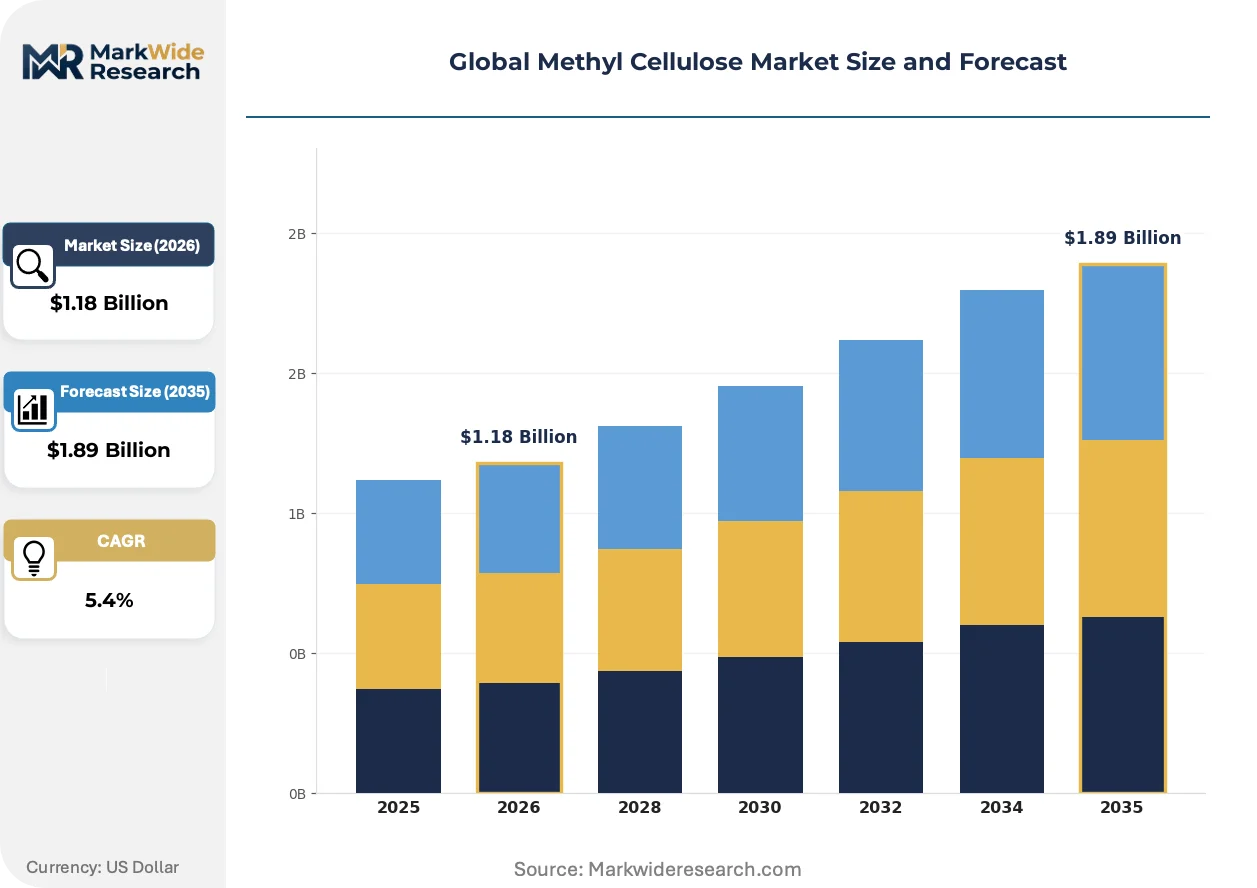
Market Dynamics
Pharmaceutical-grade methyl cellulose capacity is consolidating around dedicated GMP-certified etherification lines as FDA excipient monographs and REACH registration requirements under ECHA force dual-track manufacturing architectures that split construction-grade commodity output from high-purity drug formulation supply.
Growth Catalysts
- Controlled-release tablet formulations:Pharmaceutical manufacturers are expanding methyl cellulose use in hydrophilic matrix systems for sustained drug delivery. USP-NF compliance requirements screen out commodity producers, deepening margin pools for certified suppliers.
- China's GB standards for construction additives:Domestic cement admixture and tile adhesive producers are scaling methyl cellulose consumption under stricter national quality benchmarks. Shandong and Jiangsu province chemical clusters drive regional volume concentration.
- Ready-to-use emulsion formats:Construction contractors are displacing on-site powder blending with pre-dispersed liquid admixtures. This format shift compresses labor costs and metering variability for mortar formulators.
Market Restraints
- Wood pulp and methyl chloride input volatility:Cellulose ether producers face feedstock cost pressure from pulp market cycles and chloromethane supply constraints. Construction-grade margins compress disproportionately during input spikes.
- Pharmaceutical-grade supply concentration:European and North American GMP-certified capacity remains anchored by a limited producer base with captive etherification technology. Toll-manufactured alternatives cannot meet batch consistency requirements for drug applications.
- Cellulose gum and starch ether substitution:Cost-sensitive construction formulators in emerging markets switch to alternative rheology modifiers when methyl cellulose premiums exceed performance deltas. Substitution elasticity is highest in standard-grade cement admixtures.
Strategic Opportunities
- India's pharmaceutical excipient localization:CDSCO's tightening import substitution incentives and PLI scheme extensions create white space for domestic methyl cellulose GMP capacity. Current supply relies heavily on European and Chinese imports.
- Low-VOC construction product mandates:EU Green Deal implementation and tightening F-Gas Regulation derivatives are accelerating water-based adhesive formulations. Methyl cellulose water retention properties align with solvent-free system requirements.
- 3D printing construction binders:Specialized cellulose ether grades are converging with extrusion-based additive manufacturing for concrete elements. Early adoption centers on Netherlands and UAE demonstration projects for complex architectural geometries.
Industry Challenges
- Dual certification timeline compression:Suppliers seeking parallel USP-NF and EP compliance face extended validation cycles for methoxy substitution degree consistency. Batch release testing for pharmaceutical grades extends lead times versus construction variants.
- Skilled etherification process engineering scarcity:Alkali-catalyzed cellulose ether production requires specialized expertise in degree of substitution control and viscosity grade tuning. Talent pools concentrate in legacy European and Japanese chemical clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Methyl Cellulose Market |
| Market Size in 2026 | $1.18 Billion |
| Market Size in 2035 | $1.89 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Pellets, Flakes, Emulsions Application: Construction Chemicals, Personal Care, Pharmaceuticals, Food & Beverages, Oilfield Services End User: Paint Manufacturers, Cosmetic Producers, Pharmaceutical Companies, Food Processing Plants Packaging Type: Poly Bags, Fiber Drums, Plastic Drums, Bulk Containers |
| Companies Covered | Nouryon, BASF SE, Dow Chemical Company, Hubei Jiahua Cellulose Co., Ltd, Shandong Head Co., Ltd, Ashland, LOTTE Fine Chemical, J. RETTENMAIER & SÖHNE GmbH + Co KG, Shin-Etsu Chemical Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Methyl Cellulose Market Shifts & Advancements
Continuous processing technologies and real-time viscosity monitoring are displacing batch etherification in premium-grade production, while regulatory fragmentation between pharmaceutical and construction purity tiers forces capital allocation into physically separated manufacturing lines.
Continuous stirred-tank etherification systems with inline methoxy distribution analyzers are converging with pharmaceutical-grade methyl cellulose production. European and North American GMP-certified facilities are retrofitting batch lines to reduce solvent recovery costs and improve substitution uniformity. This technology convergence is compressing capital intensity gaps between mid-scale specialists and integrated chemical majors.
REACH registration requirements under ECHA are tightening purity disclosure thresholds for cellulose ethers used in construction products. Suppliers must now document residual solvent profiles and heavy metal content across all viscosity grades. German and French construction chemical distributors are demanding third-party certification as a procurement precondition, filtering out non-compliant Asian imports.
Ready-mix mortar producers are consolidating supplier relationships around full-service admixture packages rather than single-ingredient procurement. Large European construction groups now specify methyl cellulose as part of bundled rheology modifier systems with guaranteed water retention performance. This bundling behavior is most visible in Germany's residential renovation sector, where contractor labor costs dominate formulation decisions.
Global Methyl Cellulose Market Segmentation
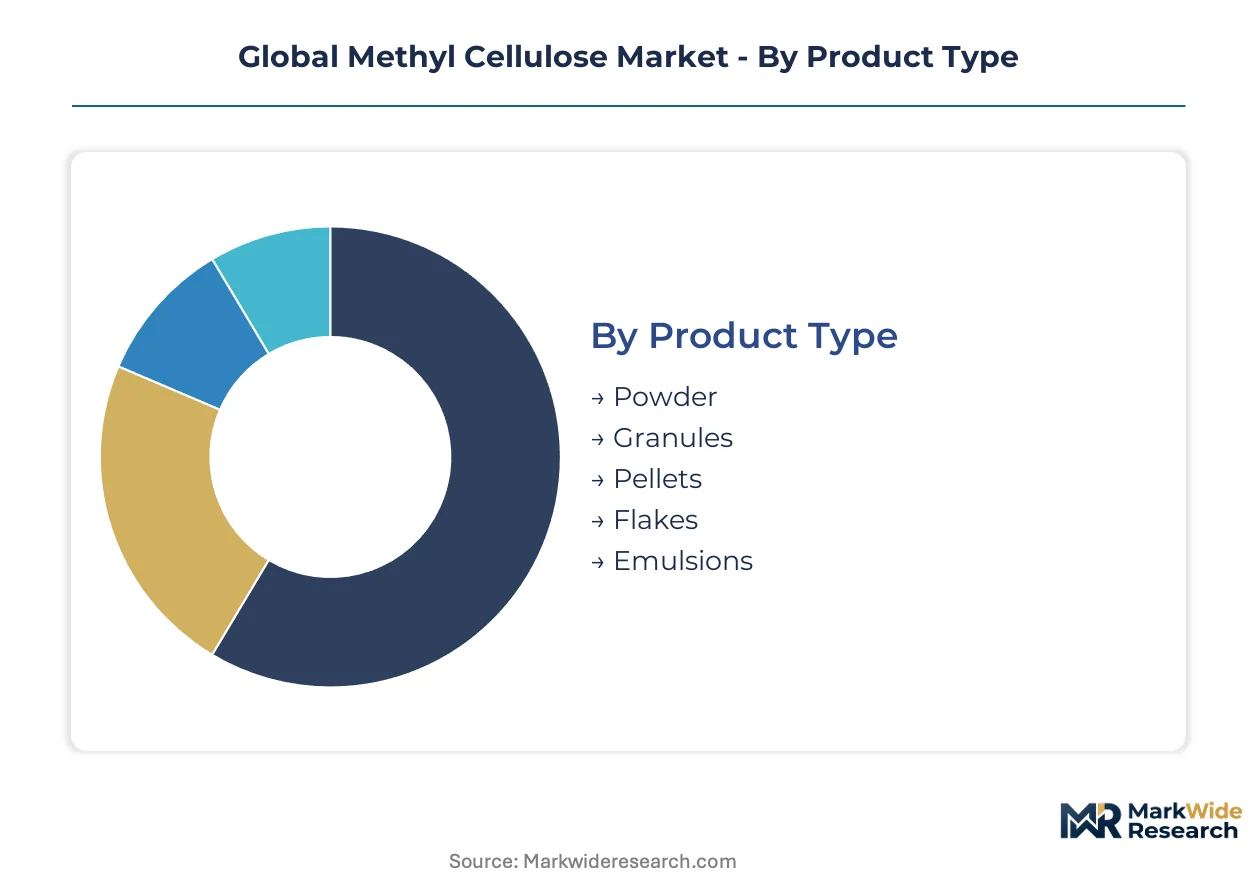
Methyl cellulose supply chains bifurcate sharply between pharmaceutical-grade purity tiers and commodity construction grades. Segmentation reveals how capital allocation, regulatory burden, and end-use performance requirements reshape competitive positioning across format, application, and customer type.
Product Type:
Powder capacity concentrates among European and Chinese producers with captive etherification lines, while emulsion manufacturing disperses toward regional blending facilities serving ready-mix mortar formulators.
- Powder:Dry particulate grades dominate current revenue through shelf stability and precise metering in automated dry-mix plants. Demand concentrates in Germany and China's construction chemical clusters, where cement admixture formulators prioritize storage efficiency and dust-controlled handling systems.
- Emulsions:Pre-dispersed liquid formats displace on-site powder blending among European ready-mix mortar producers seeking labor cost compression. Netherlands and UAE demonstration projects for 3D printing construction binders are testing specialized low-viscosity emulsion grades.
- Granules:Intermediate particle size grades serve pharmaceutical tableting operations requiring controlled dissolution profiles. CDSCO import substitution incentives in India are driving inquiries for domestic granule supply.
- Pellets:Dense agglomerated forms reduce dust exposure in high-volume food processing applications. FSSAI compliance requirements govern pellet specifications for thickening and stabilizing uses.
- Flakes:Thin-sheet formats occupy niche personal care emulsion markets. Japanese cosmetic producers specify flake geometry for specific hydration kinetics in premium skincare formulations.
Today's leader: Powder. Tomorrow's challenger: Emulsions.
Application:
Margin structures diverge across application tiers, with pharmaceutical excipient certification burdening testing costs while construction chemical volumes absorb feedstock volatility through scale.
- Construction Chemicals:Cement admixtures and tile adhesives consume the largest volume share, with China's GB standards tightening quality benchmarks for water retention performance. Shandong and Jiangsu province chemical clusters anchor regional demand concentration.
- Pharmaceuticals:Controlled-release tablet formulations command the deepest margin pools through USP-NF and EP compliance requirements that screen out commodity producers. FDA excipient monographs enforce batch consistency standards for hydrophilic matrix systems.
- Personal Care:Film-forming and rheology modification drive cosmetic emulsion demand. EU Green Deal implementation accelerates water-based adhesive formulations, aligning methyl cellulose properties with solvent-free system mandates.
- Food & Beverages:Thickening and stabilizing applications face substitution pressure from cellulose gum and starch ethers in cost-sensitive emerging markets.
- Oilfield Services:Drilling fluid viscosity modification represents a specialized niche with performance specifications tied to downhole temperature stability.
Construction Chemicals anchor volume leadership. Pharmaceuticals capture margin expansion.
End User:
Procurement sophistication separates pharmaceutical buyers demanding GMP-certified batch documentation from construction formulators optimizing delivered cost per metric ton.
- Pharmaceutical Companies:Sustained drug delivery matrix systems require methoxy substitution degree consistency validated through extended release testing cycles. Dual USP-NF and EP certification timelines compress supplier qualification windows.
- Paint Manufacturers:Water-based coating formulators specify methyl cellulose for rheology control and sag resistance. REACH registration requirements under ECHA now mandate residual solvent documentation across all viscosity grades.
- Cosmetic Producers:Premium skincare and haircare emulsions demand specific viscosity grades with tunable film-forming characteristics. Japanese and South Korean beauty markets drive specification refinement.
- Food Processing Plants:Thickening applications in processed foods operate under national food safety frameworks with varying purity disclosure thresholds.
Pharmaceutical Companies enforce the steepest certification barriers. Paint Manufacturers represent the broadest addressable base.
Packaging Type:
Packaging selection tracks handling automation levels and inventory turnover velocity, with bulk formats penetrating high-volume construction chemical accounts while drum specifications dominate pharmaceutical batch traceability.
- Poly Bags:Flexible multi-wall constructions serve automated dry-mix plants with high throughput and rapid inventory rotation. Dust-controlled discharge systems predominate in German residential renovation supply chains.
- Fiber Drums:Rigid cylindrical containers support pharmaceutical-grade batch segregation and full traceability documentation. GMP-certified facilities specify fiber drum specifications for excipient shipments.
- Plastic Drums:Chemical-resistant formats address moisture-sensitive emulsion storage requirements in humid climates.
- Bulk Containers:Intermediate bulk and tanker formats compress per-unit logistics costs for cement admixture compounders with dedicated receiving infrastructure.
Poly Bags dominate construction throughput. Fiber Drums command pharmaceutical premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled etherification process engineers concentrate in legacy European and Japanese chemical clusters, creating geographic capability asymmetries that shape methyl cellulose supply patterns. These talent pools anchor pharmaceutical-grade production while construction-grade capacity disperses toward feedstock-advantaged regions.
China
Domestic cement admixture and tile adhesive producers scale methyl cellulose consumption under stricter GB standards for construction additives. NMPA oversight of pharmaceutical excipient imports creates dual-track quality enforcement. Shandong and Jiangsu province chemical clusters drive regional volume concentration for both construction and emerging pharmaceutical applications.
Germany
Ready-mix mortar producers consolidate supplier relationships around bundled rheology modifier systems with guaranteed water retention performance. ECHA REACH registration requirements tighten purity disclosure thresholds for cellulose ethers in construction products. The Rhine-Ruhr industrial corridor hosts GMP-certified etherification facilities serving European pharmaceutical buyers.
United States
Pharmaceutical manufacturers expand methyl cellulose use in hydrophilic matrix systems for sustained drug delivery. FDA excipient monographs enforce batch consistency standards that screen out commodity producers. The Gulf Coast chemical corridor provides chloromethane feedstock access for domestic etherification operations.
India
CDSCO's tightening import substitution incentives and PLI scheme extensions create white space for domestic methyl cellulose GMP capacity. FSSAI compliance requirements govern pellet specifications for food thickening applications. Maharashtra and Gujarat pharmaceutical clusters currently rely on European and Chinese excipient imports.
Japan
Premium skincare and haircare emulsions demand specific viscosity grades with tunable film-forming characteristics from methyl cellulose suppliers. PMDA pharmaceutical regulations align with international USP-NF standards for excipient certification. The Kanto region around Tokyo anchors cosmetic formulation R&D driving specification refinement.
Global Methyl Cellulose Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the methyl cellulose value chain, with integrated chemical majors maintaining captive etherification technology while toll manufacturers serve construction-grade spot demand. The market structure bifurcates between pharmaceutical-certified GMP facilities and commodity construction chemical plants. Three archetypes dominate: European majors with dual USP-NF and EP certification, Chinese volume producers leveraging regional pulp and chloromethane access, and Japanese specialists in cosmetic-grade viscosity tuning. Competitive moves center on backward integration into wood pulp supply and geographic expansion through distribution partnerships in underpenetrated pharmaceutical markets.
Among European-integrated chemical majors, Nouryon anchors the premium segment through stringent batch consistency protocols. BASF SE and Dow Chemical Company occupy positions across multiple cellulose ether grades, representing scale-driven diversification archetypes. At the Asia-Pacific volume end, Shandong Head Co., Ltd exemplifies construction-grade cost compression through regional feedstock integration.
| Leading Market Players |
|---|
| Nouryon |
| BASF SE |
| Dow Chemical Company |
| Hubei Jiahua Cellulose Co., Ltd |
| Shandong Head Co., Ltd |
| Ashland |
| LOTTE Fine Chemical |
| J. RETTENMAIER & SÖHNE GmbH + Co KG |
| Shin-Etsu Chemical Co., Ltd |
| Others |
Supply & Pricing Matrix
EU Green Deal implementation gates qualified methyl cellulose supply and premium-tier pricing access by mandating residual solvent documentation and heavy metal disclosure across all viscosity grades. German and French construction chemical distributors now require third-party certification as a procurement precondition, filtering out non-compliant Asian imports and compressing margin pools for uncertified producers.
Pricing Analysis
The bundled-versus-unbundled service split separates European ready-mix mortar producers purchasing full-service rheology modifier packages from commodity buyers sourcing single-ingredient spot volumes. Three-tier pricing structure across pharmaceutical-grade, construction-premium, and construction-economy levels tracks certification burden and batch consistency requirements. Pricing pressure stems from wood pulp and methyl chloride input volatility that compresses construction-grade margins disproportionately during feedstock spikes. Cement admixture formulators in emerging markets exhibit highest price sensitivity, while pharmaceutical companies accepting premium positioning for USP-NF and EP compliance show lowest elasticity.
Supply Chain Analysis
Certification and qualification gating concentrates pharmaceutical-grade supply among European and North American GMP-certified facilities with captive etherification technology, while construction-grade capacity disperses toward China and Southeast Asia. Wood pulp, methyl chloride, and caustic soda constitute core input dependencies. Single-source vulnerability runs through concentrated chloromethane supply corridors. Distribution runs through regional blending facilities for emulsion formats and direct mill shipments for powder grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The methyl cellulose market functions as a regulatory compounder where FDA excipient monograph tightening and REACH registration requirement evolution continuously revalue capacity across purity tiers. CDSCO import substitution incentives in India represent the most significant near-term demand catalyst.
For Market Incumbents: Deepen backward integration into wood pulp supply to insulate margin pools from cellulose feedstock volatility. Expand GMP-certified capacity in India to capture CDSCO localization incentives before domestic competitors qualify. Starch ether substitution threats in emerging market construction grades demand proactive cost compression through continuous processing technology deployment. For New Entrants and Emerging Players: Begin with India's pharmaceutical excipient white space, where Maharashtra and Gujarat clusters currently rely on European and Chinese imports. Construction-grade toll manufacturing for regional cement admixture compounders offers lower barrier entry with faster qualification cycles. A certification-first go-to-market angle targeting CDSCO GMP pathways differentiates from commodity construction entrants. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale European cellulose ether specialists because pharmaceutical-grade certification scarcity creates defensive moats that integrated chemical majors cannot easily replicate. Long-term viability centers on dual USP-NF and EP compliance capabilities. The signal to watch is CDSCO domestic approval timelines, which would revalue Indian manufacturing assets upon acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wood Pulp Supply | Captive pulp access insulates Nouryon and BASF from cellulose feedstock volatility cycles. |
| GMP-Certified Capacity Expansion in India | Domestic CDSCO-qualified production captures PLI scheme incentives and import substitution demand. |
| Continuous Processing Technology Retrofit | Inline methoxy distribution analyzers reduce solvent recovery costs for European pharmaceutical lines. |
| Long-Term Supply Agreement with Cement Majors | Bundled rheology modifier contracts lock in German ready-mix mortar volume commitments. |
| Joint Venture for Regional Emulsion Blending | Localized liquid admixture production serves UAE and Netherlands 3D printing construction demonstration projects. |
Research Methodology
Coverage spans Germany, China, the United States, India, and Japan, with primary inputs from each major production and consumption cluster. The research combines structured interviews with cellulose ether plant managers, procurement leads at pharmaceutical and construction chemical formulators, distribution channel partners, and technical R&D directors with secondary validation from ECHA REACH registration databases, FDA excipient monograph filings, CDSCO import records, and SEC 10-K disclosures from listed chemical majors. Bottom-up capacity and demand modeling triangulates against top-down trade flow analysis.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon. The analytical framework models methyl cellulose demand by grade tier (pharmaceutical versus construction), end-use industry (pharmaceuticals, construction chemicals, personal care), packaging format (powder versus emulsion), and regional production hub. CAGRs derive from segment-level growth rate aggregation weighted by baseline revenue shares. Forecast inputs include pulp price cycle assumptions, regulatory compliance timeline estimates, and substitution elasticity parameters for starch ether alternatives.
Several conditions sit outside the modeled scope, including abrupt tariff reconfigurations affecting cellulose ether trade flows, unanticipated FDA dissolution test standard revisions, and force majeure disruptions in chloromethane supply corridors. Forecasts reflect assumptions about regulatory enforcement continuity and feedstock price reversion to historical means. A model refresh is warranted upon material change in CDSCO domestic approval velocity or EU Green Deal VOC limit implementation timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
LAMEA Dimethyl Phosphate Market
Chemicals
Flooring Chemicals Market
Chemicals
Sodium Methoxide Market
Chemicals
Sodium Hydride Market
Chemicals
Hydrogenated Dimer Acid Market
Chemicals
North America Methanol Market
Chemicals
Lanthanum Nitrate Market
Chemicals
United States Construction Chemicals Market
Chemicals
Global Commodity Chemicals Market
Chemicals
Thioacetic Acid Market
Chemicals
Asia Pacific Waterproofing Chemicals Market
Chemicals
Electronic Grade Choline Hydroxide Market
Chemicals
Airbag Propellant Chemicals Market
Chemicals
Diethyl Sulfate Market
Chemicals
Malaysia Construction Chemicals Market
Chemicals
Formalin Market