
 Purging Compound Market | 2026-2036
Purging Compound Market Size, Share, and Industry Trends Forecast 2026-2036
Purging Compound Market Analysis
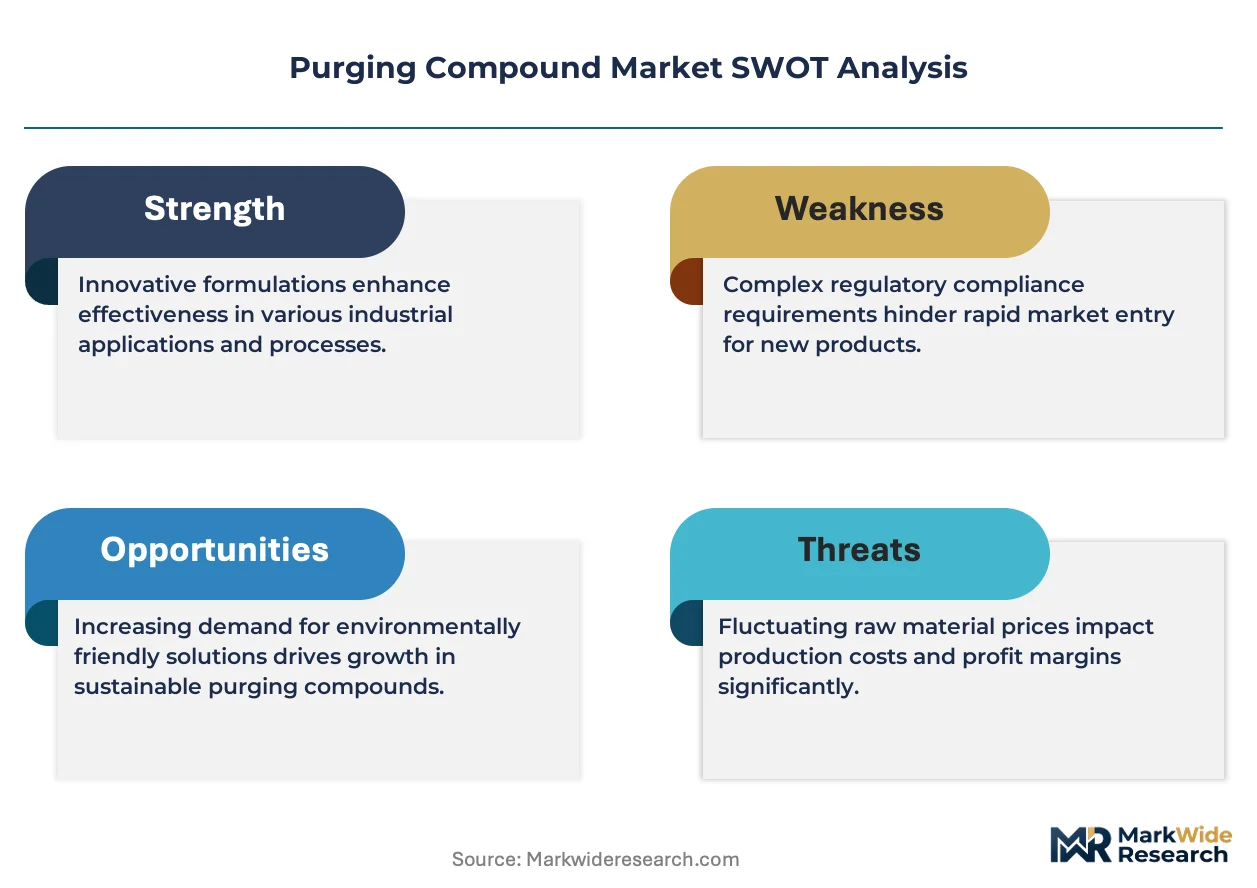
The capital-intensity divergence between integrated compound formulators and regional blenders is unwinding as multi-layer product specifications require dedicated reactor assets. Chem-Trend leverages its global technical service network to anchor long-term supply agreements with tier-one automotive molders. Dyna-Purge competes through specialized water-based formulations that reduce volatile organic compound exposure during changeover cycles. Asahi Kasei Corporation sustains leadership in thermal-grade pellets through captive polymer science capabilities.
Purging compounds are engineered cleaning formulations, typically comprising surfactant-active polymers, abrasive mineral fillers, and carrier resins, designed to remove degraded polymer residue and colorant deposits from extruder barrels, screws, and hot-runner systems. These compounds function by mechanical scouring and chemical solvation at processing temperatures between 160°C and 350°C, restoring equipment efficiency and reducing scrap rates between production runs. Thermal-grade formulations dominate volume consumption in high-temperature engineering resin applications, while water-based alternatives are capturing fastest growth in packaging sectors where FDA-compliant direct-contact requirements restrict solvent residues. The injection molding application segment commands the largest value pool due to frequent color-change cycles and stringent surface-quality standards in electronics housings.
EPA regulations under the Toxic Substances Control Act constrain volatile organic compound content in solvent-based purging compounds distributed in the United States, while REACH registration requirements in Europe mandate full chemical substance disclosure for imported formulations. FDA compliance for indirect food-contact applications shapes product development priorities among packaging-focused compound suppliers. Stakeholders must monitor evolving state-level restrictions on per- and polyfluoroalkyl substances, as these chemicals appear in certain high-performance purging formulations targeted at fluoropolymer processing equipment.
Market Dynamics
Automotive molders are consolidating their supplier base around technical-service-intensive compound formulators as multi-layer specifications and REACH-mandated chemical disclosure requirements raise barriers for regional blenders lacking captive R&D infrastructure.
Growth Catalysts
- Injection molding cycle compression:Tier-one automotive suppliers demand faster color-change protocols to accommodate just-in-sequence production schedules, expanding consumption of high-performance thermal-grade pellets.
- REACH registration mandates:ECHA's full substance disclosure requirements for imported formulations are filtering out low-transparency suppliers and concentrating demand among compliant integrated producers.
- Fluoropolymer processing expansion:Semiconductor fabrication equipment manufacturers require specialized high-temperature purging protocols, creating premium formulation demand in Japan and Germany.
Market Restraints
- Petrochemical feedstock volatility:Surfactant-active polymers and carrier resins track naphtha and propylene price swings, compressing blender margins during upstream spikes.
- Reactor asset concentration:Multi-layer product specifications require dedicated continuous reactor systems concentrated among German and Japanese chemical conglomerates.
- Water-based performance ceiling:FDA-compliant water-based formulations face temperature limitations below 280°C, excluding them from PEEK and PPS processing applications.
Strategic Opportunities
- Indian precision manufacturing clusters:PLI scheme incentives for automotive component exports are attracting injection molding capacity around Pune and Chennai, creating first-mover openings for technical service networks.
- Recycled-content compliance:EU Green Deal packaging mandates are forcing rPET processors to adopt specialized purging protocols for contaminated feedstock handling.
- Digital twin integration:IoT-enabled screw-wear monitoring systems are converging with predictive purging scheduling, enabling subscription-based compound replenishment models.
Industry Challenges
- Polymer science talent scarcity:Formulation chemists with simultaneous expertise in surfactant chemistry and high-temperature rheology command premium compensation, constraining mid-cap blender expansion.
- EPA state-level fragmentation:California's pending per- and polyfluoroalkyl substance restrictions are diverging from federal TSCA baselines, forcing dual-registration compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Purging Compound Market |
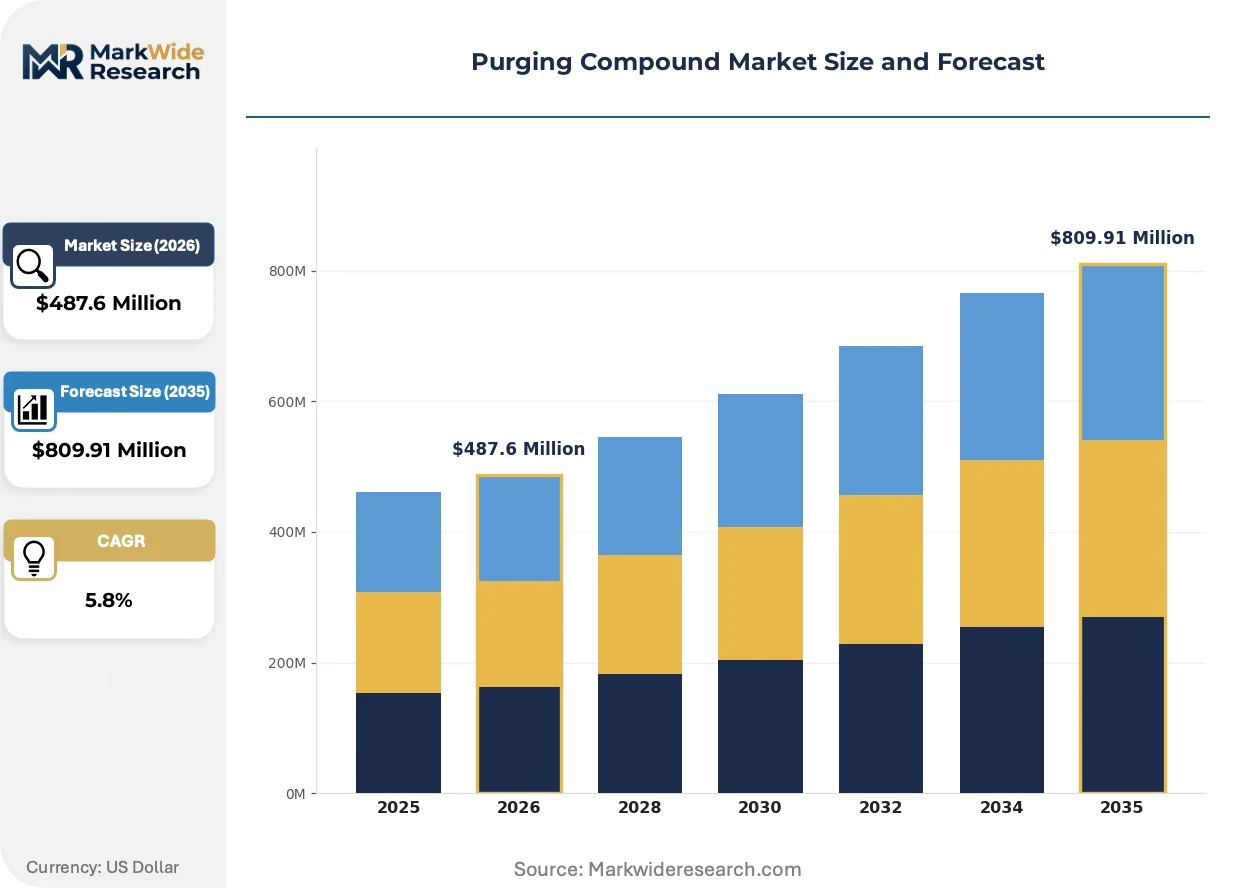
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal, Chemical, Water-Based, Solvent-Based Application: Injection Molding, Blow Molding, Extrusion, 3D Printing End User: Packaging, Automotive, Consumer Goods, Electronics Form: Pellets, Granules, Liquids, Powders |
| Companies Covered | Chem-Trend, Asahi Kasei Corporation, Purgex, Dyna-Purge, Clariant, Calsak Corporation, Shuman Plastics, Daicel Corporation, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Purging Compound Market Emerging Trajectories
Formulation chemistry and service delivery models are diverging along regulatory fault lines, with water-based systems capturing packaging share while thermal-grade innovations target semiconductor and medical device precision requirements.
Bio-based carrier resins derived from polyhydroxyalkanoates are supplanting petroleum-derived alternatives in European packaging applications. Major food-contact molders in Germany and the Netherlands have adopted these formulations to preempt EU Single-Use Plastics Directive compliance deadlines. The shift is compressing demand for conventional polyethylene-based compounds in dairy and beverage closure segments.
EPA enforcement discretion letters under TSCA Section 5 are tightening pre-manufacture notification requirements for novel abrasive mineral fillers. Compound developers seeking to introduce engineered ceramic microspheres face extended review timelines averaging fourteen months. Small and mid-size blenders in the United States are responding by licensing existing filler technologies rather than pursuing independent regulatory clearance.
Consolidated procurement desks at tier-one automotive suppliers are unbundling technical service from compound supply, negotiating standalone consulting agreements with formulators. This behavior disrupts traditional bundled pricing and concentrates purchasing leverage among buyers with multi-plant footprints. The pattern is most visible in Michigan and Stuttgart, where seating and interior component molders have centralized sourcing decisions.
Purging Compound Market Segmentation
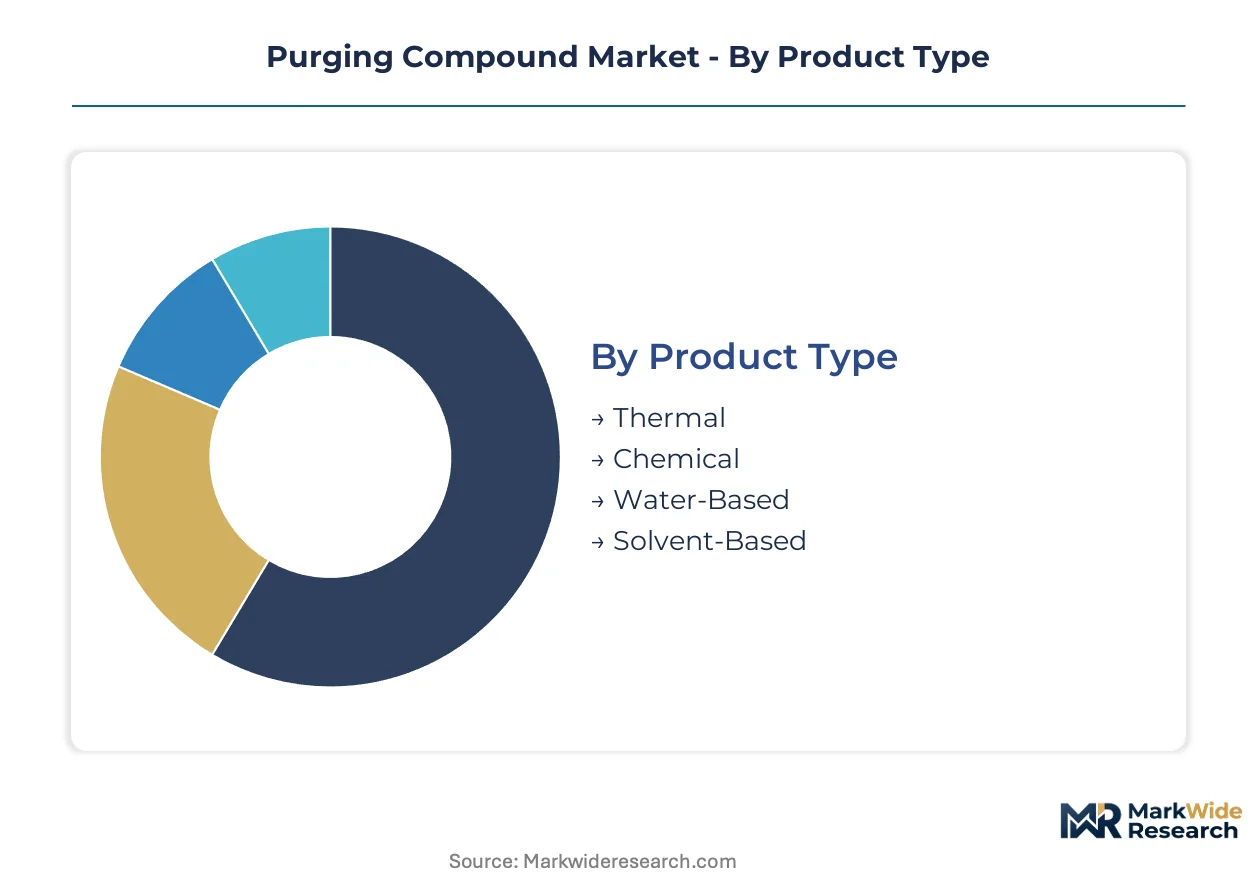
Purging compound purchasing decisions split along equipment compatibility and regulatory compliance lines. Formulators must align product specifications with processing temperature windows, resin types, and regional chemical disclosure mandates.
Product Type:
Thermal-grade formulations face the strongest substitution pressure from water-based alternatives in packaging applications below 280°C, while solvent-based systems confront regulatory phase-outs under EPA and REACH volatile organic compound restrictions.
- Thermal:Pelletized carrier resins combined with abrasive mineral fillers operate between 160°C and 350°C, scrubbing degraded polymer from extruder barrels through mechanical action. Automotive molders in Stuttgart and Toyota City specify these grades for PEEK and PPS changeover cycles where thermal stability is non-negotiable.
- Water-Based:Surfactant-dispersed aqueous formulations eliminate volatile organic compound exposure during changeover. German dairy closure manufacturers have adopted these systems to satisfy EU Single-Use Plastics Directive compliance deadlines and FDA indirect food-contact requirements.
- Chemical:Reactive solvent systems penetrate cross-linked residue layers through molecular solvation. These formulations retain niche demand in fluoropolymer processing for semiconductor fabrication equipment where aggressive cleaning action outweighs handling complexity.
- Solvent-Based:Hydrocarbon and oxygenated solvent carriers deliver rapid color-change performance. EPA Toxic Substances Control Act enforcement is compressing distribution channels for these products in the United States.
Thermal compounds anchor the volume base while water-based alternatives gain share at the steepest rate.
Application:
Processing equipment architecture dictates formulation selection, with screw-and-barrel designs favoring pelletized grades and closed-loop systems requiring liquid or granular flow characteristics.
- Injection Molding:Frequent color-change cycles in multi-cavity tools drive consumption of high-performance thermal pellets. Tier-one automotive suppliers in Michigan operate just-in-sequence schedules demanding sub-15-minute changeover protocols.
- Extrusion:Continuous production lines with extended residence times accumulate degraded polymer requiring aggressive mechanical scouring. Sheet and profile processors favor abrasive-loaded thermal formulations.
- Blow Molding:Parison programming systems with complex hot-runner networks require specialized purging protocols. Pharmaceutical packaging molders specify FDA-compliant water-based grades for blow-fill-seal equipment.
- 3D Printing:Fused deposition modeling nozzle cleaning represents an emerging specification category. Desktop and industrial printer manufacturers are developing proprietary compound partnerships.
Injection molding commands the largest value pool while 3D printer maintenance applications expand most quickly.
End User:
Customer procurement sophistication varies sharply, with automotive and electronics molders demanding bundled technical service while packaging converters prioritize unit cost minimization.
- Automotive:Seating and interior component molders consolidate supply agreements around formulators with captive polymer science capabilities. REACH-mandated chemical disclosure requirements filter out low-transparency regional blenders.
- Packaging:rPET processors handling contaminated recycled feedstock require specialized purging protocols. EU Green Deal mandates are forcing adoption of bio-based carrier resins in dairy and beverage closure segments.
- Electronics:Precision housing manufacturers enforce stringent surface-quality standards. Semiconductor fabrication equipment suppliers in Japan specify thermal-grade formulations for high-temperature engineering resin processing.
- Consumer Goods:Appliance and toy molders exhibit price-sensitive procurement patterns. These buyers favor standard-grade compounds without premium technical service attachments.
Automotive anchors the volume base while packaging gains share at the steepest rate.
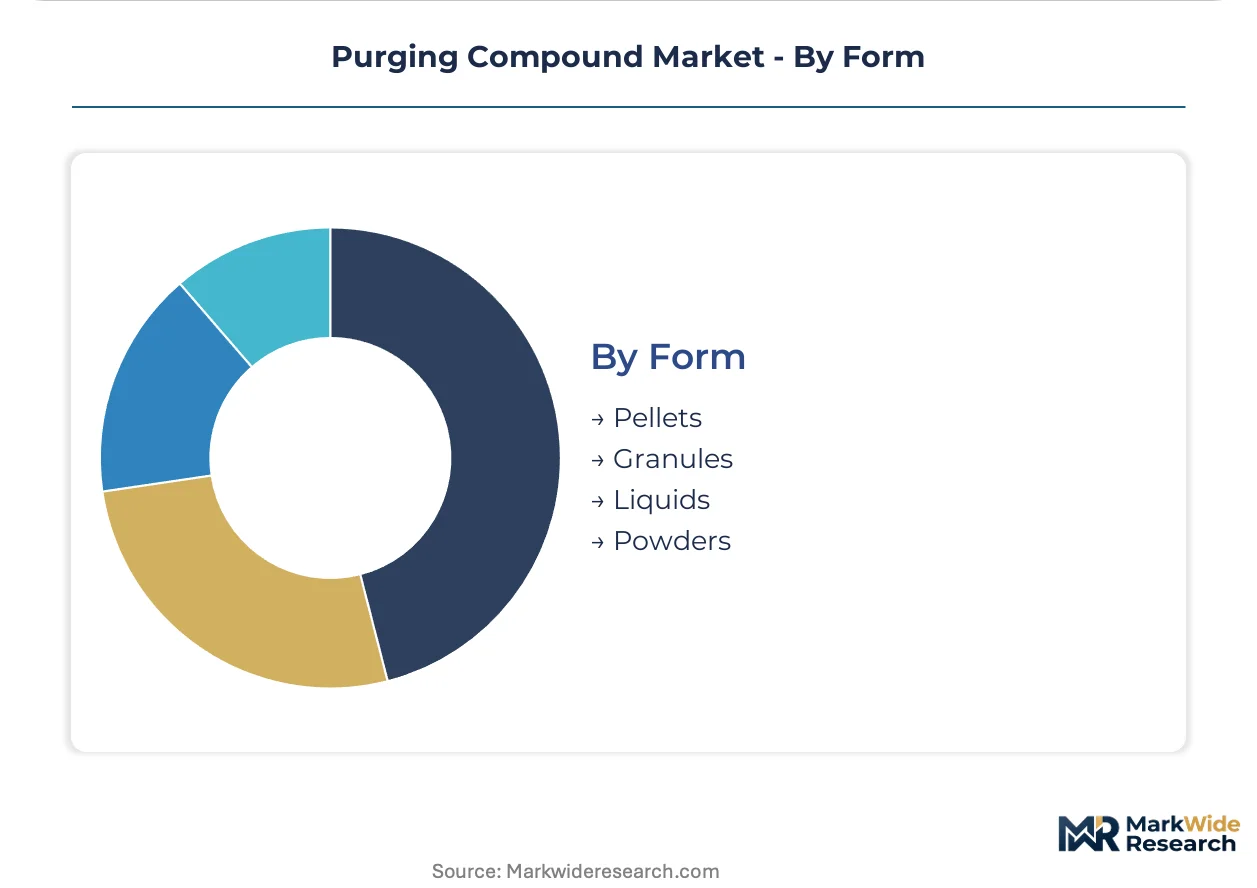
Form:
Physical state selection hinges on material handling infrastructure and dosing precision requirements, with pelletized formats dominating automated feeding systems.
- Pellets:Uniform geometry enables precise metering through gravimetric feeders. Thermal-grade pellets dominate high-temperature applications in automotive and electronics manufacturing.
- Liquids:Pump-dispensed formulations suit centralized supply systems and continuous reactor cleaning. Water-based liquids capture packaging sector share where FDA compliance restricts solvent residues.
- Granules:Irregular particle geometry provides enhanced mechanical scouring action. These forms retain demand in extrusion applications with heavy carbon buildup.
- Powders:Fine particle size enables penetration into complex hot-runner geometries. Specialized semiconductor equipment cleaning protocols specify engineered ceramic microsphere powders.
Pellets anchor the volume base while liquids gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Automotive molders in Germany and Japan absorb premium formulations for precision requirements, while packaging converters in India and Southeast Asia prioritize unit cost minimization over technical service bundles.
United States
Tier-one automotive suppliers in Michigan demand sub-15-minute color-change protocols for just-in-sequence production schedules. EPA enforcement under the Toxic Substances Control Act constrains volatile organic compound content in solvent-based formulations, filtering distribution channels. Precision manufacturing clusters around Detroit and Chicago anchor thermal-grade pellet consumption for high-temperature engineering resin applications.
Germany
Seating and interior component molders in Stuttgart consolidate supply agreements around formulators with captive polymer science capabilities. REACH registration mandates from ECHA require full chemical substance disclosure for imported formulations, raising barriers for low-transparency regional blenders. Dairy closure manufacturers in the Netherlands and western Germany have adopted bio-based carrier resins to satisfy EU Single-Use Plastics Directive compliance deadlines.
Japan
Semiconductor fabrication equipment manufacturers require specialized high-temperature purging protocols for fluoropolymer processing, creating premium formulation demand. METI industrial standards shape product development priorities for thermal-grade pellets operating above 300°C. Manufacturing clusters in Toyota City and Nagoya specify these grades for PEEK and PPS changeover cycles where thermal stability is non-negotiable.
India
PLI scheme incentives for automotive component exports are attracting injection molding capacity around Pune and Chennai, creating first-mover openings for technical service networks. BIS certification requirements for industrial chemicals constrain import channels for non-compliant formulations. Precision manufacturing clusters in Maharashtra and Tamil Nadu exhibit rising procurement sophistication as tier-one supplier relationships deepen.
China
Packaging sector expansion drives water-based formulation adoption for FDA-compliant indirect food-contact applications. MIIT standards for chemical substance management are converging with international disclosure norms, reshaping import compliance costs. Yangtze River Delta manufacturing hubs around Shanghai concentrate demand for mid-grade thermal pellets serving electronics housing molders.
Purging Compound Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated chemical conglomerates commanding premium positions while regional blenders compete on price. The vendor base splits between formulators with captive reactor assets and compounders licensing filler technologies. Three archetypes dominate: integrated polymer science specialists, technical service-intensive formulators, and regional cost-optimized blenders. Capacity expansion and strategic partnerships represent the dominant competitive moves as multi-layer product specifications raise asset barriers.
Among the integrated specialists, Asahi Kasei Corporation and Daicel Corporation exemplify the polymer science archetype with captive formulation capabilities. Chem-Trend occupies a position within the technical service-intensive tier, anchoring long-term supply relationships through global support networks. Dyna-Purge sits within the specialized formulation segment, representing water-based alternatives that reduce volatile organic compound exposure. Clariant and 3M Company exemplify diversified chemical conglomerates leveraging broad material science portfolios across industrial applications.
| Leading Market Players |
|---|
| Chem-Trend |
| Asahi Kasei Corporation |
| Purgex |
| Dyna-Purge |
| Clariant |
| Calsak Corporation |
| Shuman Plastics |
| Daicel Corporation |
| 3M Company |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day formulation lead times for REACH-compliant thermal-grade pellets concentrate pricing power among German and Japanese integrated producers with captive reactor assets, while regional blenders lacking ECHA registration face margin compression from import compliance costs and petrochemical feedstock volatility.
Pricing Analysis
After-sales technical service contracts anchor lifetime value for tier-one automotive molders, with Chem-Trend and similar formulators bundling predictive maintenance protocols into multi-year supply agreements. Three-tier pricing structure across premium, standard, and economy levels separates FDA-compliant water-based formulations for packaging from thermal-grade pellets for high-temperature engineering resins. Pricing pressure stems from consolidated procurement desks unbundling service from compound supply, compressing margins for mid-cap blenders. Packaging converters in India and Southeast Asia exhibit highest price sensitivity, while semiconductor equipment manufacturers in Japan absorb premium formulations without volume negotiation.
Supply Chain Analysis
Inventory buffers for surfactant-active polymers and abrasive mineral fillers extend to ninety days for non-integrated blenders, exposing margin compression during naphtha and propylene price spikes. Supply concentrates in Germany, Japan, and the United States where dedicated continuous reactor systems serve precision manufacturing clusters. Formulation chemistry draws from petrochemical feedstocks, engineered ceramic microspheres, and bio-based polyhydroxyalkanoate carrier resins. Single-source vulnerability runs through ECHA-registered integrated producers controlling REACH-compliant import channels. Distribution runs through direct technical service networks for automotive molders and chemical distributors for packaging converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized formulation chemists commanding premium compensation for simultaneous expertise in surfactant chemistry and high-temperature rheology constrain mid-cap blender expansion, creating durable competitive moats for integrated producers with captive polymer science infrastructure.
For Market Incumbents: Compound technical service intensity through predictive purging scheduling integrated with IoT-enabled screw-wear monitoring, defending against unbundling pressure from consolidated procurement desks. Deepen backward integration into bio-based carrier resin production to preempt EU Single-Use Plastics Directive compliance deadlines and secure margin against petroleum feedstock volatility. For New Entrants and Emerging Players: FDA fast-track compliance for indirect food-contact water-based formulations opens white-space in pharmaceutical blow-fill-seal equipment maintenance, where incumbent technical service networks have limited presence. Target precision manufacturing clusters around Pune and Chennai under India's PLI scheme for automotive component exports, leveraging first-mover positioning before tier-one supplier relationships mature. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized reactor assets and dormant REACH registrations, offering immediate compliance infrastructure for market entry. Long-term viability hinges on formulation chemistry talent pipelines and regulatory clearance timelines for novel abrasive mineral fillers. Watch EPA enforcement discretion letters under TSCA Section 5 as inflection indicators for competitive positioning in engineered ceramic microsphere applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Carrier Resins | Preempts EU Single-Use Plastics Directive deadlines for dairy closure manufacturers in Germany and the Netherlands. |
| REACH Registration Completion for Import Formulations | Filters out low-transparency regional blenders from European automotive supply chains under ECHA mandates. |
| IoT-Enabled Predictive Purging Platform Launch | Enables subscription-based compound replenishment models converging with digital twin integration. |
| Technical Service Network Expansion to Indian Precision Clusters | Captures first-mover positioning around Pune and Chennai injection molding capacity under PLI incentives. |
| Joint Venture for Fluoropolymer Processing Formulations | Addresses semiconductor fabrication equipment demand in Toyota City and Nagoya requiring thermal-grade pellets above 300°C. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, customs and trade data, ACC and Cefic industry reports, and ECHA REACH registration databases, combining interviews with plant managers at injection molding facilities, procurement leads at tier-one automotive suppliers, distribution channel partners, and technical R&D directors at compound formulators. Bottom-up demand modeling from equipment installed base and changeover frequency triangulates against top-down value chain analysis.
Segmentation dimensions modeled span product type, application, end user, and form, with additional granularity on regulatory compliance tier and processing temperature window across the analysis window. CAGRs derive from regression analysis of historical consumption patterns against equipment investment cycles and polymer processing technology adoption curves. Forecast inputs incorporate REACH registration timelines, EPA TSCA enforcement patterns, and PLI scheme incentive disbursement rates.
Decision-makers should treat outputs as directional under assumptions of sustained REACH compliance stringency and petrochemical feedstock price correlation; material deviation in regulatory enforcement or bio-based carrier resin cost parity would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
North America Metal Cleaning Chemicals Market
Cleaning Chemicals
North America Surface Treatment Chemicals Market
Cleaning Chemicals
Metal Polish Products Market
Cleaning Chemicals
Cleaning Chemicals Market
Cleaning Chemicals
Efflorescence Remover Market
Cleaning Chemicals
Deck Brightener Market
Cleaning Chemicals
Biodegradable Spray Tank Line-Cleaning Chemistry Market
Cleaning Chemicals
Dust and Emission Control Chemicals for Ore Handling Market
Cleaning Chemicals
Cleaning Products Market
Cleaning Chemicals
Dust Suppressant Market
Cleaning Chemicals
Rust Remover Market
Cleaning Chemicals
Cleaning Chemicals for Airports and Transport Hubs Market
Cleaning Chemicals
Korea Industrial and Institutional Cleaning Chemicals Market
Cleaning Chemicals
Kitchen Vent Hood and Duct Cleaning Chemicals Market
Cleaning Chemicals
Industrial and Institutional (Iandi) Cleaning Chemicals Market
Cleaning Chemicals
Industrial Cleaning Chemicals Market