
 Thioacetic Acid Market | 2026-2036
Thioacetic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Thioacetic Acid Market Analytics
Buyer concentration among pharmaceutical intermediates producers is pivoting toward a smaller set of large-scale API manufacturers with captive solvent-recovery capabilities. Arkema sustains European supply leadership through backward integration into mercaptan chemistry. Toyobo anchors Asian demand via specialized polymer-grade thioacetic acid output for high-performance fibers. Changzhou Jieying Chemical competes on volume throughput from its Jiangsu manufacturing base.
Thioacetic acid is an organosulfur compound with the formula CH3COSH, typically synthesized through acetyl chloride thiolation or ketene-hydrogen sulfide reaction, and functions primarily as a thioacetylating agent and polymerization regulator across industrial chemistry. The liquid form dominates commercial trade due to handling efficiency in continuous-flow reactor systems, while pharmaceutical-grade specifications command premium positioning through tightened residual-sulfide thresholds. Reagent-grade demand leads absolute volume within laboratory and analytical applications, whereas industrial-grade supply anchors bulk chemical manufacturing in agrochemical and textile auxiliaries.
EPA oversight in the United States and REACH registration requirements in Europe constrain market entry through mandatory toxicological dossiers and exposure-limit documentation. China's MEE enforces wastewater-sulfide discharge standards that elevate treatment capital for thioacetic acid producers operating near ecological red lines. Stakeholders must monitor evolving pharmaceutical-grade certification protocols across multiple jurisdictions to secure long-term supply contracts with regulated end-users.
Market Dynamics
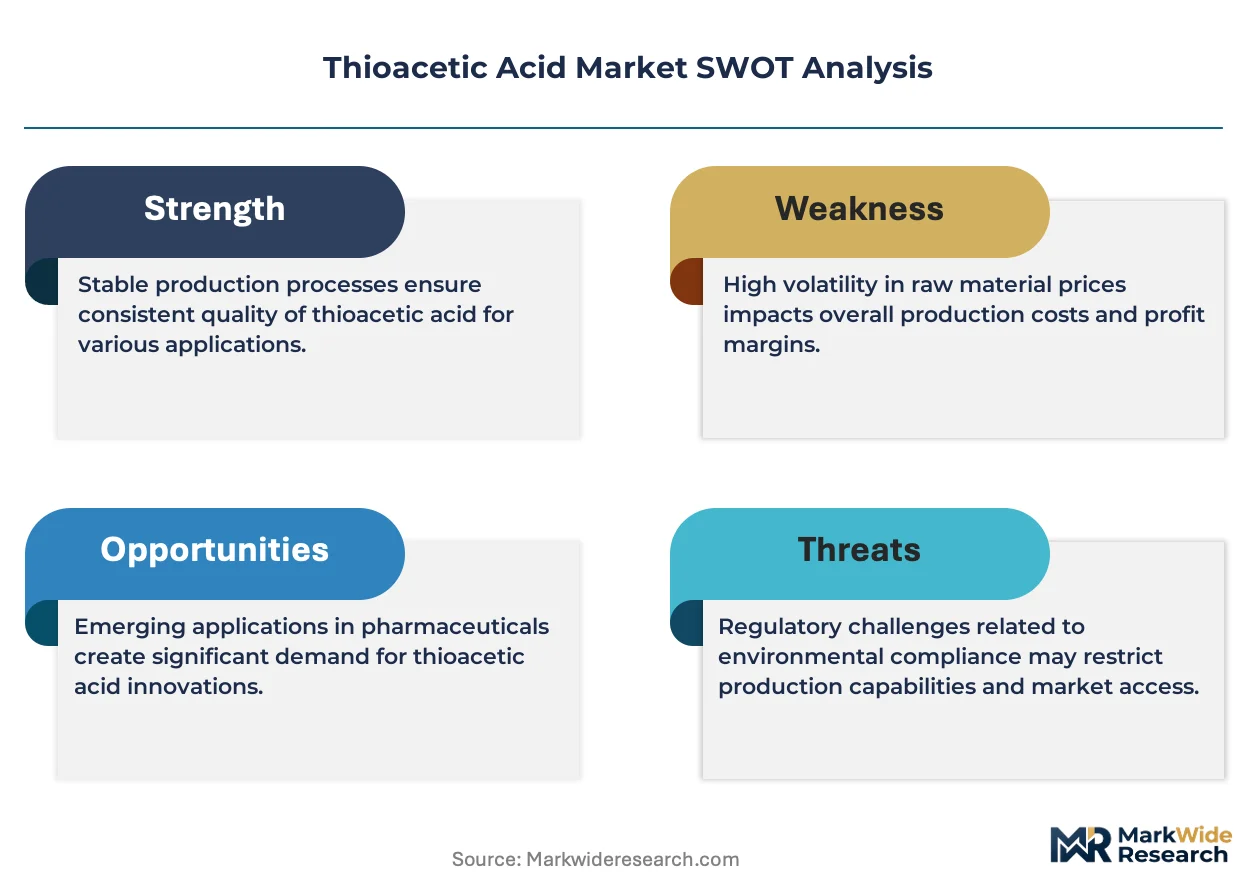
Pharmaceutical-grade thioacetic acid procurement is consolidating around large-scale API manufacturers with captive solvent-recovery infrastructure, compressing spot-market liquidity and elevating contract tenure requirements for qualified suppliers.
Growth Catalysts
- REACH registration mandates:European ECHA compliance deadlines for thioacetic acid dossiers are filtering out non-compliant traders and concentrating volume among registered producers with toxicological documentation.
- Acetyl chloride thiolation process optimization:Continuous-flow reactor adoption in Jiangsu province manufacturing clusters is lowering batch-to-batch variability for reagent-grade output.
- Polymerization regulator demand:High-performance fiber manufacturers in Japan are expanding thioacetic acid offtake for controlled molecular-weight polymer synthesis.
Market Restraints
- Hydrogen sulfide feedstock volatility:Refinery-derived H2S supply fluctuations directly compress thioacetic acid margin structures during crude sulfur price spikes.
- Jiangsu-Shandong supply concentration:Over two-thirds of merchant-grade capacity sits within 400 kilometers of Changzhou, creating single-region exposure to MEE wastewater enforcement actions.
- Ketene route substitution economics:Acetic anhydride-based thioacetylation in certain agrochemical intermediates is displacing thioacetic acid in cost-sensitive applications.
Strategic Opportunities
- Indian CDSCO pharmaceutical-grade certification:Domestic API producers under PLI scheme incentives are seeking qualified thioacetic acid suppliers with DMF-ready documentation packages.
- Bio-based acetyl precursor integration:Fermentation-derived acetic acid convergence with electrochemical thiolation is opening carbon-intensity reduction pathways for European green chemistry procurement.
- Direct manufacturer-to-API producer channel development:Bypassing traditional chemical distributor markups through qualified supplier portals is capturing margin for both parties.
Industry Challenges
- Residual sulfide analytical capability gaps:Pharmaceutical buyers require sub-ppm detection thresholds that many regional testing laboratories cannot consistently deliver, extending qualification timelines.
- Multi-jurisdiction certification synchronization:Reconciling EPA TSCA Section 5 notifications with REACH annex requirements and China NMPA filing protocols strains regulatory affairs bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thioacetic Acid Market |
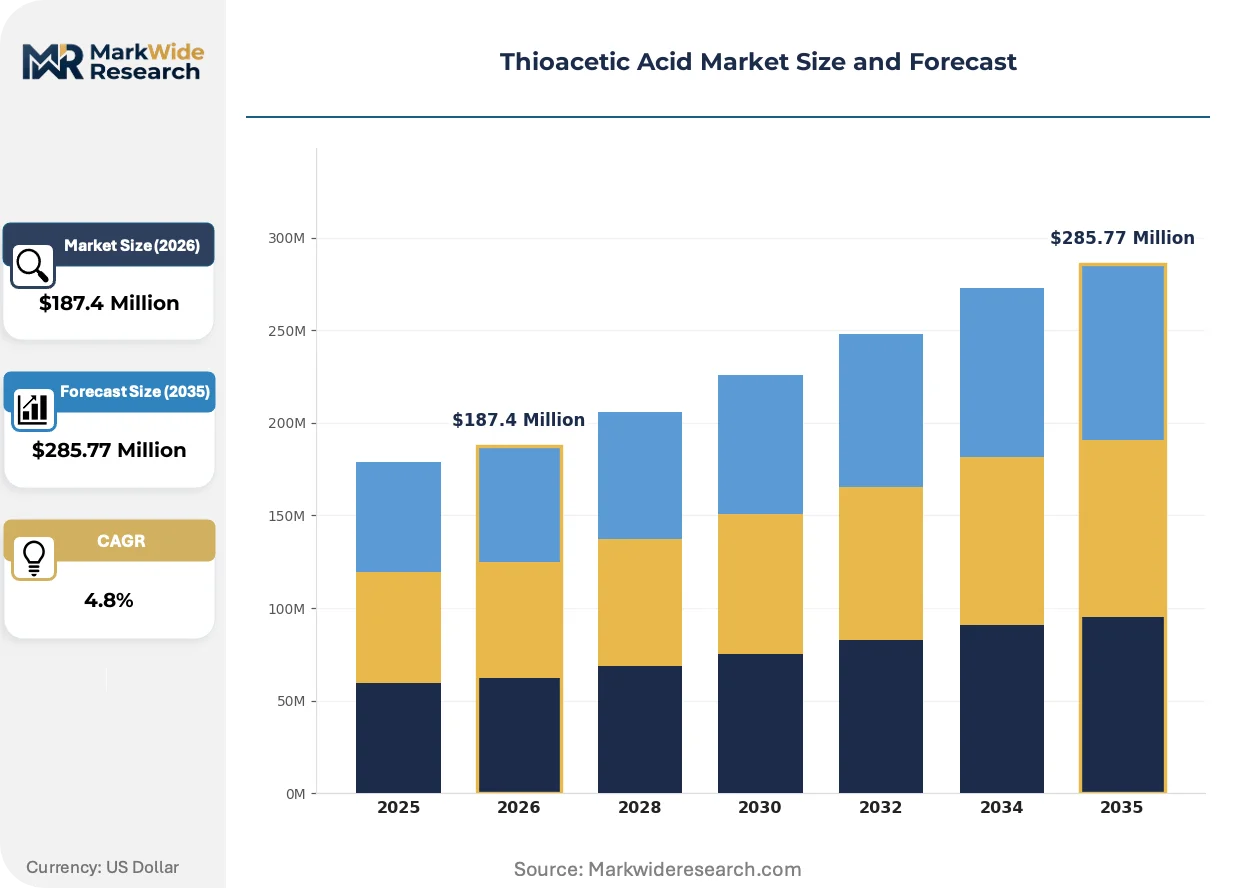
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Reagent Grade, Laboratory Grade, Pharmaceutical Grade End Use Industry: Chemicals, Pharmaceuticals, Agriculture, Textiles Form: Liquid, Solid, Powder, Crystals Distribution Channel: Direct Sales, Distributors, Online Retail, Chemicals Suppliers |
| Companies Covered | Arkema, Toyobo, Changzhou Jieying Chemical, Yancheng Liankai Chemical, Lianyungang Yaran Fine Chemicals, Shanghai Sinchao Fine Chemical, Taixing Zhongran Chemical, Toray Fine Chemicals, BRUNO BOCK Chemische Fabrik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thioacetic Acid Market Evolving Landscape
Continuous manufacturing architectures and regulatory data integrity requirements are recalibrating how thioacetic acid quality assurance integrates into downstream pharmaceutical production workflows.
Membrane-based sulfide removal systems are absorbing residual contaminant loads in thioacetic acid purification trains, enabling pharmaceutical-grade producers to meet tightened ICH Q3C residual solvent guidelines without thermal degradation of the thioester functionality. European API manufacturers with integrated quality units are adopting these systems fastest, compressing the competitive window for suppliers still relying on traditional distillation polishing.
REACH Annex XVII restrictions on persistent organic pollutant precursors are tightening thioacetic acid impurity profiling requirements for European import clearance, forcing non-EU producers to expand analytical method validation suites. The regulation most affects Chinese exporters serving German and Swiss pharmaceutical intermediates markets, who are responding by securing EU-based release testing partnerships.
Consignment inventory arrangements are displacing traditional spot purchasing among mid-scale pharmaceutical intermediates producers, with thioacetic acid suppliers bearing working capital burdens in exchange for multi-year offtake commitments. The model is most visible in North American generic API manufacturing, where FDA inspection backlogs have lengthened supplier qualification cycles and buyers seek supply security.
Thioacetic Acid Market Segmentation
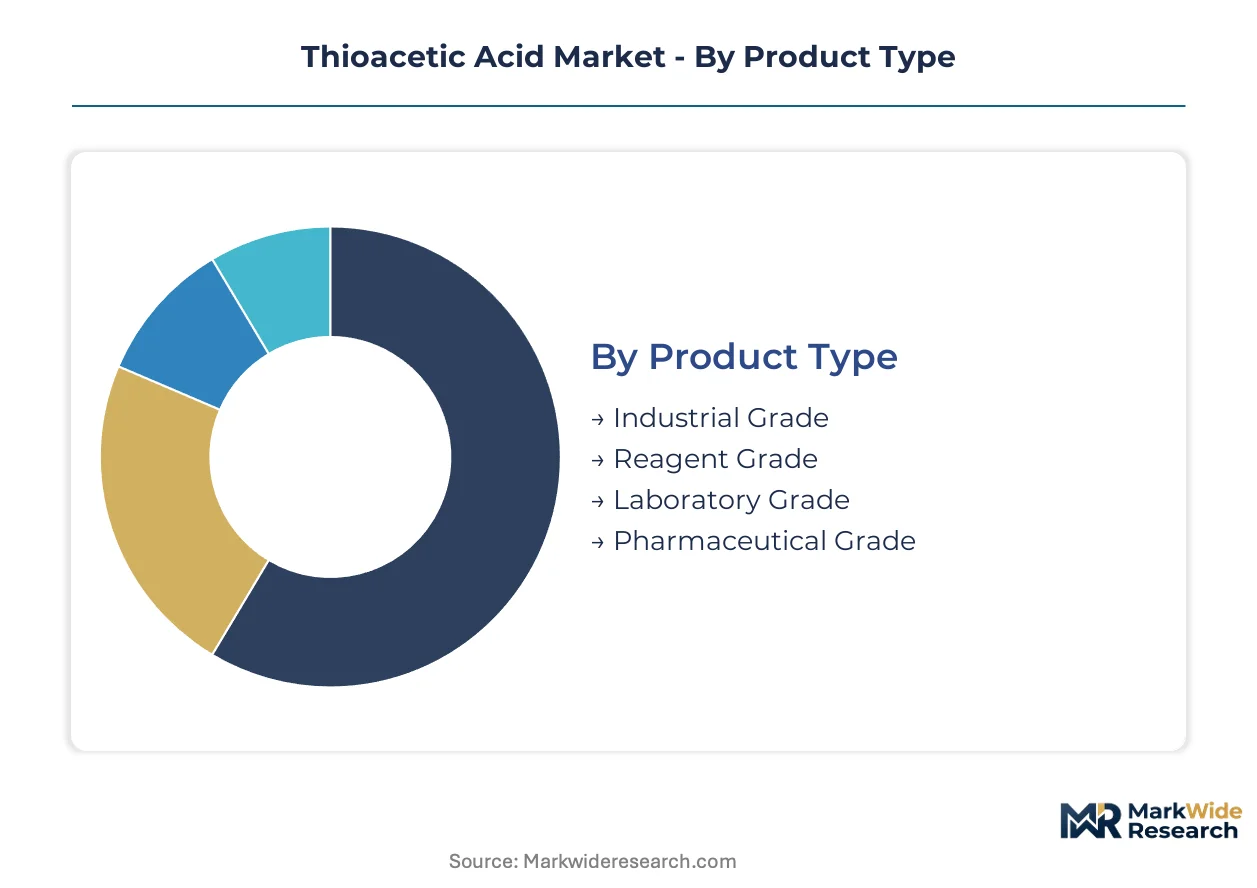
Segmentation in thioacetic acid markets tracks how purity specifications, physical form, and channel structure align with distinct value capture mechanisms across regulated and unregulated demand pools. Procurement patterns diverge sharply between bulk chemical manufacturing and pharmaceutical-grade qualification pathways.
Product Type:
Standardization intensity increases with regulatory burden across this spectrum, from commodity chemical specifications to dossier-grade documentation requirements.
- Pharmaceutical Grade:Stringent residual-sulfide thresholds below 10 ppm and full ICH Q3C solvent documentation define this tier. Demand concentrates among API manufacturers in Germany and Switzerland seeking REACH-registered supply with validated analytical methods.
- Reagent Grade:Purity levels of 98-99% with batch-specific certificates of analysis serve laboratory synthesis and analytical applications. Procurement is pivoting toward large-scale API producers with captive solvent-recovery infrastructure in Jiangsu province manufacturing clusters.
- Industrial Grade:Bulk thioacetic acid for agrochemical intermediates and textile auxiliaries, typically 90-95% purity with higher residual mercaptan content.
- Laboratory Grade:Small-volume packaging for academic and R&D use with basic specification sheets rather than full regulatory dossiers.
Most installed capacity flows through Industrial Grade. Expansion is steepest in Pharmaceutical Grade.
End Use Industry:
Application maturity varies from established polymerization chemistry to emerging bio-based acetyl precursor integration.
- Pharmaceuticals:Thioacetic acid functions as a thioacetylating agent in active ingredient synthesis, particularly for sulfur-containing heterocycles. Japanese high-performance fiber manufacturers and European generic API producers drive specification escalation through tightened impurity profiling.
- Chemicals:Polymerization regulator applications in controlled molecular-weight synthesis anchor volume demand. Toyobo's specialized polymer-grade output serves this segment with dedicated mercaptan-chemistry integration.
- Agriculture:Intermediate production for thiocarbamate herbicides and fungicide actives, facing substitution pressure from acetic anhydride-based thioacetylation in cost-sensitive applications.
- Textiles:Auxiliary applications in dye fixation and fiber modification, concentrated in Shandong province manufacturing bases serving domestic apparel supply chains.
Chemicals processing commands the largest volume throughput. Pharmaceuticals is climbing the fastest as CDSCO certification requirements under India's PLI scheme create new qualification pathways.
Form:
Handling economics and thermal stability constraints determine physical state selection across downstream process architectures.
- Liquid:Dominates commercial trade due to pumping efficiency in continuous-flow reactor systems and reduced atmospheric exposure during transfer. Jiangsu province producers have optimized acetyl chloride thiolation processes specifically for liquid output consistency.
- Solid:Stabilized formulations for transport security in high-temperature climates, particularly for Middle Eastern and Southeast Asian distribution.
- Powder:Specialized drying and anti-caking treatments for precise dosing in batch polymerization systems.
- Crystals:High-purity recrystallized material for analytical reference standards and exacting pharmaceutical applications.
Liquid form carries the majority of merchant volume. Crystals are gaining share fastest through pharmaceutical-grade certification protocols.
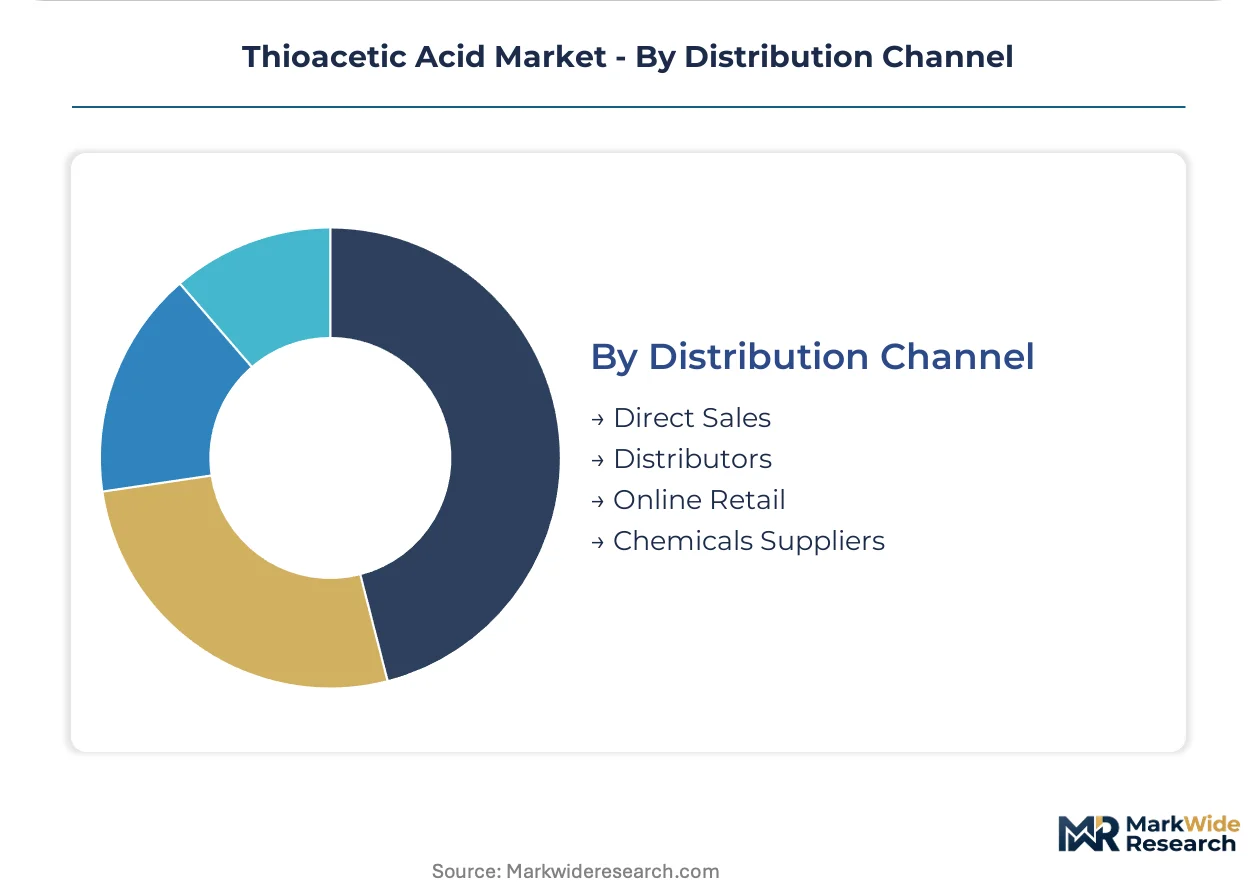
Distribution Channel:
Channel selection reflects buyer scale, qualification burden, and working capital positioning across the procurement spectrum.
- Direct Sales:Manufacturer-to-API producer relationships bypass traditional distributor markups, capturing margin for both parties. Consignment inventory arrangements are displacing spot purchasing among mid-scale North American generic API manufacturers facing FDA inspection backlogs.
- Distributors:Regional chemical distributors with warehousing and just-in-time delivery capabilities serve fragmented agrochemical and textile auxiliary demand.
- Chemicals Suppliers:Integrated fine chemical merchants offering thioacetic acid alongside complementary organosulfur reagents for laboratory and pilot-scale procurement.
- Online Retail:E-commerce platforms for small-volume laboratory and academic purchases with credit-card terms and rapid fulfillment.
Distributors handle the broadest geographic coverage. Direct Sales is expanding most quickly as qualified supplier portals consolidate long-term offtake commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands thioacetic acid manufacturing scale while Germany sets pharmaceutical-grade purity benchmarks. Japan's high-performance fiber sector sustains specialized polymer-grade demand. India is emerging as a qualification target under domestic production incentives.
China
Jiangsu and Shandong provinces host over two-thirds of merchant-grade capacity, with Changzhou manufacturing clusters optimizing acetyl chloride thiolation for liquid-form consistency. MEE wastewater-sulfide discharge standards elevate treatment capital for producers operating near ecological red lines. Taixing and Yancheng chemical parks concentrate fine chemical output serving both domestic API manufacturers and export markets.
Germany
REACH-registered supply with validated analytical methods anchors European pharmaceutical-grade procurement, particularly from generic API producers in the Rhine-Ruhr chemical corridor. ECHA compliance deadlines for thioacetic acid dossiers filter out non-compliant traders, concentrating volume among registered producers with toxicological documentation. Ludwigshafen and Leverkusen industrial zones integrate thioacetic acid into sulfur-heterocycle active ingredient synthesis.
Japan
Toyobo and Toray Fine Chemicals drive polymer-grade specification escalation for controlled molecular-weight synthesis in high-performance fiber applications. METI industrial standards shape impurity profiling requirements for domestic pharmaceutical intermediate supply. Osaka and Nagoya manufacturing bases maintain captive mercaptan-chemistry integration for quality assurance.
India
Domestic API producers under the PLI scheme seek qualified suppliers with DMF-ready documentation packages, creating new qualification pathways for CDSCO pharmaceutical-grade certification. CDSCO filing protocols strain regulatory affairs bandwidth for multinational suppliers entering the market. Gujarat and Maharashtra pharmaceutical clusters are expanding thioacetic acid offtake for sulfur-containing heterocycle synthesis.
United States
North American generic API manufacturers facing FDA inspection backlogs are adopting consignment inventory arrangements, displacing traditional spot purchasing. EPA TSCA Section 5 notification requirements constrain market entry through mandatory toxicological dossiers. New Jersey and Pennsylvania chemical corridors sustain reagent-grade demand from mid-scale pharmaceutical intermediates producers.
Thioacetic Acid Market Competitive Landscape
Chinese producers anchor volume-tier supply; European specialists hold pharmaceutical-grade certification advantages. The vendor base splits between scale-driven Jiangsu-Shandong manufacturers and quality-focused Western registrants with REACH dossiers. Three archetypes dominate: backward-integrated mercaptan chemistry operators, continuous-flow reactor specialists, and distributor-dependent regional suppliers. Capacity expansion in Jiangsu province and strategic partnerships for EU release testing represent the dominant competitive vectors.
Within the European specialist tier, Arkema and BRUNO BOCK Chemische Fabrik exemplify REACH-registered producers with toxicological documentation capabilities. Among Asian fabricators, Toyobo occupies a position in polymer-grade output for high-performance fiber applications, while Changzhou Jieying Chemical represents Jiangsu-based volume throughput. These three companies illustrate how geographic origin and regulatory positioning stratify competitive access to pharmaceutical versus industrial demand pools.
| Leading Market Players |
|---|
| Arkema |
| Toyobo |
| Changzhou Jieying Chemical |
| Yancheng Liankai Chemical |
| Lianyungang Yaran Fine Chemicals |
| Shanghai Sinchao Fine Chemical |
| Taixing Zhongran Chemical |
| Toray Fine Chemicals |
| BRUNO BOCK Chemische Fabrik |
| Others |
Value Network & Pricing Analysis
Pharmaceutical-grade certification ladders create stark divergence between REACH-registered European supply and commodity-grade Asian output, with this tier gap manifesting in both contract tenure structures and the geographic layering of inventory buffers. Jiangsu province producers command spot-market liquidity through volume throughput, while German and Swiss API manufacturers absorb working capital burdens via consignment arrangements to secure qualified supply.
Pricing Analysis
Capacity additions in Jiangsu province are reshaping price floors for reagent-grade material as continuous-flow reactor optimization compresses batch-to-batch variability costs. Three-tier pricing structure across pharmaceutical, reagent, and industrial grades reflects residual-sulfide thresholds and ICH Q3C documentation burdens. Cost compression in industrial-grade tiers intensifies because acetic anhydride substitution economics displace thioacetic acid in agrochemical applications. Mid-scale pharmaceutical intermediates producers exhibit highest price sensitivity, whereas large-scale API manufacturers with captive solvent-recovery infrastructure prioritize supply security over unit economics.
Supply Chain Analysis
Specialized chemical engineering talent shortages in Changzhou and Taixing chemical parks constrain expansion velocity for mercaptan-chemistry operations. Manufacturing gravity centers on China, Germany, and Japan, with feedstock supply anchored in refinery-derived hydrogen sulfide from crude sulfur recovery operations. Jiangsu-Shandong concentration creates single-region exposure to MEE wastewater enforcement actions. Distribution runs through qualified supplier portals for pharmaceutical-grade offtake and regional chemical distributors for agrochemical and textile auxiliary demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in thioacetic acid markets rests on pharmaceutical-grade certification premiums and continuous manufacturing cost-down curves, with membrane-based sulfide removal systems enabling producers to capture value from tightened ICH Q3C guidelines.
For Market Incumbents: Anticipate displacement pressure from acetic anhydride-based thioacetylation in cost-sensitive agrochemical applications by deepening REACH dossier advantages and securing EU-based release testing partnerships for Chinese export supply. Backward integration into mercaptan chemistry and captive hydrogen sulfide sourcing defend margin position against feedstock volatility. For New Entrants and Emerging Players: Capture qualification pathways under India's PLI scheme by assembling DMF-ready documentation packages for CDSCO pharmaceutical-grade certification, targeting Gujarat and Maharashtra pharmaceutical clusters with direct manufacturer-to-API producer channel development. Bio-based acetyl precursor integration via fermentation-derived acetic acid convergence opens carbon-intensity reduction positioning for European green chemistry procurement. For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory affairs bandwidth strains under multi-jurisdiction certification synchronization between EPA TSCA Section 5 notifications, REACH annex requirements, and China NMPA filing protocols. Acquisition targets with validated analytical methods for sub-ppm residual sulfide detection and established consignment inventory arrangements with North American generic API manufacturers offer durable positioning. Watch for FDA inspection backlog resolution as inflection indicator for spot-to-contract purchasing mix normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mercaptan Chemistry | Arkema's captive supply of hydrogen sulfide feedstock insulates margin from crude sulfur price spikes. |
| Continuous-Flow Reactor Optimization | Jiangsu province manufacturers reduce batch-to-batch variability for reagent-grade liquid output consistency. |
| Membrane-Based Sulfide Removal Systems | European API manufacturers adopt purification trains enabling ICH Q3C compliance without thermal degradation. |
| EU Release Testing Partnerships | Chinese exporters secure German and Swiss market access under REACH Annex XVII impurity profiling requirements. |
| Consignment Inventory Arrangements | North American generic API manufacturers displace spot purchasing to secure supply amid FDA inspection backlogs. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at Jiangsu and Shandong manufacturing facilities, procurement leads at European generic API producers, distribution channel partners serving agrochemical intermediates markets, and technical R&D directors overseeing mercaptan-chemistry integration. Secondary validation drew from customs and trade data, SEC 10-K filings of listed chemical producers, ECHA registration dossiers, and MEE wastewater discharge compliance records. Bottom-up capacity and utilization estimates triangulated against top-down demand modeling from end-use industry consumption patterns.
Segment-weighting approaches applied differential growth assumptions across pharmaceutical-grade, reagent-grade, and industrial-grade tiers, with further disaggregation by liquid versus solid form factors and direct sales versus distributor channel structures. CAGRs were derived from regression analysis of historical price-volume relationships and forward projection of regulatory compliance cost burdens. Forecast inputs incorporated hydrogen sulfide feedstock cost trajectories, REACH registration deadline impacts on trader participation, and PLI scheme incentive effects on Indian API manufacturing expansion.
Underlying measurement precision varies by segment; pharmaceutical-grade volume carries tighter precision than industrial-grade given consolidated buyer concentration and contract visibility. Forecasts reflect assumptions regarding MEE enforcement continuity, ECHA dossier acceptance rates, and CDSCO certification timeline standardization. Material deviation in crude sulfur price volatility, FDA inspection throughput, or dual carbon policy stringency warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Polyphosphoric Acid (PPA) Market
Chemicals
Asia-Pacific Acetic Acid Market
Chemicals
North America Ethylene Dichloride (EDC) Market
Chemicals
Benzalkonium Bromide Market
Chemicals
Ammonia Market
Chemicals
Global Glycine Market
Chemicals
Isoamyl Acetate Market
Chemicals
Etching Chemicals Market
Chemicals
Phenothiazine Market
Chemicals
Asia-Pacific Surface Treatment Chemicals Market
Chemicals
Sodium Phosphate Tribasic Market
Chemicals
Fireworks Market
Chemicals
Sodium Aluminum Hydride Market
Chemicals
Amyl Nitrite Market
Chemicals
Fluorochemicals Market
Chemicals
Perchloric Acid Market