
 Global N-Butanol Market | 2026-2036
Global N-Butanol Market Size, Share, and Industry Trends Forecast 2026-2036
Global N-Butanol Market Analysis
Specialty coatings formulators is rotating toward bio-butanol blends as architectural and automotive OEM specifications tighten VOC thresholds. BASF SE leverages its integrated Ludwigshafen complex to sustain captive supply of high-purity grades for European coatings houses. OQ Chemicals anchors its position through backward integration into propylene feedstock at its Oberhausen site. Dow Chemical Company competes on manufacturing scale across Gulf Coast assets, while Sasol Limited differentiates via Fischer-Tropsch-derived butanol streams from Secunda.
N-butanol is a four-carbon primary alcohol with molecular formula C₄H₉OH, produced industrially through propylene hydroformylation followed by hydrogenation of the resulting butyraldehyde; it serves as a versatile solvent and chemical intermediate for butyl acrylate, butyl acetate, and glycol ether manufacturing. Normal butanol occupies the dominant volume share given its entrenched role in acrylic ester production for adhesives and coatings, though bio-butanol derived from agricultural feedstocks is gaining fastest traction as refiners seek lower-carbon intensity pathways under EU Green Deal benchmarks. Chemical intermediate applications command the deepest margin pools due to long-term offtake contracts with downstream polymer producers, while fuel additive demand remains structurally constrained by blend-wall limitations in gasoline specifications.
EPA hazardous air pollutant standards under the National Emission Standards for Hazardous Air Pollutants constrain US solvent recovery operations, while REACH registration requirements in Europe mandate exhaustive toxicity dossiers for butanol imports above one tonne annually. China's MEE enforces volatile organic compound emission caps at chemical parks in Shandong and Jiangsu provinces, forcing capacity consolidation toward integrated sites. Stakeholders must monitor carbon border adjustment mechanism developments and decide between retrofitting existing propylene-based assets or licensing fermentation technology for bio-butanol scale-up.
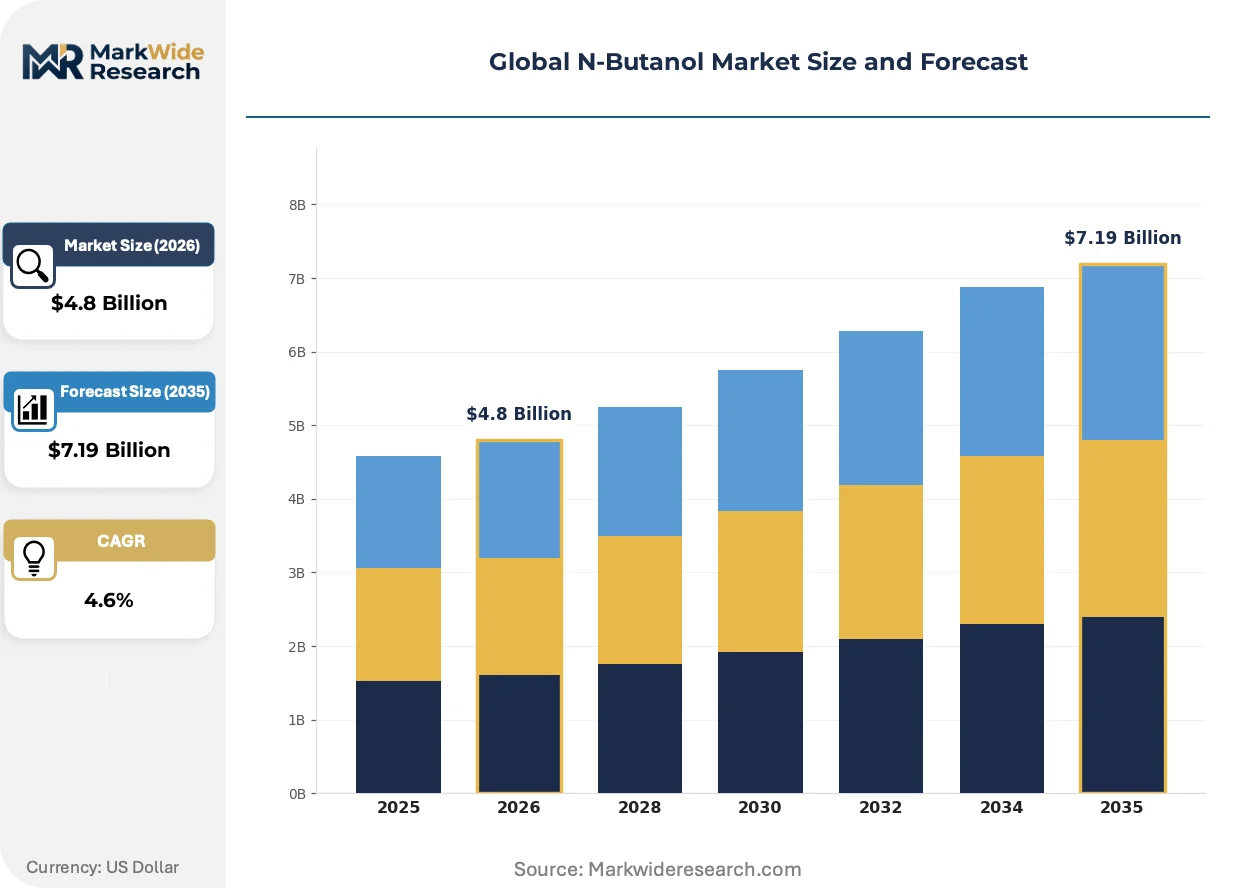
Market Dynamics
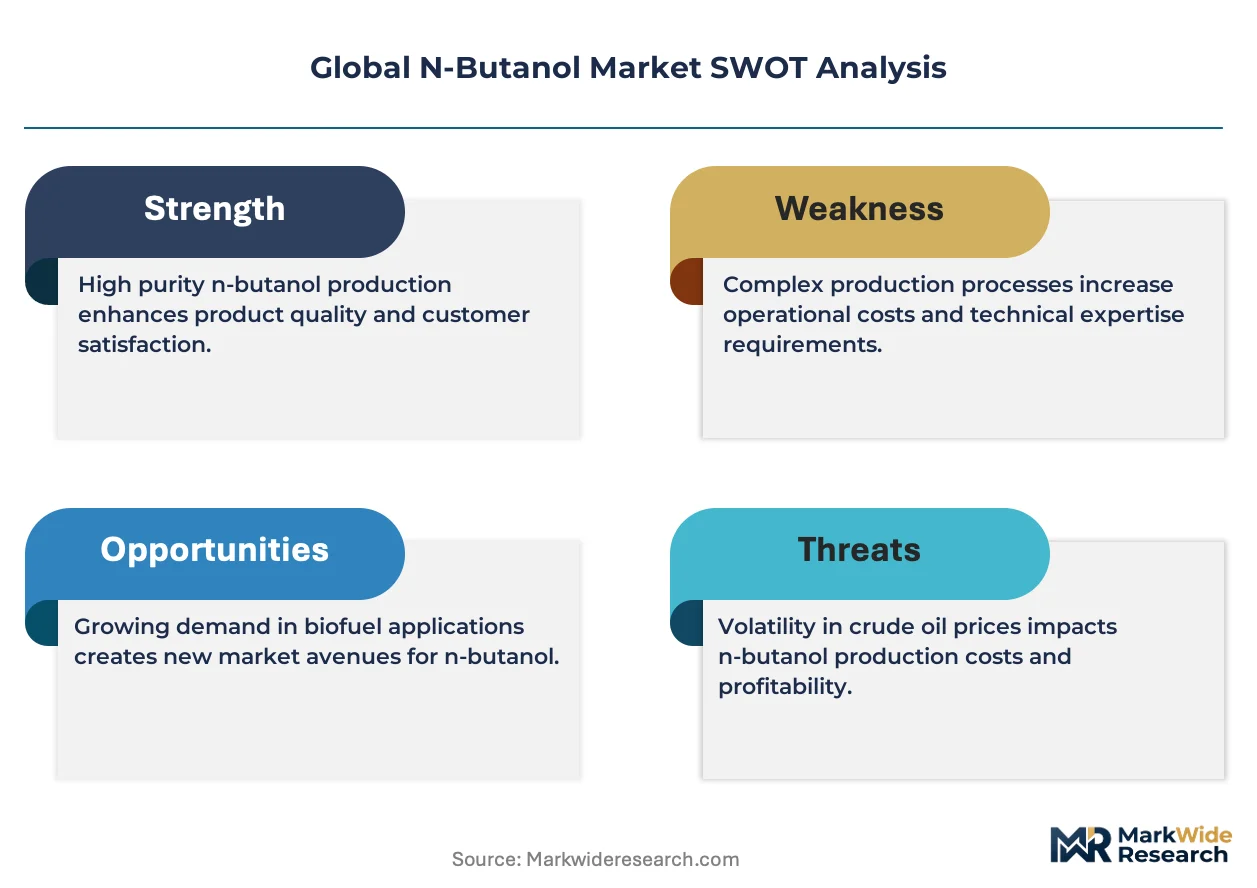
Propylene feedstock volatility and REACH-driven purity mandates are compressing margins for non-integrated n-butanol producers while accelerating consolidation toward backward-integrated petrochemical complexes.
Growth Catalysts
- Acrylic ester demand:Specialty coatings manufacturers in Germany and the Netherlands are expanding offtake for high-performance automotive OEM finishes, tightening VOC specifications under EU Green Deal benchmarks.
- MEE emission caps:China's Ministry of Ecology and Environment is forcing capacity consolidation toward integrated sites in Ningbo and Zhenjiang, capturing downstream derivative value chains.
- Fischer-Tropsch pathways:Synthetic fuel complexes in South Africa are diversifying into alcohol streams, creating alternative supply origins for European chemical intermediate buyers.
Market Restraints
- Propylene cost volatility:Crude-linked naphtha cracking economics transmit directly to hydroformylation feedstock costs, squeezing standalone butanol units without upstream integration.
- Blend-wall constraints:Gasoline specifications in the United States cap fuel additive incorporation, structurally limiting bio-butanol penetration in transportation applications.
- REACH dossier burdens:ECHA registration requirements for imports above one tonne annually impose exhaustive toxicity documentation costs on non-EU suppliers.
Strategic Opportunities
- Fermentation scale-up:Agricultural feedstock-derived bio-butanol offers lower-carbon intensity pathways under EU Green Deal carbon border adjustment mechanisms, attracting refinery retrofit investments.
- Shandong consolidation:China's chemical park rationalization is displacing small-scale producers, creating acquisition targets for integrated operators seeking captive solvent supply.
- Butyl acrylate integration:Long-term offtake contracts with downstream polymer producers in the coatings and adhesives sectors command premium margin pools through volume commitments.
Industry Challenges
- EPA NESHAP compliance:Hazardous air pollutant standards for solvent recovery operations in the United States require capital-intensive emission control retrofits at aging Gulf Coast facilities.
- Dual carbon alignment:China's national carbon neutrality targets are accelerating feedstock transition timelines, forcing simultaneous propylene optimization and bio-route piloting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global N-Butanol Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Normal Butanol, Isobutanol, Bio-Butanol, Others Application: Solvent, Chemical Intermediate, Fuel Additive, Coatings End User: Automotive, Chemicals, Paints, Pharmaceuticals Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | OQ Chemicals, SABIC, BASF SE, Formosa Plastics Corporation, Sasol Limited, Dow Chemical Company, Mitsubishi Chemical Corporation, Petronas Chemicals Group Berhad, Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global N-Butanol Market Emerging Trajectories
Process intensification and carbon accounting transparency are reshaping competitive positioning in n-butanol manufacturing, with purity grades and provenance documentation becoming primary differentiation vectors.
Membrane separation technology for aldehyde hydrogenation effluent purification is miniaturizing downstream distillation requirements. Specialty coatings formulators in Belgium and Italy are adopting these compact units to secure pharmaceutical-grade butanol for high-solids resin synthesis. The technology is compressing capital intensity thresholds for mid-scale entrants previously excluded by fired-heater economics.
REACH registration requirements are tightening purity specifications for butanol imports above one tonne annually, mandating exhaustive toxicity dossiers that favor established European producers with existing ECHA submissions. Asian exporters without pre-registered substances face extended qualification timelines, redirecting spot volumes toward Middle Eastern and African markets with less stringent chemical safety frameworks.
Architectural and automotive OEM specifications are tightening VOC thresholds, rotating procurement toward bio-butanol blends with certified carbon intensity scores. German coatings houses are unbundling solvent supply contracts from resin purchasing, creating standalone butanol tender processes that reward documented renewable content. This pattern is most visible in the Benelux cluster, where integrated petrochemical buyers are establishing separate sustainability-grade procurement lanes.
Global N-Butanol Market Segmentation
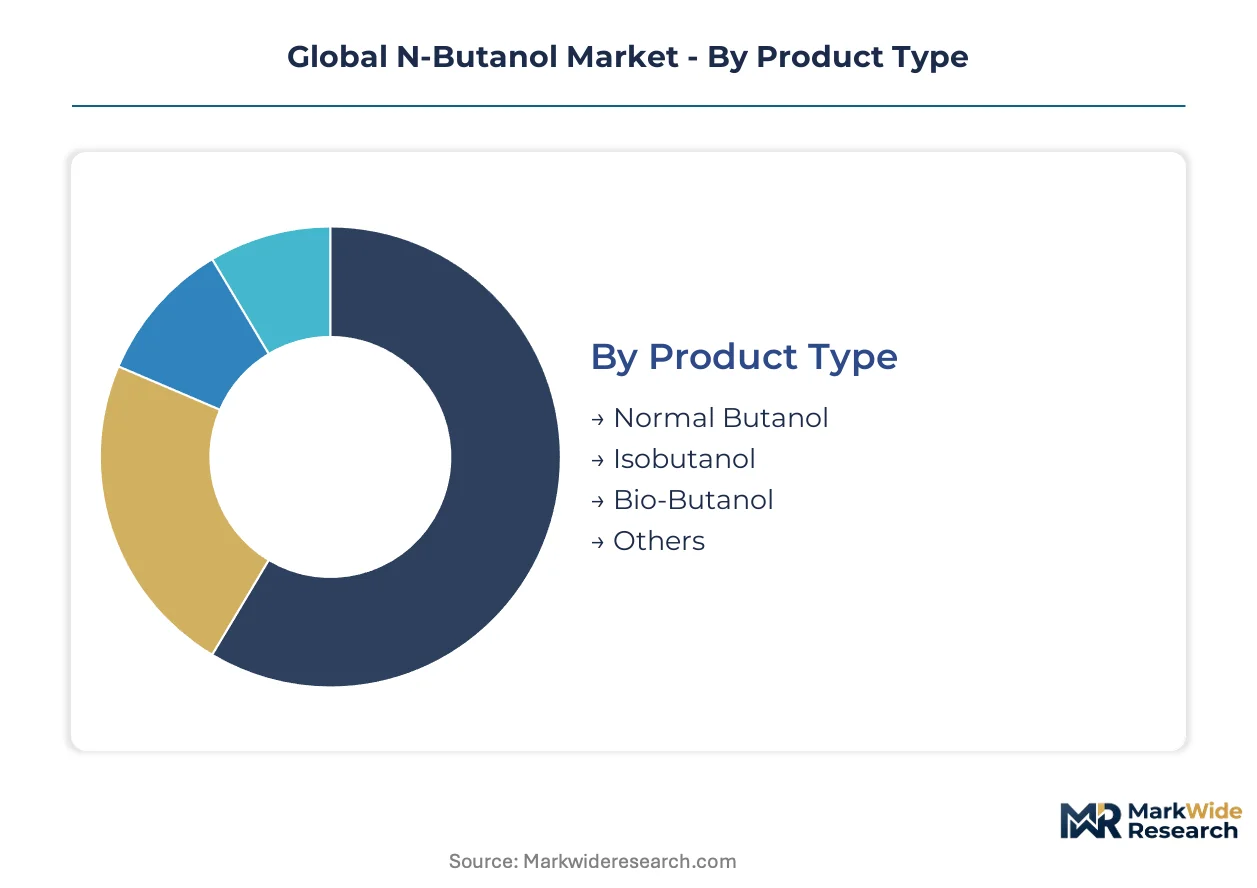
Segmentation in the n-butanol market determines margin capture and regulatory exposure. Product chemistry dictates feedstock sourcing and carbon intensity scoring. Application mix shapes contract structures and geographic concentration of demand.
Product Type:
Normal butanol faces substitution pressure from bio-derived alternatives as EU Green Deal carbon accounting tightens procurement specifications. Isobutanol competes on octane enhancement in fuel applications. Bio-butanol carries premium positioning under emerging border adjustment mechanisms.
- Normal Butanol:Four-carbon primary alcohol produced via propylene hydroformylation and subsequent hydrogenation of butyraldehyde. Demand concentrates in German and Dutch coatings houses for butyl acrylate production, where REACH-registered supply chains command preference over unregistered Asian imports.
- Isobutanol:Branched-chain isomer with superior blending characteristics in gasoline formulations. Fuel additive specifications in the United States absorb volumes from South African Fischer-Tropsch complexes, though blend-wall constraints cap penetration rates.
- Bio-Butanol:Fermentation-derived from agricultural feedstocks with certified renewable content. German coatings formulators unbundle solvent contracts to source separately, rewarding documented carbon intensity scores.
- Others:Specialty grades including pharmaceutical and electronic purity specifications. Belgian membrane separation technology enables compact production for high-solids resin synthesis.
Normal butanol retains volume leadership; bio-butanol holds the steepest expansion curve.
Application:
Margin pools vary sharply across applications, with chemical intermediates commanding long-term offtake contracts and solvents facing emission-control compliance burdens.
- Solvent:Recovery operations in US Gulf Coast facilities face EPA NESHAP retrofit requirements. Architectural coatings specifications tighten VOC thresholds in Benelux markets.
- Chemical Intermediate:Butyl acrylate and butyl acetate production anchor demand from downstream polymer producers. Shandong chemical park consolidation in China displaces small-scale units toward integrated Ningbo and Zhenjiang complexes.
- Fuel Additive:Gasoline blend-wall specifications structurally constrain US market penetration. South African synthetic fuel complexes diversify into alcohol streams for European buyers.
- Coatings:Automotive OEM finishes in Germany absorb high-purity grades. BASF's Ludwigshafen complex supplies captive volumes to European coatings houses.
Chemical intermediate applications generate the deepest margin pools; fuel additive demand faces structural ceiling effects.
End User:
Customer concentration and contract duration differentiate end-use segments, with automotive and pharmaceutical buyers imposing the strictest purity documentation.
- Automotive:OEM coating specifications in Germany and the Netherlands drive high-performance acrylic resin demand. Long-term supply agreements predominate.
- Chemicals:Integrated petrochemical buyers in China capture downstream derivative value through captive butanol-to-acrylate chains. MEE emission caps accelerate consolidation.
- Paints:Architectural formulators rotate procurement toward bio-butanol blends with certified renewable content. Separate sustainability-grade procurement lanes emerge in Benelux.
- Pharmaceuticals:Pharmaceutical-grade specifications require membrane purification technology. Belgian and Italian formulators adopt compact units for high-solids synthesis.
Chemical end users concentrate procurement volume; pharmaceutical buyers impose the steepest purity premiums.
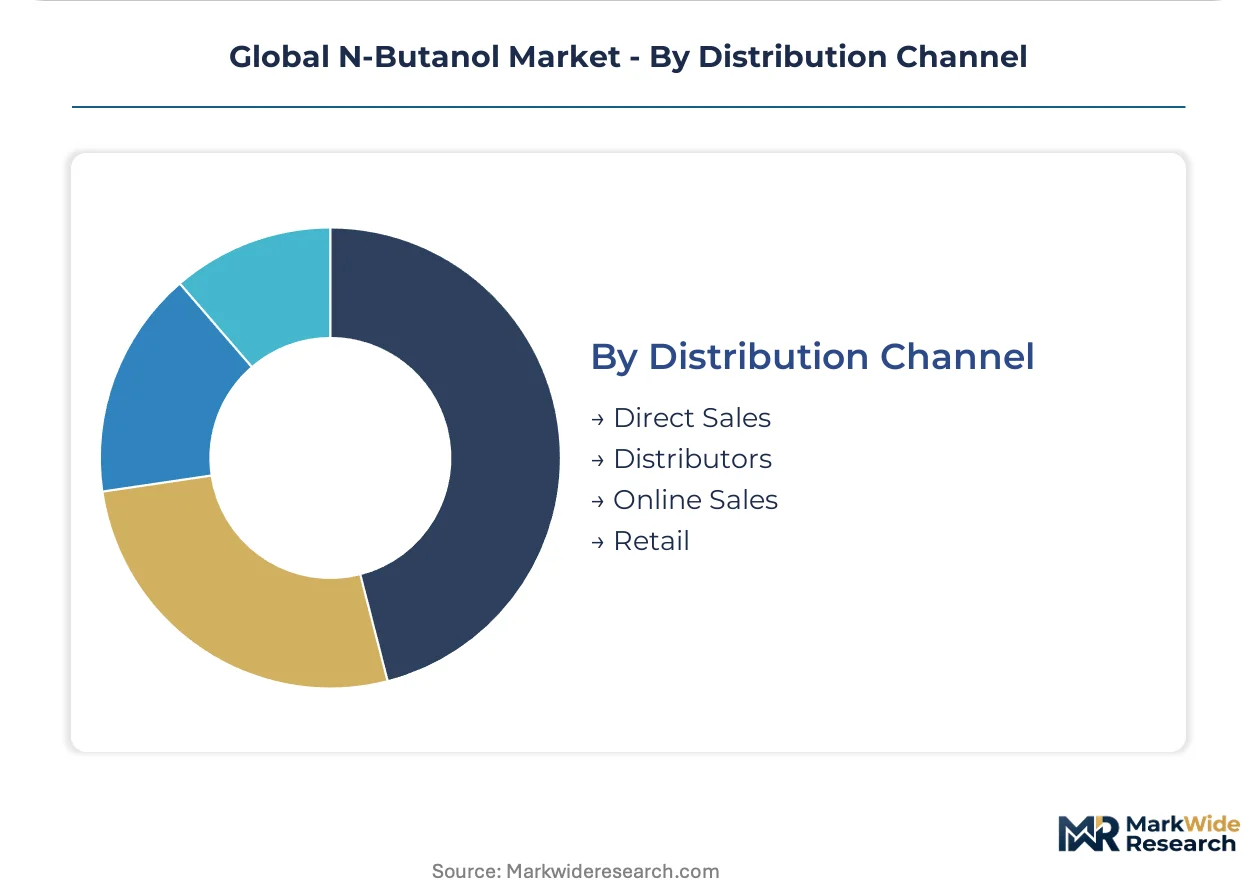
Distribution Channel:
Channel selection reflects shipment scale, documentation requirements, and geographic proximity to integrated production assets.
- Direct Sales:Long-term offtake contracts with downstream polymer producers predominate. Dow Chemical's Gulf Coast assets supply major coatings houses directly.
- Distributors:Regional solvent blenders and mid-scale formulators access spot volumes. REACH registration gaps redirect Asian exports toward Middle Eastern and African markets.
- Online Sales:Limited to standardized industrial grades with established safety documentation. Small-batch pharmaceutical and electronic purity specifications remain relationship-driven.
- Retail:Minimal penetration given bulk shipment economics and hazardous material handling requirements. Specialty laboratory supply houses serve niche volumes.
Direct sales anchor contract volume; distributor channels absorb spot market volatility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated petrochemical complexes in China, Germany, and the United States concentrate supply capacity for n-butanol derivatives. Regulatory divergence across REACH, EPA NESHAP, and China's MEE emission frameworks fragments qualification pathways. Demand clusters concentrate in automotive coatings corridors and chemical intermediate hubs.
China
MEE emission caps at Shandong chemical parks are displacing small-scale butanol producers toward integrated Ningbo and Zhenjiang complexes. Dual carbon targets accelerate feedstock transition timelines for propylene-based assets. Yangtze River Delta petrochemical buyers capture downstream derivative value through captive butanol-to-acrylate chains.
Germany
REACH registration requirements mandate exhaustive toxicity dossiers for butanol imports above one tonne annually. EU Green Deal carbon accounting tightens procurement specifications for automotive OEM coating applications. Ludwigshafen and Oberhausen industrial clusters anchor high-purity supply to Benelux coatings houses.
United States
EPA NESHAP standards constrain solvent recovery operations at Gulf Coast facilities, requiring capital-intensive emission control retrofits. Architectural coatings specifications tighten VOC thresholds in Southeast and Midwest markets. Dow Chemical's Texas-Louisiana assets supply major coatings houses through direct long-term contracts.
South Africa
Fischer-Tropsch synthetic fuel complexes at Secunda diversify into alcohol streams for European chemical intermediate buyers. Blend-wall constraints in US gasoline specifications redirect fuel-grade volumes toward industrial solvent applications. Sasol Limited anchors alternative supply origins for buyers seeking non-propylene feedstock pathways.
Japan
METI industrial standards shape purity specifications for electronic-grade butanol in semiconductor manufacturing clusters. Mitsubishi Chemical Corporation's Chubu region facilities serve pharmaceutical and specialty coatings formulators. Kanto and Kansai industrial corridors concentrate demand for high-solids resin synthesis applications.
Global N-Butanol Market Vendor Landscape
Concentration sits with backward-integrated petrochemical majors controlling propylene feedstock and hydrogenation assets. The competitive terrain splits between European REACH-registered incumbents, Gulf Coast scale operators, and Asian integrated complexes capturing downstream value. Three archetypes dominate: petrochemical majors with captive feedstock, regional specialists with fermentation pilot capacity, and Fischer-Tropsch diversifiers from synthetic fuel origins. Consolidation accelerates through chemical park rationalization in China and emission-control retrofit requirements in the United States.
Among German-headquartered incumbents, BASF SE and OQ Chemicals exemplify the REACH-registered archetype with established ECHA dossiers. Dow Chemical Company represents the scale-driven Gulf Coast operator with direct supply relationships to coatings houses. Sasol Limited anchors the Fischer-Tropsch diversification pathway from South African synthetic fuel complexes.
| Leading Market Players |
|---|
| OQ Chemicals |
| SABIC |
| BASF SE |
| Formosa Plastics Corporation |
| Sasol Limited |
| Dow Chemical Company |
| Mitsubishi Chemical Corporation |
| Petronas Chemicals Group Berhad |
| Eastman Chemical Company |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between German coatings houses and Ludwigshafen-based producers lock in propylene-linked price visibility while insulating buyers from spot volatility in Asian export markets. These structures concentrate procurement power among REACH-registered incumbents who can guarantee purity documentation for automotive OEM specifications.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, industrial-standard, and fuel-blend economy levels separates buyers by certification burden and volume commitment. Price differentiation hinges on REACH registration status and carbon intensity scoring under EU Green Deal benchmarks. Cost compression in standard industrial grades is intensifying because Shandong chemical park consolidation is flooding spot markets with displaced capacity. Mid-scale solvent blenders exhibit acute price sensitivity, while pharmaceutical formulators absorb premiums for membrane-purified supply.
Supply Chain Analysis
Port congestion at Rotterdam and Antwerp is elevating inbound logistics costs for propylene feedstock arriving from Middle Eastern crackers, compressing margins for non-integrated European units. Supply concentrates in China, Germany, and the United States, with production anchored in Ningbo, Ludwigshafen, and Texas-Louisiana corridors. The chain draws from propylene, syngas, and agricultural feedstock origins, exposing buyers to naphtha-cracking economics and fermentation crop yields. Single-source vulnerability runs through Fischer-Tropsch-derived streams from Secunda. Distribution runs through direct sales to downstream polymer producers and regional distributor networks serving spot buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The n-butanol market sits at a platform-economics inflection where carbon accounting interoperability between EU ETS and emerging Chinese national ETS is reshaping contract structures. This ecosystem shift rewards producers who can document feedstock provenance across dual compliance frameworks.
For Market Incumbents: Fortify backward integration into propylene feedstock or syngas streams to defend against bio-butanol fermentation entrants exploiting agricultural subsidy pathways. Prioritize REACH dossier updates for pharmaceutical-grade certifications before ECHA deadline pressures intensify. Capture Shandong consolidation targets to secure captive solvent supply for Yangtze River Delta acrylate chains. For New Entrants and Emerging Players: ECHA fast-track registration for imports above one tonne annually opens white-space access to Benelux coatings houses unbundling solvent procurement from resin contracts. Target pharmaceutical-grade membrane purification in Belgium and Italy where incumbent capacity is constrained by fired-heater economics. Lead with certified renewable content documentation to penetrate sustainability-grade procurement lanes. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors Fischer-Tropsch diversifiers with alternative feedstock pathways and fermentation pilots with agricultural offtake agreements. Long-term viability hinges on carbon border adjustment mechanism alignment and dual carbon target compliance in China. Watch for MEE emission cap enforcement intensity as the inflection signal for Chinese capacity rationalization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Feedstock | OQ Chemicals' Oberhausen model insulates margin from naphtha volatility. |
| Fermentation Technology Licensing | Agricultural feedstock pathways attract refinery retrofit capital under EU Green Deal. |
| REACH Dossier Expansion | ECHA registration gaps redirect Asian spot volumes toward less regulated markets. |
| Shandong Chemical Park Acquisition | MEE emission caps displace small-scale units toward integrated Ningbo operators. |
| Membrane Separation Scale-Up | Belgian compact units enable pharmaceutical-grade production for high-solids resins. |
Methodological Framework
A spread of perspectives from plant managers at integrated petrochemical complexes, procurement leads at downstream coatings OEMs, distribution channel partners in Benelux markets, and technical R&D directors at fermentation pilot facilities converged on the working assumptions. These primary inputs were cross-referenced against customs and trade data from Yangtze River Delta port authorities, ACC and Cefic industry reports, SEC 10-K filings from listed chemical majors, and EPA NESHAP compliance disclosures. Bottom-up capacity assessments triangulated with top-down demand modeling across acrylic ester, solvent, and fuel additive applications.
Segmentation dimensions modeled include grade tier (pharmaceutical, industrial, fuel-blend), end-use industry (automotive OEM, architectural coatings, pharmaceutical synthesis), and regional production hub configuration (integrated petrochemical complex, standalone unit, fermentation pilot). CAGRs were derived from elasticity-adjusted demand projections and capacity expansion timelines across the projection horizon. Industry-specific forecast inputs incorporated propylene hydroformylation yield rates and EU carbon border adjustment mechanism phase-in assumptions.
Underlying assumptions cover REACH registration continuity, MEE emission cap enforcement trajectories, and propylene-naphtha price correlation stability, with deviation risk concentrated in agricultural feedstock cost spikes and dual carbon policy acceleration in China. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Azodicarbonamide (ADC) Market
Chemicals
Diethyl Sulfate Market
Chemicals
Egypt Acidulants Market
Chemicals
Industrial Hydrofluoric Acid Market
Chemicals
Sodium Azide Market
Chemicals
Global Zinc Pyrithione Market
Chemicals
Hexafluorosilicic Acid Market
Chemicals
Benzoyl Alcohol Market
Chemicals
Lanthanum Nitrate Market
Chemicals
Leather Tanning Chemicals Market
Chemicals
Heptaldehyde Market
Chemicals
Methyl P-Hydroxybenzoate Market
Chemicals
Betaine Market
Chemicals
Global Electronic Grade Phosphoric Acid Market
Chemicals
4-Dichlorodiphenyl Sulfone (DCDPS) Market
Chemicals
Hydrophobing Agents Market