
 Household Paper Market | 2026-2036
Household Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Household Paper Market Intelligence
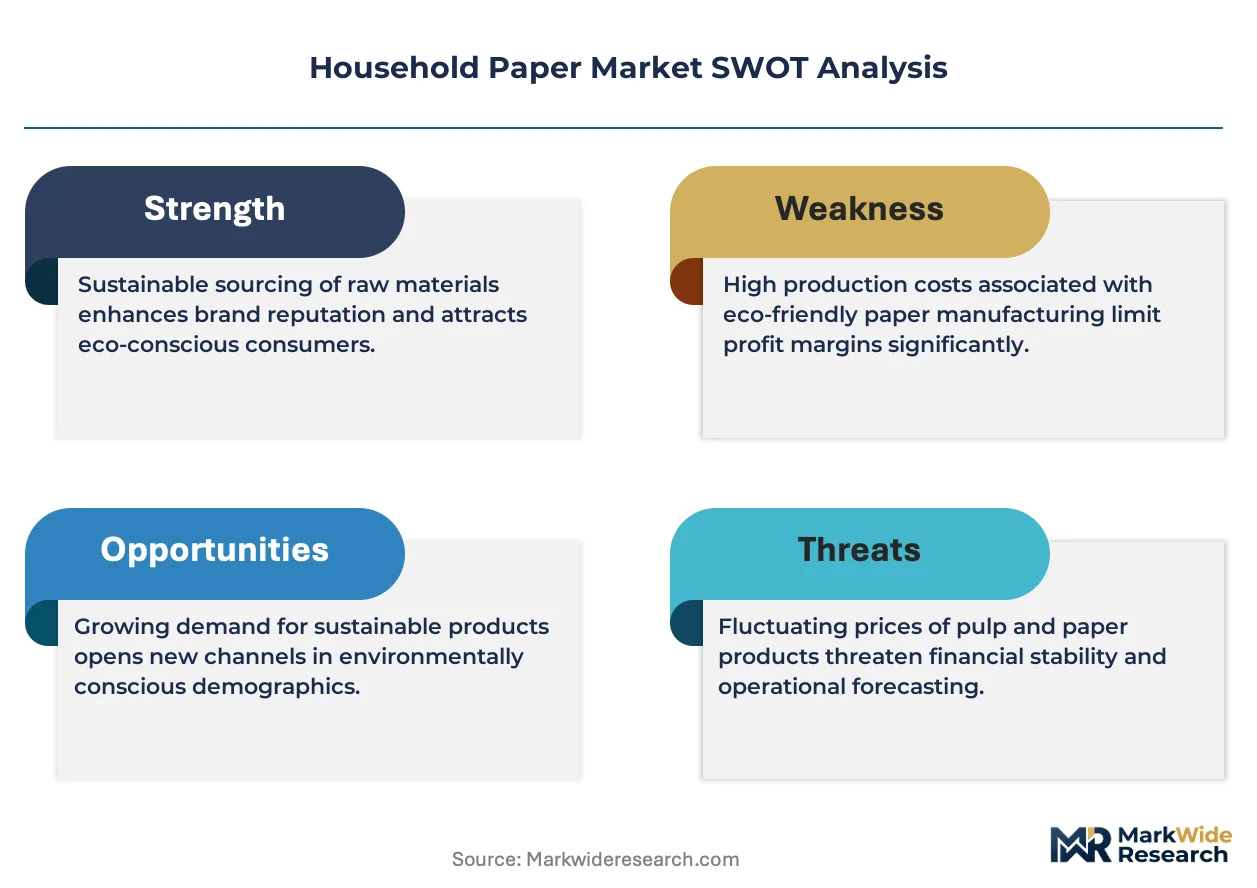
Expertise in sustainable pulp sourcing and circular economy models is redrawing the competitive landscape for household paper manufacturers. This shift prioritizes supply chain transparency and eco-certification. Procter & Gamble competes heavily on brand recognition and product innovation in premium segments. Essity leverages its strong focus on sustainability and professional hygiene solutions to gain market share. Kimberly-Clark sustains its position through extensive global distribution networks and brand loyalty.
Household paper encompasses a category of lightweight, disposable paper products engineered for absorbency, softness, and strength. These products, such as toilet paper and paper towels, are defined by technical parameters like basis weight and ply count, which determine their functional properties for personal hygiene and cleaning tasks. While toilet paper and paper towels represent mature, high-volume product types, the material segment is experiencing a notable shift. Demand for products made from recycled paper and bamboo is accelerating due to consumer-driven sustainability preferences.
The market operates under various environmental and health regulations that influence manufacturing and material sourcing. Standards from the Forest Stewardship Council (FSC) govern sustainable forestry practices, while bodies like the US EPA set guidelines for recycled content in paper products. Concurrently, EU directives on packaging waste push manufacturers toward more eco-friendly packaging solutions. Navigating the balance between raw material cost volatility and the investment required for sustainable product innovation remains the central strategic challenge for producers.
Market Dynamics
The central dynamic shaping the household paper market is the consumer-driven push for sustainability, which intersects with volatile raw material costs. This tension forces manufacturers to innovate in alternative fibers and circular economy models while managing margin pressures from fluctuating pulp prices.
Growth Catalysts
- Hospitality Sector Growth:Expansion in the global hotel and restaurant industry, especially in tourism-focused economies, directly increases consumption of away-from-home products like paper towels and napkins, driving volume demand.
- Hygiene Modernization in India:Rising disposable incomes and public health initiatives promoted by bodies like the FSSAI are accelerating the adoption of household paper products in India, shifting consumption from traditional cloths to disposable options.
- EU Green Deal Implementation:European Union policies are creating demand for products with high recycled content and plastic-free packaging, incentivizing producers to invest in certified sustainable materials and processes to access premium market segments.
Market Restraints
- Pulp Price Volatility:The cost of virgin wood pulp, a primary raw material, is subject to significant price swings linked to global forestry supply, energy costs, and logistics, creating margin instability for producers.
- Substitution from Air Dryers:In commercial and institutional settings, high-efficiency electric hand dryers present a direct substitution threat to paper towels, reducing long-term consumption volumes in high-traffic restrooms.
- Water Consumption in Manufacturing:The high water intensity of the pulping and papermaking process faces increasing scrutiny and regulatory pressure in water-stressed regions, potentially raising operational costs and limiting plant expansion.
Strategic Opportunities
- Alternative Fiber Development:Investing in supply chains for non-wood fibers like bamboo, wheat straw, or bagasse offers a path to differentiate products on sustainability metrics and reduce dependence on traditional wood pulp.
- Direct-to-Consumer Channels:Establishing subscription-based e-commerce platforms allows brands to bypass retail intermediaries, build direct customer relationships, and capture higher margins, especially for niche or premium eco-friendly products.
- Private Label Partnerships:Collaborating with major retailers to produce high-quality private label lines presents a significant volume opportunity, tapping into consumer demand for value without sacrificing performance.
Industry Challenges
- Recycled Fiber Quality:Managing the inconsistent quality and potential contaminants in post-consumer recycled paper feedstock is a persistent operational challenge, requiring advanced sorting and cleaning technologies to meet product standards.
- Packaging Machinery Retooling:The transition away from plastic shrink-wrap to paper-based or compostable packaging formats necessitates significant capital expenditure to retool or replace existing packaging lines, slowing the pace of change.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Household Paper Market |
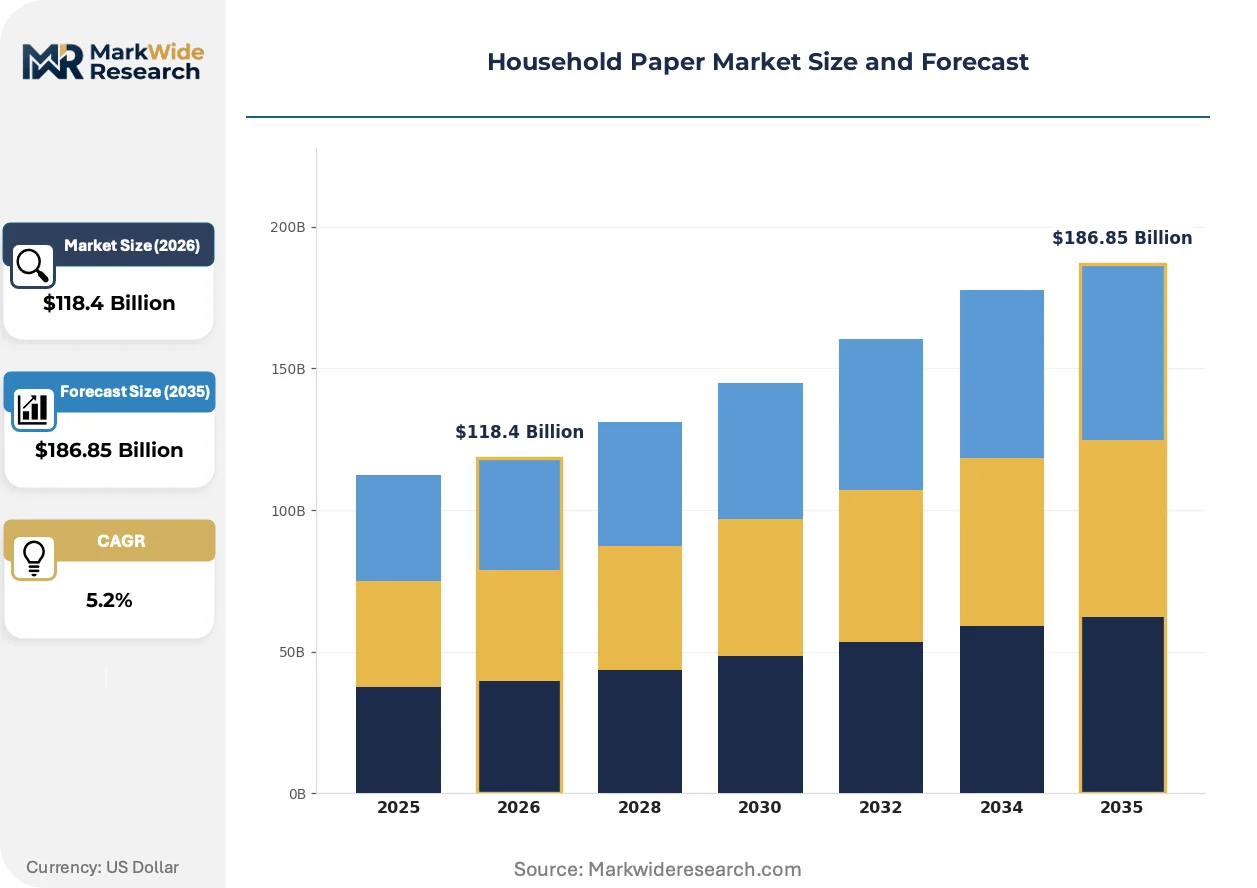
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $186.85 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Facial Tissue, Toilet Paper, Paper Towels, Napkins Material: Recycled Paper, Virgin Pulp, Bamboo, Specialty Fiber End User: Households, Restaurants, Hotels, Office Spaces Packaging Type: Bulk Pack, Retail Pack, Eco-Friendly Pack, Wrapped |
| Companies Covered | Georgia-Pacific, Empresas CMPC, Kimberly-Clark, WEPA, APP, Procter & Gamble, Sofidel, Metsa Group, Essity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Household Paper Market Strategic Shifts & Innovations
Product innovation is now defined by the need to balance ecological credentials with core functional attributes. Manufacturers are navigating the challenge of using sustainable inputs like recycled fiber without compromising the softness, strength, and absorbency that consumers expect in premium products.
Alternative fiber technology, including bamboo and unbleached pulps, provides a sustainable raw material source. These materials are being adopted by eco-conscious consumers and corporate buyers seeking to meet internal sustainability goals. This development is bifurcating the market, creating a distinct premium segment for certified green products while intensifying price competition in the conventional, virgin-pulp-based category.
Regulatory frameworks like the EU's Corporate Sustainability Reporting Directive (CSRD) are compelling manufacturers to provide greater transparency in their supply chains. This directive forces companies to disclose environmental impacts, from forestry practices to water usage, influencing procurement decisions. The professional hygiene segment is most affected, as large corporate buyers use this data to vet suppliers based on sustainability performance.
Consumer purchasing behavior is shifting towards private-label products, particularly in developed economies. This trend challenges the market share of established national brands as retailers like large supermarket chains enhance the quality and branding of their own store-brand lines. This pattern is most visible in European markets such as Germany and the UK, where discounter retail channels command significant consumer loyalty.
Household Paper Market Segmentation
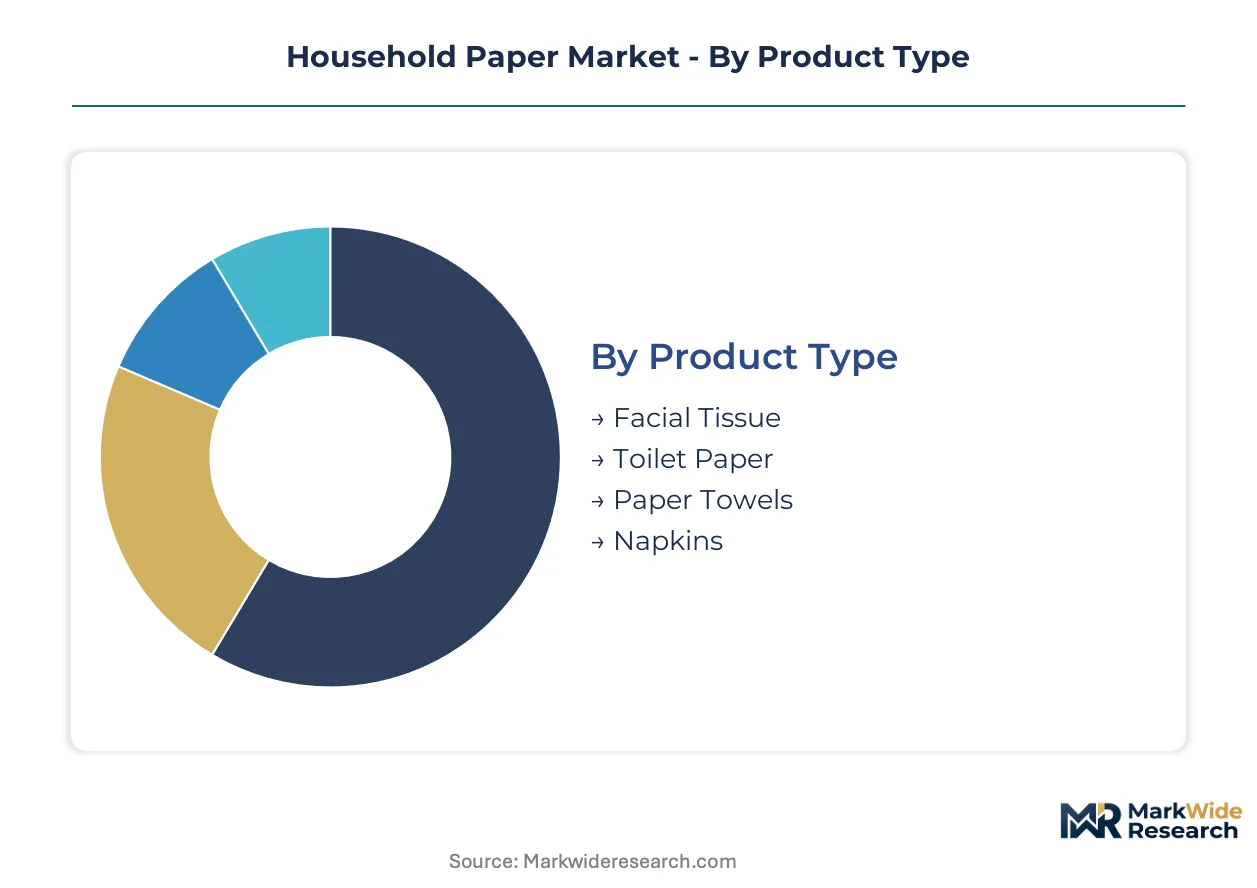
The household paper market is broadly segmented by product type, material, end user, and packaging type, reflecting diverse consumer needs and operational considerations. Understanding these segments helps manufacturers tailor product development and distribution strategies effectively. Each segment responds differently to sustainability pressures and raw material price fluctuations.
Product Type:
Product types within the household paper market exhibit varying demand patterns influenced by regional hygiene practices and economic development.
- Toilet Paper:This essential personal hygiene product is characterized by its high absorbency and softness, often measured by ply count. Demand is robust across all developed economies and rapidly expanding in emerging markets like India and China, driven by improved sanitation infrastructure.
- Paper Towels:Engineered for strength and absorbency in cleaning tasks, paper towels are crucial for both household and away-from-home applications. The hospitality sector in Europe and the United States drives significant consumption, particularly for quick spill management and surface cleaning.
- Facial Tissue:Designed for softness and gentle skin contact, facial tissues primarily serve personal care and cosmetic purposes.
- Napkins:These disposable paper products are used for dining and food service, with substantial volume consumed in restaurants and catering establishments.
Toilet Paper holds the largest share; momentum sits with Paper Towels.
Material:
Material segmentation reveals a market undergoing a significant transition, with traditional inputs facing increasing competition from sustainable alternatives.
- Virgin Pulp:Derived directly from wood fibers, virgin pulp provides superior strength, softness, and brightness, serving as the benchmark for premium products. However, its cost is highly volatile, impacted by global forestry supply and energy prices.
- Recycled Paper:Comprising post-consumer or post-industrial paper waste, recycled paper appeals to environmentally conscious consumers and meets regulatory guidelines like those from the US EPA. Quality consistency remains a challenge, requiring advanced processing technologies.
- Bamboo:Sourced from fast-growing bamboo plants, this non-wood fiber offers a sustainable and hypoallergenic alternative.
- Specialty Fiber:This category includes various non-wood fibers such as bagasse or wheat straw, used for specific performance attributes or eco-certification.
Virgin Pulp dominates material usage; Recycled Paper and Bamboo are gaining share fastest.
End User:
The end-user segmentation highlights distinct purchasing behaviors and product requirements across consumer and commercial sectors.
- Households:Individual consumers represent the largest end-user segment, purchasing household paper products for daily personal hygiene and cleaning tasks. Brand loyalty and convenience are significant purchasing drivers, with direct-to-consumer models gaining traction.
- Hotels:The hospitality sector, particularly hotels, demands high volumes of paper products for guest amenities and operational cleaning. Expansion in tourism-focused economies like Spain and Thailand directly influences this segment's growth.
- Restaurants:Food service establishments consume napkins and paper towels for hygiene and customer convenience, often prioritizing cost-effectiveness and bulk supply.
- Office Spaces:Commercial offices utilize paper products for restroom facilities and general cleaning, with procurement often managed through institutional suppliers.
Households represent the primary demand source; however, Hotels show significant expansion.
Packaging Type:
Packaging types are increasingly influenced by environmental regulations and consumer preferences for reduced plastic waste.
- Retail Pack:Designed for individual consumer purchase, retail packs emphasize branding, product information, and shelf appeal. Manufacturers are investing in plastic-free solutions to meet EU directives on packaging waste.
- Eco-Friendly Pack:This segment includes packaging made from recycled content, compostable materials, or designs that minimize environmental impact. The EU Green Deal heavily influences product development towards these sustainable formats.
- Bulk Pack:Large-format packaging caters to commercial and institutional buyers, prioritizing cost efficiency and reduced frequency of replenishment.
- Wrapped:Individual product wrapping, traditionally plastic-based, ensures hygiene and protection, though it faces pressure for more sustainable alternatives.
Retail Pack remains widespread; Eco-Friendly Pack is experiencing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing power disparities are evident between mature markets like the United States and rapidly developing economies such as India. Manufacturers navigate diverse consumer expectations and regulatory landscapes across these geographies. This dynamic influences product development and supply chain strategies for household paper products.
India
Rising disposable incomes and increasing hygiene awareness drive demand for household paper products in India. The FSSAI's public health initiatives encourage a shift from traditional cloths to disposable options. Major cities like Mumbai and Delhi are experiencing significant growth in modern retail, facilitating product distribution.
Germany
Consumer preferences for eco-friendly products and stringent environmental regulations shape the household paper market in Germany. The EU Green Deal incentivizes manufacturers to adopt sustainable materials and packaging solutions. The Rhine-Ruhr region, a major industrial hub, sees demand for certified sustainable products in both household and professional hygiene segments.
United States
The hospitality sector's expansion, particularly in tourism-heavy states, increases consumption of paper towels and napkins across the United States. US EPA guidelines for recycled content in paper products influence material sourcing decisions. Large metropolitan areas such as New York and Los Angeles drive significant demand for premium and convenient household paper solutions.
China
Improved sanitation infrastructure and growing urbanization contribute to the expanding demand for toilet paper and paper towels in China. The country's dual carbon goals push for more sustainable manufacturing practices within the paper industry. Industrial clusters in the Yangtze River Delta are seeing increased production and consumption of diverse household paper products.
Spain
Tourism-focused economies like Spain exhibit strong demand for away-from-home paper products, particularly within hotels and restaurants. EU directives on packaging waste encourage manufacturers to implement more eco-friendly packaging solutions. Coastal regions, including Andalusia and Catalonia, experience high seasonal consumption from the hospitality industry.
Household Paper Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the household paper market. The industry structure is characterized by a mix of large multinational corporations and specialized regional players. Strategic archetypes include innovation-driven premium brands, sustainability-focused specialists, and mass-market producers leveraging scale. Companies frequently engage in strategic partnerships and portfolio diversification to maintain market relevance.
Global consumer goods giants, such as Procter & Gamble, occupy a strong position in premium segments through brand recognition and continuous product innovation. Essity represents a key player focusing on sustainability and professional hygiene solutions, expanding its market share with eco-certified offerings. Kimberly-Clark, with its extensive global distribution networks, anchors significant market volume and leverages strong brand loyalty across diverse product categories.
| Leading Market Players |
|---|
| Georgia-Pacific |
| Empresas CMPC |
| Kimberly-Clark |
| WEPA |
| APP |
| Procter & Gamble |
| Sofidel |
| Metsa Group |
| Essity |
| Others |
Cost & Logistics Intelligence
Large-scale manufacturing economies in household paper production shape supply concentration, thereby influencing price floors across various product categories. This structural advantage often dictates the competitive landscape and the ability of producers to absorb raw material cost volatility.
Pricing Analysis
The customization-premium spread differentiates pricing for household paper products, with specialized eco-certified offerings commanding higher prices compared to standard virgin pulp lines. Transactional per-unit pricing dominates the retail segment, while contract-based long-term offtake agreements characterize the institutional buyer market. Brand premium and certification level serve as significant price differentiation drivers for consumers. Pricing softness stems from intense competition within the conventional, virgin-pulp-based category. Households typically exhibit higher price sensitivity for staple items, whereas professional hygiene buyers prioritize performance and sustainability certifications.
Supply Chain Analysis
Just-in-time inventory strategies, coupled with strategic stockpiles for key raw materials, characterize the household paper supply chain. Geographic supply concentration for virgin pulp centers on countries like Brazil, Canada, and the United States, while recycled paper sourcing is more localized to developed economies. The industry relies heavily on virgin wood pulp, recycled paper, and bamboo fibers as primary inputs. Commodity price volatility for wood pulp represents a significant structural risk for manufacturers. Distribution runs through established retail channels, institutional distributors, and a growing direct-to-consumer e-commerce model.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The household paper market functions as a defensive-moat industry, with strong brand loyalty and established distribution networks creating significant switching costs for consumers.
For Market Incumbents: Secure long-term supply agreements for alternative fibers like bamboo to mitigate pulp price volatility and meet sustainability mandates. Invest in advanced sorting and cleaning technologies for recycled fiber feedstock to maintain product quality against new entrants. Expand direct-to-consumer e-commerce platforms to capture higher margins and build customer relationships, countering traditional retail channel pressures. Enhance product innovation in premium segments to differentiate from private label growth.
For New Entrants and Emerging Players: Anchor in niche segments by developing products from specialty fibers such as bagasse or wheat straw, targeting eco-conscious consumers. Focus on underpenetrated emerging economies like India, leveraging rising hygiene awareness and disposable incomes. Establish partnerships with major retailers for private label opportunities, gaining volume without extensive brand-building. A direct-to-consumer subscription model offers a viable go-to-market angle for premium, sustainable offerings.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated manufacturers with strong sustainability credentials and diversified fiber sourcing. Long-term viability over the next decade hinges on companies demonstrating agility in adapting to evolving environmental regulations and consumer preferences for eco-friendly products. Acquisition targets should include specialized alternative fiber producers or companies with advanced recycling technologies. The signal to watch is the pace of regulatory adoption for circular economy models in key markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Diversify Fiber Sourcing | Reduces dependence on volatile virgin pulp markets and aligns with sustainability goals. |
| Invest in Advanced Recycling | Improves quality of recycled content, meeting regulatory standards and consumer demand. |
| Expand Direct-to-Consumer Channels | Builds customer loyalty and captures higher margins, bypassing traditional retail intermediaries. |
| Develop Eco-Certified Product Lines | Accesses premium market segments driven by consumer and corporate sustainability mandates. |
| Strategic Private Label Partnerships | Secures significant volume opportunities by collaborating with large retail chains. |
Research Approach
A standing panel of procurement managers, R&D directors, sustainability officers, and retail buyers provided ongoing calibration for primary insights and market dynamics. This primary research was rigorously combined with secondary validation from sources including Forest Stewardship Council (FSC) reports, US EPA guidelines, EU Green Deal directives, and company financial disclosures. Bottom-up and top-down triangulation ensured comprehensive data coverage and accuracy.
Consistency checks against external benchmarks validated the analytical framework across the entire analysis window. The model segmented the market by product type, material, end user, packaging type, and key functional attributes like absorbency and ply count. Compound Annual Growth Rates were derived from historical data analysis and projected market drivers. Key industry-specific forecast inputs included pulp price trends and hospitality sector expansion rates.
Material uncertainties — including unforeseen shifts in raw material costs or accelerated adoption of alternative hand-drying technologies — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory stability and consumer behavior trends. Revision becomes warranted when significant policy changes or disruptive innovations cross established thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Thin Printing Paper Market
Paper Products
Wood-Based Panel Market
Paper Products
White Top Testliner Market
Paper Products
Americas Stone Paper Market
Paper Products
Coated Wood Free Papers Market
Paper Products
Organic Tissue Paper Market
Paper Products
Billing Paper Market
Paper Products
Paper Based Laminates Market
Paper Products
Metallized Paper Market
Paper Products
Dissolving Pulp Market
Paper Products
Duplex Paper and Board Market
Paper Products
Uncoated White Top Testliner Market
Paper Products
Photographic Paper Market
Paper Products
Paper Core Market
Paper Products
Recovered Paper Market
Paper Products
Paper and Board Technologies Market