
 Benzenoid Market | 2026-2036
Benzenoid Market Size, Share, and Industry Trends Forecast 2026-2036
Benzenoid Market Analysis
Multi-source procurement for aromatic feedstocks is pivoting toward long-term contracts with integrated refiners. BASF anchors European supply through its Ludwigshafen complex, leveraging backward integration into cracker operations. Givaudan competes by sustaining captive extraction capabilities for high-purity toluene derivatives used in fine fragrances. Eternis Fine Chemicals dominates South Asian supply chains, controlling rail-tanker distribution across the Deccan industrial corridor.
Benzenoids constitute a class of aromatic hydrocarbons and their functionalized derivatives, characterized by conjugated six-carbon ring structures with alternating double bonds and substitution patterns that determine reactivity profiles. These compounds serve as foundational intermediates for synthetic fragrance molecules, polymer precursors, and pharmaceutical actives, with purity grades typically specified above 99.5% for pharmaceutical applications. Toluene and xylene product lines carry mature margin structures tied to fuel-blending economics, while aniline channels into higher-value polyurethane and dye chemistries where specification premiums widen. Pharmaceutical-grade phenol derivatives represent the fastest-expanding application segment as CDMOs expand capacity for active pharmaceutical ingredient synthesis.
EPA standards under the Toxic Substances Control Act constrain permissible benzene content in consumer-facing formulations, forcing reformulation of solvent-based coatings. REACH registration requirements in Europe mandate full substance dossiers for benzenoid imports above one-tonne thresholds, elevating compliance costs for non-EU exporters. India's BIS certification for industrial chemicals adds a third regulatory layer for cross-border suppliers. Stakeholders must monitor evolving classification of benzenoid metabolites under carcinogenicity reviews, as reclassification would trigger downstream reformulation mandates across fragrance and paint end uses.
Market Dynamics
REACH dossier requirements and EPA purity mandates are compressing supplier margins while concentrating procurement power among integrated refiners with captive cracker capacity. This regulatory-cost squeeze is rewriting competitive positioning toward backward-integrated producers.
Growth Catalysts
- Synthetic fragrance procurement:Consumer goods formulators are locking in multi-year toluene derivative contracts to secure supply continuity for fine perfume actives.
- REACH registration thresholds:The one-tonne import dossier mandate in Europe is elevating compliance barriers that favor established dossier holders over new entrants.
- India's Deccan industrial corridor:Domestic aniline and phenol derivative production is accelerating to serve textile dye and pharmaceutical intermediate demand.
Market Restraints
- Naphtha-cracker feedstock volatility:Toluene and xylene margin structures remain tethered to fuel-blending economics, compressing chemical-grade premiums during gasoline demand spikes.
- South Asian supply concentration:Rail-tanker distribution control by dominant regional producers creates bottleneck risk for inland pharmaceutical manufacturers.
- Benzene metabolite reclassification reviews:Pending carcinogenicity reassessments by European and North American health agencies threaten downstream reformulation mandates across solvent-based coatings.
Strategic Opportunities
- Pharmaceutical-grade phenol derivatives:CDMO capacity expansion for active pharmaceutical ingredient synthesis is opening specification-premium channels above 99.5% purity grades.
- India's PLI scheme for chemicals:Production-linked incentives for domestic intermediate manufacturing are attracting capital toward aniline and phenol derivative plants.
- Biocatalytic functionalization:Enzymatic routes to substituted benzenoids are converging with traditional petrochemical processes to reduce high-pressure hydrogenation costs.
Industry Challenges
- Cross-border certification timelines:India's BIS industrial chemical approval process adds 8-14 month lead times for European and North American exporters.
- Specialized process engineering talent:Cryogenic separation and catalytic hydrogenation expertise scarcity constrains capacity expansion at mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Benzenoid Market |
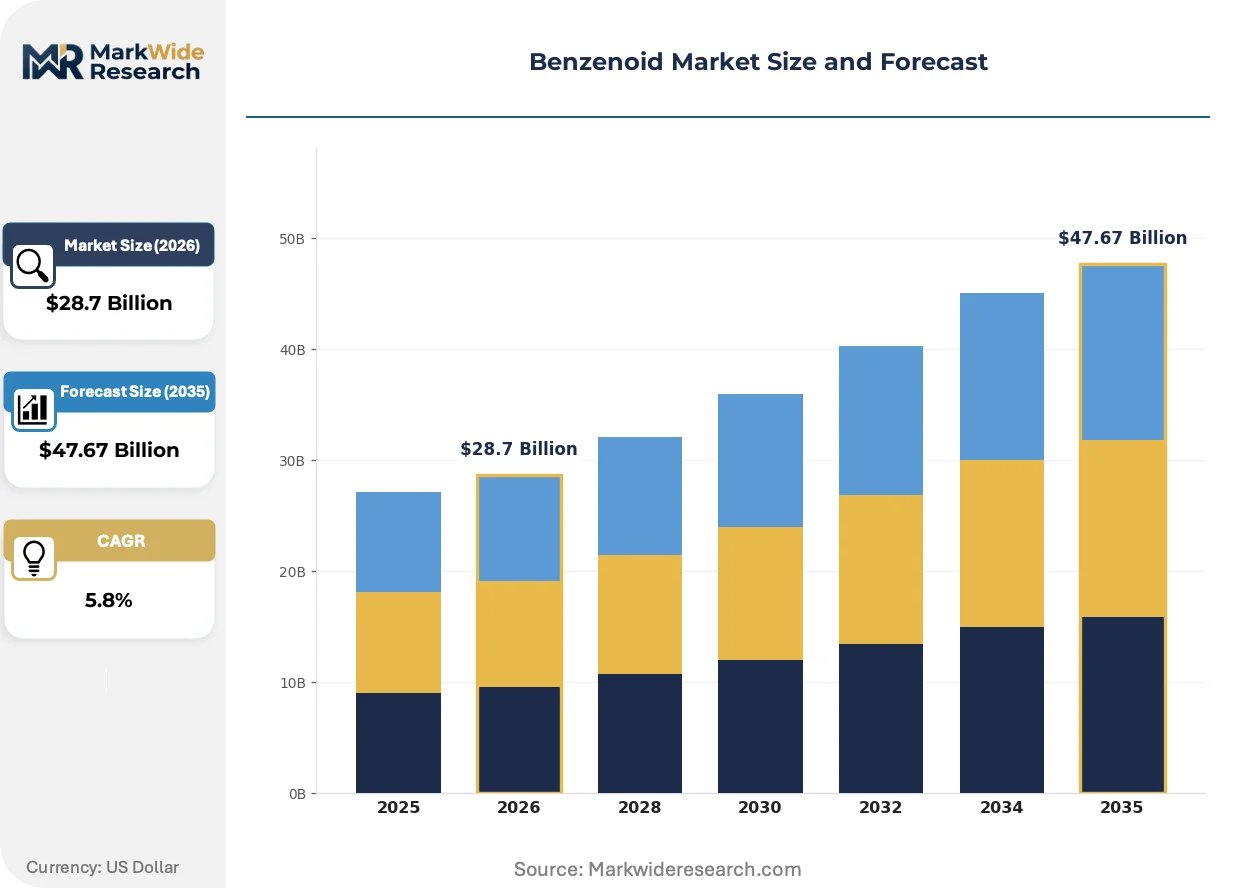
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $47.67 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toluene, Xylene, Phenol, Aniline Application: Synthetic Fragrance, Solvent, Dyes, Pharmaceuticals End User: Consumer Goods, Automotive, Textile, Paints Distribution Channel: Direct Sales, Distributors, E-commerce, Retail |
| Companies Covered | BASF, International Flavors & Fragrances, Firmenich, Givaudan, Symrise, Sensient Technologies, Sigma-Aldrich Co. LLC, Jayshree Aromatics Pvt. Ltd., Eternis Fine Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Benzenoid Market Emerging Trajectories
Continuous flow hydrogenation and membrane separation technologies are compressing batch-cycle times while regulatory metabolite tracking is forcing reformulation transparency. These forces are concentrating investment toward modular, analytics-integrated production architectures.
Membrane-based toluene fractionation is rewriting purification economics for fine fragrance intermediates. Givaudan and specialty aroma houses are retrofitting Ludwigshafen-area facilities with ceramic membrane cascades to bypass energy-intensive extractive distillation. This shift is enabling sub-ppm impurity specifications that satisfy evolving EPA solvent-content ceilings.
REACH Article 33 substance-of-very-high-concern disclosure rules are mandating full supply-chain benzene-content traceability for consumer-facing formulations. Cosmetic and coating manufacturers are responding by demanding certified sub-100-ppm aromatic certificates from intermediate suppliers. The fragrance sector faces the steepest compliance cost escalation due to complex multi-step synthesis provenance requirements.
Long-term offtake contracting is displacing spot-market purchasing for pharmaceutical-grade phenol derivatives. CDMO procurement departments in Basel and Boston are locking in five-year supply agreements with integrated refiners to secure capacity for active ingredient campaigns. This concentration of buying power is most pronounced in oncology and central nervous system therapeutic categories where purity certification carries regulatory filing weight.
Benzenoid Market Segmentation
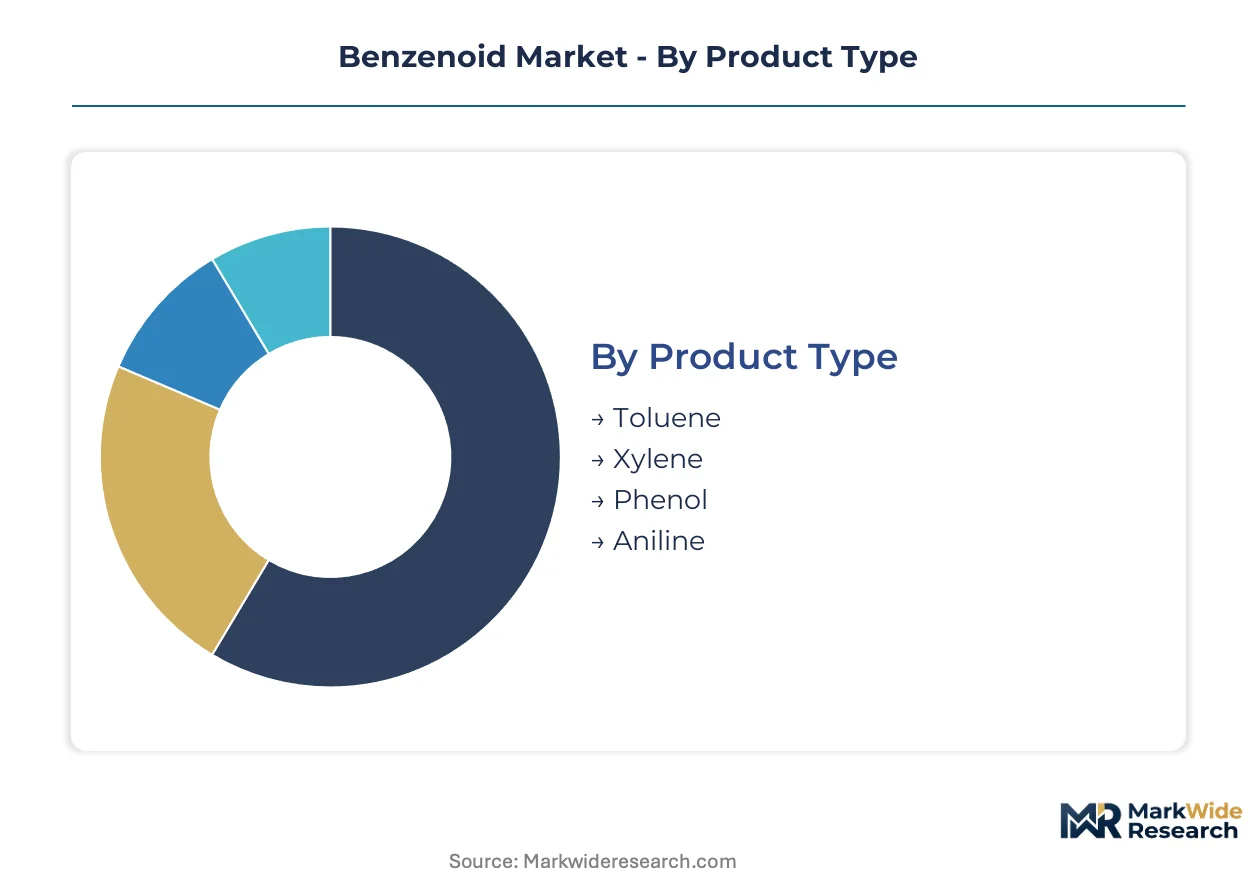
Benzenoid procurement strategies diverge sharply across purity grades and end-use specifications. Fragmentation in application requirements forces suppliers to maintain parallel production lines for fuel-blending versus pharmaceutical-grade output.
Product Type:
Customization intensity spans from commodity fuel-blending streams to pharmaceutical-grade purification protocols.
- Toluene:Aromatic hydrocarbon with methyl substitution enabling electrophilic aromatic substitution for fragrance synthesis. Fine perfume houses in Grasse and Geneva concentrate demand for nitration-grade material as EPA solvent-content ceilings tighten. Toluene margin structures remain tethered to gasoline blending economics.
- Phenol:Hydroxyl-functionalized benzene ring serving as backbone for bisphenol-A and pharmaceutical intermediates. CDMO capacity expansion in Basel and Boston locks in long-term offtake for 99.5%+ purity grades. Phenol specification premiums widen most steeply in oncology API synthesis.
- Xylene:Dimethylbenzene isomers separated via simulated moving bed adsorption for solvent and polymer applications.
- Aniline:Amino-functionalized benzene driving polyurethane and azo dye chemistries with mature margin structures.
Leading the category by volume: Toluene. Growing fastest: Phenol.
Application:
End-use concentration varies from bulk solvent consumption to trace-level fragrance formulation.
- Pharmaceuticals:Active pharmaceutical ingredient synthesis demands sub-100-ppm impurity thresholds with full provenance documentation. CDMO procurement departments enforce five-year supply agreements for oncology and central nervous system therapeutic categories. REACH Article 33 disclosure rules elevate compliance costs for multi-step synthesis tracking.
- Synthetic Fragrance:Fine perfume actives require enantiomerically pure toluene derivatives with complex multi-step provenance. Givaudan and specialty aroma houses retrofit facilities with ceramic membrane cascades to bypass energy-intensive extractive distillation. The fragrance sector faces steepest benzene metabolite reclassification risk.
- Solvent:Industrial coatings and coatings formulations with reformulation pressure from EPA Toxic Substances Control Act constraints.
- Dyes:Textile colorant intermediates concentrated in India's Deccan industrial corridor for domestic textile production.
Pharmaceuticals command the steepest specification premiums. Synthetic fragrance carries the highest regulatory compliance burden.
End User:
Procurement sophistication ranges from spot-market commodity purchasing to integrated refinery partnerships.
- Consumer Goods:Synthetic fragrance formulators lock in multi-year toluene derivative contracts to secure supply continuity for fine perfume actives. Unilever and P&G procurement teams enforce sub-100-ppm aromatic certificates from intermediate suppliers. REACH dossier requirements favor established dossier holders over new entrants.
- Textile:Azo dye manufacturers in India's Tamil Nadu and Gujarat states accelerate domestic aniline derivative production. Eternis Fine Chemicals controls rail-tanker distribution across the Deccan corridor. BIS certification adds 8-14 month lead times for European exporters.
- Automotive:Interior coating and adhesive formulations with benzene-content constraints from EPA and ECHA reviews.
- Paints:Solvent-based coating reformulation mandates pending from carcinogenicity reassessments.
Consumer goods procurement concentrates buying power through multi-year agreements. Textile demand is climbing fastest on India's PLI scheme incentives.
Distribution Channel:
Channel selection tracks shipment scale and certification complexity.
- Direct Sales:Integrated refiners with captive cracker capacity negotiate long-term offtake directly with CDMO and fragrance houses. BASF's Ludwigshafen complex anchors European supply through backward integration. Direct relationships enable real-time purity certification for regulatory filings.
- Distributors:Regional chemical distributors manage inventory for mid-scale pharmaceutical and coating manufacturers requiring smaller lot sizes.
- E-commerce:Laboratory-grade benzenoids for R&D procurement with specification documentation.
- Retail:Limited to specialty solvent formulations for professional applicators.
Direct sales capture the highest value contracts. Distributors serve the broadest geographic spread.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Deccan industrial corridor concentrates accelerating demand for aniline and phenol derivatives, while regulatory tightening across multiple jurisdictions fragments supplier access. Procurement patterns favor integrated refiners with captive cracker capacity in established chemical clusters.
United States
CDMO procurement departments in Boston and the New Jersey corridor lock in five-year supply agreements for pharmaceutical-grade phenol derivatives. EPA standards under the Toxic Substances Control Act constrain permissible benzene content in solvent-based coatings, forcing reformulation across interior automotive applications. The Gulf Coast petrochemical complex anchors domestic toluene and xylene production tied to fuel-blending economics.
Germany
BASF's Ludwigshafen complex anchors European benzenoid supply through backward integration into cracker operations. REACH registration requirements mandate full substance dossiers for imports above one-tonne thresholds, elevating compliance costs for non-EU exporters. Specialty aroma houses in the Rhine-Neckar metropolitan region retrofit facilities with ceramic membrane cascades for fine fragrance intermediates.
India
Domestic production of aniline and phenol derivatives accelerates to serve textile dye and pharmaceutical intermediate demand from Tamil Nadu and Gujarat states. The BIS certification process adds 8-14 month lead times for European and North American exporters seeking industrial chemical approval. Eternis Fine Chemicals controls rail-tanker distribution across the Deccan corridor, creating bottleneck risk for inland pharmaceutical manufacturers.
Switzerland
Fine fragrance formulators in Geneva concentrate demand for enantiomerically pure toluene derivatives with complex multi-step provenance documentation. Swissmedic pharmaceutical regulations enforce sub-100-ppm impurity thresholds with full supply-chain traceability requirements. The Basel pharmaceutical cluster drives specification-premium contracting for oncology and central nervous system therapeutic categories.
China
Dual carbon goals and MEE environmental standards compress high-pressure hydrogenation capacity expansion for substituted benzenoid production. The Yangtze River Delta chemical corridor concentrates domestic aniline derivative manufacturing for azo dye export markets. NMPA pharmaceutical regulations align with international purity benchmarks above 99.5% for active pharmaceutical ingredient synthesis inputs.
Benzenoid Market Vendor Landscape
Long-term offtake contracting dominates the current landscape as procurement departments displace spot-market purchasing for specification-critical grades. The vendor base organizes around three strategic archetypes: integrated refiners with captive cracker capacity, specialty aroma houses with membrane purification capabilities, and regional distributors controlling rail-tanker logistics. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with biocatalytic functionalization emerging as a technology licensing vector.
Within the integrated refiner archetype, BASF anchors European supply through its Ludwigshafen complex, while Givaudan occupies a position exemplifying specialty aroma house capabilities for fine fragrance intermediates. Among South Asian chemical specialists, Eternis Fine Chemicals represents regional distribution control across the Deccan industrial corridor. These three companies illustrate the competitive segmentation between backward-integrated production, purification technology differentiation, and logistics-dominated regional supply.
| Leading Market Players |
|---|
| BASF |
| International Flavors & Fragrances |
| Firmenich |
| Givaudan |
| Symrise |
| Sensient Technologies |
| Sigma-Aldrich Co. LLC |
| Jayshree Aromatics Pvt. Ltd. |
| Eternis Fine Chemicals |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap refiners in South Asia anchor supply discipline through rail-tanker distribution control across the Deccan corridor, translating logistics dominance into pricing power over inland pharmaceutical manufacturers. This ownership pattern compresses margin leakage while concentrating procurement leverage among integrated producers with captive cracker capacity.
Pricing Analysis
Volume-mass toluene and xylene streams trade on fuel-blending economics, while specification-premium phenol derivatives for oncology API synthesis command contract-based long-term offtake structures. Price differentiation hinges on purity certification above 99.5% and REACH dossier completeness, with fragrance-grade toluene derivatives carrying the steepest compliance cost escalation. Pricing pressure stems from naphtha-cracker feedstock volatility tethering chemical-grade premiums to gasoline demand spikes. Spot-market commodity buyers in solvent applications exhibit highest price sensitivity, whereas CDMO procurement departments in Basel and Boston absorb specification premiums for regulatory filing weight.
Supply Chain Analysis
Rail-tanker freight costs from Eternis Fine Chemicals' Deccan distribution network create bottleneck exposure for inland pharmaceutical manufacturers dependent on just-in-time phenol derivative delivery. Supply concentrates in Germany through BASF's Ludwigshafen complex, India via domestic aniline acceleration, and the US Gulf Coast petrochemical corridor. Raw material dependencies rest on naphtha feedstock from integrated refiners, hydrogen for catalytic functionalization, and ceramic membrane components for sub-ppm purification. Single-source vulnerability runs through South Asian rail logistics control. Distribution runs through direct long-term offtake contracts for pharmaceutical-grade material, with regional distributors managing smaller lot solvent and dye applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
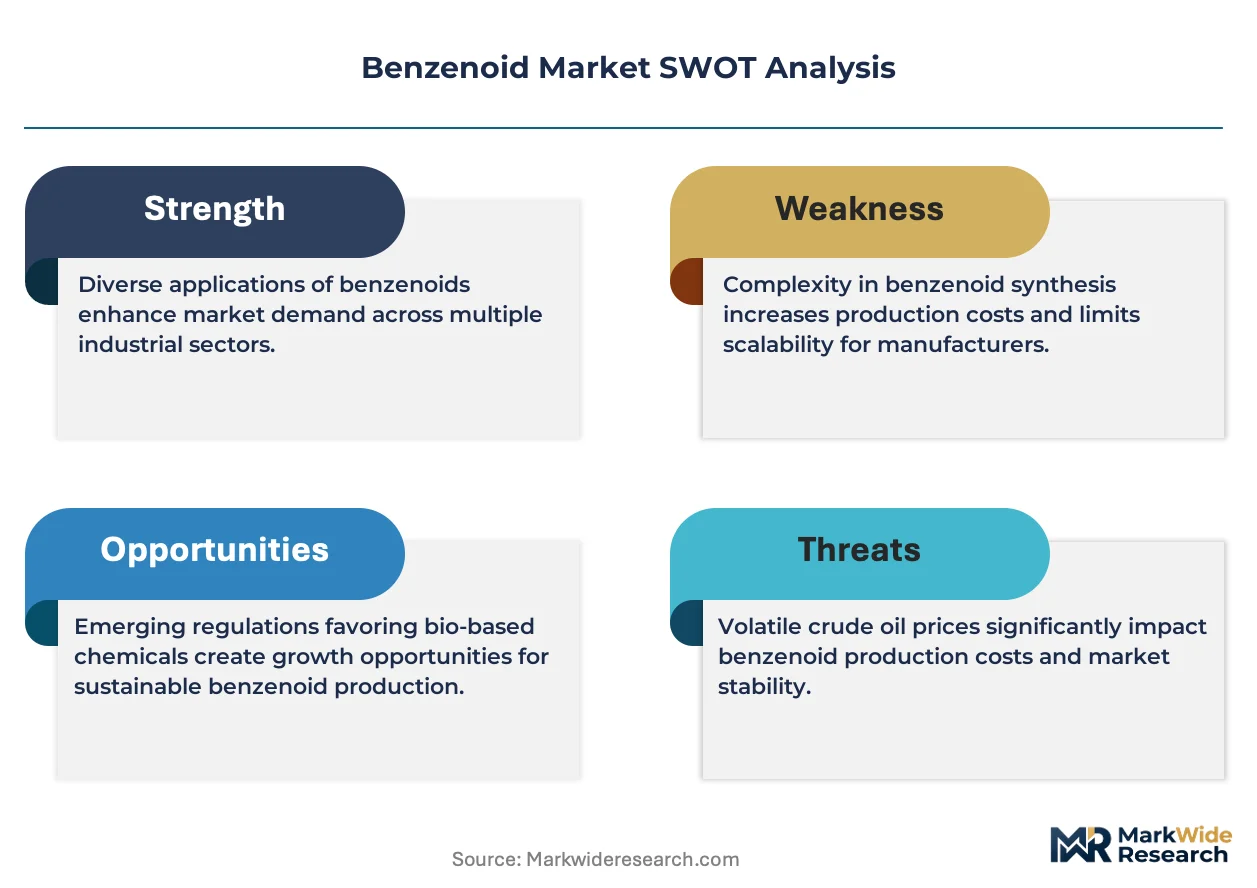
The benzenoid sector sits in a technology-transition phase as biocatalytic functionalization converges with traditional petrochemical hydrogenation routes, displacing high-pressure capital intensity with enzymatic cost structures.
For Market Incumbents: Cement backward integration into cracker operations to defend margin position against naphtha feedstock volatility and regulatory-cost compression from REACH dossier requirements. Prioritize ceramic membrane cascade retrofitting for sub-ppm impurity capture in fine fragrance intermediates, locking in Givaudan-grade specification premiums that new entrants cannot replicate without cryogenic separation expertise. For New Entrants and Emerging Players: The premium-to-economy pricing gap in pharmaceutical-grade phenol derivatives offers white-space entry below CDMO contract thresholds. Target India's PLI scheme for chemicals to capture production-linked incentives for domestic aniline and phenol derivative plants. Lead with BIS certification navigation services to compress 8-14 month approval timelines for European exporters seeking textile dye market access. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale South Asian distributors with rail-tanker logistics control in the Deccan corridor, where supply concentration creates defensive moats. Long-term viability over a multi-year window hinges on regulatory metabolite reclassification outcomes across European and North American health agencies. Monitor benzene-content traceability mandates under REACH Article 33 as the inflection signal for downstream reformulation spend acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cracker Operations | BASF's Ludwigshafen complex demonstrates margin defense against naphtha volatility through captive feedstock supply. |
| Ceramic Membrane Cascade Retrofitting | Givaudan-area facilities bypass extractive distillation energy costs while hitting EPA sub-ppm solvent ceilings. |
| Long-term Supply Agreement Structuring | CDMO procurement in Basel and Boston locks five-year offtake for oncology API purity certification requirements. |
| PLI Scheme Capacity Expansion | India's production-linked incentives attract capital toward domestic aniline and phenol derivative manufacturing clusters. |
| Biocatalytic Functionalization Licensing | Enzymatic routes reduce high-pressure hydrogenation capital intensity for substituted benzenoid production. |
Methodological Framework
Trade databases, SEC 10-K filings from listed chemical producers, and European customs records formed the secondary backbone, cross-referenced with primary interviews involving plant managers at integrated refiners, procurement leads at CDMOs, distribution channel partners across South Asia, and technical R&D directors in fragrance houses. Bottom-up volume aggregation across purity grades and end-use segments was reconciled with top-down market sizing from trade flow analysis.
Historical trendline analysis of toluene and xylene margin structures against gasoline blending economics informed the projection framework across the analysis window. Segmentation dimensions modeled include purity grade tier, end-use industry concentration, regional production hub clustering, and regulatory compliance burden. CAGRs were derived from elasticity-adjusted demand curves incorporating REACH dossier cost escalation and India's PLI incentive absorption rates.
Inputs from ECHA registration databases and US EPA enforcement disclosures were available through the study window; gaps in real-time benzene metabolite reclassification timelines introduce uncertainty bands around downstream reformulation assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Barbituric Acid Market
Chemicals
Middle East and Africa Methyl Acrylate Market
Chemicals
Precious Metal Plating Chemicals Market
Chemicals
Phosgene Market
Chemicals
Cold Phosphating Chemicals Market
Chemicals
Piroctone Olamine Market
Chemicals
Lanthanum Nitrate Market
Chemicals
Iscotrizinol Market
Chemicals
2-(4-(Bromomethyl)phenyl)propionic Acid (BMPPA) Market
Chemicals
Latin America Construction Chemicals Market
Chemicals
Acetophenone Market
Chemicals
Middle East Construction Chemicals Market
Chemicals
Paint Remover Market
Chemicals
Electronic Grade Choline Hydroxide Market
Chemicals
Sodium Ethyl P-Hydroxybenzoate Market
Chemicals
Germany Methanol Market