
 Catechol Market | 2026-2036
Catechol Market Size, Share, and Industry Trends Forecast 2026-2036
Catechol Market Analysis
Direct procurement channels between catechol producers and specialty chemical buyers is tilting toward long-term supply contracts with embedded technical service clauses. BASF SE leverages its integrated phenol derivative network to sustain captive feedstock security across European and Asian manufacturing sites. Camlin Fine Sciences anchors its position through backward integration into key aromatic precursors, while Sumitomo Chemical differentiates via precision-controlled oxidation technology that yields pharmaceutical-grade material.
Catechol is a dihydroxybenzene compound with hydroxyl groups at ortho positions, typically manufactured through phenol hydroxylation or coal tar distillation, and serves primarily as a reactive intermediate for agrochemicals, pharmaceuticals, and polymer stabilizers. The Pharmaceuticals application segment leads value capture due to stringent purity grades required for synthetic drug pathways, while the Agrochemicals product type occupies substantial volume throughput driven by herbicide and pesticide intermediate demand. The Intermediates application category records the fastest trajectory as downstream manufacturers seek dedicated precursor molecules with documented chain-of-custody compliance.
EPA regulations in the United States and REACH frameworks in Europe constrain permissible impurity profiles for catechol entering consumer-facing supply chains, compelling producers to invest in analytical certification infrastructure. China's MEE enforces wastewater discharge standards that elevate capital requirements for phenol derivative facilities in Jiangsu and Shandong provinces. Stakeholders must monitor how divergent purity standards across regulatory jurisdictions reshape qualification costs and determine which production assets can serve multiple end markets without redundant recertification cycles.
Market Dynamics
Specialty chemical buyers are consolidating purchase volumes through multi-year supply agreements that embed technical service and chain-of-custody documentation requirements.
Growth Catalysts
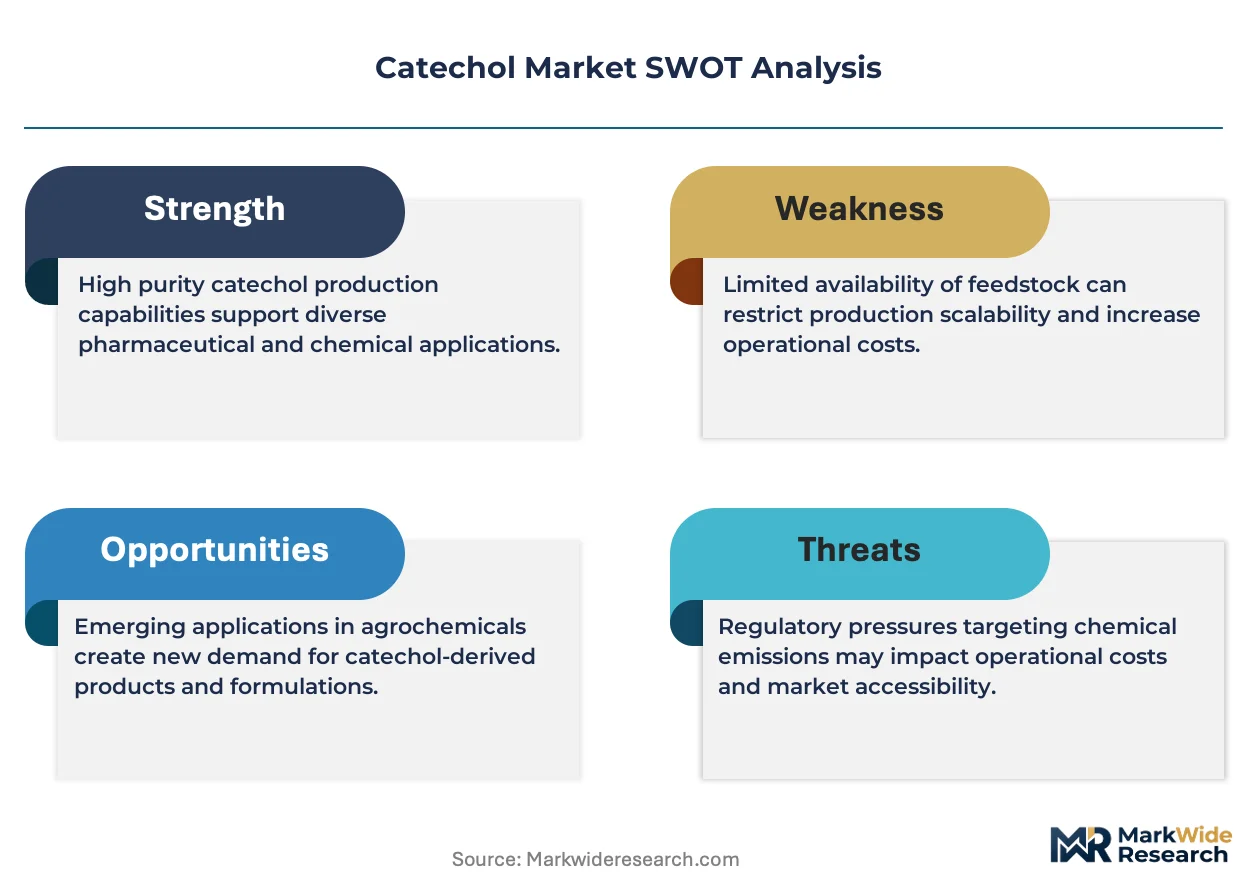
- REACH purity mandates:European ECHA frameworks for chemical intermediates are compelling pharmaceutical manufacturers to source documented pharmaceutical-grade catechol, tightening supplier qualification standards and locking in qualified producers.
- Agrochemical intermediate demand:Herbicide and pesticide synthesis pathways in China's Jiangsu and Shandong provinces are absorbing expanding catechol volumes as domestic crop protection manufacturing scales.
- Dual hydroxylation technology:Precision-controlled oxidation processes are yielding higher-purity ortho-dihydroxybenzene output with reduced phenol feedstock waste, improving process economics for dedicated producers.
Market Restraints
- Phenol feedstock volatility:Benzene-to-phenol cost spreads fluctuate with crude oil benchmarks, compressing margin predictability for hydroxylation-based catechol manufacturers without captive aromatics supply.
- Coal tar distillation concentration:Alternative production via coal tar refining clusters in select Chinese and Indian industrial zones, creating geographic supply vulnerability and logistics cost asymmetry.
- Substitute aromatic diols:Resorcinol and hydroquinone compete in specific polymer stabilizer and dye intermediate applications, capping catechol pricing power in non-pharmaceutical grades.
Strategic Opportunities
- India specialty chemical expansion:CDSCO-aligned pharmaceutical manufacturing under India's PLI scheme is creating demand for import-substituted catechol with documented regulatory compliance.
- Biocatalytic synthesis convergence:Enzymatic hydroxylation paired with continuous flow reactor design promises reduced energy intensity and wastewater generation for European producers facing EU Green Deal carbon targets.
- Direct-to-formulator channels:Agrochemical compounders in Brazil and Southeast Asia are bypassing traditional distributor tiers, opening margin capture for producers with regional technical service capabilities.
Industry Challenges
- Analytical certification capacity:Multi-jurisdictional impurity profiling for EPA, REACH, and NMPA submissions requires specialized chromatography infrastructure and trained analytical chemists in short supply.
- Legacy batch reactor retrofit:Converting phenol hydroxylation assets from batch to continuous processing demands capital deployment and extended validation timelines without interrupting qualified supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Catechol Market |
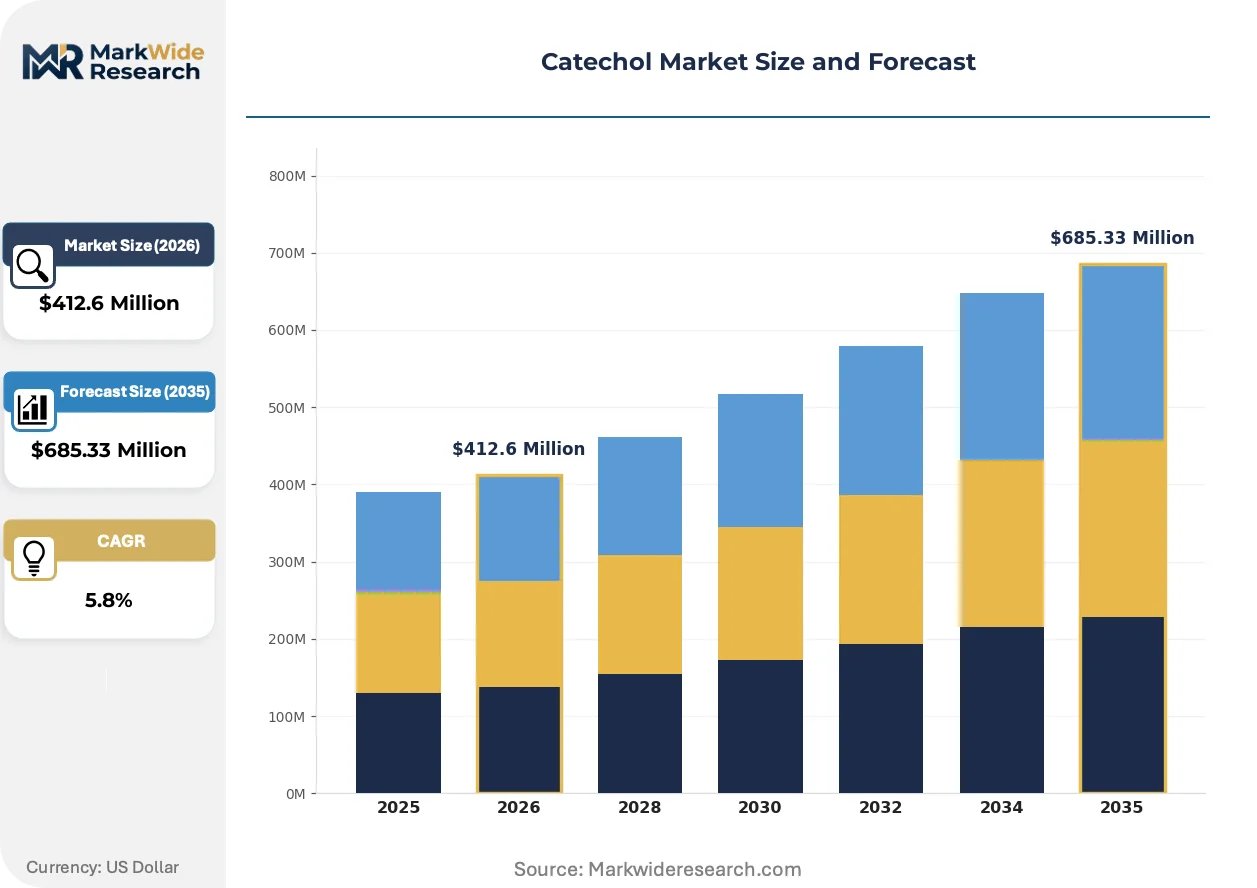
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Agrochemicals, Plastics, Dyes End User: Chemical Manufacturers, Healthcare Providers, Research Institutions, Agricultural Companies Application: Solvents, Intermediates, Antioxidants, Flavors Distribution Channel: Online Sales, Direct Sales, Distributors, Retailers |
| Companies Covered | BASF SE, Camlin Fine Sciences, Ineos Phenol, Sumitomo Chemical, Lianyungang Sanjili Chemical, Mitsui Chemicals, Solvay, Eastman, UBE Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Catechol Market Emerging Trajectories
Process intensification and digital traceability systems are compressing production cycles while hardening supply chain documentation against regulatory audit scrutiny.
Continuous flow microreactor technology for phenol hydroxylation is virtualizing traditional batch manufacturing economics. Pharmaceutical-grade catechol producers in Germany and Switzerland are adopting these systems to shrink reactor footprints and accelerate heat transfer control. This virtualization is enabling on-site modular production near downstream formulation facilities, reducing cross-border logistics exposure.
EPA's evolving standards for chemical intermediate impurity profiles are forcing US-based agrochemical formulators to requalify Asian suppliers against documented contaminant thresholds. The industrial consequence is a bifurcation between qualified and non-qualified supply tiers. Specialty chemical distributors serving US crop protection manufacturers are absorbing compliance verification costs and passing them through as service premiums.
Buyers are consolidating annual catechol volumes into framework agreements with embedded technical audit rights and quarterly purity certification. Long-term contracting is displacing spot purchasing in European pharmaceutical and polymer stabilizer segments. This pattern is most visible in German and Swiss chemical manufacturing clusters where REACH documentation continuity carries premium value.
Catechol Market Segmentation
Catechol's value chain fragments across purity grades, regulatory jurisdictions, and technical service requirements. Buyers segment procurement by documented compliance tiers rather than commodity specifications alone. Each dimension carries distinct margin structures and qualification barriers.
Product Type:
After-sales service intensity varies sharply across product grades, with pharmaceutical manufacturers demanding analytical certification continuity and technical audit access that agrochemical buyers rarely require.
- Pharmaceuticals:Ultra-high purity grades with documented impurity profiles below 50 ppm meet synthetic drug pathway requirements. Demand concentrates in German and Swiss manufacturing clusters where REACH documentation continuity commands premium pricing. ECHA-mandated chain-of-custody records lock qualified producers into multi-year framework agreements.
- Agrochemicals:Technical-grade material serves herbicide and pesticide intermediate synthesis. Volume throughput centers on Jiangsu and Shandong provinces as domestic Chinese crop protection manufacturing scales. MEE wastewater discharge standards elevate capital requirements for phenol derivative facilities serving this segment.
- Plastics:Polymer stabilizer applications absorb mid-tier purity grades with antioxidant functionality.
- Dyes:Colorant intermediate demand competes with resorcinol and hydroquinone in specific chromophore synthesis pathways.
Pharmaceuticals holds the largest share; momentum sits with Agrochemicals as China's crop protection sector expands.
End User:
Cost tier differentiation separates integrated chemical manufacturers from outsourced formulators with divergent technical capabilities and compliance infrastructure.
- Chemical Manufacturers:Integrated producers with captive aromatics supply and in-house analytical certification capacity source catechol for downstream derivative production. These buyers qualify suppliers against multi-jurisdictional impurity standards spanning EPA, REACH, and NMPA frameworks.
- Healthcare Providers:Pharmaceutical compounders and CMOs purchase documented pharmaceutical-grade material for active ingredient synthesis. CDSCO-aligned manufacturing under India's PLI scheme is expanding this buyer category's geographic footprint.
- Research Institutions:Academic and government laboratories procure small-batch high-purity material for method development and reference standard preparation.
- Agricultural Companies:Crop protection formulators in Brazil and Southeast Asia are consolidating volumes through direct-to-producer channels, bypassing traditional distributor markups.
Chemical Manufacturers dominates procurement volumes; Healthcare Providers are expanding most quickly as pharmaceutical outsourcing accelerates.
Application:
Application maturity determines whether buyers prioritize price stability or supply security in contracting structures.
- Intermediates:Reactive precursor demand for downstream synthetic pathways commands the steepest expansion trajectory. Manufacturers seek dedicated molecules with batch-specific documentation for regulatory submission packages. Precision-controlled oxidation technology yields higher-purity output with reduced phenol feedstock waste.
- Solvents:Dissolution applications in extraction and purification processes absorb technical-grade volumes with less stringent purity requirements.
- Antioxidants:Polymer stabilization and food preservation applications compete with substitute aromatic diols in specific end uses.
- Flavors:Fragrance and taste compound synthesis utilizes food-grade catechol with documented contaminant thresholds.
Intermediates captures the fastest value growth; Solvents retains the broadest volume base across industrial applications.
Distribution Channel:
Supply concentration shapes channel selection, with qualified producers in Germany and Switzerland favoring direct relationships over intermediary tiers.
- Direct Sales:Long-term supply agreements with embedded technical service clauses and quarterly purity certification dominate European pharmaceutical and polymer stabilizer procurement. These contracts displace spot purchasing as REACH documentation continuity carries premium value.
- Distributors:Specialty chemical distributors serving US crop protection manufacturers absorb compliance verification costs and pass them through as service premiums. EPA's evolving impurity standards force requalification of Asian suppliers against documented thresholds.
- Online Sales:Digital platforms facilitate small-batch procurement for research institutions and emerging market buyers with limited supplier relationships.
- Retailers:Limited presence confined to laboratory supply houses serving academic and analytical chemistry markets.
Direct Sales commands the highest value capture; Distributors maintain the widest geographic reach for mid-tier grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underwrites Germany's dominance in European phenol derivative distribution, while the Yangtze River Delta's port cluster enables China's catechol export volumes to reach pharmaceutical and agrochemical buyers across three continents.
Germany
Ludwigshafen's integrated aromatics complex feeds pharmaceutical-grade catechol output for synthetic drug pathways. ECHA REACH frameworks mandate documented impurity profiles below 50 ppm, locking qualified producers into multi-year supply contracts. The Rhine-Neckar chemical manufacturing cluster concentrates precision-controlled oxidation capacity serving Swiss and German pharmaceutical formulators.
China
Jiangsu and Shandong provinces absorb expanding volumes for herbicide and pesticide intermediate synthesis as domestic crop protection manufacturing scales. MEE wastewater discharge standards elevate capital requirements for phenol derivative facilities in these industrial zones. The Yangtze River Delta's port infrastructure enables export shipments to Brazilian and Southeast Asian agrochemical compounders.
United States
EPA evolving standards for chemical intermediate impurity profiles force agrochemical formulators to requalify Asian suppliers against documented contaminant thresholds. The Gulf Coast petrochemical corridor provides phenol feedstock access for hydroxylation-based production. Specialty chemical distributors serving crop protection manufacturers absorb compliance verification costs and pass them through as service premiums.
India
CDSCO-aligned pharmaceutical manufacturing under the PLI scheme creates demand for import-substituted catechol with documented regulatory compliance. Maharashtra and Gujarat host expanding active pharmaceutical ingredient synthesis capacity requiring ultra-high purity grades. Domestic producers are investing in analytical certification infrastructure to serve contract manufacturing organizations.
Switzerland
Swissmedic pharmaceutical-grade requirements command premium pricing for documented chain-of-custody continuity. Basel's pharmaceutical manufacturing cluster sources catechol for synthetic drug pathways with batch-specific documentation. Continuous flow microreactor adoption is shrinking reactor footprints and accelerating heat transfer control for dedicated producers.
Catechol Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in the value chain. The catechol supplier base concentrates around integrated phenol derivative networks and dedicated oxidation technology operators. Three archetypes dominate: captive aromatics producers with backward integration into feedstock security, precision oxidation specialists yielding pharmaceutical-grade material, and regional chemical manufacturers serving technical-grade agrochemical demand. Competitive moves center on multi-year supply contract capture with embedded technical service clauses, and analytical certification infrastructure deployment to satisfy divergent purity standards across regulatory jurisdictions.
Among Germany-based integrated chemical producers, BASF SE exemplifies the captive feedstock archetype through its phenol derivative network spanning European and Asian manufacturing sites. Camlin Fine Sciences anchors the backward integration specialist tier, while Sumitomo Chemical occupies a position representing precision-controlled oxidation technology for pharmaceutical-grade output. These three entities illustrate how geographic feedstock access and process technology differentiation stratify competitive positioning in qualified supply tiers.
| Leading Market Players |
|---|
| BASF SE |
| Camlin Fine Sciences |
| Ineos Phenol |
| Sumitomo Chemical |
| Lianyungang Sanjili Chemical |
| Mitsui Chemicals |
| Solvay |
| Eastman |
| UBE Industries |
| Others |
Supply Flow & Price Mechanics
Jiangsu and Shandong province phenol derivative concentration anchors margin capture for qualified European pharmaceutical buyers, while technical-grade agrochemical purchasers absorb logistics premiums from coal tar distillation clustering in select Indian industrial zones.
Pricing Analysis
Volume-discount tiering separates pharmaceutical-grade material with REACH documentation from technical-grade agrochemical volumes. Price differentiation hinges on certification grade and embedded analytical service intensity, with Swissmedic-aligned buyers showing minimal sensitivity. Cost compression in mid-tier polymer stabilizer grades reflects resorcinol substitution elasticity. Agrochemical compounders in Brazil demonstrate highest price sensitivity due to distributor markup absorption.
Supply Chain Analysis
Extended payment terms from German and Swiss pharmaceutical buyers now reach 90-120 days, pressuring working capital for phenol hydroxylation operators. Supply concentrates in China, Germany, and India, with feedstock dependency on benzene-to-phenol spreads and coal tar refining yields. Single-source vulnerability clusters around Ludwigshafen aromatics integration. Distribution runs through direct long-term contracts for qualified grades and specialty chemical distributors for technical volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around REACH and EPA impurity documentation creates formidable switching costs, locking qualified producers into multi-year framework agreements that new entrants cannot readily replicate.
For Market Incumbents: Insulate qualified supply positions through captive aromatics security and continuous flow microreactor retrofit at German and Swiss sites. Substitute aromatic diols threaten polymer stabilizer pricing power; counter via pharmaceutical-grade certification depth. Backward integration into phenol feedstock anchors margin predictability against benzene volatility. For New Entrants and Emerging Players: India's CDSCO-aligned contract manufacturing expansion offers the most penetrable geographic entry point. Target Maharashtra and Gujarat API synthesis clusters with documented regulatory compliance infrastructure. Bypass established distributor tiers through direct technical service deployment for agrochemical compounders in Southeast Asia. For Investors and Strategic Acquirers: Capital is best deployed toward precision oxidation specialists with pharmaceutical-grade output capability and existing multi-jurisdictional certification infrastructure. Long-term viability favors assets with demonstrated REACH, EPA, and NMPA submission continuity. Watch for MEE wastewater discharge enforcement intensity in Jiangsu as inflection signal for Chinese supply rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive phenol feedstock security insulates BASF and Camlin from benzene spread volatility. |
| Continuous Flow Reactor Adoption | German and Swiss producers shrink footprints while accelerating heat transfer for pharmaceutical-grade yields. |
| Long-term Supply Agreement | REACH documentation continuity locks qualified producers into multi-year European pharmaceutical contracts. |
| Green Manufacturing Transition | Enzymatic hydroxylation paired with flow reactor design addresses EU Green Deal carbon targets. |
| Joint Venture | Indian PLI scheme partnerships enable CDSCO-aligned capacity for import-substituted pharmaceutical grades. |
Methodological Framework
The analysis maps pharmaceutical-grade, agrochemical-grade, and polymer stabilizer segments, each validated through procurement leads at downstream formulators, plant managers at phenol derivative facilities, and distribution channel partners. Primary interviews with ECHA regulatory consultants and EPA compliance officers combined with customs trade data, Cefic chemical industry reports, and SEC 10-K filings from integrated aromatics producers. Bottom-up volume triangulation against top-down value estimates anchored forecast reliability.
Assumptions held fixed include REACH and EPA regulatory continuity, phenol hydroxylation technology dominance, and existing geographic production clustering. The projection horizon spans grade tier, end-use industry, and regional production hub dimensions. CAGRs derived from segment-level demand elasticity modeling against feedstock cost trajectory inputs, with precision-controlled oxidation yield improvements and MEE enforcement intensity as scenario variables.
Macroeconomic conditions sit as an overlay; deviation in crude oil benchmarks, benzene spreads, or carbon pricing implementation would shift the trajectory. Forecasts reflect these documented assumptions; regulatory acceleration, biocatalytic synthesis breakthrough, or Chinese environmental enforcement deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Methylamines Market
Chemicals
Dimethyl Phosphate Market
Chemicals
Superplasticizer Market
Chemicals
Peracetic Acid Market
Chemicals
Europe Flame Retardant Chemicals Market
Chemicals
Sodium Aluminum Hydride Market
Chemicals
Chemical As a Service Market
Chemicals
Formalin Market
Chemicals
Barbituric Acid Market
Chemicals
Neopentyl Polyhydric Alcohol Market
Chemicals
Global Pine Chemicals Market
Chemicals
Hexamine Market
Chemicals
Coal Tar Market
Chemicals
Household Insecticides Market
Chemicals
Global Commodity Chemicals Market
Chemicals
Benzhydrol Market