
 Global Engineering Adhesives Market | 2026-2036
Global Engineering Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Engineering Adhesives Market Intelligence
A transition from single-source contracts to multi-vendor qualification is realigning supply chain resilience for original equipment manufacturers. Henkel AG & Co. KGaA leverages its extensive product portfolio and global distribution network to serve diverse end-user industries. H.B. Fuller Company competes through its focus on specific application niches and dedicated customer technical support. Arkema differentiates with its specialization in high-performance polymers that serve as precursors for advanced adhesive systems, controlling a key part of the value chain.
Engineering adhesives are advanced chemical formulations designed to create high-strength structural bonds, often replacing mechanical fasteners like rivets and welds. These materials are characterized by specific performance metrics such as high shear strength, peel resistance, and thermal stability under operational stress. Epoxy and polyurethane adhesive types dominate structural bonding applications in construction fixing and aerospace. Within end-user industries, demand from consumer electronics manufacturers is accelerating due to the need for bonding dissimilar materials in compact, water-resistant devices.
Product formulation and market access are shaped by chemical safety regulations, including Europe's REACH framework managed by ECHA and the US EPA's rules on volatile organic compounds (VOCs). In Asia, compliance with national standards like China's GB standards is mandatory for market entry and influences material selection. Formulators must navigate these evolving rules while developing next-generation adhesives compatible with automated robotic dispensing and advanced composite substrates.
Market Dynamics
The central structural force in the engineering adhesives market is the dual requirement for material lightweighting and enhanced chemical safety. This pressure, originating from fuel efficiency goals in aerospace and automotive sectors, is amplified by stringent regulatory frameworks like REACH.
Growth Catalysts
- Lightweighting Mandates:The aerospace and automotive industries require advanced bonding solutions for composite materials and dissimilar substrates to reduce vehicle weight and improve fuel economy, directly driving adoption of structural adhesives over mechanical fasteners.
- Consumer Electronics Miniaturization:Demand from electronics manufacturers, particularly in Asian production hubs, for adhesives that enable compact, water-resistant designs with reliable bonding of glass, metal, and polymer components is accelerating.
- Regulatory Compliance Premiums:Stricter rules on volatile organic compounds (VOCs) from the US EPA and Europe's ECHA create market opportunities for manufacturers of compliant, low-VOC, and solvent-free adhesive formulations.
Market Restraints
- Raw Material Price Volatility:The market is sensitive to price fluctuations in petrochemical-derived feedstocks, such as epoxy resins and isocyanates, which are core components for high-performance polyurethane and epoxy adhesives, impacting formulation costs.
- Technical Application Hurdles:Stringent surface preparation requirements and extended cure times for some high-strength structural adhesives can create bottlenecks in high-volume, automated manufacturing lines, limiting their use in certain rapid-assembly processes.
- Threat from Alternative Joining Technologies:Advances in friction stir welding and specialized mechanical micro-fasteners present viable alternatives for specific structural joining applications, particularly in the automotive body-in-white segment.
Strategic Opportunities
- Bio-Based Formulations:Developing adhesives from renewable feedstocks and bio-based polymers presents a significant opportunity to meet corporate sustainability mandates and appeal to environmentally conscious end-user industries.
- Adhesives for Flexible Devices:The emergence of flexible electronics, wearables, and medical sensors creates a new frontier for specialized adhesives that offer durability, flexibility, and biocompatibility for bonding on non-rigid substrates.
- Construction Sector Penetration:There is a substantial opportunity to replace traditional cementitious mortars and mechanical fixings with high-performance construction adhesives in infrastructure projects across Southeast Asian economies.
Industry Challenges
- Fragmented Regulatory Navigation:Manufacturers face complexity in ensuring product compliance across multiple jurisdictions, each with unique chemical inventory lists and standards, such as China's GB standards and South Korea's K-REACH.
- Specialized Talent Scarcity:A shortage of formulation chemists and application engineers with dual expertise in advanced polymer science and the programming of automated robotic dispensing systems hinders new product development and implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Engineering Adhesives Market |
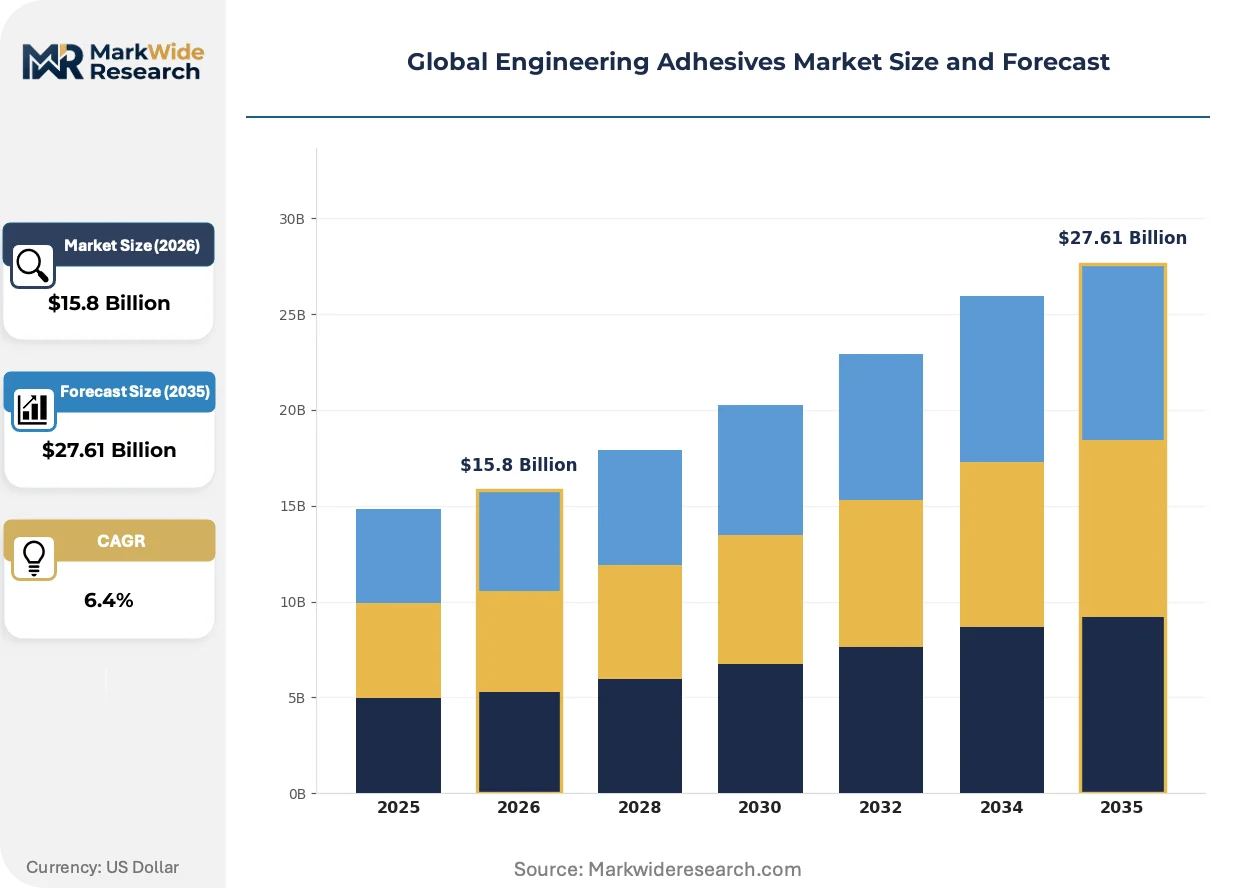
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $27.61 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Adhesive Type: Acrylic, Epoxy, Polyurethane, Silicone, Anaerobic, Cyanoacrylate Application: Electronics Assembly, Aerospace Bonding, Construction Fixing, Marine Repairs, Sports Equipment, Footwear Manufacturing End User Industry: Consumer Electronics Manufacturers, Aircraft Fabricators, Infrastructure Contractors, Boat Builders, Athletic Goods Producers, Leather Goods Companies Packaging Type: Cartridges, Bottles, Tubs, Syringes, Sachets, Bulk Containers |
| Companies Covered | 3M Company, Henkel AG & Co. KGaA, H.B. Fuller Company, Huntsman Corporation, Arkema, Dow Inc, Sika AG, Permabond LLC, Dymax Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Engineering Adhesives Market Strategic Shifts & Innovations
Innovation in the engineering adhesives market is defined by the pursuit of formulations that deliver higher performance within the constraints of global environmental regulations. Product development is reshaping competitive positioning by focusing on process compatibility and sustainable material science.
Automated robotic dispensing systems apply adhesives with high precision, consistency, and speed. Automotive and consumer electronics manufacturers are rapidly integrating these systems to increase assembly line throughput and ensure bond-line integrity. This automation is decentralizing application expertise from specialized human operators to programmable software, enabling more complex and reliable assembly designs.
Europe's REACH regulation, enforced by ECHA, continues to restrict substances of very high concern commonly used in adhesive precursors. This framework compels ongoing reformulation of products and increases R&D investment for global suppliers to maintain market access. The polyurethane adhesive segment is most affected, with formulators developing isocyanate-free systems to comply.
A shift from single-source contracts to multi-vendor qualification is realigning supply chain strategies for original equipment manufacturers. This change disrupts established supplier relationships, forcing adhesive providers to compete more intensely on application support and supply resilience. This pattern is most visible in the global aerospace industry, where mitigating supply chain risk is a primary objective.
Global Engineering Adhesives Market Segmentation
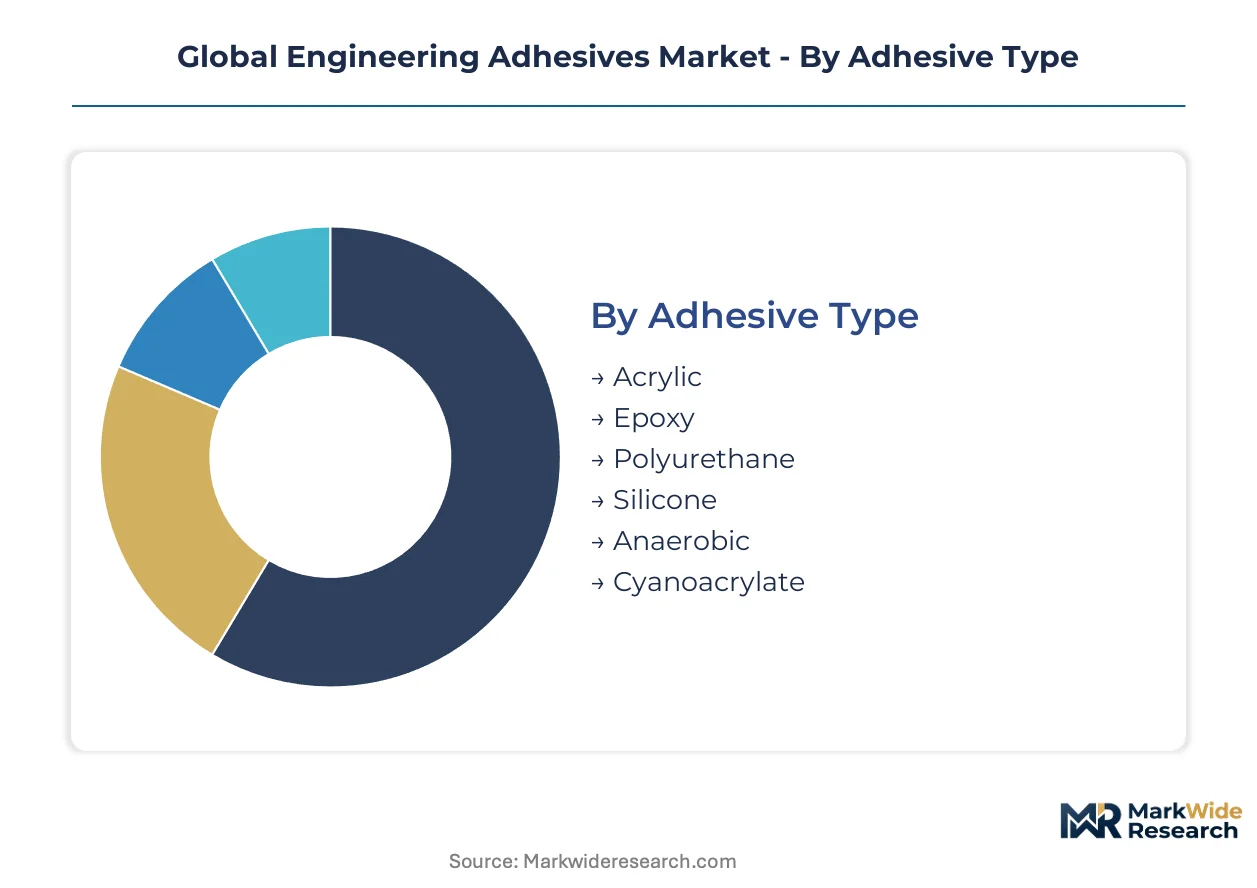
Understanding the Global Engineering Adhesives Market through a detailed segmentation analysis reveals the diverse needs across end-user industries and application types. This granular view highlights where innovation and investment in specific adhesive chemistries and delivery systems are most concentrated, influencing market development and competitive strategies.
Adhesive Type:
The capital intensity of developing and scaling production for advanced adhesive formulations varies significantly by chemical class.
- Epoxy:These thermosetting polymers form strong, rigid bonds with excellent chemical and heat resistance, widely used in structural applications for aerospace and construction due to their high shear strength. Demand for epoxy adhesives is concentrating in Germany and Japan for high-performance composite bonding.
- Polyurethane:Known for their flexibility, toughness, and good adhesion to diverse substrates, polyurethanes are prevalent in automotive and footwear manufacturing. Their use is expanding in China and India for flexible assembly and impact-resistant applications.
- Acrylic:Acrylic adhesives offer fast curing times and strong bonds to various materials, often employed in general assembly and product fabrication.
- Silicone:These elastomers provide excellent thermal stability and flexibility, making them suitable for sealing and bonding in electronics and high-temperature environments.
- Anaerobic:Anaerobic adhesives cure in the absence of oxygen and in contact with metal ions, primarily used for threadlocking and retaining metal components.
- Cyanoacrylate:Commonly known as super glues, cyanoacrylates offer rapid bonding for small components in consumer goods and medical devices.
Most installed capacity flows through Epoxy. Expansion is steepest in Polyurethane.
Application:
The market's application landscape is shaped by the specific performance requirements and processing demands of each sector.
- Electronics Assembly:Adhesives in this segment facilitate miniaturization and water resistance, bonding delicate components like microchips and displays in compact devices. Demand for these materials is accelerating in South Korea and Taiwan for advanced smartphone and wearable production.
- Aerospace Bonding:High-performance adhesives replace mechanical fasteners in aircraft structures, reducing weight and improving fuel efficiency for commercial and defense aviation. This application is expanding in the United States and France due to stringent lightweighting mandates.
- Construction Fixing:Engineering adhesives are increasingly used for structural glazing, panel bonding, and flooring installations, offering durable and aesthetic solutions.
- Marine Repairs:Specialized adhesives provide water-resistant and corrosion-proof bonds for boat construction and maintenance, including hull and deck repairs.
- Sports Equipment:Adhesives bond composite materials in athletic gear, enhancing strength, flexibility, and durability for products like skis and rackets.
- Footwear Manufacturing:These adhesives are crucial for bonding various materials in shoe production, providing flexibility and long-lasting adhesion.
The most significant application for volume is Electronics Assembly. Revenue growth is strongest in Aerospace Bonding.
End User Industry:
Customer type differentiation dictates specific product development and technical support requirements across the market.
- Consumer Electronics Manufacturers:These companies require adhesives for bonding dissimilar materials in compact, water-resistant devices, driving innovation in fast-curing and flexible formulations. Demand from these manufacturers is particularly high in China and Vietnam for device assembly.
- Aircraft Fabricators:Manufacturers of aircraft components and assemblies rely on structural adhesives for lightweighting and fatigue resistance, replacing traditional rivets and welds. These fabricators in the United States and Germany are driving demand for high-strength epoxies.
- Infrastructure Contractors:This segment utilizes adhesives for large-scale construction projects, including concrete repair, road surfacing, and bridge construction.
- Boat Builders:Adhesives provide durable, waterproof bonds for marine vessel construction, from small recreational boats to large commercial ships.
- Athletic Goods Producers:Manufacturers of sports equipment use adhesives to bond advanced composites and plastics, enhancing product performance and longevity.
- Leather Goods Companies:Adhesives offer strong, flexible bonds for assembling various leather products, including footwear and accessories.
The primary customer segment by volume is Consumer Electronics Manufacturers. The fastest expanding segment is Aircraft Fabricators.
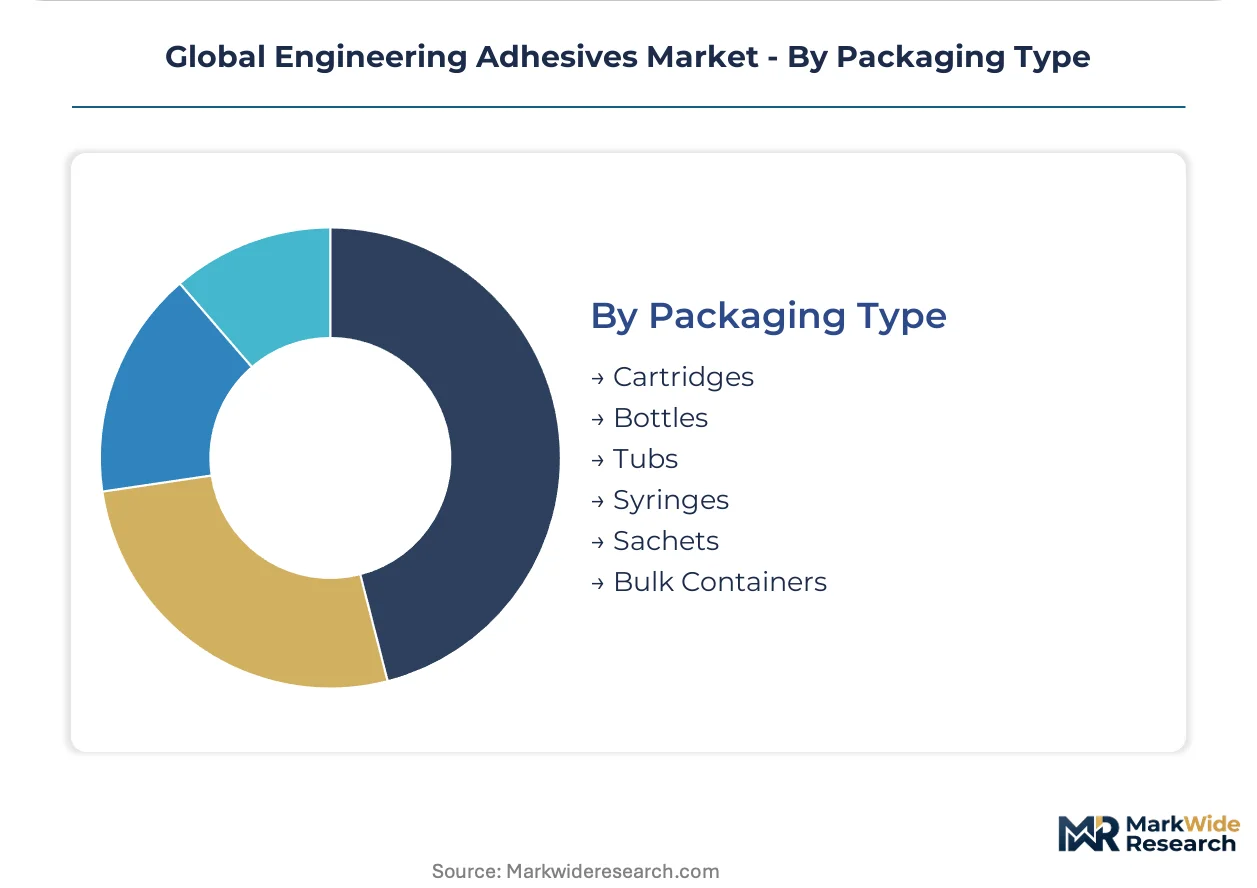
Packaging Type:
The packaging type influences application efficiency, material waste, and overall cost-effectiveness for end-users.
- Cartridges:These pre-filled tubes allow for precise, controlled dispensing of adhesives, suitable for manual or automated application in various industries. Demand for cartridges is high in Japan and South Korea for electronics assembly lines.
- Bulk Containers:Large drums or totes offer cost-effective solutions for high-volume manufacturing processes, reducing material handling and waste. These containers are widely used in the United States and China for automotive and construction applications.
- Bottles:Bottles are common for general-purpose adhesives, offering ease of use for smaller applications and DIY projects.
- Tubs:Tubs provide convenient storage and access for paste-like or high-viscosity adhesives, often applied with spatulas or brushes.
- Syringes:Syringes enable highly accurate and fine dispensing of small adhesive quantities, critical for delicate electronics or medical device assembly.
- Sachets:Single-use sachets provide pre-measured adhesive portions, minimizing waste and ensuring consistent application for small-scale tasks.
The packaging type with the largest volume consumption is Bulk Containers. Growth in adoption is most notable for Syringes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dominant industrial clusters in China and Southeast Asia concentrate significant demand for engineering adhesives. These regions drive innovation in compact device assembly and lightweighting applications. Regulatory frameworks influence product development and market access across these key manufacturing hubs.
United States
United States aerospace bonding for lightweighting and high-performance automotive applications drives significant demand. US EPA rules on volatile organic compounds influence new adhesive formulations. Seattle's aerospace cluster leads innovation in composite bonding solutions for aircraft fabricators.
China
China's consumer electronics miniaturization and rapid expansion in automotive manufacturing require advanced adhesives. China's GB standards dictate material selection and market entry for chemical products. The Yangtze River Delta region sees extensive adoption for compact device assembly and vehicle production.
Germany
Germany's demand for high-strength epoxy adhesives supports construction projects and advanced automotive components. The REACH framework from ECHA compels continuous product reformulation for market access. Bavaria's industrial base extensively utilizes advanced adhesives for precision engineering applications.
Japan
Japanese demand for epoxy adhesives concentrates in high-performance composite bonding and precision electronics assembly. METI guidelines support the development of sustainable chemical products and advanced materials. Tokyo's electronics industry drives syringe and cartridge adoption for delicate component applications.
South Korea
South Korea's advanced smartphone production and demand for water-resistant device bonding accelerate adhesive adoption. K-REACH regulations influence chemical ingredient selection and product safety for domestic manufacturers. Seoul's technology firms integrate specialized adhesives for flexible displays and wearable devices.
Global Engineering Adhesives Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue outcome-based solutions in specialized niches like bio-based formulations. The market structure reveals a blend of large, diversified chemical companies and agile, application-focused formulators. Strategic archetypes include global portfolio providers leveraging extensive distribution, application-specific innovators offering dedicated technical support, and raw material integrated suppliers controlling key value chain components. Dominant competitive moves involve strategic partnerships for market access and continuous portfolio diversification to meet evolving regulatory demands.
Within the diversified portfolio segment, Henkel AG & Co. KGaA, a German public limited company, exemplifies a global player leveraging an extensive product range and distribution network across diverse end-user industries. H.B. Fuller Company, a US-based entity, occupies a position as an application-focused specialist, providing dedicated customer technical support across specific application niches. Arkema, a French public limited company, represents a raw material integrated supplier, specializing in high-performance polymers that serve as precursors for advanced adhesive systems, thereby controlling a key part of the value chain. These prominent entities anchor distinct competitive approaches within the engineering adhesives market.
| Leading Market Players |
|---|
| 3M Company |
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| Huntsman Corporation |
| Arkema |
| Dow Inc |
| Sika AG |
| Permabond LLC |
| Dymax Corporation |
| Others |
Cost & Logistics Intelligence
A clear performance divergence between advanced structural adhesives and general-purpose formulations shapes both pricing structures and supply chain configurations. This bifurcation reflects distinct material requirements and manufacturing complexities across diverse end-user applications within the market.
Pricing Analysis
Input-cost pass-through from petrochemical-derived feedstocks, such as epoxy resins and isocyanates, directly influences adhesive pricing. The dominant pricing model is contract-based long-term off-take for high-volume original equipment manufacturers. Price differentiation stems from specialized application support and compliance with stringent certifications like REACH. Pricing softness affects standard grades due to raw material price volatility. Consumer electronics manufacturers exhibit higher price sensitivity compared to aircraft fabricators, who prioritize performance and reliability.
Supply Chain Analysis
Logistics and freight costs for specialized chemical precursors impact the final delivered price of engineering adhesives. Geographic supply concentration for these materials is notable in China and Germany, particularly for high-performance epoxy and polyurethane components. Raw material dependencies include specialized polymers and isocyanates. A structural supply chain risk is raw material price volatility, which can disrupt production schedules. Distribution runs through direct sales channels for large industrial clients and specialized distributors for niche application segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a late-cycle quality story, driven by a demand-shift toward premium specifications for lightweighting and enhanced durability.
For Market Incumbents:
Deploy continuous R&D investment to develop next-generation, low-VOC formulations compatible with automated robotic dispensing systems. Reformulate existing product lines to proactively meet evolving chemical safety regulations like Europe's REACH and China's GB standards. Expand specialized technical support teams to address complex application hurdles for advanced composite substrates, mitigating the threat from alternative joining technologies.
For New Entrants and Emerging Players:
Online technical communities and direct-to-customer e-commerce platforms offer accessible routes for market entry. Target the construction sector in Southeast Asian economies with high-performance, sustainable bio-based formulations that displace traditional cementitious mortars. Develop adhesives specifically for flexible electronics and medical sensors, offering unique value propositions around biocompatibility and durability. Focus on a go-to-market strategy emphasizing rapid prototyping and application-specific customization.
For Investors and Strategic Acquirers:
Asymmetric upside sits with niche formulators possessing proprietary technology in bio-based or high-performance, regulation-compliant chemistries. The engineering adhesives market exhibits sustained growth over the next decade, driven by fundamental shifts in manufacturing toward lightweighting and miniaturization. Acquisition targets should include companies with strong intellectual property in advanced polymer science or specialized robotic dispensing integration capabilities. The signal to watch is increased M&A activity for specialized polymer precursor suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Polyurethane | Supports growing demand for flexible bonding in automotive and footwear manufacturing in Asia. |
| Green Manufacturing Transition | Addresses corporate sustainability mandates and regulatory pressures for environmentally friendly products. |
| Long-term Supply Agreements | Secures raw material access and stabilizes costs for critical aerospace and automotive OEMs. |
| Joint Ventures in Southeast Asia | Facilitates market access and localized product development for construction adhesives. |
| Product Launch: Isocyanate-Free Systems | Ensures compliance with evolving European chemical regulations for polyurethane adhesives. |
Research Approach
Multiple input streams—industry reports, company financial statements, and expert interviews—were reconciled to construct a comprehensive market view. Primary research involved discussions with formulation chemists, OEM procurement leads, application engineers, and regulatory compliance officers. Secondary validation drew from ECHA dossiers, US EPA regulations, China's GB standards, and customs trade data, triangulating information through both bottom-up and top-down approaches.
Historical performance data and expert panel input were cross-referenced to develop the forecast framework across the analysis window. The quantitative model incorporated segmentation dimensions including adhesive type, application, end-user industry, packaging type, and regional manufacturing output. Compound annual growth rates were derived from a regression model incorporating macroeconomic indicators and specific industry forecasts like raw material price trends and automotive production volumes.
The model assumes a particular technology adoption path for automated robotic dispensing systems; alternative pathways for advanced composite bonding would alter the outlook. Forecasts reflect specific assumptions regarding regulatory evolution and material science breakthroughs. Unforeseen geopolitical events or disruptive alternative joining technologies represent specific risk factors. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Middle-East and Africa Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Middle-East and Africa Hot-Melt Adhesives Market
Adhesives & Sealants
UV Adhesives Market
Adhesives & Sealants
Gelatin Bone Glue Market
Adhesives & Sealants
US Pressure Sensitive Adhesives Market
Adhesives & Sealants
Germany Sealants Market
Adhesives & Sealants
Restorative Materials and Bonding Agents Market
Adhesives & Sealants
Germany Adhesives Market
Adhesives & Sealants
Japan Sealants Market
Adhesives & Sealants
Europe Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
South America Adhesives Market
Adhesives & Sealants
North America Adhesives Market
Adhesives & Sealants
Timber Laminating Adhesives Market
Adhesives & Sealants
Middle-East and Africa Reactive Adhesives Market
Adhesives & Sealants
Correction Fluid and Tape Market
Adhesives & Sealants
Global Spray Adhesive Market