
 Macrolides Market | 2026-2036
Macrolides Market Size, Share, and Industry Trends Forecast 2026-2036
Macrolides Market Foresight
Hospital procurement networks is reconfiguring how macrolide antibiotics reach end users, with centralized purchasing now dominating large health system contracts. Pfizer Inc. leverages its manufacturing scale to sustain supply agreements with integrated delivery networks across multiple geographies. Teva Pharmaceutical Industries Ltd. competes aggressively on cost, anchoring its position in generic azithromycin and clarithromycin formulations.
Macrolides constitute a class of polyketide antibiotics characterized by a large macrocyclic lactone ring structure, typically containing 14, 15, or 16 atoms, synthesized through bacterial fermentation or semi-synthetic modification. These agents inhibit bacterial protein synthesis by reversibly binding to the 50S ribosomal subunit, serving primarily as first-line or alternative therapies for respiratory, skin, and atypical infections. Azithromycin dominates current revenue pools due to its favorable pharmacokinetic profile and broad indication base, while injectable formulations command premium positioning in hospital settings. Oral suspension formats sustain growth in pediatric and geriatric populations where tablet compliance poses challenges.
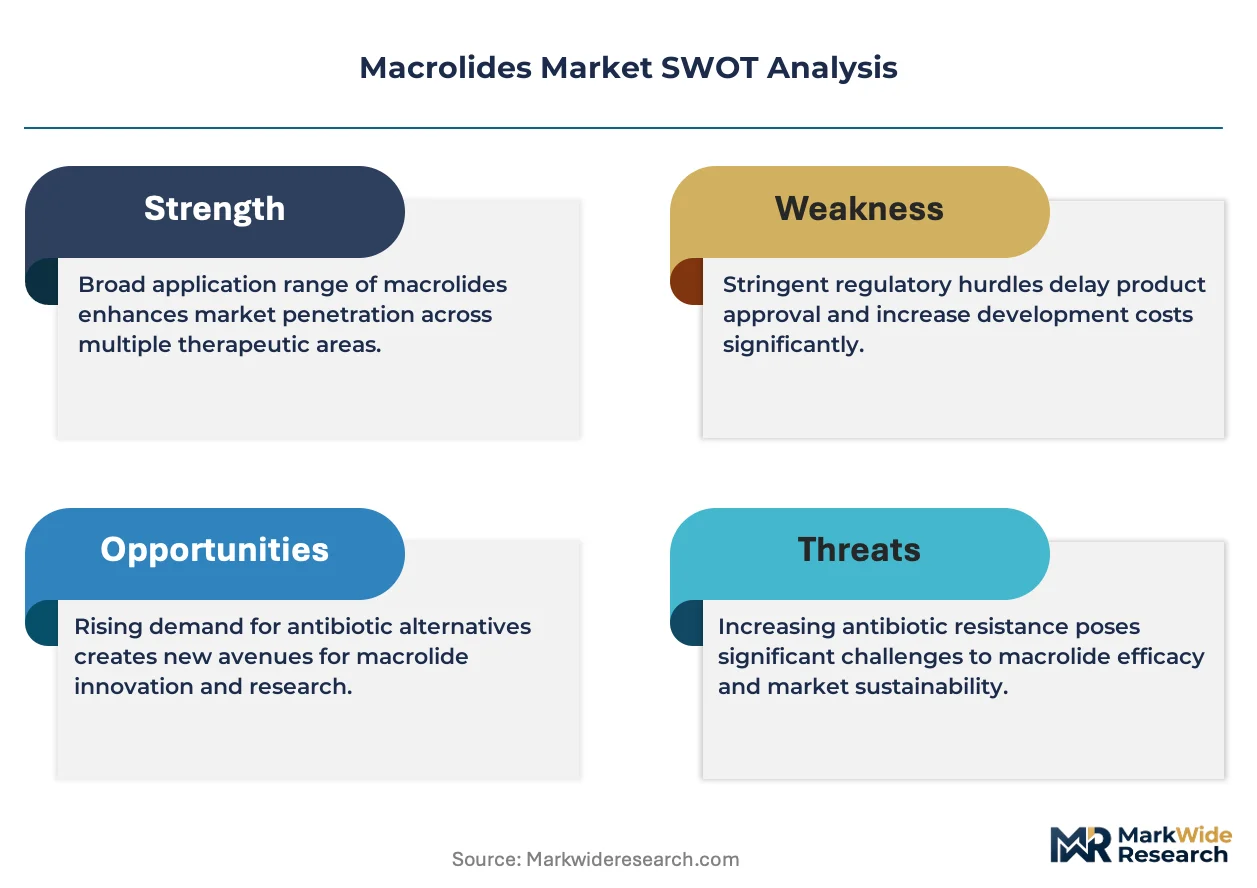
The FDA, EMA, and WHO collectively govern macrolide quality standards, with the FDA's antimicrobial stewardship mandates restricting empirical prescribing and EMA's pharmacovigilance frameworks tracking QT prolongation risks. These regulatory pressures elevate documentation requirements and narrow the therapeutic window for new product entries. Stakeholders must monitor evolving resistance surveillance data and regulatory guidance to align R&D portfolios with restricted-use pathways.
Market Dynamics
Hospital formulary consolidation is compressing the macrolide antibiotic supply chain into fewer, larger procurement contracts that favor manufacturers with integrated manufacturing networks and regulatory dossier depth.
Growth Catalysts
- Respiratory protocol expansion:Hospital infection control committees in the United States are embedding macrolides into standardized pneumonia order sets, creating recurring volume commitments.
- EMA pharmacovigilance frameworks:Tightened cardiac safety monitoring is filtering out marginal suppliers and concentrating volume with established dossier holders.
- Semi-synthetic fermentation advances:Improved polyketide synthesis yields are reducing batch-to-batch variability and shortening regulatory approval timelines for generic entrants.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production for erythromycin derivatives clusters in Chinese fermentation facilities, exposing formulators to import inspection delays.
- Resistance surveillance mandates:The FDA's antimicrobial stewardship programs require documented susceptibility testing before empirical macrolide prescribing, adding administrative friction.
- QT prolongation liability:Cardiac arrhythmia warnings on azithromycin labels have narrowed the prescriber base to physicians comfortable with electrocardiographic monitoring protocols.
Strategic Opportunities
- Pediatric suspension formats:Oral liquid formulations for children under five remain underserved by current generic portfolios, creating white space for differentiated delivery systems.
- Indian hospital procurement:CDSCO's accelerated approval pathways for essential medicines are opening tender opportunities in state government health networks.
- Combination therapy protocols:Fixed-dose pairing with beta-lactamase inhibitors is migrating from clinical trial settings to outpatient stewardship programs.
Industry Challenges
- Fermentation specialist scarcity:Industrial microbiologists capable of optimizing Streptomyces erythraea yields command premium compensation, constraining capacity expansion timelines.
- ICH Q7 compliance costs:Upgrading active pharmaceutical ingredient facilities to current good manufacturing practice standards requires capital deployment that squeezes mid-tier manufacturer margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Macrolides Market |
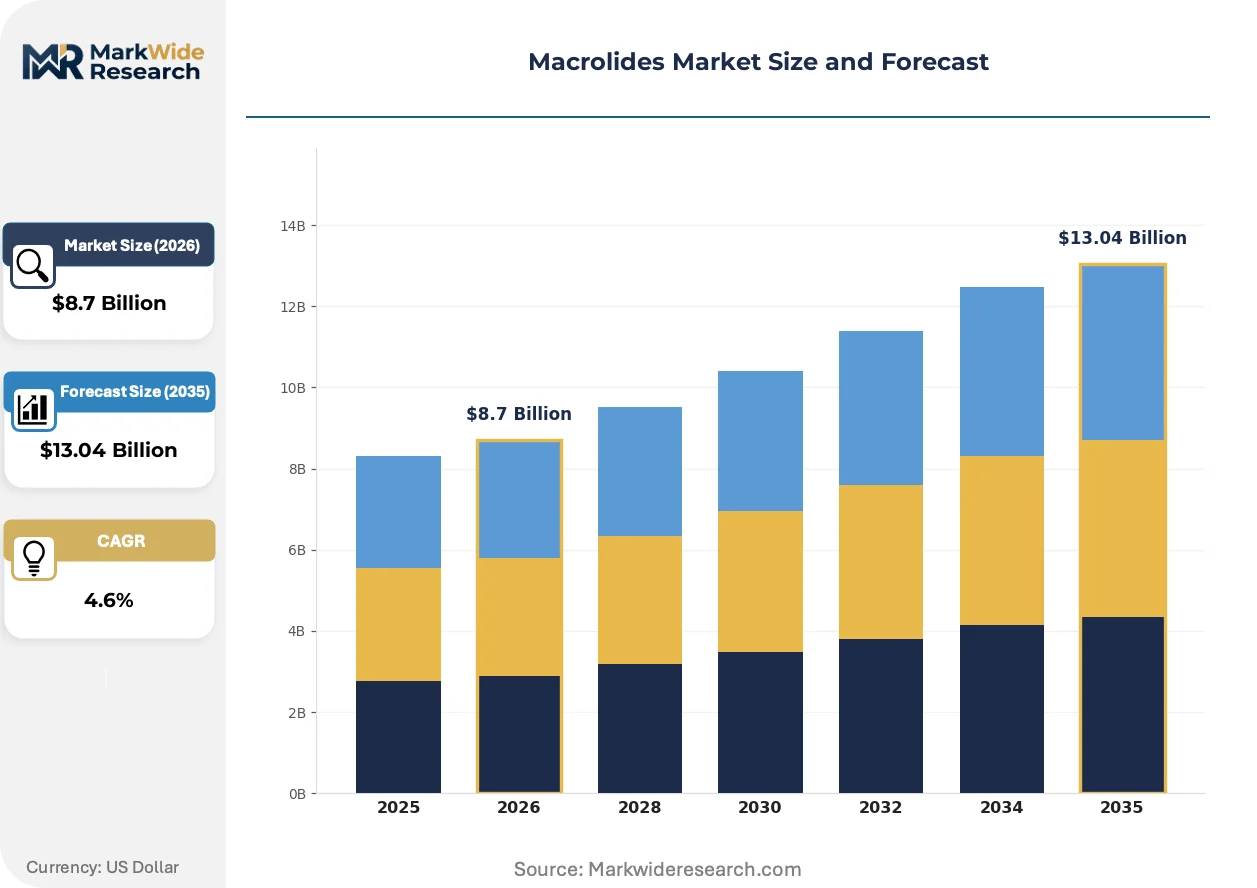
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Erythromycin, Azithromycin, Clarithromycin, Roxithromycin End User: Hospitals, Clinics, Pharmacies, Research Laboratories Application: Infections, Respiratory Diseases, Dermatological Conditions, Dental Infections Formulation: Tablets, Oral Suspension, Injectables, Topical Creams |
| Companies Covered | Pfizer Inc., Merck & Co., Inc., Sanofi S.A., Eli Lilly and Company, Abbott Laboratories, Teva Pharmaceutical Industries Ltd., GlaxoSmithKline plc, Novartis AG, Sandoz International GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Macrolides Market Shifts & Advancements
Continuous manufacturing technologies are displacing batch fermentation for macrolide production, while regulatory agencies on three continents tighten environmental discharge standards for antibiotic manufacturing waste streams.
Next-generation macrolide engineering is migrating from natural product fermentation to synthetic biology platforms. Engineered Saccharomyces cerevisiae strains now produce 15-membered ring structures with modified side chains. Biotech contract manufacturers in Germany and the Netherlands are scaling these platforms for clinical trial material supply. The shift is compressing development timelines for derivatives targeting resistant Mycoplasma pneumoniae strains.
REACH antibiotic manufacturing discharge amendments are forcing European production sites to install advanced oxidation process wastewater treatment. The EMA's tightened environmental risk assessment guidelines now require aquatic toxicity data prior to marketing authorization renewal. Facilities on the Rhine corridor are retrofitting biological treatment trains to meet predicted no-effect concentration thresholds for macrolide metabolites.
Hospital purchasing cooperatives are consolidating antibiotic sourcing into multi-year sole-source agreements with inflation-adjusted price collars. Group purchasing organizations in the United States are extracting volume commitments in exchange for formulary exclusivity. This concentration is displacing traditional wholesaler relationships and pushing manufacturers to embed clinical pharmacists directly into health system stewardship committees.
Macrolides Market Segmentation
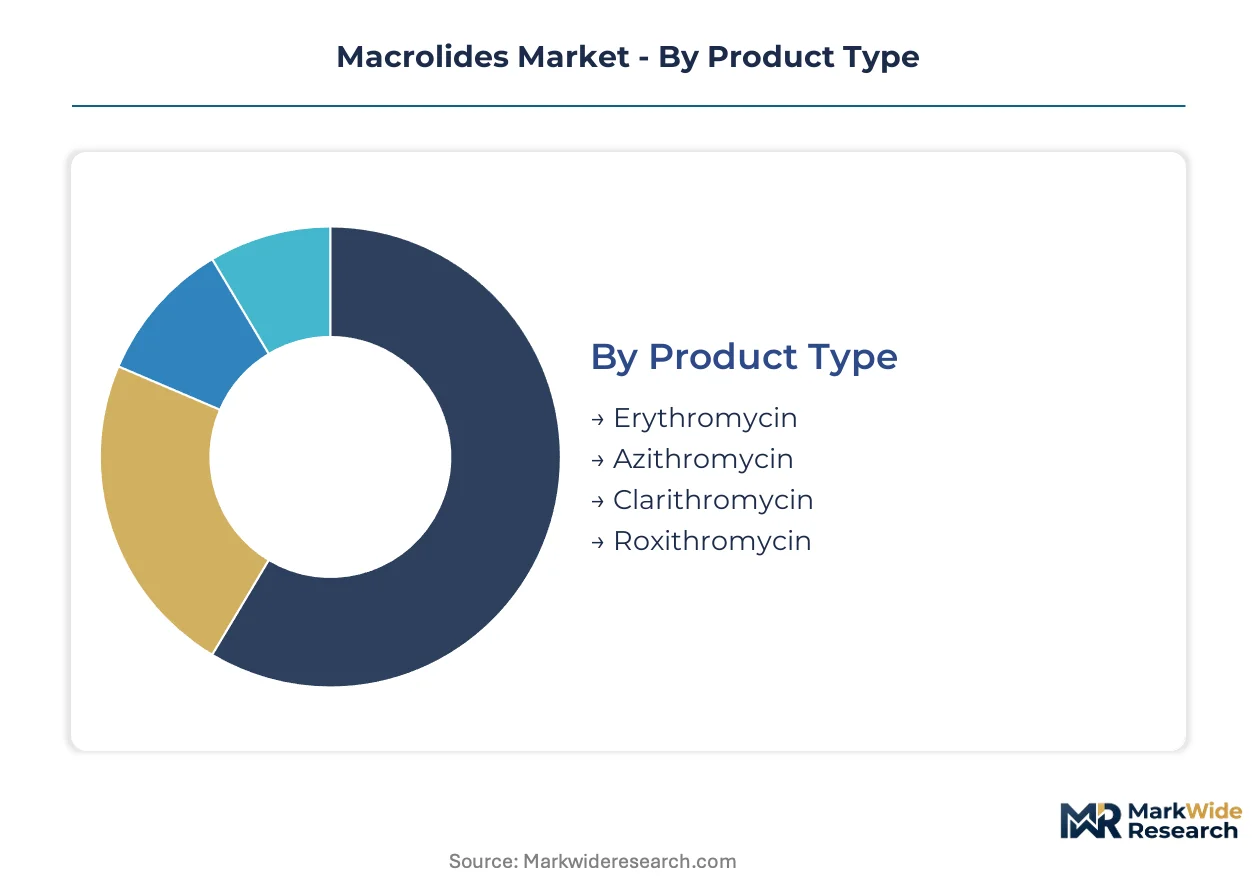
Macrolide antibiotics fragment across multiple technical and commercial dimensions, with formulation choices and end-user procurement patterns driving margin structures. Supply contracts diverge sharply between hospital formulary systems and retail pharmacy networks, creating distinct service intensity requirements.
Product Type:
After-sales service intensity varies significantly across macrolide generations, with legacy fermentation products requiring technical support for batch variability issues while semi-synthetics demand pharmacovigilance documentation.
- Erythromycin:The original 14-membered macrocyclic lactone synthesized through Streptomyces erythraea fermentation, erythromycin retains niche demand among patients with azithromycin hypersensitivity. Hospital procurement in the United States sustains volume for penicillin-allergic pneumonia protocols despite gastrointestinal tolerability limitations.
- Azithromycin:A 15-membered azalide derivative with superior tissue penetration and extended half-life enabling single-dose regimens. Pediatric suspension demand in outpatient clinic networks and travel medicine prophylaxis programs in India concentrate volume for this segment.
- Clarithromycin:6-O-methylerythromycin with improved acid stability and Helicobacter pylori eradication indications. Triple therapy protocols in Japanese hospital networks and European gastroenterology practices anchor demand.
- Roxithromycin:Semisynthetic 14-membered macrolide with reduced CYP3A4 interaction profile. Prescribing concentrates in German and French primary care settings for community-acquired respiratory infections.
By volume, azithromycin leads. By growth pace, clarithromycin is ahead in H. pylori combination protocols.
End User:
Customer type determines contract structure complexity, with integrated delivery networks negotiating multi-year agreements while independent pharmacies operate on spot purchasing terms.
- Hospitals:Centralized procurement through group purchasing organizations dominates antibiotic acquisition, with antimicrobial stewardship committees restricting empirical macrolide use to documented susceptibility. Formulary placement requires extensive clinical pharmacology dossiers and electrocardiographic safety data.
- Clinics:Outpatient networks in the United States and polyclinic systems in India drive ambulatory prescribing for upper respiratory infections. Volume concentrates in urgent care chains and occupational health facilities with standardized order sets.
- Pharmacies:Retail dispensing faces generic substitution pressures and prior authorization requirements from pharmacy benefit managers.
- Research Laboratories:Reference laboratories and contract research organizations procure macrolides for antimicrobial susceptibility testing panels and resistance surveillance studies.
By revenue concentration, hospitals dominate. By expansion trajectory, clinics are gaining share fastest.
Application:
Margins stratify across indication severity, with life-threatening respiratory infections commanding premium pricing and dermatological applications facing commoditization.
- Infections:Atypical bacterial pathogens including Mycoplasma pneumoniae, Chlamydia pneumoniae, and Legionella species constitute the core therapeutic target. Hospital protocols in the United States embed macrolides into empiric pneumonia regimens pending diagnostic confirmation.
- Respiratory Diseases:Chronic obstructive pulmonary disease exacerbations and cystic fibrosis colonization drive recurrent prescribing. Long-term azithromycin prophylaxis in Australian and Canadian cystic fibrosis centers sustains volume despite QT prolongation monitoring requirements.
- Dermatological Conditions:Acne vulgaris and rosacea applications face generic saturation and topical antibiotic stewardship restrictions.
- Dental Infections:Odontogenic abscess protocols in European dental schools and American dental service organizations concentrate perioperative prophylaxis demand.
By patient volume, respiratory diseases lead. By therapeutic innovation, infections show the steepest expansion trajectory.
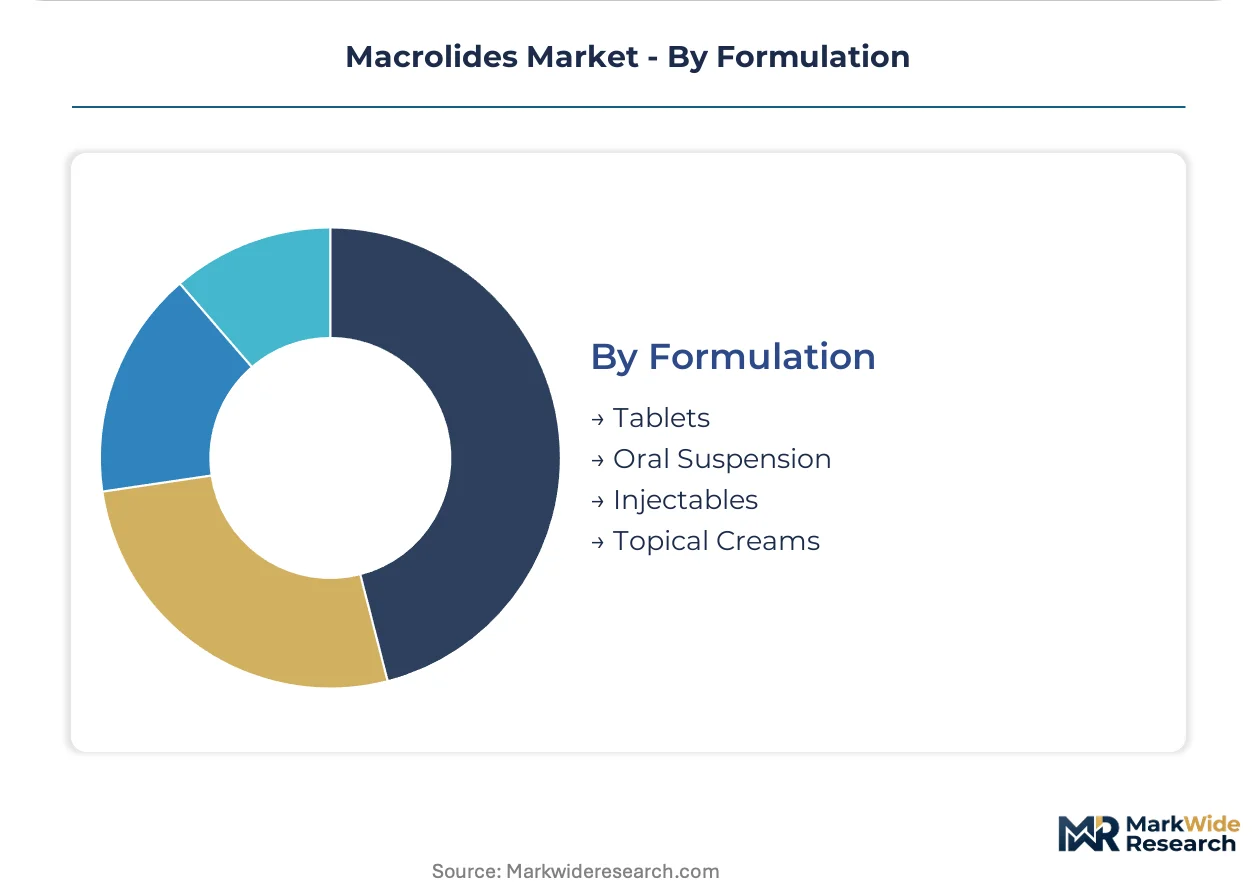
Formulation:
Supply concentration differs radically by dosage form, with sterile injectable capacity constrained by aseptic manufacturing requirements while oral solids face commodity competition.
- Tablets:Immediate-release and extended-release solid oral dosage forms dominate adult prescribing. German and Swiss contract manufacturers specialize in high-volume azithromycin tablet production for European tender markets.
- Oral Suspension:Powder-for-reconstitution and ready-to-use liquid formulations serve pediatric populations and geriatric patients with dysphagia. Flavor masking technology and stability data requirements create formulation barriers.
- Injectables:Intravenous formulations command premium hospital pricing for severe infections requiring inpatient admission.
- Topical Creams:Dermatological preparations face compounding pharmacy competition and over-the-counter substitution pressures.
By unit volume, tablets lead. By value per dose, injectables are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA antimicrobial stewardship mandates anchor the United States as the dominant geography, with hospital formulary controls and outpatient clinic networks concentrating procurement volume. Formulary placement requirements and electrocardiographic safety documentation shape competitive access across multiple geographies.
United States
Hospital infection control committees embed macrolides into standardized pneumonia order sets, creating recurring volume commitments. The FDA's antimicrobial stewardship programs require documented susceptibility testing before empirical prescribing. Integrated delivery networks in the Midwest and Southeast negotiate multi-year sole-source agreements with inflation-adjusted price collars.
Germany
Primary care prescribing for community-acquired respiratory infections sustains roxithromycin demand in outpatient settings. REACH antibiotic manufacturing discharge amendments force production sites to install advanced oxidation process wastewater treatment. The Rhine corridor facilities retrofit biological treatment trains to meet predicted no-effect concentration thresholds for macrolide metabolites.
India
Pediatric suspension demand in outpatient clinic networks and travel medicine prophylaxis programs concentrate azithromycin volume. CDSCO's accelerated approval pathways for essential medicines open tender opportunities in state government health networks. Contract manufacturers in Hyderabad and Ahmedabad scale production for domestic hospital procurement and export markets.
Japan
Triple therapy protocols in hospital networks and gastroenterology practices anchor clarithromycin demand for H. pylori eradication. PMDA pharmacovigilance frameworks track QT prolongation risks and elevate documentation requirements for new product entries. The Kansai region hosts fermentation specialists optimizing polyketide synthesis yields for regional supply.
Australia
Long-term azithromycin prophylaxis in cystic fibrosis centers sustains volume despite QT prolongation monitoring requirements. TGA antimicrobial resistance surveillance informs hospital formulary restrictions and empirical prescribing guidelines. Melbourne and Sydney research laboratories procure reference materials for susceptibility testing panels and resistance studies.
Macrolides Market Competitive Landscape
Research-intensive multinationals and high-volume generic manufacturers split the market into distinct capability tiers. Hospital formulary consolidation compresses the supply chain into fewer, larger procurement contracts that favor players with integrated manufacturing networks. Three archetypes dominate: diversified pharmaceutical conglomerates with fermentation heritage, specialized generic houses competing on cost, and biotech contract manufacturers scaling synthetic biology platforms. Competitive moves center on multi-year sole-source agreements with group purchasing organizations and backward integration into active pharmaceutical ingredient production.
Within the diversified pharmaceutical tier, Pfizer Inc. and Merck & Co., Inc. exemplify players with manufacturing scale sustaining supply agreements across multiple geographies. Teva Pharmaceutical Industries Ltd. occupies a position among high-volume generic houses, anchoring portfolio presence in oral solid and suspension formulations. These three represent distinct strategic postures: fermentation-based supply security, research-intensive portfolio breadth, and cost-optimized generic substitution.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co., Inc. |
| Sanofi S.A. |
| Eli Lilly and Company |
| Abbott Laboratories |
| Teva Pharmaceutical Industries Ltd. |
| GlaxoSmithKline plc |
| Novartis AG |
| Sandoz International GmbH |
| Others |
Supply & Pricing Matrix
Hyderabad and Ahmedabad fermentation clusters in India control erythromycin derivative capacity, translating upstream batch consistency into negotiating leverage over European and North American formulators facing formulary price collars.
Pricing Analysis
Azithromycin tablets trade at 40-60% spreads between German tender markets and Indian retail pharmacies, with contract-based long-term offtake dominating hospital procurement. Price differentiation rests on FDA bioequivalence certification tier and volume scale commitments from group purchasing organizations. Cost compression in generic oral solids is intensifying because Teva and Sandoz compete aggressively on azithromycin and clarithromycin tenders. Independent pharmacies exhibit highest price sensitivity, while integrated delivery networks with sole-source agreements show lowest sensitivity due to inflation-adjusted price collars.
Supply Chain Analysis
Streptomyces erythraea fermentation feedstock quality hinges on Chinese corn starch and Indian soybean meal inputs, with polyketide synthesis yields drawing from strain optimization expertise concentrated in Kansai region facilities. Active pharmaceutical ingredient production clusters in China, India, and Japan, exposing formulators to single-source vulnerability from import inspection delays at FDA and EMA borders. Distribution runs through group purchasing organization networks in the United States and state government tender systems in India, displacing traditional wholesaler relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital formulary consolidation fragments procurement access, creating niches for differentiated pediatric suspension formats and synthetic biology-derived next-generation macrolides that escape commodity pricing.
For Market Incumbents: Pre-empt generic substitution pressure by embedding clinical pharmacists directly into antimicrobial stewardship committees and securing backward integration into Streptomyces fermentation capacity in Hyderabad or Ahmedabad. Lock in multi-year sole-source agreements with inflation-adjusted price collars before CDSCO accelerated approval pathways flood Indian tender markets with additional generic entrants. For New Entrants and Emerging Players: Establish a beachhead in pediatric oral suspension formats for children under five, where flavor masking technology and stability data requirements create formulation barriers that generic houses have neglected. Target German biotech contract manufacturers scaling engineered Saccharomyces cerevisiae platforms for clinical trial material supply, using synthetic biology differentiation to escape fermentation-based cost competition. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors contract manufacturers with synthetic biology capabilities over legacy fermentation assets, as next-generation macrolide engineering compresses development timelines for resistant Mycoplasma pneumoniae strains. Watch EMA pharmacovigilance framework tightening on QT prolongation as the inflection signal—heightened cardiac safety documentation requirements will filter out marginal suppliers and concentrate volume with established dossier holders possessing electrocardiographic safety databases.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Fermentation | Captive supply of erythromycin derivatives insulates formulators from Chinese import inspection delays and batch variability. |
| Synthetic Biology Platform Investment | Engineered yeast strains producing 15-membered ring structures shorten regulatory timelines for resistant strain targeting. |
| Pediatric Suspension Format Development | Liquid formulations for under-five populations exploit white space where tablet compliance barriers limit generic competition. |
| Hospital Stewardship Committee Embedding | Direct pharmacist placement into antimicrobial stewardship committees secures formulary placement ahead of generic tender pressure. |
| REACH Wastewater Treatment Retrofit | Advanced oxidation process installation on Rhine corridor facilities preserves EMA marketing authorization renewal eligibility. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with fermentation operations directors, hospital formulary managers, regulatory affairs leads at EMA and FDA, and Indian CDSCO licensing officers; and secondary validation through FDA approval databases, EMA pharmacovigilance records, CDSCO essential medicines tenders, and customs trade data on erythromycin derivative imports. Bottom-up volume modeling from hospital procurement databases and GPO contract disclosures was triangulated against top-down market sizing from pharmaceutical trade associations.
Forecast inputs across the projection horizon incorporated patient volume trends in respiratory infection protocols, cystic fibrosis prophylaxis expansion, and H. pylori eradication program adoption. Segmentation dimensions modeled included macrolide generation (erythromycin, azithromycin, clarithromycin, roxithromycin), formulation type (tablet, suspension, injectable), end-user channel (hospital, clinic, pharmacy), and regional regulatory cluster (FDA, EMA, CDSCO, PMDA). CAGRs were derived from elasticity-adjusted volume projections and price trajectory assumptions tied to tender market dynamics.
Stress conditions across API import disruption severity, QT prolongation warning label expansion, and fermentation yield volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on stewardship program penetration and synthetic biology platform scale-up timelines. Cross-checking against WHO antimicrobial resistance surveillance data and national hospital procurement disclosure databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
US Sex Reassignment Hormone Therapy Market
Pharmaceuticals
Parathyroid Hormone Market
Pharmaceuticals
Valsartan Market
Pharmaceuticals
Male Hypogonadism Market
Pharmaceuticals
North America Over the Counter Drugs Market
Pharmaceuticals
Europe Novel Drug Delivery System (NDDS) Market
Pharmaceuticals
Acne Therapeutics Market
Pharmaceuticals
Multiple Myeloma Drugs Market
Pharmaceuticals
Asia Pacific Radiopharmaceuticals Market
Pharmaceuticals
Trenbolone Acetate Market
Pharmaceuticals
3D Printing Drug Market
Pharmaceuticals
Systemic Lupus Erythematous SLE Drugs Market
Pharmaceuticals
Mitotane Market
Pharmaceuticals
Zoldonat Injection Market
Pharmaceuticals
Adrenocorticotropic Hormone [ACTH] Market
Pharmaceuticals
Anti-Arrhythmic Drugs Market